
 Global Non-Invasive Monitoring Device Market | 2026-2036
Global Non-Invasive Monitoring Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Invasive Monitoring Device Market Foresight
Home healthcare is hardening as the dominant end-use vertical, displacing traditional hospital-centric procurement. Medtronic plc leverages its cardiac monitoring portfolio to anchor inpatient-to-home transitions. Koninklijke Philips N.V. sustains technology leadership in sleep analysis and respiratory tracking across European and North American channels. Masimo Corporation specializes in optical sensor architectures that dominate pulse oximetry standards.
Non-invasive monitoring devices employ photoplethysmography, electrical impedance, and infrared sensing to capture physiological parameters without skin puncture or internal insertion, typically operating at wavelengths between 660 and 940 nanometers for optical applications. These instruments serve continuous patient surveillance, chronic disease management, and early warning detection in clinical and domestic environments. Pulse oximeters and blood pressure monitors occupy mature margin pools where price compression is offset by volume scale in home healthcare channels. Photoplethysmography-based devices represent the fastest-growing technology segment as wearable form factors penetrate fitness tracking and sleep analysis applications.
FDA 510(k) premarket notification requirements govern device clearance in the United States, while EU MDR and CE marking frameworks enforce clinical evidence standards across European markets. Japan's PMDA maintains distinct quality management system inspections that extend approval timelines for foreign manufacturers. Stakeholders must monitor evolving reimbursement codes for remote therapeutic monitoring as payers recalibrate coverage thresholds for home-based data collection.
Market Dynamics
Photoplethysmography miniaturization is compressing device form factors below 30 grams while expanding parameter capture from SpO2 to blood pressure and glucose proxies. This hardware convergence is collapsing the boundary between clinical-grade and consumer monitoring tiers.
Growth Catalysts
- EU MDR clinical evidence requirements:Manufacturers are accelerating predicate device strategies to secure CE marking ahead of 2027 renewal deadlines, expanding notified body engagement across Germany and the Netherlands.
- Home healthcare channel expansion:Reimbursement codes for remote therapeutic monitoring in the United States are hardening physician prescribing patterns toward ambulatory pulse oximetry and blood pressure systems.
- Wearable photoplethysmography:Optical sensor arrays operating at 660-940 nanometers are penetrating sleep analysis and fitness tracking applications through ring and wrist-worn form factors.
Market Restraints
- Optical sensor supply concentration:Discrete photodiode and LED sourcing clusters in Taiwan and South Korea are creating 14-18 week lead time volatility for pulse oximetry module assembly.
- FDA 510(k) predicate limitations:Substantial equivalence pathways for novel glucose proxy algorithms face heightened scrutiny, extending clearance timelines for non-invasive metabolic monitoring.
- Li-ion battery chemistry constraints:Energy density limitations in sub-100mAh cells are compressing continuous monitoring duration below 72 hours for patch-based electrocardiography devices.
Strategic Opportunities
- India's PLI scheme for medical electronics:Production-linked incentives targeting 5-25% value addition are attracting contract manufacturing relocation for pulse oximetry and blood pressure monitor assembly.
- Continuous glucose monitoring proxies:Multi-wavelength photoplethysmography combined with machine learning inference is opening non-invasive metabolic tracking adjacent to diabetic populations.
- Pharmacy retail channel integration:CVS Health and Walgreens are deploying diagnostic kiosk networks that bundle blood pressure, SpO2, and atrial fibrillation screening with prescription fulfillment.
Industry Challenges
- Biomedical algorithm validation:FDA's evolving guidance on artificial intelligence-enabled diagnostic software is forcing 12-18 month retrospective clinical studies for photoplethysmography-based arrhythmia detection.
- Legacy hospital IT integration:HL7 FHIR interoperability gaps between consumer-grade wearable data streams and Epic Systems electronic health records are fragmenting remote patient monitoring workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Invasive Monitoring Device Market |
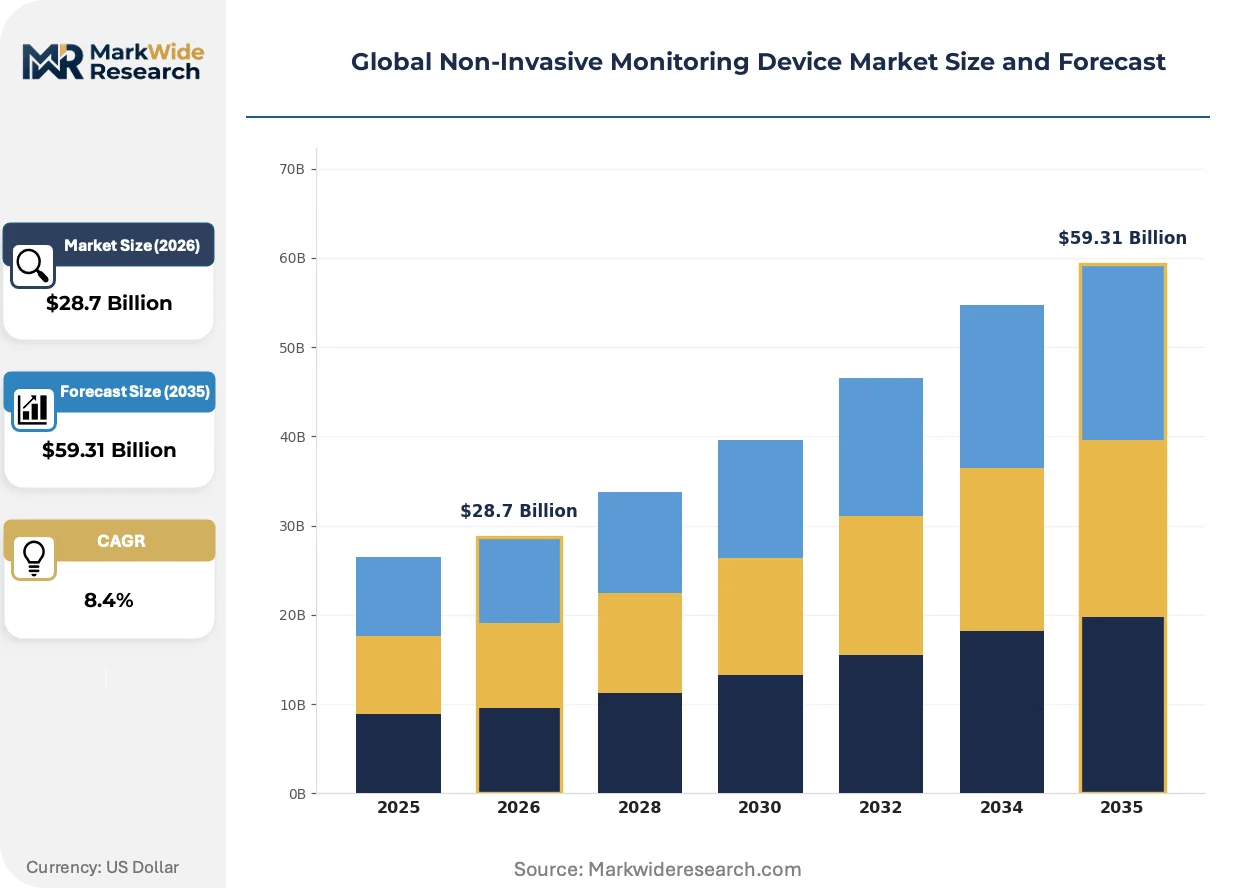
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulse Oximeters, Blood Pressure Monitors, Glucometers, Temperature Sensors, Respiratory Monitors, ECG Devices Technology: Optical Sensors, Ultrasound Sensors, Electrical Impedance, Photoplethysmography, Infrared Sensors, Capacitive Sensors Application: Cardiac Monitoring, Pulmonary Assessment, Diabetes Management, Fever Detection, Sleep Analysis, Fitness Tracking End User: Hospitals, Ambulatory Care Centers, Home Healthcare, Telemedicine Providers, Diagnostic Laboratories, Elderly Care Facilities |
| Companies Covered | Medtronic plc, Koninklijke Philips N.V., GE Healthcare, Abbott Laboratories, Siemens Healthineers AG, Masimo Corporation, Nihon Kohden Corporation, Hill-Rom Holdings, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Invasive Monitoring Device Market Shifts & Advancements
Multi-parameter fusion algorithms are collapsing single-purpose device categories into unified physiological surveillance platforms. This convergence is redrawing competitive boundaries between cardiac, respiratory, and metabolic monitoring specialists.
Photoplethysmography is automating continuous blood pressure estimation through pulse transit time calibration against electrocardiography R-wave detection. Cardiology departments in the United States and Germany are piloting these cuffless systems for 24-hour ambulatory monitoring. This automation is eliminating pneumatic pump components and reducing device weight below 20 grams for wrist-worn applications.
Japan's PMDA has tightened quality management system inspection protocols for foreign manufacturers seeking device approval, extending factory audit timelines by 4-6 months. Domestic Japanese manufacturers are leveraging this friction to defend hospital procurement relationships against US and European entrants. The sleep analysis segment is absorbing the greatest compliance burden as software-as-a-medical-device classifications proliferate.
Hospital procurement committees are unbundling device hardware from data analytics subscriptions, forcing vendors to price pulse oximetry and blood pressure monitors as capital equipment while monetizing predictive algorithms separately. This disaggregation is most visible in United States integrated delivery networks where remote patient monitoring budgets now split across biomedical engineering and information technology cost centers. The shift is compressing upfront device margins while extending revenue recognition across 36-month service terms.
Global Non-Invasive Monitoring Device Market Segmentation
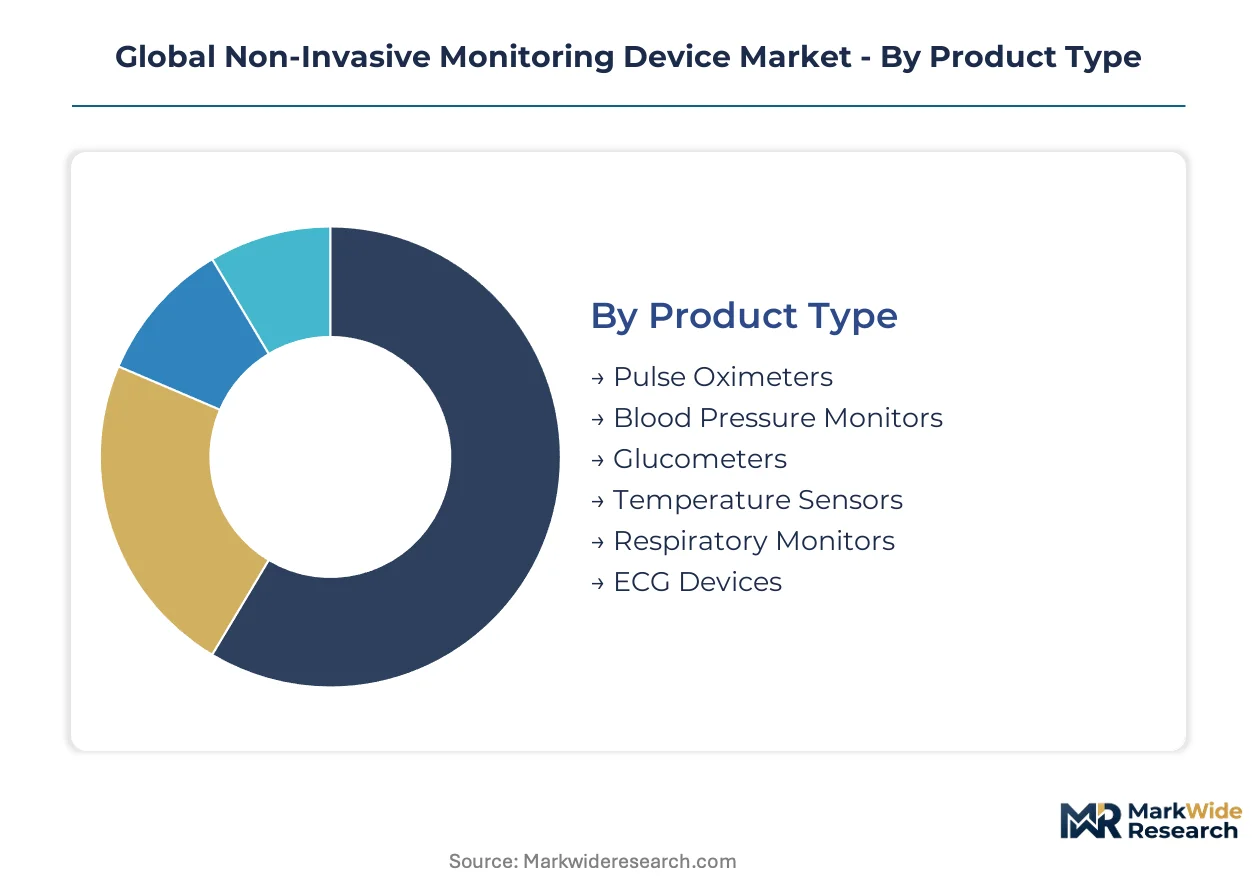
Device replacement cycles in non-invasive monitoring compress below five years for optical technologies while extending past seven years for pneumatic blood pressure systems. Procurement committees now segment purchases by interoperability requirements rather than standalone functionality. This reclassification is reshaping vendor qualification criteria across United States integrated delivery networks and German hospital chains.
Product Type:
Upgrade trajectories vary sharply across product categories, with optical devices refreshing every 36-48 months versus electromechanical systems lasting 72-96 months.
- Pulse Oximeters:Photodiode-LED pairs operating at 660-940 nanometers dominate SpO2 capture in fingertip and wrist-worn formats. Demand concentrates in United States home healthcare channels where remote therapeutic monitoring reimbursement codes harden physician prescribing toward ambulatory deployment.
- Blood Pressure Monitors:Oscillometric cuff systems with MEMS pressure sensors remain the clinical standard, though photoplethysmography-based cuffless alternatives are penetrating fitness tracking. Japanese elderly care facilities are piloting 24-hour ambulatory systems for hypertension management.
- Glucometers:Electrochemical strip-based devices face displacement pressure from continuous glucose monitoring patches. Regulatory clearance timelines for non-invasive optical glucose proxies extend past 18 months at FDA.
- Temperature Sensors:Infrared tympanic and temporal artery thermometers serve fever screening in German diagnostic laboratories and Indian primary health centers.
- Respiratory Monitors:Impedance pneumography and acoustic sensing track respiratory rate in sleep analysis applications. Capacitive pressure mats are penetrating Japanese home healthcare for apnea detection.
- ECG Devices:Single-lead patch electrodes and handheld 12-lead systems serve cardiac event monitoring. United States telemedicine providers are unbundling hardware from algorithm subscriptions.
Pulse oximeters sit at the top of the volume ranking, with ECG devices climbing the fastest as patch-based form factors displace Holter monitors.
Technology:
Cost tiers separate clinical-grade validation from consumer-grade estimation, with FDA 510(k) clearance adding 40-60% to module pricing.
- Photoplethysmography:Multi-wavelength optical arrays at 660-940 nanometers capture volumetric blood flow changes for SpO2, heart rate, and blood pressure estimation. Wearable ring and wrist-worn form factors are expanding from fitness tracking into clinical-grade sleep analysis.
- Optical Sensors:Discrete photodiodes and surface-mount LEDs constitute the core sensing layer across pulse oximetry and temperature applications. Taiwan and South Korea manufacturing clusters are creating 14-18 week lead time volatility for module assembly.
- Electrical Impedance:Tetrapolar electrode configurations measure thoracic impedance changes for respiratory rate and fluid status monitoring. German cardiology departments are piloting heart failure surveillance applications.
- Ultrasound Sensors:Continuous-wave Doppler and pulse-echo architectures capture blood flow velocity in peripheral vascular assessment. Japanese manufacturers dominate transducer miniaturization for handheld devices.
- Infrared Sensors:Thermopile and pyroelectric detectors enable non-contact temperature measurement. Demand clusters in fever screening deployments across Indian and Southeast Asian healthcare facilities.
- Capacitive Sensors:Pressure-sensitive mats and textile-integrated electrodes enable unobtrusive sleep and respiration tracking. United States sleep technology startups are integrating these into mattress overlay systems.
Photoplethysmography leads technology volume, with electrical impedance gaining share fastest in heart failure monitoring applications.
Application:
Customer type stratification separates hospital procurement committees seeking predictive algorithms from direct-to-consumer buyers prioritizing convenience.
- Cardiac Monitoring:Atrial fibrillation detection and heart rate variability analysis drive adoption of PPG-ECG fusion devices. United States integrated delivery networks are piloting remote therapeutic monitoring for post-discharge arrhythmia surveillance.
- Sleep Analysis:Polysomnography alternatives using accelerometry and optical sensing are penetrating home diagnostics. Japan's PMDA software-as-a-medical-device classifications are extending approval timelines for foreign entrants.
- Diabetes Management:Continuous glucose monitoring patches and non-invasive optical proxies serve glycemic surveillance. FDA 510(k) predicate limitations for novel glucose algorithms are compressing competitive entry.
- Pulmonary Assessment:Respiratory rate and effort monitoring support COPD and asthma management. German ambulatory care centers are deploying pulse oximetry-impedance fusion systems.
- Fitness Tracking:Consumer-grade heart rate and SpO2 estimation drives wearable volume. Ring-worn form factors from United States and Finnish vendors are displacing wrist-worn devices in sleep-focused segments.
- Fever Detection:Non-contact infrared thermometry serves mass screening in airports, schools, and workplaces. Indian production-linked incentive schemes are attracting contract manufacturing for temperature sensor assembly.
Sleep analysis commands premium pricing, with diabetes management expanding most quickly as non-invasive glucose proxies approach clinical validation.
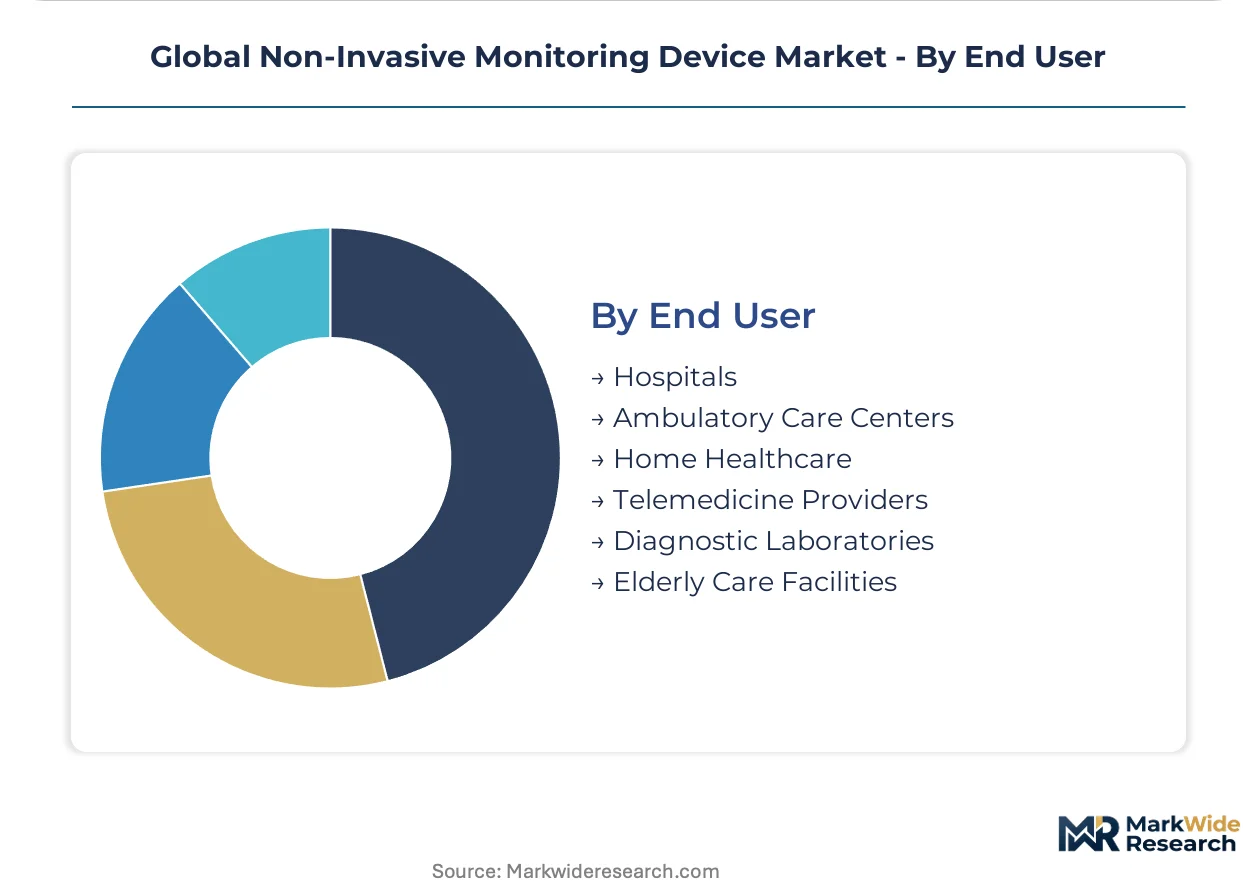
End User:
Supply concentration in optical component manufacturing is forcing end users to qualify secondary sources and extend inventory horizons.
- Home Healthcare:Elderly populations and chronic disease patients drive demand for connected pulse oximetry and blood pressure systems. United States reimbursement codes for remote therapeutic monitoring are hardening prescribing patterns toward ambulatory deployment.
- Hospitals:Acute care settings require multi-parameter patient monitors with FDA 510(k) clearance and HL7 FHIR interoperability. Procurement committees are unbundling hardware from predictive algorithm subscriptions.
- Telemedicine Providers:Virtual care platforms distribute pulse oximeters and blood pressure cuffs for remote physiological surveillance. Data integration gaps with Epic Systems electronic health records are fragmenting workflows.
- Ambulatory Care Centers:Same-day surgical and diagnostic facilities deploy portable monitoring for pre-operative assessment and recovery. German outpatient cardiology practices are adopting cuffless blood pressure systems.
- Diagnostic Laboratories:Pre-analytical patient screening and vital sign capture support test workflow efficiency. Temperature sensors and pulse oximeters constitute standard equipment across Indian and Southeast Asian lab networks.
- Elderly Care Facilities:Continuous surveillance for fall risk, sleep disruption, and cardiovascular events drives sensor deployment. Japanese domestic manufacturers are leveraging PMDA inspection friction to defend procurement relationships against foreign entrants.
Home healthcare leads end-user volume, with telemedicine providers climbing fastest as virtual care platforms scale remote monitoring infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing cost differentials are pulling assembly operations toward jurisdictions with streamlined medical device regulations. FDA 510(k) pathways and EU MDR compliance timelines create arbitrage opportunities for contract manufacturers qualifying under India's PLI scheme or Japan's PMDA inspection protocols.
United States
Remote therapeutic monitoring reimbursement codes harden physician prescribing toward ambulatory pulse oximetry and blood pressure systems. FDA 510(k) premarket notification requirements govern device clearance timelines, with predicate device strategies accelerating for optical glucose proxies. Boston and Minneapolis medical technology clusters concentrate cardiac monitoring R&D and regulatory consulting services.
Germany
Hospital procurement committees unbundle device hardware from predictive algorithm subscriptions across integrated delivery networks. EU MDR clinical evidence requirements and CE marking frameworks enforce retrospective validation studies for photoplethysmography-based arrhythmia detection. The Eindhoven-Düsseldorf corridor hosts notified bodies and optical sensor distribution hubs serving Benelux markets.
Japan
PMDA quality management system inspections extend factory audit timelines by 4-6 months for foreign manufacturers seeking device approval. Domestic manufacturers leverage this regulatory friction to defend hospital procurement relationships against US and European entrants. Osaka-based specialists dominate transducer miniaturization for handheld ultrasound devices.
India
Production-linked incentives targeting 5-25% value addition attract contract manufacturing relocation for pulse oximetry and blood pressure monitor assembly. CDSCO medical device rules align with IMDRF guidelines while permitting accelerated market entry for Class A and B devices. Tamil Nadu and Karnataka electronics manufacturing clusters scale optical sensor module assembly for export markets.
South Korea
Discrete photodiode and LED sourcing clusters create 14-18 week lead time volatility for pulse oximetry module assembly across global supply chains. MFDS quality system requirements parallel FDA structure while permitting abbreviated review for predicate-eligible devices. Seoul-based component suppliers anchor optical sensor supply for ring-worn and wrist-worn form factors.
Global Non-Invasive Monitoring Device Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with clinical-grade validation commanding 40-60% pricing premiums over consumer-tier alternatives. The vendor base concentrates around diversified health technology conglomerates and optical sensor pure-plays. Three archetypes dominate: cardiac-to-home transition specialists, sleep and respiratory tracking leaders, and component-level sensor architects. Competitive moves center on M&A for algorithm capabilities and strategic partnerships with telemedicine platforms.
Within the diversified health technology tier, Medtronic plc, Koninklijke Philips N.V., and Masimo Corporation exemplify contrasting strategic positions. Medtronic anchors cardiac monitoring portfolio breadth. Philips occupies technology leadership in sleep analysis and respiratory tracking. Masimo represents optical sensor architecture specialization that dominates pulse oximetry standards. These three entities illustrate how vertical scope choices—device-only versus platform-integrated versus component-focused—determine margin capture and customer access points across hospital, home healthcare, and consumer channels.
| Leading Market Players |
|---|
| Medtronic plc |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Abbott Laboratories |
| Siemens Healthineers AG |
| Masimo Corporation |
| Nihon Kohden Corporation |
| Hill-Rom Holdings |
| Omron Corporation |
| Others |
Supply & Pricing Matrix
United States integrated delivery network unbundling of hardware from algorithm subscriptions is forcing module suppliers to absorb upfront margin compression while extending revenue recognition across multi-year service terms. This procurement shift compels Taiwanese and South Korean optical component manufacturers to qualify secondary fabrication sources and extend inventory horizons, transmitting cost volatility through pulse oximetry and blood pressure monitor assembly tiers.
Pricing Analysis
Retailer markup layers in pharmacy diagnostic kiosk networks and direct-to-OEM volume discounts for hospital procurement committees define the dominant pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared clinical-grade modules from consumer-tier fitness tracking alternatives, with certification level and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from remote therapeutic monitoring reimbursement code recalibration compressing ambulatory device budgets. Home healthcare channels exhibit highest price sensitivity, while acute care settings prioritize interoperability premiums over unit cost.
Supply Chain Analysis
FDA 510(k) and EU MDR quality system certifications gate supplier qualification, extending onboarding timelines for foreign manufacturers seeking entry into United States and German hospital procurement channels. Discrete photodiode and LED sourcing draws from Taiwan, South Korea, and China's manufacturing clusters, with MEMS pressure sensors and lithium-ion cells as critical co-dependencies. Single-source vulnerability concentrates in 660-940 nanometer optical array fabrication. Distribution runs through medical device distributors, GPO contracts, and direct telemedicine platform integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily through chronic disease prevalence expansion and home healthcare channel hardening, with reimbursement framework evolution providing durable demand tailwinds across elderly populations.
For Market Incumbents: Anticipate algorithm-enabled diagnostic software classification proliferation by accelerating retrospective clinical study investment for photoplethysmography-based arrhythmia detection. Deepen backward integration into optical sensor module assembly through India's PLI scheme to offset Taiwan and South Korea lead time volatility. Priority defensive moves center on HL7 FHIR interoperability certification and predictive analytics subscription retention. For New Entrants and Emerging Players: Capture continuous glucose monitoring proxy white space adjacent to diabetic populations, where FDA 510(k) predicate limitations compress incumbent competitive entry. Pharmacy retail diagnostic kiosk networks offer the most penetrable channel, with machine learning inference capabilities as the critical go-to-market differentiator against hardware-centric legacy vendors. For Investors and Strategic Acquirers: Asymmetric upside sits with optical sensor pure-plays possessing multi-wavelength photoplethysmography patent estates and software-as-a-medical-device regulatory clearance pathways. Long-term viability frames around 5-10 year chronic disease management infrastructure buildout. Watch for reimbursement code expansion for non-invasive metabolic monitoring as the definitive demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Predicate device strategies compress clearance timelines for optical glucose proxies ahead of metabolic monitoring reimbursement expansion. |
| EU MDR Notified Body Engagement | Clinical evidence preparation across Germany and Netherlands secures CE marking continuity through 2027 renewal deadlines. |
| Hospital System Partnership | Epic Systems electronic health records integration contracts lock in remote patient monitoring workflow placement against fragmented competitors. |
| Software Companion Development | Predictive algorithm unbundling from hardware enables 36-month recurring revenue recognition across United States integrated delivery networks. |
| Reimbursement Strategy | Remote therapeutic monitoring code optimization hardens physician prescribing patterns toward ambulatory pulse oximetry deployment. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and telemedicine platform executives with secondary validation against FDA 510(k) filings, EU MDR notified body registries, CMS Medicare reimbursement databases, and hospital procurement records. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity across product type, technology, application, and end-user dimensions.
Input-output matrices map optical sensor module production through pulse oximetry and blood pressure monitor assembly to channel distribution, with volume and value outputs derived across the projection horizon through modeled interaction of technology adoption curves, regulatory clearance timelines, and reimbursement code evolution. Segmentation dimensions span device category, sensing modality, clinical versus consumer application, and procurement channel type. CAGRs emerge from fitted growth trajectories calibrated against historical replacement cycle patterns and interoperability requirement diffusion.
Regulatory clearance delays, reimbursement code recalibration, and optical component supply disruption are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around predicate device pathway availability and notified body capacity constraints. A model refresh is warranted upon material change in FDA artificial intelligence-enabled diagnostic software guidance or EU MDR clinical evidence requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
Medical Telemetry Market
Patient Monitoring
Respiratory Gas Monitors Market
Patient Monitoring
United Kingdom Remote Patient Monitoring Market
Patient Monitoring
Global Multi-Parameter Patient Monitoring Equipment Market
Patient Monitoring
Global Patient Positioning System Market
Patient Monitoring
Respiratory Monitoring Market
Patient Monitoring
Health Sensors Market
Patient Monitoring
South America Respiratory Monitoring Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market
Patient Monitoring
Hemoglobin Monitor Market
Patient Monitoring
Home Care Monitoring and Diagnostics Market
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market
Patient Monitoring
Global Body Temperature Monitoring Market