
 Neuro-Monitoring System Market | 2026-2036
Neuro-Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Neuro-Monitoring System Market Foresight
Equipment leasing and pay-per-use service models are narrowing the competitive field in neuro-monitoring. Medtronic leverages its integrated surgical ecosystem to bundle monitoring hardware with navigation platforms. Natus Medical anchors its position through specialized EEG and sleep diagnostic portfolios. NuVasive competes by dominating intraoperative neurophysiological monitoring for spine procedures.
A neuro-monitoring system captures, amplifies, and records electrical or magnetic signals from the central and peripheral nervous systems, typically sampling neural activity at 256–1024 Hz with 16–128 channel configurations for clinical-grade EEG or evoked potential measurement. These systems serve primarily to detect intraoperative nerve injury, localize epileptogenic foci, and quantify cognitive function loss after cerebrovascular events. EEG Systems and LTM Solutions occupy the largest installed base due to decades of clinical validation in epilepsy units, while fMRI Devices command premium pricing tied to hospital capital budgets and radiology workflow integration. Wearable Sensors and Cloud-Based Systems represent the fastest-expanding technology layer as ambulatory monitoring and remote interpretation reduce dependency on fixed infrastructure.
FDA premarket notification requirements and EU MDR technical documentation obligations shape product development timelines and market access costs for manufacturers selling into the United States and European Union. Japan's PMDA enforces JIS-compatible electromagnetic compatibility standards that add localization overhead for imported systems. Stakeholders must track how reimbursement codes for remote neuro-monitoring evolve against clinical evidence requirements for cloud-connected diagnostic platforms.
Market Dynamics
Equipment leasing and pay-per-use service models are compressing capital deployment cycles for neuro-monitoring hardware, forcing manufacturers to restructure revenue recognition around recurring service streams rather than upfront device sales.
Growth Catalysts
- EU MDR CE marking pathways:Tightened technical documentation requirements for EEG and intraoperative systems are accelerating quality differentiation, rewarding manufacturers with robust clinical validation dossiers.
- Epilepsy unit expansion:Hospitals in the United States are scaling long-term monitoring bed capacity to address surgical candidacy backlogs, directly lifting system procurement volumes.
- Cloud-connected diagnostic platforms:Remote interpretation capabilities are reducing neurologist staffing constraints in underserved regions, extending addressable market reach beyond tertiary centers.
Market Restraints
- High-performance analog front-end component concentration:Precision amplifiers and isolated power supplies for clinical-grade EEG rely on a concentrated supplier base in East Asia, exposing manufacturers to input cost volatility and lead time extension.
- FDA premarket notification timelines:510(k) clearance pathways for novel signal processing algorithms impose documentation burdens that stretch product launch schedules and freeze R&D capital.
- fMRI capital budget competition:Hospital radiology departments prioritize scanner upgrades over dedicated neuro-monitoring infrastructure, limiting standalone system penetration in budget-constrained environments.
Strategic Opportunities
- Ambulatory seizure monitoring in Germany:Reimbursement frameworks for take-home EEG systems remain underdeveloped relative to inpatient coverage, creating first-mover advantage for platform providers that secure statutory health insurance recognition.
- AI-assisted spike detection:Machine learning algorithms trained on institutional datasets are converging with wearable sensor hardware to automate epileptogenic focus localization, compressing specialist interpretation burden.
- Subscription-based remote monitoring:Neurology practices are piloting per-patient-month service models that bundle hardware, cloud storage, and overread services, displacing capital purchase decision-making.
Industry Challenges
- Clinical neurophysiologist workforce scarcity:Fellowship-trained specialists capable of intraoperative monitoring interpretation are concentrated in academic medical centers, constraining service expansion into community hospital settings.
- Legacy EMR integration complexity:Proprietary data formats from established EEG vendors require costly middleware development to achieve seamless flow into hospital electronic medical record systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuro-Monitoring System Market |
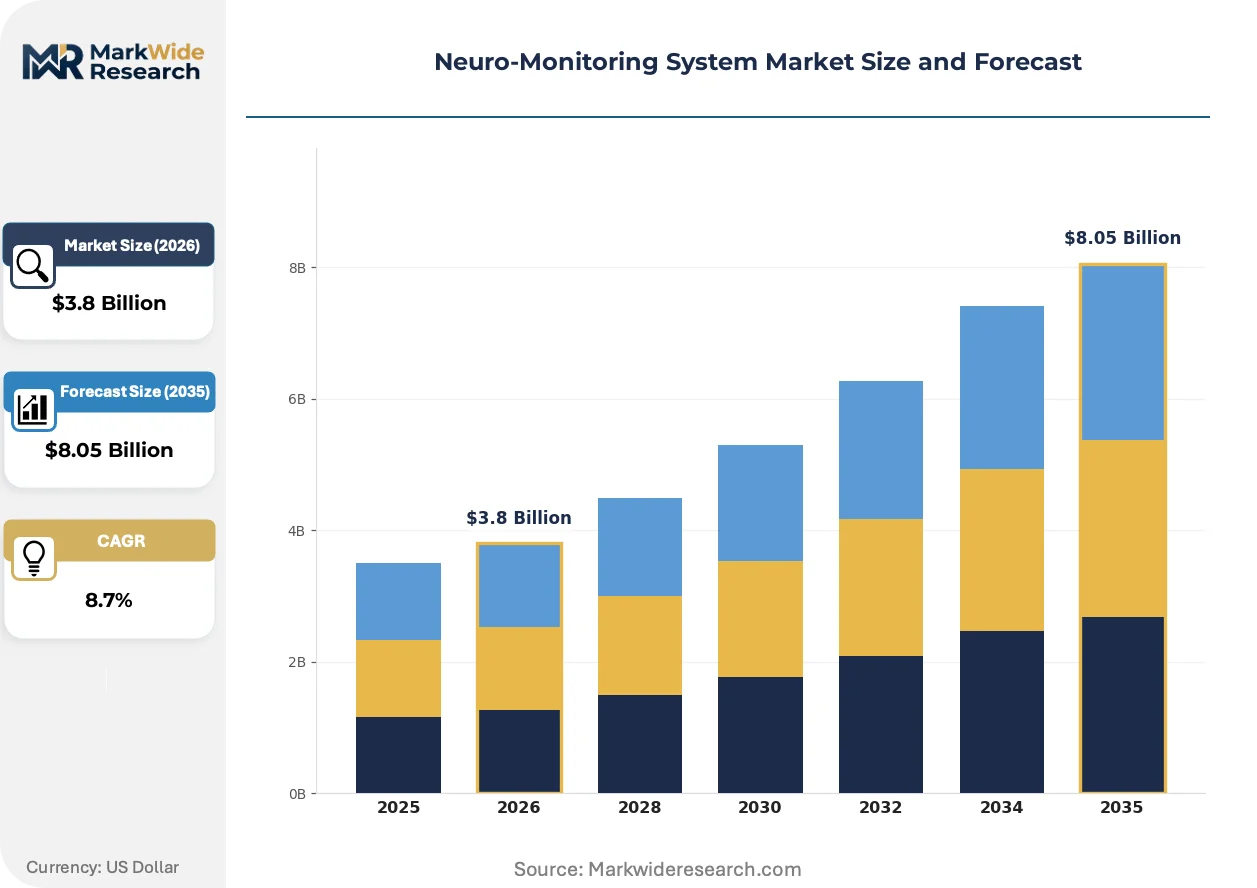
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EEG Systems, fMRI Devices, LTM Solutions, MEG Systems Application: Epilepsy Monitoring, Stroke Diagnosis, Sleep Studies, Cognitive Assessment End User: Hospitals, Research Institutions, Diagnostic Centers, Rehabilitation Facilities Technology: Wearable Sensors, Cloud-Based Systems, Real-Time Monitoring, Neurofeedback Devices |
| Companies Covered | Medtronic, Natus Medical, NuVasive, Inomed Medizintechnik GmbH, Nihon Kohden, Cadwell Industries, Checkpoint Surgical, SpecialityCare, Biotronic NeuroNetwork, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuro-Monitoring System Market Shifts & Advancements
Wearable dry-electrode arrays and edge-computing architectures are dissolving the boundary between inpatient and ambulatory neuro-monitoring, enabling continuous neural signal capture outside traditional clinical infrastructure.
Dry-electrode EEG headsets with active noise cancellation circuitry are hybridizing signal acquisition methods previously restricted to gel-based laboratory setups. Community neurology practices are piloting these devices for routine diagnostic workups, collapsing the cost and preparation time differential between office-based and hospital-grade recordings. This convergence is compressing referral patterns and redirecting diagnostic volume away from centralized epilepsy monitoring units.
FDA guidance on clinical decision support software is tightening algorithm validation requirements for AI-assisted EEG interpretation tools. Manufacturers must now submit prospective clinical performance data for predicate device comparisons, elevating development costs and extending regulatory timelines. Cloud-based platform providers with existing 510(k) clearances are responding by acquiring complementary algorithm developers to fortify their regulatory dossiers.
Hospital procurement committees are unbundling after-sales service contracts from hardware acquisitions, forcing vendors to compete on discrete maintenance, training, and software update pricing. This disintermediation is most pronounced in the United States, where health system consolidation has concentrated purchasing leverage within centralized value analysis committees. Equipment suppliers are countering margin compression by introducing outcome-guarantee clauses tied to monitoring uptime and interpretation turnaround metrics.
Neuro-Monitoring System Market Segmentation
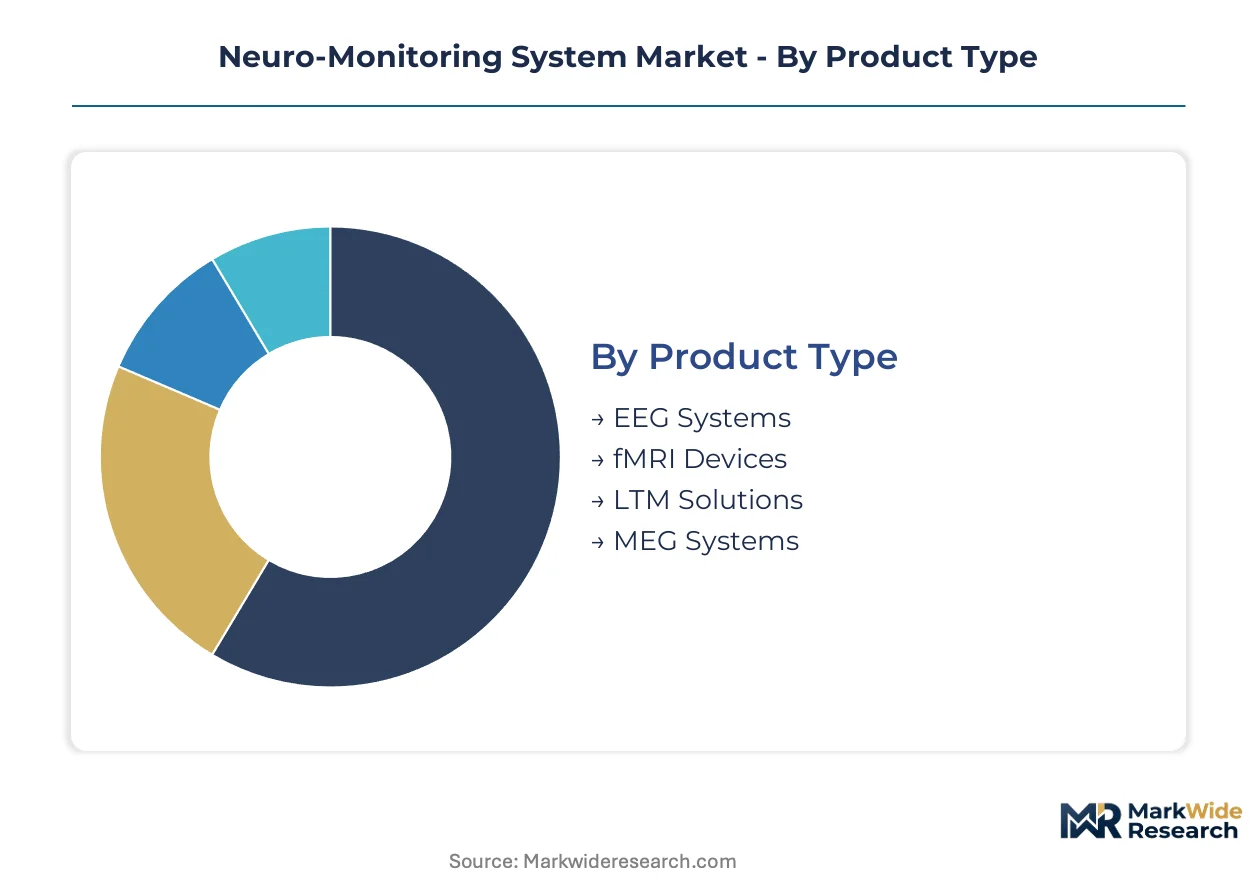
Neuro-monitoring systems fragment across multiple technical and commercial dimensions. Product architecture, clinical use case, and delivery technology each dictate distinct procurement patterns and margin structures.
Product Type:
Cost tier determines capital deployment cycles and service revenue attachment rates across hardware categories.
- EEG Systems:Electroencephalography platforms sample neural activity at 256–1024 Hz through 16–128 channel configurations. Demand concentrates in United States epilepsy units addressing surgical candidacy backlogs, with procurement lifting as hospitals expand long-term monitoring bed capacity.
- fMRI Devices:Functional magnetic resonance imaging systems command premium pricing tied to radiology department capital budgets. Hospital administrators in Germany prioritize scanner upgrades over dedicated neuro-monitoring infrastructure, constraining standalone system penetration.
- LTM Solutions:Long-term monitoring systems extend EEG capability for continuous inpatient observation.
- MEG Systems:Magnetoencephalography devices capture magnetic field fluctuations from neural activity.
EEG Systems hold installed capacity. fMRI Devices is rotating up the share rankings.
Application:
Clinical volume and reimbursement density vary sharply by neurological condition addressed.
- Epilepsy Monitoring:Seizure focus localization and surgical candidacy assessment drive the highest procedure volume. United States tertiary centers are scaling monitoring bed capacity, while German statutory health insurance frameworks for ambulatory coverage remain underdeveloped.
- Stroke Diagnosis:Cerebrovascular event quantification commands acute care investment. Japanese hospitals deploy continuous monitoring for cognitive function loss assessment, constrained by PMDA electromagnetic compatibility localization requirements.
- Sleep Studies:Polysomnography and nocturnal seizure detection applications.
- Cognitive Assessment:Neuropsychological function evaluation for dementia and traumatic injury.
Epilepsy Monitoring dominates procedure throughput. Stroke Diagnosis is climbing the fastest on acute care prioritization.
End User:
Customer type dictates purchasing authority, integration complexity, and service contract structure.
- Hospitals:Acute care and academic medical centers command the largest procurement volumes. United States health system consolidation has concentrated purchasing leverage within centralized value analysis committees, forcing vendors to unbundle after-sales service contracts.
- Research Institutions:Academic and government laboratories drive technology validation. FDA 510(k) clearance pathways for novel signal processing algorithms impose documentation burdens that stretch product launch schedules for suppliers targeting this channel.
- Diagnostic Centers:Outpatient neurology practices and specialized testing facilities.
- Rehabilitation Facilities:Post-acute and long-term care settings for recovery monitoring.
Hospitals anchor procurement volume. Research Institutions are gaining share on clinical validation requirements.
Technology:
Maturity of delivery architecture separates fixed infrastructure from distributed, service-based deployment models.
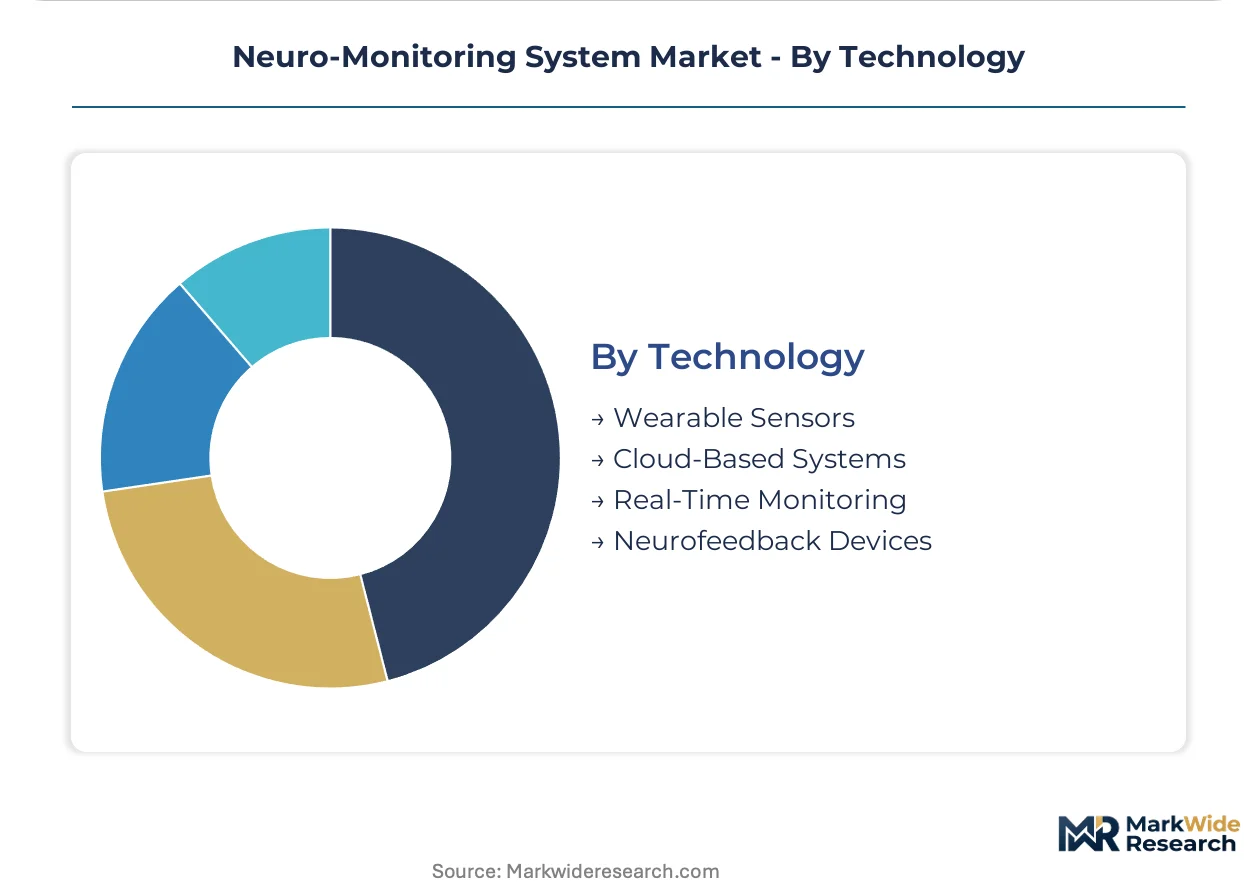
- Wearable Sensors:Dry-electrode arrays with active noise cancellation circuitry collapse preparation time differentials between office-based and hospital-grade recordings. Community neurology practices in the United States are piloting these for routine diagnostic workups, redirecting volume from centralized epilepsy units.
- Cloud-Based Systems:Remote interpretation platforms reduce neurologist staffing constraints in underserved regions. FDA guidance on clinical decision support software is tightening algorithm validation requirements, elevating development costs for platform providers.
- Real-Time Monitoring:Continuous signal processing for intraoperative and intensive care applications.
- Neurofeedback Devices:Closed-loop systems for therapeutic intervention and training.
Wearable Sensors command emerging technology premiums. Cloud-Based Systems are expanding most quickly on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for precision analog front-end components concentrates supply risk in East Asian manufacturing clusters, while finished system exports flow disproportionately toward North American and European hospital networks. Trade balances favor component-importing assemblers over raw material exporters.
United States
Epilepsy monitoring unit expansion drives capital deployment across tertiary care networks, with academic medical centers scaling long-term monitoring bed capacity to address surgical candidacy backlogs. FDA 510(k) premarket notification requirements impose documentation burdens that stretch product launch schedules for novel signal processing algorithms. The Boston-Cambridge corridor anchors neurotechnology R&D concentration, with Massachusetts General Hospital and Brigham and Women's Hospital piloting cloud-connected diagnostic platforms.
Germany
Statutory health insurance frameworks for ambulatory EEG coverage remain underdeveloped relative to inpatient reimbursement, creating first-mover opportunity for platform providers securing recognition. EU MDR CE marking pathways enforce tightened technical documentation obligations that accelerate quality differentiation among manufacturers. The Munich-Stuttgart medical technology cluster hosts specialized EEG and intraoperative system engineering, with Siemens Healthineers and Brainlab adjacent to component supply chains.
Japan
PMDA electromagnetic compatibility standards enforce JIS-compatible localization requirements that add overhead for imported neuro-monitoring systems. Stroke diagnosis applications command acute care investment, with Japanese hospitals deploying continuous monitoring for cognitive function loss assessment. The Tokyo-Osaka corridor concentrates neurosurgical volume and reimbursement density, while regional hospitals face neurologist staffing constraints that remote interpretation platforms target.
China
NMPA registration pathways for Class II and III medical devices impose clinical trial requirements that extend market access timelines for foreign manufacturers. Domestic hospital procurement committees prioritize cost-competitive EEG systems for epilepsy unit construction in tier-2 and tier-3 cities. The Shanghai-Suzhou medical device manufacturing belt hosts contract assemblers for precision amplifiers and isolated power supplies, though high-performance analog components remain import-dependent.
India
CDSCO medical device rules under the Drugs and Cosmetics Act require registration for neuro-monitoring systems above specified risk classifications, with notified body audits adding compliance overhead. Diagnostic center expansion in metropolitan corridors drives demand for portable EEG and sleep study equipment. The Bangalore-Hyderabad medtech cluster hosts emerging domestic manufacturers targeting price-sensitive ambulatory monitoring segments with simplified hardware configurations.
Neuro-Monitoring System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision analog front-ends and isolated power supplies. The vendor base organizes around three archetypes: diversified surgical ecosystem bundlers, specialized diagnostic portfolio anchors, and spine-focused intraoperative monitoring specialists. Consolidation pressure concentrates among mid-scale equipment lessors seeking recurring service revenue attachment. Dominant competitive moves include strategic partnerships with cloud platform providers and backward integration into sensor hardware manufacturing.
Within the diversified surgical ecosystem tier, Medtronic exemplifies platform bundling strategy, while Natus Medical occupies the specialized diagnostic anchor position. NuVasive represents the spine-procedure-focused archetype. Inomed Medizintechnik GmbH and Nihon Kohden sit within regional manufacturing clusters serving European and Asian hospital procurement networks respectively. These five entities collectively illustrate how competitive positioning diverges between capital equipment vendors restructured around service revenue and component suppliers defending analog performance specifications.
| Leading Market Players |
|---|
| Medtronic |
| Natus Medical |
| NuVasive |
| Inomed Medizintechnik GmbH |
| Nihon Kohden |
| Cadwell Industries |
| Checkpoint Surgical |
| SpecialityCare |
| Biotronic NeuroNetwork |
| Others |
Supply & Pricing Matrix
Undercapacity in precision analog front-end manufacturing across East Asian foundries is compressing component availability and amplifying pricing leverage for suppliers serving EEG and intraoperative system assemblers. This utilization squeeze simultaneously elevates input costs for manufacturers and tightens procurement timelines for hospital buyers.
Pricing Analysis
Industrial OEM buyers anchor subscription-based service models that bundle hardware, cloud storage, and interpretation services. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared platforms with algorithm validation from CE-marked systems and unvalidated imports. Cost compression in standard-tier equipment is intensifying because health system consolidation concentrates purchasing leverage within centralized value analysis committees. Community hospitals exhibit highest price sensitivity, while academic medical centers prioritize clinical validation over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for precision amplifier sourcing. Component manufacturing concentrates in Taiwan, South Korea, and Japan, while final assembly clusters in Germany and the United States. Isolated power supplies, dry-electrode arrays, and signal processing chips draw from this concentrated base. Single-source vulnerability persists for clinical-grade analog front-ends. Distribution runs through hospital procurement committees and specialized medical device distributors serving tertiary care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through capital expenditure recovery as hospital epilepsy unit expansion accelerates procurement velocity. Equipment leasing adoption signals the upswing phase.
For Market Incumbents: Build regulatory data moats by acquiring FDA-cleared algorithm developers to fortify 510(k) dossiers against tightening clinical decision support guidance. Deepen backward integration into sensor hardware manufacturing to defend margin position against analog component cost volatility. Cloud platform providers without predicate device clearances face existential threat from consolidated competitors with validated algorithm portfolios. For New Entrants and Emerging Players: Establish a beachhead in ambulatory seizure monitoring for German statutory health insurance recognition before reimbursement frameworks mature. Target wearable dry-electrode arrays for community neurology practices seeking to redirect diagnostic volume from centralized epilepsy units. Partner with existing cloud infrastructure providers to bypass multi-year FDA validation timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across subscription-based remote monitoring platforms as recurring service revenue displaces upfront hardware sales. Five-to-ten-year viability favors platform integrators with bundled surgical ecosystem offerings over standalone hardware vendors. Acquisition target archetype: mid-scale equipment lessors with installed base conversion potential. Monitor FDA 510(k) clearance velocity for AI-assisted EEG interpretation tools as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation obligations reward manufacturers with robust clinical validation dossiers. |
| Hospital System Partnership | Academic medical center alliances secure long-term monitoring bed capacity expansion contracts. |
| Software Companion Development | Cloud-connected diagnostic platforms reduce neurologist staffing constraints in underserved regions. |
| Reimbursement Strategy | German statutory health insurance recognition for ambulatory EEG creates first-mover advantage. |
| Acquisition of Specialist Firm | Algorithm developers with prospective clinical performance data fortify regulatory dossiers. |
Research Methodology
Operator-level perspectives from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and clinical neurophysiologists anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up equipment shipment tracking and top-down capital expenditure analysis provided triangulation across the analysis window.
Scenario-bracketing framed projections across product architecture, clinical application, end-user type, and technology delivery model. CAGRs derived from segmented volume trajectories and pricing evolution assumptions throughout the forecast period. Epilepsy surgical candidacy backlogs, cloud platform subscription attach rates, and analog component lead time volatility served as industry-specific forecast inputs.
Stress conditions across FDA premarket notification timelines, EU MDR CE marking pathway duration, and East Asian component supply continuity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement framework evolution and health system consolidation velocity. Material shifts in FDA guidance on clinical decision support software validation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Drowsiness Monitoring System Market
Patient Monitoring
Remote Home Monitoring Systems Market
Patient Monitoring
Cardiopulmonary Exercise Testing Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Brain Monitoring Systems Market
Patient Monitoring
Remote Patient Monitoring Devices Market
Patient Monitoring
Coronary Pressure Monitors Market
Patient Monitoring
Gas Exchange Monitor Market
Patient Monitoring
Europe Biomedical Sensors Market
Patient Monitoring
Global Biomedical Sensor Market
Patient Monitoring
Germany Patient Monitoring Market
Patient Monitoring
North America Hemodynamic Monitoring Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
B-Ketone Monitoring System Market
Patient Monitoring
Global Epilepsy Monitoring Devices Market
Patient Monitoring
Europe Wireless Healthcare Market