
 UAE Patient Monitoring Equipment Market | 2026-2036
UAE Patient Monitoring Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Patient Monitoring Equipment Market Analytics
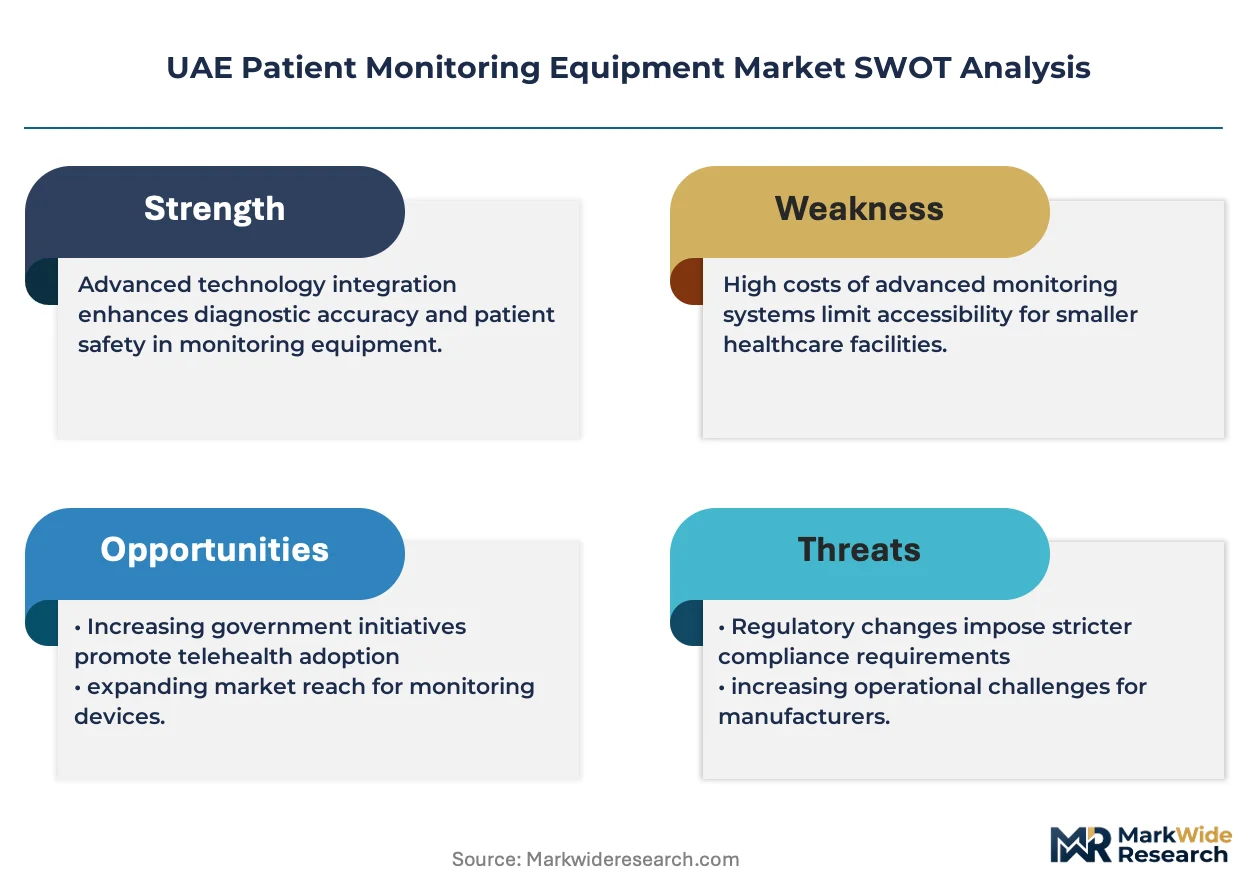
The UAE Green Agenda 2030 is pivoting hospital procurement toward energy-efficient, digitally integrated monitoring infrastructure. Koninklijke Philips NV leverages its Middle East distribution hub to sustain service contracts across Dubai Health Authority facilities. Abbott Laboratories anchors its position through localized calibration laboratories in Abu Dhabi. GE Healthcare differentiates via AI-enabled alarm management systems tailored to MOHAP workflow protocols.
Patient monitoring equipment encompasses devices that acquire, process, and display physiological parameters including ECG waveforms, SpO2 levels, non-invasive blood pressure, and respiratory rate with sampling frequencies typically exceeding 250 Hz for cardiac channels. These systems serve primarily to detect hemodynamic instability, arrhythmia onset, and respiratory depression in acute care settings before clinical deterioration escalates. Cardiac monitors command the largest installed base across UAE tertiary hospitals due to perioperative protocol density and cath lab expansion. Wireless technology segments expand fastest as Ministry of Health and Prevention (MOHAP) pushes real-time data integration into national electronic health record architecture. Hemodynamic monitors concentrate margin pools in high-acuity ICU deployments where disposable transducer sales recur predictably.
MOHAP device registration requirements and UAE.S GSO standards govern electromagnetic compatibility, cybersecurity hardening, and clinical alarm safety for all imported monitoring systems. The Emirates Authority for Standardization and Metrology (ESMA) enforces post-market surveillance obligations that lengthen vendor qualification timelines but elevate barrier to entry for uncertified manufacturers. Stakeholders must track how federal insurance mandate expansions into remote patient monitoring reimbursement reshape capital-versus-operating expenditure decisions among private hospital operators.
Market Dynamics
MOHAP's digitization mandates for inpatient tracking are compressing procurement cycles across Abu Dhabi and Dubai hospital networks, forcing vendors to pre-integrate with national electronic health record architecture before contract eligibility.
Growth Catalysts
- MOHAP Interoperability Mandates:Federal requirements for real-time data integration into national EHR systems are pulling wireless telemetry upgrades across Dubai's ambulatory surgery centers.
- Cath Lab Expansion:Tertiary hospital construction in Abu Dhabi is multiplying perioperative protocol density and cardiac monitor installation baselines.
- Remote Patient Monitoring:Federal insurance mandate expansions into RPM reimbursement are converting capital expenditure models toward recurring service frameworks among private operators.
Market Restraints
- ESMA Post-Market Surveillance:Extended vendor qualification timelines for electromagnetic compatibility and cybersecurity hardening elevate working capital requirements for importers.
- Disposable Transducer Dependency:Hemodynamic monitor margin concentration in high-acuity ICUs creates recurring supply vulnerability to polymer resin price volatility.
- Wireless Spectrum Congestion:2.4 GHz and 5 GHz band saturation in dense clinical environments generates signal interference risks for telemetry-dependent workflows.
Strategic Opportunities
- Ras Al Khaimah Healthcare Investment:Northern emirate medical city developments present greenfield deployment potential outside saturated Dubai-Abu Dhabi corridors.
- AI-Enabled Alarm Management:Machine learning integration with MOHAP workflow protocols offers differentiation where clinical alarm fatigue reduction commands premium positioning.
- Home-Based Acute Monitoring:Post-discharge hemodynamic surveillance contracts align with insurance mandate expansions and reduce hospital readmission penalties.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Specialized calibration and maintenance expertise for multi-parameter monitor suites concentrates in Dubai and Abu Dhabi, constraining rural facility uptime.
- Legacy Device Integration:Pre-digital bedside monitors in established hospital networks require middleware layers that inflate total cost of ownership and complicate cybersecurity hardening.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Patient Monitoring Equipment Market |
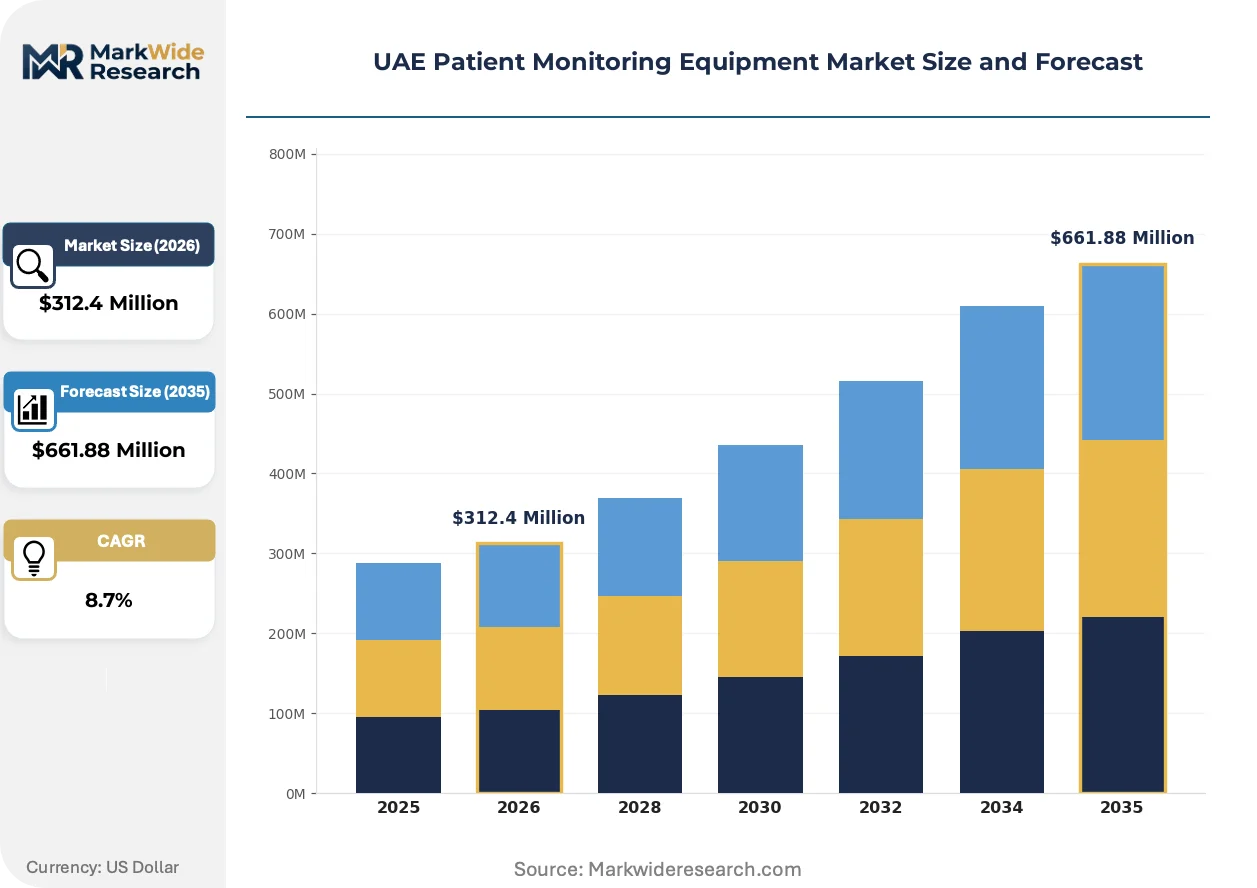
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Monitors, Respiratory Monitors, Neurological Monitors, Hemodynamic Monitors End User: Hospitals, Clinics, Home Care, Emergency Services Technology: Wireless, Portable, Wearable, Standalone Application: Chronic Disease Management, Post-operative Care, Emergency Care, Remote Monitoring |
| Companies Covered | Medtronic Care Management Services LLC, Becton Dickinson and Company, Abbott Laboratories, Boston Scientific Corporation, Baxter International Inc, Koninklijke Philips NV, Omron Corporation, Siemens Healthineers, GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Patient Monitoring Equipment Market Evolving Landscape
Wireless telemetry architectures are displacing hardwired bedside configurations across UAE acute care facilities, while regulatory pressure on data sovereignty and AI validation protocols is reshaping vendor qualification requirements.
Multi-parameter patient monitoring platforms are consolidating previously discrete cardiac, respiratory, and hemodynamic acquisition into unified acquisition modules with centralized alarm management. Dubai Health Authority facilities are piloting these integrated suites in step-down units ahead of mandated rollout timelines. This consolidation is compressing vendor count per hospital network and elevating service contract values for integrated platform providers.
UAE.S GSO standards for electromagnetic compatibility and clinical alarm safety are tightening post-market surveillance obligations through ESMA enforcement channels. Imported monitoring systems now require documented cybersecurity hardening protocols before registration approval. Cardiac monitor suites face the steepest compliance burden due to their installed base density and cath lab integration complexity.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, creating discrete competitive arenas for technical service providers. Dubai's private hospital operators are leading this separation, driven by MOHAP pressure to demonstrate lifecycle cost transparency. Abu Dhabi-based networks are following with 12-18 month lag, particularly where SEHA procurement frameworks apply.
UAE Patient Monitoring Equipment Market Segmentation
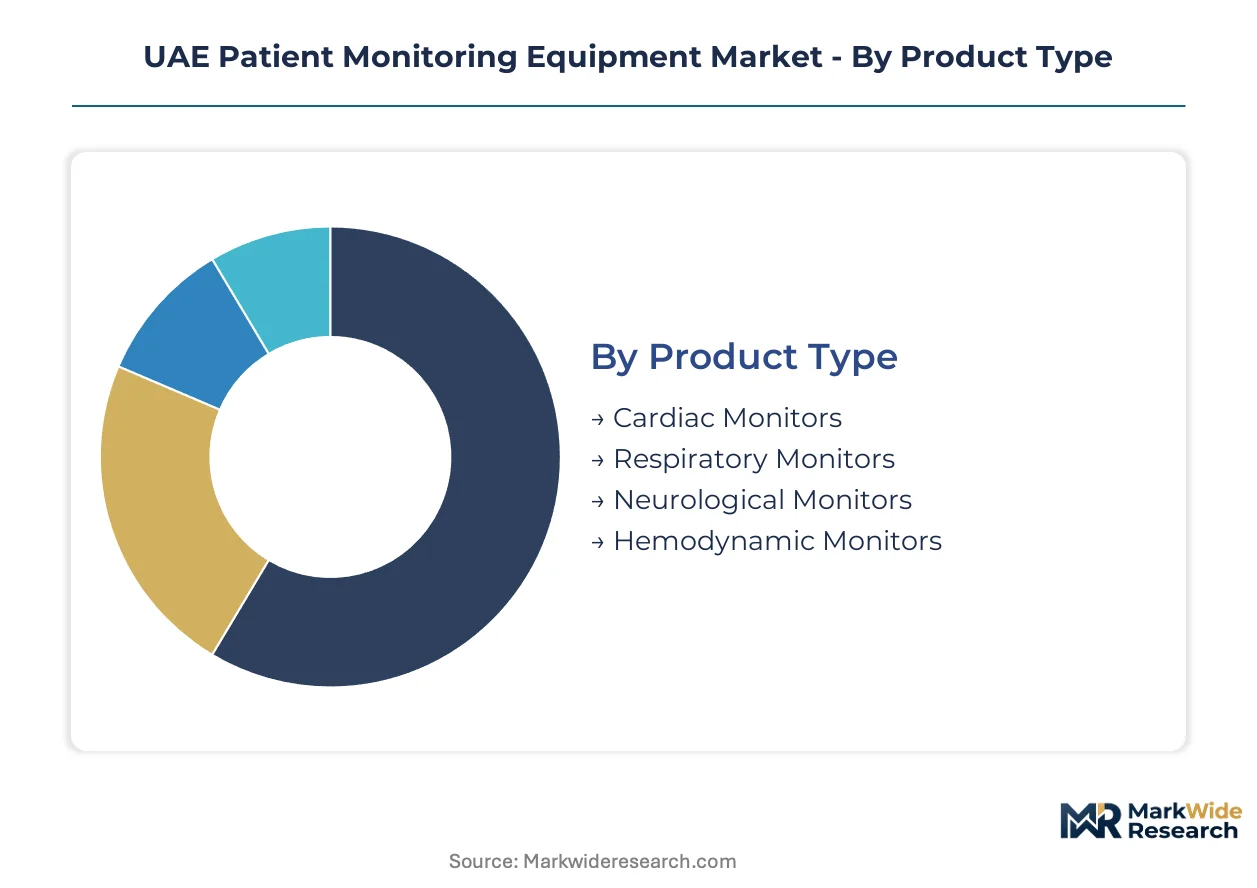
Segmentation in UAE patient monitoring equipment reveals how procurement decisions bifurcate between high-acuity institutional deployments and distributed ambulatory networks. Each dimension—product, end-user, technology, and application—carries distinct margin structures and regulatory compliance burdens that reshape vendor positioning.
Product Type:
Supply concentration in cardiac and hemodynamic monitor manufacturing creates procurement bottlenecks for UAE hospital networks seeking localized service coverage.
- Cardiac Monitors:Multi-parameter systems acquire ECG waveforms at sampling frequencies exceeding 250 Hz with arrhythmia detection algorithms embedded. Demand concentrates in Abu Dhabi tertiary hospitals where SEHA procurement frameworks mandate cath lab integration and perioperative protocol density drives installation baselines.
- Hemodynamic Monitors:Invasive pressure transduction systems measure arterial, central venous, and pulmonary artery pressures through disposable transducer sets. High-acuity ICUs in Dubai Health Authority facilities generate recurring consumable revenue streams where polymer resin price volatility threatens margin stability.
- Respiratory Monitors:Capnography and spirometry systems track end-tidal CO2 and ventilatory mechanics.
- Neurological Monitors:EEG and intracranial pressure systems serve neurocritical care units with specialized calibration requirements.
Today's leader: Cardiac Monitors. Tomorrow's challenger: Hemodynamic Monitors.
End User:
Cost tier stratification separates capital-intensive hospital deployments from recurring-revenue home care models reshaping UAE reimbursement frameworks.
- Hospitals:Tertiary and secondary acute care facilities command the largest installed base with centralized biomedical engineering departments handling multi-vendor maintenance. Dubai and Abu Dhabi networks absorb premium pricing for integrated platform suites where MOHAP digitization mandates compress replacement cycles.
- Home Care:Post-discharge hemodynamic and cardiac surveillance systems operate on subscription service frameworks. Federal insurance mandate expansions into remote patient monitoring reimbursement convert capital expenditure models toward recurring revenue among private operators in northern emirates.
- Clinics:Outpatient diagnostic centers deploy portable multi-parameter systems for pre-operative assessment.
- Emergency Services:Ambulance and pre-hospital networks utilize ruggedized portable monitors with extended battery life.
Volume concentrates in Hospitals. Margin expansion accelerates in Home Care.
Technology:
Application requirements determine whether wireless telemetry, portable bedside units, wearable patches, or standalone configurations satisfy clinical workflow demands.
- Wireless:Real-time telemetry architectures transmit physiological data to central nursing stations without patient tethering. Dubai ambulatory surgery centers drive adoption where MOHAP interoperability mandates require integration with national electronic health record infrastructure.
- Wearable:Patch-based cardiac and respiratory monitors enable continuous monitoring outside traditional clinical settings. Post-discharge surveillance contracts in Abu Dhabi private hospital networks align with insurance reimbursement expansions and readmission penalty avoidance.
- Portable:Battery-powered multi-parameter systems serve inter-facility transport and emergency response.
- Standalone:Hardwired bedside configurations persist in legacy infrastructure where middleware integration costs delay replacement.
Wireless platforms claim infrastructure investment. Wearable formats gain reimbursement traction.
Application:
Customer workflow integration separates chronic disease management platforms requiring longitudinal data from acute intervention systems prioritizing alarm velocity.
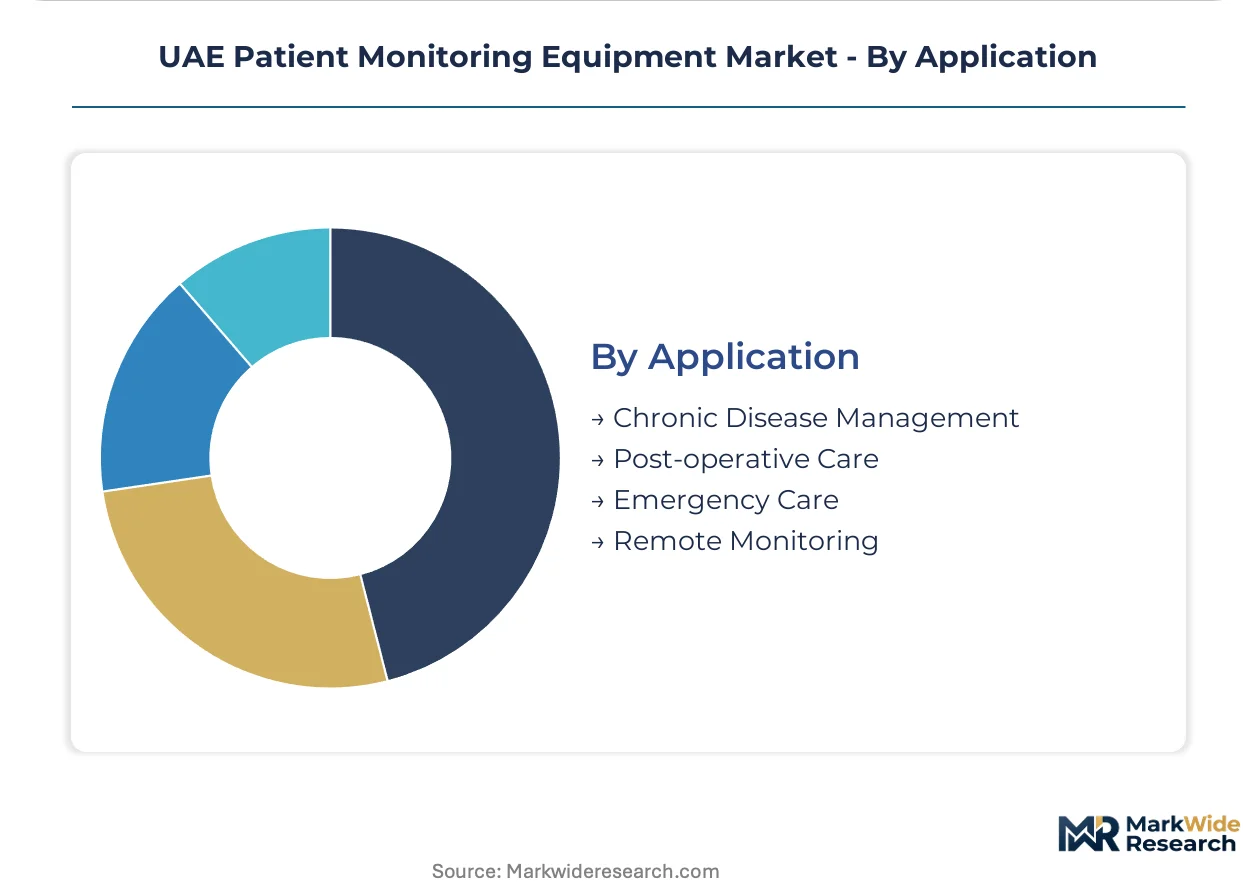
- Chronic Disease Management:Longitudinal monitoring platforms track cardiac, respiratory, and metabolic parameters across months to years. Dubai Health Authority pilot programs in diabetes and heart failure populations test reimbursement models before federal mandate expansion.
- Emergency Care:Rapid-deployment monitors prioritize alarm latency and defibrillation compatibility over data archiving. Abu Dhabi emergency medical services specify ruggedized portable systems with extended temperature operating ranges for desert deployment conditions.
- Post-operative Care:Step-down unit monitoring balances alarm sensitivity with false positive reduction.
- Remote Monitoring:Home-based surveillance contracts extend acute care monitoring beyond discharge.
Chronic Disease Management anchors recurring revenue. Emergency Care commands premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient monitoring equipment manufacturing originated in North American and European industrial clusters during the 1960s, with production scaling through Japanese electronics corridors in subsequent decades. The UAE market absorbs technology through import-dependent healthcare infrastructure rather than domestic fabrication.
Dubai
Dubai Health Authority procurement frameworks drive multi-parameter monitor installations across 14 public hospitals and 20+ private facilities. MOHAP interoperability mandates require wireless telemetry integration with the national electronic health record platform NABIDH. Dubai Healthcare City clusters specialist cardiac centers where cath lab expansion multiplies perioperative monitor density.
Abu Dhabi
SEHA procurement frameworks govern device selection across 12 hospitals and 60+ clinics with centralized biomedical engineering services. The Department of Health Abu Dhabi mandates cybersecurity hardening protocols for all networked monitoring systems. Cleveland Clinic Abu Dhabi and Sheikh Khalifa Medical City anchor high-acuity ICU deployments with recurring hemodynamic transducer consumption.
Sharjah
Sharjah Health Authority facilities operate 8 hospitals with growing ambulatory surgery center networks. The emirate's medical device import licensing follows ESMA electromagnetic compatibility standards with 14-18 week approval timelines. University Hospital Sharjah and Al Qassimi Hospital concentrate cardiac monitor installations serving northern emirate referral flows.
Northern Emirates
Ras Al Khaimah and Fujairah healthcare investment zones present greenfield deployment opportunities outside saturated Dubai-Abu Dhabi corridors. Federal insurance mandate expansions into remote patient monitoring reimbursement convert capital models toward subscription frameworks. RAK Hospital and Fujairah Hospital anchor regional networks with limited on-site biomedical engineering capacity.
UAE Patient Monitoring Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service contract integration and AI-enabled alarm management capabilities. The vendor base concentrates around integrated platform providers with localized calibration infrastructure and discrete technical service specialists. Three archetypes dominate: multinational conglomerates with Middle East distribution hubs, regional subsidiaries with federal registration expertise, and independent service contractors unbundling maintenance from capital sales. M&A activity targets AI alarm management capabilities while strategic partnerships secure MOHAP pre-integration certification.
Among diversified healthcare conglomerates, Medtronic Care Management Services LLC and Abbott Laboratories exemplify the premium-service archetype through sustained federal contract relationships. Koninklijke Philips NV occupies a position as the integrated platform anchor with established Dubai Health Authority service frameworks. Siemens Healthineers and GE Healthcare represent the technology-differentiation tier where AI-enabled workflow protocols command procurement preference.
| Leading Market Players |
|---|
| Medtronic Care Management Services LLC |
| Becton Dickinson and Company |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Baxter International Inc |
| Koninklijke Philips NV |
| Omron Corporation |
| Siemens Healthineers |
| GE Healthcare |
| Others |
Value Network & Pricing Analysis
Biomedical engineering talent concentration in Dubai and Abu Dhabi creates labor-cost differentials that widen pricing-tier spreads between premium integrated platforms and economy bedside monitors. MOHAP digitization mandates compress procurement cycles, forcing vendors to absorb pre-integration certification costs that stratify final pricing across hospital network tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates UAE patient monitoring equipment procurement. Premium tiers command spreads based on AI-enabled alarm management capabilities and MOHAP pre-integration certification, while standard configurations compete on cath lab compatibility and service contract bundling. Cost compression in economy tiers intensifies because SEHA procurement frameworks prioritize lifecycle cost transparency over upfront capital expenditure. Private hospital operators in Dubai exhibit highest price sensitivity due to unbundled service contract requirements, whereas Abu Dhabi SEHA networks absorb premium pricing for centralized platform standardization.
Supply Chain Analysis
Single-source vulnerability sits with semiconductor component suppliers concentrated in Taiwan, South Korea, and Japan. Disposable transducer manufacturing draws from polymer resin feedstocks anchored in Saudi Arabian and Qatari petrochemical corridors. Supply chain risk centers on electromagnetic compatibility certification delays at ESMA that extend working capital cycles for importers. Distribution runs through Dubai's Jebel Ali Free Zone medical device clusters before radiating to Abu Dhabi, Sharjah, and northern emirate hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MOHAP's interoperability mandate for real-time EHR integration functions as a regulatory compounder, accelerating replacement cycles and elevating vendor qualification barriers that concentrate procurement among pre-certified platform providers.
For Market Incumbents: Cement service contract lock-in through localized calibration laboratories in Abu Dhabi and Dubai, insulating against independent technical service contractors unbundling maintenance from capital sales. Deepen backward integration into disposable transducer manufacturing to offset polymer resin price volatility threatening hemodynamic monitor margins. Prioritize AI alarm management R&D aligned with MOHAP workflow protocols to defend premium positioning against technology-differentiation challengers.
For New Entrants and Emerging Players: ESMA cybersecurity hardening requirements for networked monitoring systems open a window for niche specialists offering middleware integration layers for legacy device retrofit. Target northern emirate greenfield deployments in Ras Al Khaimah and Fujairah where biomedical engineering talent scarcity constrains incumbent service response times. Pursue hospital-at-home acute monitoring contracts leveraging federal insurance mandate expansions into remote patient monitoring reimbursement.
For Investors and Strategic Acquirers: Integrated platform providers with Middle East distribution hubs are the most active acquirer in this space, seeking AI alarm management capabilities and MOHAP pre-integration certification assets. Long-term viability hinges on recurring revenue conversion through subscription-based remote monitoring service frameworks. Watch for federal insurance mandate expansion velocity into post-discharge hemodynamic surveillance as inflection indicator for capital-to-operating expenditure model shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Pre-Integration Certification | Qualification for Dubai Health Authority and SEHA procurement frameworks accelerates contract eligibility. |
| AI-Enabled Alarm Management Development | Machine learning integration with federal workflow protocols commands premium positioning against commodity monitors. |
| Localized Calibration Laboratory Expansion | Abu Dhabi and Dubai service infrastructure insulates against independent contractor unbundling threats. |
| Remote Patient Monitoring Reimbursement Strategy | Federal insurance mandate alignment converts hospital capital expenditure toward recurring service revenue. |
| Disposable Transducer Backward Integration | Captive polymer resin sourcing hedges margin volatility in high-acuity ICU hemodynamic monitor deployments. |
Research Methodology
Multiple input streams — hospital procurement database analysis, biomedical engineering director interviews, and ESMA regulatory filing review — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged hospital purchasing committees, GPO contracts managers, and MOHAP device registration specialists across Dubai, Abu Dhabi, and Sharjah. Secondary validation incorporated UAE.S GSO standards documentation, SEHA procurement framework disclosures, and federal insurance mandate expansion records.
Data-stream reconciliation applied analytical frameworks across product type, end-user tier, technology format, and application workflow dimensions over the projection horizon. CAGRs were derived from installed base replacement cycle compression, cath lab expansion trajectories, and wireless telemetry adoption curves modeled against MOHAP digitization mandate timelines. Forecast inputs incorporated polymer resin price volatility indices and biomedical engineering labor market tightness metrics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ESMA certification timeline extensions or federal insurance mandate implementation delays. Projections reflect assumptions regarding MOHAP interoperability mandate adherence rates and wireless spectrum allocation stability in dense clinical environments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market
Patient Monitoring
Global Body Temperature Monitoring Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Cardiac Rhythm Remote Monitoring Devices Market
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market
Patient Monitoring
Asia-Pacific Respiratory Monitoring Market
Patient Monitoring
Europe Wireless Healthcare Market
Patient Monitoring
Clinical Alarm Management Market
Patient Monitoring
Drowsiness Monitoring System Market
Patient Monitoring
ECG Monitoring System Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
South America Remote Patient Monitoring Systems Market