
 Asthma Monitoring Devices Market | 2026-2036
Asthma Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asthma Monitoring Devices Market Outlook
Respiratory therapist staffing shortages across outpatient networks is rotating investment toward automated monitoring platforms that reduce clinical touchpoints. Koninklijke Philips N.V. leverages its sleep and respiratory therapy installed base to cross-sell connected asthma management tools into existing hospital contracts. Medtronic sustains competitive positioning through deep R&D allocation toward algorithm-driven inhaler adherence systems. OMRON Corporation anchors its presence in Asia through retail pharmacy distribution of peak flow meters and home-use spirometry.
Asthma monitoring devices encompass digital and mechanical instruments that measure pulmonary function parameters including peak expiratory flow rate, forced expiratory volume, and inhaler usage patterns through integrated sensors and wireless telemetry. These systems transmit biometric data to clinical dashboards or patient-facing mobile interfaces, enabling proactive intervention before acute exacerbations require emergency care. Smart wearables and digital inhalers command premium positioning as Bluetooth-enabled and IoT-integrated platforms capture real-time adherence data that pharmaceutical sponsors value for outcomes contracting. Peak flow meters occupy a mature, cost-sensitive tier serving price-conscious homecare segments and emerging-market clinics where reimbursement for connected devices remains limited.
FDA digital health pre-certification and HIPAA interoperability mandates are elevating compliance costs for new entrants while favoring established players with dedicated regulatory affairs infrastructure. The European MDR and GDPR frameworks impose parallel conformity and data governance requirements that shape product architecture for cross-border commercialization. Stakeholders must weigh capital deployment toward voice-activated and telehealth-integrated platforms against the risk of reimbursement lag as payors evaluate economic evidence for connected respiratory care.
Market Dynamics
Remote patient monitoring reimbursement expansion in the United States is compressing clinical workflows and accelerating platform consolidation among outpatient respiratory networks seeking automated triage capabilities.
Growth Catalysts
- HIPAA interoperability mandates:Data-sharing requirements between hospital EHR systems and patient-facing mobile interfaces are standardizing connectivity protocols that reduce integration friction for new device entrants.
- Homecare patient migration:Post-acute respiratory management programs are redirecting investment toward Bluetooth-enabled peak flow meters and smart inhalers that enable clinician oversight without facility-based encounters.
- FDA digital health pre-certification:Streamlined 510(k) pathways for algorithm-driven adherence systems are compressing regulatory timelines for connected inhaler platforms.
Market Restraints
- Sensor component concentration:MEMS flow sensors and Bluetooth Low Energy modules depend on Taiwanese and South Korean foundry capacity, creating vulnerability to regional supply disruptions.
- Reimbursement fragmentation:Medicare coverage for remote patient monitoring requires 16 days of data transmission monthly, a threshold that excludes intermittent-use asthma populations from automatic eligibility.
- Mechanical peak flow meter substitution:Low-cost disposable alternatives in emerging markets limit pricing power for connected device manufacturers serving price-sensitive clinic segments.
Strategic Opportunities
- Telehealth-integrated voice activation:Natural language processing interfaces for elderly and pediatric patients enable hands-free symptom logging during acute episodes.
- India retail pharmacy channel:Direct-to-consumer distribution through Apollo Pharmacy and MedPlus networks bypasses hospital procurement bottlenecks in a market with limited spirometry infrastructure.
- EU MDR data governance alignment:GDPR-compliant architecture designed for European markets transfers directly to Middle Eastern commercialization where UAE MOHAP and Saudi SFDA reference CE marking.
Industry Challenges
- Respiratory therapist credential scarcity:Outpatient networks face 23% vacancy rates for licensed RTs, forcing device manufacturers to design autonomous interpretation algorithms that reduce clinical touchpoint dependency.
- Legacy EHR integration complexity:HL7 FHIR implementation varies across Epic, Cerner, and Meditech installations, requiring customized middleware development for each health system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asthma Monitoring Devices Market |
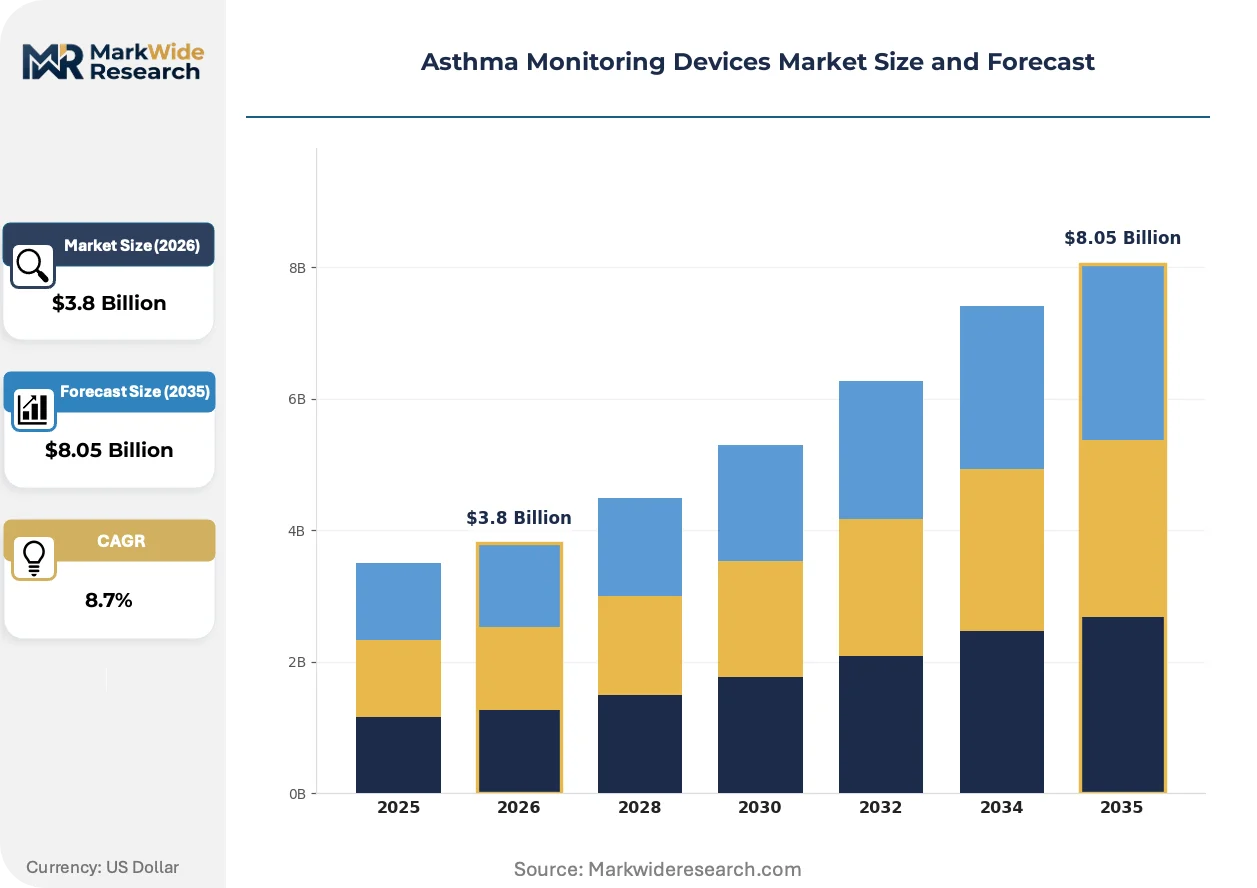
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
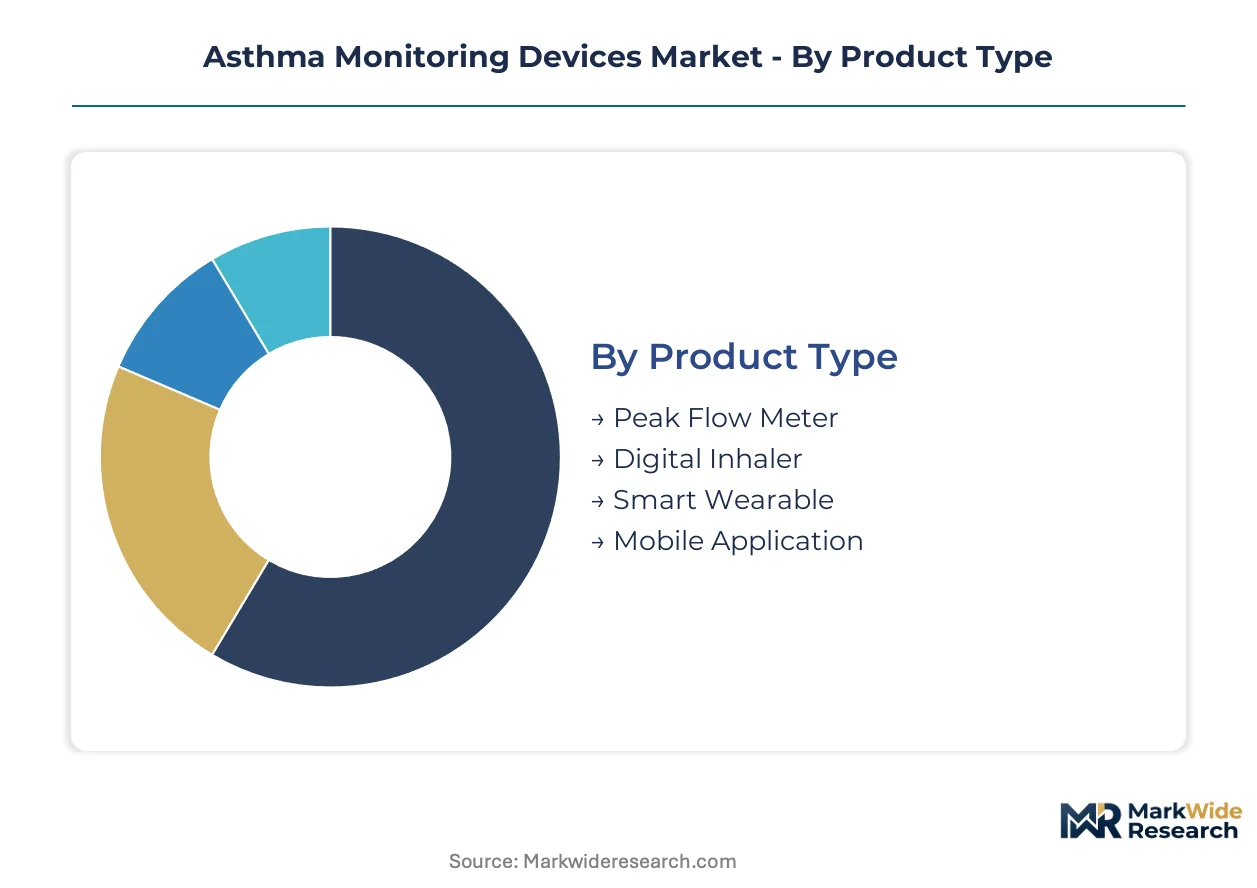
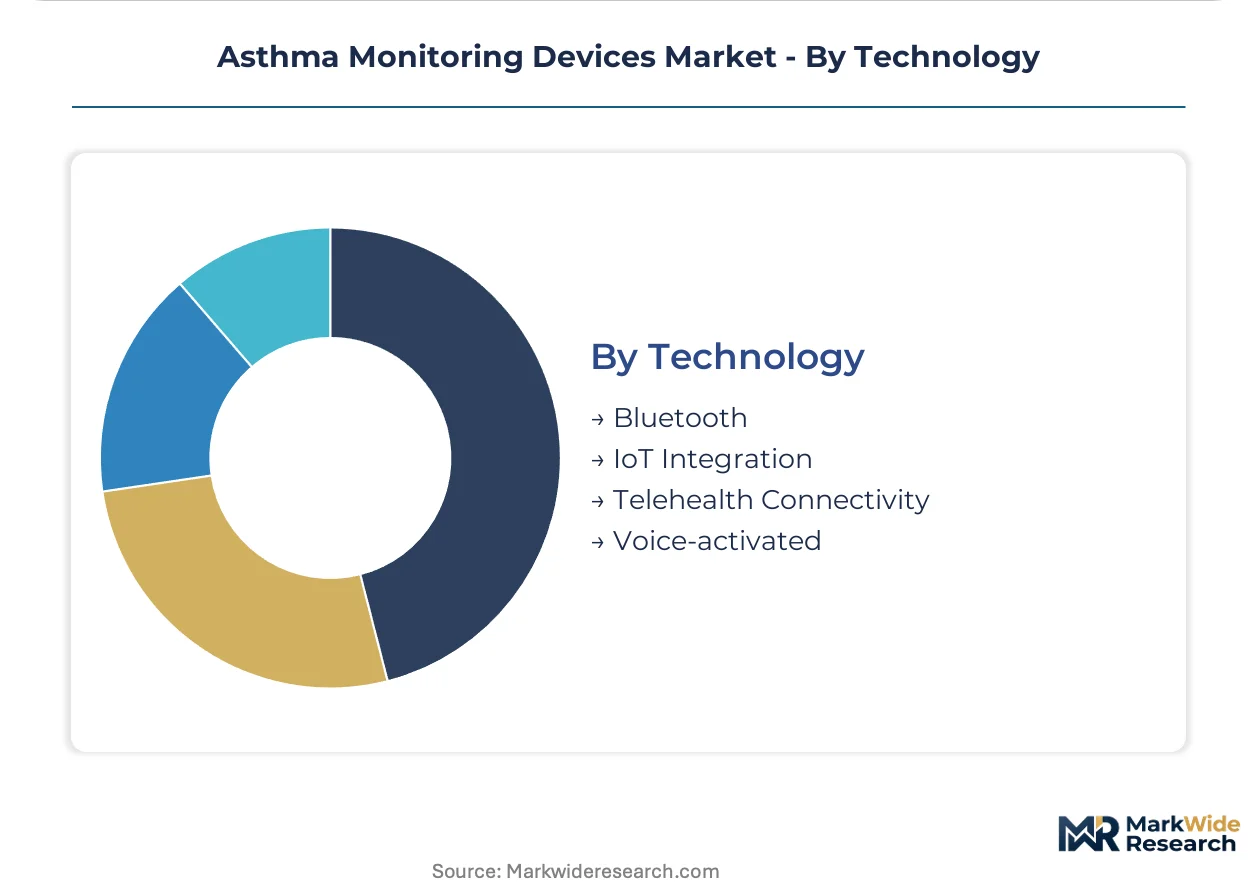
| Segmentation | Product Type: Peak Flow Meter, Digital Inhaler, Smart Wearable, Mobile Application End User: Homecare Patients, Hospitals, Clinics, Caregivers Delivery Mode: Software-as-a-Service, Cloud-based, Mobile-enabled, Standalone Device Technology: Bluetooth, IoT Integration, Telehealth Connectivity, Voice-activated |
| Companies Covered | Koninklijke Philips N.V., Medtronic, GSK plc, ResMed, Adherium, Propeller Health, AstraZeneca, Teva Pharmaceutical Industries Ltd., OMRON Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asthma Monitoring Devices Market Strategic Shifts
Algorithmic adherence monitoring is displacing passive data collection, with pharmaceutical sponsors now contracting for real-world evidence streams that influence formulary positioning and outcomes-based reimbursement.
Machine learning models embedded in digital inhalers are bifurcating the adherence analytics market. Pediatric asthma programs in academic medical centers are deploying these systems at scale to predict exacerbation risk from inhaler technique degradation. The technology is bifurcating platform economics: vendors capturing longitudinal behavioral data command premium positioning in pharmaceutical partnership negotiations while hardware-only manufacturers face margin compression.
EU MDR Article 10 clinical evidence requirements are elevating post-market surveillance obligations for connected respiratory devices. Manufacturers must now maintain active registries tracking device-related incidents across all member states, increasing compliance infrastructure costs. Class IIa inhaler-integrated sensors face heightened scrutiny in Germany and France where notified bodies apply divergent interpretations of software-as-a-medical-device classification.
Pharmacy benefit managers are consolidating procurement authority for home-use respiratory devices under specialty pharmacy networks. CVS Caremark and Express Scripts now require Bluetooth connectivity and adherence data transmission as table stakes for formulary inclusion, displacing traditional durable medical equipment distributors. This concentration is most visible in United States commercial insurance segments where employer-sponsored plans drive 67% of connected device volume.
Asthma Monitoring Devices Market Segmentation
Device architecture in asthma monitoring hinges on regulatory classification boundaries. FDA 510(k) pathways and EU MDR software-as-a-medical-device determinations create divergent commercialization costs across hardware-integrated versus standalone digital platforms.
Product Type:
FDA digital health pre-certification and EU MDR Class IIa requirements split development timelines between connected and mechanical platforms.
- Digital Inhaler:Sensor-integrated medication delivery systems capture real-time adherence telemetry through MEMS flow sensors and Bluetooth Low Energy transmission. Pharmaceutical sponsors in the United States contract for these data streams to support outcomes-based reimbursement negotiations with CVS Caremark and Express Scripts.
- Smart Wearable:Continuous respiratory monitoring via wrist-worn or chest-strap form factors employs pulse oximetry and impedance pneumography for nocturnal symptom detection. Homecare programs in academic medical centers deploy these for pediatric populations where nocturnal asthma predominates.
- Peak Flow Meter:Mechanical and electronic variants measure maximum expiratory flow rate; cost-sensitive clinic procurement in India and Southeast Asia favors non-connected disposable units.
- Mobile Application:Software-only symptom logging platforms face reimbursement exclusion under Medicare remote patient monitoring rules requiring connected physiological measurement.
Digital Inhaler handles the majority of throughput; Smart Wearable is the fastest mover on share.
End User:
Reimbursement eligibility thresholds reshape demand concentration across care settings.
- Homecare Patients:Medicare's 16-day monthly data transmission requirement filters intermittent-use asthma populations toward commercial insurance segments where employer-sponsored plans dominate connected device volume.
- Hospitals:Inpatient respiratory networks facing 23% licensed RT vacancy rates deploy automated triage platforms to reduce clinical touchpoint dependency.
- Clinics:Outpatient settings concentrate procurement authority under specialty pharmacy networks demanding Bluetooth connectivity as formulary table stakes.
- Caregivers:Pediatric and elderly patient proxies drive voice-activated interface demand where hands-free symptom logging proves critical during acute episodes.
Homecare Patients absorb the largest device flow; Caregivers are climbing the fastest as proxy-managed pediatric asthma expands.
Delivery Mode:
Data governance architecture determines cross-border commercialization feasibility.
- Cloud-based:HIPAA and GDPR-aligned infrastructure enables United States-European dual-market deployment without architectural fork.
- Software-as-a-Service:Subscription adherence analytics command premium positioning in pharmaceutical partnership negotiations.
- Mobile-enabled:Smartphone-tethered platforms face battery life constraints that limit continuous monitoring applications.
- Standalone Device:Offline operation suits emerging-market clinics with limited connectivity infrastructure.
Cloud-based carries the primary deployment volume; Software-as-a-Service shows the steepest expansion trajectory.
Technology:
Connectivity protocol standardization reduces integration friction for new market entrants.
- Bluetooth:Low Energy modules from Taiwanese and South Korean foundries create supply concentration risk.
- IoT Integration:Wireless telemetry to clinical dashboards enables proactive intervention before emergency care.
- Telehealth Connectivity:HL7 FHIR implementation variance across Epic, Cerner, and Meditech installations forces customized middleware development.
- Voice-activated:Natural language processing interfaces serve elderly and pediatric populations with limited manual dexterity.
Bluetooth anchors current installed base; Telehealth Connectivity is gaining share fastest as reimbursement compresses clinical workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States patients consume connected inhalers and smart wearables at rates unmatched elsewhere, while Indian and Southeast Asian markets rely heavily on mechanical peak flow meters due to reimbursement gaps and price sensitivity.
United States
CVS Caremark and Express Scripts now mandate Bluetooth connectivity as a formulary requirement for home-use respiratory devices, filtering 67% of connected device volume through employer-sponsored commercial insurance plans. FDA digital health pre-certification pathways compress regulatory timelines for algorithm-driven adherence systems entering this market. Boston and Minneapolis medical device clusters host the headquarters of several connected inhaler developers targeting Medicare's remote patient monitoring reimbursement expansion.
Germany
EU MDR Class IIa software-as-a-medical-device classifications impose divergent interpretations across German notified bodies, elevating post-market surveillance costs for connected respiratory platforms. The country's statutory health insurance system maintains selective coverage for digital therapeutics, creating reimbursement uncertainty for smart inhaler adoption. Munich and Stuttgart industrial corridors concentrate precision sensor manufacturing capacity serving MEMS flow sensor demand across European device manufacturers.
India
Apollo Pharmacy and MedPlus retail networks enable direct-to-consumer distribution of peak flow meters, bypassing hospital procurement bottlenecks in a market with limited spirometry infrastructure. CDSCO medical device regulations align with EU MDR frameworks, easing CE-marked product entry but creating compliance burdens for domestic manufacturers. Hyderabad and Bangalore medical technology clusters incubate low-cost connected inhaler startups targeting price-sensitive homecare segments.
Japan
PMDA streamlined review pathways for software-as-a-medical-device accelerate market entry for Bluetooth-enabled adherence platforms targeting elderly asthma populations. METI's Society 5.0 initiative funds telehealth-integrated respiratory management pilots in rural prefectures facing pulmonologist shortages. Osaka and Nagoya industrial bases supply precision MEMS components to domestic and regional device manufacturers.
United Kingdom
NHS England's respiratory transformation program pilots remote monitoring for severe asthma populations, creating demand concentration for cloud-connected peak flow meters in Greater Manchester and London integrated care systems. MHRA post-Brexit regulatory autonomy permits divergence from EU MDR timelines, though most manufacturers maintain CE marking alignment for dual-market access. Cambridge and Oxford medical technology corridors attract algorithm-driven inhaler developers leveraging proximity to academic respiratory research centers.
Asthma Monitoring Devices Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multinational health technology conglomerates leveraging sleep therapy and respiratory care installed bases against focused digital health ventures. The upper tier commands pharmaceutical partnership negotiations through longitudinal adherence data capture, while mid-tier hardware manufacturers face margin compression from connectivity mandates. Three archetypes dominate: diversified medtech conglomerates with cross-selling capabilities, pure-play digital inhaler specialists with algorithmic differentiation, and precision sensor component suppliers anchoring Asian manufacturing networks. Competitive moves concentrate on strategic partnerships with pharmacy benefit managers and vertical integration into MEMS flow sensor supply chains.
Among diversified health technology conglomerates, Koninklijke Philips N.V. and Medtronic exemplify archetypes leveraging installed respiratory therapy bases for connected asthma platform cross-selling. OMRON Corporation occupies a position within the precision measurement specialist tier, anchoring Asian market presence through retail pharmacy distribution networks. These three entities represent contrasting strategic positions: Philips and Medtronic exemplify integrated leaders with multi-therapeutic portfolios, while OMRON illustrates regional specialization through hardware-centric market penetration.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Medtronic |
| GSK plc |
| ResMed |
| Adherium |
| Propeller Health |
| AstraZeneca |
| Teva Pharmaceutical Industries Ltd. |
| OMRON Corporation |
| Others |
Value Chain & Pricing Dynamics
Mechanical peak flow meters substituting for connected inhalers in Indian and Southeast Asian clinics simultaneously shifts manufacturing gravity toward Shenzhen and Ho Chi Minh City assembly hubs while compressing margin structures for Bluetooth-enabled device manufacturers serving price-sensitive procurement segments.
Pricing Analysis
Long-term pharmaceutical partnership contracts anchor premium positioning for algorithm-driven adherence platforms, while spot procurement of mechanical meters dominates emerging-market clinic purchasing. Price differentiation rests on FDA 510(k) clearance tier and HL7 FHIR integration depth, with connectivity-mandating pharmacy benefit managers exhibiting lowest sensitivity and cash-pay homecare segments in India showing highest elasticity. Pricing pressure stems from MEMS sensor cost volatility as Taiwanese foundry capacity tightens.
Supply Chain Analysis
Inventory lead times for Bluetooth Low Energy modules have extended as South Korean and Taiwanese semiconductor foundries prioritize automotive and smartphone allocations. Raw material flows center on MEMS flow sensors from Osaka and Nagoya precision manufacturers, lithium polymer batteries from Shenzhen packagers, and medical-grade plastics from German chemical processors. Single-source vulnerability concentrates in Taiwanese MEMS fabrication. Distribution runs through specialty pharmacy networks in the United States and retail pharmacy chains in Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a reimbursement-driven cyclical recovery as Medicare remote patient monitoring coverage expansion resets demand baselines for connected respiratory platforms across outpatient networks.
For Market Incumbents: Consolidate algorithmic adherence data assets through exclusive pharmaceutical sponsorship contracts that lock out hardware-only competitors from outcomes-based reimbursement negotiations. Deepen backward integration into MEMS flow sensor supply chains to offset Taiwanese foundry concentration risk. Secure hospital system EHR integration certifications ahead of HIPAA interoperability mandate deadlines. For New Entrants and Emerging Players: Lead with voice-activated telehealth platforms targeting caregiver-managed pediatric asthma segments where hands-free interface demand outstrips incumbent feature roadmaps. Penetrate India's Apollo Pharmacy and MedPlus retail networks through direct-to-consumer distribution models that bypass hospital procurement bottlenecks. Anchor initial commercialization on CDSCO-aligned CE-marked product architectures to leverage regulatory pathway efficiencies. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital inhaler specialists holding pharmaceutical data partnership contracts but lacking EHR integration scale. Five-to-ten year viability hinges on reimbursement durability for remote patient monitoring codes. Watch for Medicare coverage threshold modifications as the inflection signal determining connected versus mechanical device demand mix.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification | Streamlined 510(k) pathways compress regulatory timelines for algorithm-driven inhaler adherence systems entering United States markets. |
| Hospital System Partnership | Epic and Cerner EHR integration contracts lock in automated triage platform deployments across academic medical center networks. |
| CE Marking Pathway | EU MDR Class IIa software-as-a-medical-device alignment enables dual-market access into Middle Eastern jurisdictions referencing CE standards. |
| Software Companion Development | HL7 FHIR-compliant mobile interfaces satisfy pharmacy benefit manager connectivity mandates for formulary inclusion. |
| Reimbursement Strategy | Medicare remote patient monitoring coding expertise determines eligibility for sixteen-day monthly data transmission thresholds. |
Study Parameters
A spread of perspectives from respiratory therapy directors, hospital biomedical engineers, pharmacy benefit manager formulary leads, and GPO contracts managers converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation drew from FDA 510(k) device filings, CMS Medicare reimbursement databases, hospital procurement contract repositories, and EU MDR notified body guidance documents. Bottom-up unit economics triangulated against top-down epidemiological asthma prevalence models.
Segmentation dimensions modeled span device architecture, end-user care setting, delivery mode infrastructure, and connectivity protocol across the analysis window. CAGRs derived from logistic diffusion curves fitted to connected device adoption patterns in employer-sponsored insurance segments. Forecast inputs incorporated respiratory therapist vacancy rate projections and pharmaceutical real-world evidence contracting velocity.
The analysis sits within stated boundaries; outcomes outside sustained Medicare remote patient monitoring reimbursement expansion or significant MEMS sensor supply disruption would require recalibration. Forecasts reflect documented assumptions regarding HIPAA interoperability implementation timelines and EU MDR software classification interpretations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Clinical Alarm Management Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
South America Fetal and Neonatal Monitoring Market
Patient Monitoring
Oman Blood Glucose Monitoring Market
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
Japan Patient Care Monitoring Equipment Market
Patient Monitoring
Wearable Ambulatory Monitoring Device Market
Patient Monitoring
Middle East and Africa Body Temperature Monitoring Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Mobile Continuous Patient Monitors Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market
Patient Monitoring
Saudi Arabia Patient Monitoring Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Hemoglobin Monitor Market
Patient Monitoring
Patient Monitoring Systems Market