
 Home Care Market | 2026-2036
Home Care Market Size, Share, and Industry Trends Forecast 2026-2036
Home Care Market Intelligence
Buyer concentration across the Home Care Market is rebalancing as hospital systems and Medicare Advantage plans consolidate purchasing power while direct-to-consumer channels fragment access for family caregivers. Griswold Home Care leverages its franchise network to sustain localized service density in suburban markets. BrightStar Care anchors its position through clinical staffing models that compete with traditional skilled nursing facilities. Home Instead dominates the companion services segment through brand strength and established referral relationships with discharge planners.
Home care encompasses medically supervised and non-medical support services delivered in residential settings, including wound care administration, medication management, mobility assistance, and activities of daily living supervision using FDA-registered devices and caregiver-monitored protocols. The primary purpose is to substitute institutional care with clinically equivalent outcomes at lower systemic cost. Personal care products and home health aids command the largest revenue pools due to recurring consumption patterns, while rehabilitation services and hospice care represent faster-growing segments as palliative care reimbursement expands and orthopedic procedure volumes rise. Safety equipment margins concentrate in certified fall-prevention systems rather than basic monitoring devices.
The FDA regulates home health aids and mobility equipment as Class I and II medical devices, while the CMS reimbursement framework shapes demand through Medicare Home Health Prospective Payment System adjustments and value-based purchasing pilots. State-level licensing boards for nurses and home health aides create patchwork compliance requirements that favor multi-state operators with dedicated regulatory affairs functions. Stakeholders must monitor how CMS innovation center demonstrations for hospital-at-home models reshape referral economics and capital allocation between facility-based and residential care delivery.
Market Dynamics
Hospital-at-home reimbursement pilots from CMS are compressing traditional facility discharge timelines and redirecting capital toward residential care infrastructure.
Growth Catalysts
- Post-acute diversion protocols:Medicare's value-based purchasing pilots reward hospitals for reducing readmissions through home-based recovery monitoring.
- EU MDR certification pathways:Streamlined conformity assessment for Class II remote monitoring devices accelerates product entry across member states.
- Aging-in-place housing stock:Suburban municipalities retrofit zoning codes to permit accessory dwelling units for multigenerational care arrangements.
Market Restraints
- Direct care workforce scarcity:Licensed practical nurse vacancy rates exceed 20% in rural counties, constraining service expansion.
- Reimbursement lag structure:Medicare Home Health Prospective Payment System updates trail cost inflation by 18-24 months.
- Device interoperability gaps:Proprietary data formats from legacy monitoring hardware block seamless EHR integration.
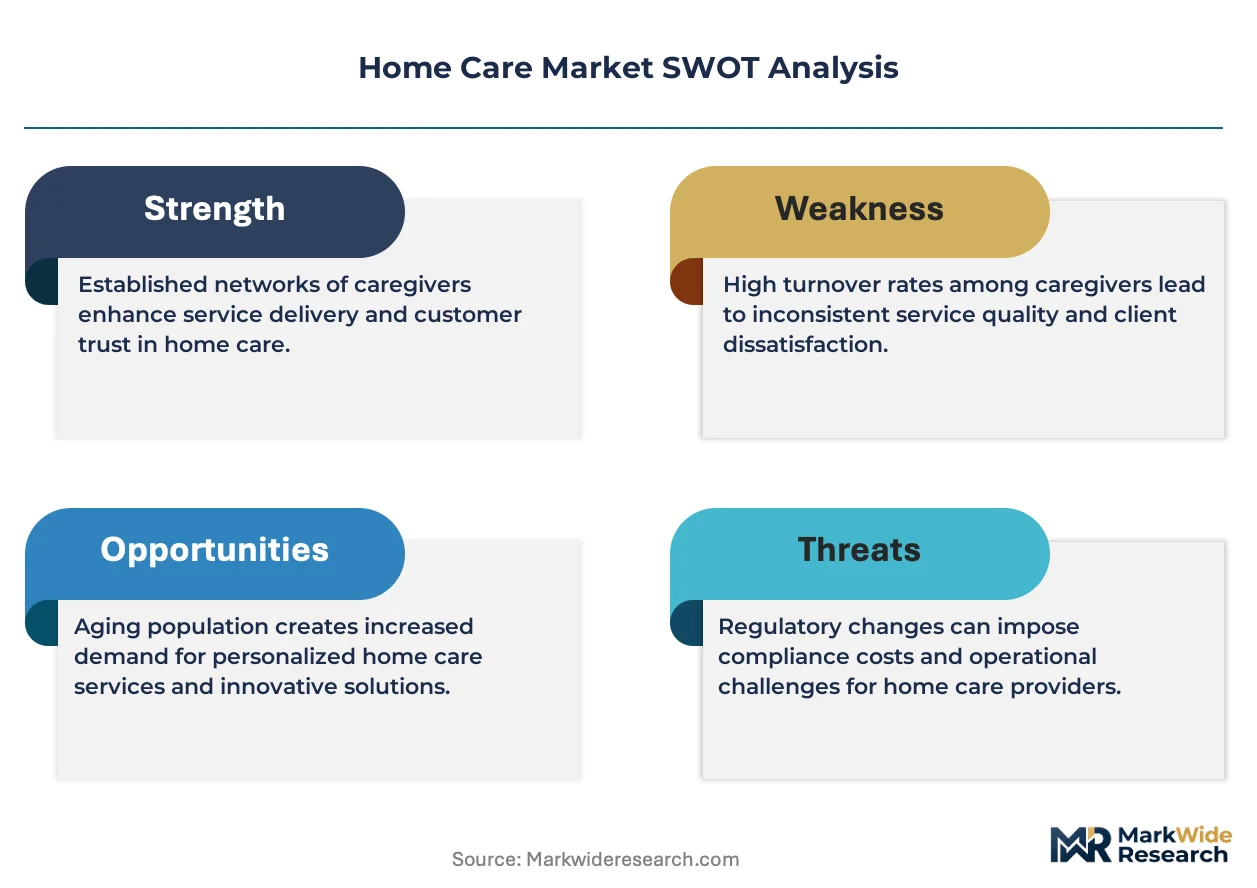
Strategic Opportunities
- Hospital-at-home waivers:CMS innovation center demonstrations in 25 states permit acute-level care delivery in residential settings.
- Remote patient monitoring CPT codes:New physician fee schedule billing categories create sustainable revenue streams for continuous vital sign surveillance.
- AI-enabled fall prediction:Machine learning models analyzing gait patterns through ambient sensors reduce emergency department utilization.
Industry Challenges
- Caregiver credentialing fragmentation:State-level home health aide training hour requirements vary from 75 to 180 hours, complicating multi-state staffing.
- Technology deployment capex:FDA-validated connected device suites require upfront investment exceeding $15,000 per patient bed equivalent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Care Market |
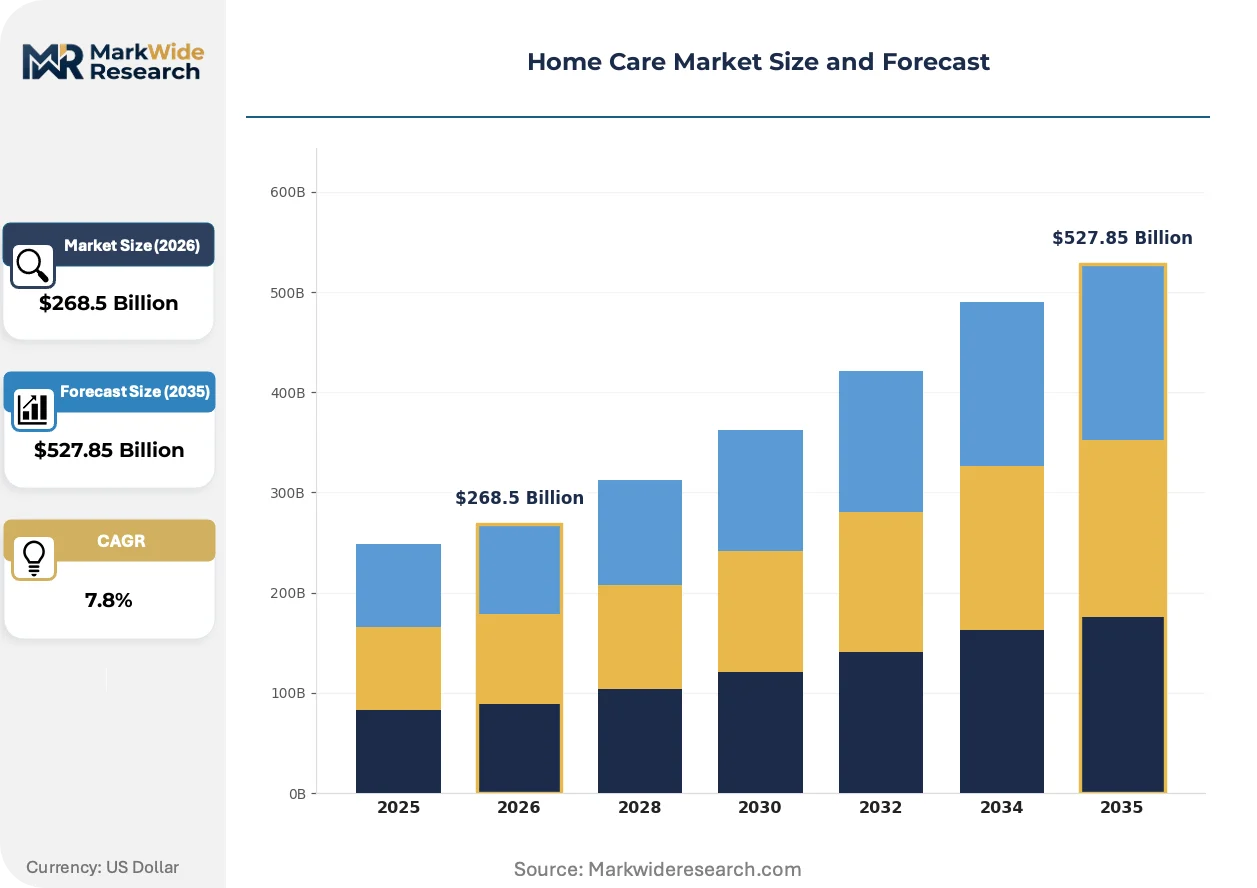
| Market Size in 2026 | $268.5 Billion |
| Market Size in 2035 | $527.85 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Care Products, Home Health Aids, Mobility Aids, Safety Equipment Service Type: In-Home Nursing, Companion Services, Rehabilitation Services, Hospice Care End User: Seniors, Disabled Individuals, Post-Surgery Patients, Caregivers Distribution Channel: Pharmacies, Online Retailers, Medical Supply Stores, Home Health Agencies |
| Companies Covered | 2nd Family, Griswold Home Care, BrightStar Care, Pansy Homecare, Upward Health, Home Instead, Right at Home, CenterWell Home Health, Visiting Angels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Care Market Strategic Shifts & Innovations
Digital health infrastructure is penetrating residential settings faster than regulatory frameworks can standardize data governance and liability allocation.
Remote physiological monitoring is converging with predictive analytics platforms to enable preemptive clinical intervention before acute deterioration. Medicare Advantage plans in Florida and Arizona deploy these integrated systems for congestive heart failure cohorts. The convergence is compressing emergency transport incidence and shifting risk-bearing toward payers.
EU Medical Device Regulation recertification deadlines force manufacturers to resubmit technical documentation for legacy fall-detection hardware. Smaller device suppliers lack notified body relationships and exit the market. German and French procurement consortia now require MDR compliance as a mandatory bid qualification.
Family caregivers increasingly coordinate services through direct-to-consumer platforms rather than hospital discharge planners. Adult children in California and Texas arrange companion care through mobile applications with transparent pricing. This channel disintermediation fragments traditional referral economics and pressures franchise operators to build proprietary digital intake systems.
Home Care Market Segmentation
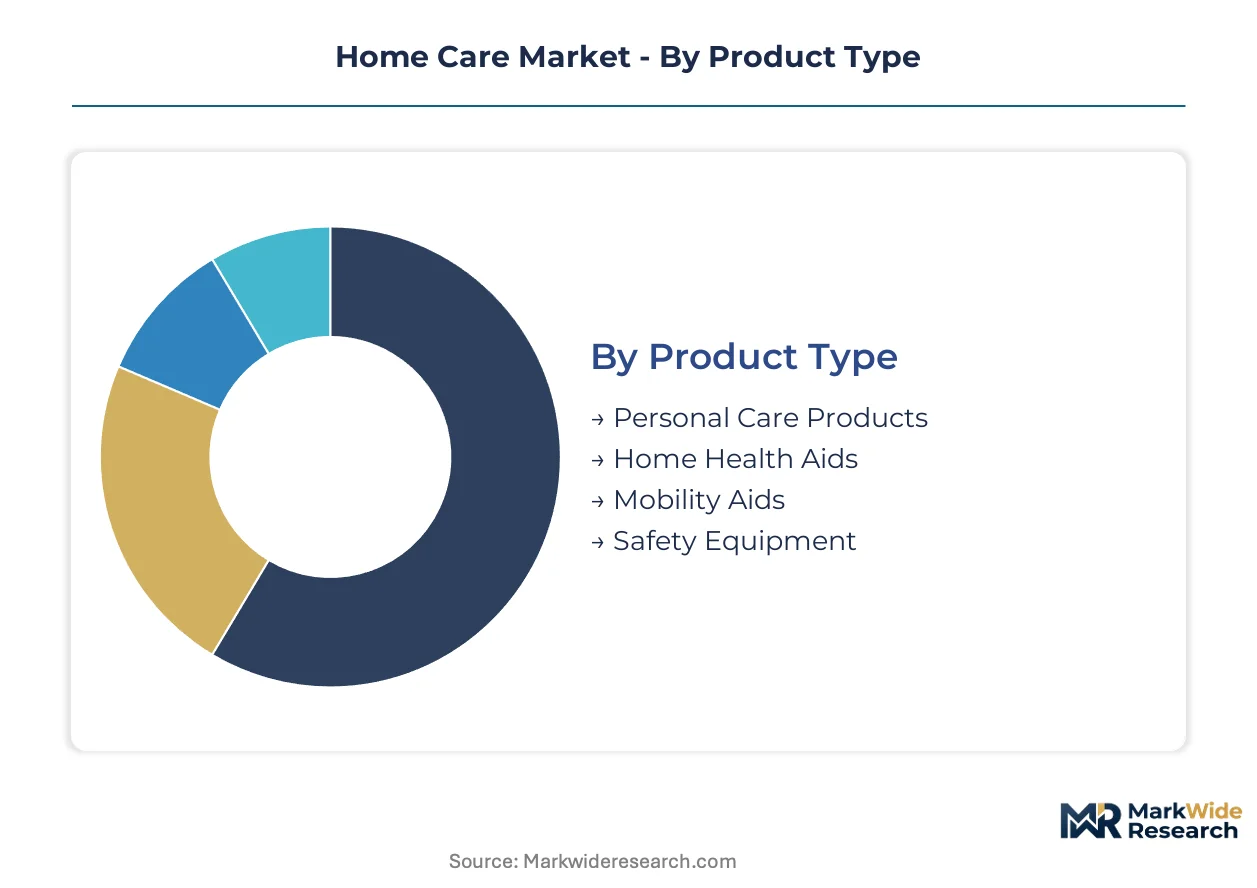
Segmentation in home care reveals how reimbursement pathways and regulatory thresholds partition commercial opportunity. Product categories face divergent FDA device classifications, while service types map to distinct CMS billing codes that shape margin structures and capital requirements.
Product Type:
FDA device classification tiers split this category into divergent compliance burdens: Class I exemptions for basic aids versus Class II 510(k) pathways for connected monitoring equipment. EU MDR recertification deadlines further stratify competitive viability between legacy suppliers and notified body-aligned manufacturers.
- Personal Care Products:Adult diapers, skin care formulations, and bathing aids constitute high-frequency replenishment categories with pharmacy-driven distribution. Demand concentrates in suburban markets across the United States where aging-in-place demographics and Medicare Advantage supplemental benefits sustain recurring purchase patterns.
- Home Health Aids:Blood pressure monitors, pulse oximeters, and glucose meters require FDA Class II clearance and software validation for connected variants. Post-surgery patients in Florida and Texas drive adoption as hospital-at-home waivers expand reimbursable remote monitoring protocols.
- Mobility Aids:Wheelchairs, walkers, and transfer benches span manual and powered variants with divergent reimbursement codes.
- Safety Equipment:Fall-detection sensors and emergency response systems face EU MDR technical documentation resubmission requirements.
Leading the category by volume: Personal Care Products. Growing fastest: Home Health Aids.
Service Type:
CMS reimbursement intensity varies dramatically across this spectrum, from non-skilled companion services excluded from Medicare fee schedules to hospice care with per-diem capitation rates. Labor credentialing requirements scale with clinical complexity, creating structural barriers to multi-service integration.
- In-Home Nursing:Licensed practical and registered nurse services delivering wound care, medication administration, and vital sign monitoring under physician orders. Demand clusters in Arizona and Pennsylvania where hospital-at-home pilots redirect acute-level capacity toward residential settings.
- Companion Services:Non-medical supervision for activities of daily living including meal preparation, transportation, and social engagement. Family caregivers in California arrange these services through direct-to-consumer platforms that disintermediate traditional discharge planner referrals.
- Rehabilitation Services:Physical and occupational therapy delivered in residential settings with distinct CPT billing codes.
- Hospice Care:Palliative services for terminal diagnoses with Medicare per-diem reimbursement and interdisciplinary team requirements.
Dominant by revenue: In-Home Nursing. Expanding most quickly: Hospice Care.
End User:
Clinical acuity and payer mix differentiate user segments, with post-surgery patients commanding higher reimbursement rates but shorter engagement durations versus chronic senior populations with extended service horizons.
- Seniors:Adults aged 65+ with chronic conditions requiring ongoing assistance with activities of daily living and medication management. This population dominates volume across Medicare-reimbursed service lines in suburban United States markets.
- Disabled Individuals:Working-age adults with physical or cognitive impairments accessing services through Medicaid waiver programs and private long-term disability insurance.
- Post-Surgery Patients:Individuals discharged early from inpatient facilities to home-based recovery protocols under hospital-at-home waivers.
- Caregivers:Family members purchasing assistive devices and respite services to sustain informal care arrangements.
Largest addressable population: Seniors. Steepest expansion trajectory: Post-Surgery Patients.
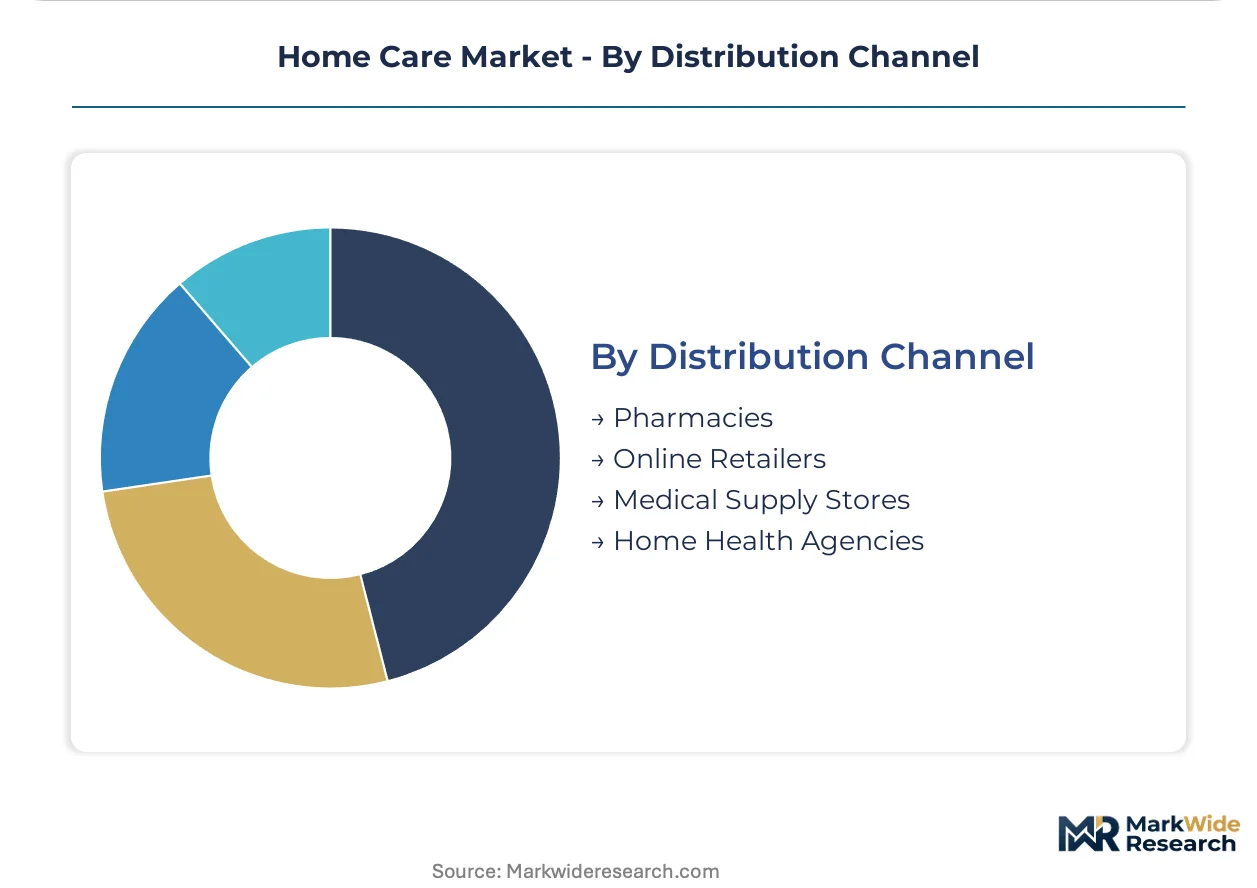
Distribution Channel:
Channel economics reflect reimbursement capture versus margin retention tradeoffs, with institutional referral networks commanding volume and direct-to-consumer platforms extracting premium pricing for convenience.
- Pharmacies:Retail and specialty pharmacy networks dispensing personal care products and durable medical equipment with Medicare Part B billing capabilities. CVS and Walgreens locations in the United States anchor this channel with formulary integration and insurance adjudication infrastructure.
- Online Retailers:Amazon and specialized medical supply platforms offering transparent pricing and subscription replenishment for consumable categories. Adult children caregivers in Texas increasingly coordinate purchases through these channels for remote monitoring of aging parents.
- Medical Supply Stores:Local durable medical equipment suppliers with Medicare accreditation and fitting services for mobility aids.
- Home Health Agencies:Integrated service providers bundling device provision with skilled nursing and therapy delivery.
Highest transaction volume: Pharmacies. Gaining share fastest: Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States where Medicare reimbursement policies and hospital-at-home waivers redirect acute care toward residential settings. Aging demographics across suburban markets sustain volume for personal care products and skilled nursing services. Regulatory divergence between national health systems fragments competitive positioning across developed economies.
United States
Post-surgery patients and congestive heart failure cohorts drive adoption of remote monitoring protocols under CMS innovation center demonstrations. The Medicare Home Health Prospective Payment System shapes referral economics through value-based purchasing pilots that penalize hospital readmissions. Service density clusters in Florida and Arizona where hospital-at-home waivers permit acute-level care delivery in residential settings.
Germany
EU Medical Device Regulation recertification deadlines force resubmission of technical documentation for legacy fall-detection hardware. The country's national health regulator mandates MDR compliance as a mandatory bid qualification for procurement consortia in Bavaria and North Rhine-Westphalia. Notified body-aligned manufacturers consolidate market position as smaller suppliers exit.
Japan
Super-aging demographics expand demand for companion services and mobility aids as multigenerational households decline. METI standards for connected home health devices accelerate product registration pathways for remote monitoring equipment. Industrial concentration in the Kanto region around Tokyo anchors distribution infrastructure for FDA-registered device imports.
United Kingdom
NHS long-term plan commitments to out-of-hospital care redirect capital toward residential nursing and rehabilitation capacity. The Care Quality Commission inspection framework tightens compliance requirements for multi-state operators expanding from the United States. London and Southeast England concentrate purchasing power through integrated care system consolidations.
Canada
Provincial health authority procurement of home health services shifts toward outcome-based contracts for chronic disease management. Health Canada device licensing requirements align with FDA Class II pathways for connected monitoring equipment. Ontario and Quebec anchor service expansion as hospital discharge planners formalize home-based recovery protocols.
Home Care Market Key Industry Players
United States operators anchor one tier through franchise networks and Medicare accreditation density; European specialists hold compliance-driven positioning around MDR certification capabilities. Market structure fragments across service archetypes rather than consolidating around integrated platforms. Three strategic archetypes dominate: clinical staffing models competing with skilled nursing facilities, companion service specialists leveraging brand strength with discharge planners, and technology-enabled platforms coordinating family caregiver purchases. Competitive moves concentrate on multi-state licensing expansion and proprietary digital intake system development.
Within the franchise-network tier, Griswold Home Care and Home Instead exemplify localized service density strategies in suburban United States markets. BrightStar Care occupies a position representing clinical staffing models that bridge home care and skilled nursing facility capabilities. These three operators anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| 2nd Family |
| Griswold Home Care |
| BrightStar Care |
| Pansy Homecare |
| Upward Health |
| Home Instead |
| Right at Home |
| CenterWell Home Health |
| Visiting Angels |
| Others |
Cost & Logistics Intelligence
Franchise-network vertical integration anchors both supply position and pricing power for multi-state home care operators, as proprietary caregiver training academies and centralized procurement of FDA-registered devices reduce variable cost exposure while enabling premium positioning against fragmented local competitors. This integration choice concentrates margin capture within BrightStar Care and Griswold Home Care, insulating them from reimbursement lag pressures that compress pricing flexibility for non-integrated regional agencies.
Pricing Analysis
Volume concentrates in personal care products with thin margins, while home health aids and safety equipment generate premium returns through FDA Class II certification requirements and Medicare Part B reimbursement eligibility. Price differentiation rests on clinical credential tier and geographic service density, with hospital-at-home waiver markets in Florida and Arizona commanding rate premiums over standard home health markets. Pricing pressure stems from direct-to-consumer platform transparency, which exposes family caregivers to unbundled rate comparisons and erodes traditional franchise markup structures. Medicare Advantage plans exhibit lowest price sensitivity due to risk-based capitation, while self-pay companion services face highest elasticity as adult children comparison-shop mobile application quotes.
Supply Chain Analysis
EU MDR notified body alignment gates supplier viability, forcing recertification investments that stratify competitive access between legacy device manufacturers and compliant market entrants. Manufacturing concentrates in Germany for fall-detection sensors, China for consumable personal care products, and the United States for connected monitoring hardware requiring FDA software validation. Raw material dependencies include medical-grade polymers for adult diapers, semiconductor components for pulse oximeters, and lithium battery cells for powered mobility aids. Supply chain risk centers on single-source vulnerability for notified body audit capacity, creating bottlenecks for Class II device technical documentation reviews. Distribution runs through pharmacy networks for replenishment categories and integrated home health agencies for device-service bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU MDR recertification deadlines and state-level caregiver training hour fragmentation construct barrier-to-entry moats favoring operators with dedicated regulatory affairs functions and multi-state licensing infrastructure.
For Market Incumbents: Deepen vertical integration into proprietary caregiver training academies to offset workforce scarcity and credentialing fragmentation, while expanding hospital-at-home waiver capture through direct contracting with Medicare Advantage plans in Arizona and Pennsylvania. These moves defend against technology-enabled platforms disintermediating traditional discharge planner referral channels. For New Entrants and Emerging Players: Launch via direct-to-consumer mobile applications targeting adult children caregivers in Texas and California arranging companion services for aging parents, bypassing franchise network density requirements. White-space opportunity concentrates in AI-enabled fall prediction subscription models that reduce emergency department utilization for congestive heart failure cohorts. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated health systems seeking hospital-at-home capabilities, with long-term viability favoring operators with demonstrated CMS innovation center demonstration participation and proprietary digital intake systems. The signal to watch is CMS expansion of acute-level care waivers beyond the current 25-state pilot structure.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Completion | Notified body alignment preserves market access in German and French procurement consortia. |
| Hospital-at-Home Waiver Participation | CMS innovation center demonstration entry redirects acute-level referral volume from skilled nursing facilities. |
| Proprietary Caregiver Training Academy | Centralized credentialing reduces state-level compliance fragmentation and vacancy rate exposure. |
| Remote Patient Monitoring CPT Code Capture | New physician fee schedule billing categories create sustainable revenue streams for continuous surveillance. |
| Direct-to-Consumer Platform Launch | Mobile application transparency disintermediates traditional franchise referral economics for family caregivers. |
Research Approach
Multi-period observation of CMS reimbursement pathway modifications, FDA device classification adjustments, and state-level licensing requirement changes anchored the trend analysis, supplemented by interviews with home health agency operators, Medicare Advantage plan contracting officers, biomedical device regulatory consultants, and hospital discharge planners. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare cost report filings, EU MDR notified body registration records, and state health department training hour documentation. Bottom-up service line volume estimates triangulated against top-down national health expenditure accounts.
Segment-weighting applied differential growth assumptions across product type, service type, end user, and distribution channel dimensions, with particular sensitivity to hospital-at-home waiver expansion trajectories and remote patient monitoring CPT code utilization rates. CAGRs were derived through logistic adoption curve modeling for technology-enabled segments and demographic projection anchoring for senior population-driven categories. Reimbursement lag structures and workforce vacancy rate projections served as key forecast inputs.
EU MDR implementation delays, CMS innovation center demonstration suspension, and acute caregiver supply shocks are the dominant revision risks to modeled trajectories. A model refresh is warranted upon material change in Medicare Home Health Prospective Payment System update timing or hospital-at-home waiver geographic expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Global Ambient Assisted Living (AAL) Market
Home Healthcare
Home Care Products Market
Home Healthcare
UK Home Healthcare Market
Home Healthcare
US House Calls Market
Home Healthcare
Global Home Health Hub Market
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
Smart Mattress Market
Home Healthcare
Senior in-Home Care Services Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
Home Healthcare Market
Home Healthcare
Virtual Companion Care Market
Home Healthcare
Smart Home Healthcare Market
Home Healthcare
Chemotherapy at Home Services Market
Home Healthcare
Global Home Health Care Services Market
Home Healthcare
Outpatient Home Therapy Market
Home Healthcare
Smart Pillow Market