
 Home Diagnostics Market | 2026-2036
Home Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Home Diagnostics Market Outlook
Capital-intensity divergence between integrated diagnostics giants and point-of-care specialists is collapsing as miniaturization and cloud connectivity lower barriers to entry. Abbott Laboratories leverages vertical integration across biosensor manufacturing to sustain cost leadership in blood glucose monitoring. Roche Holding AG anchors premium positioning through molecular diagnostics platforms that compete on clinical-grade accuracy for home settings.
Home diagnostics encompasses self-administered testing devices that analyze biological specimens—blood, urine, saliva—using electrochemical, optical, or nucleic-acid amplification methods to deliver actionable health metrics outside clinical facilities. Smartphone-enabled devices integrate camera-based colorimetry and Bluetooth telemetry to transmit encrypted results to electronic health records, enabling remote physician monitoring of chronic conditions. Blood glucose monitors occupy the most mature segment with established reimbursement but thinning margins, while molecular diagnostics represents the fastest-expanding category as PCR-miniaturization and CRISPR-based assays penetrate infectious disease and cancer screening applications. Immunoassay technology dominates pregnancy and allergy testing volumes through low-cost lateral-flow manufacturing, though biosensors are displacing electrochemical strips in metabolic monitoring through continuous rather than episodic measurement.
FDA 510(k) pathways and EMA CE marking under the In Vitro Diagnostic Regulation shape product development timelines and clinical evidence requirements for home-use claims. HIPAA and GDPR compliance obligations constrain data architecture choices for cloud-connected devices, creating compliance costs that favor larger players with dedicated regulatory affairs teams. Stakeholders must monitor evolving FDA guidance on artificial-intelligence-enabled diagnostic interpretation and corresponding liability frameworks for algorithm-driven patient recommendations.
Market Dynamics
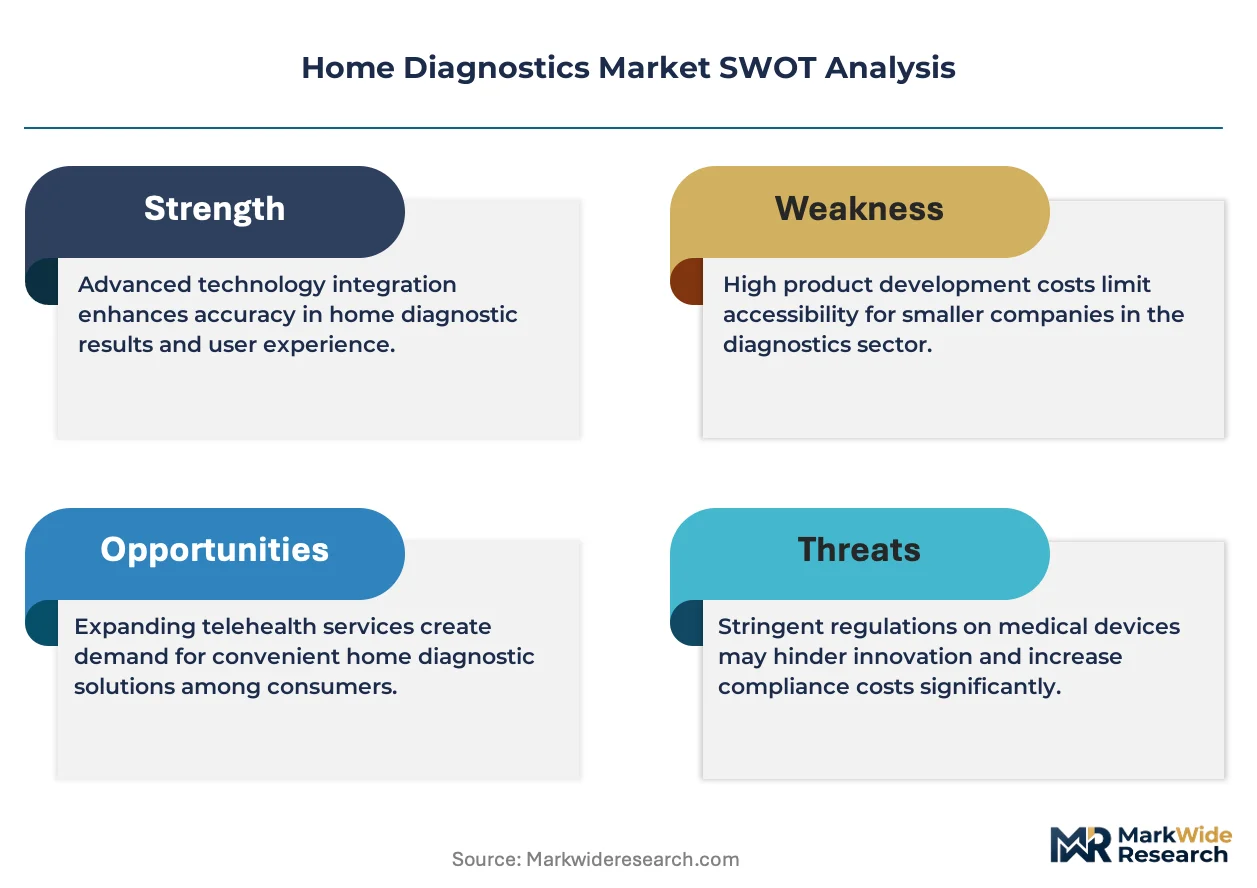
Miniaturization of nucleic-acid amplification platforms and cloud-connected biosensors is collapsing the capital barrier between clinical laboratories and home settings, forcing integrated diagnostics giants to compete directly with point-of-care specialists on cost and connectivity.
Growth Catalysts
- Reimbursement alignment for remote patient monitoring:CMS coverage expansion for continuous glucose monitoring and cardiac telemetry in the United States incentivizes physician adoption of smartphone-integrated devices for chronic disease management.
- EMA streamlined CE marking under IVDR:The European Union's In Vitro Diagnostic Regulation introduces performance-based conformity routes that accelerate market entry for software-enabled diagnostics with established clinical evidence.
- Aging demographics in Germany and Japan:Government home care subsidies and long-term care insurance structures in these markets concentrate demand for self-administered metabolic and cardiovascular monitoring among elderly populations.
Market Restraints
- Optical sensor supply concentration:Precision CMOS image sensors and narrow-band LED emitters for colorimetric assays depend on Taiwanese and South Korean semiconductor foundries, exposing manufacturers to geographic supply disruption.
- Clinical validation cost inflation:FDA 510(k) clearance for novel biomarker claims requires prospective studies against predicate devices, with per-submission costs exceeding earlier glucose monitor pathways by substantial multiples.
- Substitution by retail clinic testing:CVS MinuteClinic and Walgreens Health Corner locations offer rapid diagnostic panels with immediate physician interpretation, capturing price-sensitive consumers who might otherwise purchase home devices.
Strategic Opportunities
- Underpenetrated cancer screening in Japan:Colorectal and gastric cancer home testing kits face cultural resistance to self-collection but benefit from METI industrial policy support for preventive healthcare technology adoption.
- Convergence of CRISPR with smartphone imaging:Guide-RNA detection platforms paired with camera-based fluorescence quantification enable infectious disease identification at sensitivity thresholds previously requiring laboratory PCR.
- Direct-to-consumer pharmacy distribution:Amazon Pharmacy and Capsule fulfillment networks bypass traditional durable medical equipment channels, capturing subscription revenue from chronic condition patients seeking automated resupply.
Industry Challenges
- Biostatistician scarcity for algorithm validation:FDA guidance on artificial-intelligence-enabled diagnostic interpretation demands rigorous training-set documentation and bias mitigation protocols that exceed current talent pools in most device firms.
- HIPAA-GDPR architectural tension:Cloud-connected devices serving US and EU patients simultaneously face conflicting data localization and consent-management requirements that complicate unified platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Diagnostics Market |
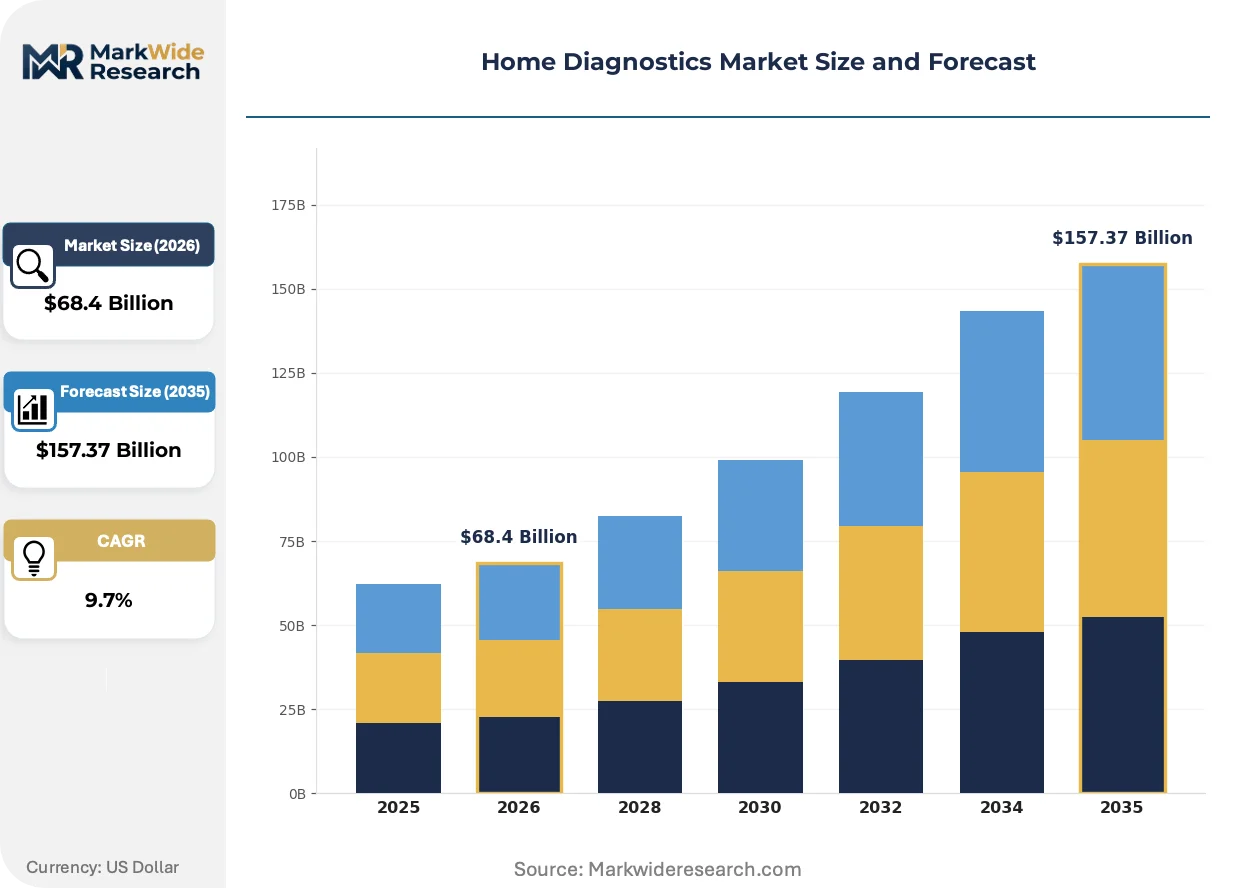
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $157.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Monitors, Pregnancy Test Kits, Cholesterol Test Kits, Allergy Test Kits Technology: Smartphone-Enabled Devices, Immunoassay, Biosensors, Molecular Diagnostics End User: Home Care Patients, Caregivers, Healthcare Providers, Individuals Distribution Channel: Online Retailers, Pharmacies, Hospital Outlets, Health Stores |
| Companies Covered | Abbott Laboratories, Roche Holding AG, Becton Dickinson & Company, ACON Laboratories, Inc., ARKRAY Inc., BTNX, Inc., Bionime Corporation, Quidel Corporation, Assure Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Diagnostics Market Strategic Shifts
Continuous biosensor formats are overtaking episodic test strips across metabolic monitoring, while regulatory frameworks race to accommodate algorithm-driven diagnostic interpretation without compromising safety thresholds.
Photonic ring resonators and graphene field-effect transistors are supplanting amperometric electrochemical strips in next-generation glucose and lactate monitors. Patients with Type 1 diabetes in Germany and the United States are adopting factory-calibrated continuous monitors at rates that compress replacement cycles from quarterly to annual. This shift is enabling subscription-based revenue models that lock in consumable revenue streams while marginalizing traditional strip manufacturers.
The EU AI Act's risk-classification framework for medical-device software is reshaping development roadmaps for diagnostic algorithms. Manufacturers must now document training-data provenance and performance across demographic subgroups before CE marking, extending timelines for machine-learning-enabled interpretation features. Blood glucose prediction algorithms and arrhythmia detection classifiers face the most stringent conformity assessment routes under this structure.
Physician practices are unbundling device procurement from interpretation services, purchasing hardware directly while outsourcing telemetry review to remote patient monitoring platforms. Cardiology groups in the United States are leading this split, contracting with independent diagnostic testing facilities for overnight oximetry and Holter analysis rather than maintaining in-house interpretation capacity. This channel fragmentation concentrates purchasing power among large practice networks while squeezing margins for device vendors dependent on bundled service revenue.
Home Diagnostics Market Segmentation
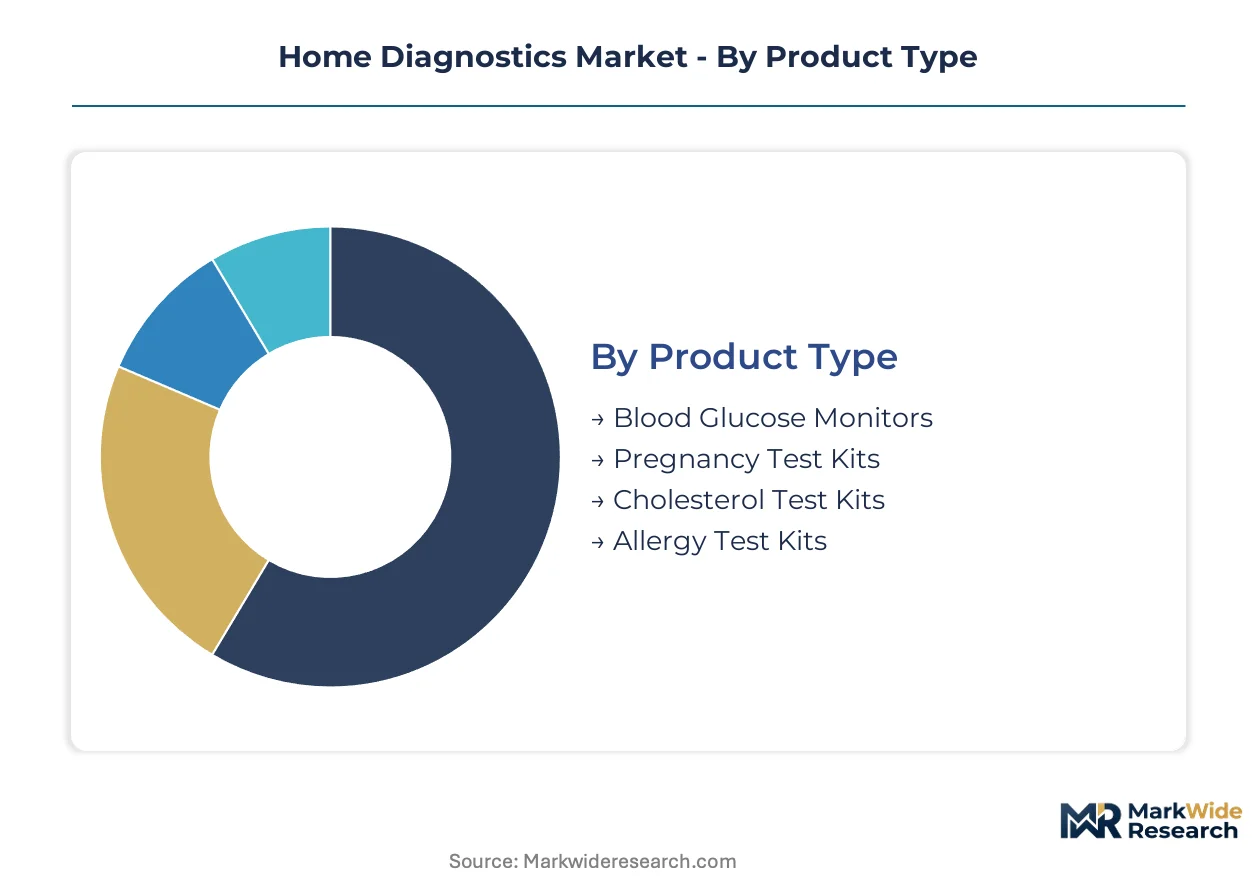
Home diagnostics segmentation reveals how regulatory pathways, technology maturation, and reimbursement structures fragment commercial opportunity across patient populations and purchase channels. Understanding these divides exposes where FDA 510(k) clearance costs concentrate versus where direct-to-consumer marketing economics dominate.
Product Type:
FDA clearance stringency varies sharply across specimen types, with blood-based assays facing predicate-device comparison requirements that urine and saliva formats largely bypass.
- Blood Glucose Monitors:Electrochemical strip technology and factory-calibrated continuous sensors dominate this segment. German and United States reimbursement codes for Type 1 diabetes patients sustain quarterly to annual replacement cycles, though photonic ring resonators are displacing amperometric strips in premium tiers.
- Pregnancy Test Kits:Lateral-flow immunoassay manufacturing at massive scale drives unit economics below competitor categories. Demand concentrates in pharmacy and online channels where privacy preferences override clinical interpretation needs.
- Cholesterol Test Kits:Fingerstick lipid panels face substitution pressure from retail clinic testing. FDA 510(k) requirements for LDL quantification accuracy limit entrant proliferation.
- Allergy Test Kits:IgE detection through skin-prick alternatives serves pollen and food sensitivity screening. Direct-to-consumer marketing bypasses physician gatekeeping that constrains prescription-dependent categories.
Established volume favors blood glucose monitors; emerging adoption favors allergy test kits.
Technology:
Cost tier stratification separates disposable consumables from capital-intensive connected platforms, with subscription revenue models now penetrating the premium tier.
- Smartphone-Enabled Devices:Bluetooth telemetry and camera-based colorimetry integrate home testing with electronic health records. HIPAA compliance costs favor larger vendors with dedicated regulatory affairs teams.
- Immunoassay:Lateral-flow manufacturing dominates pregnancy and infectious disease screening at lowest per-test cost. South Korean and Taiwanese foundry concentration for precision CMOS sensors creates supply vulnerability.
- Biosensors:Continuous glucose monitoring and lactate tracking enable real-time metabolic surveillance. German and Japanese aging demographics accelerate physician adoption for remote patient monitoring.
- Molecular Diagnostics:PCR-miniaturization and CRISPR-based assays penetrate infectious disease and cancer screening. EMA CE marking under IVDR accelerates software-enabled diagnostic entry with established clinical evidence.
Disposable economics favor immunoassay; connected platform revenue favors biosensors.
End User:
Customer type determines whether procurement flows through durable medical equipment channels or direct-to-consumer retail, with profound margin implications.
- Home Care Patients:Chronic disease management among elderly populations drives metabolic and cardiovascular monitoring demand. Japan's long-term care insurance structures concentrate subsidy flow to this segment.
- Caregivers:Proxy testing for pediatric and geriatric patients requires simplified collection protocols and clear result interpretation. Training burden limits molecular diagnostic penetration.
- Healthcare Providers:Physician practices unbundle device procurement from interpretation services, purchasing hardware directly while outsourcing telemetry review to remote monitoring platforms.
- Individuals:Wellness-oriented consumers drive allergy and fertility testing volumes through Amazon Pharmacy and direct-to-consumer fulfillment networks.
Reimbursement concentration favors home care patients; margin expansion favors individuals.
Distribution Channel:
Channel selection shapes pricing power, with subscription resupply models capturing lifetime value that transactional retail cannot match.
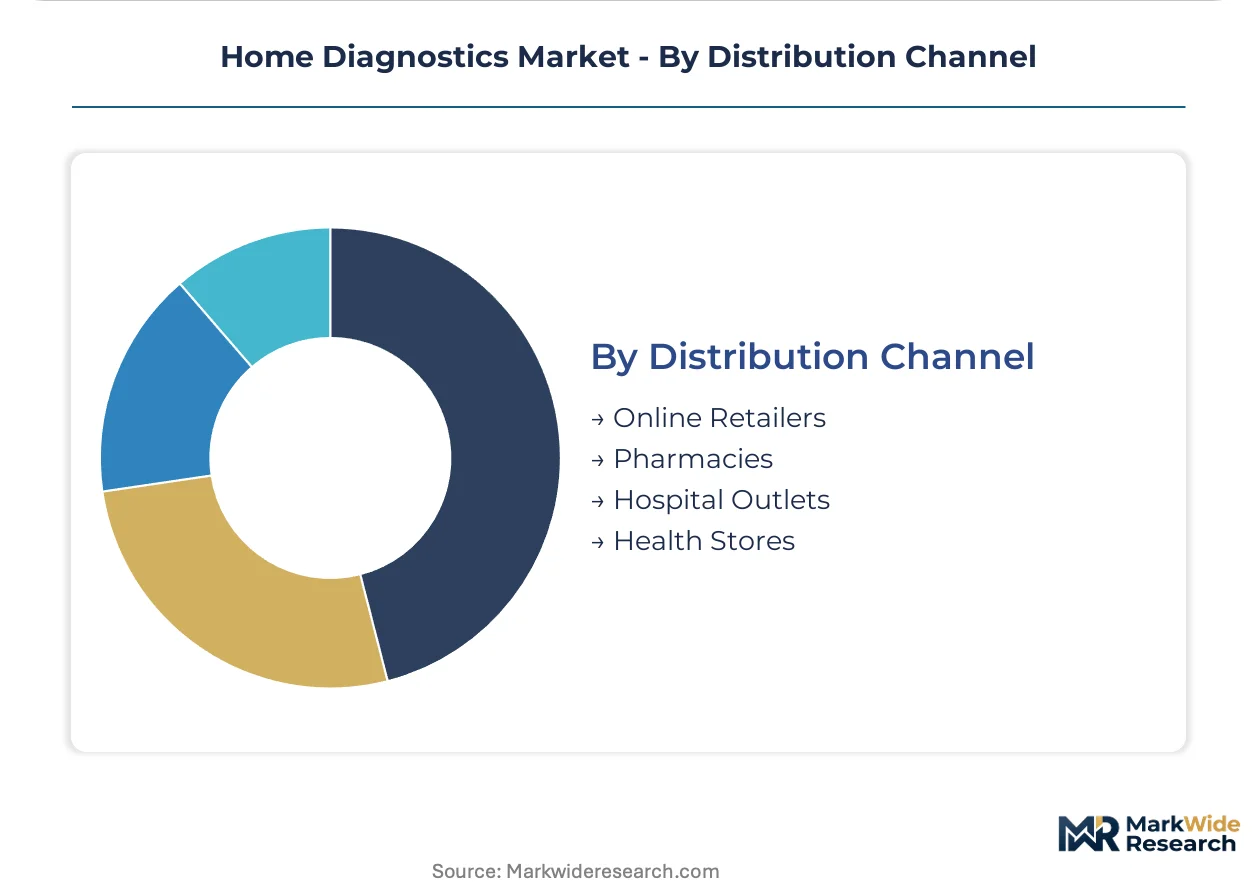
- Online Retailers:Amazon Pharmacy and Capsule networks bypass traditional durable medical equipment channels, capturing automated resupply revenue from chronic condition patients.
- Pharmacies:CVS and Walgreens locations compete with their own retail clinic testing services, creating channel conflict for home device vendors.
- Hospital Outlets:Discharge planning integration drives glucose monitor and anticoagulation testing prescriptions, though procurement committees squeeze vendor margins.
- Health Stores:Allergy and wellness testing kits reach price-sensitive consumers outside pharmacy networks, with limited clinical credibility for diagnostic claims.
Subscription lock-in favors online retailers; clinical credibility favors hospital outlets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pricing power exceeds German levels by substantial margins due to CMS reimbursement generosity, while Japanese consumers face higher out-of-pocket exposure despite METI industrial policy support for preventive healthcare technology adoption.
United States
Type 1 diabetes patients drive factory-calibrated continuous glucose monitor replacement cycles from quarterly to annual intervals. FDA 510(k) clearance pathways for smartphone-enabled devices streamline market entry for Bluetooth telemetry platforms. California's Silicon Valley concentration anchors digital health startup formation for camera-based colorimetry integration.
Germany
Aging demographics and statutory health insurance reimbursement alignment concentrate demand for metabolic and cardiovascular self-monitoring devices. EMA CE marking under IVDR accelerates software-enabled diagnostic entry with established clinical evidence. Bavaria's medical technology cluster around Munich sustains biosensor manufacturing capability for photonic ring resonator production.
Japan
Long-term care insurance structures subsidize elderly home care patients for chronic disease management applications. METI industrial policy supports preventive healthcare technology adoption despite cultural resistance to self-collection for cancer screening. Tokyo-Osaka corridor hosts precision CMOS image sensor supply relationships with Taiwanese foundries.
United Kingdom
NHS long-term plan integration of remote patient monitoring creates procurement concentration among large practice networks. MHRA post-Brexit regulatory autonomy maintains alignment with FDA guidance on artificial-intelligence-enabled diagnostic interpretation. London's digital health ecosystem attracts molecular diagnostics platform development for infectious disease screening.
South Korea
MFDS regulatory efficiency supports rapid market entry for miniaturized PCR platforms and CRISPR-based assays. National health insurance coverage expansion for diabetes management accelerates continuous biosensor adoption rates. Seoul-Suwon semiconductor cluster supplies narrow-band LED emitters for colorimetric home diagnostic devices.
Home Diagnostics Market Competitive Environment
Concentration sits with integrated diagnostics giants that leverage captive biosensor manufacturing and molecular diagnostics platforms to sustain cost leadership and premium positioning simultaneously. The competitive structure tiered between multinational conglomerates with vertical integration depth and point-of-care specialists competing on connectivity and algorithm-driven interpretation features. Strategic archetypes include integrated laboratory-to-home platform operators, continuous monitoring subscription specialists, and direct-to-consumer lateral-flow manufacturers. Dominant competitive moves encompass M&A activity targeting software-enabled telemetry capabilities and strategic partnerships with remote patient monitoring platforms for physician channel access.
Within the integrated diagnostics tier, Abbott Laboratories and Roche Holding AG occupy positions that exemplify divergent strategic postures toward home settings. Abbott's vertical integration across biosensor manufacturing sustains cost leadership in blood glucose monitoring through in-house production of electrochemical and photonic sensing elements. Roche anchors premium positioning through molecular diagnostics platforms that compete on clinical-grade accuracy for PCR-miniaturization and nucleic-acid amplification applications in home environments. ARKRAY Inc. represents the specialist archetype with concentrated exposure to metabolic monitoring markets in Japan and Germany where aging demographics concentrate demand.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Holding AG |
| Becton Dickinson & Company |
| ACON Laboratories, Inc. |
| ARKRAY Inc. |
| BTNX, Inc. |
| Bionime Corporation |
| Quidel Corporation |
| Assure Tech |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements for precision CMOS image sensors and narrow-band LED emitters lock in supply access for biosensor manufacturers while anchoring price visibility against foundry capacity volatility in Taiwanese and South Korean semiconductor clusters. These contractual structures concentrate procurement power among Abbott Laboratories and Roche Holding AG, forcing point-of-care specialists into spot-market exposure for optical components that determine colorimetric assay accuracy.
Pricing Analysis
The customization-premium spread separates factory-calibrated continuous glucose monitors from electrochemical strip systems, with photonic ring resonator configurations commanding substantial markups over amperometric alternatives. Pricing stratifies across premium, standard, and economy tiers based on Bluetooth telemetry integration and FDA 510(k) clearance tier, with reimbursement-eligible devices in the United States and Germany showing lowest price sensitivity among insured elderly populations. Cost compression in lateral-flow immunoassays intensifies as South Korean contract manufacturers scale pregnancy test volumes, squeezing margin contribution from disposable consumable categories.
Supply Chain Analysis
Inventory lead times for precision optical sensors stretch substantially beyond electrochemical strip components, exposing manufacturers to demand-supply mismatches when glucose monitor replacement cycles accelerate. Component sourcing centers on Taiwan for CMOS image sensors, South Korea for LED emitters, and Germany for photonic ring resonator substrates, with single-source vulnerability concentrated in Taiwanese foundry capacity for camera-based colorimetry modules. Distribution runs through Amazon Pharmacy subscription networks and CVS retail channels, with hospital procurement committees extracting price concessions through volume aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as smartphone-enabled diagnostics mandate interoperability with electronic health record systems and remote patient monitoring platforms, collapsing standalone device margins.
For Market Incumbents: Shield subscription revenue streams by deepening backward integration into biosensor manufacturing and securing exclusive telemetry partnerships with United States cardiology groups. FDA 510(k) clearance for algorithm-driven interpretation features provides defensive moats against software-native entrants threatening to unbundle hardware from analytics.
For New Entrants and Emerging Players: Differentiate on CRISPR-miniaturization paired with smartphone fluorescence imaging, targeting Japan's underpenetrated colorectal cancer screening segment where cultural resistance to self-collection has suppressed incumbent penetration. Direct-to-consumer pharmacy distribution through Capsule networks bypasses durable medical equipment channel gatekeeping that protects established glucose monitor franchises.
For Investors and Strategic Acquirers: Capital is best deployed toward molecular diagnostics platform operators with established EMA CE marking under IVDR and software-enabled telemetry capabilities, as these assets compound value through algorithm-driven interpretation features that resist commoditization. Watch for FDA guidance finalization on artificial-intelligence-enabled diagnostic liability frameworks as the inflection signal determining regulatory compliance cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway under IVDR | EMA streamlined conformity routes accelerate software-enabled diagnostic entry with established clinical evidence. |
| Hospital System Partnership | Physician practices unbundle device procurement from interpretation services, concentrating purchasing power. |
| Software Companion Development | Bluetooth telemetry integration with electronic health records enables remote physician monitoring revenue. |
| Reimbursement Strategy | CMS coverage expansion for continuous glucose monitoring locks in quarterly to annual replacement cycles. |
| Strategic Partnership | Remote patient monitoring platforms outsource telemetry review, fragmenting traditional bundled service revenue. |
Study Parameters
Desk research of FDA 510(k) filings, EMA CE marking databases, CMS reimbursement schedules, and hospital procurement records preceded structured interviews with biomedical engineers, GPO contracts managers, regulatory affairs leads, and remote patient monitoring platform executives. Secondary validation drew from SEC 10-K disclosures, patent filings for photonic ring resonator and graphene field-effect transistor technologies, and trade data for precision CMOS sensor imports. Bottom-up and top-down triangulation cross-checked unit volume assumptions against reimbursement code utilization and durable medical equipment channel shipments.
Variance decomposition across product type, technology platform, end-user segment, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate assumptions weighted by reimbursement eligibility and aging demographic concentration in Germany, Japan, and the United States. Forecast inputs incorporated IVDR implementation timelines, FDA guidance evolution on algorithm validation, and foundry capacity expansion for optical sensor components.
The analysis sits within stated boundaries; outcomes outside EMA regulatory alignment, CMS reimbursement continuity, or Taiwanese foundry supply stability would require recalibration. Forecasts reflect documented assumptions regarding physician adoption curves and patient compliance rates for self-administered testing protocols. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Urinalysis Market
Diagnostics
South Africa in-Vitro Diagnostics Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
Antigen Kit Market
Diagnostics
Middle East and Africa HIV Diagnosis and Treatment Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Global Liver Disease Diagnostics Market
Diagnostics
Malaria Diagnostics Market
Diagnostics
Semen Analysis Systems Market
Diagnostics
Global Artificial Intelligence (AI) in Diagnostics Market
Diagnostics
Haptoglobin Reagent Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
Global Transplant Diagnostics Market