
 Europe Wireless Healthcare Market | 2026-2036
Europe Wireless Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wireless Healthcare Market Foresight
Germany is rewriting the competitive map for wireless healthcare infrastructure through its hospital digitization programs and telemedicine reimbursement reforms. Koninklijke Philips N.V. leverages its diagnostic imaging heritage to anchor connected care ecosystems across Nordic and Benelux markets. Siemens Healthineers AG sustains deep R&D intensity in edge-computing architectures for clinical decision support. Qualcomm Technologies Inc. competes on 5G modem integration for low-latency remote surgical applications.
Europe wireless healthcare encompasses networked medical devices, software platforms, and communication protocols that transmit patient data without physical cabling, typically operating across Bluetooth Low Energy at 2.4 GHz, Wi-Fi 6/6E standards, and licensed cellular bands to enable continuous physiological monitoring and clinical intervention at distance. Its primary commercial purpose is to shift acute and chronic care delivery from centralized hospital settings toward distributed, patient-accessible endpoints. Telehealth solutions occupy the largest value pool as health systems prioritize virtual consultation platforms with embedded payment and prescription workflows. Wearable sensors represent the fastest-expanding segment, driven by diabetes and cardiovascular patient populations seeking ambulatory glucose and arrhythmia detection. Remote monitoring devices retain mature, high-margin positions in post-acute care contracts where device-plus-service bundling creates switching costs.
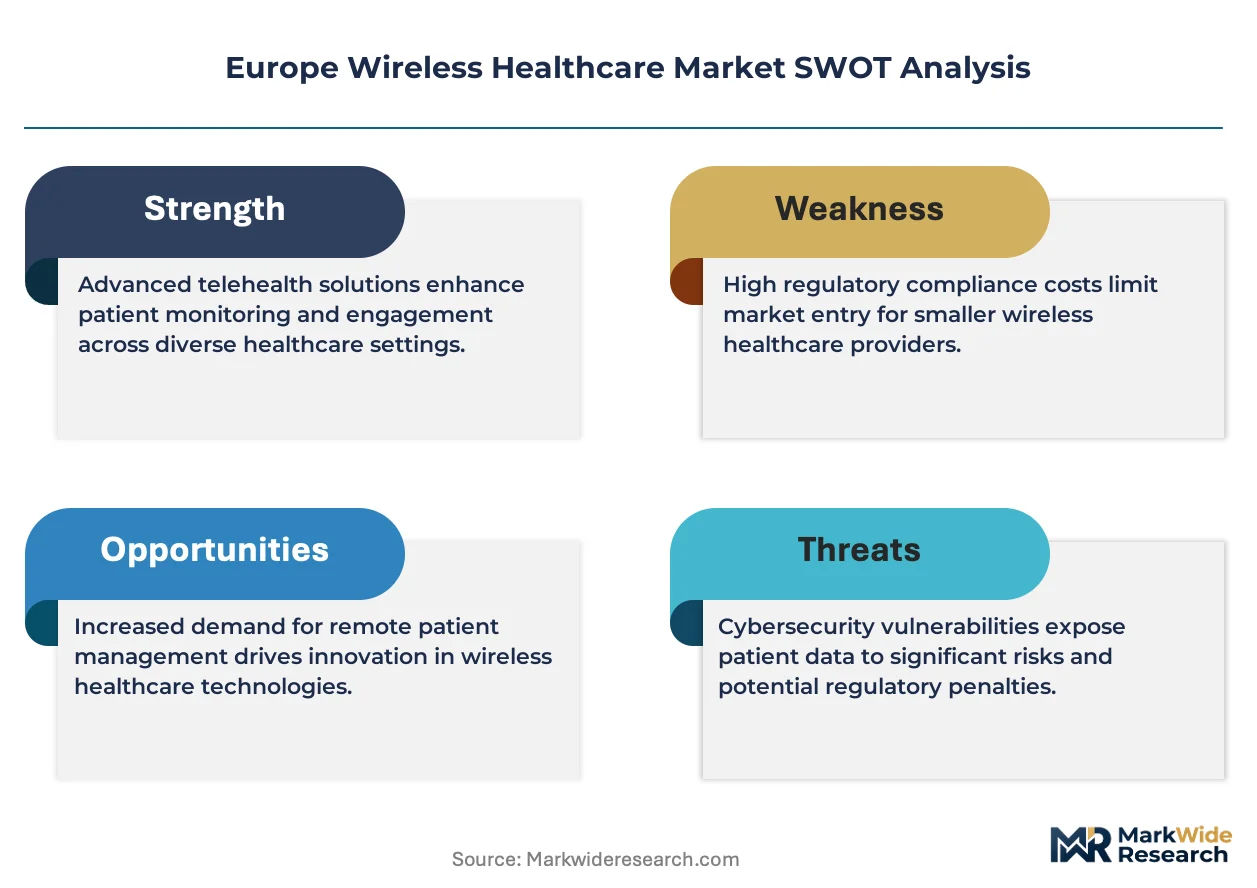
EMA oversight of software-as-a-medical-device classification, combined with EU MDR cybersecurity annexes and GDPR health data processing requirements, shapes product development timelines and cross-border deployment permissions for wireless health platforms. CE marking under MDR now demands explicit radio-frequency performance validation and post-market surveillance of connectivity failures, raising barriers for non-EU technology suppliers. Stakeholders must monitor how the EU AI Act intersects with clinical decision algorithms embedded in wireless diagnostic tools, as this regulatory overlap will determine which platforms gain scalable market access across member states.
Market Dynamics
The EU Medical Device Regulation's cybersecurity annexes are compressing product development timelines while simultaneously elevating compliance costs, forcing wireless health platform developers to rearchitect radio-frequency validation pipelines and post-market surveillance systems before CE marking approval.
Growth Catalysts
- Telemedicine reimbursement parity:Germany's statutory health insurance reforms now compensate remote consultations at rates matching in-person visits, accelerating provider investment in virtual care infrastructure.
- Bluetooth Low Energy 5.3:The updated protocol's extended advertising sets and improved coexistence algorithms enable continuous glucose monitors to operate with sub-10mW power budgets, extending wearable sensor battery life beyond fourteen days.
- Chronic disease management infrastructure:France's regional health agencies are procuring integrated remote monitoring suites for heart failure and COPD patient cohorts exceeding two million individuals.
Market Restraints
- GDPR health data processing complexity:Cross-border patient data flows require explicit member-state authorization, fragmenting cloud hosting architectures and inflating legal compliance overhead for multi-national platform deployments.
- Semiconductor supply concentration:Custom ASICs for ultra-low-power medical radio modules depend on TSMC's 22nm specialty processes, creating single-source vulnerability for European device manufacturers.
- Lithium-polymer cell chemistry limitations:Wearable form-factor constraints prevent adoption of safer solid-state alternatives, exposing manufacturers to thermal runaway liability and air-shipping restrictions under ICAO regulations.
Strategic Opportunities
- Eastern European hospital digitization:Poland and Romania are allocating cohesion funds toward connected care infrastructure, creating first-mover advantages for platforms with Polish-language clinical decision support modules.
- EU AI Act convergence:The regulation's risk-classification framework for clinical decision algorithms creates regulatory clarity that accelerates CE marking pathways for AI-embedded diagnostic wearables.
- 5G network slicing for remote surgery:Vodafone and Deutsche Telekom are deploying guaranteed-latency slices for telesurgical applications, enabling equipment vendors to offer service-level agreements below 10ms end-to-end delay.
Industry Challenges
- Embedded cybersecurity engineering scarcity:The intersection of medical device software validation and cryptographic implementation requires specialized talent pools concentrated in Eindhoven, Munich, and Cambridge clusters, constraining development velocity.
- MDR technical documentation burden:CE marking dossiers now demand explicit radio-frequency electromagnetic compatibility testing protocols and clinical evidence for connectivity failure modes, extending preparation cycles by eight to fourteen months.
- Legacy hospital IT integration friction:HL7 FHIR interoperability remains inconsistently implemented across NHS trusts and German university hospitals, forcing platform vendors to maintain multiple interface adapters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wireless Healthcare Market |
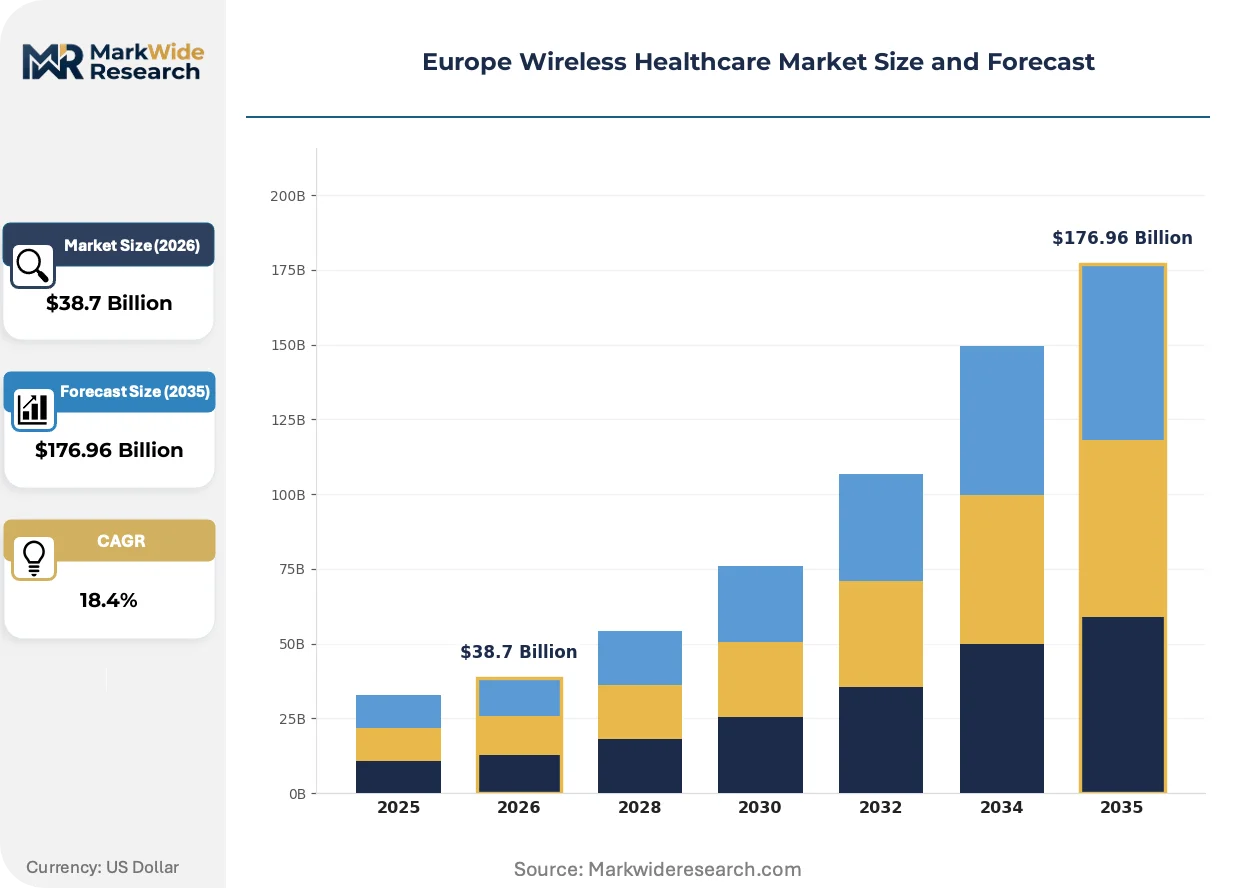
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telehealth Solutions, Remote Monitoring Devices, Wearable Sensors, Mobile Health Apps End User: Hospitals, Clinics, Homecare Providers, Patients Technology: Bluetooth, Wi-Fi, Cellular, RFID Application: Chronic Disease Management, Fitness Tracking, Medication Adherence, Diagnostic Support |
| Companies Covered | Koninklijke Philips N.V., Medtronic plc, Siemens Healthineers AG, GE Healthcare, Cisco Systems Inc., Qualcomm Technologies Inc., IBM Corporation, AT&T Inc., Motorola Solutions Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wireless Healthcare Market Shifts & Advancements
Edge-computing architectures are migrating clinical inference from centralized cloud infrastructure toward bedside and wearable processors, driven by latency requirements for real-time arrhythmia detection and data sovereignty constraints under GDPR.
Digital twin technology is virtualizing patient physiological models for predictive intervention. Cardiology departments at Charité Berlin and Karolinska Institutet are deploying heart failure simulations that ingest continuous hemodynamic streams from implantable sensors. The approach is virtualizing acute event prediction, compressing emergency department admission rates for monitored cohorts.
EMA's software-as-a-medical-device guidance revision is tightening algorithm change control requirements. Manufacturers must now submit pre-defined modification protocols for machine learning model updates, treating post-market algorithm drift as regulatory events. Diabetes management platforms with embedded insulin dosing recommendations face the steepest compliance burden, with several vendors withdrawing from European markets rather than revalidating continuous learning architectures.
Hospital procurement consortia are consolidating wireless health platform selection across multi-site networks. NHS England's MedTech Funding Mandate now requires integrated remote monitoring contracts to include outcome-based payment terms tied to hospitalization reduction metrics. Spanish autonomous community health services and Italian regional health authorities are adopting similar consolidated tender structures, compressing vendor negotiation cycles and elevating scale requirements for competitive participation.
Europe Wireless Healthcare Market Segmentation
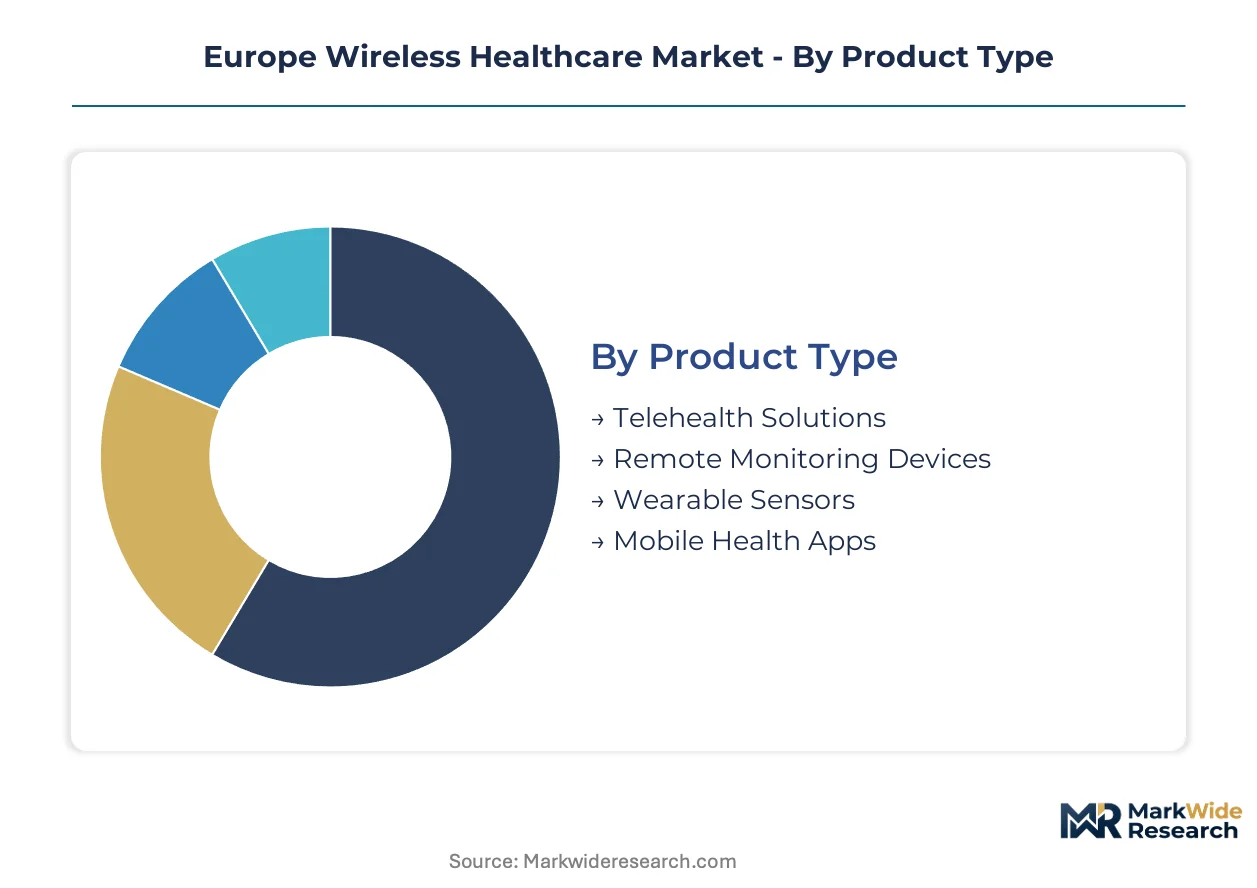
Segmentation reveals divergent investment cycles across Europe's wireless healthcare landscape. Product refresh rates vary from months for consumer-facing apps to years for regulated medical devices, reshaping vendor portfolio priorities and R&D allocation across the continent.
Product Type:
Wearable sensors turn over fastest as consumer electronics lifecycles compress medical device expectations, while remote monitoring hardware operates on extended depreciation schedules tied to hospital procurement frameworks.
- Telehealth Solutions:Cloud-native platforms integrating video consultation, e-prescribing, and billing workflows. German statutory insurers now reimburse virtual visits at parity with face-to-face consultations, accelerating platform procurement by hospital networks in Bavaria and North Rhine-Westphalia.
- Remote Monitoring Devices:Hub-and-spoke systems collecting physiological data from implantable or external sensors for clinical review. France's regional health agencies are deploying these for heart failure cohorts exceeding two million patients, with device-plus-service contracts creating multi-year switching costs.
- Wearable Sensors:Ambulatory devices for glucose, cardiac rhythm, and activity tracking. Continuous glucose monitors from Nordic manufacturers dominate pharmacy channel distribution across Denmark and Sweden.
- Mobile Health Apps:Consumer-facing software for wellness tracking and medication reminders. GDPR health data processing requirements fragment development teams between Dublin and Berlin compliance centers.
Telehealth solutions dominate installed base. Wearable sensors are where expansion concentrates.
End User:
Cost-tier stratification separates institutional buyers with capital budgets from individual consumers paying out-of-pocket, fragmenting pricing architectures and distribution channels across European markets.
- Hospitals:Acute care institutions deploying enterprise wireless infrastructure for patient monitoring and clinical workflow optimization. University hospitals in Heidelberg and Rotterdam lead procurement of edge-computing architectures for real-time decision support.
- Clinics:Outpatient facilities adopting lightweight telehealth platforms for specialist consultations. Italian regional health authorities are consolidating clinic procurement across Lombardy and Veneto.
- Homecare Providers:Organizations managing post-acute and chronic care in residential settings. German homecare networks are expanding remote patient monitoring platforms under new reimbursement codes.
- Patients:Individual consumers purchasing direct-to-consumer wearables and wellness applications. Direct sales channels concentrate in the United Kingdom and Netherlands.
Hospitals anchor procurement volume. Homecare providers are gaining share fastest.
Technology:
Radio-frequency protocol selection determines power budgets, range, and regulatory validation burden, with trade-offs between battery longevity and data throughput shaping design decisions for specific clinical applications.
- Bluetooth:Short-range wireless standard operating at 2.4 GHz, dominant in wearable glucose monitors and cardiac event recorders. Version 5.3's extended advertising sets enable fourteen-day battery life in continuous monitoring patches.
- Wi-Fi:Higher-bandwidth protocol for stationary monitoring hubs and telehealth endpoints. Hospital IT departments in Paris and Vienna prioritize Wi-Fi 6E for reduced interference with existing medical telemetry.
- Cellular:Licensed spectrum enabling wide-area connectivity for mobile patient populations. Vodafone and Deutsche Telekom are deploying network slices for guaranteed-latency remote surgical applications.
- RFID:Passive and active tagging for asset tracking and patient identification. Nordic hospitals lead adoption for pharmaceutical supply chain verification.
Bluetooth dominates wearable connectivity. Cellular is climbing the fastest for remote patient monitoring.
Application:
Maturity gradients separate established therapeutic categories with proven reimbursement pathways from emerging wellness segments still seeking sustainable monetization models.
- Chronic Disease Management:Structured programs for diabetes, heart failure, and COPD combining remote monitoring with care coordination. EMA software-as-a-medical-device oversight tightens algorithm change control for insulin dosing platforms.
- Fitness Tracking:Consumer wellness applications for activity and sleep monitoring. Spanish and Italian markets show highest per-capita adoption rates.
- Medication Adherence:Systems prompting and verifying pharmaceutical compliance. Pharmacy chains in the United Kingdom are piloting smart packaging integrations.
- Diagnostic Support:AI-embedded tools for preliminary clinical assessment. EU AI Act risk classification creates regulatory clarity accelerating CE marking for algorithmic diagnostic wearables.
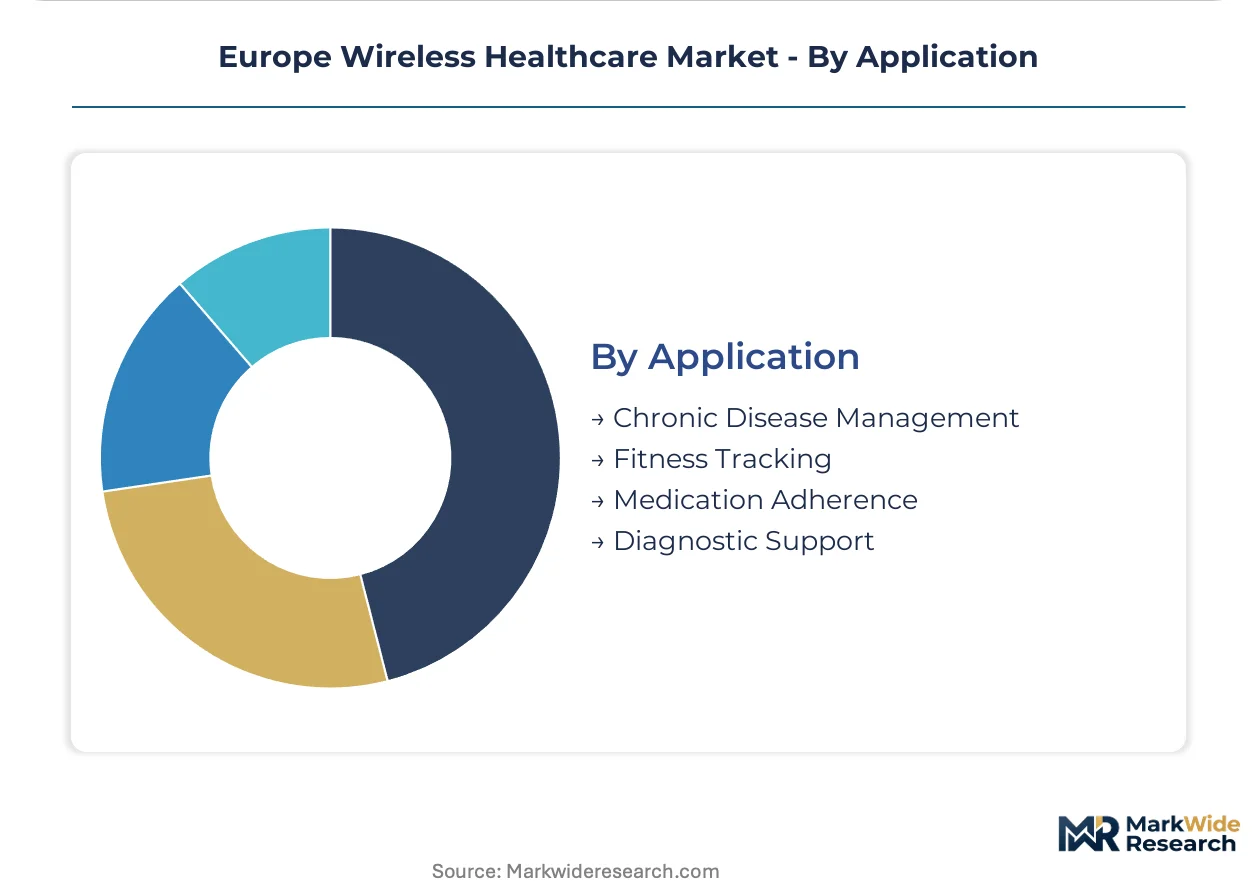
Chronic disease management dominates revenue concentration. Diagnostic support is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes wireless healthcare infrastructure through hospital digitization programs, while France and the United Kingdom prioritize homecare monitoring platforms. This consumption-mix differential reflects divergent reimbursement architectures and chronic disease management strategies across the continent.
Germany
Statutory health insurance reforms compensate remote consultations at parity with in-person visits, accelerating provider investment in virtual care infrastructure. The EU MDR cybersecurity annexes tighten CE marking requirements for connected devices. University hospitals in Heidelberg and Munich lead procurement of edge-computing architectures for real-time clinical decision support.
France
Regional health agencies procure integrated remote monitoring suites for heart failure and COPD patient cohorts exceeding two million individuals. ANSM oversight of software-as-a-medical-device classification shapes platform development timelines. The Paris-Saclay cluster concentrates telehealth platform engineering talent alongside major hospital network procurement centers.
United Kingdom
NHS England's MedTech Funding Mandate requires integrated remote monitoring contracts with outcome-based payment terms tied to hospitalization reduction metrics. GDPR health data processing requirements fragment cloud hosting architectures across member-state borders. London and the Southeast anchor digital health startup formation while Midlands trusts pilot 5G-connected ambulance services.
Netherlands
Homecare networks expand remote patient monitoring platforms under new reimbursement codes for post-acute care. Eindhoven's semiconductor ecosystem supplies ultra-low-power radio modules for wearable glucose monitors. Philips leverages its diagnostic imaging heritage to anchor connected care ecosystems across Nordic and Benelux markets.
Poland
Cohesion funds allocate capital toward connected care infrastructure in Eastern European hospital digitization programs. The EU AI Act's risk-classification framework creates regulatory clarity for AI-embedded diagnostic wearables. Warsaw and Krakow clinical centers adopt Polish-language clinical decision support modules, creating first-mover advantages for localized platforms.
Europe Wireless Healthcare Market Competitive Landscape
Capability concentration sits with diagnostic imaging and semiconductor specialists; scale advantage sits with diversified health technology conglomerates. The vendor base organizes around three strategic archetypes: heritage medical device manufacturers with installed base leverage, telecommunications infrastructure providers with 5G network assets, and semiconductor specialists with low-latency radio expertise. Dominant competitive moves include strategic partnerships between device manufacturers and cloud platform operators, plus geographic expansion through regional health authority procurement consolidation.
Within the heritage medical technology tier, Koninklijke Philips N.V. and Siemens Healthineers AG exemplify European-headquartered conglomerates with deep diagnostic imaging legacies that anchor connected care ecosystem positions. Qualcomm Technologies Inc. represents the semiconductor archetype, with its San Diego-based corporate structure and cellular modem specialization occupying a position in low-latency remote surgical applications. These three entities collectively illustrate how capability depth in adjacent medical or communications technology translates into wireless healthcare platform relevance.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Medtronic plc |
| Siemens Healthineers AG |
| GE Healthcare |
| Cisco Systems Inc. |
| Qualcomm Technologies Inc. |
| IBM Corporation |
| AT&T Inc. |
| Motorola Solutions Inc. |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp corridor freight costs shape component sourcing economics for wireless health device manufacturers, concentrating procurement power among Dutch and Belgian distributors while forcing price stratification between CE-marked premium tiers and unbundled economy alternatives.
Pricing Analysis
Long-term device-plus-service contracts dominate hospital procurement, with three-year bundled agreements locking in subscription revenues for remote monitoring platforms. Price differentiation separates MDR-certified systems with post-market surveillance obligations from economy-tier consumer wearables lacking clinical validation. Pricing pressure intensifies as German statutory insurers demand outcome-based reimbursement tied to hospitalization reduction metrics. Homecare providers exhibit highest price sensitivity due to thin operating margins, while university hospitals prioritize integration capabilities over unit cost.
Supply Chain Analysis
Silicon wafer feedstocks for ultra-low-power radio modules draw from Taiwan, South Korea, and the United States, with TSMC's 22nm specialty processes anchoring European device manufacturer dependencies. Lithium-polymer cells, ceramic capacitors, and medical-grade plastics constitute critical input categories. Single-source vulnerability concentrates in semiconductor foundry capacity, exposing procurement timelines to allocation constraints. Distribution runs through specialized medical device distributors in Munich and Eindhoven, with direct-to-hospital contracts gaining share among large health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's wireless healthcare market sits in early-cycle expansion, with Germany's telemedicine reimbursement parity creating immediate demand inflection for platform vendors.
For Market Incumbents: Pre-empt regulatory fragmentation by securing MDR cybersecurity annex compliance ahead of CE marking deadlines for connected device portfolios. Philips and Siemens Healthineers should deepen edge-computing R&D partnerships with Eindhoven semiconductor clusters to defend against Qualcomm's 5G modem integration threat. Vertical control over radio-frequency validation pipelines reduces eight-to-fourteen-month technical documentation cycles. For New Entrants and Emerging Players: Eastern European hospital digitization programs in Poland and Romania offer lowest competitive density for connected care infrastructure tenders. Polish-language clinical decision support modules create first-mover advantages in Warsaw and Krakow clinical centers. Direct procurement relationships with regional health authorities bypass entrenched distributor networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semiconductor specialists with low-latency radio expertise over pure-play telehealth software vendors. Long-term viability hinges on regulatory moats around MDR compliance and GDPR health data processing architectures. Watch for EU AI Act risk-classification rulings on clinical decision algorithms as inflection signals for AI-embedded diagnostic wearable valuations.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Cybersecurity Annex Compliance | CE marking pathways now demand explicit radio-frequency validation, elevating barriers for non-EU suppliers. |
| 5G Network Slicing Partnership | Vodafone and Deutsche Telekom guaranteed-latency slices enable sub-10ms telesurgical service agreements. |
| Edge-Computing Architecture Migration | GDPR data sovereignty constraints push clinical inference toward bedside processors at Charité Berlin and Karolinska Institutet. |
| Polish-Language Localization | Warsaw clinical centers adopt native clinical decision support, creating procurement advantages for regional platforms. |
| Outcome-Based Contracting | NHS England's MedTech Funding Mandate ties payment to hospitalization reduction metrics, reshaping vendor economics. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committees, GPO contracts managers, and regulatory affairs leads at wireless health platform developers, then refined through secondary validation against EMA software-as-a-medical-device guidance documents, EU MDR cybersecurity annexes, NHS procurement databases, and GDPR health data processing rulings. Bottom-up device shipment estimates and top-down health system expenditure allocations were triangulated to anchor market sizing.
Demand-supply balance modeling across the projection horizon incorporated technology segmentation by radio-frequency protocol, end-user tier stratification between institutional and consumer purchasers, and application maturity gradients separating chronic disease management from diagnostic support. CAGRs were derived from installed base growth rates and replacement cycle compression in wearable sensors. Forecast inputs included German statutory insurance reimbursement parity implementation and French regional health agency procurement volumes for heart failure monitoring.
Practitioners should monitor EU AI Act risk-classification rulings on clinical decision algorithms and MDR post-market surveillance connectivity failure reporting for early signals of regulatory-driven forecast revision. Cross-checking against EMA software-as-a-medical-device guidance updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Middle East and Africa Patient Monitoring Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
Patient Monitoring Systems Market
Patient Monitoring
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market
Patient Monitoring
Europe Biomedical Sensors Market
Patient Monitoring
Wearable ECG Monitors Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Respiratory Gas Monitors Market
Patient Monitoring
Bedside Monitors Market
Patient Monitoring
Dehydration Monitoring Systems Market
Patient Monitoring
B-Ketone Monitoring System Market
Patient Monitoring
China ICU Patient Monitor Market