
 Sleep Monitoring Devices Market | 2026-2036
Sleep Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Monitoring Devices Market Outlook
EU MDR is restructuring the cost-of-entry calculus for clinical-grade sleep monitors in Europe by mandating stricter biocompatibility and software validation documentation. ResMed Inc. navigates this landscape through its established respiratory-sleep overlap expertise and deep regulatory affairs infrastructure. Oura Health Oy differentiates via consumer-health bridge positioning, leveraging ring-form factor minimalism against wrist-worn saturation. Xiaomi Corporation competes on manufacturing scale, occupying aggressive price bands across Asia-Pacific consumer channels.
Sleep monitoring devices comprise sensor-integrated hardware and algorithmic software platforms that capture physiological signals—heart rate variability, blood oxygen saturation, movement patterns, and cortical electrical activity—to generate sleep architecture assessments and respiratory event indices. Pulse oximetry-enabled wearables dominate volume shipments due to low unit cost and consumer familiarity, while EEG monitoring commands premium positioning in clinical validation workflows where polysomnography correlation determines reimbursement eligibility. Smart mattresses anchor the fastest-growing product category as hospitality and senior living operators embed fleet-level sleep analytics into wellness service contracts.
FDA 510(k) pathways govern US market access for diagnostic sleep devices, with the agency scrutinizing algorithm performance against AASM scoring criteria for apnea-hypopnea index equivalence. Japan's PMDA and METI coordinate on harmonizing software-as-medical-device classifications for AI-augmented sleep staging tools, creating dual-track compliance obligations for multinational vendors. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring that increasingly incorporate sleep-derived biomarkers into chronic disease management bundles.
Market Dynamics
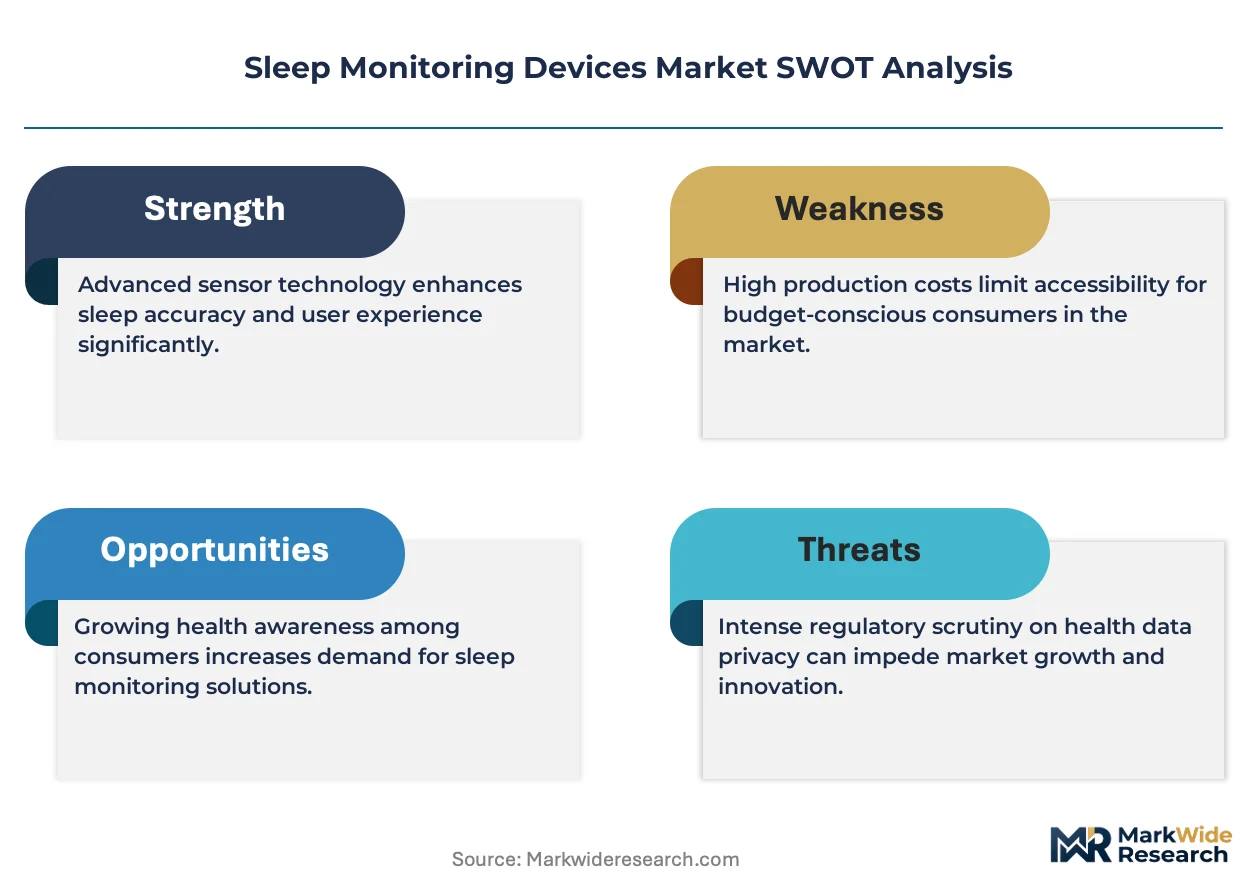
The convergence of EU MDR compliance mandates with AI-augmented diagnostic algorithms is restructuring competitive entry costs and accelerating vendor consolidation across clinical-grade sleep monitoring segments.
Growth Catalysts
- EU MDR Software-as-Medical-Device Classification:Harmonized validation requirements for AI sleep staging tools are creating predictable reimbursement pathways for EEG-integrated systems in Germany and France.
- METI Sleep Health Initiatives:Japan's Ministry of Economy, Trade and Industry is underwriting prescription-integrated monitor deployment across geriatric care networks.
- Hospital-at-Home Expansion:US Medicare remote patient monitoring code expansions are incorporating sleep-derived biomarkers into chronic disease management bundles for heart failure and COPD cohorts.
Market Restraints
- EEG Electrode Biocompatibility Certification:EU MDR Annex I requirements for prolonged skin-contact materials are extending clinical device approval timelines by 14-18 months.
- Semiconductor Foundry Concentration:Taiwan-based MEMS sensor fabrication bottlenecks are constraining pulse oximetry module availability for mid-tier wearable manufacturers.
- Polysomnography Substitution Ceiling:Consumer wrist-worn devices remain non-reimbursable for diagnostic apnea-hypopnea index determination in most US payer contracts.
Strategic Opportunities
- India PLI Medical Device Scheme:Production-linked incentives for local manufacturing of Class C diagnostic hardware are attracting contract assembly investments for Asia-Pacific distribution.
- Smart Mattress Fleet Analytics:Hospitality and senior living operators are embedding sleep quality metrics into wellness service contracts as differentiated amenities.
- FDA Breakthrough Device Designation:Expedited review pathways for AI-augmented sleep staging algorithms are compressing time-to-reimbursement for novel neurological biomarker applications.
Industry Challenges
- Algorithm Validation Talent Scarcity:Clinical sleep scoring expertise and machine learning engineering capabilities rarely coexist within single product development teams.
- Legacy EHR Integration Complexity:HL7 FHIR interoperability gaps between cloud-based sleep platforms and hospital information systems are delaying enterprise sales cycles.
- ISO 14155 Clinical Investigation Burden:Prospective validation studies for software-as-medical-device sleep monitors require 24-36 month follow-up periods for apnea-hypopnea index correlation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Monitoring Devices Market |
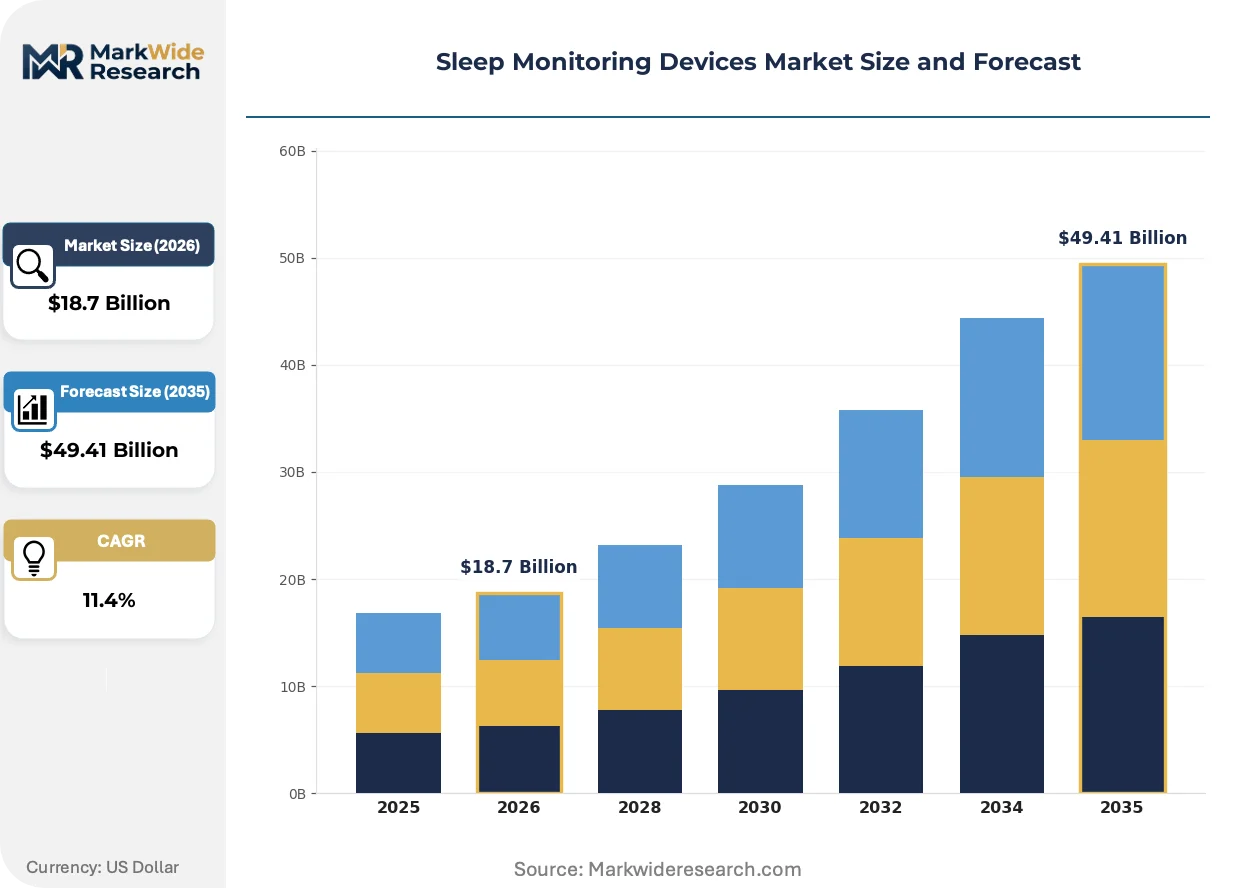
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Sleep Trackers, Smart Mattresses, Bed Sensors Technology: Actigraphy, EEG Monitoring, Infrared Sensors, Pulse Oximetry End User: Consumers, Healthcare Providers, Sleep Clinics, Researchers Application: Sleep Apnea Management, Sleep Quality Tracking, Sleep Research, Wellness Monitoring |
| Companies Covered | Garmin Ltd., Oura Health Oy, ResMed Inc., Xiaomi Corporation, Withings, Fitbit, Apple Inc., Huawei Device Co Ltd., Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Monitoring Devices Market Strategic Shifts
Non-contact radar and ballistocardiography sensing modalities are displacing electrode-dependent architectures, while regulatory frameworks race to classify algorithmic sleep staging as reimbursable diagnostic output.
Radar-based contactless sleep monitoring is expanding into senior living and hospitality deployments where skin-adhesive electrodes create compliance friction. Marriott International and Brookdale Senior Living are piloting under-mattress radar arrays for unobtrusive respiratory event detection. This modality is compressing the addressable market for wearable pulse oximeters in institutional settings by eliminating charging dependencies and skin irritation liabilities.
Japan's PMDA and METI coordination on harmonized software-as-medical-device classifications is creating dual-track compliance obligations for AI-augmented sleep staging tools. Vendors must simultaneously satisfy clinical validation requirements and cybersecurity attestation standards. Multinational manufacturers are responding by establishing Tokyo-based regulatory affairs subsidiaries to manage parallel submission workflows.
Provider purchasing committees are consolidating sleep monitor procurement under integrated remote patient monitoring vendor relationships. Health systems including Kaiser Permanente and Intermountain Healthcare are bundling sleep-derived biomarker feeds into existing cardiac and pulmonary RPM contracts. This concentration is most visible in US Medicare Advantage networks where per-member-per-month capitation models reward consolidated data platform adoption.
Sleep Monitoring Devices Market Segmentation
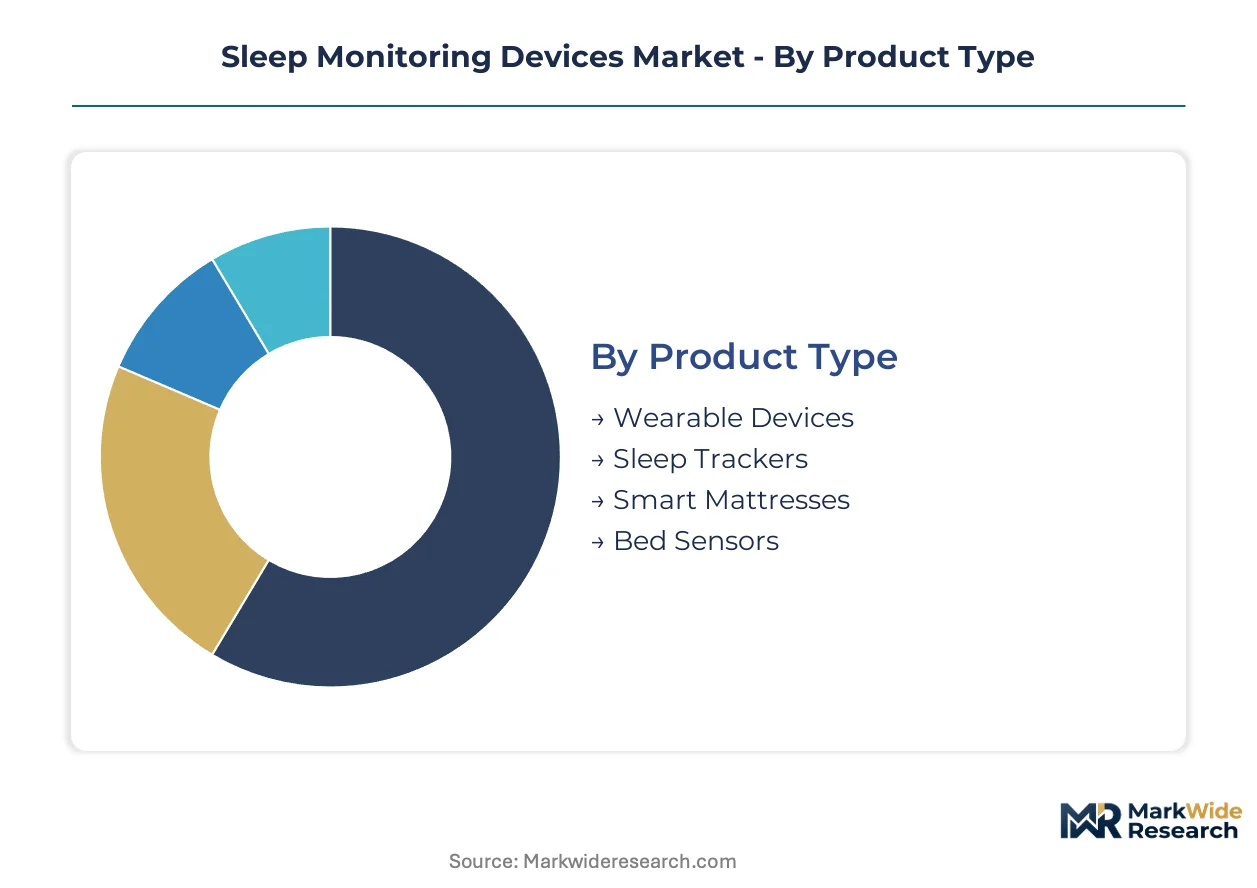
Sleep monitoring devices fragment across hardware form factors, sensing modalities, and reimbursement pathways. Each segment carries distinct capital requirements, regulatory burdens, and customer acquisition economics that reshape vendor positioning.
Product Type:
Wearable devices demand the heaviest upfront investment in MEMS sensor fabrication and algorithm validation infrastructure.
- Wearable Devices:Wrist-worn and ring-form hardware integrating accelerometers, optical heart rate sensors, and SpO2 photoplethysmography. Procurement concentrates among US Medicare Advantage networks embedding sleep biomarkers into cardiac RPM bundles, constrained by FDA 510(k) algorithm performance thresholds against AASM scoring criteria.
- Smart Mattresses:Pressure-sensor arrays and ballistocardiography modules embedded within mattress infrastructure. Hospitality operators including Marriott International are piloting fleet-level deployments for wellness service differentiation, compressing addressable volume for consumer wearables in institutional settings.
- Sleep Trackers:Under-mattress or bedside non-contact monitors utilizing radar or acoustic sensing. Japan's geriatric care networks are expanding procurement under METI-backed sleep health initiatives.
- Bed Sensors:Discrete adhesive or clip-on sensors attaching to existing bedding. Lower unit economics attract price-sensitive Asia-Pacific consumer channels.
Wearable devices absorb the bulk of installed capacity; smart mattresses are expanding most quickly.
Technology:
Technology selection determines reimbursement eligibility and clinical validation burden across regulatory jurisdictions.
- Pulse Oximetry:Photoplethysmography-based SpO2 monitoring dominates shipment volumes through low unit cost and consumer familiarity. Taiwan-based MEMS foundry bottlenecks are constraining module availability for mid-tier manufacturers.
- EEG Monitoring:Electroencephalography systems capturing cortical electrical activity for sleep architecture staging. German sleep clinics are expanding procurement as EU MDR tightens clinical-grade device requirements for polysomnography correlation.
- Actigraphy:Accelerometer-based movement pattern analysis for circadian rhythm assessment. Consumer health applications in wellness monitoring drive volume.
- Infrared Sensors:Non-contact thermal and motion detection for respiratory event identification. Senior living operators favor unobtrusive deployment eliminating skin-adhesive compliance friction.
Pulse oximetry anchors current shipment volumes; EEG monitoring commands premium positioning in clinical validation workflows.
End User:
Customer type dictates pricing power, contract duration, and data integration requirements.
- Healthcare Providers:Hospital systems and integrated delivery networks bundling sleep monitoring into remote patient management. Kaiser Permanente and Intermountain Healthcare are consolidating procurement under existing cardiac and pulmonary RPM contracts.
- Sleep Clinics:Specialized diagnostic facilities requiring polysomnography-correlated output for apnea-hypopnea index determination. EU MDR Annex I biocompatibility requirements are extending approval timelines.
- Consumers:Direct-to-purchase individuals seeking wellness insights without prescription integration. Price sensitivity drives Asia-Pacific volume concentration.
- Researchers:Academic and pharmaceutical investigators requiring raw signal access and algorithm transparency. Niche demand with extended sales cycles.
Healthcare providers command the largest contract values; sleep clinics are tightening technical specifications fastest.
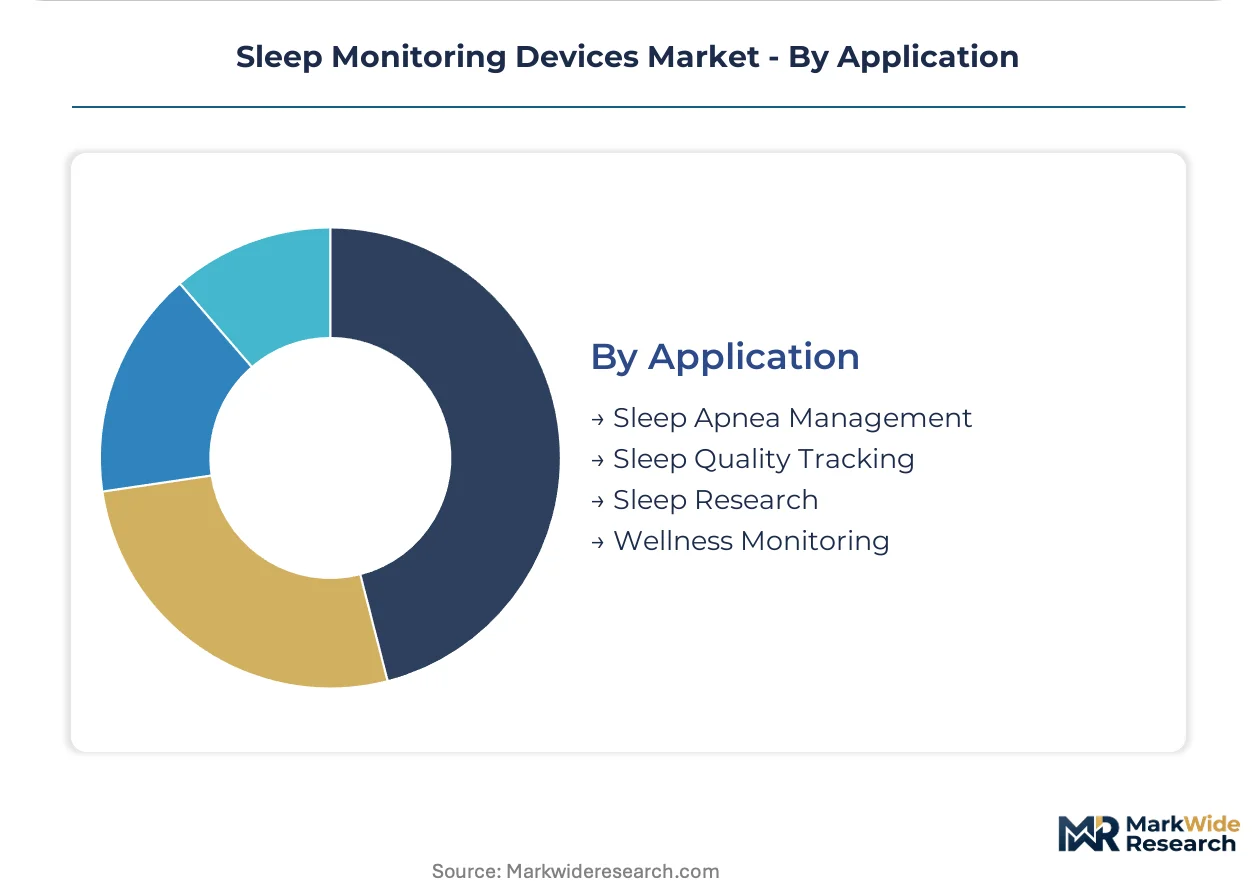
Application:
Use case segmentation aligns with reimbursement code availability and chronic disease management integration.
- Sleep Apnea Management:Diagnostic and therapeutic monitoring for obstructive and central sleep apnea. US Medicare remote patient monitoring code expansions are incorporating sleep-derived biomarkers into heart failure and COPD management bundles.
- Wellness Monitoring:General sleep quality and recovery tracking for lifestyle optimization. Consumer channel dominance with limited reimbursement coverage.
- Sleep Quality Tracking:Architecture assessment including REM, deep sleep, and latency metrics. Bridge positioning between clinical and consumer segments.
- Sleep Research:Protocol-driven data collection for academic and pharmaceutical studies. ISO 14155 clinical investigation requirements impose 24-36 month validation timelines.
Sleep apnea management captures the bulk of reimbursable revenue; wellness monitoring is climbing the fastest through consumer channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Bangalore are concentrating contract manufacturing for pulse oximetry modules and MEMS sensors. These tax-advantaged corridors attract assembly investments targeting Asia-Pacific distribution networks. Germany's MedTech clusters anchor European clinical-grade device production.
United States
Medicare Advantage networks in California and Texas are embedding sleep biomarkers into cardiac remote patient monitoring bundles. FDA 510(k) pathways govern diagnostic device market access, with algorithm performance scrutinized against AASM scoring criteria. Minneapolis-St. Paul hosts a concentration of medical device engineering talent serving provider purchasing committees.
Germany
Sleep clinics in Bavaria and North Rhine-Westphalia are expanding procurement of EEG-based systems. EU MDR Annex I biocompatibility requirements for prolonged skin-contact materials are extending clinical device approval timelines. Berlin-Brandenburg clusters house regulatory affairs subsidiaries managing harmonized software-as-medical-device classifications.
Japan
Aging demographics in Kanto and Kansai regions are accelerating provider adoption of prescription-integrated monitors. METI sleep health initiatives underwrite deployment across geriatric care networks. Tokyo-based regulatory affairs subsidiaries manage parallel PMDA submission workflows for AI-augmented sleep staging tools.
China
Consumer channel volume concentrates in Yangtze River Delta and Pearl River Delta manufacturing corridors. MIIT standards and NMPA software-as-medical-device classifications create dual-track compliance for multinational vendors. Shenzhen Special Economic Zone hosts contract assembly investments for wearable pulse oximetry modules.
India
Production-linked incentives under the PLI Medical Device Scheme are attracting assembly investments for Class C diagnostic hardware. CDSCO regulatory pathways for software-enabled devices are harmonizing with ISO 14155 clinical investigation standards. Karnataka and Maharashtra clusters are developing component sourcing capabilities for Asia-Pacific distribution.
Sleep Monitoring Devices Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies into three archetypes: respiratory-sleep overlap specialists leveraging deep regulatory infrastructure; consumer-health bridge players emphasizing minimal form factors; and manufacturing-scale operators occupying aggressive price bands. Consolidation pressures intensify as EU MDR compliance costs reshape entry economics. Dominant competitive moves include strategic partnerships with hospitality operators and portfolio diversification into smart mattress fleet analytics.
Among diversified technology conglomerates, Apple Inc. and Xiaomi Corporation occupy positions spanning consumer electronics and health monitoring verticals. Garmin Ltd. and Huawei Device Co Ltd. exemplify the wearable-specialist archetype, with geographic origins in Kansas and Shenzhen respectively anchoring distinct regional channel strategies. ResMed Inc. and Koninklijke Philips N.V. represent the respiratory-sleep overlap tier, leveraging established clinical validation workflows. Oura Health Oy and Withings sit within the premium-consumer bridge segment, where ring-form and hybrid-watch minimalism differentiates against wrist-worn saturation.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Oura Health Oy |
| ResMed Inc. |
| Xiaomi Corporation |
| Withings |
| Fitbit |
| Apple Inc. |
| Huawei Device Co Ltd. |
| Koninklijke Philips N.V. |
| Others |
Value Chain & Pricing Dynamics
Radar-based contactless sensing is displacing electrode-dependent architectures across institutional sleep monitoring deployments, simultaneously compressing manufacturing costs for hospitality fleet buyers while concentrating component sourcing around Taiwan-based MEMS foundries and Shenzhen assembly corridors. This modality shift redraws procurement economics by eliminating consumable electrode expenses and skin-contact biocompatibility certification burdens.
Pricing Analysis
Short lead-time premiums of 15-25% apply to EEG-integrated systems for German sleep clinics facing EU MDR approval bottlenecks, while spot inventory discounts emerge for pulse oximetry modules amid Taiwan foundry overcapacity. Three-tier pricing structure across premium clinical-grade, standard prescription-integrated, and economy consumer wellness levels dominates, with FDA 510(k) certification tier and software validation depth as primary price differentiation drivers. Pricing pressure stems from Xiaomi Corporation's manufacturing scale aggression across Asia-Pacific consumer channels. Direct-to-consumer wellness buyers exhibit highest price sensitivity; hospital purchasing committees demonstrate lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from hospitality operators like Marriott International, while distributor networks serve fragmented sleep clinic procurement across Germany and Japan. Component concentration centers on Taiwan for MEMS pulse oximetry sensors, China for pressure-sensor mattress arrays and radar modules, and Germany for EEG electrode biocompatible materials. Raw material dependencies include indium tin oxide for transparent conductive films, medical-grade silicones for skin-contact electrodes, and rare-earth elements for precision magnetometers. Single-source vulnerability around Taiwan semiconductor fabrication poses structural risk. Distribution runs through medical device GPOs for healthcare provider contracts and consumer electronics retail for wellness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sleep monitoring market is transitioning from electrode-dependent polysomnography correlation toward radar-based contactless validation, with AI-augmented sleep staging algorithms replacing legacy manual scoring workflows.
For Market Incumbents: Anchor defensive positioning through backward integration into MEMS sensor fabrication and captive algorithm development teams combining clinical sleep scoring expertise with machine learning engineering. ResMed Inc. and Koninklijke Philips N.V. must fortify regulatory affairs infrastructure against EU MDR software-as-medical-device classification complexity. Priority lever: consolidate procurement relationships with Kaiser Permanente and Intermountain Healthcare under expanded remote patient monitoring bundles. For New Entrants and Emerging Players: Begin with white-space targeting of India's geriatric care networks under PLI Medical Device Scheme incentives, where CDSCO regulatory pathways are harmonizing with ISO 14155 standards. Smart mattress fleet analytics for senior living operators present the most penetrable institutional segment. Go-to-market angle: partner with Brookdale Senior Living or comparable operators for pilot deployments validating radar-based respiratory event detection against polysomnography correlation. For Investors and Strategic Acquirers: Re-rating potential sits with AI-augmented sleep staging algorithm developers holding FDA Breakthrough Device Designation, given expedited reimbursement pathway catalysts and neurological biomarker application expansion. Long-term viability over the next decade hinges on software-as-medical-device classification durability and EHR interoperability execution. Acquisition target archetype: clinical validation-stage platforms with completed ISO 14155 investigations. Signal to watch: CMS remote patient monitoring code expansions incorporating sleep-derived biomarkers into chronic disease management bundles.| Strategic Initiative | Industry Significance |
|---|---|
| EEG Electrode Biocompatibility Certification Investment | EU MDR Annex I compliance secures German sleep clinic procurement against 14-18 month approval delays. |
| Radar-Based Contactless Sensing Platform Launch | Marriott International fleet pilots validate hospitality wellness service differentiation without skin-adhesive friction. |
| Tokyo Regulatory Affairs Subsidiary Establishment | PMDA-METI parallel submission workflows capture Japan prescription-integrated monitor deployment subsidies. |
| Hospital System RPM Bundle Partnership | Kaiser Permanente cardiac monitoring contracts embed sleep biomarkers into per-member-per-month capitation models. |
| AI Sleep Staging Algorithm FDA Submission | Breakthrough Device Designation compresses time-to-reimbursement for novel neurological biomarker applications. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with biomedical engineers, hospital purchasing committee members, sleep clinic medical directors, and GPO contracts managers. Primary fieldwork combined with validation against FDA 510(k) submission databases, EU MDR notified body documentation, PMDA approval registers, and METI sleep health initiative disbursement records. Bottom-up shipment modeling triangulated against top-down reimbursement code analysis.
Data-stream reconciliation across unit shipment projections, average selling price trajectories, and reimbursement code expansion timelines informed analytical framework construction across the projection horizon. Segmentation dimensions modeled include hardware form factor, sensing technology modality, end-user archetype, and application use case, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs were derived from installed base growth rates and replacement cycle analysis, incorporating Taiwan foundry capacity constraints and EU MDR approval timeline extensions as industry-specific forecast inputs.
Underlying measurement precision varies by segment; clinical-grade EEG systems carry tighter precision than consumer wellness wearables due to structured reimbursement code documentation. Forecasts reflect assumptions around semiconductor foundry capacity normalization, EU MDR software-as-medical-device classification stability, and CMS remote patient monitoring code expansion continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Germany Patient Monitoring Market
Patient Monitoring
Real Time Health Monitoring Devices Market
Patient Monitoring
Asia-Pacific Fetal and Neonatal Monitoring Market
Patient Monitoring
Infusion Rate Monitoring Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Global Patient Monitoring Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
Dehydration Monitoring Systems Market
Patient Monitoring
Wearable Heart Monitoring Devices Market
Patient Monitoring
Germany Blood Glucose Monitoring Market
Patient Monitoring
Global Hemodynamic Monitoring System Market
Patient Monitoring
Patient Monitoring Accessories Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Neuro-Monitoring System Market
Patient Monitoring
Healthcare Biosensors IoT Market
Patient Monitoring
Multi-Channel Remote ECG Monitors Market