
 Remote Home Monitoring Systems Market | 2026-2036
Remote Home Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Home Monitoring Systems Market Analytics
The capital-intensity gap between professionally installed and self-monitored offerings is collapsing as subscription economics reshape vendor priorities. ADT Inc. leverages its nationwide technician network to sustain recurring revenue density in professionally managed security. SimpliSafe, Inc. competes through direct-to-consumer positioning that minimizes upfront hardware friction. Google Inc. anchors its ecosystem play by bundling Nest thermostats and cameras with cloud storage tiers.
Remote home monitoring systems comprise networked sensors, cameras, and control hubs that communicate through low-power wireless protocols to enable real-time property oversight from distant locations. Typical deployments integrate motion detectors with 1080p video streams and cloud-based alert routing to smartphones, serving both intrusion detection and environmental anomaly identification. Wi-Fi and Z-Wave connectivity segments dominate unit shipments, though Zigbee is gaining traction in energy management applications where mesh resilience matters. Health monitoring represents the fastest-growing application vertical as pulse-oximetry and fall-detection peripherals merge with traditional security infrastructure. Cameras and sensors together capture the majority of hardware margin pools, while thermostat and alarm hardware increasingly function as loss-leader entry points for service contracts.
The FCC governs wireless spectrum allocation for device communication, while FDA oversight applies to health-monitoring peripherals that cross into medical device classification. State-level privacy statutes in California and Illinois are forcing firmware architects to localize video processing and encrypt biometric data at the edge. Stakeholders must weigh the pace of Medicare reimbursement expansion against the fragmentation of state privacy compliance before committing to regional manufacturing footprints.
Market Dynamics
Subscription economics are collapsing the capital-intensity gap between professionally installed and self-monitored offerings, forcing vendors to prioritize recurring revenue density over upfront hardware margins.
Growth Catalysts
- Medicare Advantage expansion:Supplemental benefits in the United States increasingly subsidize in-home monitoring for chronic disease management, creating institutional demand pull for health-integrated sensor deployments.
- FCC broadband infrastructure investments:Federal Communications Commission funding is expanding addressable markets for connected sensor deployments in previously underserved rural and exurban areas.
- Aging-in-place demographics:Elderly homeowners across North America and Western Europe are accelerating hardware and service adoption as institutional care costs rise and independent living preferences strengthen.
Market Restraints
- Silicon supply concentration:Semiconductor fabrication for sensor microcontrollers remains concentrated in East Asian foundries, exposing hardware vendors to geopolitical disruption and capacity constraints.
- State privacy fragmentation:California and Illinois biometric statutes force firmware architects to localize video processing and encrypt data at the edge, multiplying compliance engineering costs across jurisdictions.
- Cellular module cost volatility:LTE-M and NB-IoT radio components face input cost pressure from rare earth processing bottlenecks and substrate material shortages.
Strategic Opportunities
- Energy management convergence:Zigbee mesh resilience is gaining traction where utilities deploy demand-response programs, enabling thermostat and sensor bundling for grid-interactive home ecosystems.
- Fall-detection peripheral integration:Pulse-oximetry and accelerometer peripherals merging with security infrastructure represent untapped white space in health-monitoring applications.
- Direct-to-consumer channel maturation:Minimal upfront hardware friction through online self-installation is opening underpenetrated younger homeowner segments previously priced out of professional monitoring contracts.
Industry Challenges
- Edge AI firmware talent scarcity:Computer vision engineers capable of implementing on-device biometric processing without cloud dependency command premium compensation and extended recruitment timelines.
- Legacy security protocol integration:Z-Wave and Zigbee hub architectures must interoperate with decades-old hardwired alarm panels in retrofit installations, complicating commissioning workflows.
- FDA medical device classification ambiguity:Health-monitoring peripherals crossing into diagnostic thresholds trigger extended certification timelines that delay product launches and freeze R&D roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Home Monitoring Systems Market |
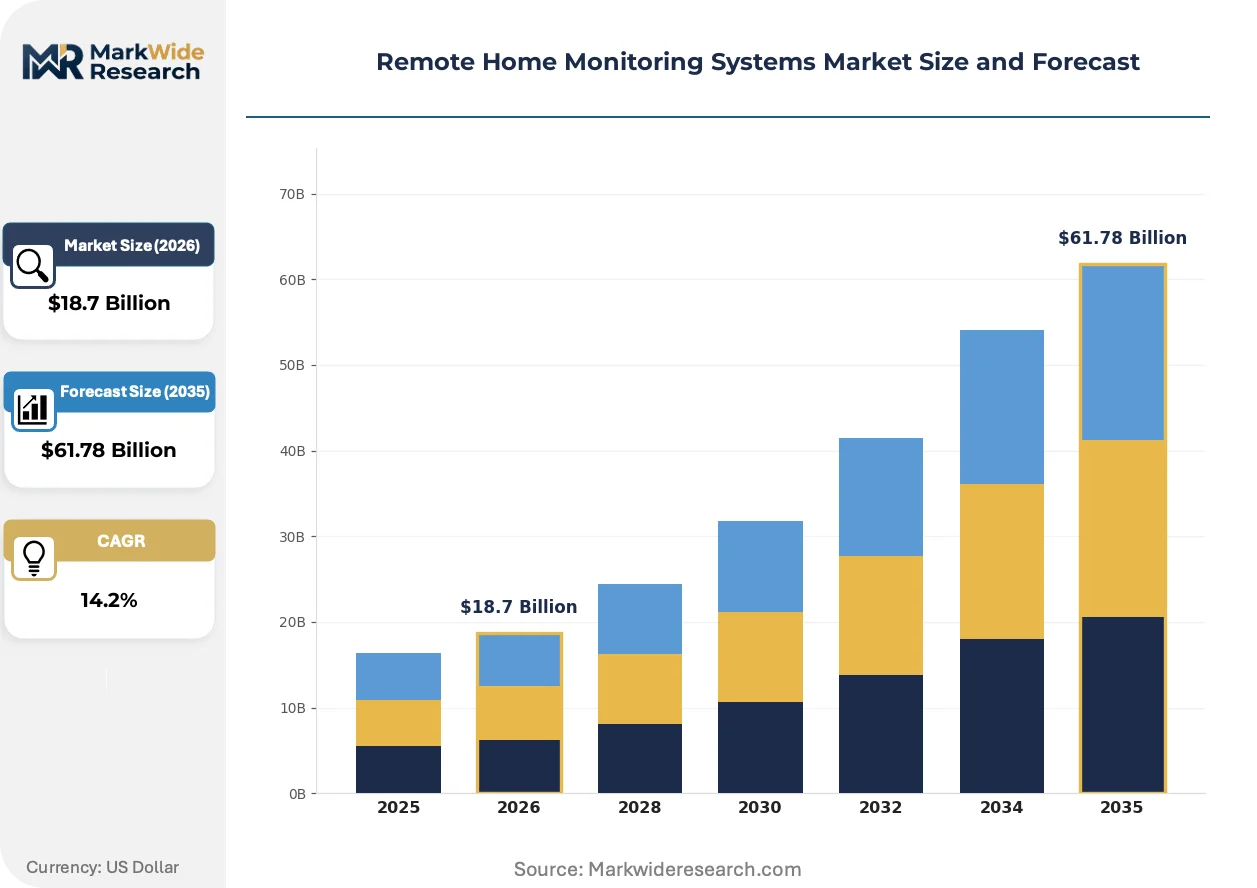
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth Application: Security, Energy Management, Health Monitoring, Automation End User: Homeowners, Renters, Property Managers, Caregivers Device Type: Cameras, Sensors, Alarms, Thermostats |
| Companies Covered | ADT Inc., Vivint Smart Home, Inc., SimpliSafe, Inc., Ring LLC, Honeywell International Inc., Google Inc., Samsung Electronics Co., Ltd., Bosch Security Systems, Inc., Frontpoint Security Solutions, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Home Monitoring Systems Market Evolving Landscape
Wireless protocol unbundling and edge computing migration are fragmenting the traditional hub-centric architecture, enabling distributed intelligence that reduces latency and cloud dependency.
Wi-Fi 6E and Thread radio stacks are decomposing the historical dominance of Z-Wave and Zigbee in residential sensor networks. Multi-protocol silicon from Nordic Semiconductor and Silicon Labs allows single-chip implementations that previously required dedicated radios. This convergence is compressing hardware bill-of-materials costs while expanding interoperability across competing ecosystem boundaries.
GDPR and the EU AI Act are mandating algorithmic transparency for biometric identification systems deployed in European households. Manufacturers must document training data provenance and enable user-facing explainability for fall-detection and facial recognition outputs. France's CNIL has issued binding guidelines that push processing toward edge localization, accelerating on-device neural network deployment.
Homeowners are unbundling monitoring contracts from hardware purchase decisions, treating sensors as depreciating appliances rather than service-tethered assets. Amazon and Google retail channels now dominate initial equipment acquisition, displacing security dealer showrooms for first-time buyers. This pattern is most visible in United States suburban markets where brand familiarity and return policies outweigh professional installation assurances.
Remote Home Monitoring Systems Market Segmentation
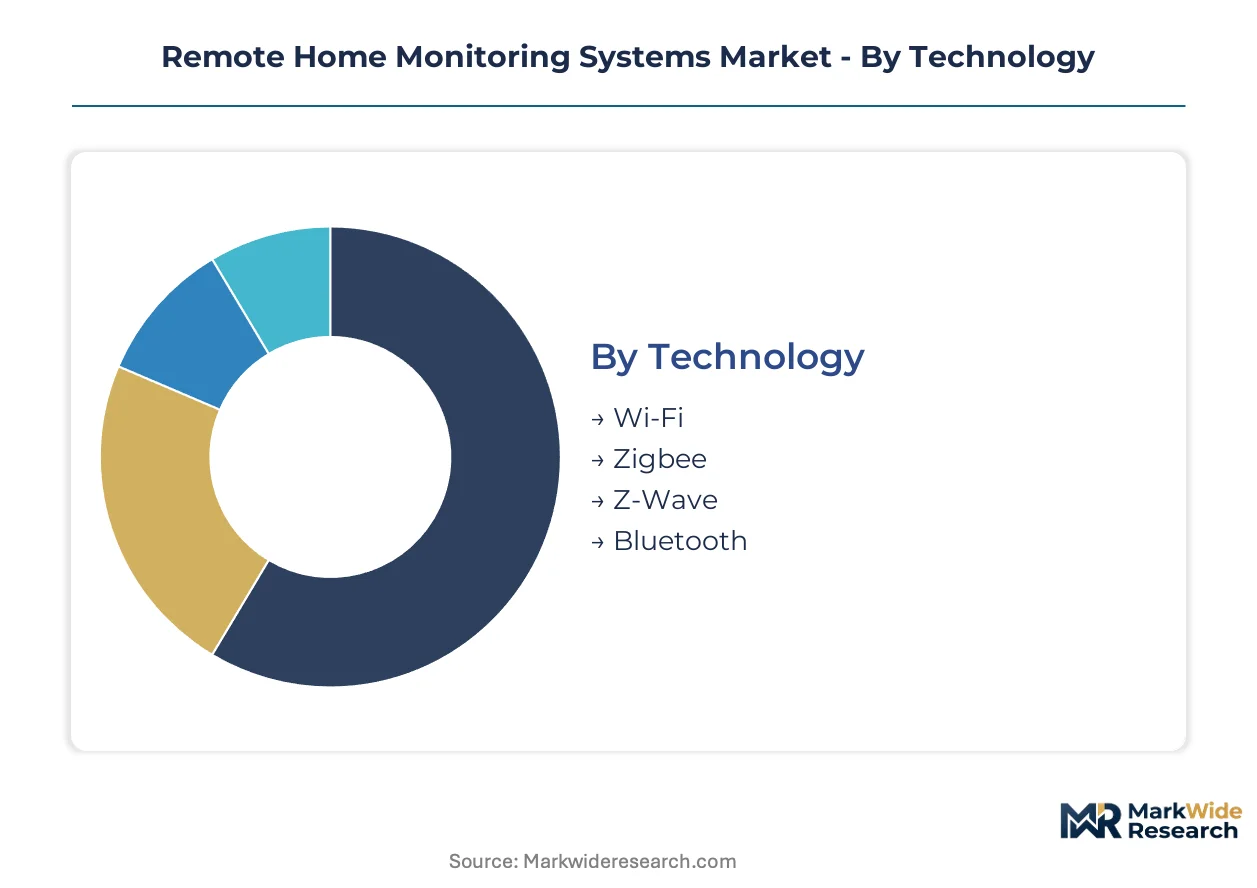
Remote home monitoring systems fragment across protocol standards, use cases, and buyer archetypes. Each segmentation axis reveals distinct margin structures and substitution vulnerabilities that reshape vendor positioning.
Technology:
Wi-Fi faces the strongest substitution pressure as Thread and Matter protocols erode its dominance in new construction deployments.
- Wi-Fi:Ubiquitous IP-based connectivity leveraging existing residential infrastructure. Demand concentrates in United States suburban retrofits where router density eliminates hub costs, though congestion in 2.4 GHz bands degrades performance in dense apartment blocks.
- Zigbee:Mesh networking protocol optimized for low-power sensor arrays. European utilities in Germany and France are driving demand through demand-response programs that reward grid-interactive thermostat deployments.
- Z-Wave:Sub-GHz proprietary mesh with superior wall penetration. Commands premium in United States professionally monitored security installations where dealer certification programs lock in ecosystem loyalty.
- Bluetooth:Short-range protocol dominating wearable peripheral connections. Apple and Google ecosystem bundling accelerates adoption for health-monitoring wristbands and fall-detection pendants.
Wi-Fi retains volume leadership; Bluetooth holds the steepest expansion curve.
Application:
Security applications command the highest service attach rates, while energy management faces margin compression from utility subsidy programs.
- Security:Intrusion detection through motion sensors, glass-break detectors, and perimeter cameras. United States professionally monitored contracts sustain recurring revenue density despite self-install alternatives.
- Energy Management:Thermostat and load-control optimization for demand-response participation. Zigbee mesh resilience matters most where French and German utilities deploy time-of-use pricing incentives.
- Health Monitoring:Pulse-oximetry, fall-detection, and medication adherence peripherals. Medicare Advantage supplemental benefits in the United States create institutional demand pull for chronic disease management.
- Automation:Scene-based lighting, climate, and access control orchestration. Younger homeowners in United Kingdom urban markets treat automation as standard rather than premium feature.
Security retains volume leadership; Health Monitoring holds the steepest expansion curve.
End User:
Property managers face the most acute substitution threat from integrated building management systems that absorb residential monitoring functions.
- Homeowners:Primary decision-makers with equity stake in property protection. Aging-in-place demographics in the United States and United Kingdom accelerate hardware adoption among elderly cohorts.
- Renters:Price-sensitive segment prioritizing portability and lease-friendly installation. Direct-to-consumer channels with minimal upfront friction capture this cohort.
- Property Managers:Multi-unit operators seeking centralized oversight across portfolios. United States institutional landlords deploy sensors for vacancy monitoring and maintenance dispatch.
- Caregivers:Family members and professional aides monitoring elderly or disabled residents. Japanese and German long-term care insurance programs subsidize sensor deployments.
Homeowners retain volume leadership; Caregivers hold the steepest expansion curve.
Device Type:
Standalone alarm hardware faces existential pressure from smartphone-native notification systems that eliminate dedicated siren requirements.
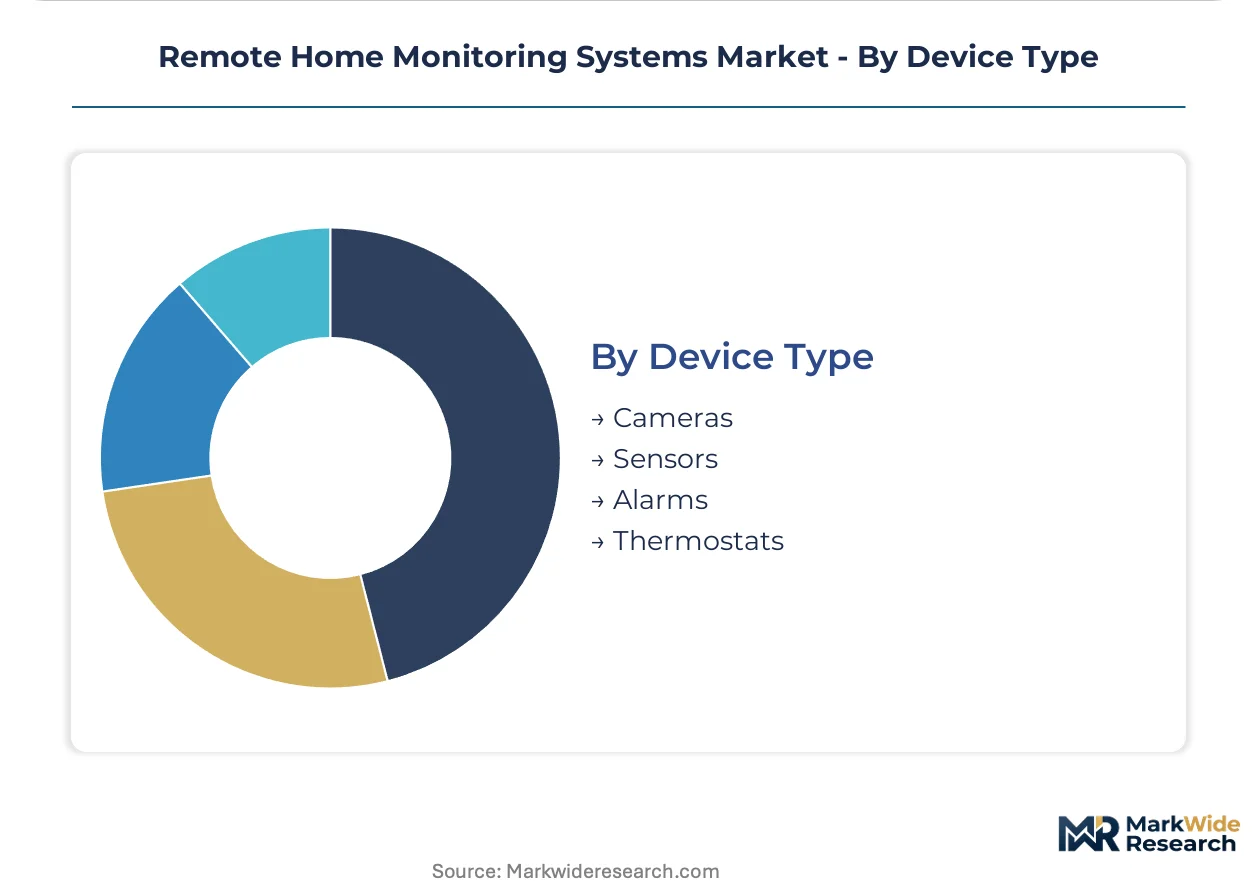
- Cameras:1080p and 4K video streams with cloud storage tiers. Edge AI firmware for on-device person detection reduces latency and privacy exposure in California and Illinois jurisdictions.
- Sensors:Motion, door-window, water leak, and environmental detectors. Z-Wave and Zigbee variants dominate professional installations; Wi-Fi sensors capture self-install growth.
- Alarms:Audible sirens and strobe lights for intrusion deterrence. Increasingly bundled as loss-leader entry points rather than standalone margin contributors.
- Thermostats:Climate control with occupancy sensing and utility program integration. Nest and Ecobee ecosystem bundling displaces independent HVAC controller sales.
Cameras retain volume leadership; Sensors hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between markets emphasizing health-integrated monitoring versus those prioritizing security-centric deployments. Medicare Advantage subsidies in the United States drive chronic disease management applications, while European demand concentrates on energy management and data privacy compliance. Asia-Pacific adoption remains nascent, with Japan and South Korea leading through aging demographics and smart city infrastructure.
United States
Medicare Advantage supplemental benefits subsidize in-home monitoring for chronic disease management, creating institutional demand pull for health-integrated sensor deployments. The FCC's broadband infrastructure investments expand addressable markets in previously underserved rural and exurban areas. Greater Boston and the Pacific Northwest host dense clusters of sensor startups developing edge AI firmware for privacy-compliant video processing.
Germany
Utilities in Baden-Württemberg and North Rhine-Westphalia deploy demand-response programs rewarding grid-interactive thermostat deployments through Zigbee mesh networks. The EU AI Act mandates algorithmic transparency for biometric identification systems, forcing manufacturers to document training data provenance. Munich's industrial corridor concentrates R&D activity for energy management convergence between security and climate control systems.
United Kingdom
Aging-in-place demographics accelerate hardware adoption among elderly cohorts seeking independent living alternatives to institutional care. GDPR compliance requirements push processing toward edge localization, accelerating on-device neural network deployment. London's suburban markets exhibit the strongest pattern of homeowners unbundling monitoring contracts from hardware purchase decisions.
Japan
Long-term care insurance programs subsidize sensor deployments for family caregivers monitoring elderly residents. METI standards guide interoperability protocols for smart home ecosystems integrating health and security functions. The Kansai region around Osaka hosts manufacturing clusters for fall-detection peripherals merging with traditional security infrastructure.
France
CNIL binding guidelines enforce edge localization for biometric data processing, multiplying compliance engineering costs for cloud-dependent architectures. French utilities leverage Zigbee mesh resilience for time-of-use pricing incentives in Île-de-France and Auvergne-Rhône-Alpes. Lyon and Grenoble anchor development clusters for pulse-oximetry peripherals crossing into medical device classification thresholds.
Remote Home Monitoring Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with subscription economics collapsing historical capital-intensity gaps between professionally installed and self-monitored offerings. The market structure reflects consolidation around recurring revenue density rather than upfront hardware margins. Three archetypes dominate: nationwide technician networks sustaining professional monitoring contracts, direct-to-consumer channels minimizing installation friction, and ecosystem players bundling sensors with cloud storage tiers. Competitive moves concentrate on strategic partnerships with utilities for demand-response programs and vertical integration into edge AI firmware development.
Within the professional monitoring tier, ADT Inc. and Vivint Smart Home, Inc. exemplify the technician-network model that locks in ecosystem loyalty through dealer certification programs. SimpliSafe, Inc. occupies a distinct position in the direct-to-consumer vector, representing the minimal-friction approach that opens underpenetrated younger homeowner segments. These three companies collectively illustrate the strategic divergence between recurring revenue density and upfront hardware margin capture that defines current competitive positioning.
| Leading Market Players |
|---|
| ADT Inc. |
| Vivint Smart Home, Inc. |
| SimpliSafe, Inc. |
| Ring LLC |
| Honeywell International Inc. |
| Google Inc. |
| Samsung Electronics Co., Ltd. |
| Bosch Security Systems, Inc. |
| Frontpoint Security Solutions, LLC |
| Others |
Value Network & Pricing Analysis
FCC equipment authorization requirements gate both supply qualification and price differentiation simultaneously, as Sub-GHz radio certifications for Z-Wave modules create tiered vendor access that separates premium professional installations from economy self-install segments. Medicare Advantage reimbursement thresholds further stratify pricing by conditioning subsidy eligibility on FDA-cleared health peripherals, compressing margins for uncertified alternatives while amplifying returns for compliant systems.
Pricing Analysis
Long-term service contracts dominate hardware monetization, with recurring subscription revenue offsetting upfront sensor costs across 36-month terms. Three-tier pricing structure across premium, standard, and economy levels reflects installation modality—professionally monitored Z-Wave deployments command certification premiums, while Wi-Fi self-install alternatives compete on hardware minimization. Cost compression in cellular-connected tiers is intensifying because LTE-M module shortages force vendors to absorb radio cost volatility. Renters exhibit acute price sensitivity, whereas institutional caregivers prioritize reimbursement eligibility over hardware expenditure.
Supply Chain Analysis
Strategic stockpiling of semiconductor inventory distinguishes professional security vendors from direct-to-consumer players exposed to spot-market microcontroller volatility. Taiwan, South Korea, and China anchor sensor microcontroller fabrication, while Malaysia and Mexico concentrate final assembly for North American distribution. Rare earth processing bottlenecks in Chinese substrate facilities constrain NB-IoT radio availability. Distribution runs through certified dealer networks for Z-Wave ecosystems, whereas Wi-Fi and Thread variants bypass intermediaries via Amazon and Google retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Matter protocol interoperability is collapsing ecosystem silos, transforming hardware margins into platform-access fees as homeowners unbundle monitoring from equipment purchase. This shift rewards firmware-capable vendors while commoditizing hub-centric architectures.
For Market Incumbents: Consolidate technician certification networks to lock in Z-Wave ecosystem loyalty against Thread-enabled challengers. Deepen backward integration into edge AI firmware development to satisfy California and Illinois biometric encryption mandates without cloud dependency. Prioritize Medicare Advantage partnership density to secure chronic disease management reimbursement streams. For New Entrants and Emerging Players: Caregiver-facing service layers represent underexploited white space where incumbents under-serve family monitoring workflows beyond basic intrusion alerts. Japan and Germany long-term care insurance programs offer the most penetrable reimbursement pathways. Pursue direct-to-consumer positioning with portable Bluetooth peripherals that bypass professional installation entirely. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed professional monitoring networks carrying heavy technician infrastructure overhead against declining installation margins. Five-to-ten-year viability hinges on successful SaaS transition from hardware-tethered contracts. Watch Medicare Advantage supplemental benefit expansion rates as the decisive inflection signal for health-integrated sensor demand.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Firmware Development | On-device biometric processing satisfies CNIL and state privacy mandates without cloud latency. |
| Utility Demand-Response Partnership | Zigbee mesh bundling with French and German time-of-use programs creates grid-interactive revenue streams. |
| Medicare Advantage Reimbursement Strategy | FDA-cleared pulse-oximetry peripherals unlock institutional subsidy pools for chronic disease monitoring. |
| Multi-Protocol Silicon Integration | Nordic Semiconductor and Silicon Labs chipsets collapse dedicated radio costs while expanding interoperability. |
| Direct-to-Consumer Channel Maturation | Amazon and Google retail dominance displaces dealer showrooms for first-time buyer acquisition. |
Research Methodology
Desk research of FCC equipment authorization databases, FDA 510(k) filings, and utility demand-response program disclosures preceded structured interviews with professional monitoring network operators, smart home platform engineers, Medicare Advantage plan administrators, and semiconductor procurement leads. Secondary validation drew from EIA energy consumption surveys, CMS Medicare supplemental benefit data, and EU AI Act implementation guidance. Bottom-up sensor shipment modeling triangulated against top-down service revenue estimates.
Variance decomposition across protocol standards, installation modalities, and reimbursement eligibility clusters shaped analytical framework construction over the projection horizon. Segmentation dimensions included connectivity technology, application vertical, end-user archetype, and device category. CAGRs derived from logistic diffusion curves calibrated to aging-in-place demographic trajectories and broadband infrastructure deployment schedules. Medicare Advantage enrollment expansion and FCC rural connectivity funding trajectories served as primary demand-side forecast inputs.
Underlying assumptions cover stable semiconductor foundry capacity allocation, with deviation risk concentrated in East Asian geopolitical disruption and rare earth export restrictions. Forecasts reflect reimbursement policy continuity and privacy regulation enforcement intensity. Revision becomes warranted when Medicare supplemental benefit coverage thresholds cross institutional adoption tipping points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Compartment Syndrome Monitoring Devices Market
Patient Monitoring
ECG Monitoring System Market
Patient Monitoring
Epro, E-Patient Diaries and Ecoa Market
Patient Monitoring
Global Patient Monitoring Market
Patient Monitoring
South America Remote Patient Monitoring Systems Market
Patient Monitoring
Europe Biomedical Sensors Market
Patient Monitoring
Germany Blood Glucose Monitoring Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
Central Patient Monitoring System Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market
Patient Monitoring
Respiratory Monitoring Devices Market
Patient Monitoring
Global Intrapartum Monitoring Devices Market