
 North America Body Temperature Monitoring Market | 2026-2036
North America Body Temperature Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
North America Body Temperature Monitoring Market Analytics
Bluetooth-enabled continuous monitoring is narrowing the performance gap between hospital-grade and home-use thermometry, compressing the traditional three-tier product hierarchy into two functional classes. Hill-Rom anchors the acute-care segment through its installed base of patient monitoring platforms. Exergen Corporation differentiates on temporal artery infrared technology, sustaining premium positioning in outpatient settings. OMRON Healthcare competes aggressively in the homecare channel, leveraging its cardiovascular device distribution to cross-sell temperature monitors.
Body temperature monitoring encompasses devices that measure core or surface thermal status through thermistor, infrared, or thermocouple sensing elements, typically resolving to 0.1°C accuracy for clinical decision-making. The primary commercial purpose centers on infection screening, fever surveillance, and physiological status tracking across human and veterinary populations. Infrared scanners lead the product type hierarchy in revenue contribution, though continuous monitors represent the fastest-expanding margin pool as subscription telemetry models penetrate long-term care facilities. Digital technology dominates unit volume, while thermocouple sensors retain niche dominance in critical care applications requiring sub-second response times.
FDA device classification under 21 CFR 880.2920 shapes predicate pathway requirements for clinical thermometers, while HIPAA governs data transmission from connected monitors into electronic health records. Health Canada and the U.S. EPA regulate mercury-containing device disposal, accelerating the phase-out of legacy glass thermometers. Stakeholders must monitor CMS reimbursement coding for remote patient monitoring, as temperature data streams become reimbursable telemetry inputs under evolving billing guidelines.
Market Dynamics
Bluetooth-enabled continuous monitoring is collapsing the traditional hospital-home-ambulatory device hierarchy into two functional tiers, forcing incumbents to defend installed bases against subscription telemetry models penetrating long-term care networks.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined predicate clearance for contactless infrared thermometers reduces time-to-market for next-generation devices, particularly benefiting ambulatory surgery centers standardizing fever screening protocols.
- Remote patient monitoring reimbursement:CMS billing code expansions for temperature telemetry in skilled nursing facilities convert capital equipment sales into recurring revenue streams, attracting private equity into device-leasing platforms.
- Integrated health system consolidation:Northeast U.S. hospital networks are mandating unified temperature protocols across acute and outpatient sites, creating sole-source procurement opportunities for platform vendors.
Market Restraints
- Mercury disposal compliance costs:EPA and Health Canada regulations on legacy glass thermometer retirement impose hazardous waste handling burdens on rural clinics with limited reverse logistics infrastructure.
- Infrared sensor supply concentration:Thermopile detector manufacturing concentrates in East Asian fabs, exposing U.S. and Canadian device assemblers to lead-time volatility and tariff exposure.
- Clinical accuracy skepticism:Temporal artery readings show ambient temperature sensitivity in uncontrolled environments, limiting deployment confidence in home settings without supervised calibration.
Strategic Opportunities
- Canadian long-term care expansion:Provincial health authorities in Ontario and British Columbia are funding connected monitor installations in nursing homes, creating first-mover advantages for telemetry-integrated vendors.
- Veterinary temperature monitoring:Livestock operations and companion animal clinics represent an underpenetrated adjacent market with lower regulatory barriers and faster replacement cycles than human clinical settings.
- AI-driven predictive fever algorithms:Machine learning integration with continuous streams enables early sepsis detection, opening high-value subscriptions in ICU step-down units.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for Bluetooth Low Energy stack optimization and HIPAA-compliant edge processing faces talent competition from consumer wearables manufacturers.
- Multi-jurisdiction calibration validation:Devices must demonstrate traceability to NIST standards for U.S. deployment and NRC certification for Canadian commercial sale, doubling pre-market testing timelines.
- EHR integration complexity:HL7 FHIR connectivity requires custom middleware development for each major electronic health record platform, fragmenting engineering resources across Epic, Cerner, and MEDITECH implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Body Temperature Monitoring Market |
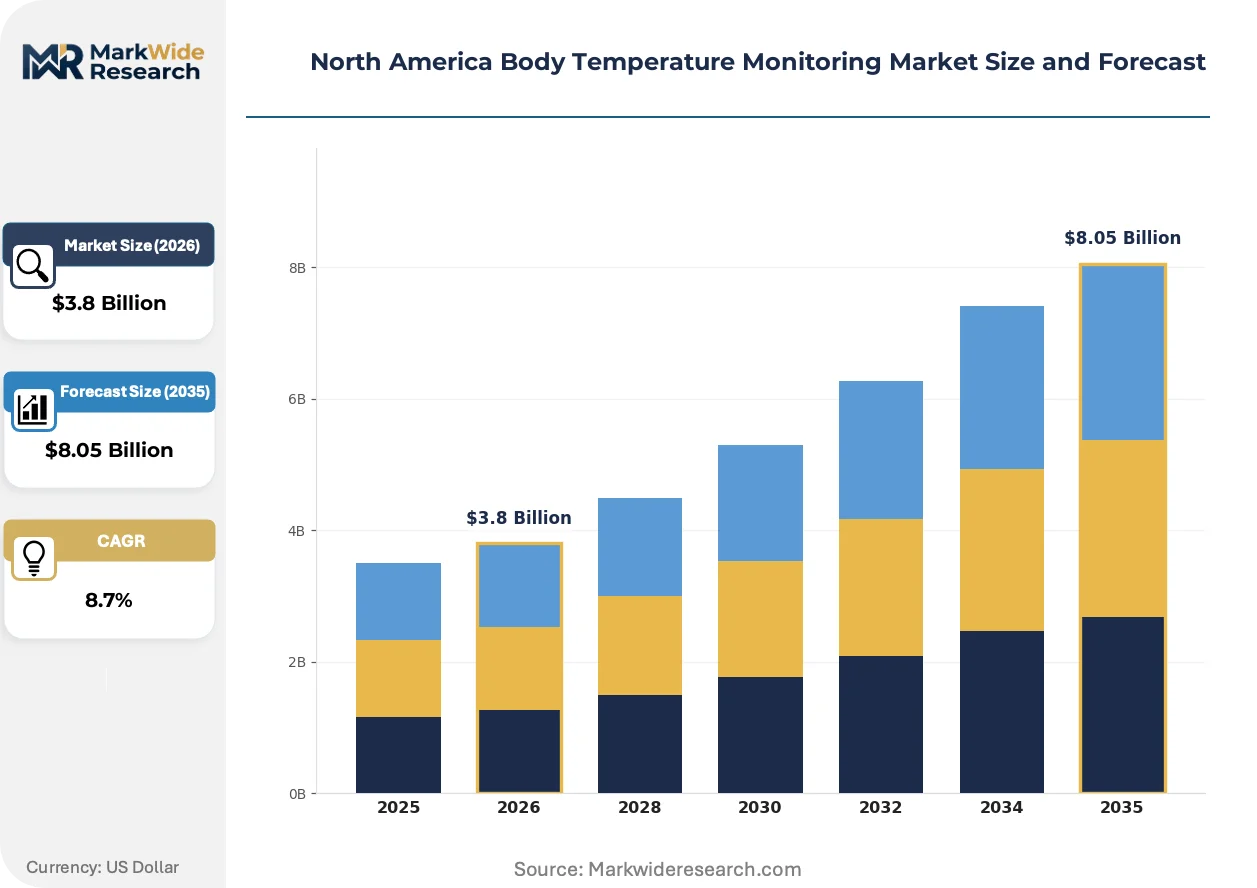
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digi-Thermometers, Infrared Scanners, Continuous Monitors, Disposable Thermometers End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Technology: Digital, Infrared, Thermocouple, Mercury Application: Clinical Use, Home Monitoring, Sports Training, Veterinary |
| Companies Covered | Hill-Rom, Helen of Troy, 3M Company, American Diagnostic Corporation, Cardinal Health, A&D Medical, Medline Industries, Exergen Corporation, OMRON Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Body Temperature Monitoring Market Evolving Landscape
Sensor fusion and edge computing are redefining what constitutes a thermometer, transforming single-point measurement devices into continuous physiological surveillance nodes with predictive capabilities.
Multi-spectral infrared arrays are virtualizing the distinction between surface and core temperature estimation by combining skin thermal emission with ambient compensation algorithms. Hospital systems in the U.S. Northeast are piloting these arrays in emergency department triage workflows, reducing manual measurement bottlenecks during respiratory season surges. This convergence is virtualizing the traditional nurse-workstation interaction model, compressing vital sign acquisition into background monitoring that requires no staff intervention.
Health Canada's Medical Device Single Audit Program alignment with FDA Quality System Regulation is harmonizing compliance burdens for cross-border manufacturers. Dual-registered firms now face consolidated inspection schedules rather than redundant agency audits, redirecting quality assurance resources toward design innovation. Smaller Canadian device developers benefit disproportionately, as the mutual recognition arrangement reduces entry costs into the larger U.S. reimbursement pool.
Hospital procurement committees are consolidating temperature device specifications across IDN networks, replacing site-by-site purchasing with enterprise-wide master service agreements. Group purchasing organizations are capturing this consolidation, bundling thermometry with broader patient monitoring capital packages. The shift is most pronounced in Texas and California health systems, where multi-hospital contracts now specify interoperable Bluetooth connectivity as a mandatory technical requirement.
North America Body Temperature Monitoring Market Segmentation
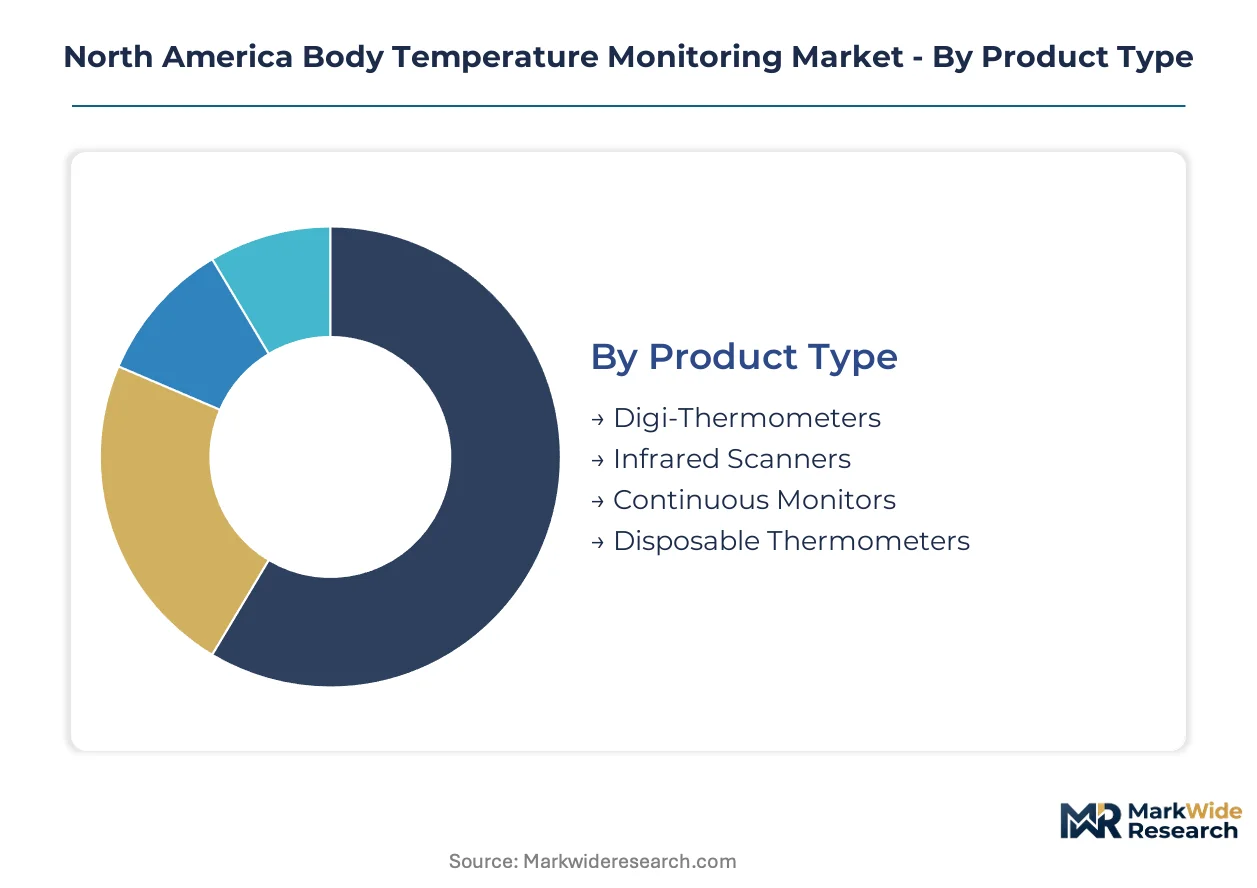
Body temperature monitoring segments reflect divergent accuracy requirements, connectivity standards, and procurement economics across acute care and consumer channels. Device classification under FDA 21 CFR 880.2920 and Health Canada regulations creates distinct predicate pathways for each product category, shaping competitive entry barriers and margin structures.
Product Type:
Use-case spectrum spans single-point screening to longitudinal physiological surveillance, with connectivity capabilities determining reimbursement eligibility and replacement cycle velocity.
- Infrared Scanners:Non-contact thermopile arrays measure surface thermal emission with sub-second response, calibrated for ambient temperature compensation. Hospital procurement in the U.S. Northeast corridor concentrates demand for FDA-cleared contactless units, driven by integrated health system standardization of fever screening protocols across emergency departments and ambulatory entry points.
- Continuous Monitors:Bluetooth-enabled wearable patches or adhesive sensors transmit temperature telemetry to cloud platforms, resolving to clinical-grade 0.1°C precision. CMS reimbursement coding expansions for remote patient monitoring in skilled nursing facilities convert capital sales into subscription revenue, attracting private equity into device-leasing platforms.
- Digi-Thermometers:Handheld thermistor-based devices with LCD displays dominate homecare unit volume through pharmacy and mass retail distribution.
- Disposable Thermometers:Single-use chemical dot or strip formats serve isolation protocols and resource-limited settings with minimal cross-contamination risk.
The dominant share belongs to Infrared Scanners, while Continuous Monitors is closing the gap fastest.
End User:
Procurement authority concentrates in institutional purchasing committees, with homecare demand fragmented across direct-to-consumer and retail pharmacy channels.
- Hospitals:Acute-care networks mandate enterprise-wide temperature protocol standardization, creating sole-source opportunities for platform vendors with EHR-integrated monitoring ecosystems. Texas and California health systems now specify interoperable Bluetooth connectivity as mandatory in multi-hospital contracts.
- Long-term Care Facilities:Provincial health authorities in Ontario and British Columbia fund connected monitor installations, creating first-mover advantages for telemetry-integrated vendors in Canadian nursing homes.
- Homecare:Consumer-directed purchasing through cardiovascular device cross-selling networks leverages existing chronic disease management relationships.
- Clinics:Federally qualified health centers and rural practices face mercury disposal compliance burdens under EPA regulations, accelerating digital replacement of legacy glass thermometers.
Hospitals command the largest procurement volume, though Long-term Care Facilities is expanding most quickly.
Technology:
Sensor modality selection trades measurement speed, accuracy, and environmental robustness against unit economics and regulatory clearance complexity.
- Digital:Thermistor-based architectures with microcontroller signal processing achieve 0.1°C resolution through polynomial calibration curves. FDA 510(k) predicate pathways for digital thermometers streamline clearance timelines, benefiting ambulatory surgery centers standardizing fever screening.
- Infrared:Thermopile detectors and microbolometer arrays enable non-contact measurement, though East Asian fab concentration exposes U.S. and Canadian assemblers to lead-time volatility.
- Thermocouple:Sub-second response times sustain niche dominance in critical care applications requiring rapid physiological status confirmation.
- Mercury:Legacy glass thermometer phase-out accelerates under EPA and Health Canada hazardous waste regulations, imposing reverse logistics burdens on rural clinics.
Digital technology leads unit shipments, while Infrared is climbing the fastest on revenue contribution.
Application:
Regulatory classification and reimbursement eligibility fragment addressable markets across human clinical, consumer wellness, and veterinary domains.
- Clinical Use:Diagnostic-grade devices require FDA clearance and NIST-traceable calibration, serving infection screening, fever surveillance, and physiological status tracking in licensed healthcare settings.
- Home Monitoring:Consumer wellness devices face lower accuracy thresholds but demand Bluetooth connectivity for integration with chronic disease management platforms.
- Sports Training:Athlete thermal load monitoring represents an emerging adjacent market with faster replacement cycles than clinical settings.
- Veterinary:Livestock operations and companion animal clinics offer underpenetrated expansion with reduced regulatory barriers compared to human medical device pathways.
Clinical Use retains the dominant revenue position, though Home Monitoring is gaining share fastest on connectivity-enabled subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and long-term care operators drive demand concentration across North American markets. Federal reimbursement pathways and provincial funding programs shape device selection criteria. Northeast corridor health systems and Canadian provincial authorities anchor regional purchasing volume.
United States
The Northeast corridor dominates procurement through integrated delivery network consolidation. FDA 510(k) pathway acceleration for contactless infrared devices reduces clearance timelines for ambulatory surgery centers. Boston and New York health systems mandate interoperable Bluetooth connectivity across multi-hospital contracts.
Canada
Provincial health authorities in Ontario and British Columbia fund connected monitor installations in nursing homes. Health Canada's Medical Device Single Audit Program alignment with FDA Quality System Regulation harmonizes cross-border compliance. Toronto and Vancouver clusters attract telemetry-integrated vendors seeking first-mover positioning.
Mexico
Hospital modernization programs in Mexico City and Monterrey drive demand for digital replacement of mercury-containing devices. The national pharmaceutical regulator enforces hazardous waste disposal standards for legacy thermometer retirement. Northern border states concentrate device assembly operations serving U.S. distribution channels.
North America Body Temperature Monitoring Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct procurement tiers. Hospital procurement committees and group purchasing organizations consolidate purchasing power around platform vendors with EHR integration capabilities. Three archetypes dominate: integrated patient monitoring platforms, infrared technology specialists, and cardiovascular device cross-sellers. Competitive moves center on enterprise-wide master service agreements and subscription telemetry models converting capital sales into recurring revenue.
Among diversified health technology conglomerates, 3M Company and Cardinal Health represent channel-controlling archetypes with broad distribution infrastructure. Exergen Corporation occupies a specialist position focused on temporal artery infrared technology. OMRON Healthcare exemplifies the cardiovascular cross-selling model leveraging chronic disease management relationships.
| Leading Market Players |
|---|
| Hill-Rom |
| Helen of Troy |
| 3M Company |
| American Diagnostic Corporation |
| Cardinal Health |
| A&D Medical |
| Medline Industries |
| Exergen Corporation |
| OMRON Healthcare |
| Others |
Value Network & Pricing Analysis
Thermopile fab undercapacity in East Asia tightens component availability for North American device assemblers, compressing margins at the contract manufacturing tier while amplifying pricing leverage for integrated platform vendors with captive sensor sourcing.
Pricing Analysis
Cost-plus contracts with thermopile suppliers index to rare earth oxide benchmarks, transferring commodity volatility downstream. Pricing stratifies across FDA-cleared clinical tiers, uncertified wellness devices, and disposable single-use formats, with quality-grade differentiation widening spreads. Cost compression in homecare channels intensifies as cardiovascular device cross-sellers bundle temperature monitors below standalone price points. Hospital procurement committees show lowest price sensitivity, prioritizing EHR interoperability over per-unit cost.
Supply Chain Analysis
Extended payment terms from U.S. hospital networks now reach 90-120 days, forcing device assemblers into supply-chain finance facilities. Thermopile detector manufacturing concentrates in Taiwan, Japan, and China, while final assembly feeds from Mexico and Malaysia. Single-source vulnerability concentrates in East Asian MEMS foundries exposed to tariff escalation. Distribution runs through group purchasing organizations consolidating procurement across integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in the U.S. Northeast corridor, where multi-hospital contracts now mandate sole-source platform agreements that freeze out fragmented device specialists.
For Market Incumbents: Pre-empt telemetry-integrated competitors by embedding Bluetooth-enabled temperature streams into existing patient monitoring platforms before subscription models capture long-term care networks. Defend installed bases through EHR integration depth with Epic and Cerner rather than hardware feature differentiation. Vertical integration into thermopile sourcing mitigates East Asian fab concentration risk. For New Entrants and Emerging Players: Build out veterinary temperature monitoring capabilities where regulatory barriers fall below human clinical thresholds and replacement cycles accelerate. Canadian provincial funding programs in Ontario and British Columbia offer the most penetrable entry point for telemetry-integrated devices. Go-to-market leverage rests on direct relationships with long-term care operators bypassing hospital procurement committees. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across disposable thermometer manufacturing as automated assembly displaces manual production. Long-term viability favors platform vendors with recurring telemetry revenue over transactional device sellers. Acquisition targets should demonstrate HL7 FHIR connectivity capabilities. The signal to watch is CMS reimbursement coding expansion velocity for remote patient monitoring temperature streams.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Streamlined predicate clearance reduces time-to-market for contactless infrared devices targeting ambulatory surgery centers. |
| Hospital System Partnership | Enterprise-wide master service agreements with Northeast corridor IDNs lock out competing vendors through interoperability mandates. |
| Software Companion Development | AI-driven predictive fever algorithms integrated with continuous monitors enable early sepsis detection subscriptions in ICU step-down units. |
| Reimbursement Strategy | CMS billing code alignment for temperature telemetry converts capital equipment sales into recurring revenue streams in skilled nursing facilities. |
| CE Marking Pathway | Health Canada MDSAP alignment with FDA Quality System Regulation harmonizes compliance for cross-border manufacturers seeking dual registration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS reimbursement coding databases, hospital procurement contracts, and GPO pricing agreements. Interviews with biomedical engineers, hospital purchasing committee members, long-term care facility operators, and GPO contracts managers inform demand-side validation. Top-down market sizing triangulates against bottom-up unit shipment estimates across infrared scanner, continuous monitor, and digital thermometer categories.
Forecast inputs incorporate product type segmentation by connectivity capability, end-user procurement authority concentration, and technology modality selection patterns. Modeled dimensions span acute care versus homecare channels, subscription versus transactional revenue models, and FDA-cleared versus wellness-grade device tiers. CAGRs derive from installed base replacement velocity, reimbursement eligibility expansion, and telemetry adoption curves across the projection horizon. Industry-specific inputs include thermopile supply lead times and EHR integration complexity assessments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private equity-backed device-leasing platforms would shift outcomes beyond modeled parameters. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
MRI Compatible Patient Monitoring Systems Market
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
Real Time Health Monitoring Devices Market
Patient Monitoring
Urine Monitoring Systems Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market
Patient Monitoring
Pain Monitoring Devices Market
Patient Monitoring
Global Multi-Parameter Patient Monitoring Equipment Market
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Global Non-Invasive Monitoring Device Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market