
 Respiratory Gas Monitors Market | 2026-2036
Respiratory Gas Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Gas Monitors Market Intelligence
Multi-source procurement for sensor modules is restructuring supply economics across the respiratory gas monitors industry. Philips Healthcare leverages captive infrared spectroscopy manufacturing to protect margin pools on capnography platforms. GE Healthcare competes through broad critical care system integration, while Hamilton Medical specializes in compact multigas configurations for transport ventilators.
Respiratory gas monitors are medical devices that measure partial pressures of oxygen, carbon dioxide, and anesthetic agents in inspired and expired breath, typically employing infrared spectroscopy with wavelength specificity of 4.26 µm for CO2 detection to guide ventilation management and depth-of-anesthesia assessment. Capnography monitors lead clinical adoption in operating rooms due to mandatory use during moderate sedation protocols. Gas analyzers and multigas monitors represent faster-growing segments as intensive care units adopt integrated metabolic monitoring. Electrochemical sensor technology sustains cost advantages in portable pulse oximetry, while paramagnetic sensors command premium positioning in high-accuracy anesthesia workstations.
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements shape product development timelines and testing burdens for manufacturers seeking market access in the United States and European Union. The EPA and OSHA additionally influence workplace exposure limits for calibration gases used in device manufacturing and field service. Stakeholders must monitor evolving ISO 80601-2-55 standards for respiratory gas monitor electrical safety and electromagnetic compatibility as these technical specifications determine competitive eligibility across procurement channels.
Market Dynamics
EU MDR Class IIa certification timelines and ISO 80601-2-55 electromagnetic compatibility standards are compressing product development cycles while elevating testing burdens for manufacturers seeking market access across European and North American procurement channels.
Growth Catalysts
- Mandatory Capnography Protocols:Moderate sedation guidelines in US surgical centers now require continuous end-tidal CO2 monitoring, creating pull-through demand for integrated anesthesia workstations.
- Transport Ventilator Integration:Compact multigas configurations are embedding into mobile critical care platforms for emergency medical services and inter-hospital patient transfers.
- Infrared Spectroscopy Advances:Wavelength-specific detection at 4.26 µm for CO2 and expanded anesthetic agent libraries are improving depth-of-anesthesia assessment accuracy.
Market Restraints
- Sensor Module Concentration:Infrared detector manufacturing concentrates among specialized optical component suppliers, creating single-source vulnerability for capnography platform producers.
- Calibration Gas Cost Volatility:Helium and specialty gas mixtures face supply pressure from semiconductor and aerospace competing demand, elevating field service operational costs.
- Electrochemical Limitations:Portable pulse oximetry platforms face accuracy degradation at extreme perfusion states, constraining deployment in low-resource emergency settings.
Strategic Opportunities
- Home-Based Respiratory Monitoring:Post-acute care discharge protocols in Germany and the Netherlands are creating demand for patient-operated capnography devices with remote telemetry.
- AI-Enhanced Alarm Management:Machine learning integration with multigas analyzers is reducing false-positive ventilation alerts in intensive care unit environments.
- Metabolic Monitoring Convergence:Indirect calorimetry integration with respiratory gas monitors is opening critical care nutrition assessment applications.
Industry Challenges
- 510(k) Submission Backlogs:FDA premarket notification review timelines for modified capnography algorithms are extending commercialization schedules by quarters.
- Legacy System Interoperability:Proprietary data protocols from installed anesthesia workstations complicate third-party monitor integration in hospital IT environments.
- Specialized Field Service Talent:Infrared optical alignment and paramagnetic sensor calibration require technician competencies that outpace vocational training program output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Gas Monitors Market |
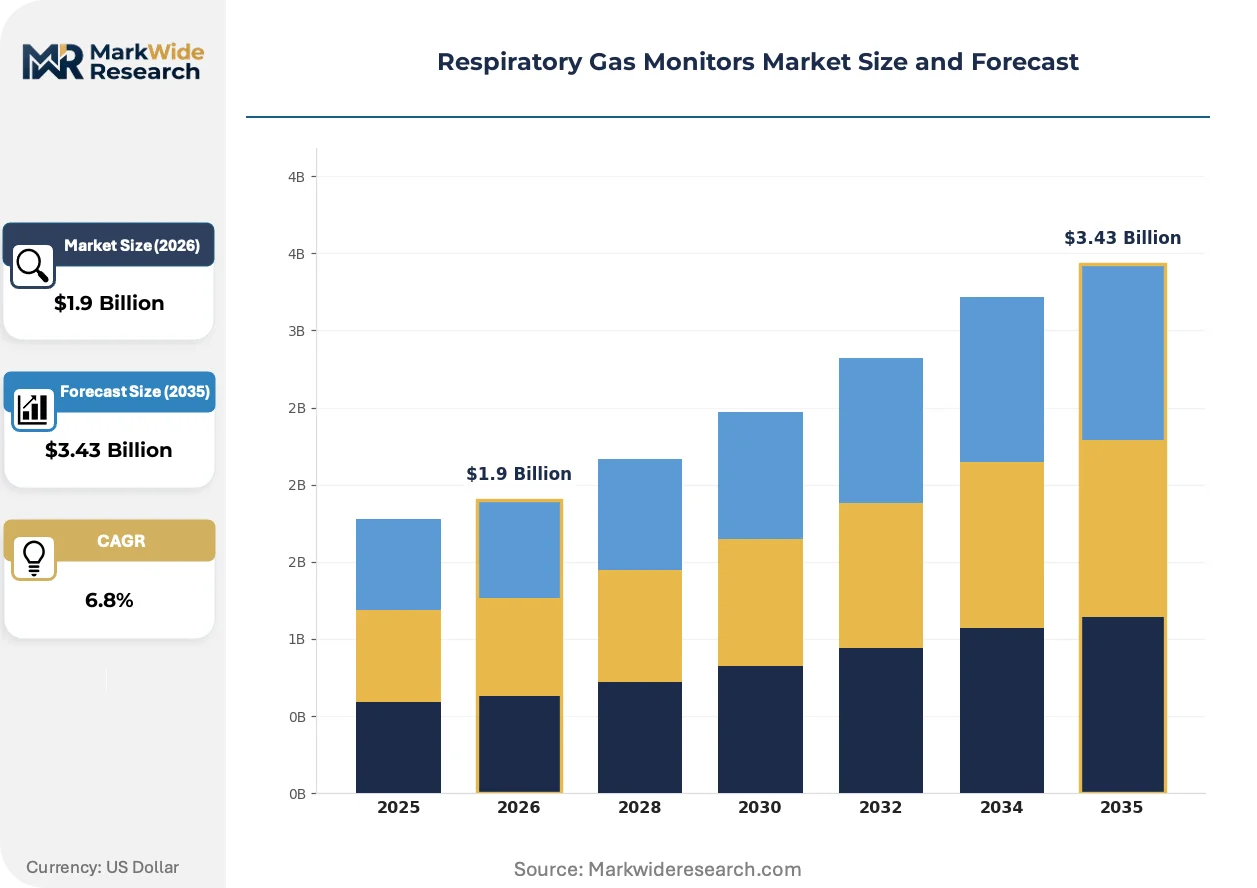
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capnography Monitors, Pulse Oximeters, Gas Analyzers, Multigas Monitors, Flow Meters Technology: Infrared Spectroscopy, Electrochemical Sensors, Paramagnetic Sensors, Laser Absorption, Ultrasonic Technology Application: Anesthesia Monitoring, Critical Care, Pulmonary Function Testing, Emergency Response, Sleep Apnea Assessment End User: Operating Rooms, Intensive Care Units, Ambulatory Care Centers, Diagnostic Laboratories, Rehabilitation Centers |
| Companies Covered | Philips Healthcare, GE Healthcare, ResMed, Medtronic, Draegerwerk, Siemens Healthineers, Vitalograph, Hamilton Medical, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Gas Monitors Market Strategic Shifts & Innovations
Digital signal processing architectures and miniaturized optical benches are compressing device footprints while expanding real-time analytics capabilities across point-of-care and operating room deployments.
Microelectromechanical systems (MEMS) infrared sources paired with photonic integrated circuits are automating wavelength calibration sequences previously requiring manual technician intervention. Academic medical centers in Switzerland and Sweden are piloting these self-calibrating capnography modules for continuous bedside monitoring. The technology is automating quality assurance workflows and reducing clinical engineering labor allocation per device by half.
EU MDR technical documentation requirements for electrical safety and electromagnetic compatibility are mandating redesigned isolation architectures and expanded biocompatibility testing for patient-contacting sampling lines. Manufacturers serving European Union member states must now maintain post-market surveillance systems with periodic safety update reporting. High-accuracy anesthesia workstation producers are responding by consolidating variant configurations to reduce certification multiplicity.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, compelling manufacturers to compete on discrete calibration, repair, and training service pricing. Integrated delivery networks in Texas and Florida are leading this disaggregation, sourcing field service from third-party clinical engineering firms. The shift is compressing OEM service margin pools while elevating transparency requirements for spare parts availability and technical documentation access.
Respiratory Gas Monitors Market Segmentation
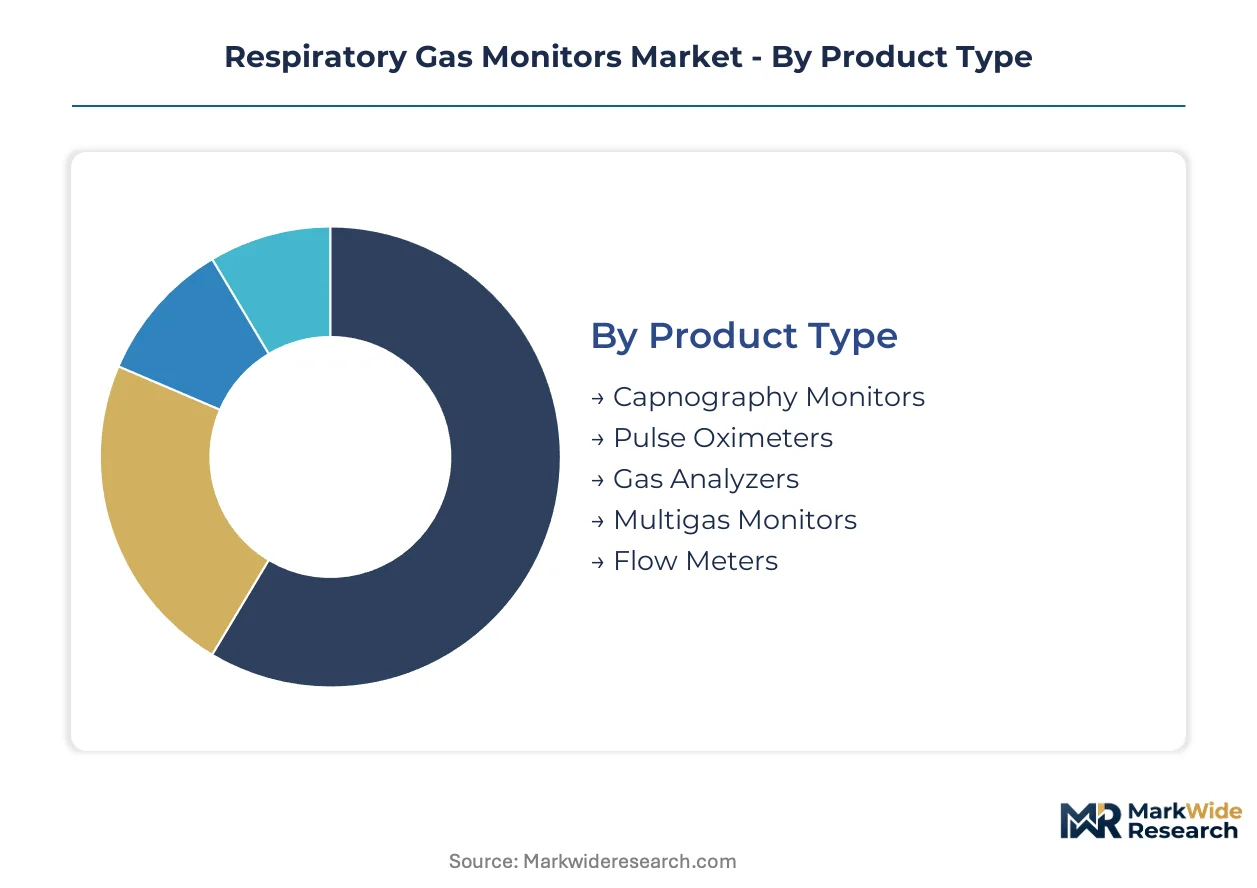
Respiratory gas monitors fragment across four distinct classification axes, each revealing divergent buyer priorities. Product type segmentation separates capital-intensive anesthesia workstations from portable point-of-care devices. Technology and application categories expose trade-offs between accuracy specifications and deployment flexibility.
Product Type:
Hospital procurement committees weight integration depth against mobility requirements when selecting across this category.
- Capnography Monitors:These devices measure end-tidal CO2 through infrared spectroscopy at 4.26 µm wavelength specificity, serving as the clinical standard for ventilation adequacy assessment. Demand concentrates in US operating rooms where FDA-mandated moderate sedation protocols require continuous monitoring. Mandatory use during procedural sedation creates stable replacement cycles.
- Gas Analyzers:Benchtop and bedside units quantify multiple respiratory gases simultaneously through paramagnetic or electrochemical detection methods. German intensive care units favor these for metabolic monitoring integration, driven by post-acute care protocols emphasizing indirect calorimetry. The segment climbs fastest as critical care nutrition assessment gains priority.
- Pulse Oximeters:Finger-clip and handheld devices employ photoplethysmography for SpO2 and pulse rate measurement.
- Multigas Monitors:Compact configurations embed into transport ventilators for emergency medical services deployment.
- Flow Meters:Standalone and integrated units measure inspiratory and expiratory volumes.
Volume sits with capnography monitors; growth tilts toward gas analyzers.
Technology:
Accuracy requirements and calibration burden differentiate buyer selection across detection methodologies.
- Infrared Spectroscopy:Non-dispersive infrared sources paired with wavelength-specific filters enable CO2 and anesthetic agent identification. Swiss academic medical centers pilot MEMS-based self-calibrating modules for continuous bedside monitoring. Automation reduces clinical engineering labor allocation.
- Electrochemical Sensors:Galvanic fuel cell and amperometric designs offer cost advantages in portable pulse oximetry. Low-resource emergency settings face accuracy degradation at extreme perfusion states. Cost sensitivity sustains deployment despite performance limitations.
- Paramagnetic Sensors:Oxygen measurement through magnetic susceptibility differences commands premium positioning in high-accuracy anesthesia workstations.
- Laser Absorption:Tunable diode laser spectroscopy enables trace gas detection with enhanced specificity.
- Ultrasonic Technology:Time-of-flight measurement of gas flow velocities supports non-consumable flow sensing.
Electrochemical sensors dominate unit volume; infrared spectroscopy gains share fastest through miniaturization advances.
Application:
Clinical setting acuity and reimbursement coding shape demand patterns across use cases.
- Anesthesia Monitoring:Integrated workstation configurations track inspired and expired concentrations of oxygen, CO2, and volatile agents. North American surgical centers anchor demand through bundled payment structures incentivizing depth-of-anesthesia assessment. Regulatory mandates sustain replacement velocity.
- Critical Care:Multigas and metabolic monitoring applications support ventilation weaning and nutrition optimization. Netherlands post-acute discharge protocols create pull-through for remote telemetry-enabled devices. Integration with electronic health records drives specification requirements.
- Pulmonary Function Testing:Diagnostic laboratories employ gas analyzers for diffusion capacity and lung volume assessment.
- Emergency Response:Compact capnography modules embed into pre-hospital transport platforms.
- Sleep Apnea Assessment:Home-based nocturnal monitoring applications favor portable pulse oximetry configurations.
Anesthesia monitoring holds volume concentration; critical care demonstrates steepest expansion trajectory.
End User:
Capital availability and technical staffing depth determine procurement specifications across care settings.
- Operating Rooms:Anesthesia workstations with integrated gas monitoring command highest per-unit value. US integrated delivery networks unbundle service contracts, compressing OEM margin pools. Procurement committees prioritize interoperability with existing infrastructure.
- Intensive Care Units:Multigas analyzers support mechanical ventilation management and metabolic assessment. German hospitals anchor European demand through Draegerwerk-validated clinical protocols. Staff training requirements favor familiar platform architectures.
- Ambulatory Care Centers:Moderate sedation protocols in outpatient surgical settings drive capnography adoption.
- Diagnostic Laboratories:Pulmonary function testing equipment requires periodic calibration gas supply.
- Rehabilitation Centers:Post-acute respiratory monitoring supports ventilator weaning programs.
Operating rooms concentrate revenue; intensive care units expand most quickly through metabolic monitoring convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German optical component manufacturing anchors sensor module supply for capnography platforms, with Draegerwerk-validated clinical protocols driving procurement specifications across European hospital networks.
United States
FDA-mandated moderate sedation protocols in outpatient surgical centers create pull-through demand for integrated anesthesia workstations. The 510(k) premarket notification pathway shapes product development timelines for modified capnography algorithms. Texas and Florida integrated delivery networks unbundle service contracts, sourcing field service from third-party clinical engineering firms.
Germany
Intensive care units favor multigas analyzers for metabolic monitoring integration through post-acute care protocols emphasizing indirect calorimetry. EU MDR Class IIa certification requirements mandate redesigned isolation architectures and expanded biocompatibility testing for patient-contacting sampling lines. Draegerwerk anchors production and clinical validation protocols in Lübeck and surrounding northern regions.
Switzerland
Academic medical centers pilot MEMS-based self-calibrating capnography modules for continuous bedside monitoring. Swissmedic technical documentation requirements align with EU MDR electrical safety and electromagnetic compatibility standards. Zurich and Basel clusters automate quality assurance workflows, reducing clinical engineering labor allocation per device.
Netherlands
Post-acute care discharge protocols create demand for patient-operated capnography devices with remote telemetry capabilities. The Dutch national health insurer's coverage decisions influence specification requirements for home-based respiratory monitoring. Randstad hospital procurement committees prioritize interoperability with existing electronic health record infrastructure.
Sweden
Academic medical centers collaborate with Swiss institutions on photonic integrated circuit development for automated wavelength calibration. The Swedish Medical Products Agency enforces ISO 80601-2-55 electromagnetic compatibility standards for market access. Stockholm and Gothenburg research clusters compress device footprints through miniaturized optical bench architectures.
Respiratory Gas Monitors Market Key Industry Players
Strategic partnerships dominate the current landscape as manufacturers seek to secure sensor module supply and accelerate regulatory certification timelines. The vendor base concentrates around diversified medical technology conglomerates with captive optical manufacturing capabilities and specialized respiratory care pure-plays. Two archetypes define competitive positioning: integrated critical care system providers leveraging broad portfolio breadth, and compact multigas specialists targeting transport ventilation applications. M&A activity and technology licensing agreements represent the dominant competitive moves, with players acquiring optical component suppliers and in-licensing MEMS-based self-calibration intellectual property.
Among diversified healthcare technology conglomerates, Philips Healthcare and GE Healthcare exemplify scale-driven positioning through broad critical care system integration, while Hamilton Medical occupies a specialized position in compact multigas configurations for transport ventilators. These three anchors represent divergent strategic bets: captive infrared spectroscopy manufacturing for margin protection, ecosystem integration for account control, and miniaturization expertise for emergency medical services penetration.
| Leading Market Players |
|---|
| Philips Healthcare |
| GE Healthcare |
| ResMed |
| Medtronic |
| Draegerwerk |
| Siemens Healthineers |
| Vitalograph |
| Hamilton Medical |
| Nihon Kohden Corporation |
| Others |
Cost & Logistics Intelligence
Integrated delivery networks in Texas and Florida concentrate procurement authority for anesthesia workstations, compressing OEM service margin pools through unbundled after-sales contracts and third-party clinical engineering sourcing. This buyer consolidation shifts pricing power toward hospital procurement committees demanding discrete calibration, repair, and training service pricing with transparent spare parts availability.
Pricing Analysis
Warranty and field service bundling separates premium-tier anesthesia workstation contracts from unbundled standard configurations favored by cost-conscious ambulatory surgical centers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status and ISO 80601-2-55 electromagnetic compatibility certification grade. Cost compression in portable pulse oximetry intensifies as electrochemical sensor manufacturers compete on unit economics for low-resource emergency settings. Ambulatory care centers exhibit highest price sensitivity, while operating room procurement committees prioritize integration depth over per-unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from hospital procurement committees, while specialized distributors serve diagnostic laboratories and rehabilitation centers with periodic calibration gas requirements. Infrared detector manufacturing concentrates in Germany and Switzerland, with MEMS-based optical component sourcing anchored in Swedish research clusters. German and Dutch production of helium and specialty gas mixtures faces competing semiconductor and aerospace demand. Single-source vulnerability for wavelength-specific filters at 4.26 µm creates procurement risk for capnography platform producers. Distribution runs through clinical engineering firms in North America and authorized service partners in EU member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized infrared optical component capacity constrains capnography platform production, propping pricing for MEMS-based self-calibrating modules as hospital procurement committees prioritize reduced clinical engineering labor allocation.
For Market Incumbents: Acquire MEMS infrared source manufacturing capabilities to secure wavelength-specific detector supply against emerging photonic integrated circuit specialists. Consolidate variant configurations to reduce EU MDR Class IIa certification multiplicity and compress product development timelines. Backward integration into calibration gas blending operations mitigates helium supply volatility from semiconductor industry competing demand. For New Entrants and Emerging Players: Home-based respiratory monitoring in Germany and the Netherlands represents an underserved buyer archetype with pull-through from post-acute care discharge protocols. Emergency medical services transport ventilator integration offers second white-space target as compact multigas configurations displace standalone monitors. Reimbursement strategy alignment with Dutch national health insurer coverage decisions provides critical go-to-market positioning. For Investors and Strategic Acquirers: The window for entry favors optical component specialists with captive MEMS manufacturing and automated wavelength calibration intellectual property. Long-term viability rests on consolidation plays across fragmented infrared detector suppliers serving anesthesia workstation OEMs. FDA 510(k) submission backlog resolution velocity signals inflection timing for modified capnography algorithm commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Pathway | Redesigned isolation architectures open European hospital procurement channels for high-accuracy anesthesia workstations. |
| Hospital System Partnership | Integrated delivery network contracts in Texas and Florida secure volume placement against third-party service disaggregation. |
| Software Companion Development | AI-enhanced alarm management for multigas analyzers reduces false-positive ventilation alerts in intensive care units. |
| Backward Integration into Optical Components | Captive MEMS infrared source manufacturing protects margin pools from specialized detector supplier concentration. |
| Reimbursement Strategy | Alignment with Dutch national health insurer coverage decisions enables home-based capnography device specification requirements. |
Research Approach
Independent corroboration across hospital procurement committee interviews, biomedical engineering director consultations, and GPO contracts manager surveys underwrites the qualitative findings. Primary fieldwork with anesthesia department heads, clinical engineering supervisors, and regulatory affairs specialists at manufacturers seeking FDA 510(k) clearance complements secondary validation through FDA premarket notification databases, EU MDR technical documentation registries, and hospital procurement database analysis. Bottom-up demand modeling across capnography monitors, gas analyzers, and multigas configurations triangulates with top-down market sizing from anesthesia workstation shipment tracking.
Rate-of-change decomposition separates volume expansion from value capture across product type, technology, application, and end user dimensions over the projection horizon. Analytical framework models adoption curves for infrared spectroscopy miniaturization, electrochemical sensor cost trajectories, and paramagnetic sensor premium positioning. CAGRs derive from segmented demand forecasting incorporating moderate sedation protocol mandate expansion, transport ventilator integration velocity, and metabolic monitoring convergence in critical care nutrition assessment.
Revisions become necessary when FDA 510(k) review timeline extensions, EU MDR certification bottleneck accumulation, or helium supply disruption from semiconductor industry demand surges materialize. Forecasts reflect assumptions regarding infrared detector manufacturing capacity expansion, clinical engineering labor availability for field service, and hospital procurement committee unbundling velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
North America Patient Monitoring Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
Fetal and Neonatal Heart Monitor Market
Patient Monitoring
Middle East and Africa Body Temperature Monitoring Market
Patient Monitoring
United States Cardiac Holter Monitor Market
Patient Monitoring
Remote Patient Monitoring System Market
Patient Monitoring
Urine Monitoring Systems Market
Patient Monitoring
Oman Blood Glucose Monitoring Market
Patient Monitoring
Multi-Channel Remote ECG Monitors Market
Patient Monitoring
Japan Patient Care Monitoring Equipment Market
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market
Patient Monitoring
Urine Output Monitoring Systems Market
Patient Monitoring
Global Multi-Parameter Patient Monitoring Equipment Market
Patient Monitoring
Wearable ECG Monitors Market
Patient Monitoring
Online Patient Observation Market