
 Global Fetal and Neonatal Monitoring Market | 2026-2036
Global Fetal and Neonatal Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fetal and Neonatal Monitoring Market Foresight
Disposable sensor polymers are broadening cost structures for manufacturers shifting from reusable gold-plated electrodes. GE Healthcare leverages vertical integration across imaging and monitoring platforms to sustain pricing power in cardiotocography systems. Koninklijke Philips N.V. anchors its neonatal portfolio on pulse oximetry and acoustic sensor platforms. Siemens Healthineers differentiates through magnetocardiography R&D pipelines.
Fetal and neonatal monitoring encompasses electronic systems that track fetal heart rate, uterine contractions, neonatal oxygen saturation, and cerebral oxygenation through cardiotocography, pulse oximetry, and near-infrared spectroscopy, operating across frequencies from 1-3 MHz for Doppler ultrasound and 660-940 nm wavelengths for optical sensors, with primary purpose of detecting hypoxia, acidosis, and hemodynamic instability before irreversible injury occurs. Electronic fetal monitors and pulse oximeters lead product category revenue due to universal deployment in labor and delivery wards, while near-infrared spectroscopy is expanding fastest in neonatal intensive care as clinicians demand continuous cerebral oxygenation data. Cardiotocography technology remains the mature workhorse with compressed margins, whereas fetal electrocardiography commands premium positioning in high-risk pregnancy centers.
FDA 510(k) clearance pathways, EU MDR recertification requirements under Regulation (EU) 2017/745, and China's NMPA Class II/III registration standards collectively determine market access timelines and clinical evidence burdens for device manufacturers. Japan's PMDA enforces JIS quality management standards that shape procurement specifications for Asian hospital networks. Stakeholders must monitor regulatory divergence between FDA's evolving premarket notification framework and EU MDR's intensified notified body scrutiny as this friction determines which product portfolios achieve synchronized multi-region launches.
Market Dynamics
EU MDR recertification timelines under Regulation (EU) 2017/745 are compressing product launch windows and forcing manufacturers to restructure clinical evidence portfolios ahead of notified body capacity constraints.
Growth Catalysts
- China's NMPA Class III registration pathway:Accelerated review tracks for innovative devices are shortening market entry timelines for cerebral oximetry systems in tertiary hospitals.
- Disposable polymer sensor adoption:Single-use electrode platforms are eliminating cross-contamination protocols and reducing sterilization overhead in labor and delivery wards.
- Near-infrared spectroscopy:Continuous cerebral oxygenation monitoring is displacing intermittent blood gas sampling in neonatal intensive care units across Germany and the United States.
Market Restraints
- Palladium and gold electrode costs:Precious metal price volatility in reusable sensor manufacturing is squeezing gross margins on cardiotocography hardware.
- Notified body capacity bottlenecks:EU MDR recertification queue lengths are extending product lifecycle management costs by twelve to eighteen months for legacy devices.
- Optical sensor interference:Melanin pigmentation variability limits pulse oximetry accuracy across diverse neonatal populations, constraining universal deployment claims.
Strategic Opportunities
- Rural China hospital networks:County-level maternal health infrastructure expansion is creating first-time demand for portable fetal monitors outside tier-one cities.
- Magnetocardiography-neonatal MRI convergence:Non-invasive cardiac magnetic field mapping is opening diagnostic pathways for congenital heart defect screening without radiation exposure.
- Japan's PMDA Sakigake designation:Fast-track approval incentives for breakthrough devices are attracting R&D investment in acoustic biosensor platforms for apnea detection.
Industry Challenges
- Biomedical signal processing expertise:Scarcity of engineers specializing in fetal ECG extraction algorithms is delaying algorithm validation timelines.
- Legacy CTG system integration:Proprietary data formats from installed cardiotocography bases are obstructing interoperability with new wireless patch sensors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fetal and Neonatal Monitoring Market |
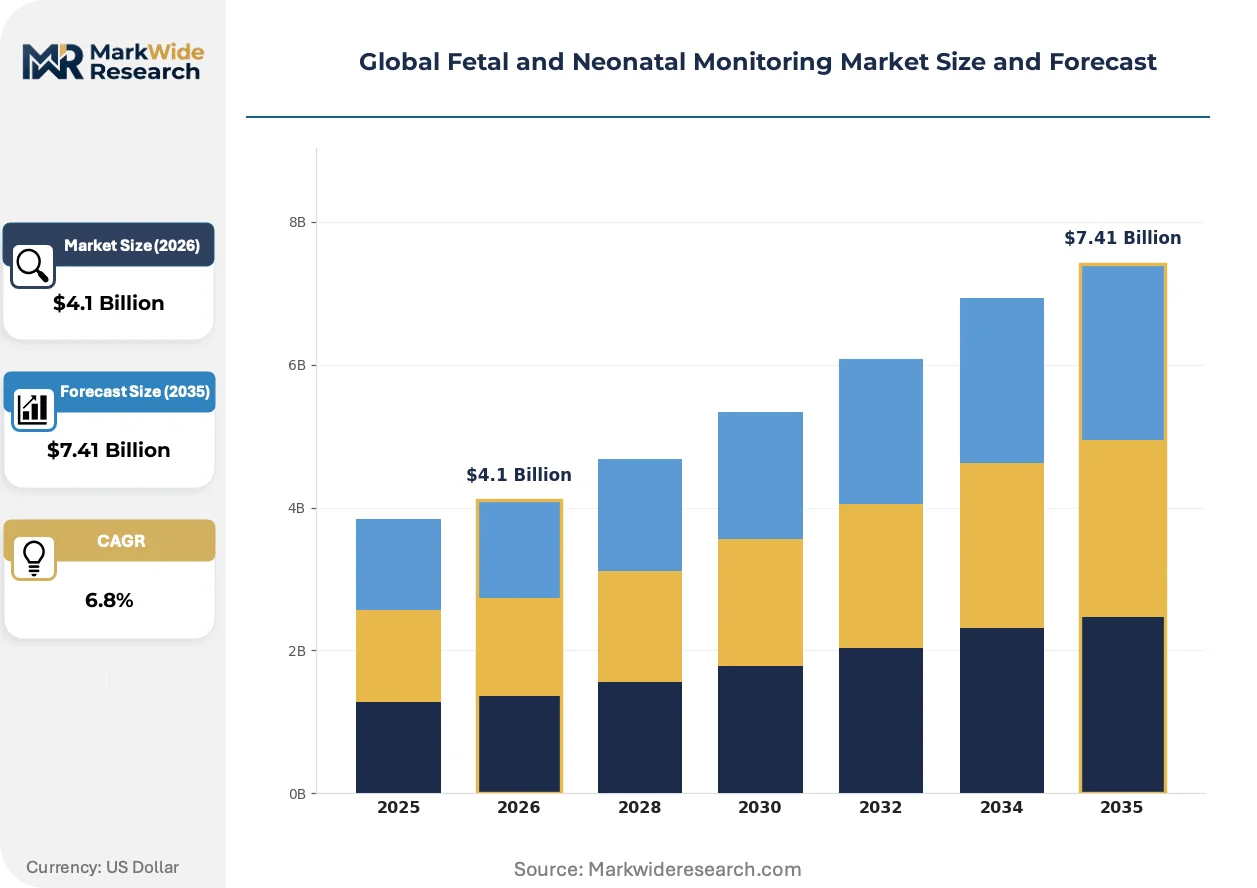
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Dopplers, Electronic Fetal Monitors, Toco Transducers, Neonatal Ventilators, Pulse Oximeters Technology: Cardiotocography, Fetal Electrocardiography, Near-Infrared Spectroscopy, Magnetocardiography, Acoustic Sensors Application: Labor Monitoring, Prenatal Diagnosis, Postnatal Care, Neonatal Intensive Care, Risk Assessment End User: Hospitals, Birthing Centers, Maternity Clinics, Pediatric Units, Diagnostic Laboratories |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Medtronic, Siemens Healthineers, Drägerwerk AG & Co. KGaA, Masimo Corporation, Mindray Medical, Becton, Dickinson and Company, Arjo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fetal and Neonatal Monitoring Market Shifts & Advancements
Wireless patch-based monitoring architectures are displacing traditional bedside console systems, compressing capital expenditure cycles and enabling ambulatory maternal-fetal surveillance outside conventional labor ward footprints.
Artificial intelligence-based cardiotocography interpretation is unifying fetal heart rate pattern classification across heterogeneous clinician training backgrounds. Academic medical centers in the United States and the Netherlands are piloting FDA-cleared algorithms for intrapartum decision support. This convergence is reducing inter-observer variability in hypoxia risk stratification while compressing liability exposure for understaffed delivery units.
EU MDR technical documentation requirements are elevating clinical evidence burdens for legacy pulse oximetry platforms. Manufacturers must now submit post-market surveillance data spanning entire product families rather than single-device variants. Neonatal monitoring portfolios with fragmented SKU architectures face disproportionate compliance costs compared to streamlined cardiotocography platforms with unified hardware bases.
Hospital procurement committees are consolidating vendor relationships through enterprise monitoring contracts that bundle fetal, neonatal, and maternal platforms under single-source agreements. German hospital networks and US integrated delivery systems are leading this concentration, displacing point-product purchasing autonomy from individual department heads. This shift favors manufacturers with cross-platform interoperability credentials and penalizes specialized single-modality suppliers.
Global Fetal and Neonatal Monitoring Market Segmentation
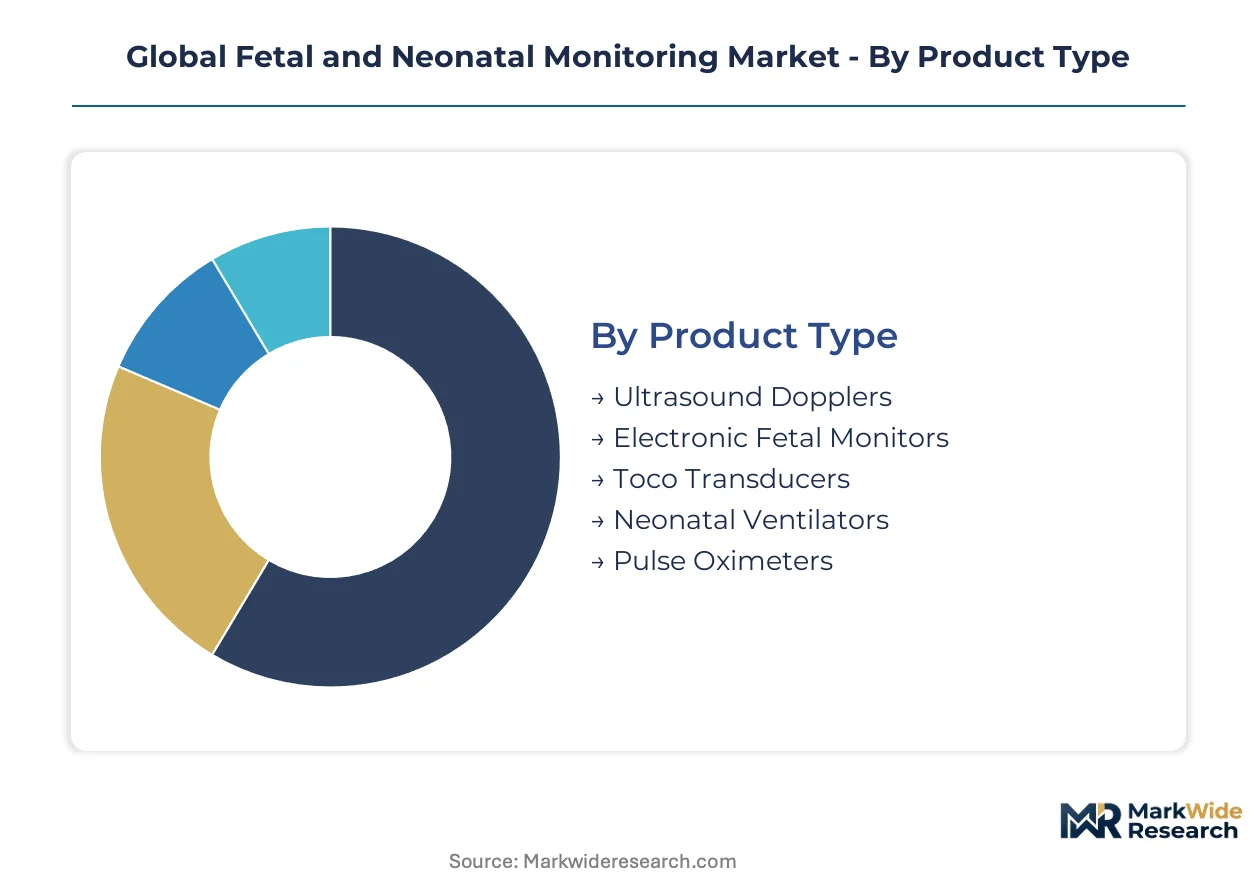
Segmentation reveals how fetal and neonatal monitoring demand fragments across clinical workflows and procurement hierarchies. Product type and technology splits expose margin concentration points, while end-user and application dimensions illuminate where purchasing authority is consolidating.
Product Type:
Volume deployment concentrates on established bedside platforms, while premium pricing attaches to portable and disposable configurations.
- Electronic Fetal Monitors:Multi-parameter bedside consoles integrate cardiotocography with maternal vital signs tracking. Demand clusters in United States tertiary hospital labor wards where enterprise monitoring contracts bundle fetal and maternal platforms under single-source agreements.
- Pulse Oximeters:Optical sensors operating at 660-940 nm wavelengths enable continuous neonatal oxygen saturation monitoring. Adoption accelerates in German neonatal intensive care units as clinicians displace intermittent blood gas sampling with real-time cerebral oxygenation data.
- Ultrasound Dopplers:Handheld 1-3 MHz Doppler devices support intermittent fetal heart rate auscultation in outpatient settings.
- Toco Transducers:Strain-gauge pressure sensors measure uterine contraction frequency and intensity during labor.
- Neonatal Ventilators:Pressure-limited respiratory support systems integrate with monitoring platforms for synchronized ventilation.
Mature deployment sits with electronic fetal monitors. Newer deployment is concentrated in pulse oximeters.
Technology:
Application context determines whether clinicians prioritize real-time surveillance precision or non-invasive diagnostic depth.
- Near-Infrared Spectroscopy:Optical cerebral oxygenation monitoring at 700-1000 nm wavelengths penetrates neonatal skull tissue to measure regional tissue oxygen saturation. United States academic medical centers are piloting continuous cerebral oximetry in preterm infant neuroprotection protocols.
- Cardiotocography:Simultaneous fetal heart rate and uterine contraction recording remains the universal standard for intrapartum hypoxia detection. Compressed margins characterize this mature technology segment as hospital procurement committees negotiate enterprise pricing for installed base replacements.
- Fetal Electrocardiography:Direct fetal ECG signal extraction through maternal abdominal electrodes.
- Magnetocardiography:Non-invasive cardiac magnetic field mapping for congenital heart defect screening.
- Acoustic Sensors:Piezoelectric or MEMS-based platforms for neonatal apnea and breathing pattern detection.
Cardiotocography anchors routine labor surveillance. Near-infrared spectroscopy is gaining share fastest in specialized neonatal intensive care applications.
Application:
Clinical setting dictates monitoring intensity, from intermittent screening through continuous multi-parameter surveillance.
- Neonatal Intensive Care:Continuous multi-modal monitoring of preterm and critically ill newborns demands integrated cardiotocography, pulse oximetry, and cerebral oxygenation platforms. China's NMPA accelerated review tracks are shortening market entry timelines for cerebral oximetry systems in tertiary hospital networks.
- Labor Monitoring:Intrapartum fetal heart rate and contraction surveillance in delivery wards.
- Prenatal Diagnosis:Fetal anomaly screening and biophysical profile assessment in outpatient settings.
- Postnatal Care:Transition monitoring from delivery suite to maternity ward.
- Risk Assessment:High-risk pregnancy identification and surveillance protocol activation.
Labor monitoring represents installed base concentration. Neonatal intensive care shows steepest expansion trajectory as prematurity rates and survival expectations rise.
End User:
Procurement authority concentrates at health system level, compressing vendor relationships and favoring cross-platform suppliers.
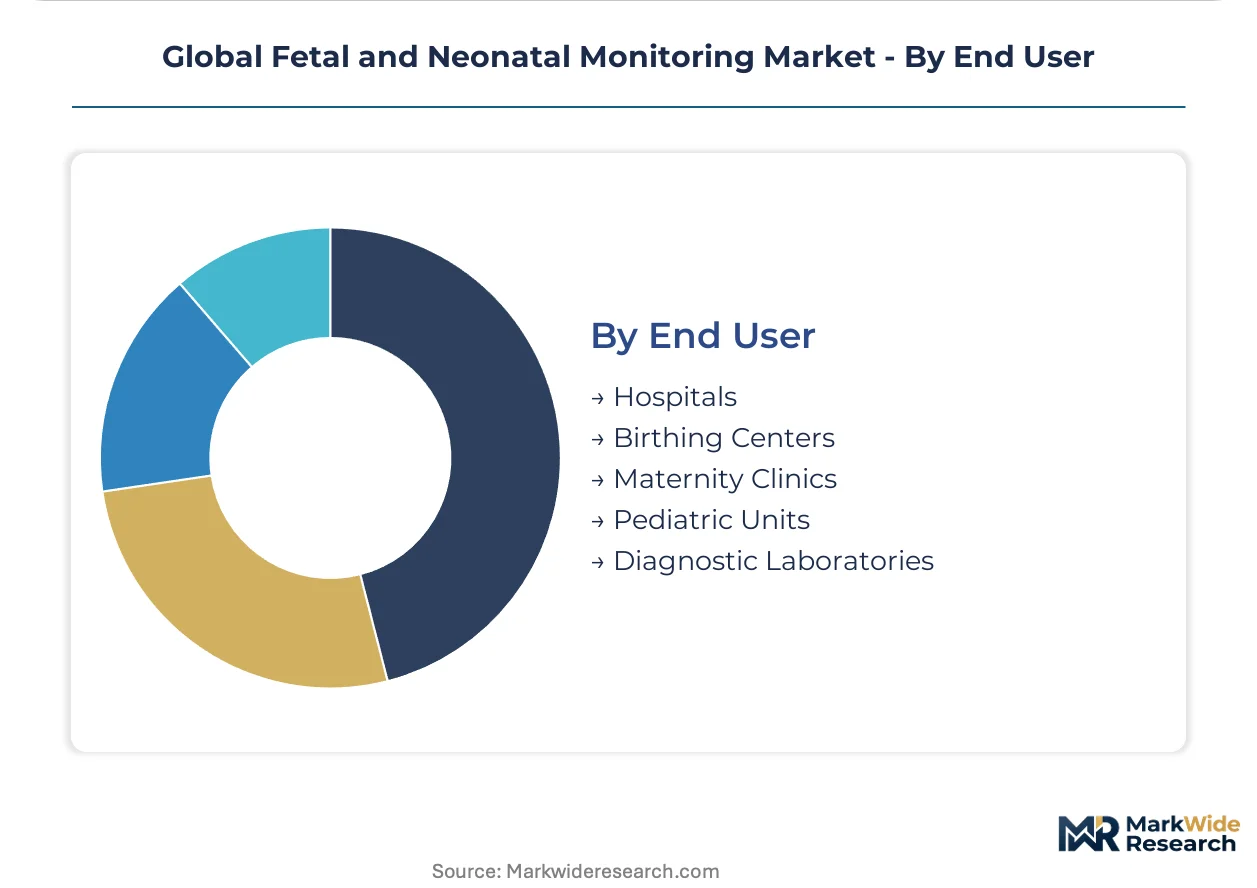
- Hospitals:Integrated delivery systems and German hospital networks are consolidating enterprise monitoring contracts that bundle fetal, neonatal, and maternal platforms. Single-source agreements displace point-product purchasing autonomy from individual department heads.
- Birthing Centers:Low-intervention delivery settings requiring portable monitoring for emergency transfer protocols.
- Maternity Clinics:Outpatient prenatal surveillance and non-stress testing facilities.
- Pediatric Units:General pediatric floors with intermittent neonatal monitoring requirements.
- Diagnostic Laboratories:Centralized fetal echocardiography and specialized testing services.
Hospital procurement dominates capital expenditure. Birthing centers represent emerging demand for portable and wireless configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States tertiary hospitals concentrate procurement authority through enterprise monitoring contracts that bundle fetal, neonatal, and maternal platforms. Germany's neonatal intensive care units lead European cerebral oximetry adoption. China's county-level hospital expansion is creating first-time demand for portable fetal monitors outside tier-one cities.
United States
Integrated delivery systems in California, Texas, and the Northeast Corridor are consolidating vendor relationships under single-source enterprise agreements. FDA 510(k) clearance pathways determine market access timelines for cardiotocography and pulse oximetry platforms. Academic medical centers in Boston and the San Francisco Bay Area pilot AI-based fetal heart rate interpretation algorithms for intrapartum decision support.
Germany
Hospital networks in North Rhine-Westphalia and Bavaria are displacing intermittent blood gas sampling with continuous cerebral oxygenation monitoring in neonatal intensive care. EU MDR recertification under Regulation (EU) 2017/745 is compressing product launch windows for legacy pulse oximetry devices. The Frankfurt-Rhine-Main medical technology cluster hosts R&D operations for magnetocardiography-neonatal MRI convergence platforms.
China
NMPA Class III registration pathways for innovative devices are accelerating cerebral oximetry market entry in Shanghai and Beijing tertiary hospitals. County-level maternal health infrastructure expansion in Sichuan and Shandong provinces is generating demand for portable fetal monitors. The Yangtze River Delta medical device manufacturing base supplies disposable polymer sensors for domestic and export markets.
Japan
PMDA Sakigake fast-track designation is attracting R&D investment in acoustic biosensor platforms for neonatal apnea detection. JIS quality management standards shape procurement specifications for Asian hospital networks. The Kanto region's precision manufacturing ecosystem supports miniaturized wireless patch sensor production for ambulatory maternal-fetal surveillance.
India
CDSCO medical device registration requirements are structuring market entry pathways for multinational cardiotocography manufacturers. Maharashtra and Karnataka state health missions are expanding neonatal intensive care capacity in tier-two cities. The Delhi-NCR corridor serves as the primary distribution hub for imported fetal monitoring equipment serving northern Indian hospital networks.
Global Fetal and Neonatal Monitoring Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational conglomerates dominating enterprise hospital contracts while regional fabricators capture price-sensitive tier-two and rural deployments. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with cross-platform interoperability credentials, specialized neonatal monitoring pure-plays with premium sensor technology, and emerging Asian manufacturers with cost-optimized disposable configurations. Competitive intensity centers on M&A activity targeting wireless patch sensor startups and strategic partnerships between imaging equipment makers and AI algorithm developers.
Among diversified conglomerates, GE Healthcare and Koninklijke Philips N.V. exemplify the cross-platform bundling archetype that procurement committees increasingly favor. Siemens Healthineers occupies a distinct position within the advanced diagnostic imaging convergence tier. These three entities represent the dominant competitive anchors against which specialized players and emerging manufacturers must differentiate their value propositions.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Medtronic |
| Siemens Healthineers |
| Drägerwerk AG & Co. KGaA |
| Masimo Corporation |
| Mindray Medical |
| Becton, Dickinson and Company |
| Arjo |
| Others |
Supply & Pricing Matrix
Enterprise hospital procurement committees in the United States and German hospital networks concentrate purchasing authority through bundled monitoring contracts, compressing vendor relationships and anchoring pricing power with cross-platform suppliers. This buyer concentration feeds back into supply chain restructuring as manufacturers prioritize backward integration into sensor component production to defend margin positions against procurement pressure.
Pricing Analysis
Volume deployment of cardiotocography hardware runs on compressed margins in mature installed base replacements, while cerebral oximetry systems and wireless patch platforms capture premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared AI-interpretation systems from legacy CTG consoles and unbranded portable monitors for rural China. Pricing pressure stems from precious metal volatility in reusable electrode manufacturing, with palladium and gold costs squeezing gross margins. County-level hospitals in China exhibit highest price sensitivity, whereas United States academic medical centers prioritize clinical evidence and interoperability over unit cost.
Supply Chain Analysis
Freight costs for temperature-sensitive optical sensor components and sterile disposable polymers elevate landed costs for manufacturers sourcing from Yangtze River Delta production bases to European and North American end markets. Component supply concentrates in China for disposable polymer sensors, Germany for precision strain-gauge transducers, and Japan for miniaturized MEMS acoustic platforms. Raw material dependencies span palladium and gold for reusable electrodes, medical-grade silicones for patch substrates, and rare-earth elements for magnetocardiography sensors. Single-source vulnerability in notified body capacity for EU MDR recertification extends product lifecycle management timelines. Distribution runs through hospital GPO contracts in the United States, direct tender relationships in Germany, and provincial procurement platforms in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR recertification timelines and enterprise procurement consolidation are forcing weaker single-modality suppliers toward exit or acquisition, positioning this market as a consolidation play for cross-platform capable manufacturers.
For Market Incumbents: To counter wireless patch sensor startups displacing bedside console architectures, GE Healthcare and Philips must deepen backward integration into disposable polymer sensor production and accelerate FDA-cleared AI algorithm deployment for intrapartum decision support. Capacity addition in China's Yangtze River Delta manufacturing corridor secures cost-competitive supply for county-level hospital expansion. For New Entrants and Emerging Players: Enter via portable fetal monitor configurations targeting China's county-level maternal health infrastructure outside tier-one cities, where first-time demand for basic cardiotocography outpaces supply from established multinationals. White-space concentration sits with wireless ambulatory platforms for birthing center emergency transfer protocols and acoustic biosensor platforms for Japan's PMDA Sakigake fast-track pathway. Go-to-market execution should anchor on provincial procurement platform relationships rather than direct hospital sales. For Investors and Strategic Acquirers: The window for entry favors wireless patch sensor technology specialists with FDA 510(k) clearance progress and EU MDR technical documentation readiness, positioned for acquisition by diversified conglomerates seeking cross-platform interoperability credentials. Long-term viability hinges on algorithm differentiation and regulatory synchronization across FDA, EU MDR, and NMPA pathways. The signal to watch is M&A activity targeting AI-based cardiotocography interpretation startups and magnetocardiography-neonatal MRI convergence platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerated review tracks for AI-based fetal heart rate interpretation algorithms reduce time-to-revenue for decision support platforms. |
| EU MDR Technical Documentation | Post-market surveillance data spanning entire pulse oximetry product families elevates compliance costs for fragmented SKU architectures. |
| Hospital System Partnership | Enterprise monitoring contracts bundling fetal, neonatal, and maternal platforms displace point-product purchasing autonomy in German networks. |
| Software Companion Development | AI-based cardiotocography interpretation unifies fetal heart rate pattern classification across heterogeneous clinician training backgrounds. |
| Reimbursement Strategy | Cerebral oximetry coverage expansion in United States academic medical centers pilots continuous monitoring in preterm infant neuroprotection protocols. |
Research Methodology
Independent corroboration across hospital procurement committee interviews, biomedical engineering directors, and regulatory affairs specialists at multinational manufacturers underwrites the qualitative findings. Primary fieldwork with GPO contracts managers and neonatal intensive care clinicians combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, and NMPA registration databases. Bottom-up triangulation across product-level shipment data and top-down reconciliation against hospital capital expenditure disclosures anchored segment-level outputs.
Comparable-period anchoring to historical cardiotocography installed base replacement cycles and cerebral oximetry pilot adoption timelines structured the projection horizon. Segmentation modeling spanned product type, technology platform, clinical application, and end-user procurement hierarchy, with geographic regulatory cluster differentiation for FDA, EU MDR, and NMPA pathways. CAGRs derived from weighted average of clinician adoption curve analysis and procurement contract renewal patterns, incorporating prematurity rate trajectories and NICU capacity expansion plans as demand-side inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR recertification queue extensions or China NMPA registration pathway disruptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Remote Patient Monitoring System Market
Patient Monitoring
B-Ketone Monitoring System Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market
Patient Monitoring
South America Remote Patient Monitoring Systems Market
Patient Monitoring
Global Patient Monitoring Market
Patient Monitoring
Body Fat Measurement Market
Patient Monitoring
Urine Monitoring Systems Market
Patient Monitoring
Germany Patient Care Monitoring Equipment Market
Patient Monitoring
Middle East and Africa Remote Patient Monitoring Market
Patient Monitoring
Global Body Temperature Monitoring Market
Patient Monitoring
Respiratory Monitoring Devices Market
Patient Monitoring
Global Heart Rate Monitor Market
Patient Monitoring
Telemonitoring Systems Market
Patient Monitoring
North America Wearable Ambulatory Monitoring Devices Market