
 Hemoglobin Monitor Market | 2026-2036
Hemoglobin Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Hemoglobin Monitor Market Foresight
Silicon photonics is broadening the performance envelope of non-invasive hemoglobin monitors by replacing discrete optical components with chip-scale spectrometers. Siemens Healthineers leverages its installed base in European hospital laboratories to sustain premium positioning for tabletop analyzers. Masimo Corporation anchors its North American presence through proprietary signal extraction technology that differentiates its wearable sensors from pulse-oximetry commoditization.
Hemoglobin monitors are clinical instruments that quantify hemoglobin concentration in whole blood through optical absorbance, electrical impedance, or electrochemical reaction, typically reporting results in grams per deciliter within seconds to minutes for diagnostic or therapeutic monitoring purposes. Portable devices dominate volume shipments in low-resource settings where laboratory infrastructure remains sparse, while laboratory equipment captures disproportionate value through bundled reagent contracts and service agreements. Optical technology leads installed capacity but electrochemical platforms are gaining fastest in wearable formats where power budgets and miniaturization constraints favor amperometric approaches.
FDA 510(k) premarket notification requirements shape product development timelines and clinical evidence burdens for manufacturers seeking US commercialization, while the EU Medical Device Regulation imposes stricter post-market surveillance and notified body oversight on devices entering European markets. The International Organization for Standardization publishes ISO 80601-2-61 for pulse oximeter safety and performance, which hemoglobin monitor developers reference for electromagnetic compatibility and alarm system design. Stakeholders must monitor evolving harmonization gaps between FDA software-as-a-medical-device guidance and EU AI Act risk classification for algorithms that estimate hemoglobin without direct blood sampling.
Market Dynamics
Point-of-care adoption in hospital emergency departments is compressing the traditional laboratory testing cycle, forcing manufacturers to recalibrate device architectures around speed and bedside usability rather than central lab throughput.
Growth Catalysts
- FDA 510(k) Pathway Compression:Streamlined premarket notification for non-invasive optical sensors is shortening time-to-market for new entrants seeking US commercialization.
- Silicon Photonics Integration:Chip-scale spectrometers are replacing discrete optical components, reducing device footprint and unit cost for portable hemoglobin monitors.
- Emergency Department Triage Demand:Clinicians in US acute care settings require sub-minute anemia assessment to accelerate patient disposition decisions.
Market Restraints
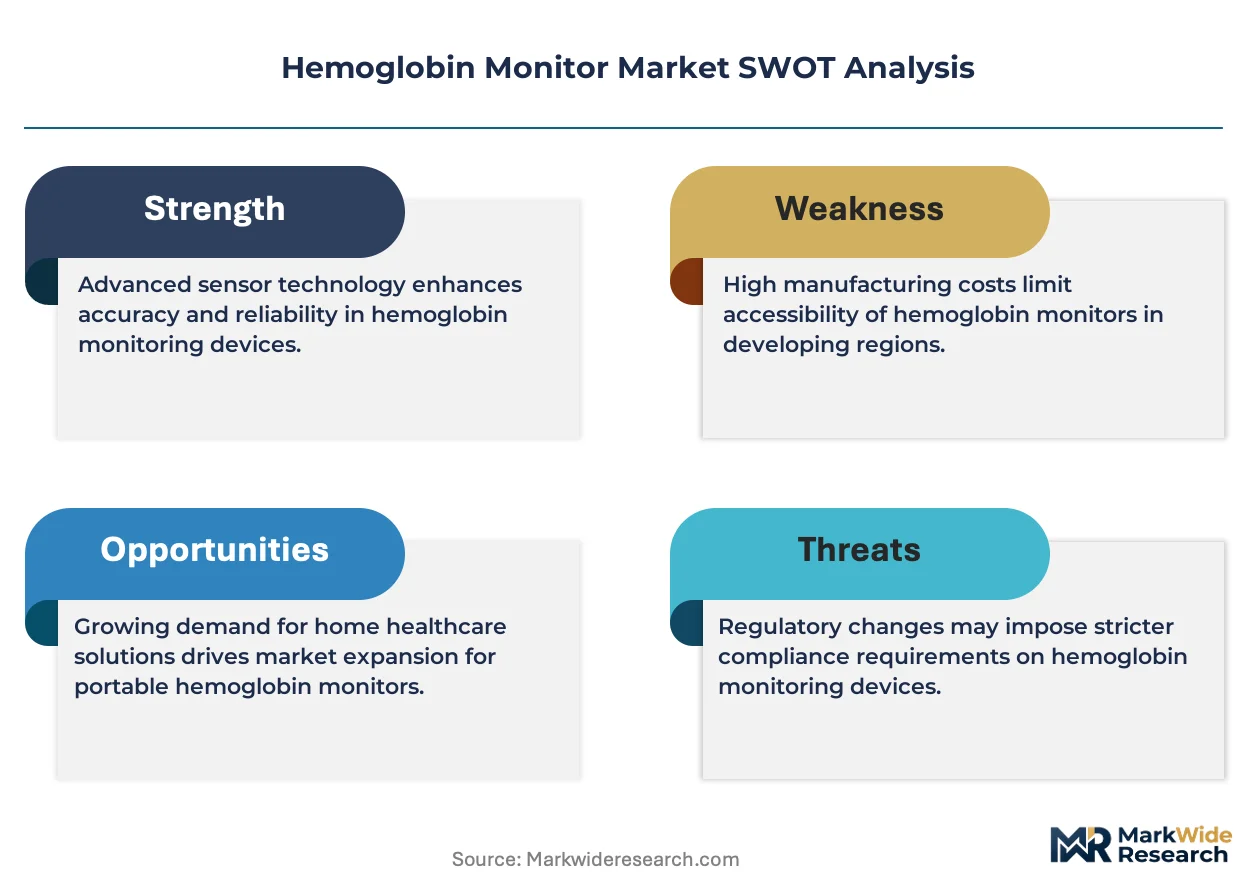
- Optical Sensor Calibration Drift:Non-invasive devices face accuracy degradation across skin tone variations, limiting clinical acceptance in diverse patient populations.
- Reagent-Dependent Laboratory Systems:Tabletop analyzers remain tethered to consumable supply chains concentrated in Western European manufacturing clusters.
- EU MDR Compliance Burden:Stricter post-market surveillance and notified body oversight are extending certification timelines for devices entering European markets.
Strategic Opportunities
- Sub-Saharan Africa Laboratory Infrastructure Gaps:Portable battery-operated devices address diagnostic access in settings lacking cold chain and centralized pathology.
- Home Hemodialysis Monitoring:Wearable electrochemical sensors enable patient-managed anemia tracking outside clinical facilities.
- ISO 80601-2-61 Harmonization:Pulse oximeter safety standards provide a regulatory template for hemoglobin monitor developers seeking multi-jurisdictional approval.
Industry Challenges
- Multidisciplinary R&D Talent Scarcity:Device developers compete for optical engineers with silicon photonics and biomedical signal processing expertise.
- Legacy Hospital Information System Integration:Point-of-care devices must interface with fragmented electronic health record architectures across US health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemoglobin Monitor Market |
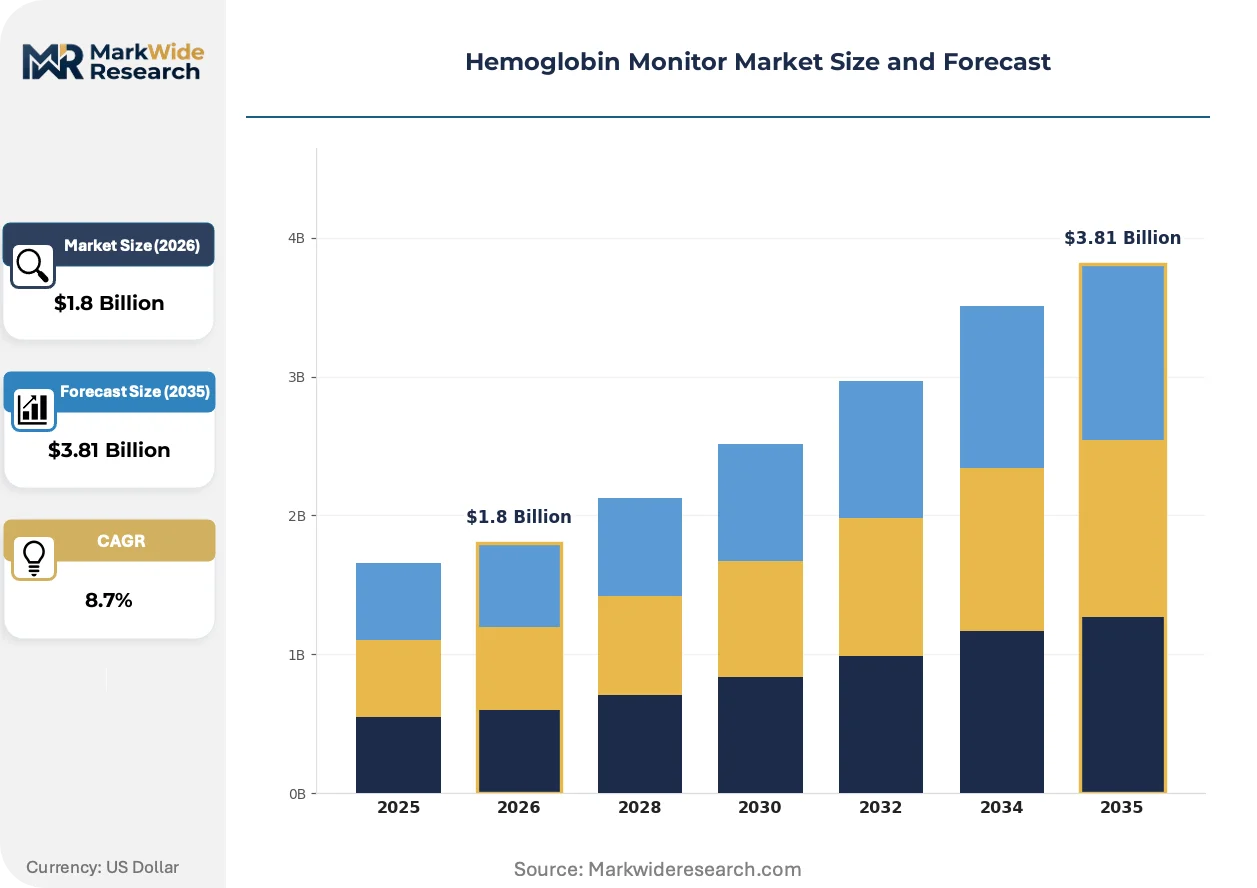
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Tabletop Analyzers, Wearable Sensors, Laboratory Equipment Technology: Optical, Electrical, Colorimetric, Electrochemical End User: Hospitals, Clinics, Homecare, Blood Banks Application: Diagnostics, Research, Blood Donation, Anemia Management |
| Companies Covered | Abbott, Siemens Healthineers, Sysmex Corporation, Masimo Corporation, EKF Diagnostics, HemoCue, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Nihon Kohden Corporation, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemoglobin Monitor Market Shifts & Advancements
Silicon photonics, regulatory harmonization pressures, and procurement consolidation are restructuring how hemoglobin monitoring technology reaches clinical endpoints.
Photonic integrated circuits are absorbing functions previously performed by discrete lenses, filters, and detectors in benchtop spectrophotometers. Emergency departments and outpatient clinics are adopting chip-based devices to reduce capital expenditure and maintenance overhead. This consolidation is absorbing margin from traditional optical component suppliers while enabling new entrants to bypass legacy supply chain relationships.
The EU Medical Device Regulation is imposing stricter clinical evidence requirements and post-market surveillance obligations on hemoglobin monitor manufacturers. European notified bodies are demanding extended follow-up data for software-as-a-medical-device classifications. Developers targeting European markets are responding by front-loading clinical validation budgets and restructuring quality management systems to satisfy MDR Annex IX conformity assessment routes.
Integrated delivery networks in the United States are consolidating laboratory procurement decisions under centralized supply chain officers. Hospital systems are unbundling after-sales service agreements from capital equipment purchases, forcing manufacturers to compete on transparent lifecycle cost rather than bundled reagent contracts. This concentration is most visible in multi-hospital systems across Texas, California, and Florida, where procurement officers negotiate enterprise-wide device standardization.
Hemoglobin Monitor Market Segmentation
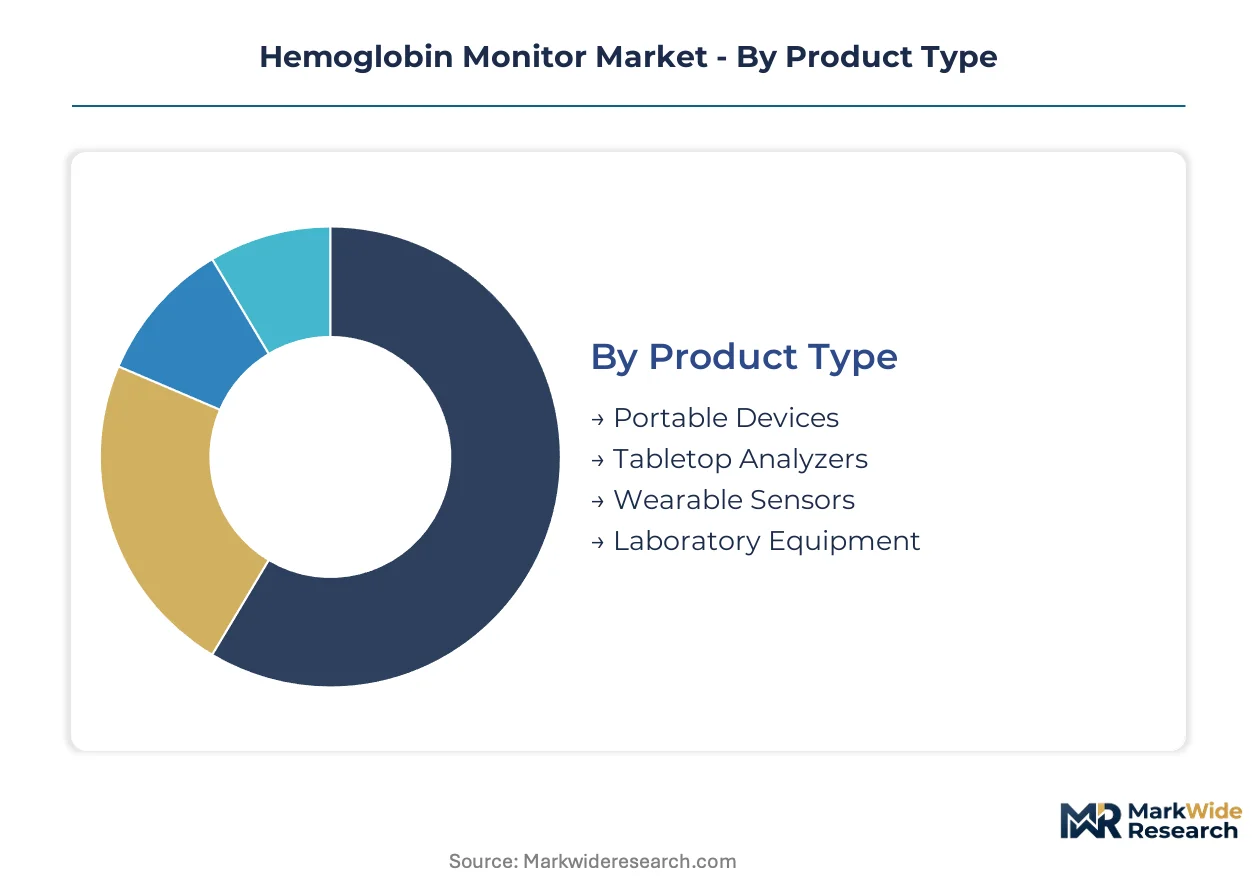
Product architecture and integration depth determine how hemoglobin monitors reach clinical endpoints. Segmentation reveals which formats function as standalone instruments versus embedded components within broader care workflows.
Product Type:
Standalone portable devices dominate deployments where laboratory infrastructure remains absent, while embedded laboratory systems integrate into automated hematology workflows.
- Portable Devices:Battery-operated units weighing under 2 kilograms deploy optical absorbance or electrical impedance methods. Demand clusters in rural India and sub-Saharan Africa where cold-chain pathology remains unavailable. Calibration drift across skin tone variations constrains clinical acceptance despite WHO prequalification efforts.
- Tabletop Analyzers:Benchtop instruments process venous samples through photometric or electrochemical detection, typically interfacing with laboratory information systems. Siemens Healthineers and Roche Diagnostics sustain premium positioning through bundled reagent contracts in European hospital networks.
- Wearable Sensors:Continuous monitoring patches leverage photoplethysmography for ambulatory hemoglobin estimation. Masimo's signal extraction technology differentiates offerings from pulse-oximetry commoditization in US acute care settings.
- Laboratory Equipment:High-throughput analyzers integrate into automated hematology lines, capturing disproportionate value through service agreements and consumable lock-in.
Volume placements concentrate in portable devices; the faster expansion belongs to wearable sensors.
Technology:
Detection methodology governs accuracy thresholds, power budgets, and regulatory classification pathways.
- Optical:Spectrophotometric and photoplethysmographic approaches measure hemoglobin absorbance at specific wavelengths. FDA 510(k) clearances for non-invasive optical sensors are compressing time-to-market for chip-scale spectrometer developers.
- Electrical:Impedance-based counters distinguish red blood cell volume and concentration in automated hematology analyzers. This technology anchors laboratory throughput in Japanese and German hospital systems.
- Colorimetric:Visual comparison methods using reagent strips persist in resource-constrained settings despite subjective interpretation limitations.
- Electrochemical:Amperometric sensors enable miniaturization for wearable formats where power constraints favor low-current detection. Home hemodialysis monitoring applications are climbing the fastest in North American markets.
Optical platforms command installed capacity leadership; electrochemical approaches are gaining share fastest in ambulatory formats.
End User:
Procurement authority and reimbursement pathways segment demand across institutional and consumer channels.
- Hospitals:Emergency departments in US integrated delivery networks drive point-of-care adoption for sub-minute anemia triage. Silicon photonics integration is reducing capital expenditure for bedside deployment.
- Clinics:Outpatient facilities prioritize portable devices with minimal maintenance overhead. Procurement decisions in Texas and California health systems are consolidating under enterprise supply chain officers.
- Homecare:Patient-managed monitoring expands through wearable electrochemical sensors. EU MDR compliance burdens are extending certification timelines for software-as-medical-device classifications in this channel.
- Blood Banks:Donor screening protocols require high-throughput laboratory equipment with traceable calibration standards.
Hospital procurement volumes dominate institutional placements; homecare channels are expanding most quickly through dialysis patient populations.
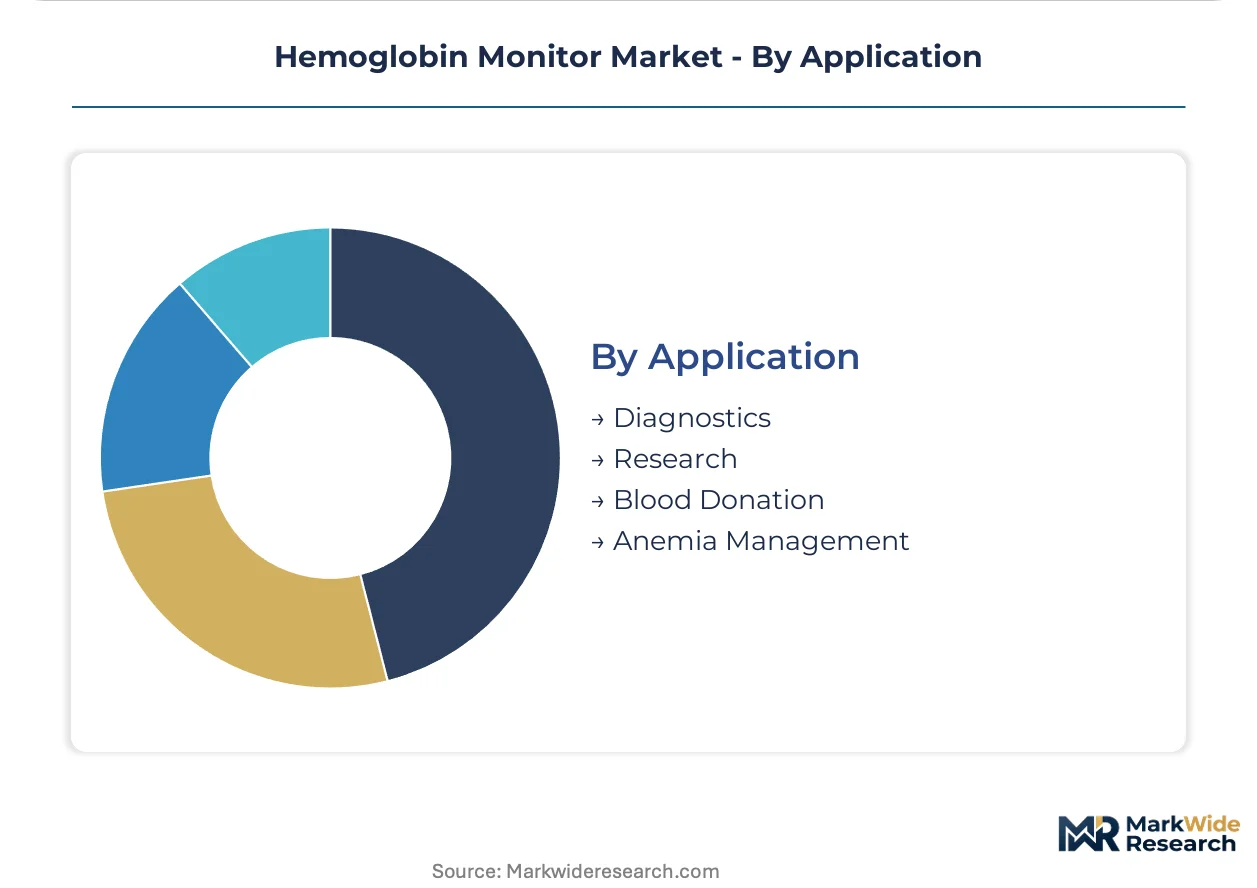
Application:
Clinical purpose determines performance specifications, regulatory evidence requirements, and reimbursement codes.
- Diagnostics:Acute anemia detection and chronic disease monitoring represent the primary revenue pool. Point-of-care adoption in US emergency departments is compressing traditional laboratory testing cycles.
- Research:Clinical trials and epidemiological studies demand calibrated instruments with documented precision profiles. Academic medical centers in Massachusetts and California anchor this segment.
- Blood Donation:Pre-donation hemoglobin screening prevents deferral and ensures donor safety. Portable devices address infrastructure gaps in Indian and Nigerian collection centers.
- Anemia Management:Chronic tracking for oncology and chronic kidney disease patients drives wearable sensor demand. ISO 80601-2-61 harmonization provides regulatory templates for multi-jurisdictional approval.
Diagnostic applications capture the deepest revenue base; anemia management applications are climbing the fastest through home-based monitoring expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Dubai Healthcare City concentrate manufacturing and distribution for hemoglobin monitoring devices, channeling investment toward duty-exempt assembly and regional regulatory fast-tracks.
United States
Emergency departments across Texas, California, and Florida health systems drive point-of-care adoption for sub-minute anemia triage. FDA 510(k) premarket notification pathways compress clearance timelines for non-invasive optical sensors. Silicon photonics startups cluster in Massachusetts and California, leveraging venture capital access to develop chip-scale spectrometers.
Germany
Hospital laboratory networks in Bavaria and North Rhine-Westphalia sustain premium demand for tabletop analyzers through bundled reagent contracts. EU Medical Device Regulation imposes stricter post-market surveillance and notified body oversight, extending certification timelines. Siemens Healthineers anchors its European presence through installed base maintenance in Frankfurt and Munich medical centers.
China
Domestic procurement policies favor NMPA-cleared devices for tier-two and tier-three hospital upgrades in Jiangsu and Guangdong provinces. Shenzhen Mindray Bio-Medical Electronics exemplifies local manufacturing scale in the Pearl River Delta. The country's national medical device regulator accelerates review timelines for innovative optical technologies under priority review channels.
India
WHO prequalification efforts and national anemia screening programs drive portable device demand in Maharashtra and Karnataka primary health centers. CDSCO regulates medical device imports and local manufacturing under the Medical Device Rules framework. Diagnostic access gaps in rural Bihar and Uttar Pradesh channel NGO and government procurement toward battery-operated units.
Japan
Aging demographics and chronic kidney disease prevalence sustain demand for home monitoring in Tokyo and Osaka metropolitan areas. PMDA oversees pharmaceutical and medical device safety, requiring local clinical trials for novel hemoglobin estimation algorithms. Sysmex Corporation and Nihon Kohden Corporation anchor domestic laboratory and patient monitoring supply chains.
Hemoglobin Monitor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier instrument makers defending margin through service bundling while volume producers compete on unit cost in emerging markets. The vendor base organizes into three tiers: multinational conglomerates with diversified diagnostics portfolios, mid-cap specialists focused on single-parameter monitoring, and regional assemblers serving price-sensitive procurement. Strategic moves concentrate on silicon photonics R&D partnerships and vertical integration into optical component supply.
Among diversified health technology conglomerates, Abbott and Danaher Corporation occupy positions spanning laboratory automation and point-of-care diagnostics. Masimo Corporation exemplifies the specialist archetype through proprietary signal extraction technology that differentiates wearable sensors from commodity pulse-oximetry. Siemens Healthineers represents the European premium-tier model, leveraging decades of installed base relationships in hospital laboratory networks.
| Leading Market Players |
|---|
| Abbott |
| Siemens Healthineers |
| Sysmex Corporation |
| Masimo Corporation |
| EKF Diagnostics |
| HemoCue |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Nihon Kohden Corporation |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
Silicon wafer spot prices and photonics-grade substrate costs cascade through hemoglobin monitor manufacturing, compressing margins for optical component suppliers while amplifying pricing power for integrated device manufacturers with captive chip fabrication.
Pricing Analysis
Lead-time premiums command 15-25 percent markups for FDA-cleared devices with sub-90-day delivery, while spot inventory of pre-certified units trades at discounts in secondary distribution channels. Three-tier pricing structure across premium, standard, and economy levels separates Masimo's signal-extraction-enabled wearables from mid-tier portable devices and unbranded colorimetric strips. Cost compression in the economy tier intensifies as Shenzhen assemblers flood Indian and Nigerian procurement tenders with battery-operated units lacking ISO 80601-2-61 harmonization. Public hospital systems in Texas and California exhibit highest price sensitivity, while German laboratory networks sustain premium tolerance through bundled reagent contracts.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific shipping lanes has restructured procurement calendars, with US distributors front-loading inventory ahead of peak ocean container rates. Manufacturing concentrates in China for silicon photonics foundry services, Germany for precision optical components, and Malaysia for final device assembly. Raw material dependencies span indium phosphide wafers, medical-grade polymers, and lithium-ion cells for portable power. Single-source vulnerability concentrates in European reagent manufacturing clusters serving tabletop analyzer installed bases. Distribution runs through hospital GPO contracts in North America, regional device distributors in sub-Saharan Africa, and direct government procurement in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around silicon photonics capability and regulatory certification scale, with EU MDR compliance burdens forcing sub-scale developers toward acquisition or exit.
For Market Incumbents: Deepen backward integration into photonics-grade substrate supply through partnerships with Taiwan and China foundries, insulating against wafer price volatility. Expand ISO 80601-2-61 harmonization investments to accelerate multi-jurisdictional clearance timelines. Defend against Masimo's signal extraction moat by acquiring electrochemical sensor startups with home hemodialysis monitoring pipelines. For New Entrants and Emerging Players: Direct-to-clinic digital procurement platforms bypass entrenched GPO relationships and compress customer acquisition costs for chip-scale spectrometer developers. Target rural Indian primary health centers and Nigerian blood bank collection sites where WHO prequalification substitutes for FDA clearance. White-space opportunity concentrates in wearable electrochemical formats for chronic kidney disease patient populations outside clinical facilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with EU MDR technical documentation packages but limited US commercial infrastructure, particularly in Bavaria and North Rhine-Westphalia laboratory equipment clusters. Long-term viability hinges on software-as-medical-device revenue streams and recurring calibration service attach rates. Watch FDA 510(k) clearance velocity for non-invasive optical sensors as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics R&D Partnership | Chip-scale spectrometer development reduces component count and unit cost for portable formats. |
| FDA 510(k) Submission Acceleration | Premarket notification compression enables faster US commercialization for optical sensor entrants. |
| Hospital System Partnership | Integrated delivery network procurement consolidation favors enterprise-wide device standardization agreements. |
| Software Companion Development | Algorithm-based hemoglobin estimation triggers EU AI Act risk classification and extended validation requirements. |
| Reimbursement Strategy | CPT code alignment for point-of-care anemia triage unlocks emergency department procurement budgets. |
Research Methodology
Document review covered FDA 510(k) clearance databases, EU MDR notified body technical documentation, and ISO 80601-2-61 harmonization guidance, complemented by interviews with hospital biomedical engineers, GPO contracts managers, and point-of-care device procurement officers. Secondary sources included CMS Medicare reimbursement schedules, hospital capital equipment expenditure filings, and silicon photonics foundry capacity disclosures. Bottom-up triangulation across device shipment estimates and top-down validation through laboratory procurement spend analysis anchored market sizing.
Installed base projections and replacement cycle assumptions drove volume estimates across portable, tabletop, wearable, and laboratory equipment formats. Segmentation modeling incorporated product architecture, detection technology, end-user procurement authority, and clinical application purpose. CAGRs derived from weighted average of historical penetration curves and technology substitution elasticities, with silicon photonics adoption rates and EU MDR certification timelines as key demand-side inputs.
The model holds under stable regulatory harmonization progress and contained freight cost volatility; deviation in FDA software-as-medical-device guidance or EU AI Act enforcement intensity would shift commercialization timelines and competitive positioning. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
Global Intrapartum Monitoring Devices Market
Patient Monitoring
US Remote Patient Monitoring and Care Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market
Patient Monitoring
Urine Output Monitoring Systems Market
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
Drowsiness Monitoring System Market
Patient Monitoring
Middle East and Africa Patient Monitoring Market
Patient Monitoring
Global Bed Monitoring System and Baby Monitoring System Market
Patient Monitoring
Compartment Syndrome Monitoring Devices Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Global Vital Sign Monitoring Market
Patient Monitoring
Digital Patient Monitoring Devices Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
Global IOT Sensors in Healthcare Market