
 South Africa Patient Monitoring Market | 2026-2036
South Africa Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Patient Monitoring Market Analytics
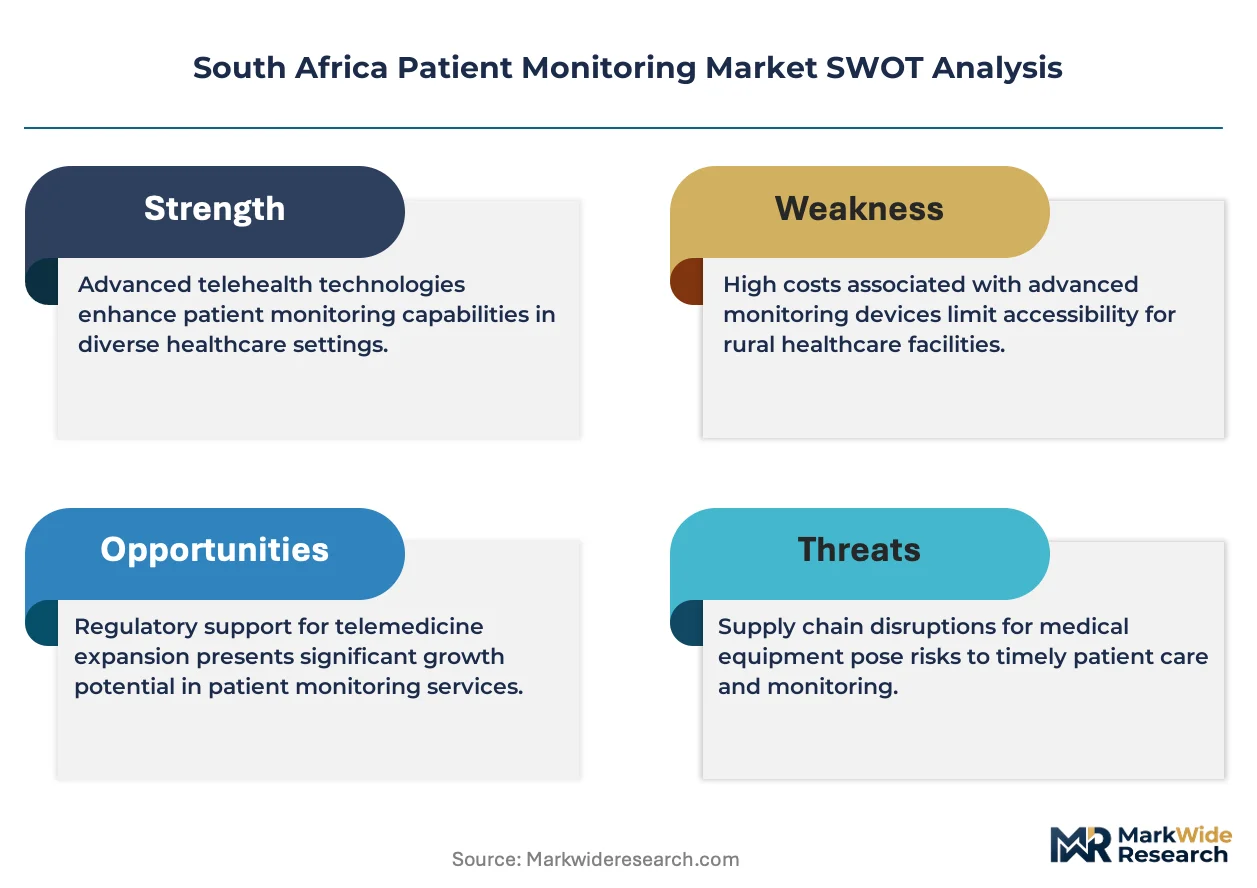
Remote monitoring subscription tiers is restructuring how equipment vendors capture lifetime value from acute-care deployments. Philips Healthcare sustains broad channel coverage across public hospital networks through long-term service contracts. GE Healthcare dominates imaging-integrated monitoring suites in tertiary facilities. Masimo Corporation specializes in pulse oximetry and noninvasive hemoglobin tracking for high-acuity settings.
Patient monitoring encompasses continuous or intermittent physiological measurement systems—electrocardiography, pulse oximetry, capnography, blood pressure, and respiratory rate—typically operating at sampling frequencies from 125 Hz to 1000 Hz for waveform capture, with alarm latency thresholds under 10 seconds for critical events. These systems enable early detection of patient deterioration, reduce unplanned intensive care admissions, and support clinical workflow optimization in resource-constrained environments. Wearable devices and remote monitoring systems are gaining fastest traction as home care providers and rehabilitation centers seek to extend observation beyond ward boundaries. Bedside monitors retain the largest installed base in public hospitals but face margin compression from procurement centralization under provincial health departments.
South Africa's Health Products Regulatory Authority governs medical device registration and post-market surveillance, while the South African Bureau of Standards enforces IEC 60601 electrical safety and EMC compliance for monitoring equipment. The National Health Insurance framework will reshape purchasing concentration and technical specifications as provincial procurement merges toward centralized acquisition. Stakeholders must track regulatory harmonization timelines and provincial tender restructuring to align product portfolios with evolving reimbursement and compliance pathways.
Market Dynamics
The National Health Insurance policy is consolidating procurement authority under provincial health departments, compressing margins for equipment vendors while expanding volume commitments through centralized tender frameworks.
Growth Catalysts
- NHI Centralization:The National Health Insurance framework is merging provincial purchasing into centralized acquisition pools, creating predictable demand pipelines for certified device vendors.
- Wireless Transmission Protocols:Home care providers in Gauteng province are adopting Bluetooth Low Energy and cellular telemetry to extend monitoring beyond hospital wards.
- High-Acuity Specialization:Tertiary facilities are expanding pulse oximetry and noninvasive hemoglobin tracking capabilities for critical care units.
Market Restraints
- Import Dependency:Monitoring equipment relies on semiconductor and sensor imports subject to currency volatility and shipping disruptions through Durban port corridors.
- IEC 60601 Compliance Burden:South African Bureau of Standards electrical safety certification requires extensive EMC testing, extending product launch timelines by 8-14 months.
- Disposable Sensor Costs:Single-use pulse oximeter probes and ECG electrodes constitute recurring operational expenditures that strain constrained public hospital budgets.
Strategic Opportunities
- Home Care Extension:Rehabilitation centers in KwaZulu-Natal and Western Cape provinces represent underpenetrated channels for wearable ambulatory monitors.
- Remote Subscription Models:Equipment vendors can capture lifetime value through tiered service contracts bundling hardware, connectivity, and clinical decision support.
- Regulatory Harmonization:Alignment between South African Health Products Regulatory Authority and WHO prequalification pathways could accelerate export eligibility to neighboring SADC markets.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Public hospitals face critical shortages of technicians trained on multi-parameter monitor calibration and alarm configuration.
- Legacy System Integration:Bedside monitors from disparate manufacturers require middleware development to feed unified electronic health record platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Patient Monitoring Market |
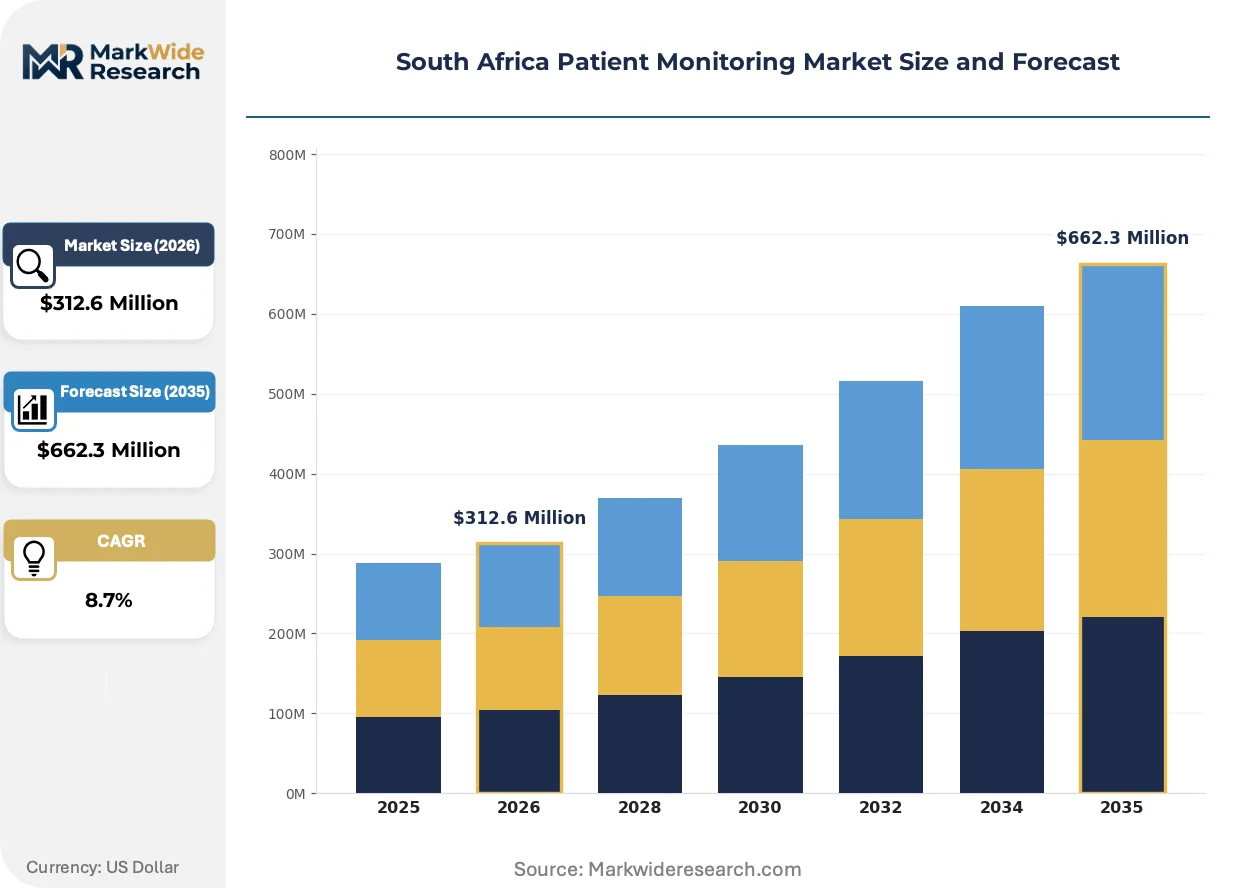
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Bedside Monitors, Remote Monitoring Systems, Diagnostic Equipment Technology: Wireless Transmission, Bluetooth Connectivity, Cloud Computing, Sensor Technology End User: Hospitals, Home Care Providers, Specialty Clinics, Rehabilitation Centers Application: Cardiac Monitoring, Neurological Assessment, Maternal Care, Chronic Disease Management |
| Companies Covered | GE Healthcare, Abbott Laboratories, Philips Healthcare, Medtronic, Johnson & Johnson, Becton, Dickinson and Company, Boston Scientific Corporation, Masimo Corporation, Nihon Kohden Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Patient Monitoring Market Evolving Landscape
Algorithmic processing of physiological waveforms is reducing false alarm rates while cloud-based telemetry architectures are enabling real-time clinician notification beyond traditional ward boundaries.
Artificial intelligence embedded in patient monitoring systems is automating arrhythmia detection and respiratory pattern analysis. Tertiary hospitals in Johannesburg and Cape Town are deploying these modules to reduce nurse alarm fatigue. The technology is automating clinical surveillance tasks previously requiring continuous human attention, compressing response times for patient deterioration events.
South Africa's Health Products Regulatory Authority is tightening post-market surveillance requirements for software-as-medical-device updates, mandating documented validation for algorithm changes. Manufacturers must now submit cybersecurity risk assessments alongside traditional safety filings. Class C and D monitoring devices face expanded clinical evidence requirements before registration renewal.
Provincial health departments are unbundling equipment procurement from multi-year service agreements, separating capital purchases from technical support contracts. Public hospital networks in Gauteng and Western Cape are piloting this approach to improve lifecycle cost transparency. The shift is most visible in large academic medical centers negotiating standalone preventive maintenance schedules.
South Africa Patient Monitoring Market Segmentation
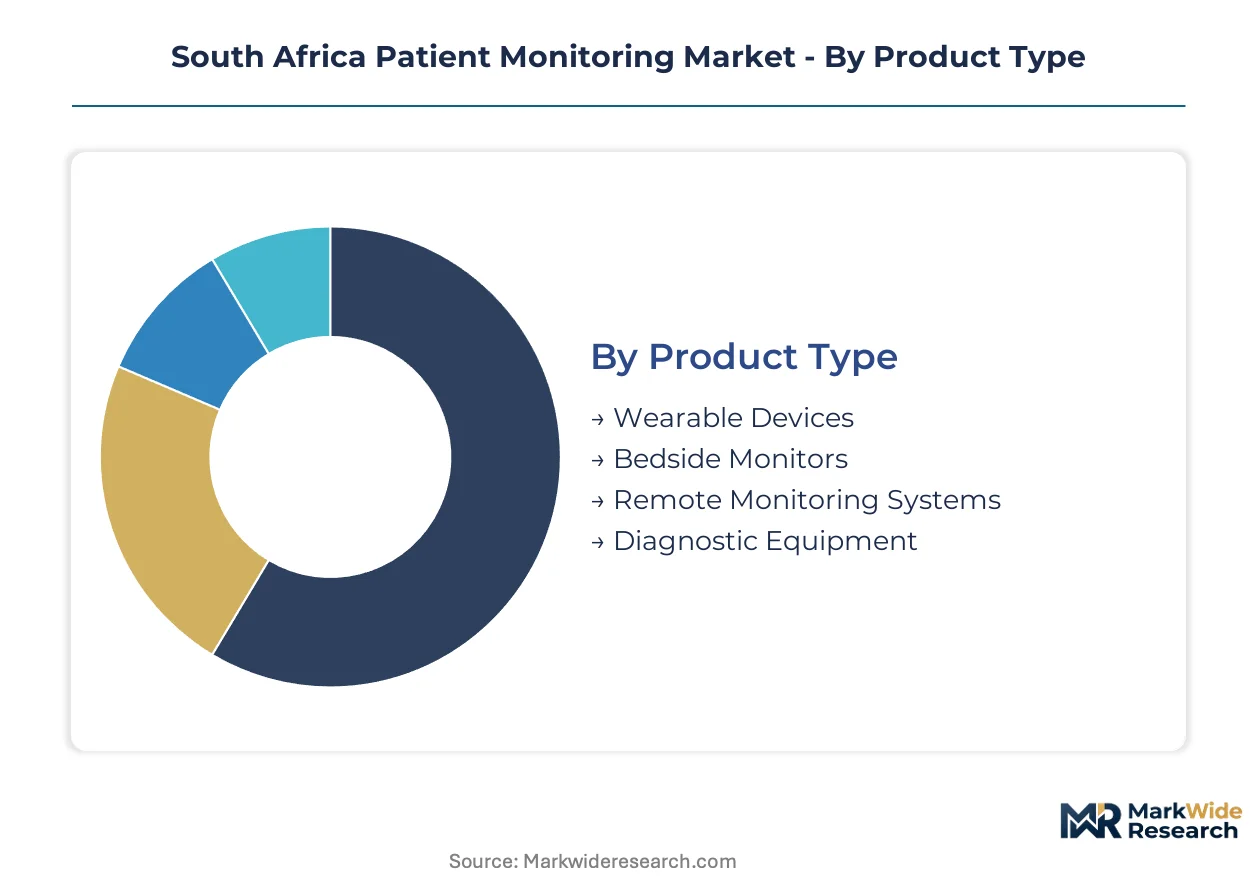
Patient monitoring equipment in South Africa exhibits distinct procurement patterns across hardware categories, connectivity standards, and care settings. Understanding these segment boundaries helps vendors align certification timelines with provincial tender specifications and reimbursement pathways.
Product Type:
Bedside monitors command the highest unit volumes in public hospital networks, while wearable devices capture premium pricing in private home care channels.
- Bedside Monitors:Multi-parameter systems integrating ECG, pulse oximetry, and blood pressure measurement at 125-1000 Hz sampling frequencies. Procurement concentrates in Gauteng and Western Cape provincial health departments, where centralization under National Health Insurance frameworks is compressing margins but locking in multi-year volume commitments.
- Wearable Devices:Ambulatory monitors with Bluetooth Low Energy transmission for continuous physiological tracking outside clinical settings. Demand clusters among home care providers in Johannesburg's northern suburbs and Cape Town's Atlantic seaboard, driven by post-acute discharge protocols and remote patient monitoring reimbursement pilots.
- Remote Monitoring Systems:Cloud-connected telemetry platforms enabling real-time clinician notification beyond ward boundaries.
- Diagnostic Equipment:Stationary systems for episodic physiological assessment in clinical environments.
Mature deployment sits with bedside monitors in tertiary facilities. Newer deployment is concentrated in wearable devices for post-acute and rehabilitation settings.
Technology:
Wireless protocols are displacing hardwired architectures as provincial health departments prioritize infrastructure flexibility and reduced installation costs.
- Wireless Transmission:Cellular and Wi-Fi telemetry enabling real-time data streaming from patient to central monitoring stations. Adoption is accelerating in KwaZulu-Natal public hospitals seeking to extend monitoring to overflow wards without fixed infrastructure investment.
- Bluetooth Connectivity:Low-energy protocols for short-range device-to-gateway communication in ambulatory and home settings. Deployment concentrates among Gauteng home care providers integrating patient-generated data into electronic health record platforms.
- Cloud Computing:Centralized data architectures supporting multi-site monitoring and predictive analytics.
- Sensor Technology:Semiconductor-based physiological detection components including pulse oximetry LEDs and ECG electrodes.
Established infrastructure relies on hardwired sensor networks. Cloud computing represents the steepest expansion trajectory as tertiary facilities deploy AI-enabled arrhythmia detection modules.
End User:
Hospital procurement dominates absolute equipment volumes, though home care providers are expanding fastest as reimbursement shifts toward community-based chronic disease management.
- Hospitals:Acute-care facilities requiring continuous multi-parameter monitoring for critical, step-down, and general ward patients. Demand concentrates in Chris Hani Baragwanath, Groote Schuur, and Tygerberg academic complexes, where imaging-integrated monitoring suites command premium procurement cycles.
- Home Care Providers:Community-based services managing post-acute and chronic patients outside institutional settings. Growth centers in Gauteng's private nursing networks, where National Health Insurance pilot programs are testing remote monitoring reimbursement.
- Specialty Clinics:Cardiac, neurological, and maternal-focused outpatient facilities requiring episodic diagnostic monitoring.
- Rehabilitation Centers:Post-surgical and stroke recovery facilities in KwaZulu-Natal and Western Cape provinces seeking ambulatory monitoring for mobility-assessed patients.
Installed base concentration remains with hospitals. Rehabilitation centers and home care providers are gaining share fastest as discharge-to-community protocols expand.
Application:
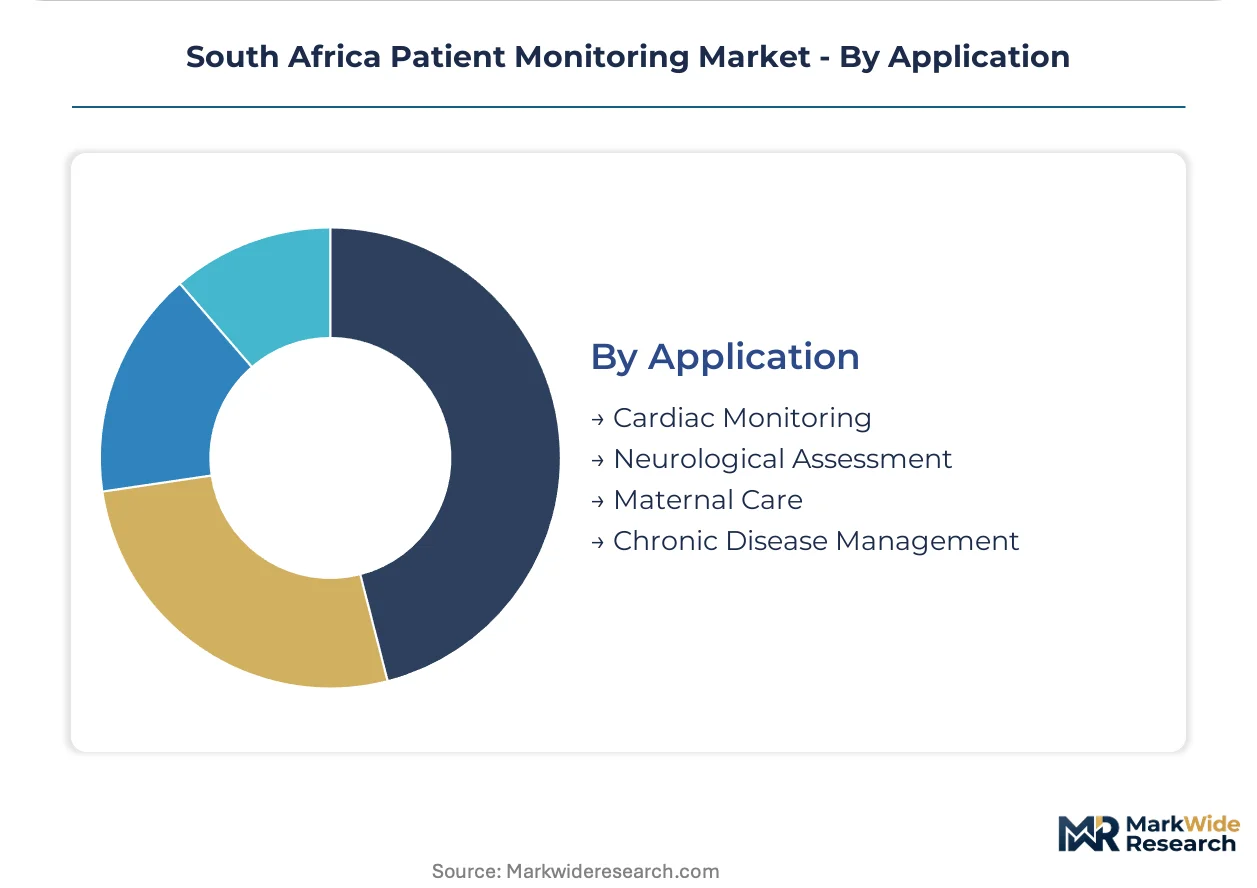
Cardiac monitoring generates the highest equipment utilization rates, while chronic disease management is reshaping procurement specifications toward longitudinal data capture.
- Cardiac Monitoring:Continuous ECG and arrhythmia detection systems for acute coronary syndrome, post-surgical recovery, and critical care surveillance. Deployment concentrates in Johannesburg and Cape Town tertiary cardiac units, where AI-enabled automated detection is reducing nurse alarm fatigue.
- Chronic Disease Management:Longitudinal tracking of hypertension, diabetes, and respiratory conditions through connected home devices. Adoption is climbing fastest in Western Cape public health networks, where provincial tenders now specify remote monitoring compatibility for chronic care program expansion.
- Neurological Assessment:EEG and intracranial pressure monitoring for stroke, trauma, and seizure management.
- Maternal Care:Fetal heart rate and uterine contraction monitoring for labor and delivery units.
Critical-acuity applications dominate bedside monitor deployment. Chronic disease management is driving the fastest equipment refresh cycles as home-based reimbursement models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for patient monitoring hardware sits with semiconductor and sensor suppliers in East Asia and Western Europe, while South Africa's demand absorbs these imports through Durban port corridors. Provincial health departments in Gauteng, Western Cape, and KwaZulu-Natal drive procurement volumes as National Health Insurance centralization reshapes distribution pathways.
Gauteng Province
Johannesburg and Pretoria academic medical centers anchor the country's highest monitoring equipment density, driven by Chris Hani Baragwanath and Steve Biko Hospital procurement cycles. The National Health Insurance pilot programs here specify wireless telemetry compatibility for chronic disease management tenders. Home care providers in Johannesburg's northern suburbs are deploying Bluetooth-enabled ambulatory monitors for post-acute discharge protocols.
Western Cape Province
Cape Town's Groote Schuur and Tygerberg hospitals command premium procurement cycles for imaging-integrated monitoring suites. The provincial health department is unbundling equipment purchases from service contracts to improve lifecycle cost transparency. Rehabilitation centers along the Atlantic seaboard represent underpenetrated channels for wearable devices serving mobility-assessed patients.
KwaZulu-Natal Province
Durban and Pietermaritzburg public hospitals are accelerating wireless transmission adoption to extend monitoring to overflow wards without fixed infrastructure investment. The South African Health Products Regulatory Authority's post-market surveillance requirements are tightening software validation standards for devices deployed here. Private nursing networks in eThekwini are testing remote monitoring reimbursement models.
South Africa Patient Monitoring Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across South Africa's patient monitoring sector. The market structure shows moderate consolidation among multinational device manufacturers holding long-term provincial service contracts, while specialized sensor suppliers and regional distributors populate fragmented lower tiers. Three archetypes dominate: imaging-integrated suite providers, pulse oximetry specialists, and connectivity-focused remote monitoring platforms. Competitive moves center on multi-year tender positioning under National Health Insurance frameworks and middleware development for electronic health record integration.
Within the imaging-integrated tier, GE Healthcare and Philips Healthcare occupy positions as anchors for tertiary facility procurement. Masimo Corporation exemplifies the high-acuity specialization archetype through its pulse oximetry and noninvasive hemoglobin tracking capabilities. These three manufacturers represent distinct strategic postures—GE Healthcare through imaging suite dominance, Philips Healthcare through broad channel coverage, and Masimo Corporation through critical-care sensor specialization.
| Leading Market Players |
|---|
| GE Healthcare |
| Abbott Laboratories |
| Philips Healthcare |
| Medtronic |
| Johnson & Johnson |
| Becton, Dickinson and Company |
| Boston Scientific Corporation |
| Masimo Corporation |
| Nihon Kohden Corporation |
| Others |
Value Network & Pricing Analysis
IEC 60601 electrical safety certification gates qualified supply access for patient monitoring equipment in South Africa, compressing margins for uncertified vendors while enabling premium-tier pricing for compliant manufacturers serving provincial health department tenders.
Pricing Analysis
Margin tightening in bedside monitor procurement reflects National Health Insurance centralization consolidating purchasing authority under Gauteng, Western Cape, and KwaZulu-Natal provincial health departments. Three-tier pricing structure across premium imaging-integrated suites, standard multi-parameter systems, and economy ward monitors differentiates by certification grade and after-sales service bundling. Cost compression accelerates as unbundled equipment purchases separate capital outlays from technical support contracts. Public hospital networks exhibit highest price sensitivity, while private home care providers in Johannesburg's northern suburbs absorb premium pricing for Bluetooth-enabled ambulatory devices.
Supply Chain Analysis
Domestic-content mandates remain nascent for medical device assembly in South Africa, leaving procurement dependent on semiconductor and sensor imports from Taiwan, South Korea, and Germany. Pulse oximetry LEDs, ECG electrodes, and multi-parameter monitor chipsets feed from East Asian fabrication facilities through Durban port corridors. Single-source vulnerability concentrates in specialized sensor components where alternative suppliers face extended South African Bureau of Standards EMC validation timelines. Distribution runs through multinational device manufacturers holding long-term provincial service contracts, with regional distributors populating fragmented lower tiers for disposable consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's patient monitoring market functions as a cost-of-compliance story where IEC 60601 electrical safety certification and South African Health Products Regulatory Authority registration create substantial barrier-to-entry moats favoring established multinational manufacturers with validated quality management systems.
For Market Incumbents: Lock in multi-year provincial tender positioning under National Health Insurance centralization frameworks by deepening technical service capabilities and middleware development for electronic health record integration. Consolidate channel control through preventive maintenance contracts that extend beyond standalone equipment sales, defending against margin compression from unbundled procurement pilots at Groote Schuur and Tygerberg academic complexes. For New Entrants and Emerging Players: Begin with wearable ambulatory monitors targeting rehabilitation centers in KwaZulu-Natal and Western Cape provinces, where underpenetrated channels and mobility-assessed patient protocols create white-space opportunity. Home care providers in eThekwini private nursing networks offer the most penetrable segment, with remote monitoring reimbursement pilots enabling a software-as-medical-device go-to-market angle that sidesteps capital-intensive bedside monitor procurement cycles. For Investors and Strategic Acquirers: National Health Insurance tender restructuring toward centralized provincial acquisition pools is the leading indicator that long-term contract visibility will concentrate among manufacturers with established biomedical engineering service networks. Acquisition target archetypes include specialized pulse oximetry sensor suppliers and regional distributors with validated South African Bureau of Standards compliance track records. Watch for provincial health department unbundling of equipment from service contracts as the signal for lifecycle cost transparency becoming a competitive differentiator.| Strategic Initiative | Industry Significance |
|---|---|
| South African Health Products Regulatory Authority Registration Pathway | Software validation requirements for algorithm updates extend compliance timelines for AI-enabled arrhythmia detection modules. |
| Provincial Hospital System Partnership | Long-term service contracts at Chris Hani Baragwanath and Steve Biko Hospital anchor revenue predictability under NHI frameworks. |
| Bluetooth Low Energy Companion Development | Wireless telemetry integration enables home care providers in Gauteng to feed patient-generated data into electronic health record platforms. |
| Reimbursement Strategy Alignment | Remote monitoring subscription tiers capture lifetime value as National Health Insurance pilots test chronic disease management coverage. |
| Biomedical Engineering Talent Investment | Technician training programs address critical shortages in multi-parameter monitor calibration and alarm configuration at public hospitals. |
Research Methodology
Multi-period observation of provincial tender awards, regulatory filing timelines, and wireless telemetry adoption rates anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and home care provider operations directors. Secondary validation drew from South African Health Products Regulatory Authority registration databases, South African Bureau of Standards certification records, provincial health department procurement disclosures, and hospital equipment utilization audits. Bottom-up equipment shipment tracking and top-down healthcare expenditure modeling were triangulated to reconcile volume and value estimates.
Segment-weighting approaches distributed total market value across product type, connectivity standard, end-user facility, and clinical application dimensions, with provincial procurement concentration and reimbursement pathway maturity serving as additional analytical layers. CAGRs were derived from fitted growth curves applied to historical shipment data and projected tender pipeline visibility, incorporating AI-enabled monitoring module deployment rates and chronic disease management program expansion trajectories across the analysis window.
Currency volatility affecting semiconductor import costs, shipping disruptions through Durban port corridors, and delays in National Health Insurance implementation timelines are the dominant revision risks to forecast assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Vital Sign Monitoring Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Wearable ECG Monitors Market
Patient Monitoring
Italy Patient Monitoring Market
Patient Monitoring
United Kingdom Patient Monitoring Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
Remote Patient Monitoring Software Market
Patient Monitoring
Patient Scales Market
Patient Monitoring
Clinical Alarm Management Market
Patient Monitoring
Australia Patient Monitoring Market
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market
Patient Monitoring
Wearable Ambulatory Monitoring Device Market
Patient Monitoring
Brain Monitoring Systems Market
Patient Monitoring
North America Patient Temperature Management Market
Patient Monitoring
Digital Patient Monitoring Systems Market
Patient Monitoring
North America Remote Patient Monitoring Systems Market