
 Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market | 2026-2036
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market Intelligence
The EU Medical Device Regulation is shifting procurement criteria toward validated clinical-grade ABPM systems across European cardiology networks. Omron Healthcare leverages its oscillometric sensor portfolio to dominate home care channels in Japan and Germany. GE Healthcare sustains hospital-based deployment through integrated telemetry platforms that anchor enterprise hypertension programs.
Ambulatory Blood Pressure Monitoring devices are wearable diagnostic instruments that measure systolic and diastolic pressure at programmed intervals over 24-48 hours using oscillometric or auscultatory methods, producing circadian pattern data for masked hypertension detection and white-coat syndrome differentiation. Oscillometric devices lead volume sales due to automated measurement reliability and minimal technician dependency, while mobile ABPM units represent the fastest-expanding product class as Bluetooth-enabled units feed directly into telehealth platforms and remote patient monitoring dashboards. Pulse wave instruments occupy a narrower premium segment where arterial stiffness assessment commands higher reimbursement in specialized cardiology clinics.
FDA 510(k) clearance requirements and the EU MDR's Class IIa designation enforce clinical validation thresholds that filter out consumer-grade entrants, while Japan's PMDA maintains distinct accuracy certification protocols that shape product development priorities for manufacturers targeting East Asian markets. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring in the United States and Germany, where telehealth platform integration is becoming a prerequisite for institutional purchasing decisions rather than a secondary feature.
Market Dynamics
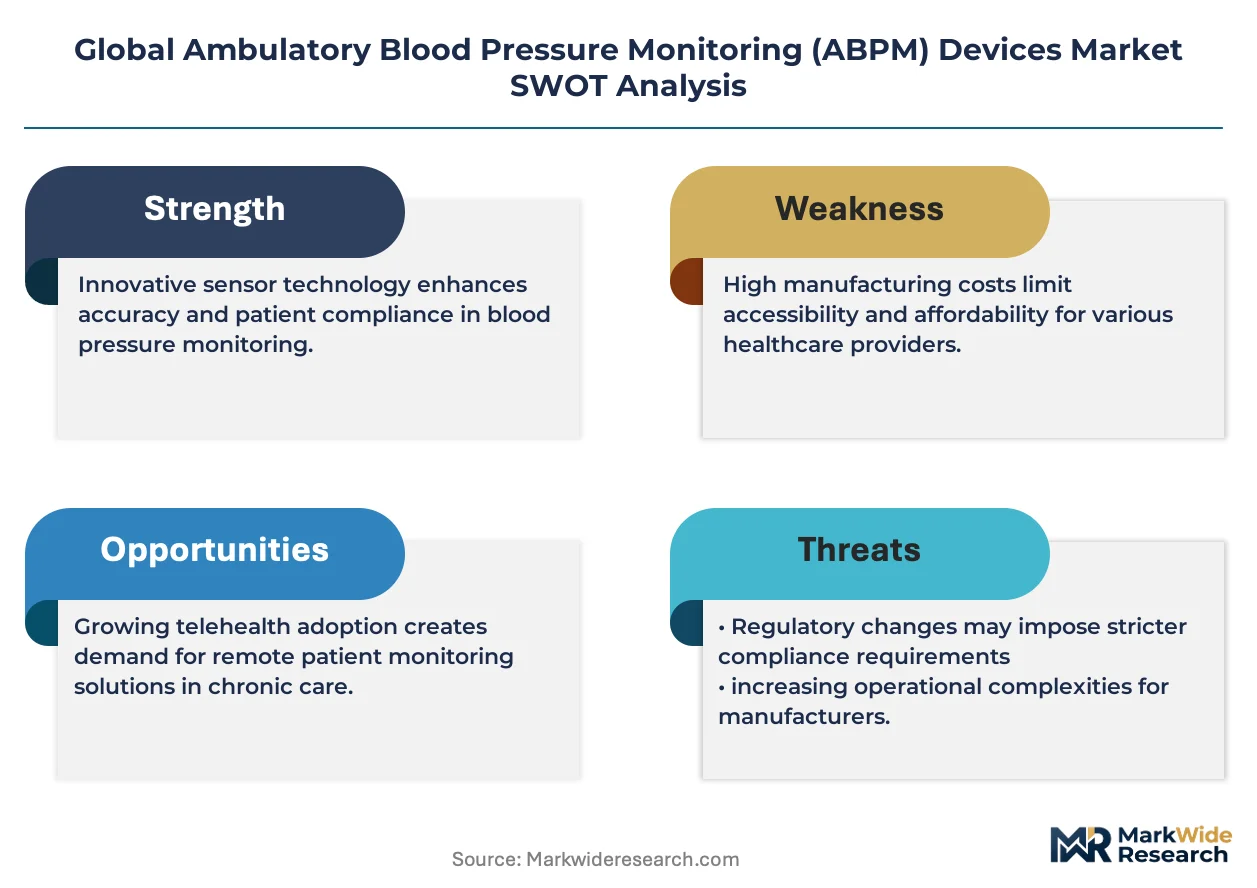
Telehealth platform integration is compressing the traditional ABPM procurement cycle, forcing manufacturers to embed Bluetooth connectivity and cloud APIs as baseline features rather than premium add-ons for cardiology networks.
Growth Catalysts
- EU MDR Class IIa designation:The tightened clinical validation threshold is filtering out consumer-grade competitors and elevating procurement standards across German and French hospital systems toward certified oscillometric systems.
- Remote patient monitoring reimbursement:CMS coding expansions in the United States are institutionalizing ABPM as a billable telehealth component, accelerating deployment through Medicare Advantage networks.
- Japan's aging demographic cluster:Metropolitan Tokyo and Osaka prefectures are driving PMDA-cleared device volumes as home-based hypertension management replaces frequent clinic visits for elderly populations.
Market Restraints
- Semiconductor component concentration:Pressure sensor MEMS fabrication depends heavily on Taiwanese foundry capacity, exposing lead-time volatility for oscillometric device manufacturers.
- FDA 510(k) pathway duration:Clinical validation requirements for algorithm modifications extend clearance timelines, delaying feature updates for mobile ABPM platforms.
- Consumer wearable substitution:Photoplethysmography-enabled smartwatches from Apple and Samsung are capturing price-sensitive screening demand outside reimbursed diagnostic channels.
Strategic Opportunities
- India's diagnostic infrastructure expansion:Ayushman Bharat health scheme penetration into tier-2 cities is creating first-time institutional demand for validated ABPM systems in cardiology clinics.
- Arterial stiffness assessment convergence:Pulse wave velocity integration with standard ABPM protocols is opening premium reimbursement tiers in German and Japanese specialized hypertension centers.
- Cloud-native platform distribution:Direct-to-clinic SaaS models are bypassing traditional medical device distributors, capturing margin and utilization data for manufacturers.
Industry Challenges
- Embedded software validation expertise:FDA cybersecurity guidance and EU MDR software lifecycle requirements are outstripping talent availability for algorithm verification and penetration testing.
- Legacy EHR integration complexity:HL7 FHIR compliance and proprietary hospital system architectures are extending deployment timelines and inflating professional services costs for ABPM platform vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market |
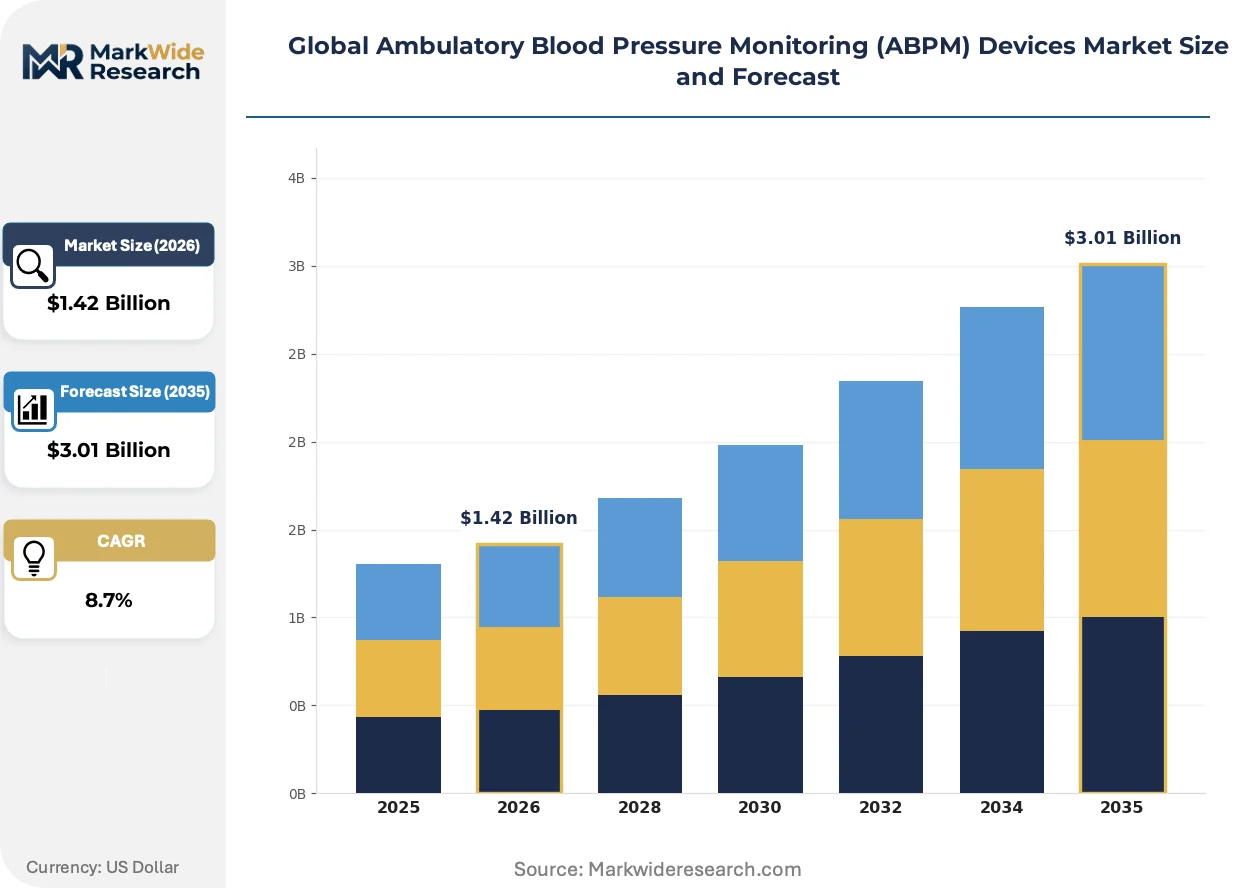
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oscillometric Devices, Aneroid Devices, Digital Monitors, Pulse Wave Instruments, Mobile ABPM Devices Application: Hypertension Diagnosis, Cardiovascular Risk Assessment, Sleep Apnea Monitoring, Renal Disease Management, Stroke Prevention, Stress Analysis End User: Cardiology Clinics, Primary Care Centers, Diagnostic Laboratories, Research Institutes, Home Care Patients Deployment Mode: Hospital-Based, Ambulatory Clinics, Remote Patient Monitoring, Telehealth Platforms, Outpatient Settings |
| Companies Covered | Omron Healthcare, GE Healthcare, Schiller AG, Spacelabs Healthcare, Bosch & Sohn GmbH & Co. KG, SunTech Medical, Welch Allyn, Hill-Rom Holdings, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market Strategic Shifts & Innovations
Artificial intelligence inference at the device edge is compressing diagnostic latency and enabling real-time arrhythmia flagging during ambulatory monitoring sessions.
Photoplethysmography-oscillometry hybrid sensors are electrifying the miniaturization trajectory for wrist-worn ABPM units. Cardiology clinics in Germany and Japan are piloting these systems for 48-hour monitoring protocols that previously required upper-arm cuffs. The technology is electrifying competition between traditional device manufacturers and consumer electronics entrants by collapsing the form-factor gap without sacrificing clinical-grade accuracy validation.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up data collection from deployed ABPM devices. Manufacturers must now maintain vigilance systems that track algorithm performance across diverse patient populations. French and Italian notified bodies are enforcing this most stringently, pushing vendors toward cloud-connected architectures that enable remote performance monitoring and automated adverse event reporting.
Hospital procurement committees are consolidating vendor relationships around enterprise-wide hypertension management platforms rather than discrete device purchases. Integrated telemetry systems that feed directly into Epic and Cerner EHR instances are displacing standalone ABPM units in US health system RFPs. This concentration is most visible in the United States, where IDN purchasing power and value-based care contracts favor single-vendor platform commitments over best-of-breed device selection.
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market Segmentation
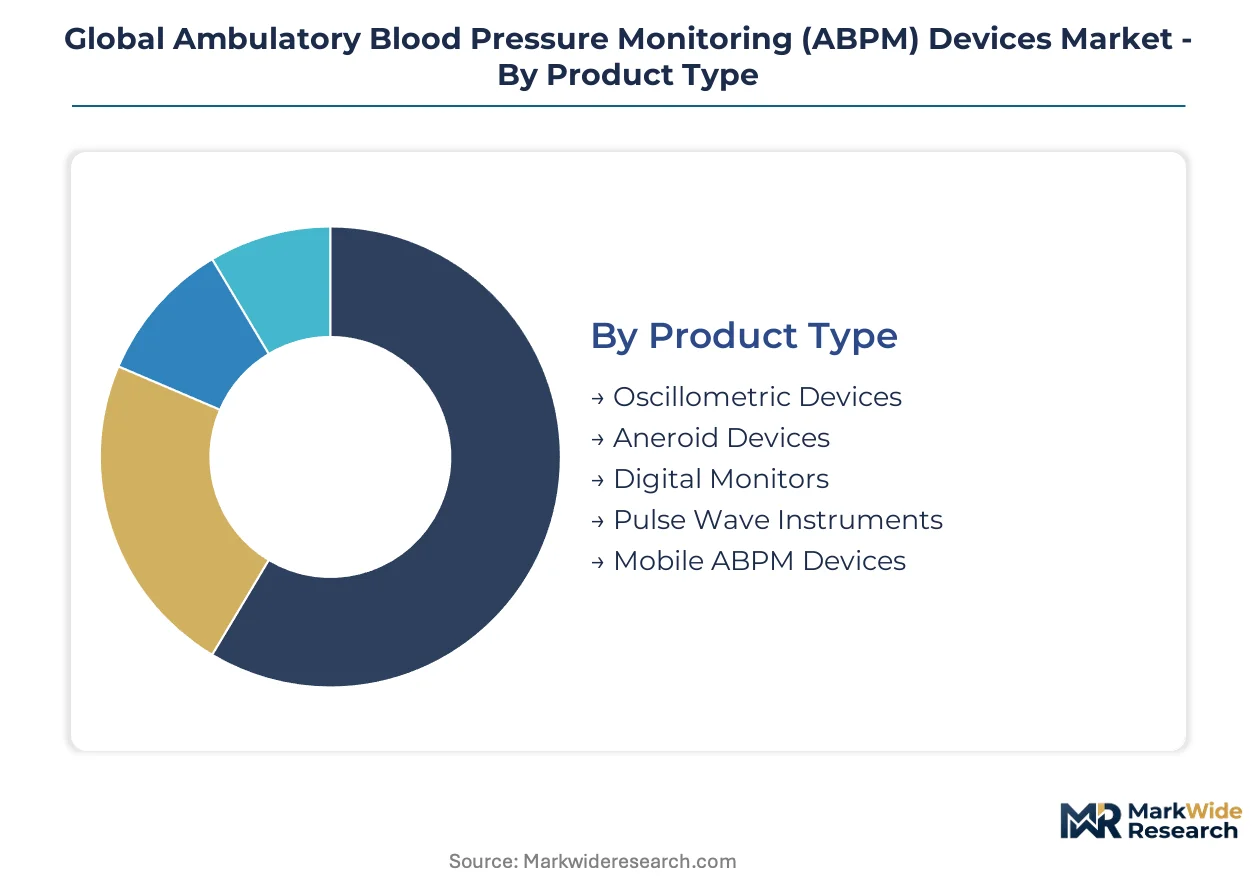
Segmentation in the ABPM devices market reveals how clinical validation requirements, reimbursement pathways, and patient mobility needs fragment demand across distinct hardware configurations and care delivery settings. Understanding these divides exposes where procurement budgets concentrate and where technology substitution threatens incumbent positions.
Product Type:
Oscillometric devices anchor the standardization end of the spectrum with automated cuff-based measurement protocols, while pulse wave instruments occupy the premium customization tier requiring specialized calibration for arterial stiffness assessment.
- Oscillometric Devices:Automated cuff-based systems detect arterial oscillations through MEMS pressure sensors to calculate systolic and diastolic values without stethoscope dependence. Cardiology clinics in Germany and Japan deploy these as default diagnostic tools where technician shortages limit auscultatory method feasibility.
- Mobile ABPM Devices:Bluetooth-enabled wearable units transmit encrypted readings to cloud telemetry platforms for real-time clinician review. Demand concentrates in United States Medicare Advantage networks where CMS remote patient monitoring reimbursement codes reward continuous data streaming over episodic clinic visits.
- Aneroid Devices:Manual cuff-and-gauge systems requiring trained auscultation persist in resource-constrained primary care settings.
- Digital Monitors:Consumer-facing fixed-position units with LCD displays serve home care patients outside reimbursed diagnostic channels.
- Pulse Wave Instruments:Advanced systems measuring pulse wave velocity for arterial stiffness quantification command premium pricing in specialized hypertension centers.
Most installed capacity flows through oscillometric devices. Expansion is steepest in mobile ABPM devices.
Application:
Volume concentrates in diagnostic applications where reimbursement certainty justifies capital expenditure, while preventive and comorbidity management applications carry higher margin but smaller addressable patient populations.
- Hypertension Diagnosis:Twenty-four to forty-eight hour ambulatory protocols differentiate masked hypertension from white-coat syndrome through circadian pattern analysis. Primary care centers in Japan's Osaka prefecture deploy ABPM as gatekeeping tools to reduce unnecessary cardiology referrals among elderly populations with variable clinic readings.
- Cardiovascular Risk Assessment:Integrated risk scoring algorithms combine ABPM data with laboratory biomarkers to stratify patients for aggressive intervention. German hospital systems embed these assessments within value-based care contracts that penalize avoidable myocardial infarction events.
- Sleep Apnea Monitoring:Nocturnal blood pressure dipping pattern analysis supplements polysomnography for obstructive sleep apnea screening.
- Renal Disease Management:ABPM guides antihypertensive therapy titration in chronic kidney disease patients where clinic measurements prove unreliable.
- Stroke Prevention:Ambulatory monitoring identifies blood pressure variability markers associated with cerebrovascular event risk.
- Stress Analysis:Workplace and laboratory stressor protocols measure pressor responses for research and occupational health applications.
Hypertension diagnosis captures the dominant share of procedure volume. Cardiovascular risk assessment is climbing the fastest as value-based contracts expand.
End User:
Institutional procurement dominates revenue concentration, though home care channels are eroding the hospital-centric deployment model as reimbursement shifts toward outpatient monitoring.
- Cardiology Clinics:Specialized hypertension centers maintain dedicated ABPM fleets with same-day fitting and next-day interpretation workflows. French cardiology networks under EU MDR jurisdiction now require validated clinical-grade systems with systematic post-market surveillance data collection.
- Home Care Patients:Direct-to-patient dispensing models bypass clinic infrastructure entirely, with patients returning devices via courier after monitoring completion. United States telehealth platform integrations enable this shift through automated data transmission and remote physician oversight.
- Primary Care Centers:Gatekeeper physicians initiate ABPM referrals before specialist escalation.
- Diagnostic Laboratories:Centralized testing facilities process high-volume ABPM studies for health system networks.
- Research Institutes:Academic medical centers deploy ABPM for clinical trial endpoints and epidemiological cohort studies.
Cardiology clinics retain the deepest installed base. Home care patients are gaining share fastest as remote patient monitoring reimbursement matures.
Deployment Mode:
Physical site-based deployment still dominates device utilization, though cloud-native architectures are collapsing the distinction between ambulatory clinic and remote patient monitoring categories.
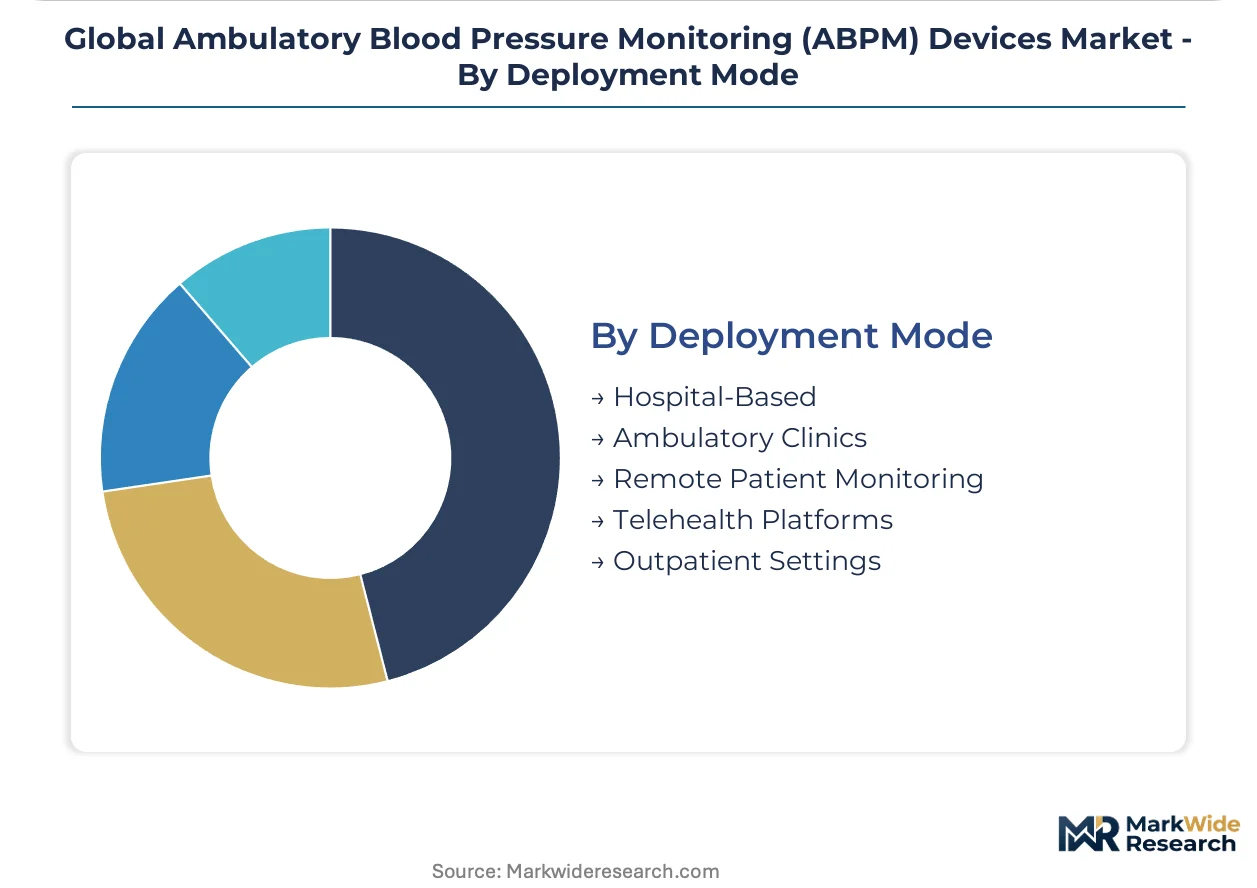
- Remote Patient Monitoring:Continuous data streaming to clinician dashboards replaces episodic clinic visits for chronic hypertension management. United States Medicare Advantage plans now treat ABPM-derived data as billable remote therapeutic monitoring, accelerating platform procurement decisions.
- Telehealth Platforms:Integrated software ecosystems combine device data with video consultation and EHR documentation within single vendor relationships. Epic and Cerner integration capabilities have become disqualifying criteria for health system RFPs.
- Hospital-Based:Inpatient telemetry units deploy ABPM for perioperative blood pressure management.
- Ambulatory Clinics:Same-day walk-in fitting services maintain high device turnover rates.
- Outpatient Settings:Mixed-use environments span primary care, occupational health, and community health center deployments.
Remote patient monitoring infrastructure is expanding most quickly. Telehealth platforms are capturing margin through SaaS pricing models that displace capital equipment sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ABPM device manufacturing traces its commercial lineage to Japanese and German precision instrumentation traditions of the 1970s, where oscillometric sensor miniaturization first enabled wearable 24-hour monitoring protocols. Contemporary demand clusters reflect these origins while expanding into telehealth-integrated markets.
United States
Medicare Advantage networks and CMS remote patient monitoring reimbursement codes are institutionalizing ABPM as billable telehealth infrastructure. FDA 510(k) clearance pathways enforce clinical validation thresholds that filter consumer-grade entrants. Device deployment concentrates in Medicare-saturated markets including Florida, Arizona, and Texas where elderly population density justifies ambulatory monitoring fleets.
Germany
Value-based care contracts penalizing avoidable cardiovascular events are embedding ABPM within enterprise hypertension management platforms. EU MDR Class IIa designation and notified body enforcement from TÜV Süd and BSI elevate procurement standards toward validated clinical-grade systems. The Rhine-Ruhr metropolitan corridor maintains the deepest installed base of oscillometric devices across European cardiology networks.
Japan
Metropolitan Tokyo and Osaka prefectures are driving PMDA-cleared device volumes as home-based hypertension management replaces frequent clinic visits for elderly populations. Japan's PMDA maintains distinct accuracy certification protocols that shape product development priorities for manufacturers targeting East Asian markets. Pulsed wave velocity assessment commands premium reimbursement in specialized hypertension centers concentrated in the Kanto region.
India
Ayushman Bharat health scheme penetration into tier-2 cities is creating first-time institutional demand for validated ABPM systems in cardiology clinics. CDSCO medical device registration requirements are tightening import quality standards while domestic manufacturing incentives accelerate local assembly. Maharashtra and Karnataka host the fastest-growing diagnostic infrastructure clusters where private hospital chains are standardizing oscillometric protocols.
United Kingdom
NHS England hypertension pathway reforms are mandating ambulatory confirmation before antihypertensive therapy initiation. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining UKCA marking timelines. London and Southeast England cardiology networks are piloting cloud-native ABPM platforms integrated with Epic EHR deployments.
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market Key Industry Players
Premium-margin players sit above commodity-margin players across the certification-grade divide, with clinical-validation depth determining pricing power. The vendor base stratifies into three tiers: integrated healthcare conglomerates with enterprise platform capabilities, specialized cardiovascular device manufacturers with regulatory expertise, and emerging telehealth-native entrants leveraging SaaS distribution models. Dominant competitive moves include strategic partnerships with EHR vendors for seamless data integration and geographic expansion through notified body certification stacking across FDA, EU MDR, and PMDA jurisdictions.
Within the integrated healthcare conglomerate tier, Omron Healthcare and GE Healthcare exemplify divergent channel strategies. Omron leverages its oscillometric sensor portfolio to dominate home care channels in Japan and Germany where direct-to-patient dispensing models bypass traditional distributor markups. GE Healthcare sustains hospital-based deployment through integrated telemetry platforms that anchor enterprise hypertension programs in United States health systems. Bosch & Sohn GmbH & Co. KG represents the specialized European manufacturer archetype, with its GmbH structure signaling family-owned precision instrumentation heritage concentrated in German-speaking clinical markets.
| Leading Market Players |
|---|
| Omron Healthcare |
| GE Healthcare |
| Schiller AG |
| Spacelabs Healthcare |
| Bosch & Sohn GmbH & Co. KG |
| SunTech Medical |
| Welch Allyn |
| Hill-Rom Holdings |
| Koninklijke Philips N.V. |
| Others |
Cost & Logistics Intelligence
Captive MEMS sensor production in Taiwan and Japan anchors pricing power for oscillometric device manufacturers, while outsourced cuff assembly in Southeast Asia compresses margins for second-tier entrants competing on standard ABPM units. This bifurcation separates premium pulse wave instrument vendors with in-house pressure sensor fabrication from commodity players exposed to foundry pricing volatility.
Pricing Analysis
Certification-grade pricing stratification separates FDA 510(k)-cleared systems from consumer-grade monitors, with reimbursement eligibility in Medicare Advantage networks commanding substantial premiums over direct-pay channels. Price differentiation rests on clinical validation depth and telehealth platform integration maturity, not hardware specifications alone. Cost compression in standard oscillometric tiers intensifies as cloud-native SaaS models displace capital equipment sales. Primary care centers in India exhibit acute price sensitivity, while German cardiology clinics prioritize validated accuracy over unit economics.
Supply Chain Analysis
Reverse-logistics networks for 48-hour ABPM device returns concentrate refurbishment capacity in Germany and the United States, where sanitized cuff replacement and firmware reloading extend unit lifecycles across multiple patient deployments. Component sourcing draws from Taiwanese MEMS foundries for pressure sensors, Japanese precision manufacturers for calibration modules, and Malaysian assembly plants for cuff fabrication. Single-source vulnerability in MEMS fabrication exposes lead-time volatility when foundry capacity tightens. Distribution runs through cardiology-focused medical device distributors in Europe and direct-to-clinic SaaS platforms in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ABPM devices hinges on software companion monetization and premium-tier shift toward arterial stiffness assessment protocols that command higher reimbursement per procedure.
For Market Incumbents: To counter telehealth-native entrants with cloud-first distribution, established manufacturers should deepen EHR integration partnerships with Epic and Cerner while adding pulse wave velocity capabilities to standard oscillometric platforms. Backward integration into MEMS sensor design reduces foundry dependency and protects gross margins against Taiwanese capacity constraints. For New Entrants and Emerging Players: Tier-2 Indian cardiology clinics under Ayushman Bharat expansion represent the most penetrable buyer archetype, with first-time institutional demand for validated systems outpacing established vendor coverage. A hardware-as-a-service model with per-monitoring-session pricing bypasses capital budget limitations while capturing utilization data for platform refinement. For Investors and Strategic Acquirers: Roll-up economics work for specialized cardiovascular device manufacturers with stacked regulatory certifications across FDA, EU MDR, and PMDA jurisdictions because hospital procurement consolidation favors single-vendor platform commitments over fragmented device sourcing. Targets with embedded software validation expertise and existing HL7 FHIR connectivity command scarcity premiums. Practitioners should monitor CMS reimbursement code expansions for remote therapeutic monitoring and EU MDR post-market surveillance enforcement stringency as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance pathway validates clinical-grade accuracy for Medicare reimbursement eligibility. |
| CE Marking Pathway | EU MDR Class IIa designation filters consumer-grade competitors from German hospital procurement. |
| Hospital System Partnership | Epic EHR integration anchors enterprise hypertension management platform selection. |
| Software Companion Development | Cloud-native SaaS models displace capital sales with recurring telemetry revenue streams. |
| Reimbursement Strategy | CMS remote patient monitoring coding institutionalizes ABPM as billable telehealth infrastructure. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory filings and procurement databases. Interviews with cardiology clinic directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers triangulated against FDA 510(k) filings, EU MDR notified body records, CMS reimbursement data, and PMDA certification databases. Bottom-up device shipment estimates and top-down healthcare expenditure allocations were reconciled to establish market sizing.
Rate-of-change decomposition across the projection horizon separates volume growth from pricing evolution and mix shift toward premium segments. The analytical framework models product type, application, end user, and deployment mode dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from procedure volume trajectories, reimbursement code expansion timelines, and telehealth platform adoption curves specific to hypertension management protocols.
Underlying measurement precision varies by segment; mobile ABPM and pulse wave instruments carry tighter precision than aneroid devices due to connected data validation. Forecasts reflect assumptions regarding CMS coding continuity, EU MDR enforcement consistency, and MEMS foundry capacity stability. Practitioners should monitor semiconductor supply constraints, cybersecurity guidance updates, and value-based care contract penetration for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Fetal and Neonatal Heart Monitor Market
Patient Monitoring
Heart Failure Monitoring Systems Market
Patient Monitoring
Remote Home Monitoring Systems Market
Patient Monitoring
Global Patient Monitoring Market
Patient Monitoring
Hemoglobin Monitor Market
Patient Monitoring
Asia-Pacific Patient Monitoring Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market
Patient Monitoring
Wrist Blood Pressure Monitors Market
Patient Monitoring
Digital Patient Monitoring Systems Market
Patient Monitoring
Blood Pressure Monitors Market
Patient Monitoring
Medical Telemetry Market
Patient Monitoring
Global Arrhythmia Monitoring Devices Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
Drowsiness Monitoring System Market