
 HIV Drugs Market | 2026-2036
HIV Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
HIV Drugs Market Intelligence
Sub-Saharan African procurement of generic antiretroviral supplies is shifting toward long-acting formulations and fixed-dose combinations. Gilead Sciences leverages its nucleoside reverse transcriptase inhibitor portfolio to sustain manufacturing scale across multiple continents. ViiV Healthcare anchors the integrase strand transfer inhibitor segment through concentrated R&D investment in pediatric and injectable delivery systems.
HIV drugs comprise pharmaceutical agents designed to suppress viral replication through interference with specific stages of the retroviral life cycle, typically formulated as small-molecule oral tablets or long-acting injectable suspensions requiring cold-chain distribution. These therapeutics serve the primary purpose of reducing viral load to undetectable levels, thereby preventing disease progression and transmission. Antiretroviral therapy dominates prescription volumes as the foundational regimen, while integrase strand transfer inhibitors represent the fastest-expanding drug class due to superior resistance profiles and tolerability. Pre-exposure prophylaxis application is gaining structural importance as prevention frameworks integrate pharmaceutical intervention with behavioral health programs.
FDA approval standards for bioequivalence and the WHO prequalification program govern market access for both originator and generic manufacturers, directly determining which formulations reach public procurement channels. EMA guidelines on pediatric investigation plans and the FDA's orphan drug incentives shape development priorities for underserved patient populations. Stakeholders must monitor evolving regulatory requirements for long-acting depot formulations and prepare for potential shifts in reimbursement criteria tied to treatment-as-prevention outcomes.
Market Dynamics
Long-acting injectable formulations are compressing dosing intervals from daily tablets to monthly or quarterly administration, fundamentally restructuring patient adherence programs and pharmaceutical supply chains toward cold-chain depot distribution networks.
Growth Catalysts
- FDA Accelerated Approval Pathways:Streamlined review timelines for antiretroviral therapies with novel mechanisms compress development cycles and reduce time-to-revenue for manufacturers targeting treatment-experienced patient populations.
- Pre-Exposure Prophylaxis Integration:Public health systems in high-burden regions are embedding pharmaceutical prevention into behavioral health frameworks, expanding addressable patient pools beyond treatment-naïve cohorts.
- Sub-Saharan Africa Procurement Scale:Government-backed treatment access programs command the largest patient volumes globally, creating predictable demand anchors for generic fixed-dose combination manufacturing.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthesis of integrase strand transfer inhibitors relies on specialized contract manufacturers concentrated in India and China, exposing supply continuity to geopolitical friction.
- Cold-Chain Distribution Costs:Long-acting injectable suspensions require continuous temperature-controlled logistics from manufacturing through point-of-care administration, elevating per-dose fulfillment expenses.
- WHO Prequalification Timelines:Stringent bioequivalence documentation requirements for generic manufacturers delay market entry into public procurement channels by 18-24 months versus originator approvals.
Strategic Opportunities
- Pediatric Formulation Gaps:EMA pediatric investigation plan incentives and FDA orphan drug designations create regulatory tailwinds for developers addressing weight-band-adjusted dosing in children under 12 years.
- Dual-Action Combination Therapies:Convergence of nucleoside reverse transcriptase inhibitors with integrase strand transfer inhibitors in single-tablet regimens is expanding into treatment-naïve adult segments seeking simplified adherence.
- Direct-to-Clinic Distribution Models:Hospital procurement systems in South Africa and Kenya are piloting vendor-managed inventory programs that bypass traditional wholesale intermediaries.
Industry Challenges
- Formulation Chemistry Expertise Scarcity:Long-acting depot development requires specialized pharmacokinetic modeling capabilities that remain concentrated within a limited pool of contract research organizations.
- Legacy Supply Chain Reconfiguration:Transitioning from oral tablet distribution to cold-chain injectable logistics demands capital redeployment into refrigerated warehousing and specialized last-mile transport fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HIV Drugs Market |
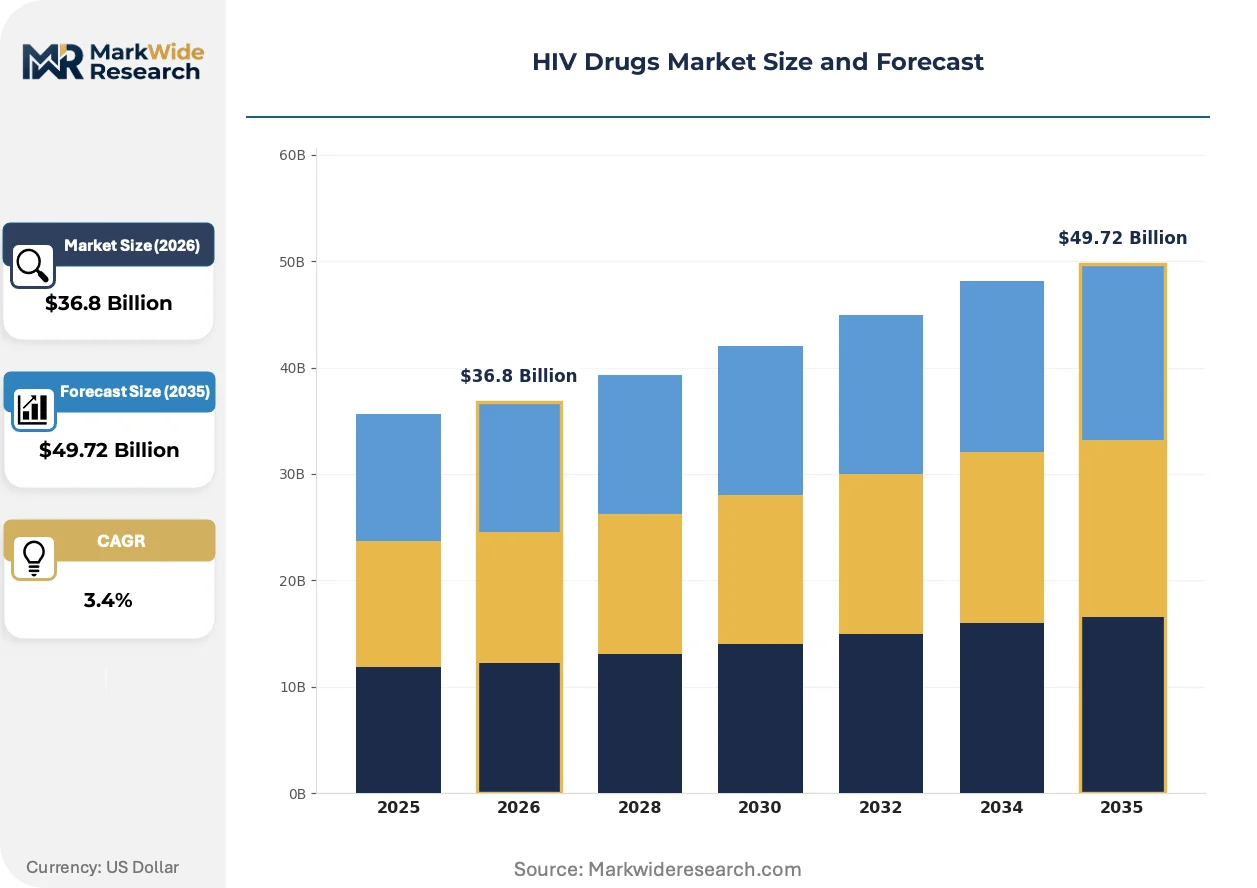
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $49.72 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Antiretroviral Therapy, Protease Inhibitors, Nucleoside Reverse Transcriptase Inhibitors, Non-Nucleoside Reverse Transcriptase Inhibitors, Integrase Strand Transfer Inhibitors Application: Pre-Exposure Prophylaxis, Post-Exposure Prophylaxis, Treatment of HIV-1 Infection, Treatment of HIV-2 Infection, Pediatric HIV Management Patient Type: Adults, Pediatric Patients, Pregnant Women, Geriatric Population, High-Risk Groups Distribution Channel: Hospitals, Specialty Pharmacies, Retail Pharmacies, Online Pharmacies, Community Health Centers |
| Companies Covered | Janssen Pharmaceuticals, GlaxoSmithKline, ViiV Healthcare, Boehringer Ingelheim International GmbH, AbbVie, Gilead Sciences, Bristol-Myers Squibb Company, F. Hoffmann-La Roche AG, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HIV Drugs Market Strategic Shifts & Innovations
Antiretroviral therapy development is pivoting toward extended-release delivery mechanisms that reduce dosing frequency while maintaining viral suppression thresholds, compressing the competitive window for daily oral regimens.
Long-acting cabotegravir-rilpivirine injectable suspensions are expanding into treatment-naïve adult populations previously restricted to oral induction protocols. HIV clinics in urban United States health systems are adopting these formulations at accelerating pace, driven by patient preference for reduced pharmacy visit frequency. This technology is expanding into viral suppression programs by enabling differentiated care models where stable patients receive quarterly rather than monthly clinical touchpoints.
EMA guidelines on pediatric investigation plans now mandate age-appropriate formulation development as a condition of market authorization for new molecular entities in the European Union. This regulatory pressure is reshaping pipeline prioritization toward dispersible tablets and palatable liquid alternatives for children weighing under 25 kilograms. The pediatric segment across EU member states is responding with accelerated enrollment in multinational clinical trials designed to satisfy both EMA and FDA evidentiary requirements simultaneously.
Public procurement authorities in high-burden countries are consolidating antiretroviral purchasing through centralized tenders that specify fixed-dose combination requirements and cold-chain compliance certifications. Hospital pharmacy directors in Nigeria and Uganda are displacing fragmented supplier relationships with single-source agreements tied to volume guarantees and performance-based logistics metrics. This consolidation is most visible in East African markets where national strategic plans explicitly target 95% viral suppression coverage through streamlined supply chains.
HIV Drugs Market Segmentation
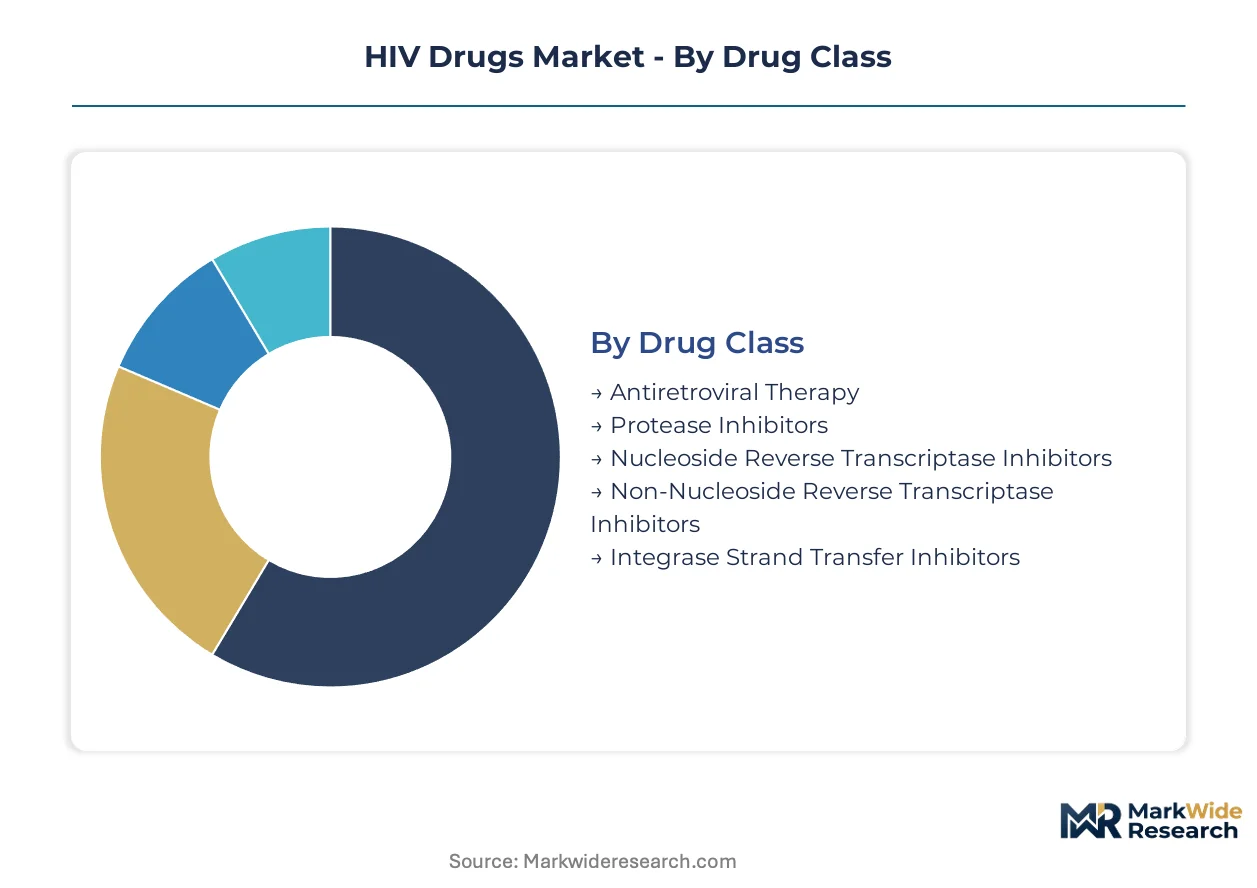
Segmentation in HIV therapeutics determines regulatory pathway complexity and procurement eligibility. Drug class selection dictates bioequivalence requirements, while application type shapes reimbursement frameworks across public health systems.
Drug Class:
FDA accelerated approval pathways and WHO prequalification programs apply differential stringency across molecular categories, with novel mechanisms receiving streamlined review and established classes facing abbreviated generic entry routes.
- Antiretroviral Therapy:Combination regimens suppressing viral replication through multi-target interference dominate prescription volumes. Hospital procurement in South Africa and Kenya anchors demand for fixed-dose combinations, driven by national viral suppression targets.
- Integrase Strand Transfer Inhibitors:Small-molecule inhibitors of viral DNA integration into host genomes achieve superior resistance profiles. Pediatric and injectable formulations from ViiV Healthcare are expanding into treatment-naïve segments seeking simplified adherence.
- Nucleoside Reverse Transcriptase Inhibitors:Backbone components of most first-line regimens manufactured at scale across multiple continents.
- Non-Nucleoside Reverse Transcriptase Inhibitors:Allosteric enzyme inhibitors with established generic competition in sub-Saharan procurement channels.
- Protease Inhibitors:Mature drug class concentrated in salvage therapy for treatment-experienced populations.
Antiretroviral Therapy sits at the top of the volume ranking, with Integrase Strand Transfer Inhibitors climbing the fastest.
Application:
Cost tiers separate acute intervention from chronic management, with prevention programs commanding premium pricing and treatment access programs operating on volume-discounted procurement.
- Treatment of HIV-1 Infection:Lifelong suppressive therapy for the predominant viral subtype. Public procurement in Nigeria and Uganda concentrates demand through centralized tenders with cold-chain compliance mandates.
- Pre-Exposure Prophylaxis:Pharmaceutical prevention for HIV-negative high-risk populations. Urban United States health systems are embedding tenofovir-based regimens into behavioral health frameworks, expanding addressable pools beyond traditional treatment cohorts.
- Pediatric HIV Management:Weight-band-adjusted dosing requirements trigger EMA pediatric investigation plan obligations.
- Post-Exposure Prophylaxis:Emergency 28-day regimens for occupational and non-occupational exposure events.
- Treatment of HIV-2 Infection:Limited commercial focus due to lower viral prevalence and natural resistance to certain drug classes.
Treatment of HIV-1 Infection captures the largest patient base, while Pre-Exposure Prophylaxis gains share fastest among prevention-oriented health systems.
Patient Type:
Supply concentration varies by population complexity, with adult formulations benefiting from manufacturing scale and specialized cohorts requiring dedicated formulation development.
- Adults:Standard-dose oral tablets and long-acting injectables serve the broadest population. FDA approval of monthly and quarterly cabotegravir-rilpivirine suspensions is restructuring adherence programs toward reduced pharmacy visit frequency.
- Pediatric Patients:Dispersible tablets and palatable liquids for children under 25 kilograms face EMA formulation mandates. Multinational trials across EU member states are accelerating enrollment to satisfy concurrent FDA evidentiary requirements.
- Pregnant Women:Teratogenicity screening and transplacental transfer studies impose additional regulatory burdens.
- Geriatric Population:Polypharmacy interactions and renal function adjustments complicate regimen selection.
- High-Risk Groups:Adherence support programs target populations with structural barriers to care engagement.
Adults dominate procurement volumes, with Pediatric Patients expanding most quickly under regulatory pressure for age-appropriate formulations.
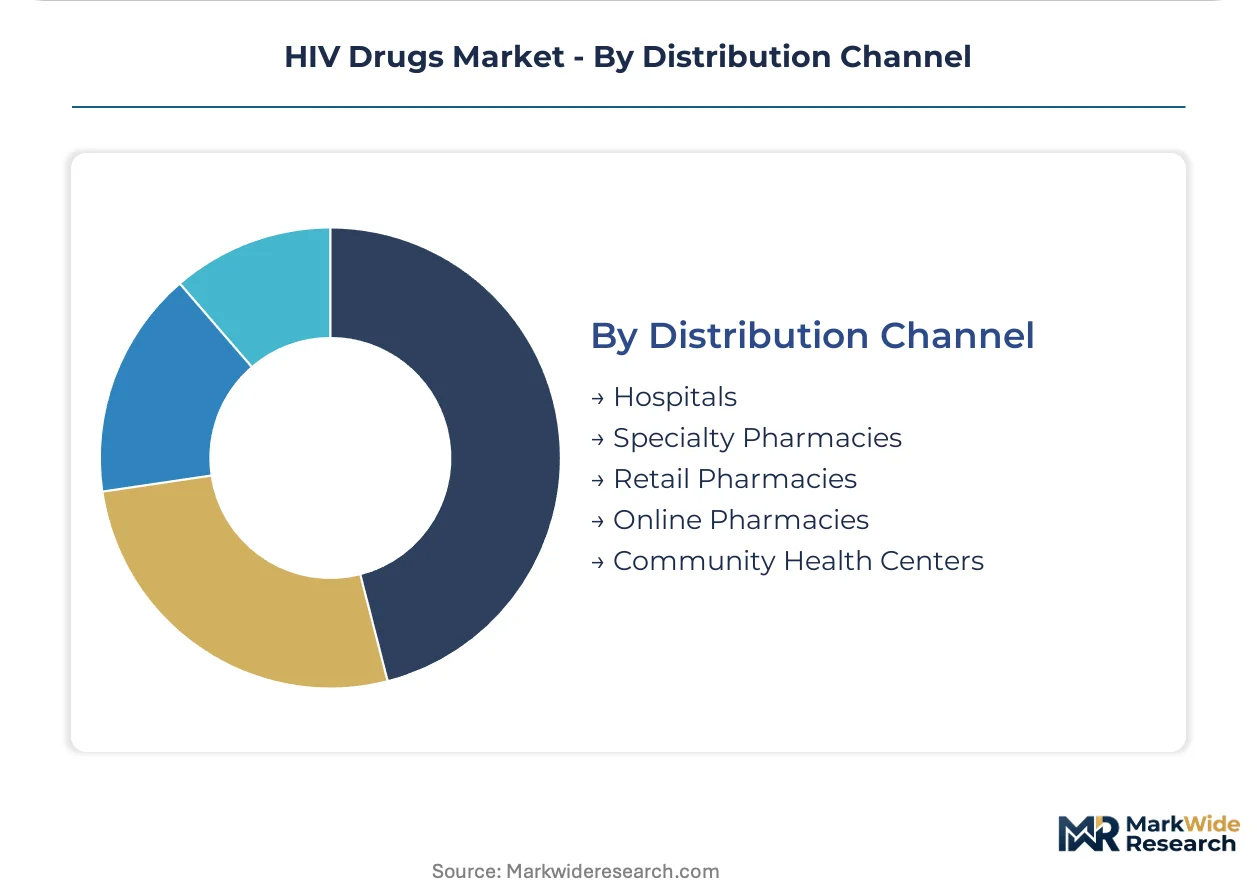
Distribution Channel:
Margin structures diverge by channel control, with direct hospital procurement capturing volume discounts and specialty pharmacies managing cold-chain injectable logistics.
- Hospitals:Institutional procurement of antiretroviral regimens anchors public health system viral suppression programs. Vendor-managed inventory pilots in South Africa and Kenya are displacing wholesale intermediaries.
- Community Health Centers:Point-of-care administration in high-burden regions links pharmaceutical distribution to differentiated care models. Quarterly clinical touchpoints for stable patients reduce system burden.
- Specialty Pharmacies:Cold-chain depot distribution networks for long-acting injectable suspensions.
- Retail Pharmacies:Fragmented dispensing for cash-pay and private insurance segments.
- Online Pharmacies:Emerging channel with limited penetration in regulated procurement environments.
Hospitals command the steepest procurement volumes, with Community Health Centers advancing fastest as differentiated care models expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa commands larger patient volumes than Brazil, yet both markets pivot toward long-acting injectable procurement as adherence programs restructure around reduced dosing frequency. National treatment access frameworks in high-burden countries are consolidating supplier relationships through centralized tenders with cold-chain compliance mandates.
United States
Urban health systems in New York and Los Angeles are accelerating adoption of cabotegravir-rilpivirine injectable suspensions for stable patients. FDA accelerated approval pathways compress development timelines for novel antiretroviral mechanisms. The Boston-Cambridge biotech corridor anchors clinical trial infrastructure for pediatric formulation development under EMA-FDA concurrent evidentiary requirements.
South Africa
Government-backed treatment access programs anchor the largest antiretroviral procurement volumes outside the United States. National Department of Health tenders specify fixed-dose combination requirements and vendor-managed inventory pilots. Gauteng and Western Cape provinces are displacing wholesale intermediaries with direct-to-clinic distribution models tied to viral suppression targets.
Kenya
Community health centers in Nairobi and Mombasa link pharmaceutical distribution to differentiated care models with quarterly clinical touchpoints. The country's national pharmaceutical regulator enforces WHO prequalification alignment for generic antiretroviral entry into public procurement. East African market concentration is visible in Kisumu, where hospital pharmacy directors consolidate supplier relationships through performance-based logistics agreements.
India
Contract manufacturers in Hyderabad and Ahmedabad supply active pharmaceutical ingredients for integrase strand transfer inhibitors to global formulation developers. CDSCO bioequivalence standards govern generic antiretroviral approvals for domestic and export markets. The Mumbai-Pune pharmaceutical belt concentrates formulation chemistry expertise for long-acting depot development.
Brazil
Federal procurement through the Ministry of Health's unified health system commands predictable demand for generic fixed-dose combinations. ANVISA streamlined review pathways for antiretroviral therapies with established safety profiles. São Paulo state anchors manufacturing scale for nucleoside reverse transcriptase inhibitors distributed across Latin American treatment access programs.
HIV Drugs Market Key Industry Players
United States-based developers anchor the novel mechanism tier; European specialists hold established portfolios. The vendor base concentrates around nucleoside reverse transcriptase inhibitor scale manufacturers and integrase strand transfer inhibitor innovators. Three archetypes dominate: originator pharmaceutical companies with FDA-approved long-acting formulations, generic manufacturers with WHO-prequalified supply chains, and contract research organizations with depot pharmacokinetic capabilities. Competitive moves center on strategic partnerships for cold-chain distribution and portfolio diversification into pediatric segments.
Within the originator tier, Gilead Sciences and ViiV Healthcare exemplify divergent scale strategies. Gilead occupies a position anchored in nucleoside reverse transcriptase inhibitor manufacturing across multiple continents. ViiV Healthcare sits within the integrase strand transfer inhibitor specialization, with GlaxoSmithKline representing the corporate structure underpinning its market presence.
| Leading Market Players |
|---|
| Janssen Pharmaceuticals |
| GlaxoSmithKline |
| ViiV Healthcare |
| Boehringer Ingelheim International GmbH |
| AbbVie |
| Gilead Sciences |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche AG |
| Merck & Co. |
| Others |
Cost & Logistics Intelligence
Specialized formulation chemists concentrated in the Mumbai-Pune pharmaceutical belt command wage premiums that compress margins on standard oral generics while sustaining spreads on long-acting depot products. Labor-cost differentials between Indian contract research organizations and Western originator labs translate directly into three-tier pricing structure across premium, standard, and economy levels for antiretroviral procurement.
Pricing Analysis
Capacity additions in India are reshaping price floors for nucleoside reverse transcriptase inhibitor backbones. Pricing stratifies across premium, standard, and economy tiers based on WHO prequalification status and cold-chain certification grade. Cost compression in the generic oral segment is intensifying because of tender consolidation in sub-Saharan Africa. Government procurement authorities in Nigeria and Uganda exhibit highest price sensitivity; originator long-acting formulations face least sensitivity among urban United States health systems.
Supply Chain Analysis
Domestic-content mandates in South Africa and Brazil are reshaping sourcing patterns for final formulation and packaging. Active pharmaceutical ingredient synthesis draws from India and China; specialized depot manufacturing rests on capabilities in the United States and Europe. Key inputs include integrase strand transfer inhibitor intermediates, long-acting suspension polymers, and cold-chain packaging materials. Single-source vulnerability concentrates in Chinese contract manufacturers for certain proprietary intermediates. Distribution runs through hospital procurement systems and vendor-managed inventory programs displacing wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Demand is pivoting toward premium long-acting injectable specifications that command sustained margin premiums over commoditized oral regimens.
For Market Incumbents: Deploy backward integration into active pharmaceutical ingredient production to secure supply continuity against geopolitical friction. Incumbents must lock in pediatric formulation capabilities ahead of EMA investigation plan deadlines. The threat of Indian generic manufacturers with WHO-prequalified supply chains eroding originator volume in sub-Saharan tenders demands defensive patent portfolio management. Channel control through direct-to-clinic distribution pilots in Kenya and South Africa preserves pricing power.
For New Entrants and Emerging Players: Long-acting depot pharmacokinetic modeling capabilities offer a technology-first wedge against established oral-focused competitors. White-space targets include weight-band-adjusted pediatric formulations for children under 25 kilograms and cold-chain logistics services for injectable suspensions. The most penetrable segment is community health center procurement in East African markets with performance-based logistics agreements. A go-to-market angle anchored in vendor-managed inventory partnerships bypasses entrenched wholesale relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among generic manufacturers with WHO-prequalified supply chains and limited long-acting formulation exposure. Long-term viability over the next decade hinges on regulatory navigation capabilities for depot product approvals and pediatric indication expansion. Acquisition targets should display backward integration into specialized intermediate synthesis or captive cold-chain distribution infrastructure. The signal to watch is FDA approval velocity for monthly versus quarterly injectable dosing intervals as a predictor of competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Development | EMA pediatric investigation plan compliance unlocks European market authorization for new molecular entities. |
| Long-Acting Injectable Scale-Up | FDA approval of cabotegravir-rilpivirine suspensions validates cold-chain manufacturing investments. |
| Backward Integration into API Synthesis | Indian contract manufacturers securing captive supply of integrase strand transfer inhibitor intermediates reduce tariff exposure. |
| WHO Prequalification Pathway | Generic manufacturers achieving WHO prequalification gain entry into centralized sub-Saharan procurement tenders. |
| Direct-to-Clinic Distribution Partnership | Vendor-managed inventory pilots in South Africa and Kenya displace wholesale intermediaries and improve viral suppression metrics. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down active pharmaceutical ingredient production tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers informed demand-side assumptions. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO prequalification databases. Cross-referencing manufacturer capacity disclosures against national tender awards enabled supply-side triangulation.
Input-output matrices mapped antiretroviral therapy volumes across drug class, application type, patient population, and regional regulatory cluster throughout the forecast period. CAGRs were derived from regression analysis of historical procurement data and projected treatment access program expansion. Industry-specific forecast inputs included national viral suppression targets, EMA pediatric investigation plan timelines, and cold-chain infrastructure investment trajectories.
The model holds under stable regulatory approval pathways and continued government funding for treatment access programs; deviation in WHO prequalification timelines or geopolitical disruption to Indian and Chinese API supply would shift volume and value projections. Forecasts reflect documented assumptions about patient enrollment rates and formulation substitution patterns. A small set of triggers—FDA accelerated approval decisions for novel mechanisms, EMA pediatric mandate enforcement, and sub-Saharan tender consolidation velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Bio-Identical Hormones Replacement Therapy Market
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Proteinuria Therapeutics Market
Biopharmaceuticals
Global Diagnostic Specialty Antibodies Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
A - Estradiol Market
Biopharmaceuticals
Recombinant Human Serum Albumin Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Human Insulin Drugs Market
Biopharmaceuticals
Oral Chemotherapy Market