
 Bio-Identical Hormones Replacement Therapy Market | 2026-2036
Bio-Identical Hormones Replacement Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Identical Hormones Replacement Therapy Market Analytics
Plant-derived estriol and estradiol from Mexican yam and soy precursors is decoupling bio-identical hormone production from traditional equine-derived conjugated estrogen economics. AbbVie Inc. leverages its established women's health infrastructure to sustain branded formulation presence across retail and specialty channels. TherapeuticsMD Inc. differentiates through its FDA-approved bio-identical progesterone capsule, occupying a narrow but defensible regulatory niche. SottoPelle Inc. controls the pellet implant segment through certified provider networks, navigating state-level compounding variations.
Bio-identical hormones replacement therapy comprises structurally identical replicas of endogenous human hormones—primarily estrone, estradiol, estriol, progesterone, and testosterone—synthesized from diosgenin through chemical conversion to achieve molecular equivalence with ovarian, adrenal, and testicular secretions. These compounds function to restore circulating hormone concentrations to physiologic premenopausal or youthful ranges, addressing vasomotor symptoms, genitourinary syndrome, and metabolic bone loss. The therapy area dimension shows menopause applications commanding the largest patient volume, while andropause testosterone replacement represents the fastest-expanding prescriber category as urology and anti-aging clinics broaden male patient protocols. Delivery mode segmentation reveals transdermal creams and gels capturing margin pools through cash-pay wellness channels, whereas oral pills sustain institutional reimbursement pathways.
The FDA exercises jurisdiction over commercial bio-identical products through its Center for Drug Evaluation and Research, while state boards of pharmacy govern compounding pharmacy operations under Section 503A of the Federal Food, Drug, and Cosmetic Act. USP <797> and <800> standards impose sterility and hazardous drug handling requirements that elevate facility compliance costs and consolidate production among accredited compounders. DEA scheduling controls for testosterone limit distribution channels and mandate prescriber registration, shaping market access for androgen therapies. Stakeholders must monitor state legislative movements toward restricted drug lists for compounded hormones and prepare for potential FDA harmonization of bio-identical product classification standards.
Market Dynamics
The FDA's Drug Quality and Security Act is fragmenting production capacity between 503B outsourcing facilities and traditional 503A compounding pharmacies, forcing manufacturers to duplicate quality systems and splitting margin pools across incompatible regulatory frameworks.
Growth Catalysts
- Aging Demographics:The US Census Bureau projects sustained expansion in the 45-64 female cohort, creating durable demand for menopause symptom management through prescriber-channel and direct-to-consumer wellness platforms.
- USP <797> Harmonization:Updated sterile compounding standards are accrediting specialized production facilities, enabling institutional purchasers to source bio-identical formulations through established GPO contracts.
- Plant-Derived Precursor Economics:Diosgenin extraction from Mexican yam and soy is decoupling active pharmaceutical ingredient sourcing from equine-derived supply chains, reducing batch-to-batch variability in estradiol and progesterone synthesis.
Market Restraints
- DEA Scheduling Controls:Testosterone's Schedule III classification mandates prescriber DEA registration and limits distribution to registered pharmacies, constricting patient access for andropause protocols outside specialized urology and anti-aging clinic networks.
- Input Concentration Risk:Diosgenin supply concentrates among Chinese and Indian fine chemical manufacturers, exposing formulation costs to raw material volatility and currency fluctuation in API procurement.
- Clinical Evidence Asymmetry:FDA-approved conjugated estrogen formulations retain superior randomized trial documentation for cardiovascular endpoints, compelling compounded bio-identical prescribers to navigate informed consent complexity.
Strategic Opportunities
- Pellet Implant Geography:State-level scope-of-practice variations in Texas, Arizona, and Florida permit certified provider networks to capture recurring insertion revenue through cash-pay wellness channels.
- Telehealth Integration:Remote prescriber platforms are expanding patient access beyond traditional endocrinology and gynecology practices, particularly in underserved rural counties lacking hormone therapy specialists.
- Anti-Aging Clinic Expansion:Functional medicine practices are incorporating bio-identical protocols into longevity-focused service bundles, creating cross-sell opportunities with peptide therapies and metabolic optimization programs.
Industry Challenges
- Compounding Pharmacy Inspection Backlogs:State board of pharmacy enforcement capacity constraints are delaying 503A facility recertification, creating production interruptions for regional compounders.
- Formulation Stability Expertise:Transdermal cream and gel compounding requires specialized pharmaceutical technology training in emulsion science and preservative selection, limiting workforce scalability.
- Insurance Reimbursement Fragmentation:Commercial payers apply inconsistent prior authorization criteria to compounded bio-identical products, forcing patient out-of-pocket payment and compressing pharmacy margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Identical Hormones Replacement Therapy Market |
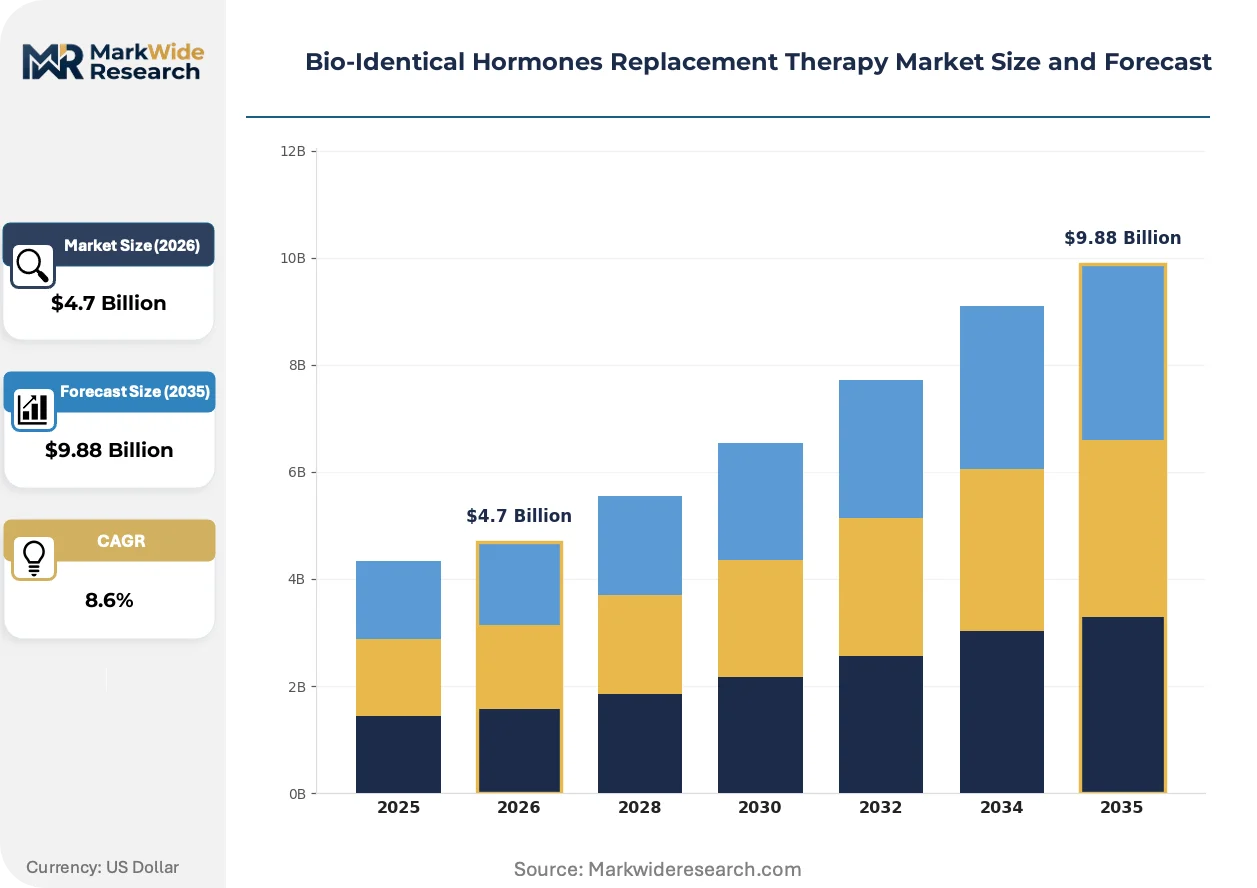
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pills, Creams, Injections, Gels Therapy Area: Menopause, Andropause, PMS, Hyperplasia Delivery Mode: Transdermal, Oral, Intramuscular, Subcutaneous End User: Clinics, Hospitals, Home Care, Specialty Pharmacies |
| Companies Covered | AbbVie Inc., Bayer AG, TherapeuticsMD Inc., Noven Pharmaceuticals Inc., Pfizer Inc., Merck KGaA, SottoPelle Inc., BIOTE MEDICAL, LLC., the biostation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Identical Hormones Replacement Therapy Market Evolving Landscape
Delivery technology maturation is compressing the historical divide between pharmaceutical-grade manufacturing and personalized compounding, enabling precision dosing while inviting heightened regulatory scrutiny of quality consistency claims.
Micronized progesterone encapsulation technology is converging with lipid-based absorption enhancement systems to improve oral bioavailability. Anti-aging and functional medicine clinics are adopting these formulations at accelerating rates for luteal phase support protocols. This convergence is compressing the efficacy gap between compounded capsules and FDA-approved alternatives, intensifying competitive pressure on branded manufacturers.
EMA's tightened pharmacovigilance requirements for hormone-containing medicines are extending batch record retention and adverse event reporting obligations to compounded distributors serving EU member states. Manufacturers must now maintain dual quality documentation systems to satisfy divergent FDA and EMA inspection standards. Specialty pharmacies with EU distribution ambitions are responding by segregating production lines and establishing separate legal entities for European market access.
Direct-to-consumer subscription models are displacing traditional prescription fulfillment through brick-and-mortar compounding pharmacies. Cash-pay patients in California, New York, and Illinois are migrating to vertically integrated telehealth platforms that combine remote consultation, laboratory monitoring, and home delivery. This channel shift concentrates patient data and purchasing behavior with platform operators, eroding independent pharmacy relationships and reordering competitive advantage toward digital patient acquisition capabilities.
Bio-Identical Hormones Replacement Therapy Market Segmentation
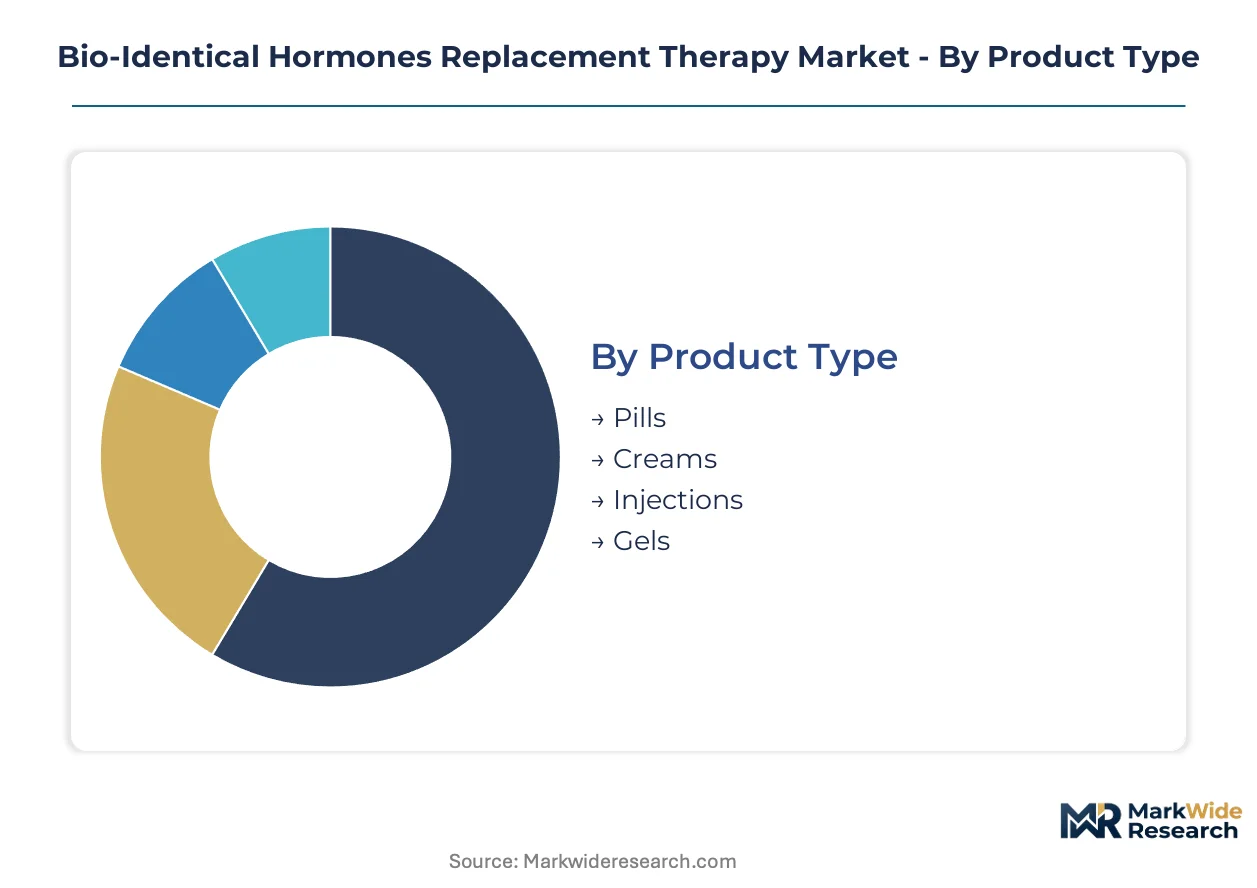
Bio-identical hormone therapy segments fracture along reimbursement pathways and prescriber channel control. Each dimension—product form, clinical indication, administration route, and care setting—carries distinct margin profiles and regulatory exposure that determine competitive positioning.
Product Type:
Cost tier separates insured institutional purchases from cash-pay wellness channel transactions.
- Pills:Oral micronized progesterone and estradiol tablets dominate institutional reimbursement through FDA-approved formulations. Hospitals and commercial payers favor this segment for standardized dosing and documented cardiovascular safety data, though compounding pharmacies capture residual demand for customized strength combinations.
- Creams:Transdermal estradiol and testosterone creams concentrate in direct-to-consumer wellness platforms and anti-aging clinic networks. Cash-pay patients in California, Texas, and Florida drive volume through subscription-based telehealth models that bypass traditional pharmacy distribution.
- Injections:Intramuscular testosterone cypionate and estradiol valerate serve urology and endocrinology practices with DEA-registered prescribers.
- Gels:Metered-dose testosterone and estradiol gels compete with creams for transdermal market share, particularly in employer-sponsored wellness programs.
Volume sits with Pills; growth tilts toward Creams.
Therapy Area:
Patient demographics and prescriber specialty concentration determine addressable market expansion rates.
- Menopause:Vasomotor symptom management in the 45-64 female cohort commands the largest patient population. Gynecology practices and telehealth platforms serving this segment benefit from standardized screening protocols and established hormone monitoring workflows.
- Andropause:Male testosterone replacement represents the steepest expansion trajectory as urology clinics and functional medicine practices broaden patient protocols beyond traditional hypogonadism diagnoses. DEA scheduling constraints limit pharmacy access but concentrate revenue in certified provider networks.
- PMS:Luteal phase progesterone supplementation serves a narrower patient base through reproductive endocrinology specialists.
- Hyperplasia:Endometrial protection protocols in estrogen therapy combinations address high-risk patient subsets within gynecologic oncology networks.
Menopause anchors current revenue; Andropause climbs the fastest.
Delivery Mode:
Patient compliance economics and prescriber training requirements stratify adoption across care settings.
- Transdermal:Creams, gels, and patches bypass hepatic first-pass metabolism, enabling lower effective doses with reduced thrombotic risk profiles. Wellness clinics in Arizona, Nevada, and Texas favor this mode for patient self-administration and reduced monitoring burden.
- Oral:Capsule and tablet formulations sustain institutional procurement through established GPO contracts and pharmacy benefit manager coverage. USP <797> compliance costs favor centralized manufacturing over local compounding for high-volume oral products.
- Intramuscular:Oil-based injections require clinical administration, concentrating utilization in hospital outpatient departments and urology clinics with nursing support.
- Subcutaneous:Pellet implants demand certified provider insertion training, creating geographic moats around SottoPelle and competing implant networks.
Oral commands institutional volume; Transdermal gains share fastest.
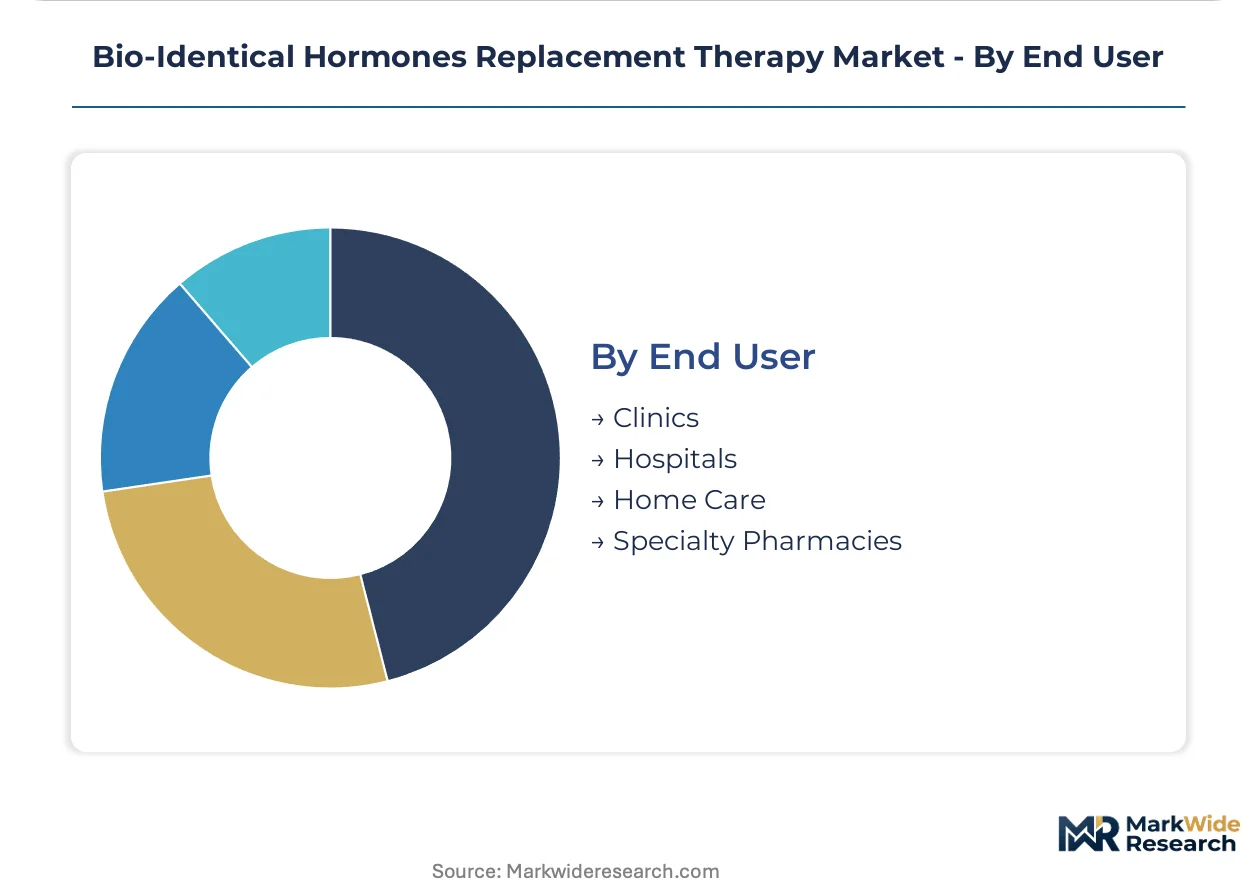
End User:
Channel control and patient data ownership determine margin capture and reorder economics.
- Clinics:Anti-aging and functional medicine practices bundle hormone protocols with metabolic optimization and peptide therapies. Cash-pay pricing and recurring consultation fees protect margins from pharmacy benefit manager compression.
- Hospitals:Academic medical centers and community hospital systems source FDA-approved formulations through 340B pricing and GPO contracts, prioritizing documented safety data over customization.
- Home Care:Self-administered transdermal and oral products serve patients in rural counties lacking specialist access, with telehealth platforms managing laboratory monitoring remotely.
- Specialty Pharmacies:503B outsourcing facilities and accredited 503A compounders navigate fragmented state regulations to serve prescriber-channel demand for personalized formulations.
Volume concentrates in Hospitals; margin expansion tilts toward Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient demand for bio-identical hormone therapy concentrates in the United States, where aging demographics and direct-to-consumer wellness channels intersect to drive prescription volume and cash-pay transactions.
United States
The 45-64 female cohort expansion and anti-aging clinic proliferation sustain market volume. FDA's Drug Quality and Security Act reshapes compounding oversight through 503A and 503B facility distinctions. Texas, Arizona, and Florida host certified pellet implant networks that capture recurring insertion revenue through cash-pay wellness channels.
Germany
Gynecology practice consolidation and EMA pharmacovigilance requirements elevate documentation standards for hormone-containing medicines. Germany's national pharmaceutical regulator enforces batch record retention obligations that extend to compounded distributors. Bavaria's medical technology cluster supports precision dosing device development for transdermal delivery systems.
United Kingdom
Telehealth platform expansion and NHS reimbursement pathway fragmentation create parallel markets for institutional and private-pay hormone therapy. The Medicines and Healthcare products Regulatory Agency governs commercial bio-identical products while pharmacy compounding falls under General Pharmaceutical Council jurisdiction. London's functional medicine practices bundle bio-identical protocols with metabolic optimization services.
Canada
Provincial formulary variations and Health Canada oversight of commercial hormone products segment market access across Ontario, Quebec, and British Columbia. The Special Access Program permits practitioner-requested compounded formulations outside standard approval pathways. Toronto's specialty pharmacy networks serve cross-border demand from US patients seeking price differentials on pellet implant procedures.
Australia
Private health insurance coverage gaps for compounded hormones concentrate demand in cash-pay wellness channels along the eastern seaboard. The Therapeutic Goods Administration classifies bio-identical products as prescription medicines requiring registered prescriber authorization. Sydney and Melbourne anti-aging clinics adopt subcutaneous pellet protocols following US training certification models.
Bio-Identical Hormones Replacement Therapy Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers navigate fragmented regulatory frameworks across FDA-approved and compounded product categories. The vendor base stratifies between multinational pharmaceutical conglomerates with women's health infrastructure, specialized pellet implant networks with certified provider systems, and regional compounding pharmacies serving personalized formulation demand. Three strategic archetypes emerge: branded formulation defenders leveraging established distribution, implant segment specialists controlling geographic provider networks, and telehealth-integrated platforms capturing direct-to-consumer subscription economics. Capacity expansion and strategic partnerships represent the dominant competitive moves, with manufacturers duplicating quality systems to serve both 503A pharmacy and 503B outsourcing facility channels.
Within the branded formulation tier, AbbVie Inc. and Bayer AG occupy positions sustained through retail and specialty channel presence. Among implant segment specialists, SottoPelle Inc. exemplifies the certified provider network model. TherapeuticsMD Inc. represents the narrow regulatory niche strategy through FDA-approved bio-identical progesterone positioning. These three anchors illustrate divergent responses to the tension between pharmaceutical-grade manufacturing standards and personalized compounding demand.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Bayer AG |
| TherapeuticsMD Inc. |
| Noven Pharmaceuticals Inc. |
| Pfizer Inc. |
| Merck KGaA |
| SottoPelle Inc. |
| BIOTE MEDICAL, LLC. |
| the biostation |
| Others |
Value Network & Pricing Analysis
Diosgenin spot pricing from Chinese and Indian fine chemical manufacturers cascades through bio-identical hormone production into three distinct pricing tiers: FDA-approved branded formulations commanding institutional premiums, 503B outsourcing facility products serving mid-market GPO contracts, and 503A compounded formulations competing on cash-pay wellness channels.
Pricing Analysis
Volume concentrates in oral pills sustaining institutional reimbursement, while margins concentrate in transdermal creams and gels capturing cash-pay wellness channel premiums. Price differentiation rests on USP <797> certification status and DEA registration tier, with accredited 503B facilities extracting 15-25% premiums over unaccredited 503A compounders. Cost compression in the compounded tier intensifies as telehealth platforms consolidate patient volume and squeeze pharmacy margins through direct sourcing negotiations. Cash-pay patients in California and Texas exhibit highest price sensitivity, whereas anti-aging clinic networks in Arizona and Florida demonstrate lowest sensitivity due to bundled service pricing.
Supply Chain Analysis
Workforce availability constraints in Shanghai, Hyderabad, and Basel limit specialized pharmaceutical technology training for emulsion science and preservative selection, capping scalable production of transdermal formulations. Active pharmaceutical ingredient sourcing draws from Chinese and Indian diosgenin extraction facilities, with Mexican yam and soy precursor processing concentrated in Guadalajara and Mumbai. Single-source vulnerability in Chinese fine chemical manufacturing exposes formulation costs to raw material volatility. Distribution runs through specialty pharmacy networks, 503B outsourcing facilities, and vertically integrated telehealth platforms serving direct-to-consumer subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bio-identical hormone therapy market sits in a technology-transition phase as plant-derived diosgenin extraction replaces equine-derived conjugated estrogen economics, decoupling production from traditional supply chains and reshaping competitive positioning across formulation tiers.
For Market Incumbents: Extend FDA-approved product lines into micronized progesterone encapsulation with lipid-based absorption enhancement, matching compounded formulation bioavailability while retaining regulatory documentation advantages. Deepen backward integration into Mexican yam and soy precursor sourcing to secure diosgenin supply against Chinese and Indian concentration risk. Invest in USP <800> hazardous drug handling certification to capture institutional GPO contracts as compliance costs consolidate production among accredited compounders. For New Entrants and Emerging Players: Begin with telehealth-integrated subscription models in Texas, Arizona, and Florida, where state-level scope-of-practice variations permit certified pellet implant networks to capture recurring insertion revenue. Target cash-pay andropause protocols in underserved rural counties lacking urology specialist access, leveraging remote prescriber platforms to bypass DEA scheduling constraints on traditional pharmacy distribution. Establish partnerships with functional medicine practices bundling hormone protocols with metabolic optimization services. For Investors and Strategic Acquirers: Distressed-cycle entries favor 503B outsourcing facilities with dual FDA-EMA quality documentation systems in the United States and Germany, positioned to serve institutional purchasers through established GPO contracts as state board of pharmacy inspection backlogs delay 503A facility recertification. Monitor state legislative movements toward restricted drug lists for compounded hormones as the inflection indicator for regulatory harmonization timing and FDA classification standard consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| USP <797> and <800> Certification Investment | Accreditation enables institutional GPO contract access and consolidates production among compliant compounders. |
| Telehealth Platform Integration | Remote prescriber networks expand patient access beyond traditional endocrinology and gynecology practice footprints. |
| Diosgenin Supply Agreement | Backward integration into Mexican yam and soy precursors reduces exposure to Chinese and Indian API concentration. |
| Pellet Implant Provider Network Expansion | Certified insertion training creates geographic moats around recurring revenue in cash-pay wellness channels. |
| Dual FDA-EMA Quality System | Segregated production lines satisfy divergent inspection standards for European market access. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with compounding pharmacy directors, 503B facility quality officers, gynecology practice administrators, anti-aging clinic operators, and state board of pharmacy enforcement staff. FDA 483 inspection observations, DEA controlled substance distribution reports, and USP <797>/<800> accreditation databases provided secondary validation. Bottom-up prescription volume estimates from specialty pharmacy dispensing data reconciled with top-down market sizing from hormone API import records.
Data-stream reconciliation across patient demographic projections, prescriber channel expansion rates, and regulatory enforcement capacity constraints shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product form, therapy area, delivery mode, and end-user channel, with CAGRs derived from patient cohort expansion rates and prescriber protocol adoption curves. Forecast inputs incorporated US Census Bureau demographic projections, state-level scope-of-practice legislative tracking, and telehealth platform patient acquisition cost trends.
State legislative shifts toward restricted drug lists for compounded hormones, FDA harmonization actions on bio-identical product classification, and DEA scheduling modifications for testosterone are the dominant revision risks. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Cancer Drug Market
Biopharmaceuticals
Lupus Nephritis Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
Spain Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
Global Biopharma Buffer Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
Human Combinatorial Antibody Libraries (Hucal) Market
Biopharmaceuticals
Isocitrate Dehydrogenase (IDH) Inhibitors Market
Biopharmaceuticals
Recombinant Therapeutic Antibodies and Proteins Market
Biopharmaceuticals
Antibody Production Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Vaccine Production Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
Global Biologics Market
Biopharmaceuticals
Biopharmaceuticals Packaging Market