
 Nucleic Acid Based Therapeutics Market | 2026-2036
Nucleic Acid Based Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Nucleic Acid Based Therapeutics Market Intelligence
Multi-source supply of critical lipid components is consolidating around a handful of qualified manufacturers. Biogen anchors its position through backward integration into antisense oligonucleotide manufacturing. BioNTech leverages its mRNA platform expertise to sustain leadership across oncology and infectious disease pipelines. Ionis Pharmaceuticals specializes in antisense chemistry, occupying a defensible niche in rare genetic disorders.
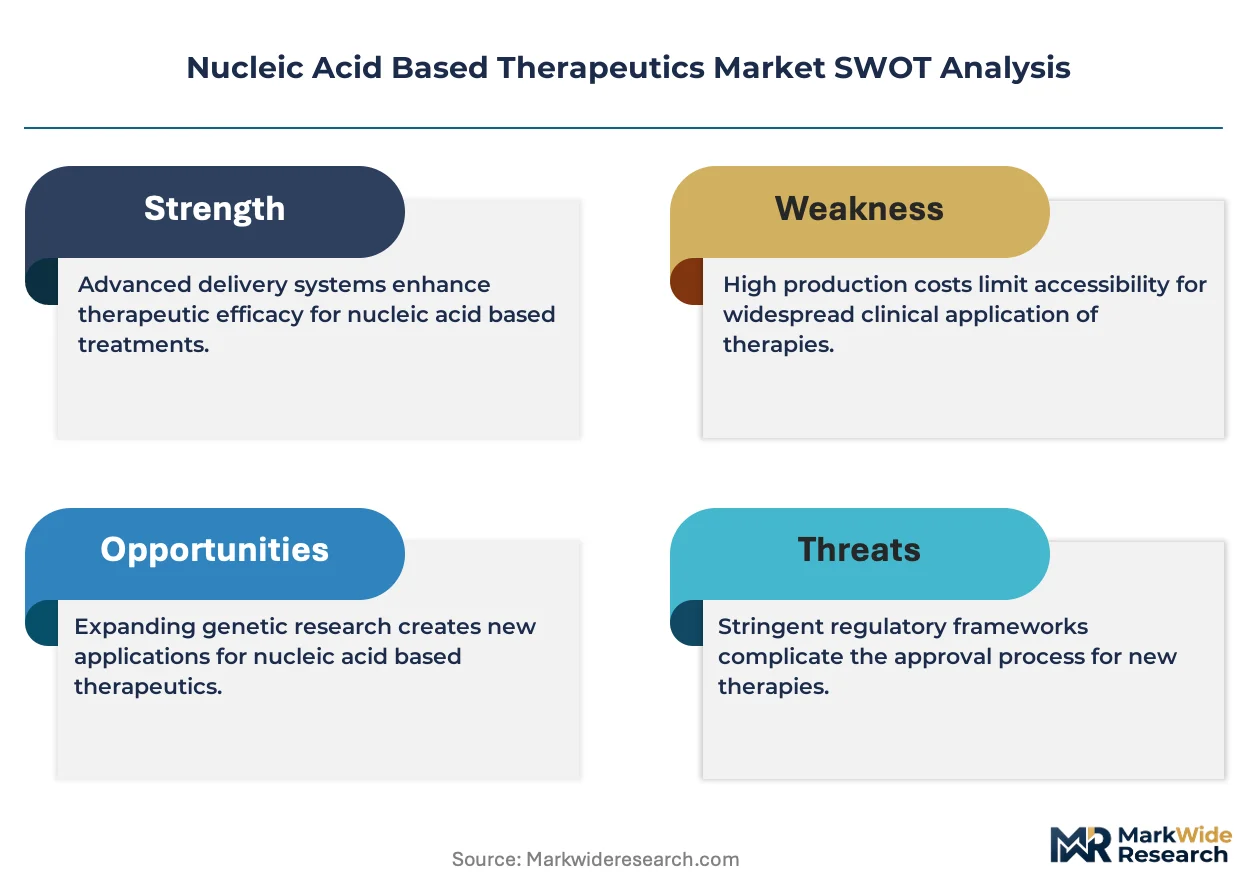
Nucleic acid based therapeutics comprise synthetic or engineered DNA and RNA molecules designed to modulate gene expression, protein synthesis, or cellular signaling through Watson-Crick base pairing and translational machinery engagement; these modalities require stabilization chemistries such as phosphorothioate backbones or 2'-O-methylation to resist nuclease degradation in vivo. Their primary commercial purpose centers on addressing previously undruggable targets in genetic, oncologic, and infectious disease indications where small molecules and biologics fail. The mRNA segment leads current revenue contribution through infectious disease vaccines and expanding oncology pipelines, while siRNA demonstrates the fastest structural growth trajectory driven by Alnylam's validated delivery platforms and new market entries. Lipid nanoparticle delivery dominates manufacturing investment, though viral vectors retain entrenched positions in gene replacement applications with higher regulatory familiarity.
FDA's Center for Biologics Evaluation and Research and EMA's Committee for Medicinal Products for Human Use enforce divergent chemistry, manufacturing, and controls standards that shape clinical trial design and commercial access timelines for nucleic acid drug sponsors. ISO 13485 and ICH Q5A guidelines further govern vector production and contamination control, raising barriers for contract manufacturers seeking multi-regional qualification. Stakeholders must monitor how FDA's emerging gene therapy guidance and the EU's ATMP framework revisions will reshape comparator requirements and post-market surveillance obligations.
Market Dynamics
Multi-source supply of critical lipid components is consolidating around a handful of qualified manufacturers, concentrating negotiating power upstream and forcing drug sponsors into long-term offtake agreements to secure manufacturing slots.
Growth Catalysts
- FDA Accelerated Approval Pathways:Compressed development timelines for gene therapies reduce capital-at-risk periods and attract venture funding into early-stage platforms.
- NIH Translational Research Funding:The National Institutes of Health directs substantial grant capital toward nucleic acid mechanism studies, de-risking preclinical work for emerging modalities.
- Lipid Nanoparticle Manufacturing Scale-Up:Contract manufacturers in the United States and Germany are expanding cleanroom capacity specifically for mRNA formulation, enabling commercial supply for oncology pipelines.
Market Restraints
- Critical Input Concentration:Ionizable lipid supply chains cluster among three qualified suppliers, creating single-source vulnerability for mid-cap drug developers.
- Cold Chain Infrastructure Requirements:Ultra-low temperature storage and distribution networks impose capital burdens that exclude smaller hospital systems from administering certain therapies.
- EMA-FDA Regulatory Divergence:Chemistry, manufacturing, and controls standards differ between the European Medicines Agency and FDA, forcing redundant qualification studies for multi-regional sponsors.
Strategic Opportunities
- Japan Rare Disease Incentives:PMDA's Sakigake designation and reimbursement premiums for nucleic acid therapies targeting ultrarare indications create favorable entry economics.
- Self-Amplifying RNA Platforms:Convergence of replicon technology with conventional mRNA manufacturing infrastructure enables dose-sparing formulations for cost-sensitive infectious disease applications.
- Direct-to-Patient Distribution Models:Specialty pharmacy channels are piloting temperature-controlled home delivery for chronic administration of antisense oligonucleotides.
Industry Challenges
- Nucleic Acid Chemist Talent Scarcity:Phosphorothioate synthesis and analytical method development expertise concentrates among veterans of legacy antisense programs, constraining team-building for new entrants.
- ISO 13485 Certification Timelines:Vector production facilities face 18-24 month qualification periods under international quality management standards, delaying clinical supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nucleic Acid Based Therapeutics Market |
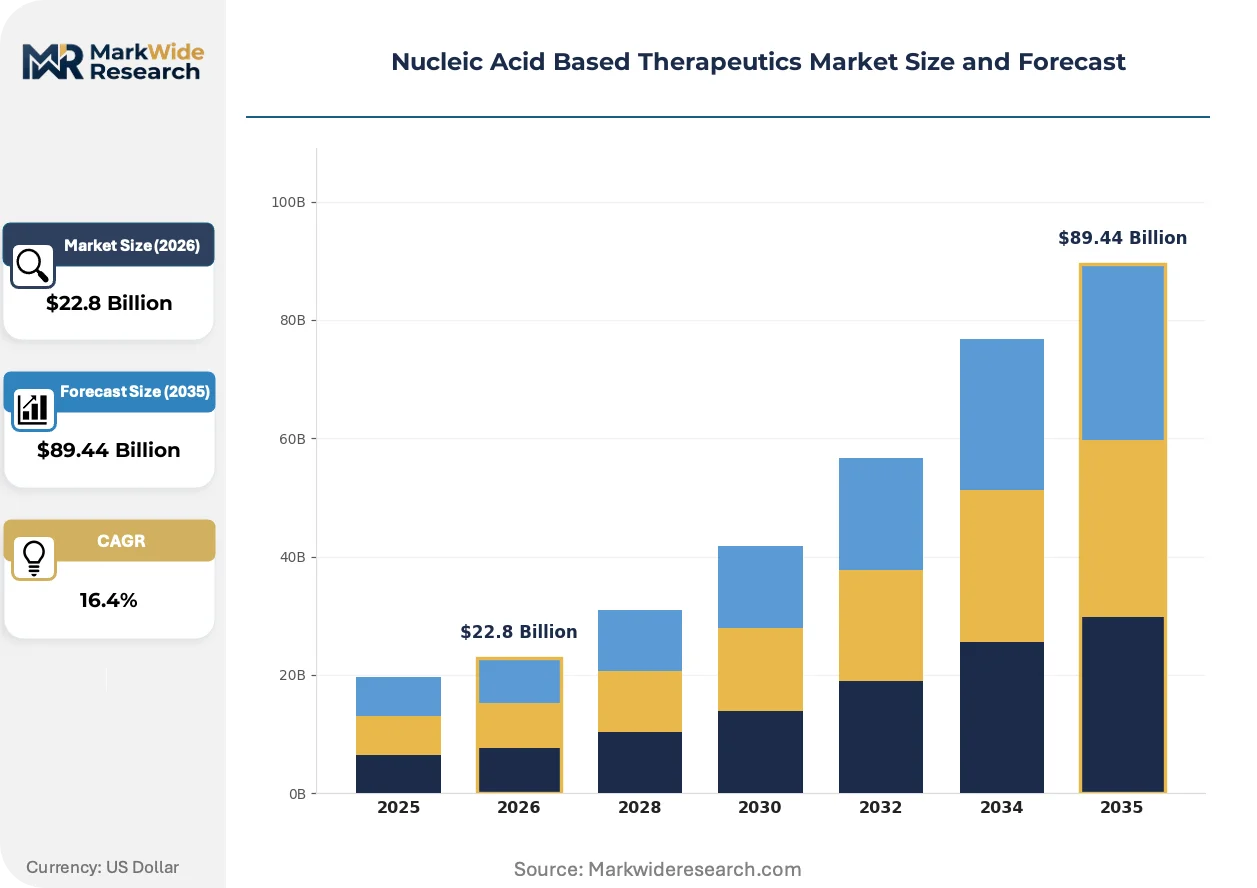
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $89.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: mRNA, siRNA, DNA, Antisense Oligonucleotides Delivery Method: Lipid Nanoparticles, Viral Vectors, Electroporation, Microinjection Therapeutic Area: Oncology, Infectious Diseases, Genetic Disorders, Cardiovascular End User: Pharmaceutical Companies, Contract Research Organizations, Academic Research Institutions, Hospitals |
| Companies Covered | Biogen, BioNTech, Ionis Pharmaceuticals, Arrowhead Pharmaceuticals, Moderna, Alnylam Pharmaceuticals, Novartis, CureVac, Sarepta Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nucleic Acid Based Therapeutics Market Strategic Shifts & Innovations
Platform standardization is compressing development timelines while regulatory convergence efforts are reshaping competitive positioning across the nucleic acid therapeutic landscape.
Circular RNA constructs are overtaking linear mRNA in next-generation vaccine design due to intrinsic stability against exonuclease degradation. Biotechnology sponsors in oncology and infectious disease are advancing circular RNA candidates through preclinical stages at accelerated pace. This structural innovation is overtaking conventional mRNA in durability-sensitive applications, extending dosing intervals and reducing cold chain burden.
EMA's Advanced Therapy Medicinal Products framework revisions are tightening post-authorization safety surveillance requirements for gene therapies. Sponsors must now commit to 15-year follow-up registries, increasing post-market cost structures. European oncology programs are responding by integrating real-world evidence collection into clinical trial protocols to satisfy both pre-approval and post-market obligations simultaneously.
Hospital procurement departments are consolidating nucleic acid therapeutic purchasing through centralized specialty pharmacy contracts. Academic medical centers in the United States are displacing decentralized buying with system-wide formulary committees that negotiate exclusive distribution agreements. This concentration is most visible in CAR-T and gene therapy categories, where treatment center certification requirements already limit eligible sites.
Nucleic Acid Based Therapeutics Market Segmentation
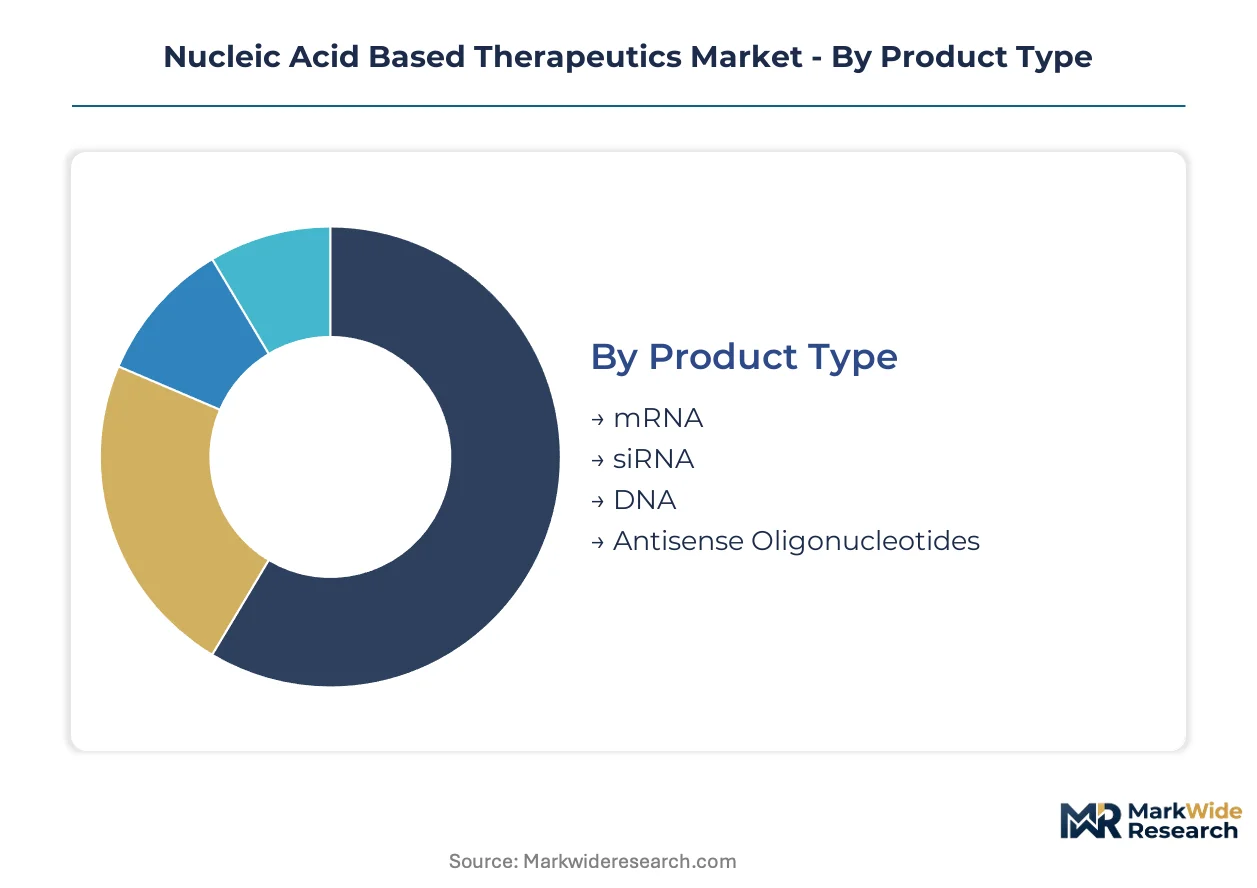
Nucleic acid therapeutics demand heterogeneous manufacturing capabilities, formulation expertise, and regulatory strategies across modalities. Segmentation reveals where capital deployment concentrates and which technology platforms command premium valuation multiples.
Product Type:
Ionizable lipid supply chains cluster among three qualified manufacturers, forcing drug sponsors into long-term offtake agreements that favor established modalities with predictable demand profiles.
- mRNA:Synthetic transcripts encoding therapeutic proteins or antigens require N1-methylpseudouridine substitution and codon optimization for translational efficiency. Demand concentrates in infectious disease vaccines and personalized cancer vaccines at major academic medical centers in the United States, driven by FDA's accelerated approval pathways compressing development timelines.
- siRNA:Small interfering RNA molecules exploit the RNA interference pathway for post-transcriptional gene silencing through RISC-mediated cleavage. Alnylam's validated GalNAc conjugate platforms anchor demand in hereditary ATTR amyloidosis and primary hyperoxaluria at tertiary care centers, with new market entries expanding the addressable patient population.
- DNA:Plasmid constructs enable sustained antigen expression for therapeutic vaccination and gene replacement through episomal persistence or chromosomal integration.
- Antisense Oligonucleotides:Phosphorothioate-modified single-stranded DNA analogs modulate splicing or induce RNase H-mediated target degradation.
Today's leader: mRNA. Tomorrow's challenger: siRNA.
Delivery Method:
Cost tiers separate platform technologies by manufacturing complexity and regulatory qualification burden, with lipid nanoparticle production commanding capital premiums against viral vector alternatives.
- Lipid Nanoparticles:Ionizable cationic lipids complexed with nucleic acid cargo through microfluidic mixing achieve endosomal escape and cytoplasmic release. Contract manufacturers in the United States and Germany are expanding cleanroom capacity specifically for mRNA formulation, enabling commercial supply for oncology pipelines.
- Viral Vectors:Engineered adeno-associated viruses and lentiviruses deliver genetic payloads with high transduction efficiency and established regulatory familiarity. AAV serotype selection and empty capsid removal dominate manufacturing investment at gene therapy-focused CDMOs.
- Electroporation:Pulsed electrical fields transiently permeabilize cell membranes for naked nucleic acid entry, applied in ex vivo cell engineering workflows.
- Microinjection:Direct physical delivery into oocytes or embryos retains specialized application in reproductive medicine and transgenic model generation.
Platform maturity favors lipid nanoparticles for mRNA; viral vectors retain entrenched positions in gene replacement applications with higher regulatory familiarity.
Therapeutic Area:
Application focus determines reimbursement pathways and prescriber specialization requirements, with oncology commanding the highest per-patient economics and genetic disorders securing orphan premium pricing.
- Oncology:Personalized neoantigen vaccines and tumor suppressor gene replacement target checkpoint-resistant malignancies. Hospital procurement departments are consolidating purchasing through centralized specialty pharmacy contracts at academic medical centers in the United States.
- Infectious Diseases:Prophylactic vaccines against respiratory pathogens leverage mRNA speed-to-clinic advantages established during pandemic response.
- Genetic Disorders:Single-gene replacement and exon-skipping strategies address previously undruggable rare disease targets where small molecules fail.
- Cardiovascular:Angiogenic growth factor expression and PCSK9-targeting siRNA emerge in ischemic heart disease and familial hypercholesterolemia.
Oncology captures current revenue concentration; genetic disorders demonstrate the steepest expansion trajectory driven by regulatory incentives for ultrarare indications.
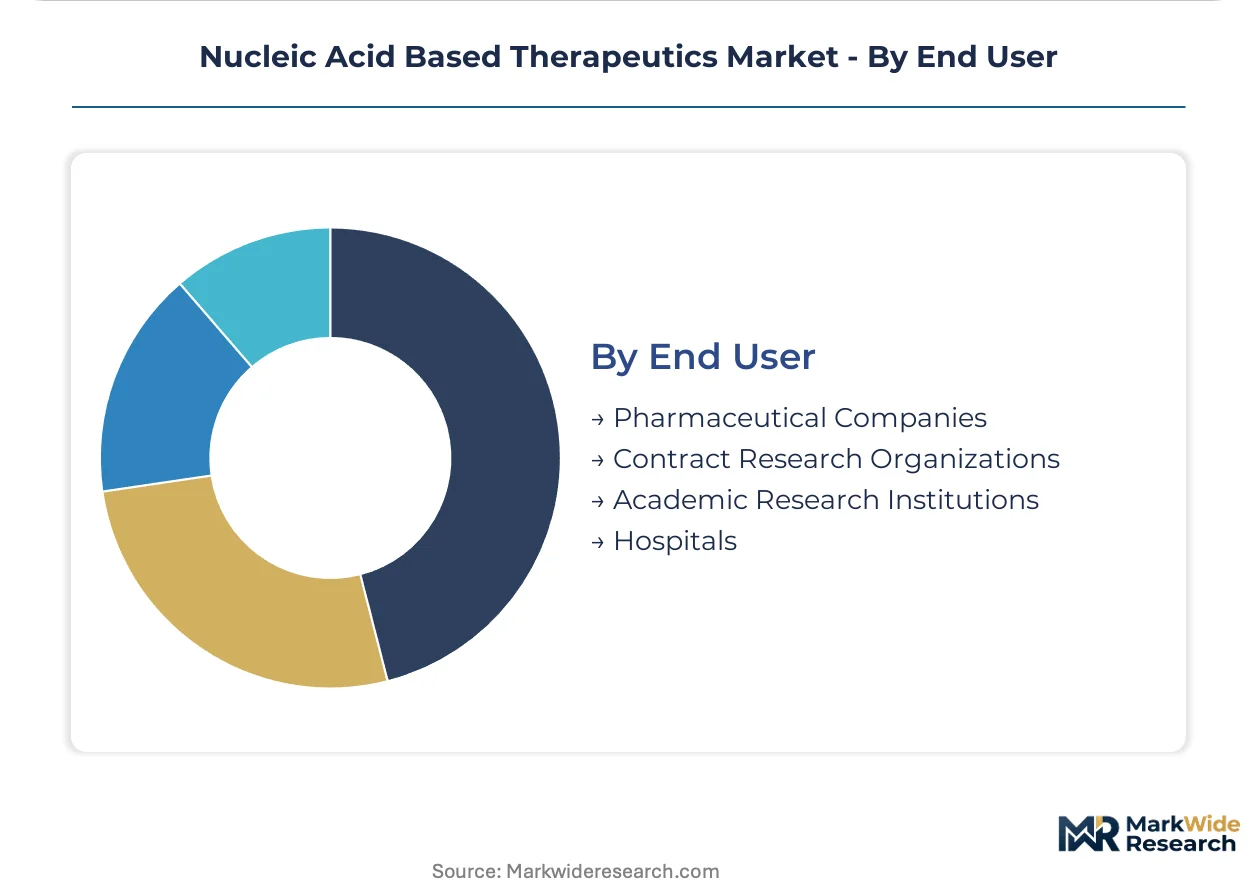
End User:
Customer type dictates contract structure complexity, with pharmaceutical companies demanding integrated CMC services and academic institutions prioritizing grant-funded access to exploratory platforms.
- Pharmaceutical Companies:Integrated drug developers and large-cap biotech sponsors internalize platform capabilities or secure dedicated manufacturing slots through strategic partnerships. Biogen anchors its position through backward integration into antisense oligonucleotide manufacturing.
- Contract Research Organizations:CDMOs and specialized testing laboratories provide analytical method development, stability studies, and regulatory submission support.
- Academic Research Institutions:University laboratories and NIH-funded translational centers de-risk preclinical mechanism studies for emerging modalities.
- Hospitals:Treatment centers with FACT accreditation and specialized pharmacy infrastructure administer cell and gene therapies under REMS protocols.
Pharmaceutical companies dominate current procurement volume; academic research institutions generate the pipeline feedstock determining tomorrow's commercial candidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing location decisions as sponsors weigh FDA's accelerated approval pathways against EMA's post-market surveillance burdens and Japan's orphan premium incentives. Cost-of-compliance gaps between jurisdictions are concentrating early-phase development in the United States while late-stage commercial manufacturing gravitates toward Germany and Switzerland.
United States
FDA's Center for Biologics Evaluation and Research anchors global clinical trial initiation through compressed review timelines for gene therapies. NIH translational research funding de-risks preclinical mechanism studies at academic medical centers. The Greater Boston corridor concentrates mRNA manufacturing infrastructure with dedicated cleanroom capacity for oncology pipeline supply.
Germany
EMA Committee for Medicinal Products for Human Use standards shape multi-regional chemistry, manufacturing, and controls qualification strategies for sponsors seeking European access. The country's federal system supports cluster development in Baden-Württemberg and Bavaria. Contract manufacturers near Frankfurt expand lipid nanoparticle formulation capacity specifically for infectious disease and cancer vaccine production.
Switzerland
Swissmedic maintains alignment with EMA standards while offering streamlined access procedures for nucleic acid therapies targeting rare genetic disorders. The Basel-Zurich corridor concentrates antisense oligonucleotide expertise inherited from legacy pharmaceutical programs. Gene therapy sponsors leverage Swiss manufacturing infrastructure for vector production serving both European and global distribution networks.
Japan
PMDA's Sakigake designation creates favorable entry economics for nucleic acid therapies targeting ultrarare indications with reimbursement premiums. The Tokyo-Osaka axis hosts specialized treatment centers with FACT accreditation for administering cell and gene therapies under risk evaluation and mitigation strategies. Domestic sponsors partner with global platforms to access replicon technology for dose-sparing infectious disease applications.
United Kingdom
Medicines and Healthcare products Regulatory Agency post-Brexit frameworks are converging with FDA standards while maintaining distinct advanced therapy medicinal products oversight. The Golden Triangle research cluster de-risks emerging modalities through proximity to university laboratories and NIH-funded translational centers. London-based procurement departments pilot centralized specialty pharmacy contracts for nucleic acid therapeutic purchasing.
Nucleic Acid Based Therapeutics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue differentiated chemistry platforms and regional regulatory arbitrage. The market structure concentrates around integrated platform owners with captive manufacturing and specialized contract developers serving mid-cap sponsors. Three archetypes dominate: backward-integrated large-cap biotech with internal oligonucleotide synthesis, pure-play RNA platform companies with lipid nanoparticle expertise, and gene therapy specialists with viral vector production infrastructure. Competitive moves center on long-term offtake agreements for ionizable lipids and strategic partnerships securing dedicated manufacturing slots.
Within the integrated platform tier, Biogen anchors backward integration into antisense oligonucleotide manufacturing while Ionis Pharmaceuticals exemplifies chemistry-specialist positioning in rare genetic disorders. BioNTech occupies a distinct vector as an mRNA platform leader spanning oncology and infectious disease pipelines. These three represent the dominant competitive archetypes: captive manufacturing scale, therapeutic-area specialization, and multi-indication platform leverage.
| Leading Market Players |
|---|
| Biogen |
| BioNTech |
| Ionis Pharmaceuticals |
| Arrowhead Pharmaceuticals |
| Moderna |
| Alnylam Pharmaceuticals |
| Novartis |
| CureVac |
| Sarepta Therapeutics |
| Others |
Cost & Logistics Intelligence
Phosphorothioate synthesis expertise concentrates among veteran chemists in the Greater Boston corridor, where labor-cost differentials between legacy antisense hubs and emerging biotech clusters widen pricing-tier spreads across GMP-grade oligonucleotide manufacturing.
Pricing Analysis
Distributor margins on ionizable lipids compress final therapy costs by 12-18 percent before hospital formulary markups. Three-tier pricing structure across premium, standard, and economy levels separates FDA-breakthrough-designated therapies from standard-of-care antisense programs and research-grade materials. Pricing pressure stems from concentrated ionizable lipid suppliers forcing long-term offtake commitments. Academic medical centers exhibit highest price sensitivity; integrated biotech sponsors with captive manufacturing show least.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale demand from academic medical centers with FACT accreditation and REMS-certified infrastructure. Ionizable lipid manufacturing clusters in the United States, Germany, and Switzerland, with plasmid DNA production anchored in the United States and viral vector expansion in Germany. Supply chains draw from phosphorothioate-modified nucleosides, synthetic cholesterol analogs, and polyethylene glycol-lipid conjugates. Single-source vulnerability at the ionizable lipid tier exposes mid-cap developers to allocation risk. Distribution runs through specialized cold-chain logistics providers with ultra-low-temperature validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: FDA's accelerated approval pathways compress capital-at-risk periods relative to EMA's 15-year post-authorization surveillance burdens, shifting early-phase development toward the United States.
For Market Incumbents: Deploy backward integration into antisense oligonucleotide synthesis to defend against emerging platform competitors with replicon technology. Secure dedicated manufacturing slots through long-term offtake agreements with qualified ionizable lipid suppliers before allocation tightens further. Capacity addition in Germany addresses EMA qualification requirements while maintaining US clinical trial velocity. For New Entrants and Emerging Players: Enter via Japan's Sakigake designation pathway for ultrarare genetic disorders, where reimbursement premiums offset development costs. Target cardiovascular siRNA applications as the most penetrable segment given Alnylam's established prescriber education infrastructure. Pursue white-label CDMO partnerships to bypass ISO 13485 qualification timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap platform companies with validated delivery chemistry but pre-revenue oncology pipelines. Long-term viability across the analysis window hinges on regulatory convergence between FDA and EMA reducing redundant CMC qualification burdens. Watch for EMA ATMP framework revisions as the inflection signal determining European commercial cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Cleanroom expansion in Greater Boston and Frankfurt secures mRNA oncology supply. |
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses development timelines for gene therapies. |
| Long-term Supply Agreement | Strategic offtake contracts with ionizable lipid manufacturers de-risk commercial launch. |
| Pipeline Diversification | Circular RNA platforms extend dosing intervals beyond linear mRNA durability limits. |
| Geographic Expansion | Swissmedic alignment with EMA standards enables streamlined European rare disease access. |
Research Approach
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and hospital procurement managers; secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases; plus customs and trade data on lipid component flows — were reconciled through bottom-up and top-down triangulation.
Historical revenue trajectories were cross-referenced against panel input from platform chemistry specialists and CDMO operations directors. Segmentation modeling spanned product type, delivery modality, therapeutic area, and regional regulatory cluster across the projection horizon. CAGRs were derived from slope analysis of modality-specific adoption curves, with inputs from NIH funding allocations and hospital capital expenditure surveys on cold-chain infrastructure.
Inputs from clinical trial registries and GPO contract databases were available through the study window; gaps in real-world pricing transparency for long-term offtake agreements introduce uncertainty bands around manufacturer margin estimates. Forecasts reflect assumptions on regulatory convergence timing and ionizable lipid supply expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Gene Vector Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Europe Gene Therapy Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Gene Panel Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Stem Cell Concentration System Market
Cell & Gene Therapy
Cell Reprogramming Market
Cell & Gene Therapy
Autologous Cell Therapy Market
Cell & Gene Therapy
Global Oncolytic Virotherapy Market
Cell & Gene Therapy
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Mesenchymal Stem Cells Market
Cell & Gene Therapy
Cancer Stem Cells Market
Cell & Gene Therapy
Regenerative Therapies Market