
 Global Diagnostic Specialty Antibodies Market | 2026-2036
Global Diagnostic Specialty Antibodies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diagnostic Specialty Antibodies Market Intelligence
The expansion of custom conjugation and validation services is hardening the distinction between commodity and specialty antibody suppliers. Thermo Fisher Scientific leverages its extensive portfolio to serve high-volume clinical laboratories and research institutions. F. Hoffmann-La Roche specializes in developing antibodies for its proprietary diagnostic platforms, creating a closed ecosystem. Agilent Technologies competes by offering integrated solutions that combine its reagents with instrumentation for immunohistochemistry applications, targeting specific pathology workflows.
Diagnostic specialty antibodies are highly specific protein reagents, primarily immunoglobulins, engineered to bind to unique antigens for biomarker detection. These antibodies are purified and often conjugated with enzymes or fluorophores, serving to identify and quantify targets in clinical diagnostics and life science research. Monoclonal antibodies command a significant market position due to their high specificity and batch-to-batch consistency. Within applications, immunohistochemistry and ELISA remain mature segments, while flow cytometry represents the fastest-growing area, particularly in academic research and pharmaceutical development.
Market access is governed by stringent regulatory frameworks, including the U.S. FDA's requirements for in vitro diagnostics and Europe's Medical Device Regulation (MDR). In China, the NMPA's evolving standards for reagent registration and clinical validation influence product development timelines and market entry strategies. Vendor selection increasingly hinges on the ability to provide comprehensive validation data that satisfies diverse international regulatory submissions for both in vitro and in vivo diagnostics.
Market Dynamics
The imperative for enhanced diagnostic certainty and reproducibility is the central force shaping the specialty antibody market. This pressure, codified in stricter regulatory frameworks like the FDA's IVD requirements and the EU's MDR, compels manufacturers to invest heavily in validation and characterization, elevating the barrier to entry.
Growth Catalysts
- Biomarker Discovery Programs:Escalating investment in oncology and neurology research by pharmaceutical companies and academic institutions creates a continuous demand for novel, highly specific antibodies to identify and validate new therapeutic targets and diagnostic markers.
- EU Medical Device Regulation:The full implementation of the MDR in Europe mandates more rigorous clinical evidence and post-market surveillance for diagnostic reagents, favoring suppliers with robust validation data and quality management systems.
- Flow Cytometry Adoption:The expansion of flow cytometry applications beyond academic research into clinical diagnostics, particularly for immunology and hematology, requires a growing supply of fluorescently conjugated monoclonal antibodies with high batch-to-batch consistency.
Market Restraints
- High Development Costs:The significant capital and time investment required for the discovery, development, optimization, and clinical validation of a single high-affinity monoclonal antibody for diagnostic use creates a substantial financial barrier.
- Regulatory Fragmentation:Divergent and evolving registration requirements between major markets, such as the NMPA in China and the FDA in the US, complicate global product launch strategies and increase compliance costs for manufacturers.
- Technical Limitations of Polyclonals:The inherent batch-to-batch variability of polyclonal antibodies limits their application in quantitative assays and automated high-throughput platforms, restricting their use to less stringent research or semi-quantitative methods.
Strategic Opportunities
- Companion Diagnostics Co-development:Opportunities exist for antibody specialists to partner with pharmaceutical firms early in the drug development pipeline to create companion diagnostics, ensuring regulatory alignment and market access upon drug approval.
- AI-Powered Antibody Design:The convergence of artificial intelligence and high-throughput screening enables the rapid in-silico design and optimization of antibodies with desired specificity and affinity, accelerating development timelines.
- Diagnostic Infrastructure Expansion:Growing healthcare investments in countries like Brazil and India are creating new markets for advanced diagnostic tests, presenting an opportunity for suppliers who can navigate local regulatory bodies like ANVISA.
Industry Challenges
- Specialized Talent Scarcity:A shortage of personnel with dual expertise in protein biochemistry and global regulatory affairs makes it difficult for companies to assemble teams capable of navigating complex international submissions to bodies like the FDA and EMA.
- Assay Standardization Hurdles:The lack of universally accepted reference materials and standards for antibody validation complicates cross-platform comparisons, leading to reproducibility issues between different laboratories and diagnostic systems.
- Intellectual Property Complexity:Navigating the dense landscape of patents covering specific antibody sequences, host cell lines, and conjugation technologies presents a significant challenge, often resulting in costly licensing agreements or litigation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diagnostic Specialty Antibodies Market |
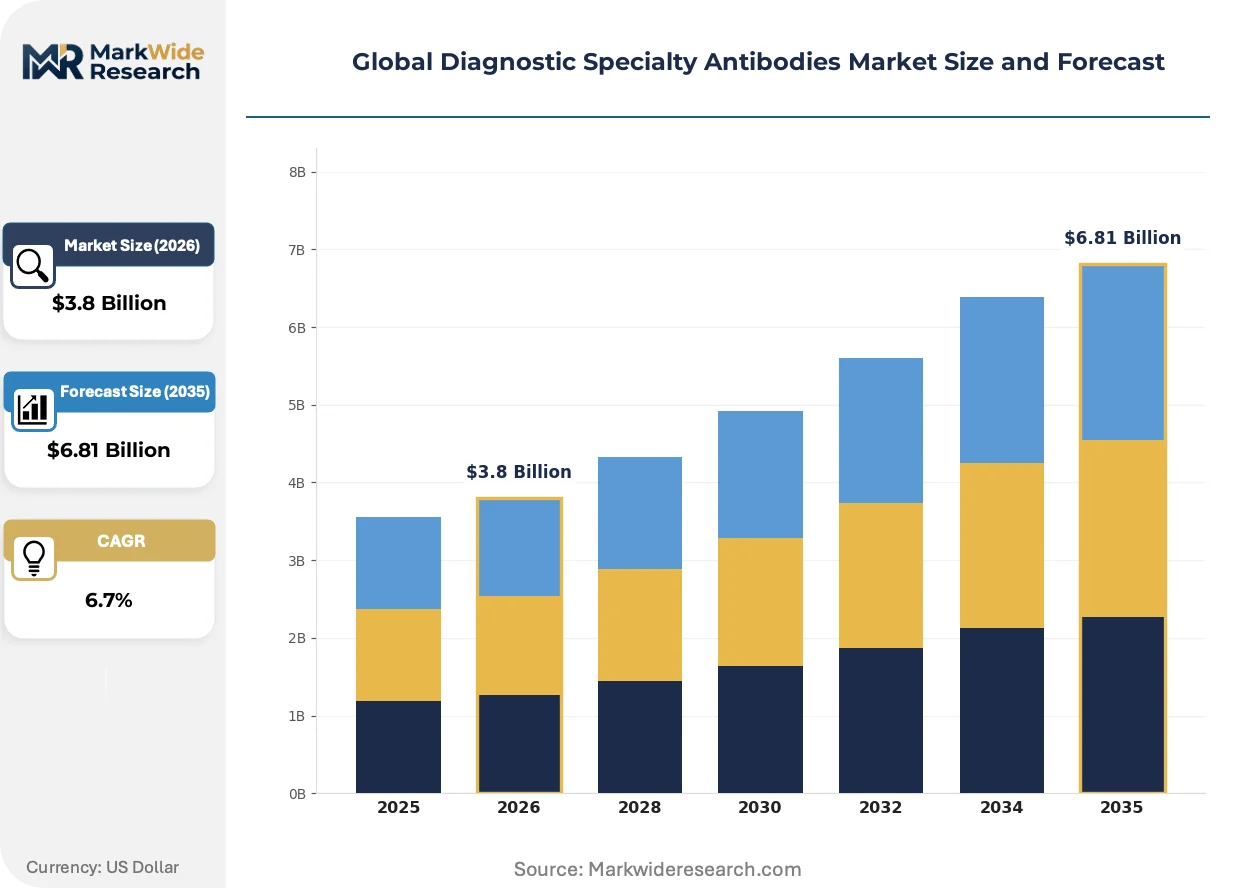
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Recombinant Antibodies, Fragment Antibodies, Conjugated Antibodies Application: Immunohistochemistry, Flow Cytometry, ELISA, Western Blotting, Immunofluorescence End User: Clinical Laboratories, Research Institutions, Diagnostic Centers, Pharmaceutical Companies, Biotechnology Firms Delivery Mode: In Vivo Diagnostics, In Vitro Diagnostics, Lateral Flow Assays, Point of Care Testing, High-Throughput Screening |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd., Danaher Corporation, Merck KGaA, Abbott Laboratories, Abcam plc, Sanofi, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diagnostic Specialty Antibodies Market Strategic Shifts & Innovations
The market's evolution is defined by a push toward automation, data-rich validation, and platform flexibility. These forces are moving the industry away from single-analyte tests and closed systems toward more efficient, reproducible, and open diagnostic solutions that can satisfy both clinical and regulatory demands.
Multiplex immunoassay technologies, such as bead-based assays and antibody microarrays, allow for the simultaneous detection of dozens of biomarkers. Clinical research organizations and large hospital laboratories are adopting these platforms to maximize data output from limited sample volumes. This technology is automating the analysis of complex protein signatures, significantly compressing the time required for disease profiling and patient stratification.
Heightened regulatory scrutiny from the U.S. FDA on companion diagnostics is a significant policy shift. This guidance compels antibody developers to engage with pharmaceutical partners much earlier to co-develop diagnostic assays alongside new therapeutics. The oncology and immunology drug pipelines are most affected, increasing the value of antibodies supported by comprehensive validation data suitable for PMA or 510(k) submissions.
A notable behavioral shift is occurring as laboratories decouple reagent purchasing from instrument contracts, resisting vendor lock-in. This disrupts the closed-ecosystem model where proprietary antibodies are tied to a specific manufacturer's analyzer, creating an opening for suppliers of high-quality, open-platform-compatible reagents. This procurement trend is most advanced within academic medical centers and independent reference labs in North America and Europe.
Global Diagnostic Specialty Antibodies Market Segmentation
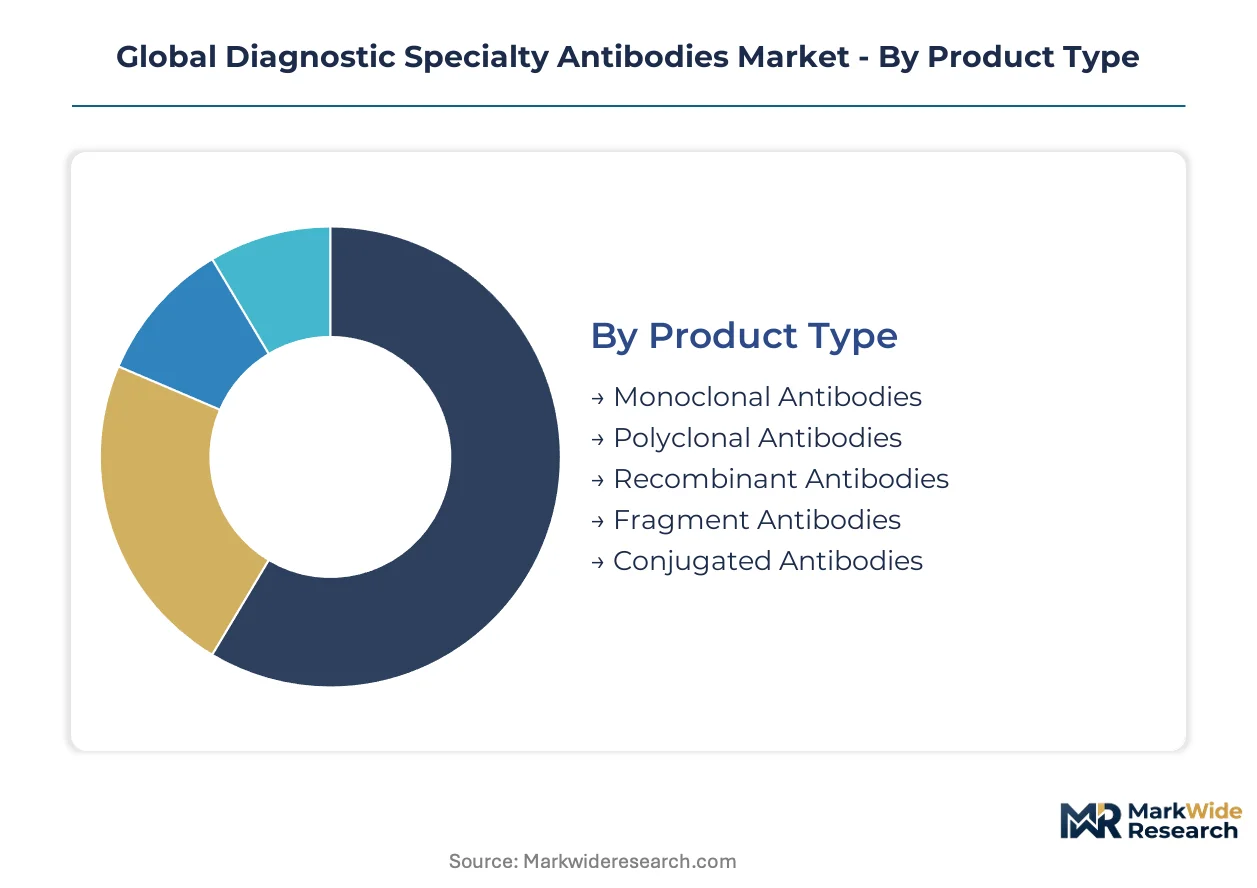
The segmentation of the global diagnostic specialty antibodies market highlights the diverse needs across clinical and research landscapes. Understanding these segments is critical for suppliers to tailor product development and market entry strategies, addressing specific technical requirements and regulatory demands of various end-users and applications.
Product Type:
Product types differentiate by their specificity, consistency, and production scale, directly influencing their cost and suitability for various diagnostic applications.
- Monoclonal Antibodies:These highly specific protein reagents bind to a single epitope on an antigen, ensuring exceptional batch-to-batch consistency for quantitative assays. Demand concentrates in clinical diagnostics and high-throughput screening platforms, driven by stringent reproducibility requirements from regulatory bodies like the FDA.
- Conjugated Antibodies:Antibodies chemically linked to reporter molecules like enzymes or fluorophores facilitate direct detection and signal amplification in immunoassays. These are crucial for applications such as ELISA and flow cytometry, enhancing sensitivity and enabling multiplexed analysis.
- Polyclonal Antibodies:Derived from multiple B cell clones, these antibodies recognize various epitopes on an antigen, offering broad reactivity and cost-effectiveness for initial screening or less stringent research.
- Recombinant Antibodies:Engineered using genetic methods, these antibodies provide superior batch consistency and can be optimized for specific binding characteristics, reducing reliance on animal immunization.
- Fragment Antibodies:Smaller antibody portions, such as Fab or scFv, offer improved tissue penetration and reduced immunogenicity, useful in specific imaging or therapeutic applications.
Today's leader: Monoclonal Antibodies. Tomorrow's challenger: Recombinant Antibodies.
Application:
Different applications demonstrate varying levels of technological maturity and growth potential within the diagnostic specialty antibodies market.
- Flow Cytometry:This technique analyzes cell populations based on light scatter and fluorescence, requiring highly specific, fluorescently conjugated antibodies for multi-parameter detection. Its adoption in academic research and clinical immunology is expanding, driven by advanced biomarker profiling needs.
- ELISA:Enzyme-linked immunosorbent assay is a plate-based immunoassay for quantitative detection of antigens or antibodies in a sample, widely used in diagnostic centers and pharmaceutical screening. It provides high-throughput screening capabilities for various analytes.
- Immunohistochemistry:This application involves detecting antigens in tissue sections using specific antibodies, a fundamental tool in pathology for disease diagnosis and prognosis.
- Western Blotting:A laboratory technique used to detect specific proteins in a sample, often employed in research for protein identification and quantification.
- Immunofluorescence:Utilizing fluorescently labeled antibodies, this method visualizes specific antigens within cells or tissues, providing spatial information for research and diagnostic purposes.
Flow Cytometry exhibits the steepest expansion trajectory, while ELISA maintains substantial market volume.
End User:
End-user segments reflect diverse procurement patterns and regulatory compliance needs for diagnostic specialty antibodies.
- Clinical Laboratories:These facilities conduct routine diagnostic testing and high-throughput screening for patient samples, demanding highly validated and reproducible reagents. Demand concentrates in the United States and Germany due to advanced diagnostic infrastructures and stringent quality controls.
- Pharmaceutical Companies:These firms utilize specialty antibodies for drug discovery, biomarker validation, and the development of companion diagnostics, requiring highly specific reagents for novel therapeutic targets. Investment in oncology and neurology research drives their demand.
- Research Institutions:Academic and government laboratories use antibodies for basic scientific research and translational studies, often requiring a broad range of antibodies for diverse experimental designs.
- Diagnostic Centers:Specialized facilities performing a wide array of diagnostic tests, from infectious diseases to genetic conditions, rely on validated antibodies for accurate and reliable results.
- Biotechnology Firms:Companies focused on developing novel assays, diagnostic kits, and therapeutic antibodies represent a key end-user segment, often engaging in early-stage antibody development.
Clinical Laboratories represent a foundational revenue base, with Pharmaceutical Companies driving innovation in co-development partnerships.
Delivery Mode:
Delivery modes are significantly influenced by regulatory frameworks and patient access requirements for diagnostic specialty antibodies.
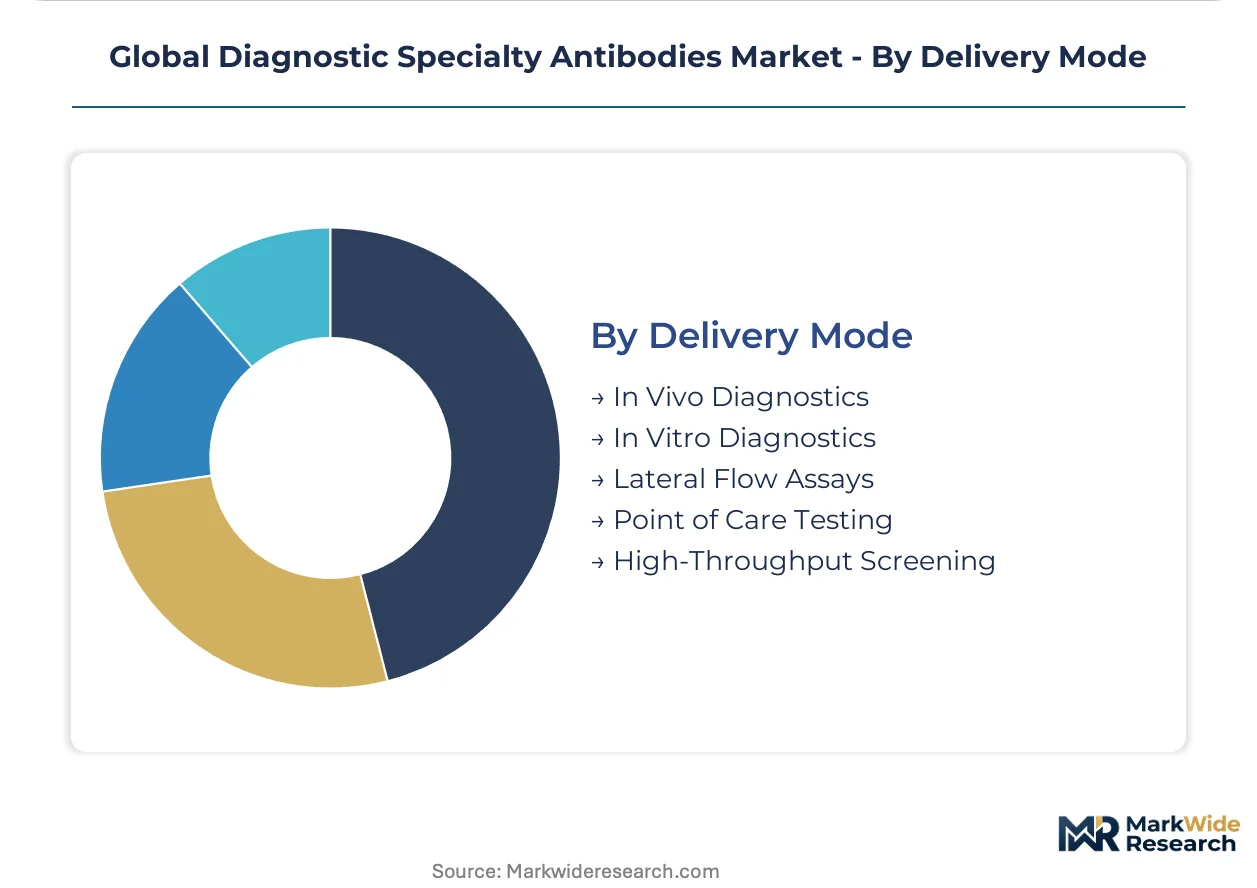
- In Vitro Diagnostics:These tests are performed on patient samples outside the body, representing the dominant delivery mode for diagnostic specialty antibodies. Demand concentrates in clinical laboratories and diagnostic centers, operating under stringent regulations such as the U.S. FDA's IVD requirements and Europe's MDR.
- High-Throughput Screening:This automated, large-scale testing approach rapidly screens thousands of samples for drug discovery, biomarker identification, or compound efficacy. Pharmaceutical companies and research institutions primarily adopt this mode for efficient data generation.
- In Vivo Diagnostics:This mode involves administering antibodies directly to patients for imaging purposes or to monitor therapeutic responses, requiring rigorous safety and efficacy validation.
- Lateral Flow Assays:Rapid, portable diagnostic tests providing qualitative or semi-quantitative results, commonly used in point-of-care settings for infectious disease detection or pregnancy testing.
- Point of Care Testing:Diagnostics performed near the patient, offering quick results outside a centralized laboratory, improving patient management and accessibility.
In Vitro Diagnostics command the largest share due to established clinical workflows, while High-Throughput Screening is expanding quickly in research settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States leads in diagnostic specialty antibody demand due to its advanced infrastructure, while Germany’s market is also significant. Both nations benefit from substantial research funding. This global market shows distinct regional dynamics.
United States
Demand for highly validated antibodies in the United States stems from extensive biomarker discovery programs. The U.S. FDA's stringent IVD requirements compel manufacturers to provide comprehensive validation data for market access. Major biotechnology clusters in Boston and San Francisco actively drive innovation in advanced diagnostic applications.
Germany
Germany's market benefits from strong academic research and clinical laboratory adoption of advanced diagnostics. The EU Medical Device Regulation (MDR) mandates rigorous clinical evidence for diagnostic reagents across Europe. Munich and Berlin host significant life science hubs specializing in novel diagnostic platform development.
China
China’s expanding healthcare investments fuel demand for advanced diagnostic tests and reagents. The NMPA's evolving standards for reagent registration significantly influence product development timelines and market entry strategies. Shanghai and Beijing are key centers for diagnostic manufacturing and clinical validation efforts.
India
India presents significant opportunities for diagnostic specialty antibodies due to growing healthcare infrastructure and increasing testing volumes. The CDSCO's evolving guidelines for reagent registration shape market entry and product development strategies. Hyderabad and Bangalore are emerging as critical hubs for pharmaceutical research and diagnostic test development.
Switzerland
Switzerland's demand for specialty antibodies is driven by its robust pharmaceutical industry and precision medicine initiatives. Swissmedic, the national regulatory authority, enforces high standards for in vitro diagnostics and research reagents. Basel and Zurich are key centers for biotechnology companies and advanced diagnostic research.
Global Diagnostic Specialty Antibodies Market Key Industry Players
Top-tier vendors anchor the consolidated segment, while a diverse array of specialized suppliers caters to niche applications. The market structure favors companies offering integrated solutions and comprehensive validation support. Strategic archetypes include platform providers, specialized reagent manufacturers, and contract development organizations. Dominant competitive moves involve portfolio diversification and strategic partnerships to navigate regulatory complexities.
Specialists in integrated diagnostic solutions include Thermo Fisher Scientific, which leverages its extensive portfolio to serve high-volume clinical laboratories and research institutions. F. Hoffmann-La Roche exemplifies a closed ecosystem model by developing antibodies for its proprietary diagnostic platforms. Agilent Technologies also occupies a position by offering integrated solutions that combine reagents with instrumentation for immunohistochemistry applications. These companies represent distinct approaches to market penetration, from broad portfolio leadership to platform-specific specialization and integrated workflow solutions.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd. |
| Danaher Corporation |
| Merck KGaA |
| Abbott Laboratories |
| Abcam plc |
| Sanofi |
| Bio-Rad Laboratories |
| Others |
Cost & Logistics Intelligence
Stricter regulatory frameworks, such as the U.S. FDA's IVD requirements and Europe's MDR, compel manufacturers to invest significantly in validation. This demand-side pressure influences supply chain configurations and pricing power for specialty antibody reagents.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity-grade antibodies. The market primarily operates on a contract-based long-term offtake model for high-volume clinical laboratories, while research institutions often engage in per-unit transactional purchasing. Price differentiation stems from comprehensive validation data required for regulatory submissions and the critical need for batch-to-batch consistency in monoclonal antibodies. Pricing exhibits upward pressure due to significant development costs and stringent validation. Research institutions display higher price sensitivity compared to pharmaceutical companies, which prioritize specificity for novel therapeutic targets.
Supply Chain Analysis
Single-source vulnerability sits with specialized manufacturers for high-affinity monoclonal antibodies. Geographic supply concentrates in the United States, Germany, and Switzerland, reflecting advanced biotechnology infrastructure. The supply chain relies on purified immunoglobulins, cell culture media, and reporter molecules as key inputs. Regulatory fragmentation across the NMPA, FDA, and EU MDR frameworks presents a significant structural risk. Distribution runs through direct sales channels for major clinical laboratories and pharmaceutical companies, complemented by specialized distributors serving research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diagnostic specialty antibodies market acts as a regulatory compounder, where the full implementation of the EU Medical Device Regulation (MDR) significantly drives demand for highly validated reagents. This regulatory push elevates product quality standards and market entry barriers.
For Market Incumbents: Cement market leadership by expanding comprehensive validation services, particularly for international regulatory submissions. Invest in AI-powered antibody design to accelerate novel antibody development and maintain a competitive edge against emerging specialized reagent manufacturers. Co-develop companion diagnostics with pharmaceutical partners early in the drug pipeline, leveraging strategic partnerships for integrated solutions. This approach mitigates the threat of commoditization and strengthens market position.
For New Entrants and Emerging Players: Capture growth opportunities by focusing on under-served geographies with expanding diagnostic infrastructure, such as Brazil and India. Target the demand for open-platform compatible reagents in academic research and independent reference laboratories. Offer specialized, highly specific recombinant antibodies supported by transparent, comprehensive validation data. A go-to-market angle centered on cost-effectiveness and flexibility can disrupt established closed ecosystems.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized reagent manufacturers demonstrating strong regulatory compliance and innovative antibody engineering capabilities. The market presents long-term viability over the next decade, driven by continuous biomarker discovery and precision medicine initiatives. Target mid-sized firms with proprietary recombinant antibody platforms or advanced validation technologies. A key signal to watch is increased M&A activity involving companies with established companion diagnostics co-development partnerships.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostics Co-development | Ensures regulatory alignment and market access upon drug approval for pharmaceutical firms. |
| AI-Powered Antibody Design | Accelerates development timelines by optimizing antibody specificity and affinity for research. |
| Investment in Validation Infrastructure | Satisfies stringent U.S. FDA and EU MDR requirements for clinical laboratories. |
| Geographic Expansion into Emerging Markets | Captures demand from growing healthcare investments in countries like India and Brazil. |
| Open-Platform Reagent Development | Addresses laboratory resistance to vendor lock-in, expanding market access for reagents. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. This approach combined insights from R&D directors at pharmaceutical companies, clinical laboratory managers, regulatory affairs specialists, and biotechnology firm executives. Secondary validation drew from U.S. FDA filings, EU MDR guidance documents, NMPA announcements, and academic research publications. Bottom-up market sizing from product segments was triangulated with top-down validation against overall industry revenue.
Segment-specific weighting was applied to project growth trajectories across the analysis window. The analytical framework integrated historical data with future projections across product type, application, end-user, delivery mode, and regional regulatory compliance. Compound annual growth rates were derived from a regression analysis of identified growth catalysts. Key forecast inputs included biomarker discovery pipeline expansion and evolving regulatory approval timelines for diagnostic tests.
Evolving regulatory landscapes, geopolitical trade policies, and unforeseen technological breakthroughs are the dominant revision risks. Forecasts reflect documented assumptions regarding market dynamics and potential supply chain disruptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Macrolide Drugs Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Drug Resistant Pulmonary Tuberculosis Market
Biopharmaceuticals
Global Oncology/Cancer Drugs Market
Biopharmaceuticals
Global Thrombin Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
Global Biopharma Buffer Market
Biopharmaceuticals
Biopharmaceutical Fermentation Market
Biopharmaceuticals
1-Step RT-PCR Kits Market
Biopharmaceuticals
Global Infertility Drugs Market
Biopharmaceuticals
Global MRSA Drugs Market
Biopharmaceuticals
Global Interferons Market
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market