
 Diabetes Drugs Market | 2026-2036
Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetes Drugs Market Intelligence
The gap between premium biologic therapies and commoditized oral generics is expanding across prescribing channels. Novo Nordisk A/S leverages its integrated manufacturing network to sustain supply security for peptide-based therapies. Eli Lilly and Company anchors its competitive stance through deep specialization in incretin mimetics. Sanofi competes on geographic reach, maintaining established insulin distribution across multiple continents.
Diabetes drugs comprise pharmacological agents designed to regulate blood glucose levels through mechanisms including insulin stimulation, peripheral glucose uptake enhancement, and hepatic glucose production suppression; these formulations range from recombinant human insulin and synthetic analogues with modified amino acid sequences to small-molecule inhibitors targeting enzymatic pathways like dipeptidyl peptidase-4. Their primary purpose is to prevent microvascular and macrovascular complications while enabling patients to achieve glycemic targets aligned with clinical guidelines. Among delivery modes, injectable formulations lead in revenue contribution due to biologic therapy dominance, though oral GLP-1 developments are accelerating fastest in development pipelines. Insulin analogues retain the largest installed patient base, while DPP-4 inhibitors occupy a mature position with flattening growth curves as newer classes capture prescriber attention.
FDA, EMA, and WHO prequalification standards collectively shape market access timelines, with FDA's Breakthrough Therapy designation compressing Phase III-to-approval intervals for novel diabetes therapies. REACH and EU MDR requirements in Europe add compliance layers for device-drug combination products like pre-filled insulin pens. Stakeholders must monitor how CMS and national health technology assessment bodies calibrate reimbursement for weight-management indications that overlap with diabetes therapy portfolios.
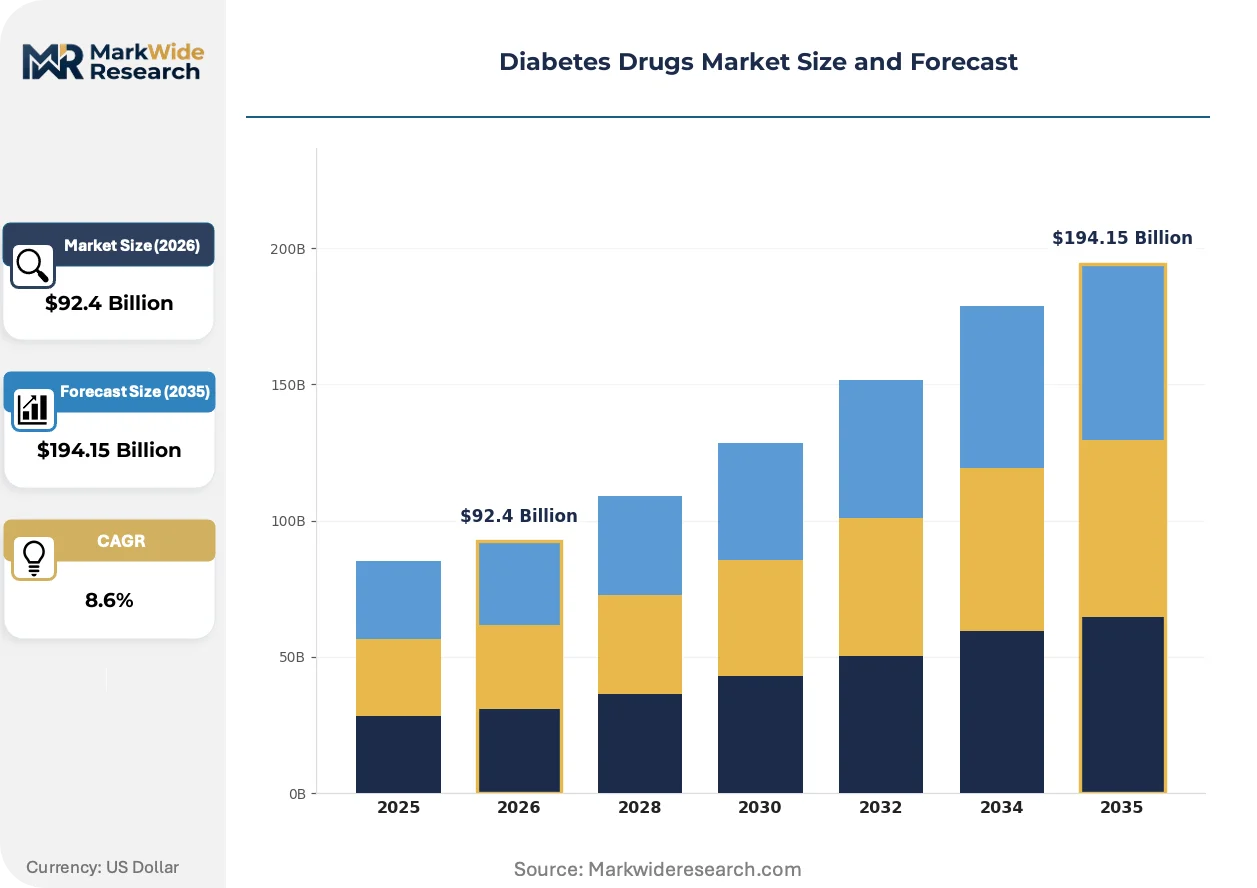
Market Dynamics
GLP-1 receptor agonists are compressing insulin analogue prescribing volumes while expanding into weight-management indications, forcing portfolio rebalancing across manufacturer pipelines.
Growth Catalysts
- FDA Breakthrough Therapy designation:The FDA's accelerated pathway compresses Phase III-to-approval intervals for novel biologic diabetes therapies, enabling earlier market entry for peptide-based formulations.
- Hospital formulary inclusion:End-user demand from hospital systems is broadening as GLP-1 receptor agonists gain formulary inclusion, expanding institutional procurement volumes.
- China reimbursement expansion:National health security schemes in China are extending coverage for next-generation incretin mimetics, unlocking patient access in the world's largest diabetes population.
Market Restraints
- Cold-chain distribution concentration:Biologic peptide therapies require uninterrupted cold-chain logistics, with supply vulnerability concentrated in third-party logistics providers lacking redundant temperature-controlled infrastructure.
- EU MDR compliance layering:The EU Medical Device Regulation imposes additional conformity assessment requirements on device-drug combination products like pre-filled insulin pens, extending certification timelines.
- Oral small-molecule substitution:DPP-4 inhibitors and SGLT-2 inhibitors continue displacing insulin initiations in Type 2 diabetes, eroding addressable market expansion for injectable therapies.
Strategic Opportunities
- Oral GLP-1 development:Small-molecule oral formulations of GLP-1 receptor agonists are advancing through clinical pipelines, promising to eliminate injection burden and expand prescriber adoption beyond endocrinology.
- India PLI scheme leverage:India's Production Linked Incentive scheme for pharmaceuticals offers cost offsets for domestic biologic manufacturing, enabling price-competitive supply for emerging market access.
- Weight-management indication overlap:Regulatory approvals for obesity treatment create dual-indication prescribing potential, with CMS and national health technology assessment bodies calibrating reimbursement for expanded labels.
Industry Challenges
- Peptide synthesis talent scarcity:Commercial-scale manufacturing of GLP-1 analogues requires specialized fermentation and purification expertise, with qualified bioprocess engineers concentrated at a limited number of contract manufacturing organizations.
- Legacy insulin pen platform integration:Next-generation connected delivery devices must interface with established dosing regimens and patient training protocols, creating user-experience friction during therapy transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetes Drugs Market |
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $194.15 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Analogues, Sulfonylureas, Biguanides, DPP-4 Inhibitors Delivery Mode: Injectable, Oral, Transdermal, Inhalable End User: Hospital, Homecare, Specialty Clinics, Retail Pharmacies Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Sanofi, AstraZeneca, Merck & Co., Inc., Boehringer Ingelheim, Novartis AG, Johnson & Johnson, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetes Drugs Market Strategic Shifts & Innovations
Biologic manufacturing scale-up and regulatory pathway compression are converging to reshape competitive entry timing, while delivery modality innovation targets adherence barriers.
Continuous glucose monitoring integration with automated insulin delivery is expanding into closed-loop artificial pancreas systems. Pediatric endocrinology departments and Type 1 diabetes patient advocacy groups are accelerating adoption of sensor-augmented pump therapy. The technology is expanding into predictive glucose control algorithms that reduce hypoglycemic events and compress HbA1c variability.
EMA's adaptive pathway pilot and FDA's Project Orbis are synchronizing multi-jurisdiction approval reviews for novel diabetes biologics. The industrial consequence is compressed regulatory submission preparation and aligned labeling across the United States and European Union markets. Biosimilar insulin developers in South Korea and India are responding by front-loading quality comparability studies to participate in parallel scientific advice.
Hospital procurement consortia are consolidating volume commitments for GLP-1 therapies through multi-year sole-source agreements. Group purchasing organizations are displacing individual hospital formulary negotiations with standardized tender processes. Germany's hospital procurement centralization under the Hospital Future Act is most visible, with regional purchasing cooperatives extracting price concessions in exchange for guaranteed minimum volumes.
Diabetes Drugs Market Segmentation
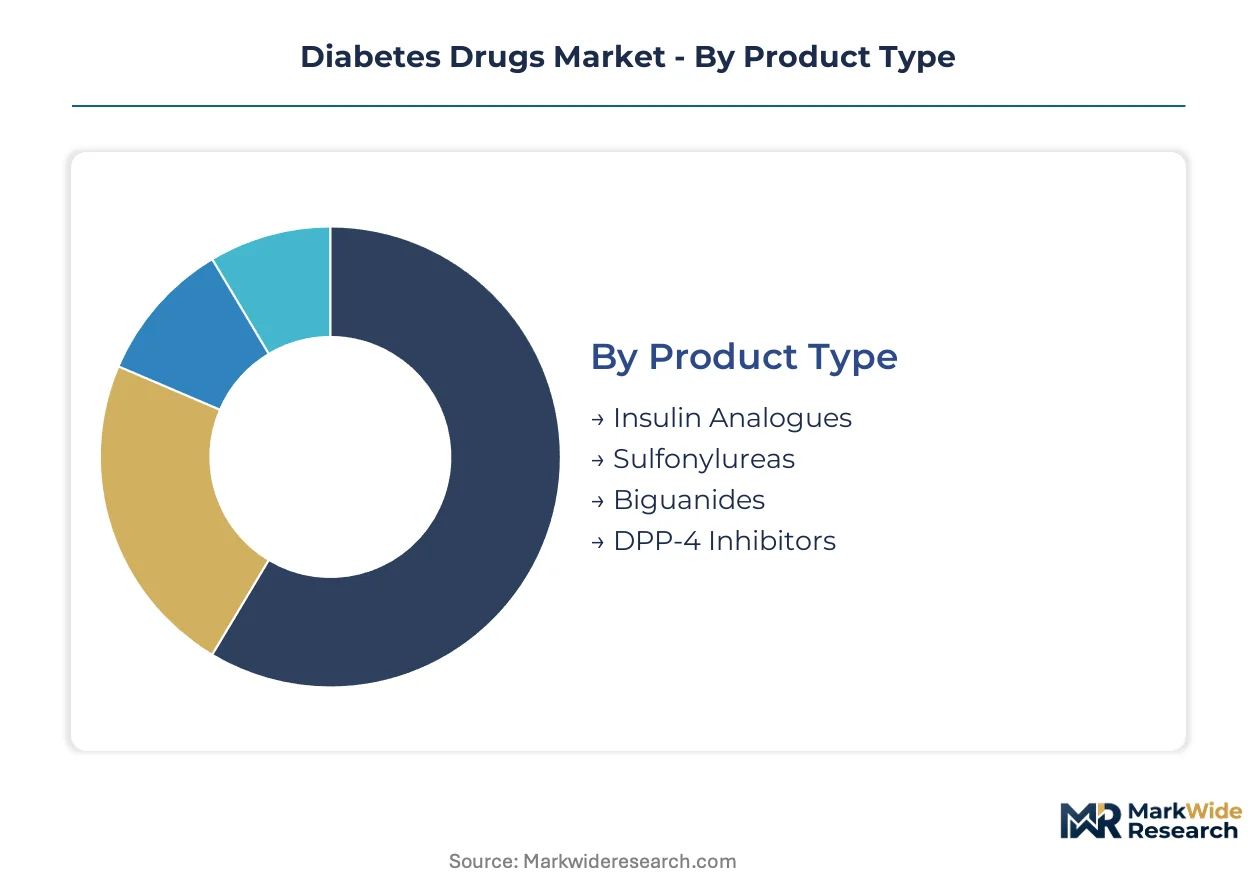
Diabetes drug segmentation reveals divergent margin profiles across delivery technologies and patient acuity levels. Prescriber channel preferences and reimbursement tiers fragment demand patterns within each product category.
Product Type:
Cost tier separates chronic maintenance therapies from premium biologic interventions requiring cold-chain infrastructure.
- Insulin Analogues:Recombinant human insulin and synthetic analogues with modified amino acid sequences enable precise glycemic control through rapid-acting and long-acting formulations. Demand concentrates in hospital systems and specialty endocrinology practices across the United States and Germany, driven by formulary inclusion for intensive insulin regimens and automated delivery integration.
- DPP-4 Inhibitors:Small-molecule enzyme inhibitors targeting dipeptidyl peptidase-4 extend endogenous incretin hormone activity with minimal hypoglycemia risk. Prescribing volumes cluster in primary care networks within China's tier-1 cities and India's metropolitan hospital chains, constrained by generic substitution pressure and SGLT-2 inhibitor displacement.
- Sulfonylureas:ATP-sensitive potassium channel blockers stimulate pancreatic beta-cell insulin secretion as second-line oral therapy.
- Biguanides:Metformin-class compounds suppress hepatic gluconeogenesis and enhance peripheral insulin sensitivity as first-line Type 2 diabetes management.
Volume sits with insulin analogues; growth tilts toward DPP-4 inhibitor combinations.
Delivery Mode:
Application context determines patient adherence barriers and supply chain complexity.
- Injectable:Subcutaneous delivery via vial-and-syringe, pre-filled pens, and pump systems dominates biologic peptide administration. Procurement concentrates in hospital outpatient departments and homecare settings across Germany and the United States, supported by connected device integration and continuous glucose monitoring interoperability.
- Oral:Small-molecule tablets and capsules eliminate cold-chain requirements and expand prescriber access beyond endocrinology. Demand clusters in retail pharmacy networks within China and India's urban centers, accelerated by oral GLP-1 candidates advancing through clinical pipelines.
- Transdermal:Patch-based delivery systems offer non-invasive insulin absorption through microneedle or iontophoretic mechanisms.
- Inhalable:Pulmonary insulin formulations provide rapid-acting prandial coverage through dry powder or liquid aerosol devices.
Injectable modalities capture installed patient base; oral formulations gain share fastest.
End User:
Customer type dictates procurement scale, pricing leverage, and clinical decision-making authority.
- Hospital:Integrated health systems and academic medical centers negotiate multi-year volume commitments through group purchasing organizations. Procurement concentrates in Germany's regional hospital cooperatives under the Hospital Future Act and United States IDN consortia, extracting price concessions for GLP-1 receptor agonist sole-source agreements.
- Homecare:Self-administered therapy management shifts fulfillment to specialty pharmacy and mail-order channels with patient support programs.
- Specialty Clinics:Endocrinology and diabetology practices drive biologic therapy initiation and dose optimization.
- Retail Pharmacies:Community-based dispensing handles oral generic maintenance prescriptions and over-the-counter glucose monitoring supplies.
Hospital procurement commands volume concentration; homecare channels expand most quickly.
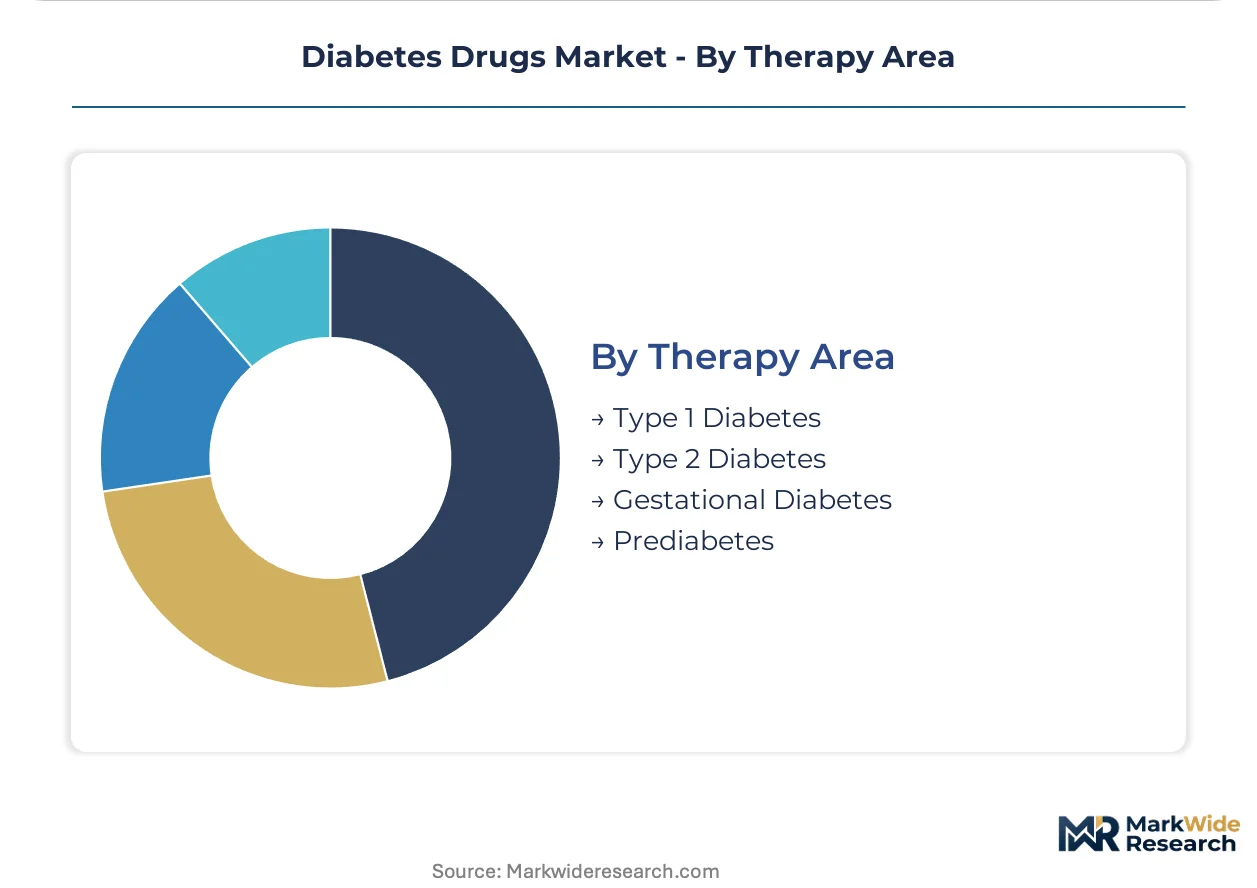
Therapy Area:
Disease severity and progression stage determine therapy intensity and monitoring requirements.
- Type 2 Diabetes:Progressive insulin resistance and beta-cell dysfunction creates the largest addressable population requiring escalating pharmacological intervention. Patient volumes cluster in China's provincial hospital systems and United States Medicare-covered populations, with prescriber attention shifting from insulin initiation toward incretin-based combination therapy.
- Type 1 Diabetes:Autoimmune beta-cell destruction mandates exogenous insulin replacement with intensive glucose monitoring. Demand concentrates in pediatric endocrinology departments across Germany and the United States, accelerated by closed-loop artificial pancreas system adoption and sensor-augmented pump therapy.
- Gestational Diabetes:Glucose intolerance during pregnancy requires short-term glycemic management with fetal safety considerations.
- Prediabetes:Impaired glucose tolerance populations represent preventive intervention opportunity with lifestyle and pharmacological modulation.
Type 2 diabetes holds patient volume concentration; Type 1 diabetes shows steepest technology premium expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Route 128 corridor anchors North American diabetes drug development, hosting dense clusters of biotech R&D and clinical trial infrastructure. Regulatory convergence between FDA and EMA accelerates multi-jurisdiction launches from this hub. Manufacturing scale-up concentrates in Midwest pharmaceutical corridors and German chemical valleys.
United States
Medicare reimbursement expansion for GLP-1 therapies drives hospital formulary adoption across IDN networks. FDA Breakthrough Therapy designation compresses Phase III-to-approval intervals for peptide-based formulations. Indianapolis and Research Triangle Park host concentrated manufacturing and clinical operations for incretin mimetics.
Germany
Hospital Future Act procurement centralization extracts price concessions through regional purchasing cooperatives. EMA adaptive pathway pilots synchronize multi-jurisdiction reviews with FDA Project Orbis. Rhine-Main and Baden-Württemberg pharmaceutical corridors concentrate insulin pen device manufacturing and cold-chain distribution infrastructure.
China
National health security schemes extend reimbursement for next-generation incretin therapies across provincial hospital systems. NMPA priority review channels accelerate domestic biologic approvals for the world's largest diabetes population. Shanghai and Suzhou biotech parks anchor peptide synthesis scale-up and contract manufacturing expansion.
India
Production Linked Incentive scheme offsets enable cost-competitive biologic manufacturing for emerging market access. CDSCO streamlined pathways accelerate biosimilar insulin approvals amid expanding domestic demand. Hyderabad and Ahmedabad pharmaceutical clusters concentrate fermentation capacity and API synthesis expertise.
Japan
PMDA Sakigake designation fast-tracks novel diabetes therapies for aging populations with high complication burdens. METI industrial policy supports domestic manufacturing resilience for critical peptide therapies. Kansai pharmaceutical corridor maintains specialized formulation capabilities and regional distribution networks.
Diabetes Drugs Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the diabetes drug value chain, with integrated biologic manufacturers maintaining supply security advantages over virtual development firms. Market structure tilts toward oligopoly in peptide-based therapies while oral small-molecules fragment across generic substitution. Three archetypes dominate: vertically integrated biologic specialists, diversified pharmaceutical conglomerates with diabetes portfolios, and regional biosimilar developers. Capacity expansion and strategic portfolio rebalancing toward incretin-based therapies constitute the dominant competitive moves.
Among integrated biologic specialists, Novo Nordisk A/S and Eli Lilly and Company exemplify the capital-intensive archetype with captive manufacturing networks for peptide-based therapies. Sanofi occupies a position bridging diversified pharmaceutical scale with established insulin distribution infrastructure across multiple continents. These three entities anchor competitive dynamics through supply security, formulary positioning, and geographic reach rather than pure R&D intensity.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Sanofi |
| AstraZeneca |
| Merck & Co., Inc. |
| Boehringer Ingelheim |
| Novartis AG |
| Johnson & Johnson |
| Pfizer |
| Others |
Cost & Logistics Intelligence
Hospital procurement consortia in Germany and the United States anchor pricing power through multi-year sole-source agreements, compressing margins for manufacturers while rewarding scale-compliant suppliers with volume guarantees. This buyer concentration forces peptide therapy producers into value-based contracting tied to HbA1c outcome thresholds, with CMS reimbursement benchmarks serving as the pricing anchor across institutional channels.
Pricing Analysis
Value-based contracting tied to glycemic outcome thresholds anchors pricing for GLP-1 receptor agonists, with CMS Medicare benchmarks and Germany's G-BA benefit assessment creating cross-border price referencing. Price differentiation rests on cold-chain certification tier and formulary exclusivity status, with hospital systems commanding steepest discounts through GPO aggregation. Cost compression in insulin analogues intensifies as biosimilar entrants from South Korea and India gain EMA and FDA approvals. Retail pharmacy channels exhibit highest price sensitivity due to generic substitution elasticity, while specialty clinics and academic medical centers prioritize clinical outcome guarantees over per-unit cost.
Supply Chain Analysis
Qualified bioprocess engineers for peptide fermentation and purification concentrate in Denmark, Germany, and the Boston corridor, constraining manufacturing scale-up velocity for GLP-1 analogues. Raw material dependencies draw from Chinese API synthesis hubs, Indian fermentation substrate suppliers, and German precision device component manufacturers. Single-source vulnerability in cold-chain third-party logistics providers creates supply interruption risk during temperature excursions. Distribution runs through hospital GPO networks in Germany and the United States, with specialty pharmacy channels expanding fastest for homecare delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance layering and FDA Breakthrough Therapy pathway investments erect formidable cost-of-compliance barriers, entrenching incumbents with captive regulatory affairs capabilities while screening out capital-constrained entrants.
For Market Incumbents: Deepen backward integration into peptide synthesis capacity to offset contract manufacturing organization bottlenecks, particularly in Denmark and German Rhine-Main corridors. Secure sole-source formulary positioning through multi-year outcome-based contracts with U.S. IDN consortia and Germany's regional hospital cooperatives. Defend against oral GLP-1 substitution threats by accelerating connected delivery device integration with continuous glucose monitoring platforms. For New Entrants and Emerging Players: India's tier-2 and tier-3 cities present underserved buyer concentration for biosimilar insulin analogues, with CDSCO streamlined pathways offering faster approval timelines than EMA or FDA routes. Oral small-molecule DPP-4 inhibitor combinations in China's provincial hospital systems represent the most penetrable white-space target. Pursue licensing partnerships with established Indian fermentation specialists to bypass talent scarcity in peptide manufacturing. For Investors and Strategic Acquirers: The window for entry favors contract manufacturing organizations with validated cold-chain infrastructure and existing FDA/EMA inspection histories. Long-term viability hinges on exposure to incretin-based therapy volumes rather than legacy insulin commoditization. Watch for CMS reimbursement decisions on weight-management indication overlaps as the critical inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive peptide synthesis capacity in Denmark and Germany insulates against CMO talent scarcity and supply interruption. |
| Regulatory Approval Pathway | FDA Breakthrough Therapy and EMA adaptive pathway participation compresses Phase III-to-approval intervals for novel biologics. |
| Hospital System Partnership | Sole-source agreements with Germany's regional cooperatives and U.S. IDN consortia lock in volume commitments. |
| Pipeline Diversification | Oral GLP-1 formulations and weight-management indication expansion reduce dependence on injectable diabetes monotherapy. |
| Reimbursement Strategy | Outcome-based contracting aligned with CMS Medicare benchmarks and G-BA assessments secures institutional access. |
Research Approach
Document review covered FDA Breakthrough Therapy designations, EMA adaptive pathway pilots, CMS Medicare reimbursement databases, and ClinicalTrials.gov entries, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from formulary databases, SEC 10-K pharmaceutical filings, and WHO prequalification standards. Bottom-up patient volume modeling and top-down market sizing triangulated across these sources.
Cross-referencing historical approval timelines against expert panel input informed the analytical framework across the projection horizon. Segmentation dimensions modeled included product type, delivery mode, end-user channel, therapy area, and regional regulatory cluster. CAGRs were derived from patient population epidemiology, reimbursement expansion trajectories, and biosimilar penetration curves. Forecast inputs incorporated cold-chain infrastructure expansion rates and peptide synthesis capacity buildout timelines.
Revisions become necessary when FDA or EMA regulatory pathway delays, CMS reimbursement recalibrations, or cold-chain logistics disruptions materialize beyond baseline assumptions. Forecasts reflect documented assumptions regarding formulary inclusion velocity and biosimilar approval cadence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Human Recombinant Insulin Market
Biopharmaceuticals
Global Myelodysplastic Syndrome (MDS) Drugs Market
Biopharmaceuticals
Biopharmaceuticals Packaging Market
Biopharmaceuticals
Asia-Pacific Plant-Based Biologics Market
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
North America and Europe Pegylated Drugs Market
Biopharmaceuticals
Proteinuria Therapeutics Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Macrolide Drugs Market
Biopharmaceuticals
Radiopharmaceutical Theranostics Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market
Biopharmaceuticals
Global Vaccine Conjugate Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Global Monoclonal Antibodies (Mabs) Market
Biopharmaceuticals
Mexico Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Penicillin G Acylase Market