
 China Insulin Drugs and Delivery Devices Market | 2026-2036
China Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Insulin Drugs and Delivery Devices Market Insights
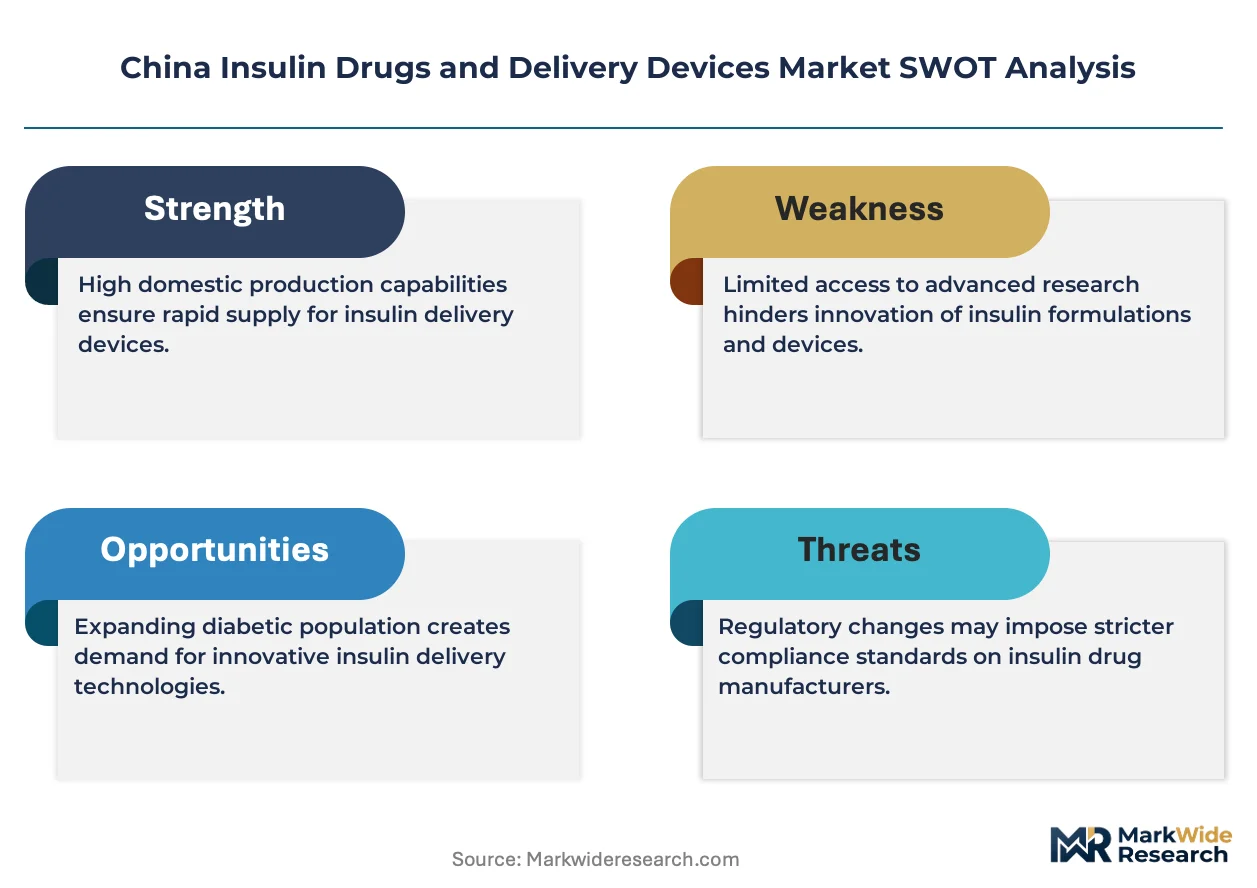
Multi-sourced API procurement is restructuring supply economics for domestic insulin finished-dose manufacturers. Gan & Lee Pharmaceuticals leverages captive recombinant DNA fermentation capacity to secure cost advantages in biosimilar insulin output. Novo Nordisk anchors premium rapid-acting analog positioning through direct hospital channel contracts in Beijing and Shanghai. Eli Lilly and Company differentiates via concentrated R&D spending on next-generation glucose-responsive formulations.
China insulin drugs and delivery devices encompass recombinant human insulin and insulin analogs formulated at 100 IU/mL concentration, paired with pen injectors, infusion pumps, and precision syringes for subcutaneous administration. These products maintain glycemic control in type 1 and type 2 diabetes patients, reducing microvascular complication incidence. Insulin pens dominate volume due to outpatient self-injection preference, while insulin pumps capture disproportionate value in pediatric and brittle diabetes segments. Biosimilar insulin represents the fastest-expanding drug category as NMPA equivalence standards mature and provincial procurement tenders favor cost-competitive entrants.
NMPA, the National Healthcare Security Administration, and provincial centralized procurement platforms collectively shape market access through volume-based purchasing mandates and reimbursement tier designations. GB standards for needle sterility and pen injector dose accuracy create compliance barriers that favor scaled domestic and multinational manufacturers. Stakeholders must monitor how NHSA national negotiation outcomes rebalance originator versus biosimilar insulin margins across hospital and retail pharmacy channels.
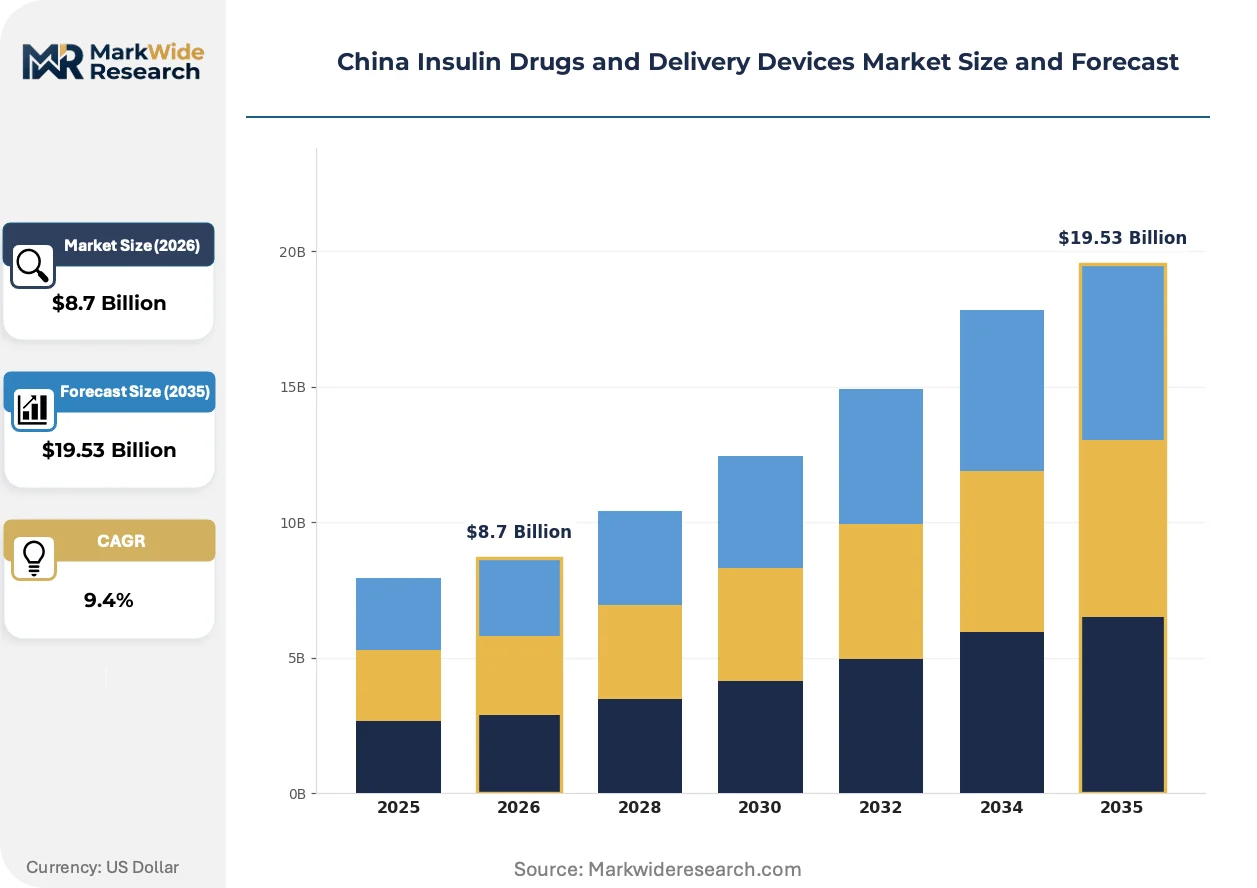
Market Dynamics
Centralized volume-based procurement by the National Healthcare Security Administration is compressing originator insulin margins while accelerating biosimilar substitution across tier-two and tier-three hospital networks.
Growth Catalysts
- NMPA Streamlined Biosimilar Pathways:The regulator's equivalence standards and abbreviated review timelines reduce domestic manufacturer entry barriers. Provincial tenders now favor cost-competitive biosimilar entrants.
- Tier-Two and Tier-Three Hospital Expansion:Hospital procurement departments in these cities are expanding insulin formulary access. Diabetes prevalence in these geographies drives volume growth.
- Recombinant DNA Fermentation Capacity:Captive upstream production of insulin active pharmaceutical ingredients secures cost advantages. Domestic manufacturers leverage this for biosimilar output scaling.
Market Restraints
- GB Standards Compliance Burden:Needle sterility and pen injector dose accuracy requirements create barriers that favor scaled manufacturers over mid-tier entrants.
- Originator Pricing Compression:Volume-based purchasing mandates force rapid-acting analog producers into margin defense. Premium positioning in Beijing and Shanghai faces tender-driven erosion.
- Substitution Ceiling in Pediatric Segments:Insulin pumps for brittle diabetes retain originator preference. Biosimilar penetration hits structural limits in high-acuity use cases.
Strategic Opportunities
- Zhejiang and Jiangsu Province Concentration:Diabetes prevalence and per-capita healthcare expenditure in these provinces outpace national averages. Targeted channel investment captures disproportionate value.
- Next-Generation Glucose-Responsive Formulations:Concentrated R&D spending on closed-loop responsive insulin creates differentiation. This technology convergence opens premium pricing corridors.
- Retail Pharmacy Channel Expansion:Outpatient self-injection preference shifts volume toward retail. Pen injector manufacturers can bypass hospital procurement constraints through this channel.
Industry Challenges
- Reimbursement Tier Navigation:NHSA national negotiation outcomes rebalance margins unpredictably. Stakeholders must monitor tier designation shifts across hospital and retail channels.
- Multi-Sourced API Quality Consistency:Restructured supply economics demand rigorous supplier qualification. Finished-dose manufacturers face audit complexity with diversified API sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Insulin Drugs and Delivery Devices Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Device Type: Insulin Pens, Insulin Pumps, Syringes, Needle-Free Injectors Drug Type: Long-Acting Insulin, Rapid-Acting Insulin, Premixed Insulin, Biosimilar Insulin End User: Hospitals, Clinics, Home Care, Retail Pharmacies Administration Route: Subcutaneous, Intravenous, Intraosseous, Intramuscular |
| Companies Covered | Gan & Lee Pharmaceuticals, Medtronic, Eli Lilly and Company, Sanofi, Novo Nordisk, Abbott Laboratories, Roche Diagnostics, Becton Dickinson, Dexcom, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Insulin Drugs and Delivery Devices Market Trends and Innovations
Closed-loop glucose-responsive insulin formulations and smart pen injector ecosystems are converging to reshape glycemic management. Device-drug integration is becoming the primary competitive axis.
Smart pen injectors with dose-memory and Bluetooth connectivity are expanding into outpatient self-monitoring workflows. Tier-two hospital diabetes clinics adopt these devices to reduce nursing documentation burden. This connectivity layer is expanding into remote patient management platforms that pharmaceutical manufacturers use to defend formulary position.
NMPA's equivalence standards for biosimilar insulin are tightening purity and immunogenicity benchmarks. Domestic manufacturers must demonstrate analytical similarity to originator reference products. Jiangsu-based producers face the steepest compliance ramps as the regulator prioritizes high-volume manufacturing sites for inspection.
Self-injection training and adherence support are unbundling from device sales. Third-party diabetes educators now contract directly with retail pharmacy chains. This service separation is most visible in Zhejiang province, where provincial health authorities pilot value-based pharmacy reimbursement that rewards outcome documentation over product volume.
China Insulin Drugs and Delivery Devices Market Segmentation
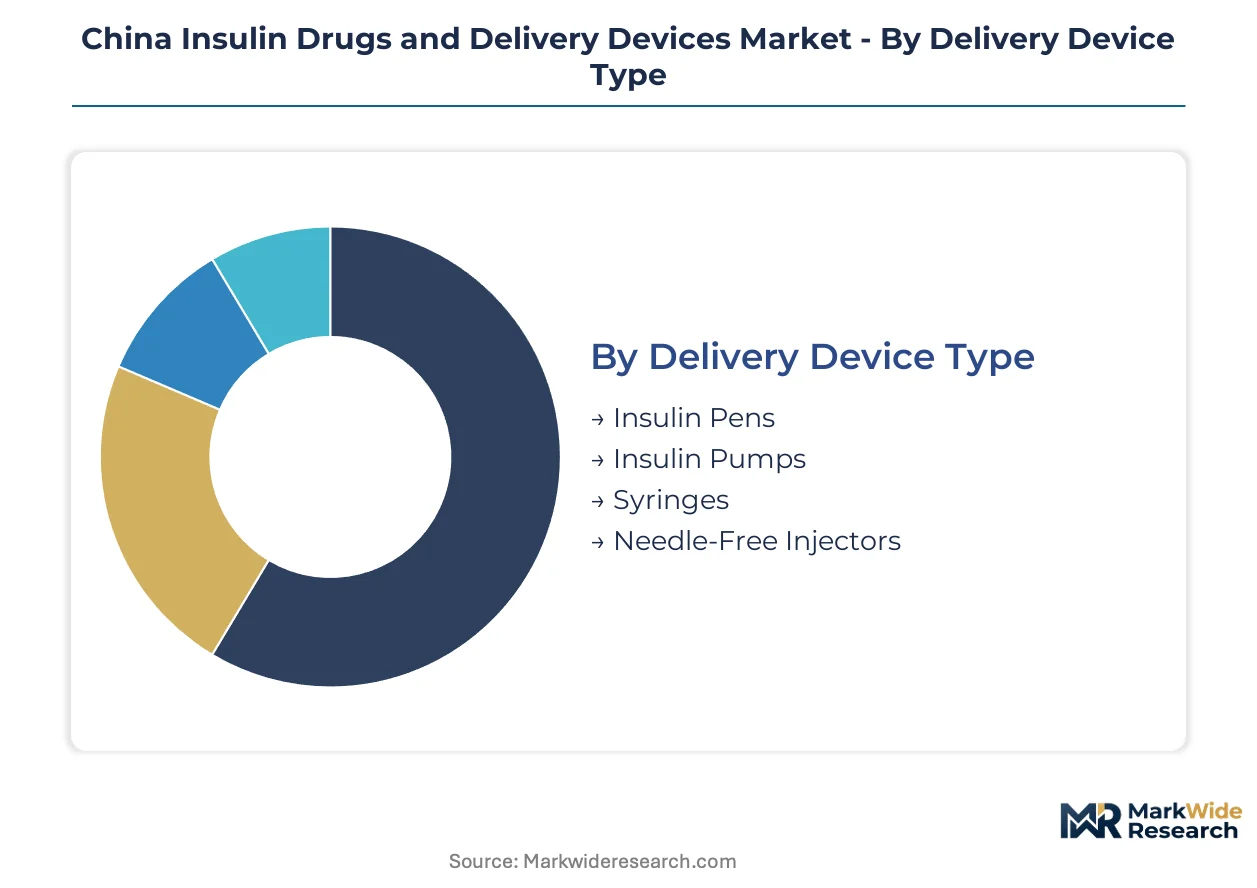
Supply concentration across insulin delivery modalities and drug formulations determines procurement leverage for hospital networks and retail pharmacy chains. NMPA regulatory pathways and NHSA volume-based purchasing create divergent margin structures across segment boundaries.
Delivery Device Type:
Device manufacturing capacity concentrates in Jiangsu and Zhejiang provinces, where GB standards compliance infrastructure supports scaled output.
- Insulin Pens:Reusable and disposable pen injectors deliver 100 IU/mL formulations with dose-memory and Bluetooth connectivity. Outpatient self-injection preference in tier-two cities drives volume concentration; nursing documentation burden reduction accelerates hospital adoption.
- Insulin Pumps:Continuous subcutaneous insulin infusion devices with closed-loop glucose-responsive capabilities capture pediatric and brittle diabetes segments. Beijing and Shanghai hospital networks maintain originator preference despite biosimilar pressure elsewhere.
- Syringes:Conventional U-100 syringes serve cost-sensitive segments with basic glycemic control needs.
- Needle-Free Injectors:Jet injection systems target needle-phobia patients and specific pediatric applications.
Insulin pens absorb the bulk of installed capacity; needle-free injectors are expanding most quickly.
Drug Type:
Cost tier stratification separates originator analogs from biosimilar entrants in provincial tender outcomes.
- Biosimilar Insulin:Recombinant human insulin and analog formulations demonstrate analytical similarity to originator reference products under NMPA equivalence standards. Tier-two and tier-three hospital procurement favors these entrants; streamlined approval pathways compress time-to-market.
- Rapid-Acting Insulin:Lispro, aspart, and glulisine analogs enable postprandial glucose control with faster onset profiles. Direct hospital channel contracts in Beijing and Shanghai defend premium positioning against tender-driven erosion.
- Long-Acting Insulin:Glargine and detemir formulations provide basal coverage with reduced hypoglycemia risk.
- Premixed Insulin:Fixed-ratio basal-bolus combinations simplify dosing regimens for elderly patients and resource-limited settings.
Long-acting insulin absorbs the bulk of installed capacity; biosimilar insulin shows the steepest expansion trajectory.
End User:
Volume distribution across customer types reflects reimbursement tier navigation and channel access patterns.
- Home Care:Self-administration by type 1 and insulin-dependent type 2 diabetes patients drives pen injector and disposable syringe demand. Zhejiang province pilots value-based pharmacy reimbursement rewarding outcome documentation.
- Retail Pharmacies:Outpatient prescription fulfillment captures chronic medication refills outside hospital procurement constraints. Jiangsu-based chains expand insulin formulary access with third-party diabetes educator contracts.
- Hospitals:Inpatient glycemic management and initial insulin initiation protocols concentrate in tier-one and tier-two facilities.
- Clinics:Community-based diabetes management provides follow-up care and prescription renewal services.
Home care absorbs the bulk of installed capacity; retail pharmacies are gaining share fastest.
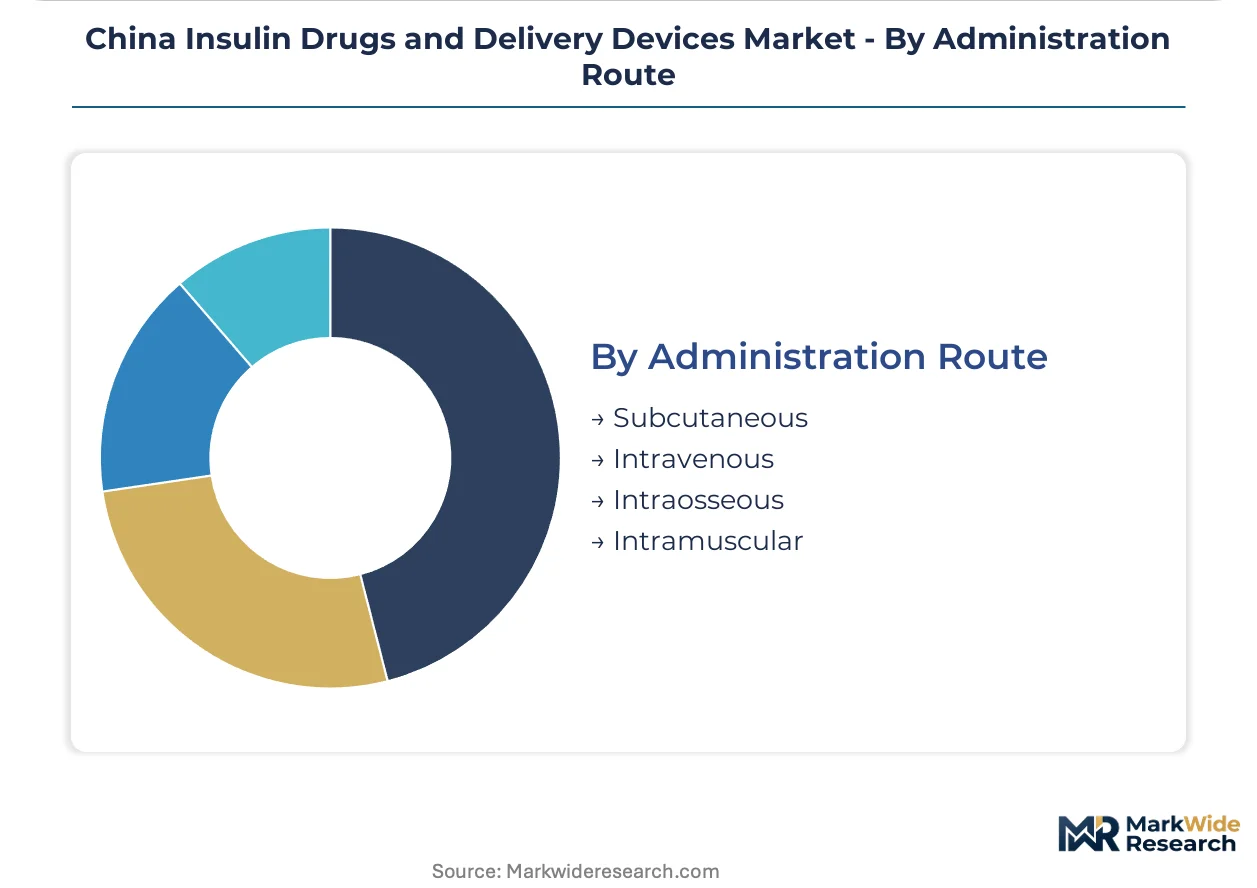
Administration Route:
Application-specific requirements determine device compatibility and training infrastructure investment.
- Subcutaneous:Abdominal, thigh, and upper arm injection sites accommodate pen injectors, pumps, and syringes for routine insulin delivery. Self-injection training programs in tier-two hospital diabetes clinics standardize technique.
- Intravenous:Hospital-based insulin infusion protocols manage diabetic ketoacidosis and perioperative hyperglycemia.
- Intramuscular:Emergency glucagon administration for severe hypoglycemia events uses specialized auto-injector formats.
- Intraosseous:Critical care settings employ vascular access alternatives when intravenous routes fail.
Subcutaneous delivery absorbs the bulk of installed capacity; intravenous protocols are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Jiangsu and Zhejiang provinces, where diabetes prevalence rates and per-capita healthcare expenditure outpace national averages. Hospital procurement departments across tier-two and tier-three cities are expanding insulin formulary access. NMPA's streamlined biosimilar approval pathways accelerate domestic manufacturer entry into these high-value markets.
Beijing-Tianjin-Hebei
Beijing anchors premium rapid-acting analog positioning through direct hospital channel contracts. NMPA maintains its headquarters here, shaping national equivalence standards for biosimilar insulin. The region's tier-one hospitals retain originator preference for pediatric and brittle diabetes segments despite biosimilar pressure elsewhere.
Yangtze River Delta
Jiangsu and Zhejiang provinces generate disproportionate volume due to elevated diabetes prevalence and healthcare spending. Provincial centralized procurement platforms favor cost-competitive biosimilar entrants. Suzhou and Hangzhou host concentrated device manufacturing capacity compliant with GB standards for needle sterility and dose accuracy.
Pearl River Delta
Guangdong province's retail pharmacy chains expand insulin formulary access with third-party diabetes educator contracts. The NHSA's volume-based purchasing mandates compress margins for originator products in Shenzhen and Guangzhou hospitals. Domestic manufacturers leverage captive recombinant DNA fermentation capacity for biosimilar output scaling.
Sichuan-Chongqing
Western China's diabetes patient population drives tier-two hospital formulary expansion in Chengdu and Chongqing. NMPA inspections prioritize high-volume manufacturing sites in this region for biosimilar equivalence verification. Local procurement departments navigate reimbursement tier designations that rebalance originator versus biosimilar margins.
Shandong Peninsula
Qingdao and Jinan hospital networks adopt smart pen injectors with Bluetooth connectivity to reduce nursing documentation burden. The region's diabetes clinics pilot remote patient management platforms that pharmaceutical manufacturers use to defend formulary position. Outpatient self-injection preference shifts volume toward retail pharmacy channels.
China Insulin Drugs and Delivery Devices Market Competitive Landscape
Capacity expansion dominates the current landscape as domestic and multinational manufacturers scale recombinant DNA fermentation and device assembly operations. The market structures around three tiers: multinational originators defending premium rapid-acting analog positions, domestic biosimilar specialists capturing provincial tender volume, and diversified medical device suppliers integrating smart connectivity features. Strategic archetypes include captive API producers, direct hospital channel contractors, and retail pharmacy-focused pen injector manufacturers. Competitive moves center on M&A for technology access and geographic expansion into tier-two city networks.
Among the multinational originators, Novo Nordisk and Eli Lilly and Company exemplify premium-tier positioning through concentrated R&D spending on next-generation formulations. Gan & Lee Pharmaceuticals represents the domestic biosimilar specialist archetype, leveraging upstream production capabilities to secure cost advantages in provincial procurement tenders. These three entities occupy distinct competitive spaces: the multinationals anchor Beijing and Shanghai hospital contracts, while the domestic player captures volume in Jiangsu and Zhejiang tier-two markets.
| Leading Market Players |
|---|
| Gan & Lee Pharmaceuticals |
| Medtronic |
| Eli Lilly and Company |
| Sanofi |
| Novo Nordisk |
| Abbott Laboratories |
| Roche Diagnostics |
| Becton Dickinson |
| Dexcom, Inc. |
| Others |
Pricing and Supply Chain Analysis
Recombinant DNA fermentation specialists concentrated in Jiangsu province anchor production economics, with labor-cost differentials between coastal and inland manufacturing zones widening the spread between premium rapid-acting analogs and economy-tier biosimilars. This workforce geography directly shapes three-tier pricing stratification across hospital procurement tiers.
Pricing Analysis
Service unbundling separates device warranties from diabetes educator support contracts, with third-party training fees now billed independently in Zhejiang retail channels. Three-tier pricing structure across premium, standard, and economy levels reflects GB standards certification grade and after-sales service inclusion. Cost compression in biosimilar tiers intensifies as NHSA volume-based purchasing mandates expand to tier-three cities. Retail pharmacy chains demonstrate highest price sensitivity; Beijing-Shanghai hospital networks retain lowest sensitivity due to originator brand preference in pediatric segments.
Supply Chain Analysis
Cold-chain logistics costs from Jiangsu and Zhejiang manufacturing hubs to western provinces constrain biosimilar distribution economics. Active pharmaceutical ingredient production draws from captive fermentation facilities in Jiangsu, pen injector components from Zhejiang precision manufacturers, and glucose sensor modules from South Korean electronics suppliers. Single-source vulnerability concentrates in recombinant DNA cell line banks held by dominant domestic producers. Distribution runs through provincial centralized procurement platforms for hospital channels and third-party logistics providers for retail pharmacy fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NMPA's tightening equivalence standards for biosimilar insulin immunogenicity create a cost-of-compliance moat that favors scaled manufacturers with dedicated regulatory affairs infrastructure over mid-tier aspirants.
For Market Incumbents: Hedge biosimilar margin erosion by deepening captive API production in Jiangsu fermentation facilities and securing direct hospital channel contracts in Beijing-Shanghai pediatric segments. Accelerate smart pen injector software certification to defend formulary position against device-agnostic procurement mandates.
For New Entrants and Emerging Players: Capture retail pharmacy volume in tier-two Zhejiang cities where value-based reimbursement pilots reward outcome documentation over tender pricing. Prioritize third-party diabetes educator partnerships as the primary go-to-market angle to bypass hospital procurement gatekeeping.
For Investors and Strategic Acquirers: Re-rating potential sits with domestic biosimilar specialists possessing NMPA-approved reference product portfolios given NHSA national negotiation outcomes favoring cost-competitive entrants. Long-term viability hinges on backward integration into fermentation capacity. Monitor Jiangsu-based manufacturing site inspection priority shifts as the inflection signal for regulatory capture timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | NMPA biosimilar equivalence submission accelerates market entry for domestic manufacturers against originator defense. |
| Manufacturing Scale-Up | Jiangsu fermentation capacity expansion secures cost advantages in provincial tender participation. |
| Hospital System Partnership | Direct Beijing-Shanghai tier-one contracts defend premium rapid-acting analog positioning against biosimilar substitution. |
| Software Companion Development | Bluetooth-enabled pen injector ecosystems reduce nursing documentation burden and strengthen formulary retention. |
| Reimbursement Strategy | NHSA national negotiation positioning determines margin allocation across hospital and retail pharmacy channels. |
Research Methodology
Multi-period observation of NMPA approval timelines, NHSA tender outcomes, and provincial reimbursement tier shifts anchored the trend analysis, supplemented by interviews with hospital procurement managers, formulary directors, regulatory affairs leads, and diabetes educator network coordinators. Secondary validation drew from NMPA drug approval databases, NHSA centralized procurement platform disclosures, hospital procurement contract registries, and GB standards technical documentation. Bottom-up patient population modeling and top-down healthcare expenditure triangulation converged on segment sizing.
Segment-weighting applied drug type, delivery device modality, and end-user channel dimensions across the projection horizon. CAGRs derived from patient prevalence trajectories, insulin intensity assumptions, and pricing elasticity by reimbursement tier. Forecast inputs incorporated NMPA inspection capacity expansion timelines and NHSA national negotiation scope expansion patterns.
The model holds under stable NMPA equivalence standard enforcement and continued NHSA volume-based purchasing mandate expansion; deviation in pediatric segment originator preference persistence or Jiangsu manufacturing site regulatory action would shift biosimilar penetration trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Disease-Modifying Antirheumatic Drug (DMARD) Market
Biopharmaceuticals
Clindamycin Phosphate Market
Biopharmaceuticals
Global Protein Expression Market
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
Spectinomycin Market
Biopharmaceuticals
Anti-Neprilysin Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Asia-Pacific Biologics Market
Biopharmaceuticals
Human Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Beta Interferon Market
Biopharmaceuticals
APAC Insulin Market
Biopharmaceuticals
Erythropoietin Drugs Market
Biopharmaceuticals
Triptorelin Market
Biopharmaceuticals
Canada Generic Drug Market
Biopharmaceuticals
Metabolism Drugs Market