
 Global Breast Cancer Drugs Market | 2026-2036
Global Breast Cancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Breast Cancer Drugs Market Foresight
Project finance structures for late-stage oncology assets is reconfiguring competitive entry barriers, allowing biotech firms to retain development control without full capital burden. F. Hoffmann-La Roche Ltd leverages its entrenched HER2 franchise to sustain pricing power across multiple indications. Pfizer Inc. anchors its position through manufacturing scale that commands preferential formulary placement. AstraZeneca differentiates via antibody-drug conjugate investments that extend its oncology pipeline depth.
Breast cancer drugs comprise pharmaceutical agents designed to interrupt malignant cell proliferation through hormonal modulation, cytotoxic destruction, or targeted molecular interference, typically requiring parenteral or oral administration with precise dosing calibrated to receptor status and disease staging. The primary purpose centers on extending progression-free survival while preserving quality of life through increasingly selective mechanisms. Targeted therapy segments command the deepest margin pools as antibody-drug conjugates and CDK4/6 inhibitors displace conventional cytotoxic regimens. Immunotherapy occupies the fastest-expanding structural position, particularly in triple-negative subsets where checkpoint inhibitors have secured transformative indications. Hormonal therapy remains the most mature category, though resistance mechanisms continue to drive next-generation aromatase inhibitor and SERD development.
FDA accelerated approval pathways, EMA adaptive licensing frameworks, and Japan PMDA's sakigake designation system collectively compress commercialization timelines while elevating post-market evidence requirements. These regulatory architectures shape demand by rewarding biomarker-defined subsets with premium reimbursement while restricting broad-label prescribing. Stakeholders must monitor evolving overall survival endpoint standards and companion diagnostic mandates that increasingly determine market access velocity.
Market Dynamics
The transition from cytotoxic chemotherapy to precision-targeted modalities is compressing treatment paradigms and redrawing competitive boundaries across oncology portfolios worldwide.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses Phase II-to-launch timelines for biomarker-defined subsets, rewarding sponsors with conditional market entry contingent on confirmatory trials.
- Companion Diagnostic Mandates:HER2, PD-L1, and BRCA testing infrastructure expansion locks prescribing behavior to assay-verified patient selection, deepening therapy adherence.
- CDK4/6 Inhibitor Class:Palbociclib and ribociclib penetration into first-line HR-positive settings has created a durable maintenance therapy archetype with extended dosing cycles.
Market Restraints
- API Concentration Risk:Active pharmaceutical ingredient manufacturing for antibody-drug conjugates concentrates in Chinese and Indian contract manufacturers, exposing supply continuity to geopolitical friction.
- EMA Adaptive Licensing Burden:Post-authorization evidence requirements impose costly registry commitments that erode net present value for mid-cap developers with limited pharmacovigilance infrastructure.
- Primary Resistance Mechanisms:PIK3CA and ESR1 mutations in hormonal therapy lines limit duration of response, forcing earlier pipeline investment in next-generation SERDs.
Strategic Opportunities
- Brain Metastasis Indications:Tucatinib's CNS-penetrant profile in HER2-positive disease establishes a template for blood-brain barrier permeable small molecules in underserved secondary settings.
- Japan PMDA Sakigake:Priority review vouchers for innovative oncology assets reduce regulatory lag for sponsors willing to conduct bridging studies in Japanese patient populations.
- ADC-IO Combinations:Trastuzumab deruxtecan plus durvalumab regimens in HER2-low expression subsets represent a mechanistic convergence opportunity displacing sequential monotherapy.
Industry Challenges
- Biomarker Assay Harmonization:Discordance between central laboratory and point-of-care PD-L1 scoring platforms creates enrollment friction in immunotherapy trials and reimbursement disputes.
- Cold Chain Integrity:Temperature excursion risks for monoclonal antibody formulations require validated distribution networks that strain operational capacity in emerging markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Breast Cancer Drugs Market |
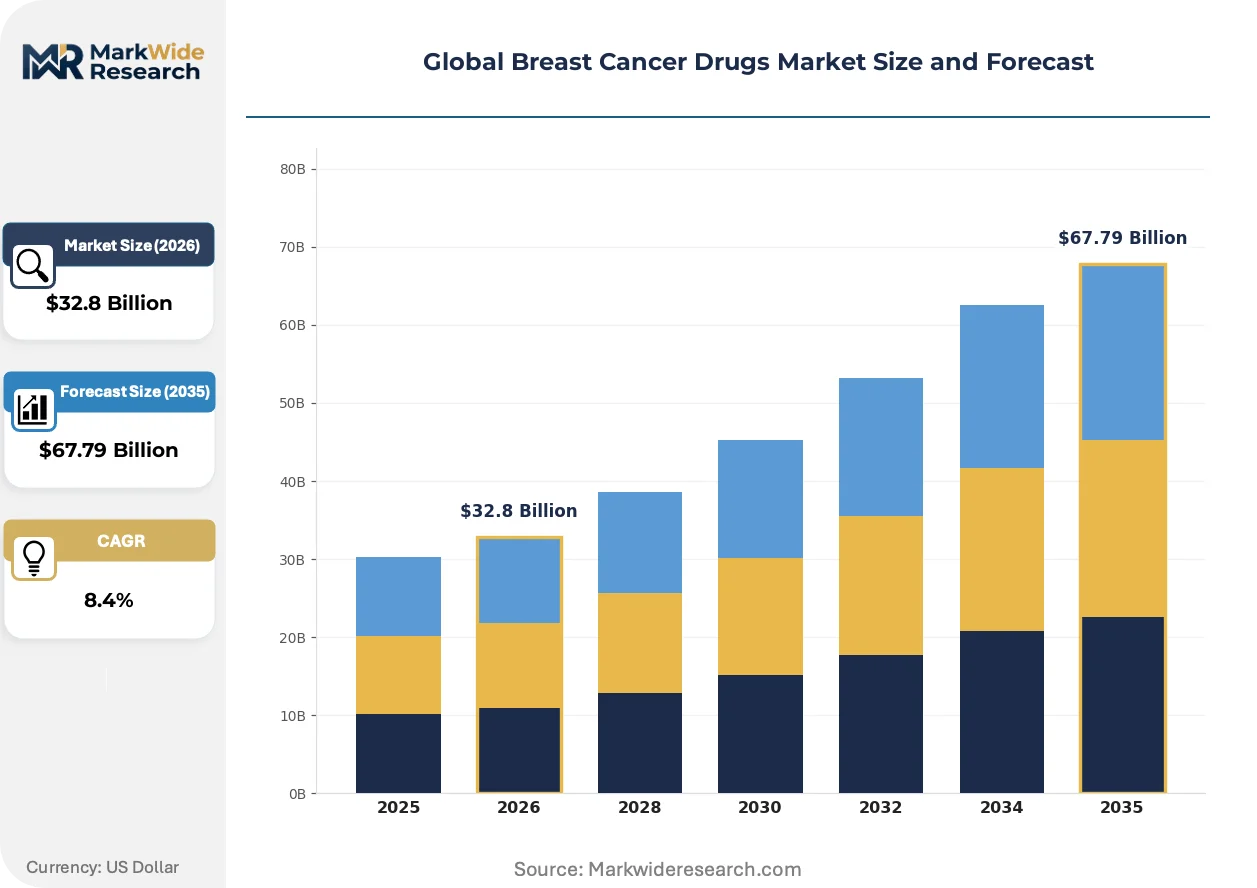
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapy, Chemotherapy, Targeted Therapy, Immunotherapy, Radiopharmaceuticals Therapy Area: Early Stage, Metastatic, HER2-Positive, Triple-Negative, Ductal Carcinoma In Situ End User: Oncology Centers, Specialty Clinics, Diagnostic Laboratories, Cancer Research Institutes Delivery Mode: Oral, Intravenous, Injectable, Implantable, Transdermal Patches |
| Companies Covered | F. Hoffmann-La Roche Ltd, Pfizer Inc., AstraZeneca, Novartis AG, Eli Lilly and Company, Merck & Co., Inc., Sanofi, Bristol-Myers Squibb Company, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Breast Cancer Drugs Market Shifts & Advancements
Antibody-drug conjugate engineering and real-world evidence generation are converging to reshape how sponsors demonstrate value and secure formulary placement across heterogeneous healthcare systems.
Next-generation linker-payload technologies are expanding the therapeutic index of HER2-directed ADCs. Daiichi Sankyo's enhancement of cleavable linker stability permits higher drug-to-antibody ratios without dose-limiting toxicities. This engineering advance is digitizing patient selection algorithms through integrated biomarker platforms that match tumor microenvironment profiles to payload mechanisms.
EMA's implementation of the Clinical Trials Information System mandates standardized electronic submission formats across all member states. The regulation eliminates procedural divergence between national competent authorities, compressing multinational protocol approval timelines. Oncology sponsors with established EU-QPPV networks capture first-mover advantage in centralized procedure filings.
Hospital system consolidation in the United States is concentrating purchasing authority within integrated delivery networks. Academic medical centers now negotiate indication-specific value-based contracts that tie reimbursement to progression-free survival benchmarks. This procurement evolution is most visible in the Northeast and Midwest, where Cleveland Clinic and Mayo Clinic anchoring effects propagate standard-of-care protocols to affiliated community oncology practices.
Global Breast Cancer Drugs Market Segmentation
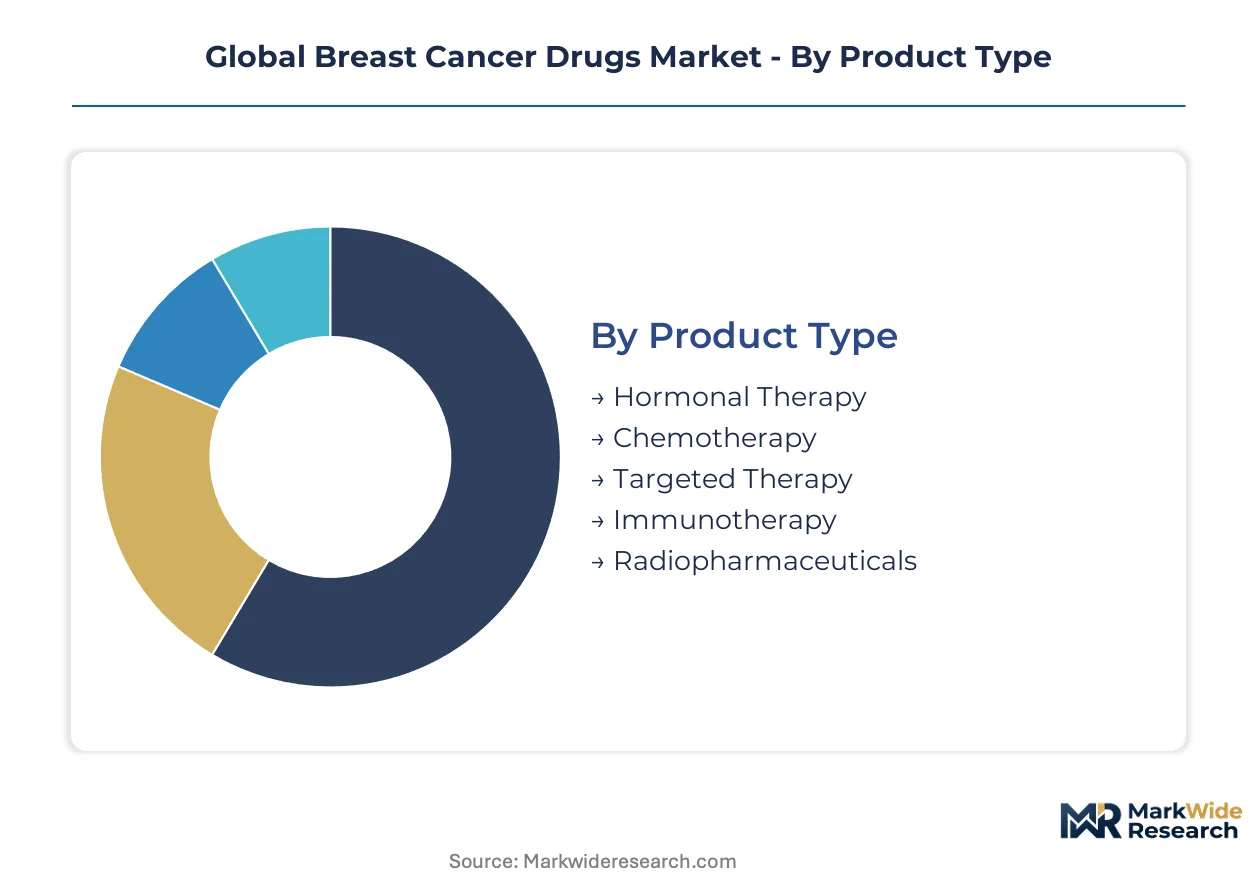
Segmentation in breast cancer therapeutics reveals how treatment paradigms fragment across molecular subtypes, care settings, and administration pathways. Each dimension carries distinct reimbursement logic and competitive entry barriers that shape portfolio prioritization.
Product Type:
Mature hormonal and cytotoxic platforms anchor volume while emerging modalities capture margin expansion.
- Targeted Therapy:Antibody-drug conjugates and CDK4/6 inhibitors deliver selective kinase inhibition with reduced off-target toxicity. United States academic medical centers concentrate adoption where companion diagnostic mandates lock prescribing to biomarker-verified populations.
- Immunotherapy:Checkpoint inhibitors targeting PD-L1/PD-1 axes activate anti-tumor immunity in microsatellite-unstable subsets. Germany's EMA-aligned reimbursement infrastructure accelerates access for triple-negative indications where chemotherapy resistance limits alternatives.
- Hormonal Therapy:SERMs and aromatase inhibitors modulate estrogen receptor signaling in HR-positive disease lines.
- Chemotherapy:Taxane and anthracycline regimens retain first-line utility in resource-constrained settings.
- Radiopharmaceuticals:Alpha-emitting isotopes target bone-metastatic lesions with localized cytotoxic payload delivery.
Targeted therapy handles the majority of throughput; immunotherapy is the fastest mover on share.
Therapy Area:
Clinical staging and receptor status stratify addressable populations across curative-intent and palliative segments.
- HER2-Positive:Amplified ERBB2 signaling drives aggressive proliferation addressable through monoclonal antibody and tyrosine kinase inhibitor combinations. Japan's PMDA sakigake designation compresses review timelines for brain-penetrant small molecules in CNS-metastatic settings.
- Triple-Negative:Absence of hormone receptor and HER2 expression eliminates targeted options, leaving chemotherapy and immunotherapy as primary modalities. United States community oncology practices concentrate trial enrollment where FDA accelerated approval pathways reward biomarker-defined subsets.
- Early Stage:Neoadjuvant and adjuvant protocols prioritize cure over chronic management.
- Metastatic:Systemic therapy focuses on progression-free survival extension and quality-of-life preservation.
- Ductal Carcinoma In Situ:Pre-invasive lesions drive active surveillance versus intervention debates.
Metastatic settings dominate prescription volume; triple-negative indications are climbing the fastest on pipeline investment.
End User:
Care delivery fragmentation creates distinct procurement and protocol standardization requirements across institutional types.
- Oncology Centers:Comprehensive cancer centers integrate medical, surgical, and radiation oncology with centralized pharmacy compounding. Germany's university hospital networks concentrate Phase I trial access where EMA adaptive licensing frameworks reward early evidence generation.
- Specialty Clinics:Community-based hematology-oncology practices manage chronic therapy administration with limited inpatient capacity. United States integrated delivery networks negotiate indication-specific value-based contracts that tie reimbursement to progression-free survival benchmarks.
- Diagnostic Laboratories:Centralized pathology and molecular testing services determine therapy eligibility through companion diagnostic workflows.
- Cancer Research Institutes:Academic centers conduct translational studies bridging preclinical discovery to clinical validation.
Oncology centers absorb the majority of infused therapy administration; specialty clinics are expanding most quickly on oral agent dispensing.
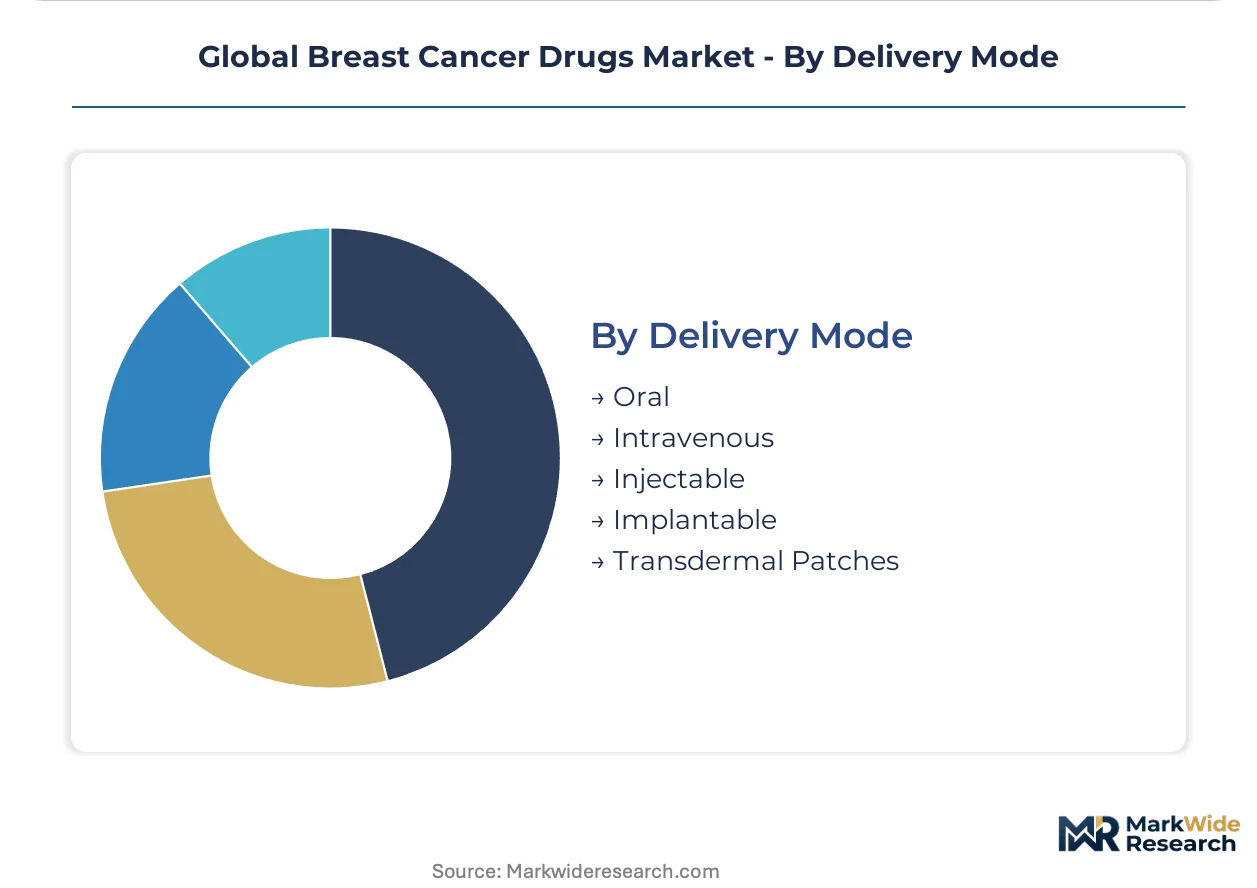
Delivery Mode:
Administration route determines site-of-care requirements, cold chain infrastructure, and patient adherence profiles.
- Intravenous:Infusion-dependent biologics require healthcare facility administration with nursing supervision and adverse event monitoring. Japan's hospital-based reimbursement system concentrates monoclonal antibody delivery within accredited cancer centers with validated cold chain networks.
- Oral:Small-molecule kinase inhibitors enable outpatient self-administration with reduced healthcare utilization. United States specialty pharmacy channels manage prior authorization and adherence monitoring for CDK4/6 inhibitors in HR-positive maintenance settings.
- Injectable:Subcutaneous formulations reduce infusion chair time while retaining healthcare professional oversight.
- Implantable:Depot formulations extend dosing intervals for hormonal therapy compliance.
- Transdermal Patches:Non-invasive delivery alternatives address needle aversion and bioavailability optimization.
Intravenous administration handles the majority of biologic therapy throughput; oral routes are gaining share fastest on patient convenience and site-of-care cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for active pharmaceutical ingredients concentrate manufacturing capacity in Asian contract manufacturers while finished biologics flow toward high-reimbursement Western markets. The United States maintains a structural deficit in antibody-drug conjugate production, sourcing linker-payload intermediates from offshore suppliers. Germany and Switzerland anchor European formulation capacity, though Japan's PMDA sakigake designation is redirecting some clinical trial investment toward domestic development.
United States
FDA accelerated approval pathways compress Phase II-to-commercialization timelines for biomarker-defined subsets, rewarding sponsors with conditional market entry. The Inflation Reduction Act's Medicare price negotiation provisions reshape revenue forecasting for oncology assets reaching loss-of-exclusivity thresholds. Boston-Cambridge and San Diego biotech clusters concentrate antibody-drug conjugate discovery, with Massachusetts General Hospital anchoring neoadjuvant trial networks.
Germany
EMA adaptive licensing frameworks enable early conditional access contingent on post-authorization evidence generation, compressing protocol approval timelines across member states. The country's statutory health insurance system maintains premium reimbursement for companion diagnostic-verified therapies, locking prescribing to assay-confirmed populations. Heidelberg and Munich university hospital networks concentrate Phase I oncology access, with German Cancer Research Center anchoring translational programs.
Japan
PMDA's sakigake designation system reduces regulatory lag for innovative oncology assets, prioritizing review timelines for sponsors conducting bridging studies in Japanese patient populations. The country's hospital-based reimbursement infrastructure concentrates monoclonal antibody delivery within accredited cancer centers with validated cold chain networks. Tokyo and Osaka metropolitan areas anchor biopharma manufacturing, with National Cancer Center Hospital East driving biomarker-driven trial enrollment.
India
CDSCO's New Drugs and Clinical Trials Act streamlines oncology protocol approvals for multinational sponsors, reducing procedural divergence from ICH-GCP standards. The country's contract manufacturing infrastructure supplies active pharmaceutical ingredients for antibody-drug conjugate linkers and cytotoxic payloads to Western formulators. Hyderabad and Bangalore clusters concentrate biologics manufacturing, with Dr. Reddy's Laboratories and Biocon anchoring biosimilar development capabilities.
Switzerland
Swissmedic's reliance procedure enables rapid market access for EMA-approved oncology therapies, compressing national authorization timelines. The country's premium pricing environment supports orphan drug and targeted therapy commercialization, with mandatory health insurance covering innovative biologics. Basel anchors global oncology headquarters concentration, with Roche and Novartis research campuses driving HER2-directed and CDK4/6 inhibitor pipeline investment.
Global Breast Cancer Drugs Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying linker technologies, payload chemistries, and companion diagnostic assays. The market structures around three tiers: large-cap pharmaceutical conglomerates with entrenched oncology franchises, mid-cap biotech firms with single-asset platforms, and specialized contract development organizations capturing manufacturing margin. Dominant competitive moves include antibody-drug conjugate pipeline acquisitions and companion diagnostic co-development partnerships that lock prescribing behavior.
Among Swiss-headquartered conglomerates, F. Hoffmann-La Roche Ltd and Novartis AG occupy positions defined by HER2-directed and CDK4/6 inhibitor portfolio depth. Pfizer Inc. represents the manufacturing-scale archetype, leveraging production volume to command preferential formulary placement. These entities exemplify how platform breadth and geographic diversification anchor competitive positioning in biomarker-defined oncology segments.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| AstraZeneca |
| Novartis AG |
| Eli Lilly and Company |
| Merck & Co., Inc. |
| Sanofi |
| Bristol-Myers Squibb Company |
| AbbVie Inc. |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's freight cost volatility transmits directly into antibody-drug conjugate landed costs, amplifying margin compression for European formulators while enabling Indian and Chinese API suppliers to extract differential pricing power through supply concentration.
Pricing Analysis
Industrial OEM buyers anchor a value-based pricing structure calibrated to progression-free survival benchmarks in United States integrated delivery networks. Pricing stratifies across premium biologics with companion diagnostic mandates, standard CDK4/6 inhibitor maintenance regimens, and economy-tier cytotoxic backbones in resource-constrained settings. Cost compression in the cytotoxic tier intensifies as biosimilar penetration accelerates, while academic medical centers demonstrate lowest price sensitivity due to formulary autonomy.
Supply Chain Analysis
Extended payment terms from European formulators to Indian contract manufacturers now stretch 90-120 days, straining working capital for Hyderabad and Bangalore API clusters. Active pharmaceutical ingredient manufacturing concentrates in India, China, and Switzerland, with linker-payload chemistry drawing from Chinese fine chemical specialists and German precision synthesis houses. Single-source vulnerability in cleavable linker technologies exposes continuity risk. Distribution runs through hospital-based specialty pharmacy channels in Japan and United States integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing-scale antibody-drug conjugate capacity represents the binding constraint across the forecast horizon, with linker-payload engineering expertise concentrated in fewer than a dozen global facilities.
For Market Incumbents: Harden supply continuity through captive linker manufacturing investments in Basel and Boston-Cambridge clusters, while locking long-term offtake agreements with Indian API suppliers before CDMO consolidation accelerates. FDA accelerated approval pathway competition from mid-cap biotech firms threatens first-mover advantage in HER2-low indications. For New Entrants and Emerging Players: Brain-metastatic subsets in HER2-positive disease represent the most penetrable entry point, given tucatinib's established CNS-penetrant template and underserved patient populations in Japanese and German academic centers. Japan PMDA sakigake designation offers regulatory fast-tracking for sponsors conducting bridging studies. Partner with National Cancer Center Hospital East for biomarker-driven trial enrollment. For Investors and Strategic Acquirers: Mid-cap biotech firms with Phase II-ready antibody-drug conjugate assets and established companion diagnostic partnerships command scarcity premia in acquisition markets. Long-term viability hinges on pipeline durability beyond first-generation HER2 and CDK4/6 inhibitor franchises. Watch EMA adaptive licensing framework expansion as signal for European market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Locks prescribing behavior to assay-verified populations in United States academic medical centers. |
| Antibody-Drug Conjugate Manufacturing Scale-Up | Captures margin from linker-payload supply concentration in Indian and Chinese contract manufacturers. |
| Brain Metastasis Indication Expansion | Opens addressable populations in HER2-positive CNS-metastatic settings following tucatinib's precedent. |
| Japan PMDA Sakigake Pathway Utilization | Compresses regulatory lag for innovative oncology assets through priority review designation. |
| Real-World Evidence Generation Partnership | Supports EMA adaptive licensing post-authorization requirements through registry infrastructure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across this study, combining structured interviews with drug development executives, regulatory affairs leads, formulary directors at United States integrated delivery networks, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market sizing.
Calibration against historical approval velocity and reimbursement decision timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include molecular subtype, therapy line, administration route, and regional regulatory cluster. CAGRs were derived from indication-level patient population forecasts, pricing trajectory assumptions, and pipeline probability-adjusted revenue contributions.
Macroeconomic conditions sit as an overlay; deviation in exchange rate volatility, healthcare expenditure growth, or biopharma M&A liquidity would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway success rates and companion diagnostic adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Ewing Sarcoma Drugs Market
Biopharmaceuticals
India Insulin Drug and Delivery Device Market
Biopharmaceuticals
Triclabendazole Market
Biopharmaceuticals
Human Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Hemophilia B Market
Biopharmaceuticals
Recombinant Hormone Market
Biopharmaceuticals
US Generic Drug Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Cephalosporin Market
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market
Biopharmaceuticals
Global Endocrinology Drugs Market
Biopharmaceuticals
Recombinant Erythropoietin Market
Biopharmaceuticals
Insulin Market