
 Recombinant Proteins Manufacturing Services Market | 2026-2036
Recombinant Proteins Manufacturing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Recombinant Proteins Manufacturing Services Market Analytics
The gap between premium mammalian cell culture services and commodity microbial fermentation offerings is expanding as sponsor demands for complex glycosylation profiles diverge from high-volume enzyme production. Lonza leverages its Switzerland-based biologics network to anchor large-scale mammalian capacity for monoclonal antibody programs. Thermo Fisher Scientific competes through integrated upstream and downstream tooling that extends across viral vector and protein workflows. GenScript specializes in gene-to-protein custom synthesis, occupying a niche between discovery-scale and GMP manufacturing.
Recombinant proteins manufacturing services encompass the contract production of proteins encoded by recombinant DNA, typically expressed in bacterial, yeast, insect, or mammalian host systems with post-translational modification capabilities critical for therapeutic function. These services supply material for clinical trials, commercial biologics, and diagnostic reagents where consistency, purity, and regulatory documentation determine usability. Monoclonal antibodies command the largest value share among product types due to their structural complexity and the specialized bioreactor infrastructure required for faithful glycoprotein expression. Cell culture technology leads in revenue contribution while chromatography purification steps represent the fastest-improving margin pool as resin innovations reduce downstream bottleneck costs. Pharmaceutical companies constitute the dominant end-user segment, though biotechnology firms represent the fastest-growing customer category as virtual development models proliferate.
FDA enforces current Good Manufacturing Practice standards through pre-approval inspections that shape facility design and quality management system investments across US-based service providers. EMA's Good Manufacturing Practice guidelines and the EU's Annex 1 revision for sterile manufacturing impose comparable containment and validation burdens on European operations, while China's NMPA accelerates alignment with ICH Q5A through updated biologics technical guidelines. Manufacturers must monitor how regulatory convergence on continuous manufacturing and real-time release testing reshapes capital deployment timelines and partnership structures.
Market Dynamics
Biopharmaceutical sponsors are fragmenting their supplier base across discovery, clinical, and commercial phases, forcing contract manufacturers to defend position through specialized platform investments rather than scale alone. This structural unbundling rewards providers with dedicated mammalian cell culture suites and modular single-use bioreactor configurations.
Growth Catalysts
- ICH Q5A alignment:China's NMPA adoption of viral safety guidelines accelerates international multi-site trial material supply from domestic CDMOs.
- Microbiome therapeutics:Engineered recombinant proteins for gut-targeted biologics create demand for anaerobic fermentation capacity in specialized contract facilities.
- Basel-Zurich corridor:Switzerland's clustered biologics infrastructure concentrates mammalian cell culture expertise and attracts sponsor co-location.
Market Restraints
- Plasma-derived protein competition:Established fractionation infrastructure for albumin and immunoglobulin limits recombinant substitution in cost-sensitive therapeutic categories.
- Chinese heparin supply concentration:Raw material dependence on a limited geographic base for certain glycoprotein production creates input vulnerability.
- FDA pre-approval inspection backlog:Extended facility clearance timelines delay commercial manufacturing transfers and compress revenue recognition windows.
Strategic Opportunities
- Continuous manufacturing:Real-time release testing frameworks under FDA's emerging guidance enable smaller-footprint facilities with faster batch turnover.
- Cell-free protein synthesis:Convergence of synthetic biology and in vitro translation systems opens toxic or unstable protein categories previously excluded from microbial hosts.
- India's PLI scheme:Production-linked incentives for biologics manufacturing attract contract service investment in Hyderabad and Bengaluru clusters.
Industry Challenges
- Process analytical technology integration:Legacy quality control laboratories resist real-time spectroscopic monitoring adoption, creating validation bottlenecks.
- Platform process scientist scarcity:Specialized expertise in clone selection and media optimization commands premium compensation, constraining facility expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recombinant Proteins Manufacturing Services Market |
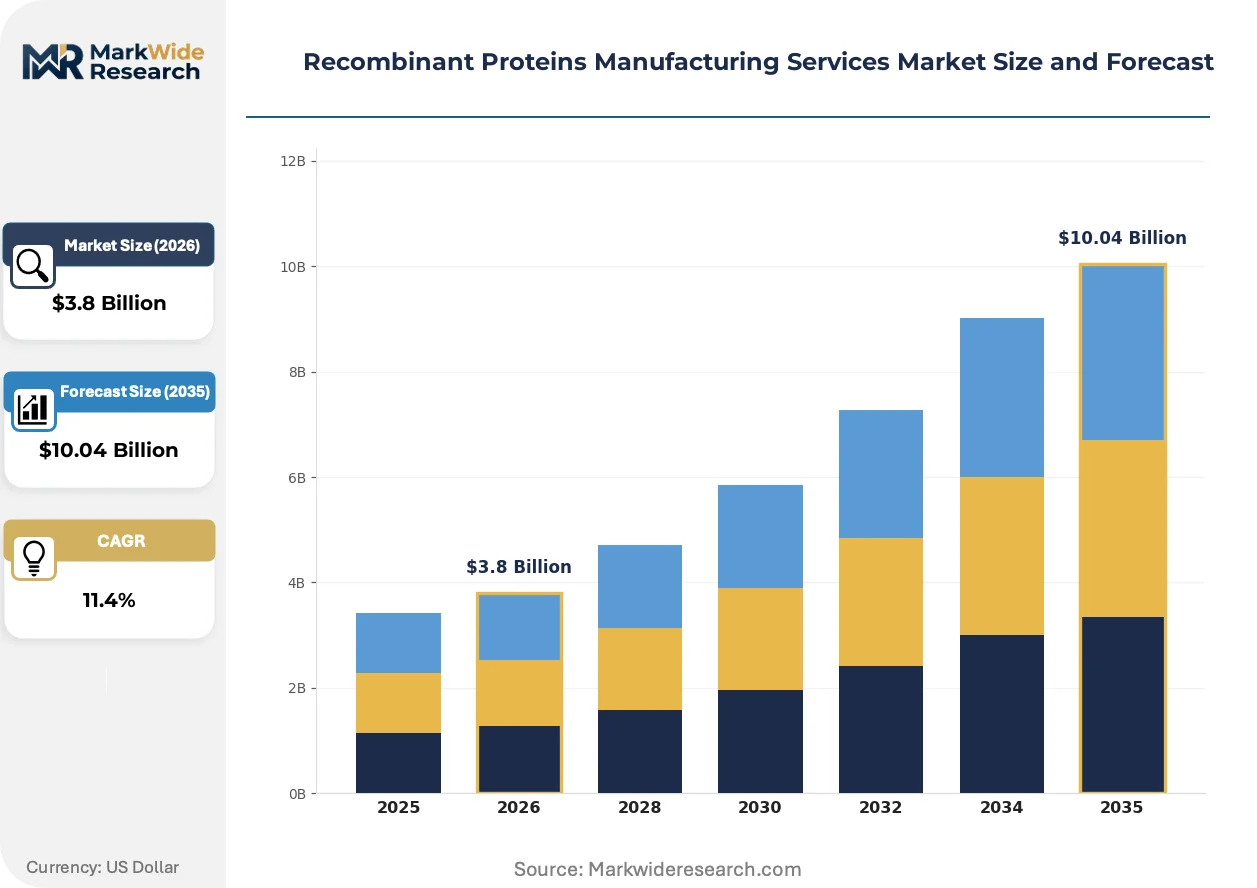
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Cytokines, Enzymes Technology: Transfection, Fermentation, Cell Culture, Chromatography End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Manufacturers Application: Therapeutics, Diagnostics, Research, Drug Development |
| Companies Covered | Lonza, Boehringer Ingelheim International GmbH, FUJIFILM Diosynth Biotechnologies, Merck KGaA, Sino Biological, GenScript, Bruker, Thermo Fisher Scientific, Bio-Techne, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recombinant Proteins Manufacturing Services Market Evolving Landscape
Single-use technologies are compressing facility construction timelines and enabling rapid product changeover, while regulatory convergence on continuous processing is redrawing capital deployment strategies across the contract manufacturing base.
Perfusion bioreactor systems are absorbing upstream capacity investments previously directed toward fed-batch stainless steel trains. Mid-sized biopharma sponsors are adopting these platforms for Phase III material supply to preserve flexibility. The technology is absorbing market share from conventional batch processes by reducing facility footprint requirements and enabling higher cell density expression.
EMA's Annex 1 revision on sterile manufacturing mandates stricter containment for multi-product facilities. European CDMOs are segregating viral and non-viral product suites to preempt inspection findings. Mammalian cell culture operations face the steepest compliance costs due to live-virus handling protocols and cross-contamination prevention requirements.
Virtual biotech developers are unbundling analytical method development from manufacturing contracts. These sponsors retain CMC expertise in-house while outsourcing production to multiple regional providers. The pattern concentrates in the United States where capital markets fund asset-light development models and distributed supply networks reduce single-source risk.
Recombinant Proteins Manufacturing Services Market Segmentation
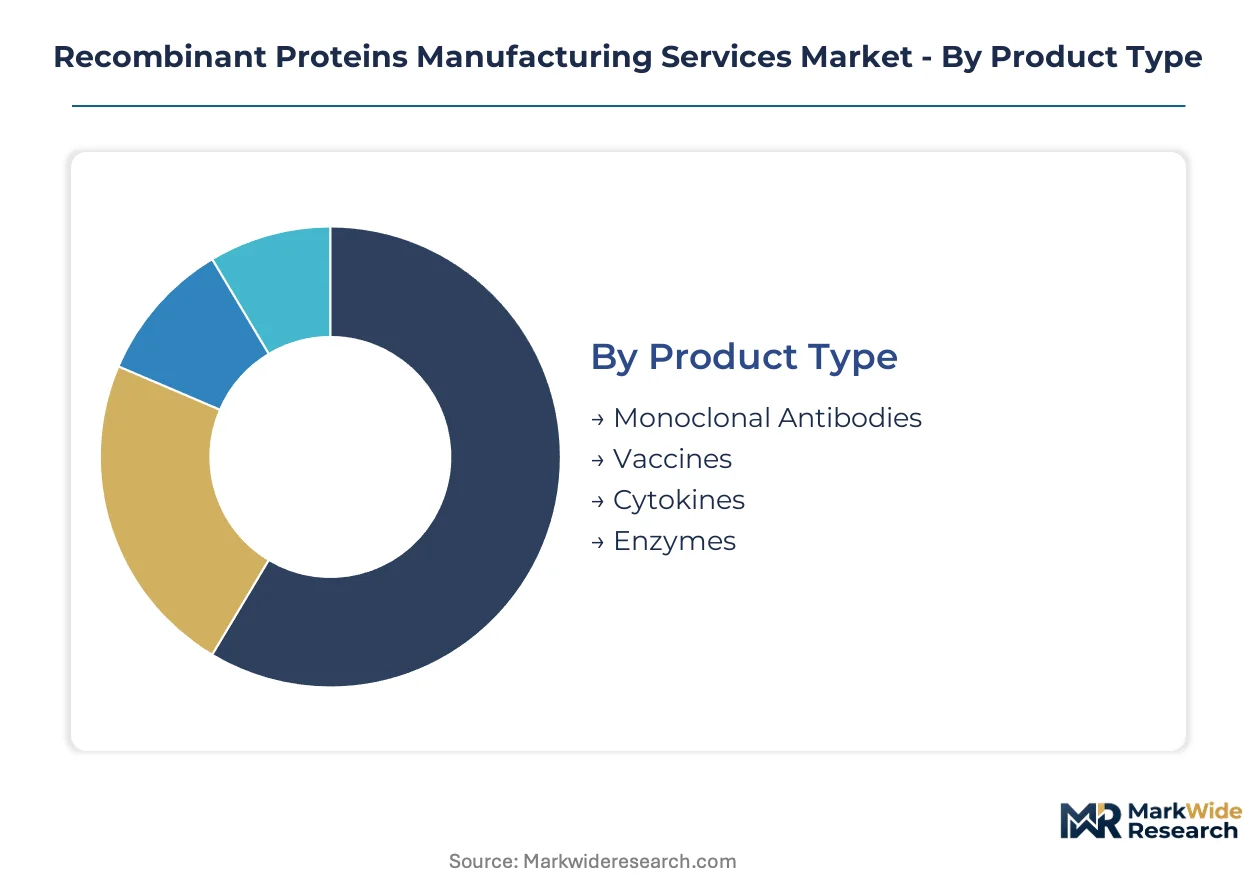
Recombinant protein manufacturing services fragment across multiple technical and commercial dimensions. Each segmentation axis reveals distinct capital requirements, customer concentration patterns, and margin structures that shape provider strategy.
Product Type:
Capital intensity varies sharply across product categories, with glycosylated biologics demanding specialized bioreactor infrastructure that microbial systems cannot replicate.
- Monoclonal Antibodies:Complex immunoglobulins requiring mammalian cell culture platforms with faithful glycosylation machinery. Demand concentrates among large pharmaceutical sponsors in the United States and Switzerland where clustered biologics infrastructure supports scale-up capacity for Phase III and commercial supply.
- Vaccines:Recombinant subunit and virus-like particle formulations spanning bacterial, yeast, and mammalian expression systems. Biotechnology firms in Germany and China drive contract uptake as these sponsors lack internal manufacturing assets for pandemic preparedness programs.
- Cytokines:Signaling proteins with stringent purity requirements for immunotherapy applications.
- Enzymes:Industrial and therapeutic catalysts typically produced through high-yield microbial fermentation.
Monoclonal antibodies absorb the bulk of installed capacity; cytokines are expanding most quickly as cell therapy adjuvants proliferate.
Technology:
Platform selection determines facility footprint, regulatory pathway complexity, and the skill intensity of operational staff.
- Cell Culture:Mammalian and insect host systems enabling post-translational modifications essential for therapeutic function. Pharmaceutical companies in the United States dominate demand as FDA pre-approval inspections enforce current Good Manufacturing Practice standards that favor established contract providers with quality management system investments.
- Chromatography:Purification workflows representing the fastest-improving margin pool as resin innovations reduce downstream bottleneck costs. Biotechnology firms across multiple geographies outsource these steps to specialists with integrated analytical method development capabilities.
- Fermentation:Microbial and yeast-based production platforms for non-glycosylated proteins.
- Transfection:Gene delivery methods establishing expression cell lines for subsequent manufacturing campaigns.
Cell culture commands the largest revenue contribution; chromatography is climbing the fastest as continuous processing adoption accelerates.
End User:
Customer type dictates contract structure, with virtual development models fragmenting supplier relationships across clinical phases.
- Pharmaceutical Companies:Large sponsors with internal manufacturing assets that outsource overflow capacity and specialized modalities. Demand concentrates in the United States where capital markets fund asset-light development models and distributed supply networks reduce single-source risk.
- Biotechnology Firms:Virtual developers representing the fastest-growing customer category as these sponsors retain chemistry, manufacturing, and controls expertise in-house while outsourcing production to multiple regional providers.
- Academic Institutions:Research-scale requirements for discovery biology and preclinical validation.
- Contract Manufacturers:Subcontracting arrangements where primary CDMOs leverage specialized partners for capacity or technology gaps.
Pharmaceutical companies anchor contract value; biotechnology firms are gaining share fastest as virtual development models proliferate.
Application:
End-use destination shapes regulatory documentation burden and batch release timeline requirements.
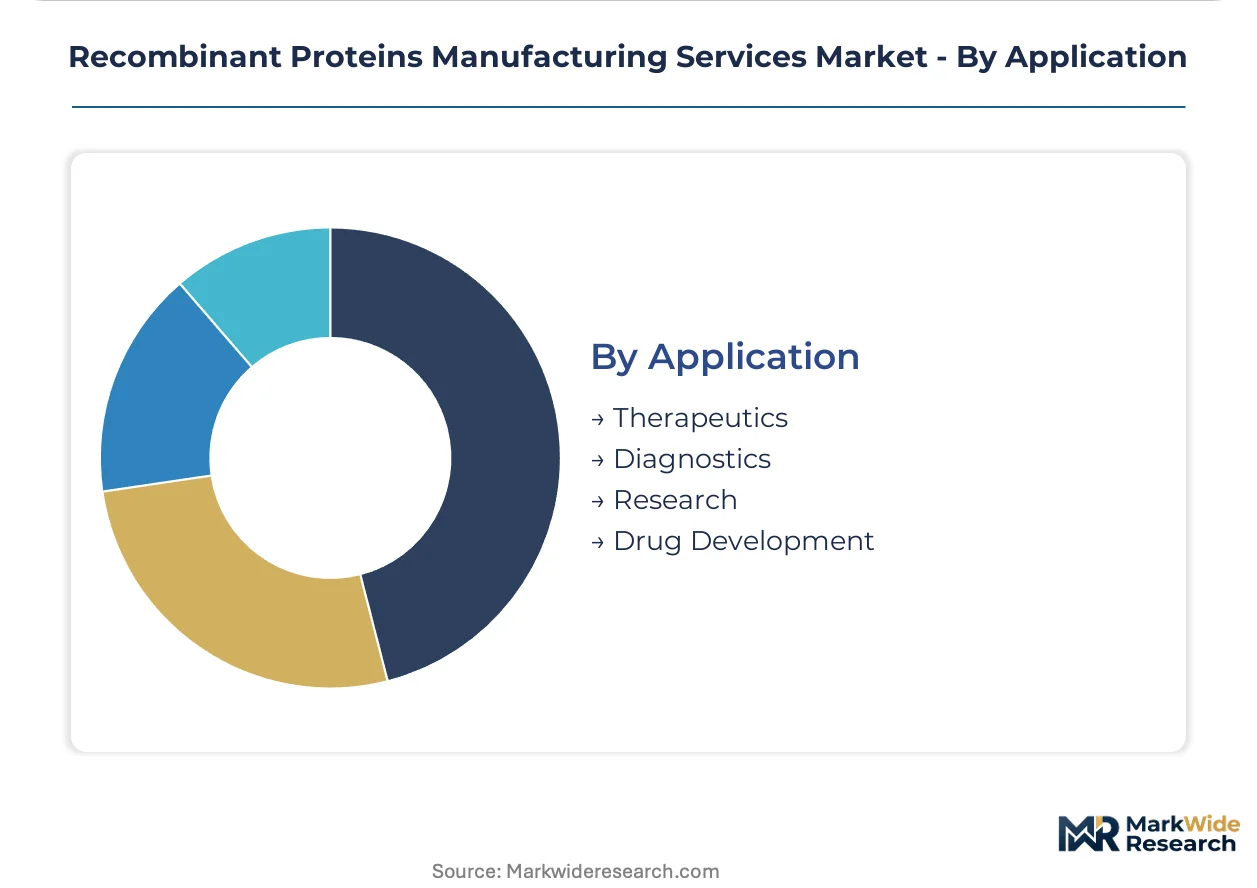
- Therapeutics:Clinical and commercial biologics subject to FDA, EMA, and NMPA validation requirements. Pharmaceutical companies in Germany and China drive service uptake as these sponsors outsource complex protein production to access specialized mammalian cell culture platforms.
- Drug Development:Clinical trial material supply requiring rapid turnaround and flexible batch sizing. Biotechnology firms in the United States concentrate demand here as capital markets fund accelerated development timelines.
- Diagnostics:Reagent-grade proteins for assay development and reference standard production.
- Research:Discovery-scale material with reduced documentation requirements.
Therapeutics absorb the bulk of quality system investment; drug development is expanding most quickly as Phase III pipeline density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Basel-Zurich corridor anchors contract manufacturing capacity for complex glycoproteins, drawing sponsor co-location through clustered biologics infrastructure and Swissmedic regulatory alignment with FDA and EMA standards.
United States
Large pharmaceutical sponsors in Massachusetts and North Carolina drive demand for Phase III and commercial mammalian cell culture capacity. FDA pre-approval inspections enforce current Good Manufacturing Practice standards that favor established contract providers with quality management system investments. The Greater Boston and Research Triangle Park clusters concentrate mammalian expertise and attract biopharma co-location.
Germany
Biotechnology firms in Munich and Heidelberg outsource recombinant protein production for pandemic preparedness and cell therapy programs. EMA's Annex 1 revision on sterile manufacturing mandates stricter containment for multi-product facilities, elevating compliance costs for European CDMOs. The country's central biologics corridor links academic research hospitals with contract manufacturing infrastructure.
China
Domestic CDMOs in Shanghai and Suzhou accelerate international multi-site trial material supply as NMPA adopts ICH Q5A viral safety guidelines. Biotechnology sponsors in Beijing and Hangzhou drive contract uptake for recombinant subunit vaccines and virus-like particle formulations. The Yangtze River Delta cluster concentrates mammalian cell culture scale-up capacity for export markets.
Switzerland
The Basel-Zurich corridor concentrates mammalian cell culture expertise through Lonza's biologics network and specialized infrastructure for monoclonal antibody programs. Swissmedic alignment with FDA and EMA standards enables seamless multi-regional trial material supply. Sponsor co-location patterns reinforce the corridor's position for large-scale commercial manufacturing transfers.
India
Hyderabad and Bengaluru clusters attract contract service investment through the Production-Linked Incentive scheme for biologics manufacturing. CDSCO regulatory pathways for biosimilars create demand for microbial fermentation capacity in cost-sensitive therapeutic categories. Domestic biotechnology sponsors retain chemistry, manufacturing, and controls expertise in-house while outsourcing production to regional providers.
Recombinant Proteins Manufacturing Services Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered vendor base where facility ownership separates commercial-scale manufacturers from discovery-scale specialists. The market structure concentrates around three strategic archetypes: integrated life science conglomerates with end-to-end tool portfolios, pure-play CDMOs with dedicated mammalian cell culture suites, and gene-to-protein custom synthesis specialists occupying niches between discovery and GMP manufacturing. Dominant competitive moves include capacity expansion in clustered biologics corridors and strategic partnerships that unbundle analytical method development from manufacturing contracts.
Among Switzerland-based biologics specialists, Lonza anchors large-scale mammalian capacity for monoclonal antibody programs through its Basel-Zurich corridor network. Thermo Fisher Scientific exemplifies the integrated conglomerate archetype with upstream and downstream tooling extending across viral vector and protein workflows. GenScript occupies a position between discovery-scale and GMP manufacturing, representing the gene-to-protein custom synthesis specialist tier that serves virtual biotechnology developers.
| Leading Market Players |
|---|
| Lonza |
| Boehringer Ingelheim International GmbH |
| FUJIFILM Diosynth Biotechnologies |
| Merck KGaA |
| Sino Biological |
| GenScript |
| Bruker |
| Thermo Fisher Scientific |
| Bio-Techne |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up CDMO specialists anchor capacity ownership across the Basel-Zurich corridor and Greater Boston clusters, translating concentrated facility control into disciplined pricing power while microbial fermentation commoditization in India compresses margins at the standard tier.
Pricing Analysis
Yield-based pricing anchors mammalian cell culture contracts, with sponsors paying premium rates for faithful glycosylation profiles that microbial systems cannot replicate. Three-tier pricing structure across premium GMP-certified, standard clinical-grade, and economy research-grade levels separates monoclonal antibody campaigns from cytokine production. Pricing pressure stems from sponsor unbundling of analytical services and distributed multi-site sourcing strategies. Biotechnology firms exhibit highest price sensitivity as virtual developers fragment spend across regional providers, while large pharmaceutical sponsors absorb premium tier costs for commercial-scale antibody supply.
Supply Chain Analysis
Domestic-content mandates under China's NMPA biologics guidelines and India's PLI scheme are reshaping sourcing patterns toward regional fermentation capacity and local chromatography resin production. Critical inputs draw from Chinese heparin suppliers, Swiss cell culture media formulators, and German chromatography equipment manufacturers. Single-source vulnerability concentrates in glycosylation-critical raw materials where geographic concentration creates input disruption risk. Distribution runs through sponsor-co-located CDMO partnerships rather than spot-market procurement, with long-term manufacturing agreements locking in capacity allocation across clinical phases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recombinant proteins manufacturing services market sits in a platform-transition phase as perfusion bioreactor systems displace fed-batch stainless steel infrastructure across Phase III material supply.
For Market Incumbents: Deploy continuous manufacturing platform investments to preempt regulatory convergence on real-time release testing frameworks. Add perfusion capacity in the Basel-Zurich corridor to defend against sponsor co-location drift toward lower-cost Asian clusters. Backward integration into single-use consumables mitigates supply disruption exposure from resin and membrane vendors. For New Entrants and Emerging Players: Enter via anaerobic fermentation specialization for microbiome therapeutic proteins, a white-space category underserved by mammalian-focused incumbents. Target CDSCO-regulated biosimilar production in Hyderabad and Bengaluru where PLI incentives offset capital intensity. Lead with gene-to-protein custom synthesis for virtual biotechnology developers retaining CMC expertise in-house. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap CDMOs with validated mammalian suites in Switzerland and Germany facing temporary FDA pre-approval inspection delays. Long-term viability hinges on continuous processing adoption curves and sponsor consolidation of distributed supplier networks. Watch NMPA ICH Q5A implementation velocity as inflection indicator for Chinese CDMO export competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | FDA emerging guidance on real-time release testing enables smaller-footprint facilities with faster batch turnover. |
| Perfusion Bioreactor Capacity Expansion | Mid-sized biopharma sponsors adopt these platforms for Phase III material supply to preserve manufacturing flexibility. |
| Analytical Method Development Unbundling | Virtual biotech developers retain CMC expertise in-house while outsourcing production to multiple regional providers. |
| Cell-Free Protein Synthesis Investment | Synthetic biology convergence opens toxic or unstable protein categories previously excluded from microbial hosts. |
| Domestic CDMO Capacity Buildout | India's PLI scheme attracts contract service investment in Hyderabad and Bengaluru biologics clusters. |
Research Methodology
Document review covered FDA pre-approval inspection records, EMA GMP certification databases, and NMPA biologics technical guidelines, complemented by interviews with contract manufacturing executives, regulatory affairs leads at biopharmaceutical sponsors, platform process scientists, and procurement managers at virtual biotechnology firms. Secondary validation drew from SEC 10-K filings, clinical trial manufacturing agreements, and customs trade data for chromatography resin imports. Bottom-up capacity modeling triangulated against top-down sponsor spend estimates.
Historical capacity utilization rates cross-referenced against expert panel input on perfusion adoption timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled included product glycosylation complexity, host system selection, clinical phase requirements, and regional regulatory cluster alignment. CAGRs derived from facility expansion announcements, sponsor pipeline density, and quality system investment trajectories. Industry-specific inputs captured EMA Annex 1 revision compliance costs and ICH Q5A alignment progress.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA pre-approval inspection backlog extension or sudden heparin supply disruption scenarios. Forecasts reflect assumptions on regulatory convergence velocity and sponsor outsourcing propensity without claiming predictive certainty. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Serine Protease Market
Biotechnology Services
Industrial Microbiology Testing Services Market
Biotechnology Services
Aptamers Market
Biotechnology Services
Proteinase K Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Bioanalytical Testing Services Market
Biotechnology Services
Global Qpcr Reagents Market
Biotechnology Services
Antibody Drug Conjugates Contract Manufacturing Market
Biotechnology Services
Global Western Blotting Market
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
Biotech API Manufacturing Services Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
GMO Testing Services Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Monoclonal Antibody Custom Service Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market