
 Asia-Pacific Stem Cell Therapy Market | 2026-2036
Asia-Pacific Stem Cell Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Stem Cell Therapy Market Outlook
Buyer concentration among hospital networks across South Korea and Japan is repositioning procurement standards toward autologous and allogeneic cell sourcing. MEDIPOST anchors South Korean supply through vertically integrated cord blood banking and therapeutic development. JW Therapeutics (Shanghai) Co., Ltd. dominates CAR-T and stem cell engineering within China's regulatory sandbox framework. Kolon TissueGene, Inc. differentiates through orthopedic gene-therapy hybrids targeting osteoarthritis segments.
Stem cell therapy deploys living, self-renewing progenitor cells derived from bone marrow, adipose tissue, umbilical cord blood, or reprogrammed somatic sources, expanded ex vivo under GMP conditions and delivered via injection, infusion, or transplantation to regenerate damaged tissue or modulate immune response. Mesenchymal stem cells occupy the largest product-type position due to established manufacturing protocols and lower tumorigenic risk profiles. Oncology leads application demand driven by hematopoietic stem cell transplantation protocols for leukemia and lymphoma, while neurology represents the fastest-growing segment as clinical trials advance for Parkinson's and stroke indications. Hospitals capture the dominant end-user channel share given the infrastructure requirements for cell handling and patient monitoring.
Japan's PMDA conditional approval framework under the Act on Regenerative Medicine Safety reshapes commercial timelines by permitting early market entry with post-marketing efficacy commitments. South Korea's MFDS and MFDS-coordinated biobank standards enforce donor traceability and quality benchmarks that filter market access. China's NMPA cell-therapy guidelines under SAMR oversight impose parallel IND and clinical trial application requirements that extend development cycles. Stakeholders must monitor divergence between national accelerated pathways and harmonized manufacturing standards to optimize portfolio sequencing across the region.
Market Dynamics
Japan's PMDA conditional approval framework compresses commercial timelines for regenerative therapies while fragmenting manufacturing standards across South Korea's MFDS-coordinated biobanks and China's NMPA dual-track IND requirements. Hospital procurement concentration in Seoul and Shanghai accelerates autologous sourcing protocols.
Growth Catalysts
- PMDA Accelerated Pathways:Japan's conditional approval mechanism under the Act on Regenerative Medicine Safety permits early market entry with post-marketing efficacy commitments, compressing development-to-revenue cycles for cell therapies.
- Oncology Center Procurement:China's tier-one hospital networks are consolidating stem cell transplantation protocols for hematologic malignancies, driving standardized autologous sourcing requirements.
- Adipose-Derived Processing:Automated closed-system bioreactors for mesenchymal stem cell expansion are reducing contamination risk and lot-to-lot variability, enabling scale-up for orthopedic and cardiovascular applications.
Market Restraints
- Donor Traceability Mandates:South Korea's MFDS biobank standards enforce exhaustive donor documentation and quality benchmarks that extend qualification timelines and inflate compliance overhead.
- Cold Chain Infrastructure Gaps:Temperature-controlled logistics for cryopreserved cell products remain concentrated in Tokyo, Seoul, and Shanghai corridors, limiting patient access in secondary cities.
- Allogeneic Immune Barriers:Histocompatibility matching requirements and graft-versus-host disease monitoring protocols constrain off-the-shelf product economics versus autologous alternatives.
Strategic Opportunities
- Neurology Trial Expansion:Parkinson's disease and ischemic stroke indications are advancing through Phase II protocols in Japan and Australia, opening addressable markets beyond oncology dominance.
- Induced Pluripotent Stem Cell Convergence:Integration of iPSC-derived cardiomyocyte platforms with CRISPR editing is enabling patient-specific disease modeling and reducing reliance on donor tissue variability.
- Shanghai Biotech Corridor Clustering:NMPA regulatory sandbox provisions for cell therapy innovation zones are attracting contract development and manufacturing organizations to Pudong and Zhangjiang hubs.
Industry Challenges
- GMP Facility Certification Bottlenecks:NMPA on-site inspections for cell therapy manufacturing sites are backlogged, delaying commercial launch timelines for domestic developers.
- Vector Supply Constraints:Lentiviral and adenoviral vector production capacity for CAR-T and gene-modified stem cell products is concentrated among limited contract manufacturers, creating raw material procurement risk.
- Cross-Border Sample Transfer Complexity:Divergent customs and biosafety protocols between Japan, South Korea, and China impede multi-center clinical trial execution and centralized manufacturing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Stem Cell Therapy Market |
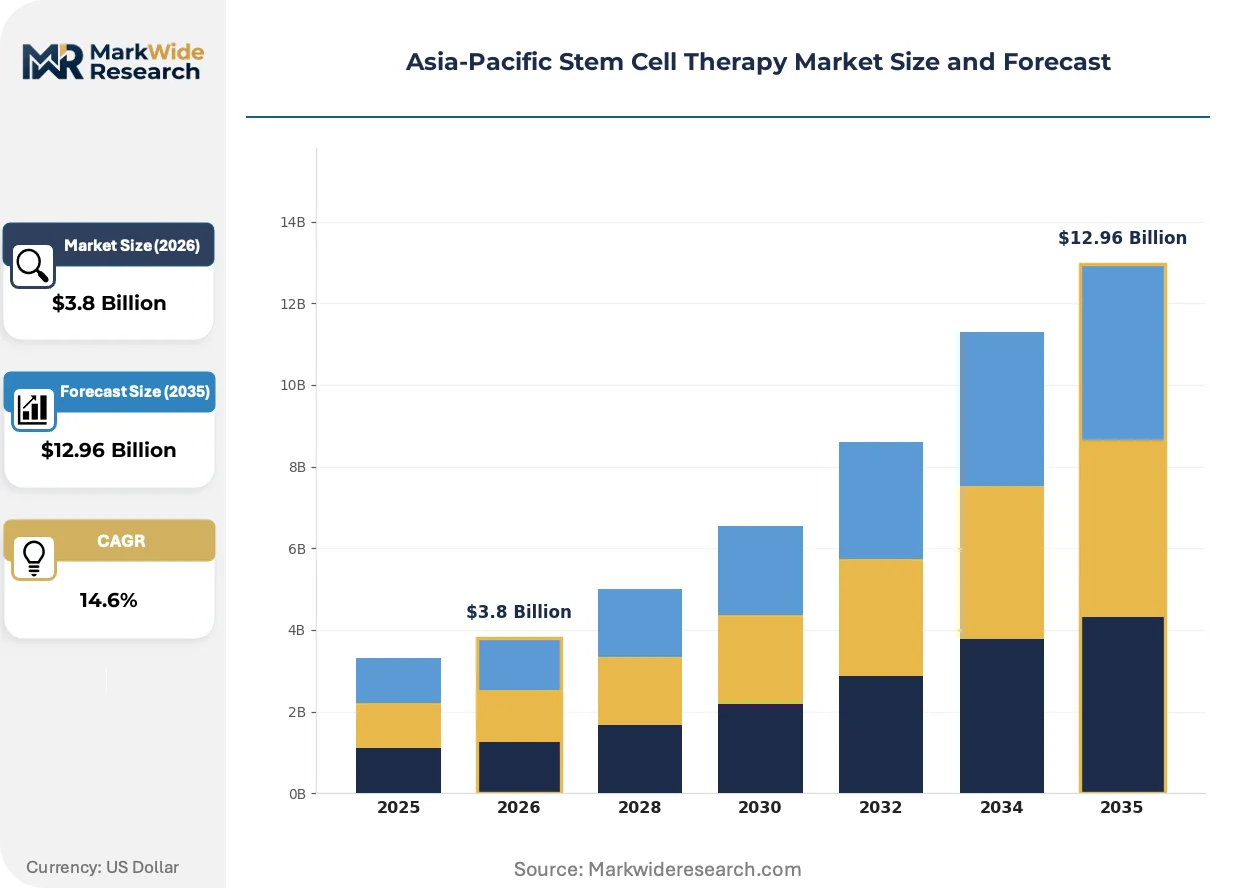
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Stem Cells, Embryonic Stem Cells, Induced Pluripotent Stem Cells, Mesenchymal Stem Cells Application: Oncology, Orthopedics, Neurology, Cardiovascular Delivery Mode: Injection, Infusion, Transplantation, Topical Application End User: Hospitals, Research Institutes, Clinics, Pharmaceutical Companies |
| Companies Covered | Kolon TissueGene, Inc., Curocell, Inc., MEDIPOST, Stempeutics Research Pvt. Ltd., JW Therapeutics (Shanghai) Co., Ltd., PHARMICELL Co., Ltd., JCR Pharmaceuticals Co., Ltd., Takara Holdings Inc, ANTEROGEN. CO., LTD, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Stem Cell Therapy Market Strategic Shifts
Manufacturing automation and regulatory pathway fragmentation are simultaneously compressing production costs and complicating geographic expansion strategies for cell therapy developers across the Asia-Pacific region.
Ex vivo expansion systems using perfusion bioreactors with integrated metabolite monitoring are expanding into commercial-scale production facilities. Seoul-based hospital networks and Shanghai CDMOs are adopting these platforms to reduce manual handling and improve lot consistency. The technology is expanding into smaller-batch personalized therapy manufacturing, enabling distributed production models that reduce centralized facility dependency.
Japan's Act on Regenerative Medicine Safety and PMDA conditional approval guidelines are creating a dual-track market entry system. Developers can secure revenue-generating commercial authorization with Phase II efficacy data, contingent on post-marketing confirmatory studies. Oncology and orthopedic segments are responding by front-loading Japan registration strategies ahead of South Korea MFDS or China NMPA full approvals.
Hospital procurement committees in tier-one Chinese cities are consolidating vendor relationships around vertically integrated suppliers with captive cord blood banking and in-house GMP processing capabilities. Regional distributors with cold chain expertise are displacing traditional pharmaceutical wholesalers in cell therapy logistics. This concentration is most visible in Beijing and Guangzhou, where provincial health authorities are mandating supplier qualification audits for stem cell transplantation programs.
Asia-Pacific Stem Cell Therapy Market Segmentation
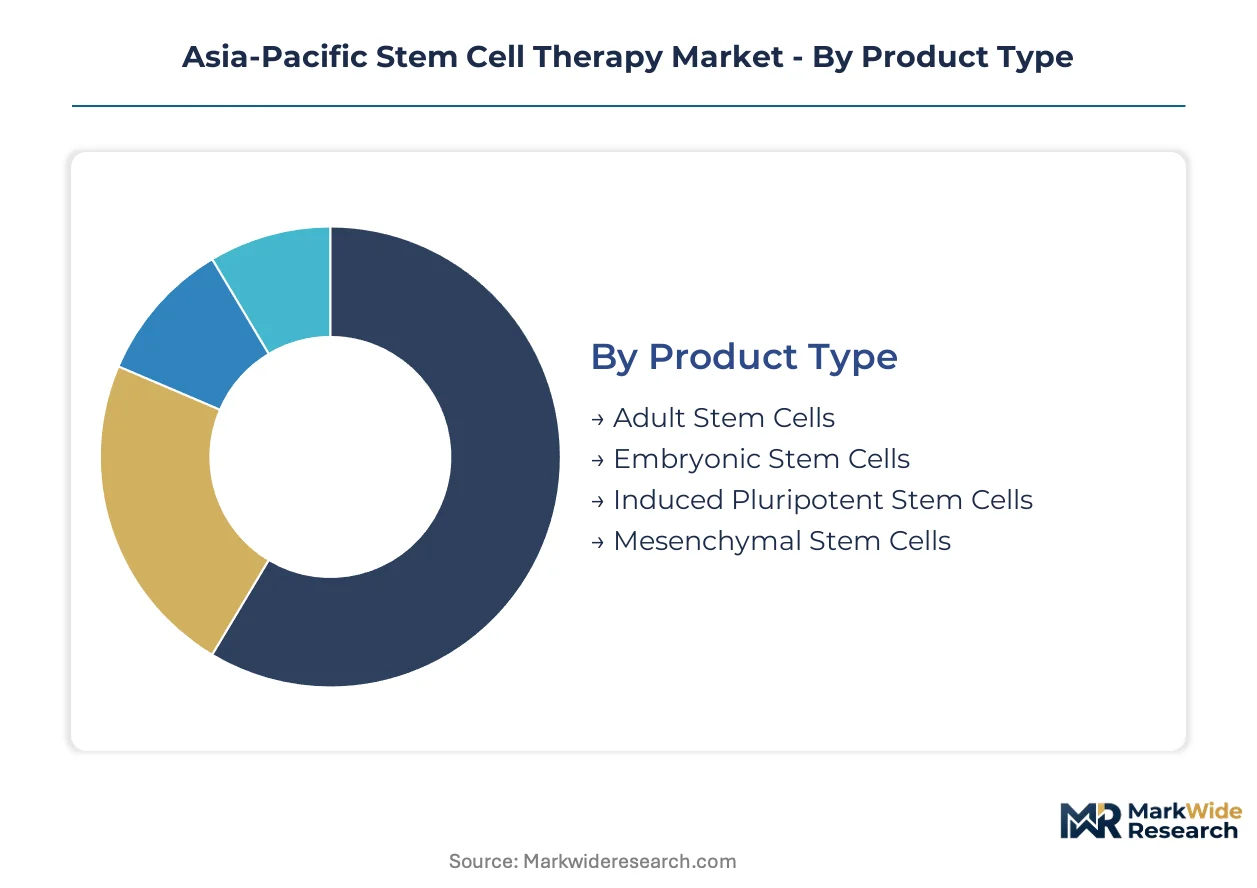
Cell therapy procurement patterns across Asia-Pacific diverge sharply by product origin and delivery complexity. Hospital networks in Seoul, Tokyo, and Shanghai prioritize segments with established cold chain protocols and regulatory clarity.
Product Type:
Manufacturing scale and donor traceability requirements concentrate supply among segments with GMP-validated expansion protocols.
- Mesenchymal Stem Cells:Derived from bone marrow, adipose tissue, and umbilical cord sources with established expansion protocols. Seoul hospital networks and Shanghai biotech corridors are consolidating procurement around adipose-derived variants for orthopedic applications. Lower tumorigenic risk profiles accelerate clinical adoption compared to pluripotent alternatives.
- Induced Pluripotent Stem Cells:Reprogrammed somatic cells enabling patient-specific disease modeling and CRISPR-edited therapeutic platforms. Japan's PMDA conditional approval framework positions iPSC-derived cardiomyocytes for early commercial entry. Manufacturing complexity and reprogramming consistency constraints limit near-term supply concentration.
- Adult Stem Cells:Hematopoietic and tissue-resident progenitor populations with established transplantation protocols in China's tier-one oncology centers.
- Embryonic Stem Cells:Pluripotent lines with restricted procurement due to ethical sourcing constraints and heightened regulatory scrutiny across South Korea's MFDS-coordinated biobanks.
Today's leader: Mesenchymal Stem Cells. Tomorrow's challenger: Induced Pluripotent Stem Cells.
Application:
Reimbursement pathways and clinical evidence depth determine where hospital procurement committees allocate stem cell therapy budgets.
- Oncology:Hematopoietic stem cell transplantation protocols for leukemia and lymphoma dominate current procedure volumes. China's NMPA dual-track IND requirements are standardizing autologous sourcing for hematologic malignancies across Beijing and Guangzhou transplant centers.
- Neurology:Parkinson's disease and ischemic stroke indications are advancing through Phase II protocols in Japan and Australia. PMDA conditional approval mechanisms compress development timelines for dopaminergic neuron replacement therapies.
- Orthopedics:Osteoarthritis and cartilage regeneration applications leverage established adipose-derived MSC processing in Seoul hospital networks.
- Cardiovascular:iPSC-derived cardiomyocyte platforms target heart failure segments with emerging evidence from Japan's regenerative medicine safety framework.
Oncology commands current revenue share. Neurology presents the steepest expansion trajectory as motor function restoration trials mature.
Delivery Mode:
Procedure complexity and infrastructure requirements filter which modalities achieve scale in hospital versus clinic settings.
- Injection:Intra-articular and intramuscular delivery of MSC suspensions for orthopedic applications. Automated closed-system preparation reduces contamination risk in Shanghai CDMO facilities.
- Infusion:Intravenous administration of expanded cell populations for systemic immunomodulation. Cold chain logistics concentrate in Tokyo, Seoul, and Shanghai corridors.
- Transplantation:Surgical implantation of scaffold-integrated cell constructs requiring operating theater infrastructure and extended patient monitoring.
- Topical Application:Dermal and ocular surface delivery with localized action minimizing systemic exposure.
Injection dominates outpatient scalability. Transplantation retains premium positioning in academic medical centers.
End User:
Capital intensity and regulatory qualification requirements segment the customer base by cell handling capability.
- Hospitals:Tier-one oncology and transplant centers in China, Japan, and South Korea with captive GMP processing units and dedicated cell therapy pharmacy infrastructure.
- Research Institutes:Academic medical centers conducting investigator-initiated trials under PMDA and MFDS oversight.
- Clinics:Outpatient facilities with limited scope to autologous adipose-derived applications requiring minimal ex vivo manipulation.
- Pharmaceutical Companies:Sponsors of multi-center trials navigating NMPA inspection backlogs and cross-border sample transfer protocols.
Hospitals anchor procurement volume. Pharmaceutical companies represent the emerging channel as commercial pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's PMDA conditional approval framework compresses commercial timelines, while China's NMPA dual-track requirements extend development cycles. Hospital procurement concentration in Seoul and Shanghai accelerates autologous sourcing protocols across divergent regulatory environments.
Japan
Tokyo's academic medical centers drive demand for iPSC-derived cardiomyocyte platforms and dopaminergic neuron replacement therapies. PMDA's conditional approval mechanism under the Act on Regenerative Medicine Safety permits early market entry with post-marketing efficacy commitments. The Kanto corridor anchors regenerative medicine manufacturing with integrated GMP facilities serving domestic and export markets.
China
Shanghai's biotech corridor concentrates CAR-T and stem cell engineering demand within NMPA regulatory sandbox zones. SAMR oversight imposes parallel IND and clinical trial application requirements that filter market access for domestic developers. Beijing and Guangzhou transplant centers standardize autologous sourcing protocols for hematologic malignancies under provincial health authority mandates.
South Korea
Seoul hospital networks expand procurement of autologous stem cell procedures with vertically integrated cord blood banking partnerships. MFDS-coordinated biobank standards enforce exhaustive donor documentation and quality benchmarks that extend qualification timelines. The Seoul Capital Area dominates orthopedic gene-therapy hybrid development through hospital-linked GMP processing units.
Australia
Melbourne and Sydney research institutes advance Phase II protocols for Parkinson's disease and ischemic stroke indications. TGA oversight aligns with international harmonization initiatives while maintaining distinct manufacturing inspection schedules. The southeastern corridor attracts multi-center trial sponsorship through established clinical research infrastructure and biosafety protocols.
India
Mumbai and Delhi-NCR oncology centers develop investigator-initiated trials under CDSCO guidance for hematopoietic stem cell transplantation. The national pharmaceutical regulator imposes incremental manufacturing standards that differentiate export-oriented from domestic-focused developers. Stempeutics Research anchors Bangalore's emerging cell therapy cluster through research institute partnerships.
Asia-Pacific Stem Cell Therapy Market Competitive Environment
Japanese producers anchor one tier through PMDA-accelerated commercial pathways; South Korean specialists hold manufacturing integration advantages through hospital network partnerships. The vendor base separates into three functional tiers: vertically integrated cord blood banks, CAR-T engineering specialists, and orthopedic gene-therapy hybrid developers. Strategic moves concentrate on GMP facility certification, regional regulatory sandbox positioning, and cold chain logistics partnerships.
Within the integrated biobanking tier, MEDIPOST exemplifies captive supply control through hospital-linked cord blood operations. Among CAR-T engineering specialists, JW Therapeutics (Shanghai) Co., Ltd. occupies a position within China's regulatory innovation zones. Kolon TissueGene, Inc. represents the orthopedic hybrid archetype with gene-modified cell platforms targeting joint regeneration segments. These three anchors illustrate divergent geographic and therapeutic positioning across the regional competitive map.
| Leading Market Players |
|---|
| Kolon TissueGene, Inc. |
| Curocell, Inc. |
| MEDIPOST |
| Stempeutics Research Pvt. Ltd. |
| JW Therapeutics (Shanghai) Co., Ltd. |
| PHARMICELL Co., Ltd. |
| JCR Pharmaceuticals Co., Ltd. |
| Takara Holdings Inc |
| ANTEROGEN. CO., LTD |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement consolidation in Shanghai and Seoul is forcing suppliers to absorb cold chain logistics costs while maintaining GMP certification standards, compressing margins across autologous and allogeneic product tiers. This buyer concentration reshapes supplier economics toward volume-based contract structures that privilege vertically integrated cord blood banks with captive processing capabilities.
Pricing Analysis
Capacity additions in South Korea's Seoul Capital Area are reshaping price floors for adipose-derived mesenchymal stem cell products. Three-tier pricing structure across premium, standard, and economy levels differentiates by GMP certification tier and donor traceability documentation depth. Cost compression in economy-tier allogeneic products is intensifying because MFDS biobank compliance overhead filters smaller competitors. Oncology centers in China's tier-one cities demonstrate lowest price sensitivity due to reimbursement anchoring, while outpatient orthopedic clinics in secondary markets exhibit highest elasticity.
Supply Chain Analysis
Cryopreserved cell logistics costs concentrate procurement decisions within Tokyo, Seoul, and Shanghai corridors where temperature-controlled infrastructure is densest. Manufacturing draws from Japan's Kanto biocluster, South Korea's MFDS-coordinated biobanks, and China's NMPA-sanctioned CDMO zones in Pudong. Lentiviral vector production capacity represents single-source vulnerability for CAR-T engineering specialists. Distribution runs through hospital-linked GMP pharmacy units that displace traditional pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific stem cell therapy market compounds steadily as aging demographics across Japan, South Korea, and China expand addressable patient populations for regenerative interventions. Hospital procurement centralization and regulatory pathway fragmentation create durable competitive moats for integrated operators.
For Market Incumbents: Hedge against NMPA inspection backlogs by diversifying manufacturing footprints across Japan's PMDA-conditional pathway and Australia's TGA-aligned facilities. Deepen backward integration into viral vector production to reduce raw material procurement risk from limited contract manufacturers. Anchor hospital network partnerships through captive cord blood banking assets that lock in autologous sourcing protocols. For New Entrants and Emerging Players: The price-point gap between premium iPSC-derived platforms and economy-tier adipose-derived MSC products opens white-space targeting for mid-market neurology indications. Parkinson's disease and ischemic stroke segments in Australia and Japan present the most penetrable entry points given Phase II trial density. Pursue regulatory sandbox positioning within Shanghai's Zhangjiang hub to compress NMPA dual-track timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated biobank operators possessing hospital-linked GMP processing units and established cold chain logistics. The five-to-ten year viability window favors acquisition targets with PMDA conditional approval experience and multi-country regulatory dossier capabilities. Monitor MFDS biobank qualification timelines as inflection indicators for South Korean supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Positioning | NMPA innovation zone access in Shanghai compresses IND-to-trial timelines for domestic developers. |
| GMP Facility Certification | MFDS-coordinated biobank standards enforce donor traceability that filters subscale competitors from hospital procurement. |
| Cold Chain Logistics Partnership | Temperature-controlled infrastructure partnerships in Tokyo-Seoul-Shanghai corridors extend patient access beyond tier-one cities. |
| iPSC Platform Integration | CRISPR-edited cardiomyocyte convergence reduces donor tissue variability for cardiovascular applications. |
| Hospital System Partnership | Vertical integration into tier-one oncology center procurement committees locks in autologous sourcing volume commitments. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down CDMO capacity tracking forms the analytical core of this study. Primary interviews with cell therapy development executives, regulatory affairs leads at PMDA and MFDS, hospital procurement managers in Seoul and Shanghai, and GMP facility operators were validated against secondary sources including ClinicalTrials.gov registry data, NMPA IND filings, PMDA conditional approval dossiers, and hospital procurement database extracts. Triangulation across these sources ensures segmentation integrity across product type, application, and end-user dimensions.
Input-output matrices map cell source availability, GMP facility certification status, and regulatory pathway velocity to commercial volume projections across the analysis window. Segmentation modeling incorporates product origin, therapeutic application, delivery complexity, and geographic regulatory cluster. CAGRs derive from procedure volume trajectories in hematologic malignancy transplantation protocols and Parkinson's disease trial enrollment curves, cross-referenced against reimbursement pathway development in Japan's Act on Regenerative Medicine Safety framework.
Caveats apply where NMPA inspection backlog resolution, MFDS biobank standard enforcement intensity, or iPSC manufacturing consistency breakthroughs could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
NTRK Fusion Gene Positive Advanced Solid Tumor Market
Cell & Gene Therapy
Leukemia Therapeutics Treatment Market
Cell & Gene Therapy
Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market
Cell & Gene Therapy
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Gene Electroporators Market
Cell & Gene Therapy
Induced Pluripotent Stem Cells Production Market
Cell & Gene Therapy
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market
Cell & Gene Therapy
Global Cancer Vaccine Market
Cell & Gene Therapy
Engineered Cell Therapy Market
Cell & Gene Therapy
Retinitis Pigmentosa Treatment Market
Cell & Gene Therapy
North America Stem Cell Therapy Market
Cell & Gene Therapy
Inherited Orphan Blood Disorders Therapeutics Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
Europe Stem Cell Therapy Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market