
 Human Insulin Drugs Market | 2026-2036
Human Insulin Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Human Insulin Drugs Market Foresight
Single-source API supply is shifting toward multi-source recombinant manufacturing across the insulin value chain. Novo Nordisk A/S anchors European production through its Danish fermentation facilities, while Eli Lilly and Company sustains North American supply via advanced biotechnology manufacturing. Sanofi competes through integrated fill-finish operations that span active pharmaceutical ingredient synthesis to prefilled pen assembly.
Human insulin drugs are recombinant protein therapeutics produced through microbial or mammalian cell culture, formulated as rapid-acting, long-acting, premixed, or ultra-rapid analogs to regulate blood glucose in diabetic patients. Long-acting insulin analogs command the largest revenue share due to once-daily dosing adherence and reduced nocturnal hypoglycemia risk. The homecare end-user segment is expanding fastest as pen-based delivery systems displace traditional vial-and-syringe administration in outpatient settings.
FDA biosimilar guidance and EMA's scientific advice framework shape product development timelines, while WHO prequalification programs determine access eligibility for procurement in low-income countries. India's CDSCO and China's NMPA have tightened cold-chain storage requirements for insulin distribution, raising compliance costs for temperature-sensitive logistics. Stakeholders must monitor biosimilar interchangeability designations and insulin pricing reform legislation as these policies reshape competitive dynamics and reimbursement structures.
Market Dynamics
Biosimilar insulin pathways at FDA and EMA are compressing approval timelines while fragmenting manufacturing concentration across Danish, Indian, and Chinese production clusters.
Growth Catalysts
- EMA Biosimilar Scientific Advice:Streamlined development frameworks reduce regulatory uncertainty for follow-on insulin developers seeking European market entry.
- Homecare Pen-Based Delivery:Outpatient administration systems are displacing hospital-centric vial-and-syringe protocols across diabetes management protocols.
- China NMPA Cold-Chain Expansion:Tightened distribution standards are accelerating domestic recombinant DNA capacity investments by local manufacturers.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient synthesis remains concentrated among three major fermentation facility operators, creating single-source vulnerability.
- Temperature-Sensitive Logistics:Insulin cold-chain requirements impose 15-25% cost premiums on distribution networks in tropical climates.
- Interchangeability Designation Delays:FDA biosimilar interchangeability standards create formulary access friction that slows payer adoption of follow-on products.
Strategic Opportunities
- Ultra-Rapid Analog Formulations:Post-meal glucose control technologies address unmet needs in Type 1 diabetes populations with high glycemic variability.
- Indian CDSCO Prequalification:WHO procurement eligibility programs open institutional purchasing channels across low-income country health systems.
- Connected Pen Integration:Bluetooth-enabled dose tracking converges with mobile health platforms to capture adherence data for value-based contracting.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Mammalian cell culture scale-up expertise concentrates among legacy fermentation specialists, constraining new facility commissioning.
- Fill-Finish Validation Timelines:Aseptic manufacturing qualification protocols extend commercialization schedules by 18-24 months for prefilled pen assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Insulin Drugs Market |
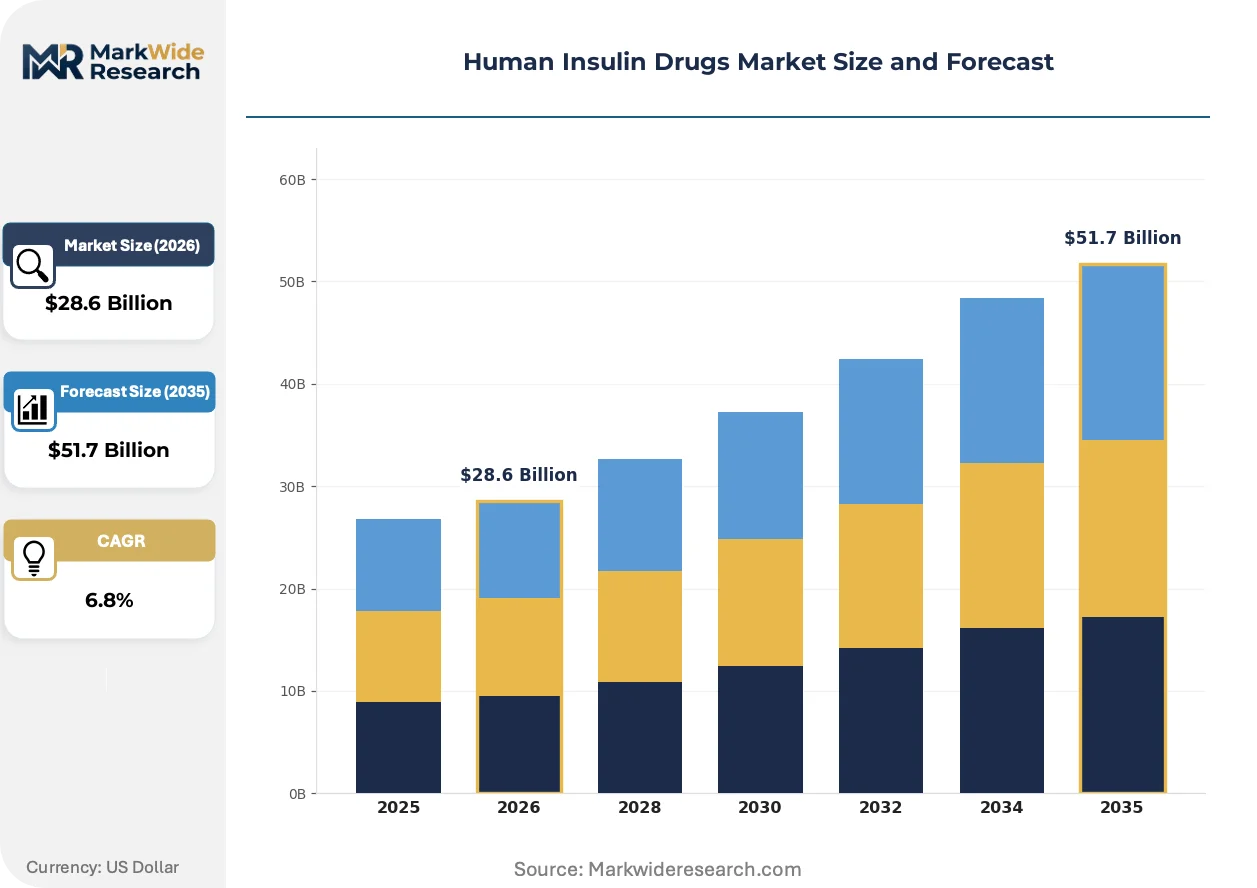
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid-Acting, Long-Acting, Premixed, Ultra-Rapid End User: Hospitals, Homecare, Clinics, Diabetes Centers Form: Injectable, Pen, Vial, Cartridge Delivery Mode: Subcutaneous, Intravenous, Inhalation, Others |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Sanofi, Biocon, Tonghua Dongbao Pharmaceutical, Julphar, Wockhardt, Gan & Lee Pharmaceuticals, BIOTON S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Insulin Drugs Market Shifts & Advancements
Insulin delivery technology is pivoting from clinical settings toward patient-controlled administration, while regulatory frameworks accelerate biosimilar competition and digital health integration reshapes adherence monitoring.
Ultra-rapid insulin analogs is overtaking conventional rapid-acting formulations in postprandial glucose management. Pediatric endocrinology practices and insulin pump users are adopting these molecules for tighter mealtime control. The technology is compressing the competitive window for first-generation analogs while expanding the addressable population for intensive insulin therapy.
EMA's Falsified Medicines Directive serialization requirements are mandating end-to-end track-and-trace infrastructure for insulin supply chains. European wholesalers must deploy verification systems at each distribution node by statutory deadlines. Prefilled pen manufacturers are absorbing compliance costs while smaller vial suppliers face market exit pressures.
Subscription-based insulin procurement is replacing transactional pharmacy purchasing among large self-insured employers in the United States. Third-party administrators are negotiating multi-year supply agreements that bundle devices, consumables, and remote monitoring services. This model is most visible in employer-sponsored health plans covering concentrated manufacturing workforces with high diabetes prevalence.
Human Insulin Drugs Market Segmentation
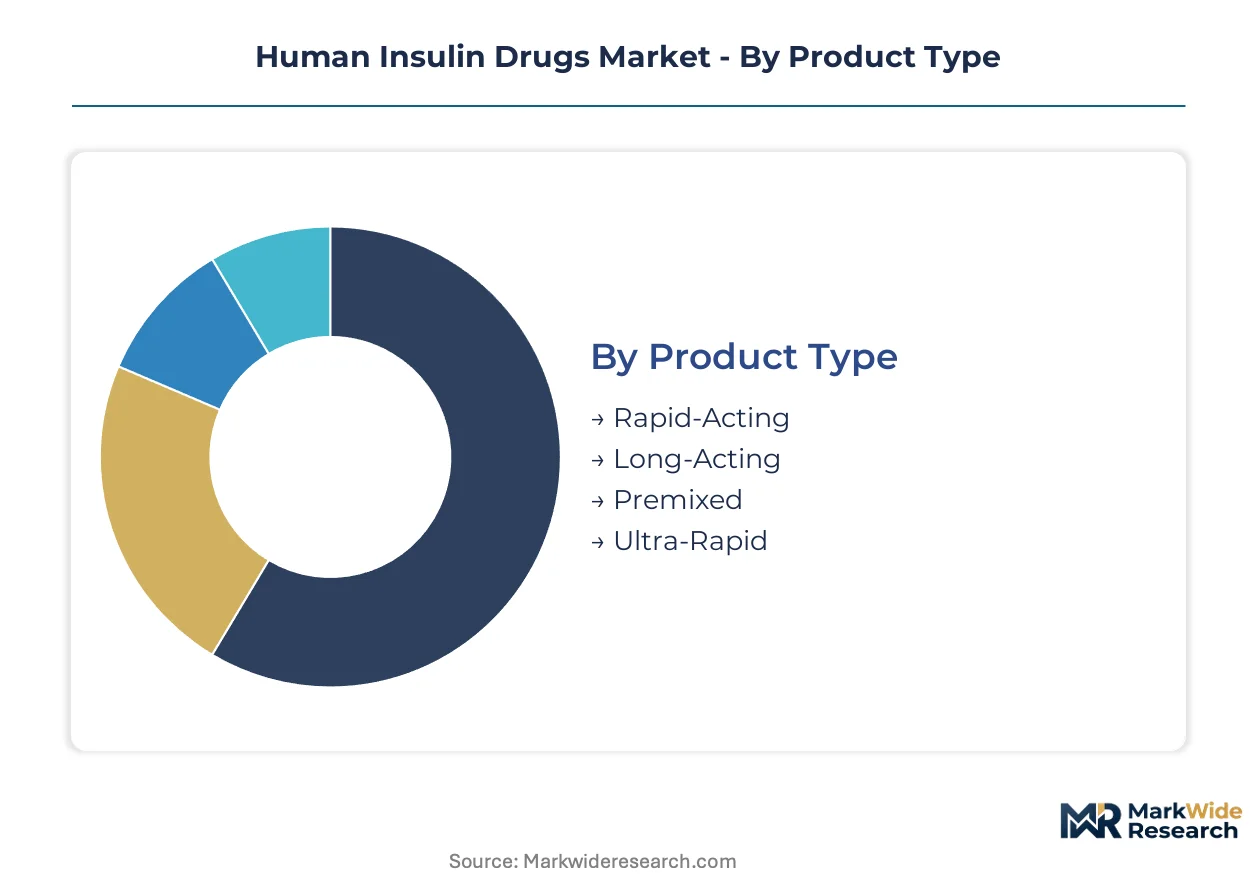
Segmentation in the insulin market reveals how formulation chemistry, administration setting, and device engineering intersect to determine patient adherence and reimbursement economics. Each dimension carries distinct cold-chain, regulatory, and pricing implications that shape manufacturer portfolio strategy.
Product Type:
Standalone basal-bolus therapy dominates intensive insulin regimens, while embedded combination therapies address polypharmacy complexity in Type 2 progression.
- Long-Acting:Recombinant insulin glargine and detemir analogs provide 24-hour basal coverage with reduced peak-trough variability. Demand concentrates in North American and European outpatient settings where once-daily dosing drives adherence metrics for payer contracts.
- Rapid-Acting:Insulin lispro, aspart, and glulisine formulations target postprandial glucose excursions with 15-minute onset profiles. Homecare pen-based delivery in the United States and Germany absorbs the majority of volume as pump therapy expands.
- Premixed:Fixed-ratio intermediate/rapid combinations serve patients requiring simplified injection schedules. Emerging market health systems in India and Mexico favor these formulations for primary care protocols.
- Ultra-Rapid:Next-generation analogs with accelerated absorption kinetics address unmet needs in closed-loop artificial pancreas systems. Pediatric endocrinology practices and insulin pump users represent the concentrated early-adopter population.
Volume placements concentrate in Long-Acting; the faster expansion belongs to Ultra-Rapid.
End User:
Care setting determines device complexity tolerance, cold-chain infrastructure requirements, and reimbursement pathway selection.
- Homecare:Self-administered pen and pump therapy dominates daily injection volume. United States Medicare Part D and German statutory health insurance reimbursement structures favor outpatient dispensing.
- Hospitals:Inpatient glycemic management protocols rely on intravenous insulin infusion and subcutaneous correctional dosing. EMA and FDA good manufacturing practice standards govern aseptic compounding requirements.
- Clinics:Outpatient endocrinology practices manage dose titration and complication screening. China's tier-1 city hospital outpatient departments are expanding dedicated diabetes clinics.
- Diabetes Centers:Specialized facilities coordinate multidisciplinary care including nutrition, podiatry, and retinal screening. India's National Programme for Prevention and Control of Cancer, Diabetes, CVD and Stroke funds these centers in district hospitals.
Homecare captures the dominant share of annual injections; Diabetes Centers are climbing the fastest as government screening programs expand.
Form:
Primary packaging format dictates stability profile, dosing precision, and patient mobility.
- Pen:Disposable and reusable multidose devices with dial-a-dose functionality. Prefilled pen assemblies from Danish and German manufacturers command premium positioning in Japanese and South Korean markets.
- Vial:Multi-dose glass containers for syringe-based withdrawal. Cost-sensitive procurement in Brazil's Sistema Único de Saúde and Nigeria's federal health programs sustains volume.
- Cartridge:Pen-compatible reservoirs for reusable device systems. European markets show preference for this format due to waste reduction regulations.
- Injectable:Syringe-administered formulations including pump infusion sets. United States integrated delivery networks negotiate bundled pricing for pump consumables.
Pen systems lead in revenue per patient; Cartridge formats are gaining share fastest amid sustainability mandates.
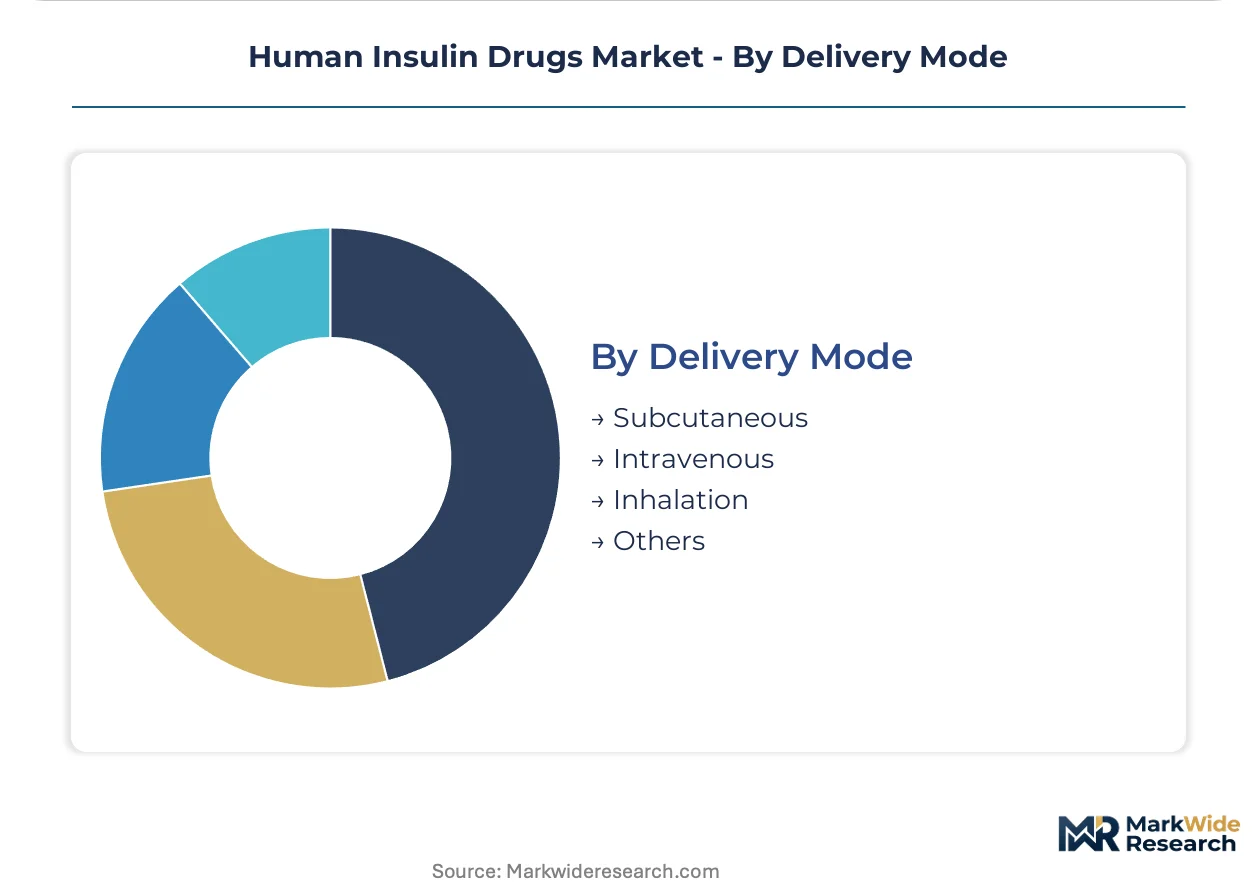
Delivery Mode:
Route of administration determines pharmacokinetic profile, training burden, and acute complication risk.
- Subcutaneous:Abdominal, thigh, or deltoid depot injection via pen, syringe, or pump infusion. This route handles over 90% of non-critical insulin administration across all geographies.
- Intravenous:Continuous infusion for diabetic ketoacidosis, perioperative glycemic control, and critical care. Hospital pharmacy compounding operations in France and Italy maintain 24-hour infusion stock.
- Inhalation:Pulmonary delivery of powdered human insulin for prandial coverage. Limited commercial presence following regulatory scrutiny of pulmonary function effects.
- Others:Includes intraperitoneal pump delivery and experimental oral formulations. Research-stage programs in Israel and Singapore explore gastrointestinal absorption technologies.
Subcutaneous administration anchors global volume; Inhalation delivery shows the steepest expansion trajectory from minimal base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in India and China, where domestic recombinant DNA production capacity is scaling rapidly to serve expanding patient populations. Hospital systems across emerging economies are broadening insulin formularies as diabetes prevalence climbs. Regulatory pathways at FDA and EMA are compressing approval timelines for biosimilar entrants.
United States
Medicare Part D reimbursement structures favor outpatient pen-based dispensing over vial-and-syringe protocols. FDA biosimilar interchangeability designations create formulary access friction that slows payer adoption of follow-on products. Indianapolis anchors North American supply through advanced biotechnology manufacturing operations sustaining regional distribution networks.
Germany
Statutory health insurance reimbursement frameworks drive adherence metrics for once-daily long-acting analogs in outpatient settings. EMA's Falsified Medicines Directive mandates end-to-end track-and-trace serialization across insulin supply chains. The Rhine-Ruhr industrial corridor hosts fill-finish operations spanning active pharmaceutical ingredient synthesis to prefilled pen assembly.
China
Tier-1 city hospital outpatient departments are expanding dedicated diabetes clinics to manage dose titration and complication screening. NMPA cold-chain storage requirements for insulin distribution have tightened, raising compliance costs for temperature-sensitive logistics. Yangtze River Delta manufacturing clusters are scaling recombinant fermentation capacity to serve domestic procurement programs.
India
The National Programme for Prevention and Control of Cancer, Diabetes, CVD and Stroke funds diabetes centers in district hospitals across high-prevalence states. CDSCO prequalification programs determine WHO procurement eligibility for institutional purchasing channels in low-income country health systems. Karnataka and Maharashtra fermentation facilities are expanding microbial cell culture output for export markets.
Denmark
European outpatient demand for long-acting basal coverage concentrates purchasing power among integrated delivery networks. EMA scientific advice frameworks reduce regulatory uncertainty for follow-on insulin developers seeking regional market entry. Copenhagen anchors continental production through Danish fermentation facilities supplying prefilled pen assemblies to Nordic and Central European markets.
Human Insulin Drugs Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale recombinant fermentation output to capture biosimilar market entry windows. The structure consolidates around three legacy fermentation specialists controlling active pharmaceutical ingredient synthesis, with emerging domestic challengers fragmenting fill-finish operations across Indian and Chinese production clusters. Two strategic archetypes define positioning: integrated multinationals commanding end-to-end supply chains, and regional specialists leveraging cost-advantaged bioprocess engineering. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players racing to secure WHO prequalification status and connected pen device registrations.
Among integrated multinationals, Novo Nordisk A/S and Eli Lilly and Company occupy positions exemplifying the legacy fermentation archetype, while Sanofi represents the fill-finish integration model. Biocon and Tonghua Dongbao Pharmaceutical sit within the emerging domestic specialist tier, leveraging regional cost structures to challenge incumbent pricing in procurement-intensive markets. These named entities anchor industry-level commentary on competitive positioning without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Sanofi |
| Biocon |
| Tonghua Dongbao Pharmaceutical |
| Julphar |
| Wockhardt |
| Gan & Lee Pharmaceuticals |
| BIOTON S.A. |
| Others |
Supply & Pricing Matrix
Fermentation facility energy costs cascade through three pricing tiers for insulin API, with Danish and North American manufacturers absorbing grid-price premiums while Indian and Chinese producers leverage subsidized industrial power rates to undercut vial pricing in procurement-intensive markets.
Pricing Analysis
Volume placements concentrate in long-acting basal analogs where Novo Nordisk and Eli Lilly command premium positioning; rapid-acting and premixed segments compete on price differentiation driven by biosimilar certification tier and cold-chain delivery cost. Three-tier pricing structure across premium patented analogs, standard biosimilars, and economy vial formulations separates Medicare Part D reimbursement tiers from emerging market cash purchases. Pricing pressure stems from WHO prequalification eligibility requirements that force margin compression for institutional procurement contracts. Uninsured and underinsured patient segments in the United States and low-income country health systems exhibit highest price sensitivity, while Japanese and German statutory insurance pools absorb premium pen-device pricing with minimal formulary friction.
Supply Chain Analysis
Regional distribution centers in Copenhagen, Indianapolis, and Shanghai anchor hub-and-spoke cold-chain networks that fan out to national wholesale nodes. Active pharmaceutical ingredient synthesis concentrates in Denmark, the United States, and India, with fill-finish operations fragmenting across Chinese and European production clusters. Raw material dependencies include recombinant yeast and E. coli cell lines, pharmaceutical-grade glucose feedstocks, and specialized borosilicate glass for pen cartridges. Single-source vulnerability in mammalian cell culture expertise constrains new facility commissioning timelines. Distribution runs through temperature-controlled 2-8°C logistics networks with 15-25% cost premiums in tropical climates, governed by FDA, EMA, CDSCO, and NMPA serialization mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The human insulin drugs market is becoming a vertical-integration race as manufacturers pursue captive control over fermentation capacity to secure biosimilar entry windows and defend margin structures against emerging domestic challengers.
For Market Incumbents: Lock in mammalian cell culture talent pools through dedicated training partnerships with Danish and German technical universities before bioprocess engineering scarcity constrains capacity expansion timelines. Secure backward integration into recombinant yeast strain development to reduce dependency on legacy fermentation specialists for API supply. Counter emerging Indian and Chinese biosimilar threats by accelerating connected pen device registrations and value-based contracting pilots with United States integrated delivery networks. For New Entrants and Emerging Players: Enter via WHO prequalification pathways for long-acting insulin analogs targeting institutional procurement channels in Nigeria, Kenya, and Indonesia where incumbent presence remains thin. Exploit cost-advantaged microbial fermentation capacity in Maharashtra and Karnataka to undercut premium pricing in Latin American and Southeast Asian tender markets. Lead with vial formulations and cartridge-compatible reservoirs rather than prefilled pen assemblies to avoid 18-24 month aseptic validation timelines that delay commercialization. For Investors and Strategic Acquirers: FDA biosimilar interchangeability designation grants are the leading indicator that payer formulary access friction is resolving and volume share shifts are accelerating toward follow-on products. Position acquisition screening around mid-cap fermentation specialists with existing EMA scientific advice engagement and CDSCO manufacturing licenses, as these assets command scarcity premiums over greenfield capacity builds. Monitor NMPA domestic procurement preference policies as the signal for when Chinese production clusters will displace imported volume in the world's second-largest diabetes market.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expands recombinant fermentation output to capture biosimilar approval windows before interchangeability designations fragment pricing. |
| Regulatory Approval Pathway | EMA scientific advice and FDA biosimilar guidance reduce development uncertainty for follow-on insulin developers seeking formulary access. |
| Backward Integration | In-house cell line development and API synthesis reduces single-source vulnerability to Danish and North American fermentation specialists. |
| Hospital System Partnership | Direct contracts with China's tier-1 diabetes clinics and India's district hospital centers secure volume commitments ahead of tender cycles. |
| Software Companion Development | Bluetooth-enabled dose tracking integration with mobile health platforms captures adherence data for value-based payer contracting. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced with primary interviews of drug development executives, regulatory affairs leads, formulary directors, hospital procurement managers, and payer access specialists across North American, European, and Asia-Pacific markets. FDA 510(k) and BLA submissions, EMA marketing authorization applications, ClinicalTrials.gov protocol registries, and WHO prequalification assessment reports provided structured secondary validation. Bottom-up patient population modeling and top-down pharmaceutical sales audit triangulation reconciled volume estimates across the analysis window.
Data-stream reconciliation combined prescription audit databases, insulin shipment customs records, and hospital procurement contract disclosures to align volume and value outputs across the projection horizon. Segmentation dimensions modeled included product type (long-acting, rapid-acting, premixed, ultra-rapid), end user (homecare, hospital, clinic, diabetes center), and form (pen, vial, cartridge, injectable), with regional regulatory cluster and cold-chain infrastructure maturity as cross-cutting variables. CAGRs were derived from polynomial trend fitting of historical volume trajectories adjusted for biosimilar entry elasticity and pricing reform legislation impacts.
Revisions become necessary when FDA interchangeability standards shift, EMA falsified medicines serialization deadlines accelerate, or NMPA domestic procurement preferences redirect volume toward Chinese manufacturers. Forecasts reflect documented assumptions around patient population growth, biosimilar adoption curves, and reimbursement policy stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Insulin Aspart Market
Biopharmaceuticals
Biopharmaceuticals Manufacturing Consumables Testing Market
Biopharmaceuticals
India Insulin Drug and Delivery Device Market
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market
Biopharmaceuticals
Laband Syndrome Therapeutics Market
Biopharmaceuticals
Immunocytokines Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Mexico Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Brazil Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Amphotericin B Market
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
Olaparib API Market
Biopharmaceuticals
Global Argatroban Market
Biopharmaceuticals
Macrolide Antibiotics Market