
 Generic Injectables Market | 2026-2036
Generic Injectables Market Size, Share, and Industry Trends Forecast 2026-2036
Generic Injectables Market Intelligence
Market Context
Capital-intensity divergence between large-scale sterile fill-finish networks and smaller regional players is redrawing competitive boundaries in generic injectables. Fresenius Kabi leverages integrated plasma-to-vial infrastructure across European and North American sites to sustain cost leadership in oncology and anesthesia portfolios. Hikma Pharmaceuticals anchors its position through Middle Eastern and US injectable facilities that specialize in anti-infective and emergency-care presentations.
Technical Definition and Segment Structure
Generic injectables are sterile liquid or lyophilized drug products administered parenterally, requiring aseptic processing, endotoxin control, and container-closure integrity validated to USP <797> and EU GMP Annex 1 standards; they serve therapeutic areas where bioavailability or patient condition precludes oral administration. Monoclonal antibodies and peptide segments command premium positioning due to manufacturing complexity and limited qualified capacity, while intravenous delivery modes occupy the dominant volume share through hospital-centric procurement. Oncology applications lead therapy-area demand as patent expirations on biologic anchors open substitutable opportunities, and home healthcare channels represent the fastest-growing end-user trajectory driven by self-administration device compatibility.
Regulatory Environment
FDA's Quality Management Maturity program and EMA's revised GMP Annex 1 for sterile manufacture are elevating compliance costs and filtering subscale participants from tender eligibility. India's CDSCO and BIS frameworks for injectable exports impose parallel certification requirements that shape facility investment decisions for suppliers targeting regulated markets. Stakeholders must monitor evolving pharmacovigilance obligations and real-world evidence expectations as payers condition reimbursement on substitutability demonstrations beyond bioequivalence alone.
Market Dynamics
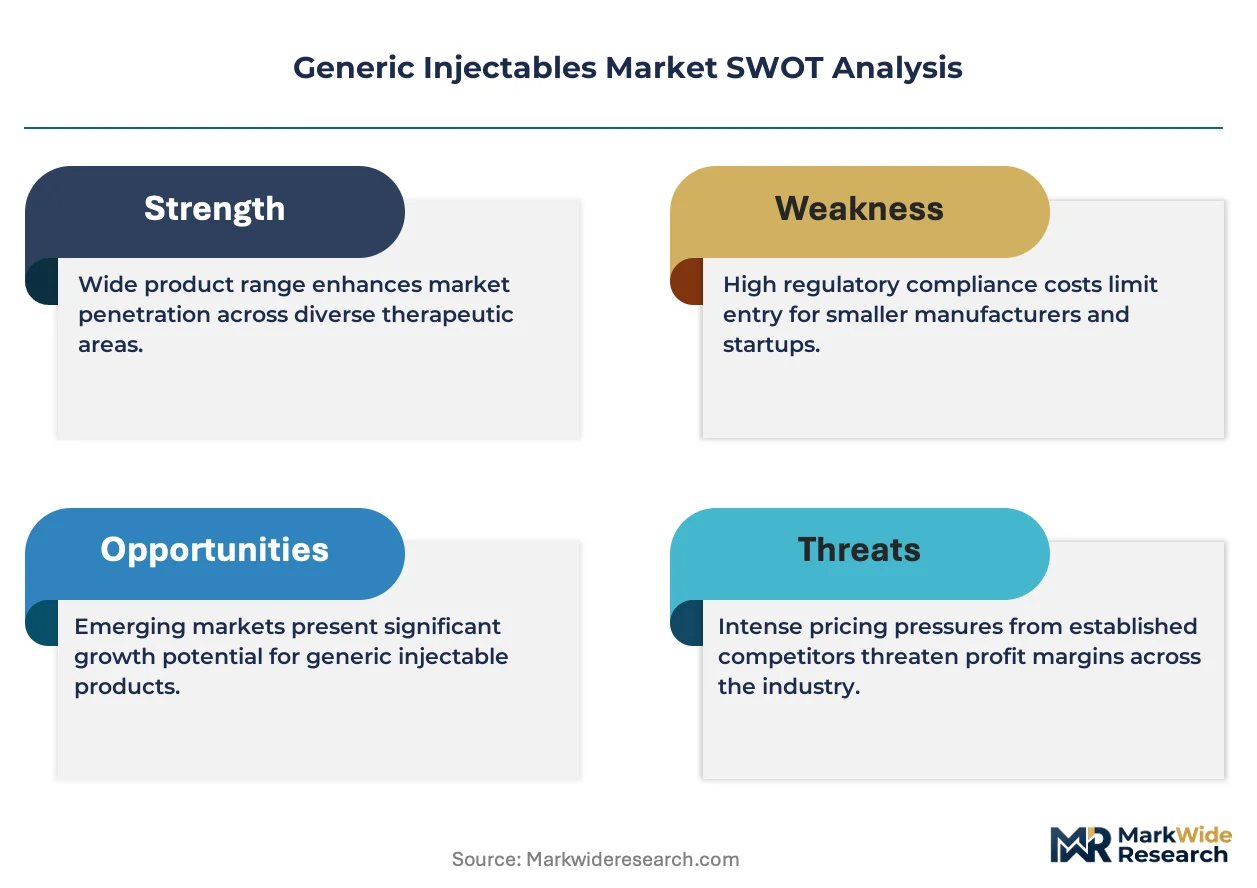
Hospital procurement consolidation and FDA biosimilar pathway refinements are compressing supplier margins while rewarding sterile fill-finish scale, forcing mid-cap manufacturers to choose between facility upgrades and portfolio exits.
Growth Catalysts
- Oncology patent cliffs:Expiring biologic anchors in cancer therapy are opening substitutable opportunities for complex parenterals across United States, German, and Indian hospital networks.
- EMA's GMP Annex 1 revisions:Streamlined sterile manufacturing standards are reducing approval friction for qualified European facilities targeting oncology and anesthesia portfolios.
- Home healthcare migration:Self-administration device compatibility is pulling injectable demand from inpatient settings toward outpatient channels in United States and Germany.
Market Restraints
- API supply concentration:Critical starting material dependencies on Chinese and Indian active pharmaceutical ingredient suppliers create vulnerability to export restriction shocks.
- Compliance cost escalation:FDA Quality Management Maturity program requirements are filtering subscale participants from tender eligibility in United States hospital systems.
- Glass vial and elastomer shortages:Container-closure component bottlenecks are extending lead times for sterile fill-finish operations across European manufacturing clusters.
Strategic Opportunities
- Peptide and monoclonal antibody white space:Limited qualified aseptic capacity for high-complexity biologics creates premium positioning opportunities for facilities with validated isolator technology.
- Indian CDSCO export certification:Parallel BIS and CDSCO frameworks for injectable exports enable Indian manufacturers to capture regulated market share through dual-compliant facility investments.
- Emergency care channel expansion:Anti-infective and anesthesia presentations in Middle Eastern government tenders offer volume allocation for suppliers with regional fill-finish presence.
Industry Challenges
- Aseptic processing talent scarcity:Qualified personnel gaps in isolator operation and media fill validation are constraining capacity expansion timelines for sterile manufacturers.
- Legacy facility reconfiguration:Brownfield upgrades to meet EU GMP Annex 1 isolator requirements demand capital deployment that strains mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generic Injectables Market |
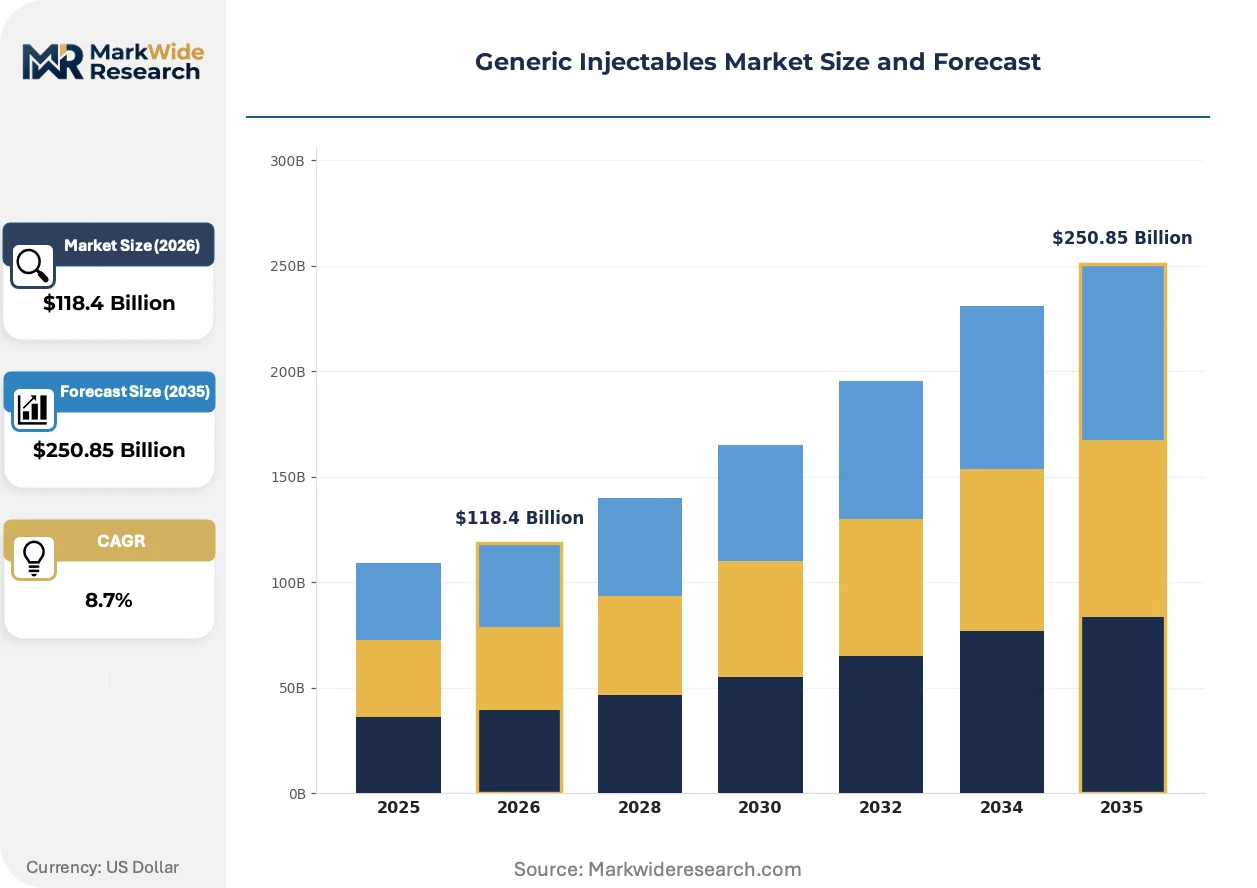
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $250.85 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Peptides, Monoclonal Antibodies, Hormones Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Intra-articular Therapy Area: Oncology, Endocrinology, Infectious Disease, Anesthesia End User: Hospitals, Clinics, Home Healthcare, Research Institutions |
| Companies Covered | Fresenius Kabi, Hikma Pharmaceuticals, Pfizer Inc., Teva Pharmaceutical Industries, Viatris, Sandoz AG, Baxter International, Lupin Ltd., Dr. Reddy’s Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generic Injectables Market Strategic Shifts & Innovations
Continuous manufacturing and isolator-based aseptic processing are displacing conventional cleanroom batch operations, while regulatory convergence and procurement centralization reshape competitive boundaries across sterile injectable supply chains.
Isolator-based restricted access barrier systems are displacing traditional Grade A/B cleanroom suites in sterile fill-finish operations. Contract manufacturers serving United States oncology biologics are adopting these systems at accelerated pace to reduce contamination risk and personnel gowning burden. This technology shift is displacing smaller regional players lacking capital for isolator retrofit, concentrating qualified capacity among large-scale network operators.
EMA's revised GMP Annex 1 for sterile manufacture mandates contamination control strategy documentation and enhanced environmental monitoring. European facilities must implement barrier technology and rapid microbial detection methods to maintain market access. Oncology and complex parenteral segments are responding with isolator investments and process analytical technology integration to defend tender eligibility.
Hospital buying consortiums in United States and Germany are consolidating injectable procurement through single-source or dual-source agreements with penalty clauses for supply interruption. Traditional fragmented distributor networks are giving way to direct manufacturer-contracting models with volume guarantees and price protection mechanisms. This concentration is most visible in United States oncology biologics, where integrated delivery networks now control substantial hospital purchasing volume.
Generic Injectables Market Segmentation
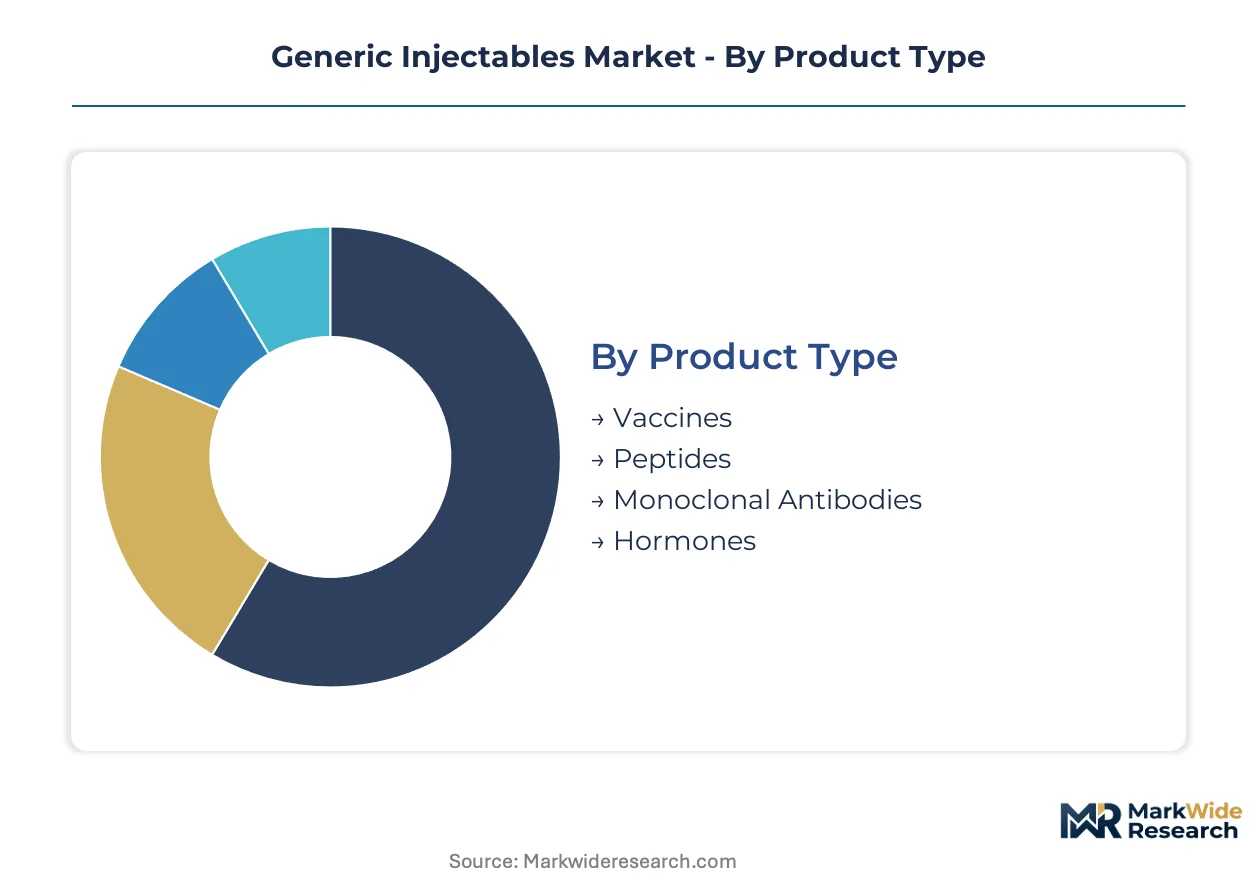
Segmentation in generic injectables reveals where sterile manufacturing complexity translates into pricing power. Product type and delivery mode stratify margin capture, while therapy area and end-user channels determine volume allocation across hospital procurement systems.
Product Type:
Margin pools concentrate in biologic-derived segments where isolator-based aseptic processing creates scarcity premiums.
- Monoclonal Antibodies:Complex glycoprotein structures demand validated single-use bioreactor trains and protein A chromatography suites. United States hospital networks concentrate procurement for oncology and immunology indications as patent expirations open substitutable opportunities.
- Peptides:Synthetic amino acid chains require solid-phase synthesis and specialized cleavage chemistry with stringent impurity profiling. German and Indian facilities with dual FDA-EMA qualifications capture premium positioning in metabolic and endocrine therapy.
- Vaccines:Adjuvanted and live-attenuated formulations serve public health procurement through government tenders.
- Hormones:Recombinant and synthetic steroid variants address endocrine replacement with established bioequivalence pathways.
The dominant share belongs to Monoclonal Antibodies, while Peptides is closing the gap fastest.
Delivery Mode:
Volume concentration tracks hospital administration workflows, with parenteral route selection driven by bioavailability requirements and patient acuity.
- Intravenous:Direct vascular administration dominates oncology biologics and emergency anesthesia in United States and German hospital systems. Large-volume infusion bags and pump-compatible presentations command sterile fill-finish capacity allocation.
- Subcutaneous:Self-administration device formats enable outpatient migration for chronic therapies. Prefilled syringes and autoinjector compatibility are expanding share in United States home healthcare channels.
- Intramuscular:Depot formulations and vaccine delivery sustain volume in clinic and public health settings.
- Intra-articular:Joint-space injections for inflammatory conditions occupy niche hospital orthopedic and rheumatology service lines.
Intravenous retains volume leadership, though Subcutaneous formats are expanding most quickly through device-enabled outpatient shift.
Therapy Area:
Procurement concentration aligns with hospital reimbursement economics and biologic patent expiration calendars.
- Oncology:Cytotoxic chemotherapies and supportive care injectables anchor hospital pharmacy budgets. United States integrated delivery networks consolidate purchasing for carboplatin, paclitaxel, and granulocyte colony-stimulating factor biosimilars.
- Anesthesia:Perioperative injectables including propofol, rocuronium, and midazolam sustain high-throughput surgical volumes. German and United States ambulatory surgery centers drive contract manufacturer allocation.
- Infectious Disease:Anti-infective parenterals including cephalosporins and carbapenems serve empiric therapy protocols.
- Endocrinology:Insulin analogs and parathyroid hormone formulations address chronic metabolic management.
Oncology commands the dominant procurement share, while Anesthesia is gaining ground fastest through ambulatory surgery expansion.
End User:
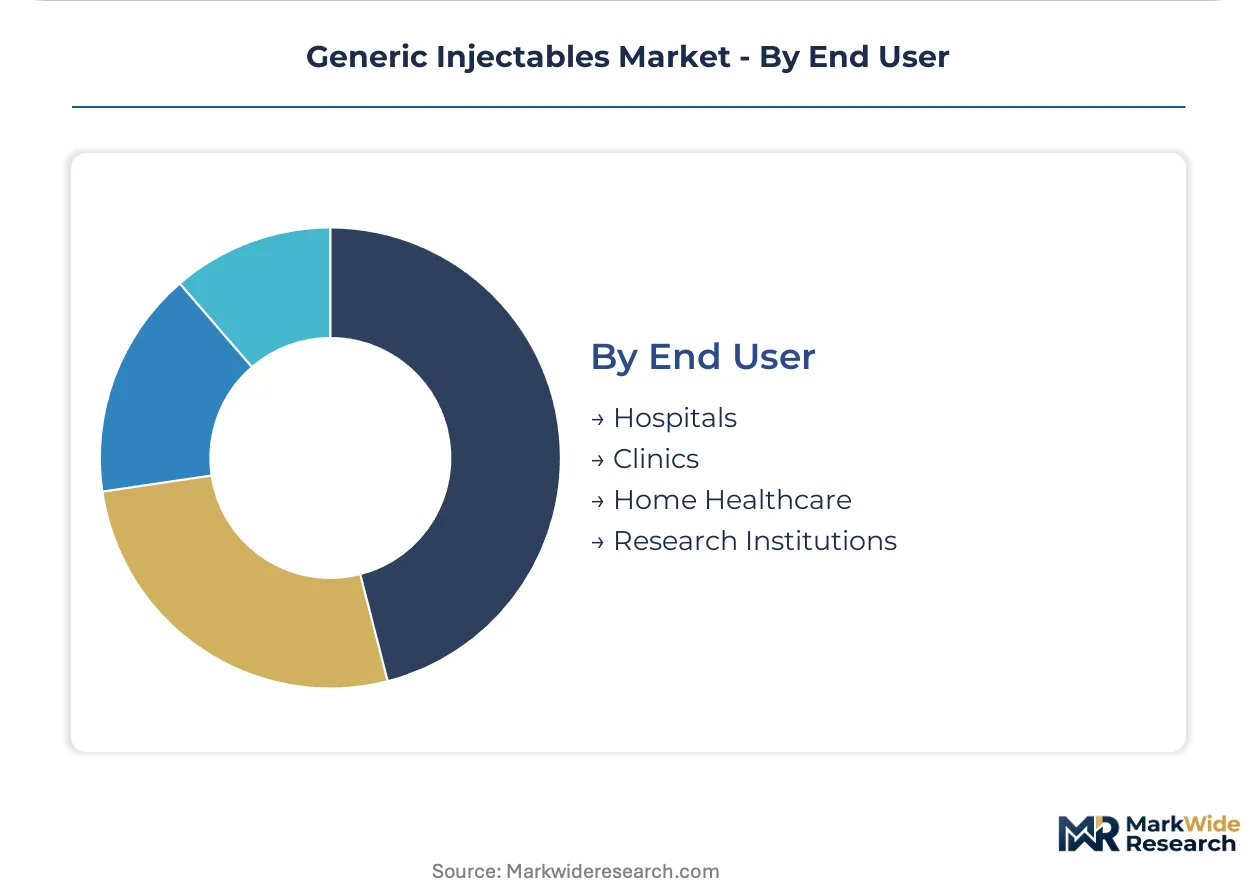
Channel economics diverge between centralized hospital purchasing and dispersed home administration.
- Hospitals:Inpatient and infusion center administration concentrates demand for high-complexity biologics requiring cold chain and clinical oversight. United States 340B program eligibility shapes generic injectable procurement for oncology and anesthesia.
- Home Healthcare:Self-administration training and remote monitoring infrastructure enable outpatient migration for chronic therapies. German disease management programs and United States Medicare home infusion benefit are accelerating channel shift.
- Clinics:Physician office administration sustains volume for vaccines and short-course anti-infectives.
- Research Institutions:Investigational product manufacturing and clinical trial material supply occupy specialized contract development segments.
Hospitals retain the dominant volume position, yet Home Healthcare is climbing the fastest through reimbursement-enabled outpatient migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement patterns diverge sharply across major markets. United States integrated delivery networks prioritize oncology biologics and 340B program eligibility, while German purchasing concentrates on anesthesia and emergency care through centralized tenders. Indian demand flows through government tenders and CDSCO-certified export channels, creating distinct volume allocation mechanics.
United States
Oncology biologics and anesthesia portfolios dominate hospital pharmacy budgets as integrated delivery networks consolidate purchasing. FDA's Quality Management Maturity program filters subscale suppliers from tender eligibility. New Jersey and North Carolina manufacturing clusters house sterile fill-finish capacity serving 340B-eligible hospitals.
Germany
Ambulatory surgery centers drive perioperative injectable demand through centralized procurement frameworks. EMA's revised GMP Annex 1 mandates contamination control strategies and barrier technology adoption. Baden-Württemberg and Bavaria host specialized facilities targeting oncology and anesthesia portfolios for European hospital networks.
India
Government tenders and CDSCO-certified export channels allocate volume across anti-infective and emergency care presentations. BIS frameworks impose parallel certification requirements for regulated market access. Maharashtra and Gujarat manufacturing clusters specialize in sterile fill-finish operations with dual FDA-EMA qualifications.
China
Domestic hospital procurement prioritizes oncology and infectious disease injectables through centralized volume-based purchasing. NMPA's evolving biosimilar pathway streamlines approval for complex parenterals. Yangtze River Delta clusters concentrate sterile manufacturing capacity serving domestic and export markets.
Switzerland
Specialized biologics and peptide manufacturing anchor the export-oriented production base. Swissmedic's stringent sterile manufacturing standards maintain premium positioning for complex parenterals. Basel-region facilities concentrate isolator-based aseptic processing for oncology and immunology portfolios.
Generic Injectables Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, creating a two-tier competitive structure in generic injectables. Plasma-to-vial infrastructure and captive API supply separate the upper tier from mid-cap manufacturers dependent on external sourcing. Three archetypes define positioning: integrated biologics specialists, regional fill-finish operators, and API-forward backward integrators. Capacity expansion and isolator technology licensing represent the dominant competitive moves as compliance costs escalate.
Among integrated European operators, Fresenius Kabi and Sandoz AG exemplify the infrastructure-heavy archetype with multi-site sterile networks spanning oncology and anesthesia portfolios. Hikma Pharmaceuticals anchors the Middle Eastern regional specialist tier through US and Jordan-based fill-finish presence. These three companies represent distinct geographic and capability positioning within the competitive matrix, illustrating how capital deployment and regulatory access shape tier membership.
| Leading Market Players |
|---|
| Fresenius Kabi |
| Hikma Pharmaceuticals |
| Pfizer Inc. |
| Teva Pharmaceutical Industries |
| Viatris |
| Sandoz AG |
| Baxter International |
| Lupin Ltd. |
| Dr. Reddy's Laboratories |
| Others |
Cost & Logistics Intelligence
Isolator-based aseptic processing displacing conventional cleanroom operations is redrawing supply geography toward capital-rich manufacturing clusters while compressing price premiums for legacy Grade A/B facilities. This substitution dynamic concentrates procurement leverage among United States integrated delivery networks and German hospital consortia that can mandate barrier technology compliance as a tender condition.
Pricing Analysis
Long-term offtake agreements with volume guarantees dominate United States oncology biologics procurement, while spot purchasing persists for emergency anti-infectives. Price differentiation rests on FDA Quality Management Maturity certification tier and isolator technology validation status. Margins are tightening due to EMA GMP Annex 1 compliance cost escalation. United States 340B-eligible hospitals exhibit highest price sensitivity, whereas Swissmedic-certified facilities command premium positioning with least sensitivity.
Supply Chain Analysis
Strategic stockpiling of glass vials and elastomer components has replaced just-in-time inventory preferences as container-closure shortages extend sterile fill-finish lead times. Supply concentrates in India, China, and Germany for active pharmaceutical ingredients and specialized packaging materials. Critical dependencies include Chinese heparin starting materials, Indian cephalosporin intermediates, and German isolator technology. Single-source vulnerability for high-purity glass tubing creates exposure to export restriction shocks. Distribution runs through direct manufacturer-contracting models with hospital buying consortiums displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's revised GMP Annex 1 mandates are accelerating a capital-intensity disruption that favors sterile manufacturing specialists with validated isolator infrastructure over subscale regional competitors.
For Market Incumbents: Shield market position through captive API supply integration and isolator technology licensing to contract manufacturing networks. Fresenius Kabi's plasma-to-vill infrastructure demonstrates how backward integration into starting materials defends margin compression from Chinese export policy volatility. Prioritize Baden-Württemberg and North Carolina capacity additions to anchor tender eligibility with United States and German hospital systems.
For New Entrants and Emerging Players: Anchor in peptide and monoclonal antibody white space where qualified aseptic capacity scarcity creates premium positioning opportunities. Indian CDSCO-certified export channels offer the most penetrable regulatory pathway for facilities with dual FDA-EMA qualifications. Pursue government tender participation in Middle Eastern emergency care procurement as the primary go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap manufacturers with isolator retrofit capability and existing regulatory dossiers. Long-term viability hinges on facility qualification breadth across United States, European, and Indian regulatory clusters. Target acquisition archetypes include sterile fill-finish operators with validated barrier technology and established hospital system relationships. Watch FDA Quality Management Maturity program enrollment rates as the signal for competitive filtering velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Retrofit | EMA GMP Annex 1 compliance defends tender eligibility for European oncology and anesthesia portfolios. |
| Dual FDA-EMA Facility Qualification | CDSCO export certification enables Indian manufacturers to capture regulated market share through parallel compliance. |
| Captive API Supply Integration | Backward integration into Chinese and Indian starting materials mitigates export restriction vulnerability for sterile fill-finish operations. |
| Hospital System Direct Contracting | United States integrated delivery network partnerships displace fragmented distributor networks with volume guarantee structures. |
| Self-Administration Device Compatibility | Prefilled syringe and autoinjector formats accelerate United States and German home healthcare channel migration. |
Research Approach
Operator-level perspectives from sterile manufacturing directors, hospital pharmacy procurement managers, regulatory affairs leads, and GPO contract specialists anchored the qualitative base. Primary interview insights combined with FDA filing databases, EMA inspection records, CDSCO export certification registries, and hospital tender documentation. Bottom-up facility capacity modeling and top-down therapy-area demand estimation provided cross-validation across the analysis window.
Sensitivity analysis tested forecast robustness against API supply disruption scenarios and regulatory timeline compression assumptions. Segmentation modeling spanned product type complexity tier, delivery mode, therapy area reimbursement economics, end-user channel, and regional regulatory cluster. CAGRs derived from facility utilization trajectories, patent expiration calendars, and procurement volume shift patterns. Forecast inputs included isolator technology adoption curves and hospital buying consortium concentration metrics.
Material uncertainties — biologic patent litigation outcomes, container-closure supply shocks, and pharmacovigilance obligation expansion — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory pathway stability and tender eligibility criteria continuity. Revision becomes warranted when FDA Quality Management Maturity program participation thresholds cross hospital system procurement mandate levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Diagnostic Specialty Antibodies Market
Biopharmaceuticals
Insulin Aspart Market
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
Insulin Market
Biopharmaceuticals
Canada Generic Drug Market
Biopharmaceuticals
Protein Kinase B Inhibitors Market
Biopharmaceuticals
Tamiflu (Oseltamivir Phosphate) Market
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Recombinant Human Serum Albumin Market
Biopharmaceuticals
Metabolism Drugs Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Vaccine Production Market
Biopharmaceuticals
Amphotericin B Market
Biopharmaceuticals
Bioactive Protein and Peptides Market
Biopharmaceuticals
Female Infertility Drugs Market
Biopharmaceuticals
Rhu Albumin Market