
 Recombinant Human Serum Albumin Market | 2026-2036
Recombinant Human Serum Albumin Market Size, Share, and Industry Trends Forecast 2026-2036
Recombinant Human Serum Albumin Market Outlook
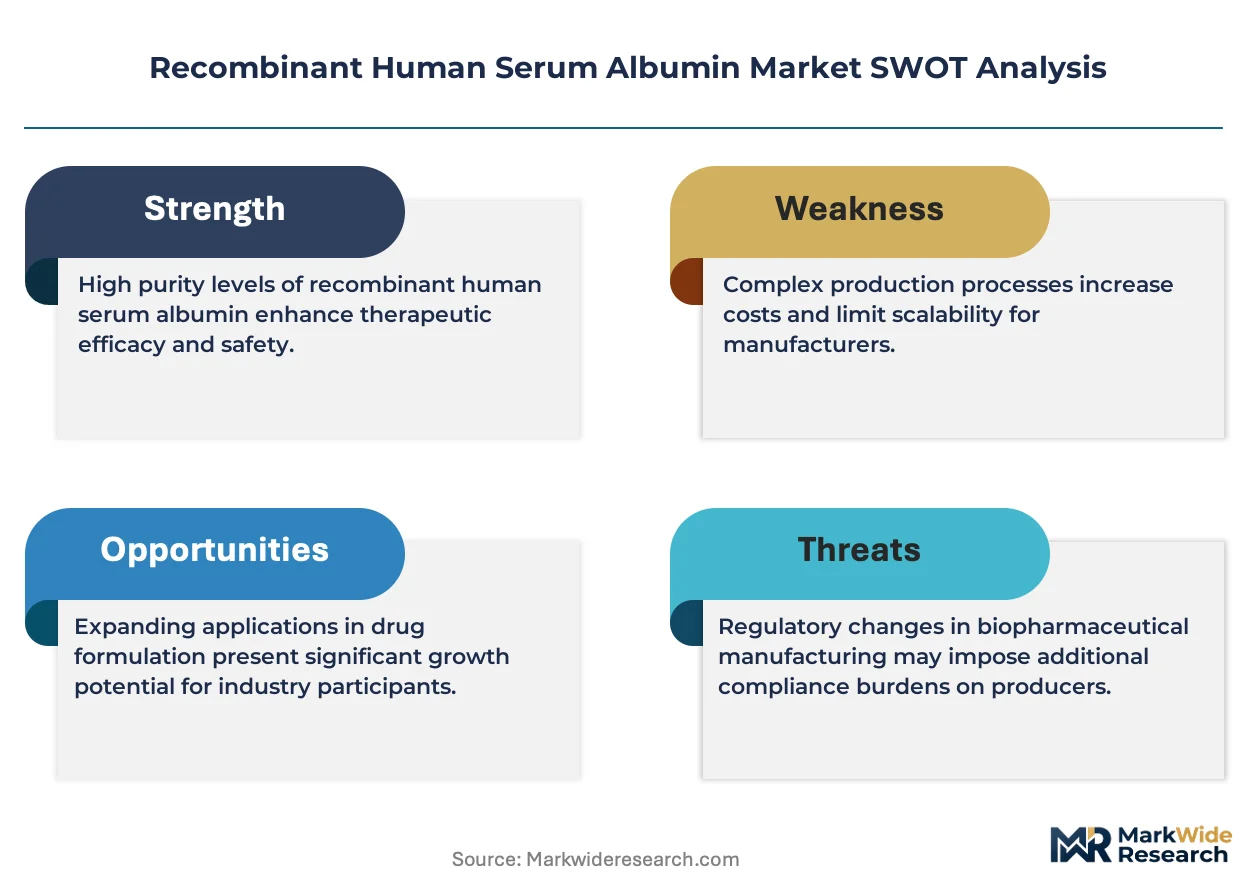
Pharmaceutical-grade specifications are bifurcating the competitive landscape into GMP-certified suppliers and research-grade commodity providers. Albumedix leverages its proprietary yeast expression platform to sustain European dominance in high-purity recombinant albumin for therapeutic applications. Merck KGaA anchors its position through backward integration into cell culture media, while Thermo Fisher Scientific extends global distribution reach across pharmaceutical and diagnostic end users.
Recombinant human serum albumin is a non-glycosylated, single-chain protein of 585 amino acids produced via microbial or plant-based expression systems, functioning primarily as a stabilizer, carrier, and osmoregulator in biopharmaceutical formulations. Pharmaceutical-grade material commands premium positioning due to stringent endotoxin and purity thresholds required for injectable therapeutics, whereas diagnostic-grade segments compete on lot-to-lot consistency for immunoassay manufacturers. Research-grade supply occupies a fragmented tier serving academic institutions with lower regulatory burden but higher price sensitivity.
FDA guidelines on animal-origin-free excipients, EMA's Good Manufacturing Practice Annex 2 for biologicals, and China's NMPA biologics manufacturing standards collectively elevate compliance costs while accelerating recombinant substitution for plasma-derived albumin. Regulatory divergence between FDA process validation requirements and EMA's evolving biosimilar frameworks forces manufacturers to maintain dual-track quality systems. Stakeholders must monitor how CDMO consolidation and national biosecurity initiatives reshape captive versus merchant supply strategies.
Market Dynamics
Regulatory mandates for animal-origin-free excipients are compressing timelines for recombinant albumin substitution across parenteral drug formulations, forcing biopharmaceutical manufacturers to requalify supply chains ahead of FDA and EMA enforcement milestones.
Growth Catalysts
- FDA excipient guidelines:Tightening restrictions on plasma-derived materials in injectable biologics are accelerating recombinant albumin qualification programs at US-based monoclonal antibody manufacturers.
- Regenerative medicine expansion:China's cell therapy sector is scaling GMP-compliant recombinant albumin consumption for stem cell culture media and cryopreservation formulations.
- Yeast expression maturation:Pichia pastoris platform yields now match therapeutic-grade purity thresholds, enabling cost-competitive displacement of plasma-derived alternatives in high-volume applications.
Market Restraints
- Upstream raw material concentration:Fermentation-grade yeast extract and defined media components face supply bottlenecks from a concentrated European supplier base.
- Regulatory friction:Divergent FDA process validation requirements and EMA biosimilar frameworks force dual-track quality system maintenance, elevating compliance overhead.
- Plasma-derived substitution inertia:Established albumin suppliers leverage long-term hospital formulary contracts to delay recombinant adoption in volume-driven markets.
Strategic Opportunities
- Vaccine adjuvant applications:Recombinant albumin is penetrating novel mRNA and viral vector vaccine formulations as a stabilizer alternative to polysorbate excipients.
- CDMO captive supply models:Chinese biologics manufacturers are integrating in-house recombinant albumin production to secure supply chain autonomy under national biosecurity initiatives.
- Plant-based expression:Nicotiana benthamiana systems offer endotoxin-free production pathways for diagnostic-grade material serving immunoassay manufacturers.
Industry Challenges
- GMP certification timelines:New manufacturing facilities face 18-24 month EMA Annex 2 compliance validation cycles before commercial release.
- Host cell protein clearance:Yeast-derived mannoprotein removal requires multi-step chromatography, compressing yields and elevating batch failure rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recombinant Human Serum Albumin Market |
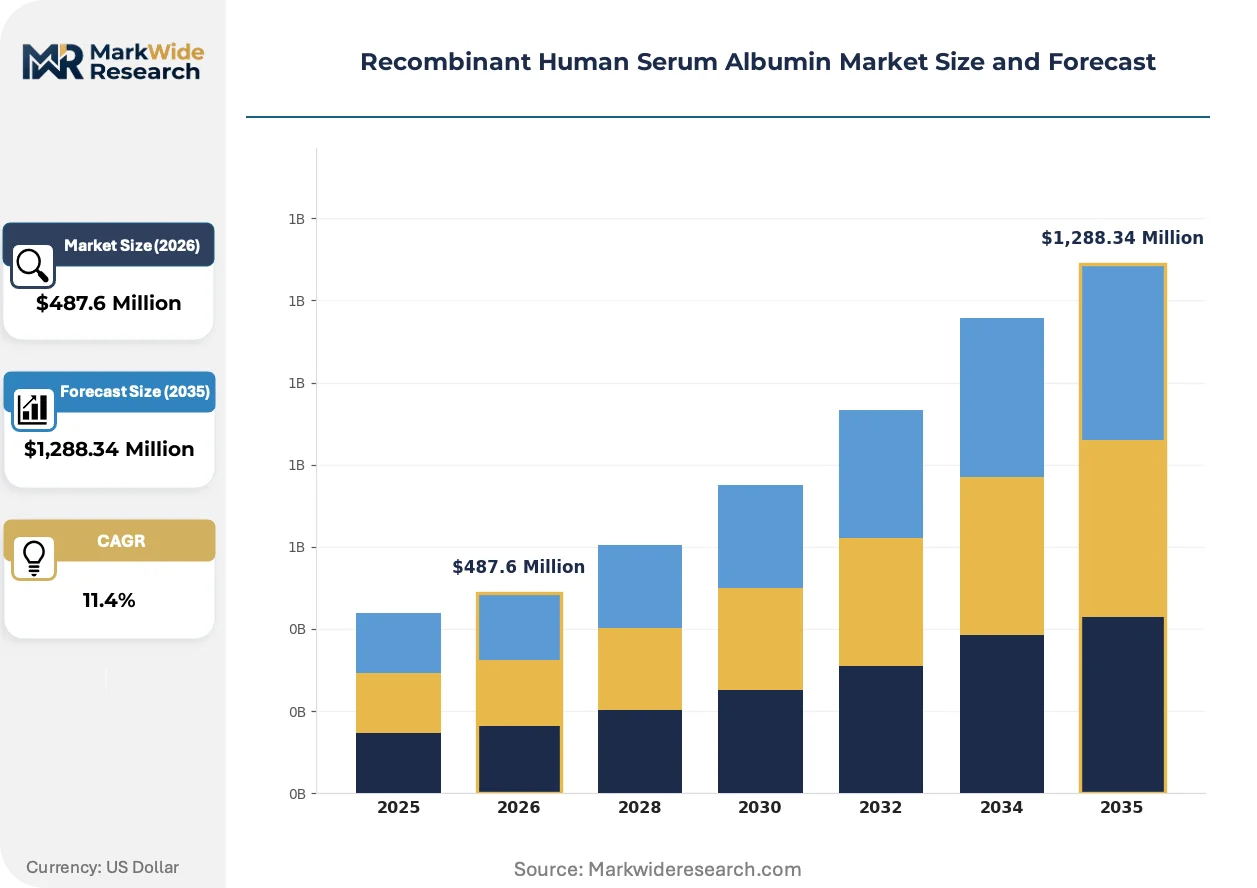
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Diagnostic Grade, Research Grade, Analytical Grade Application: Drug Delivery, Therapeutics, Diagnostic Testing, Blood Substitute End User: Hospitals, Research Institutions, Pharmaceutical Companies, Diagnostic Laboratories Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Others |
| Companies Covered | Albumedix, Merck KGaA, Ventria Bioscience, InVitria, Sartorius AG, NCPC, HiMedia Laboratories, Thermo Fisher Scientific, ACROBiosystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recombinant Human Serum Albumin Market Strategic Shifts
Expression platform diversification and regulatory harmonization pressures are converging to reshape how recombinant albumin manufacturers compete on purity, scale, and geographic proximity to biopharmaceutical clusters.
Continuous perfusion bioreactor technology is displacing traditional fed-batch fermentation in recombinant albumin production. Contract manufacturers in Singapore and South Korea are adopting perfusion systems to achieve higher cell densities and reduce facility footprint. This shift is compressing capital requirements for new entrants while enabling rapid scale-up to multi-tonne annual outputs.
EMA's evolving biosimilar framework for recombinant proteins is creating compliance complexity for albumin suppliers seeking multi-territory approval. The regulator's emphasis on comparability protocols for post-translational modifications is forcing manufacturers to invest in advanced analytical characterization. High-purity therapeutic-grade segments are responding by segregating European-bound production lines from research-grade batches.
Biopharmaceutical procurement teams are consolidating excipient suppliers to reduce qualification burden and audit frequency. Large molecule drug developers are replacing fragmented multi-source albumin purchasing with single-source strategic partnerships backed by long-term offtake agreements. This concentration is most visible in the United States, where top-ten biopharma accounts now drive the majority of pharmaceutical-grade volume negotiations.
Recombinant Human Serum Albumin Market Segmentation
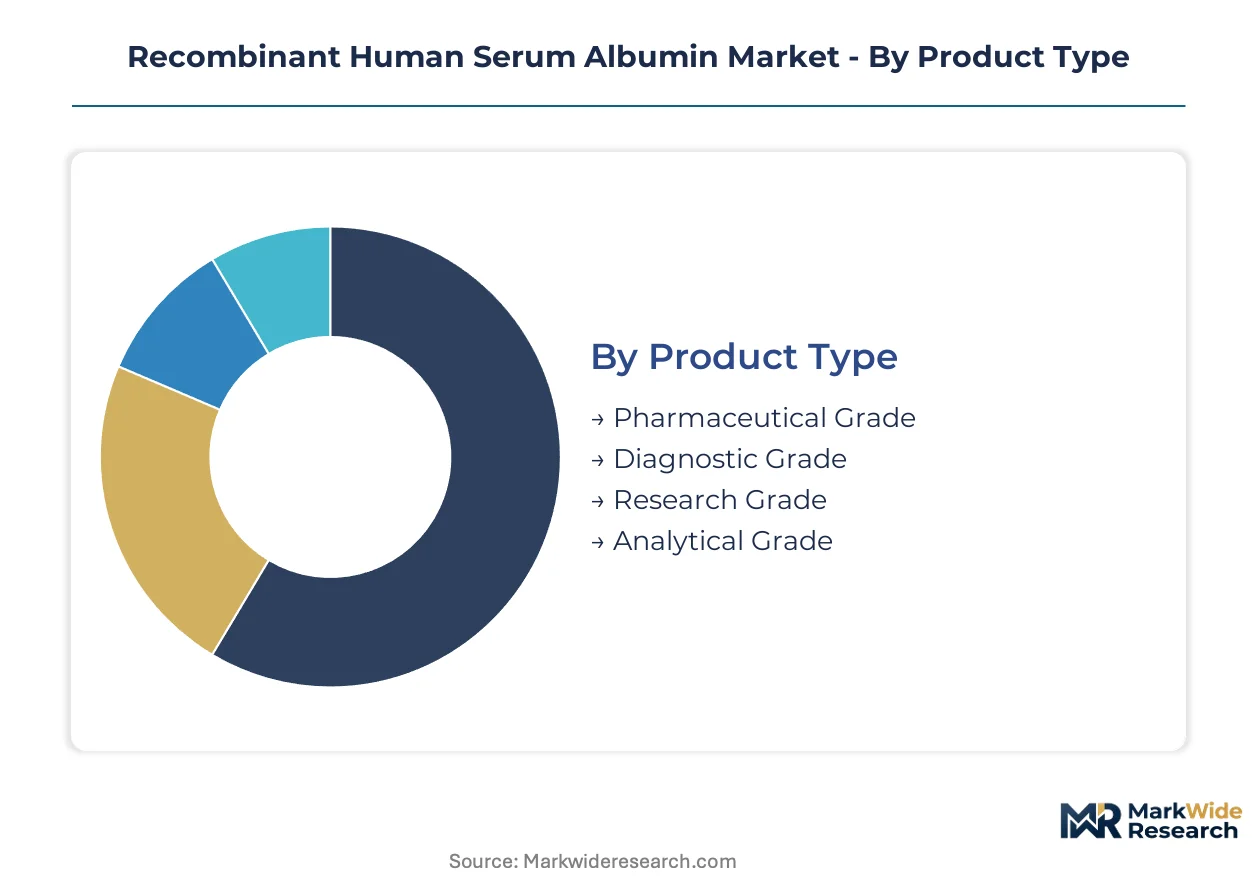
Recombinant human serum albumin manufacturers navigate distinct qualification pathways for each grade tier, with pharmaceutical and diagnostic channels demanding divergent purity certifications and supply chain documentation. Segmentation by application and end user reveals how regulatory burden and volume economics split procurement strategies across injectable therapeutics, cell culture media, and immunoassay manufacturing.
Product Type:
Pharmaceutical-grade material flows through qualified supplier programs into monoclonal antibody and cell therapy formulations, while diagnostic and research grades distribute through catalog channels with lighter documentation requirements.
- Pharmaceutical Grade:This tier meets endotoxin thresholds below 0.03 EU/mg and purity specifications exceeding 99% for parenteral administration. US-based biopharmaceutical manufacturers are consolidating supplier qualifications under FDA process validation guidelines, compressing the approved vendor list to GMP-certified facilities with dedicated production lines.
- Diagnostic Grade:Lot-to-lot consistency for immunoassay manufacturers defines this segment, with specifications targeting coefficient of variation below 2% across enzyme-linked immunosorbent assay applications. Chinese diagnostic CDMOs are scaling consumption for infectious disease test kit production under NMPA in-vitro diagnostic regulations.
- Research Grade:Academic procurement channels serve cell biology and protein chemistry laboratories with lower regulatory overhead but higher price elasticity.
- Analytical Grade:Chromatography and mass spectrometry reference standards require defined impurity profiles for method validation in quality control laboratories.
By volume, Pharmaceutical Grade leads. By growth pace, Diagnostic Grade is climbing the fastest.
Application:
Cost tier differentiation separates high-value therapeutic applications from commodity diagnostic consumption, with drug delivery commanding premium positioning against blood substitute volume plays.
- Drug Delivery:Nanoparticle stabilization and half-life extension for biologics drive formulation demand. PEGylated protein and lipid nanoparticle developers in Germany and Switzerland are qualifying recombinant albumin as a polysorbate alternative under EMA biosimilar excipient guidance.
- Therapeutics:Direct infusion for hypoalbuminemia and surgical blood volume expansion requires plasma-derived matching pharmacokinetics. Japanese regulators at PMDA are evaluating recombinant alternatives for national blood product security under METI biosecurity initiatives.
- Diagnostic Testing:Immunoassay blocking buffers and calibrator matrices consume standardized research-grade supply.
- Blood Substitute:Oxygen-carrying hemoglobin and perfluorocarbon formulations target military and emergency medicine procurement with cost-sensitive volume specifications.
Drug Delivery captures the highest margin pool. Therapeutics is expanding most quickly as hospital formularies convert from plasma-derived sources.
End User:
Customer type determines contract structure, with pharmaceutical companies negotiating multi-year offtake agreements against spot purchasing patterns in research institutions.
- Pharmaceutical Companies:Excipient qualification programs for monoclonal antibody and gene therapy developers mandate dedicated manufacturing suites and audit rights. Top-ten biopharma accounts in the United States now drive majority volume negotiations through consolidated supplier panels.
- Hospitals:Blood product procurement departments manage albumin inventory for critical care and surgical applications, with long-term plasma-derived contracts creating substitution inertia.
- Research Institutions:Academic laboratories purchase through distribution intermediaries with higher price sensitivity and fragmented order patterns.
- Diagnostic Laboratories:Reference labs and IVD manufacturers integrate recombinant albumin into automated assay platforms with stringent lot-to-lot consistency requirements.
Pharmaceutical Companies dominate contract value. Hospitals are gaining share fastest as therapeutic substitution accelerates.
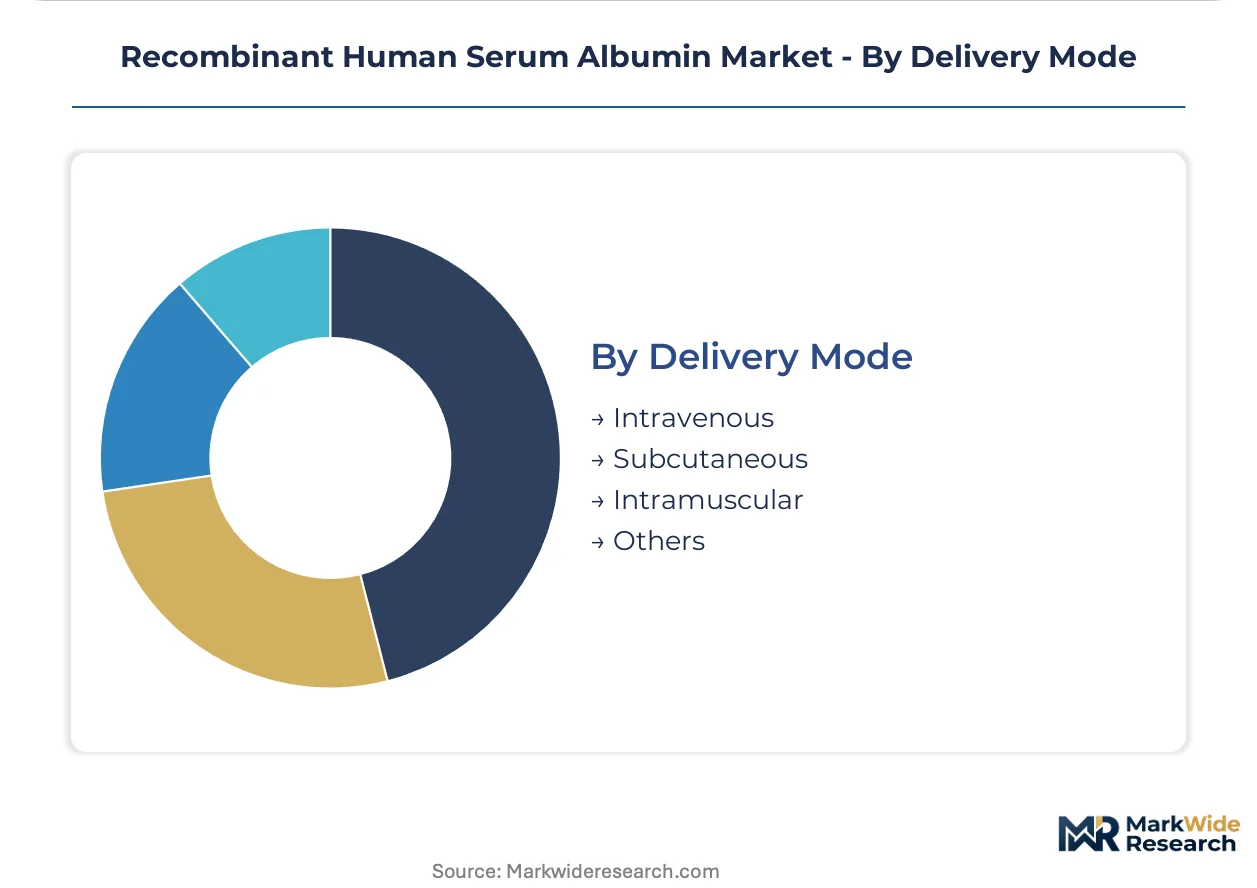
Delivery Mode:
Supply concentration varies by administration route, with intravenous formulations requiring the most stringent endotoxin controls and subcutaneous applications enabling broader supplier participation.
- Intravenous:Parenteral infusion demands pyrogen-free certification and particulate matter controls per USP <788> and EP 2.9.19 specifications. Singaporean and South Korean CDMOs are installing dedicated IV-grade production lines to serve regional biopharma clusters.
- Subcutaneous:Self-administered biologics and hormone formulations tolerate broader supplier qualification, enabling cost-competitive sourcing from yeast expression platforms.
- Intramuscular:Vaccine adjuvant applications require aluminum compatibility and thermal stability profiles distinct from standard therapeutic grades.
- Others:Topical and ophthalmic formulations occupy niche positions with specialized viscosity and osmolality specifications.
Intravenous commands the largest volume base. Subcutaneous is on the steepest expansion trajectory as self-administered biologics multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal concentrated supply from European and North American producers against surging Asian demand, with Chinese CDMOs driving the steepest volume growth as domestic biosecurity initiatives reshape trade flows.
United States
FDA process validation guidelines for animal-origin-free excipients are compressing qualification timelines at monoclonal antibody manufacturers. Biopharmaceutical procurement teams in Massachusetts and California are consolidating supplier panels to reduce audit burden. The Greater Boston cluster anchors therapeutic-grade consumption as gene therapy developers scale GMP-compliant formulations.
Germany
EMA Annex 2 compliance requirements are elevating manufacturing standards for parenteral-grade material. The country's national pharmaceutical regulator enforces stringent endotoxin thresholds for injectable biologics. The Rhine-Main biotech corridor around Frankfurt hosts specialized CDMOs installing dedicated IV-grade production lines for regional biopharma clients.
China
NMPA biologics manufacturing standards are accelerating GMP facility construction for regenerative medicine applications. National biosecurity initiatives under the 14th Five-Year Plan prioritize captive recombinant albumin supply for cell therapy developers. The Suzhou and Shanghai biotech clusters concentrate domestic CDMO capacity scaling under dual carbon compliance frameworks.
Japan
METI biosecurity programs are evaluating recombinant alternatives to plasma-derived albumin for national blood product security. PMDA regulatory pathways for therapeutic substitution require pharmacokinetic matching studies. The Kanto region around Tokyo anchors hospital formulary conversion programs as surgical blood volume expansion demand stabilizes.
Singapore
Continuous perfusion bioreactor adoption is compressing capital requirements for new manufacturing entrants. The country's national pharmaceutical regulator aligns with PIC/S standards for multi-territory export certification. The Tuas Biomedical Park concentrates contract manufacturing investments serving Asia-Pacific biopharma clusters with rapid scale-up capabilities.
Recombinant Human Serum Albumin Market Competitive Environment
Concentration sits with GMP-certified specialists and diversified life science conglomerates. The vendor base splits between yeast-expression platform owners and distribution-anchored diversified suppliers. Three archetypes dominate: proprietary platform developers, backward-integrated media suppliers, and catalog-channel distributors. Competitive moves center on capacity expansion in Asian biotech corridors and strategic partnerships locking long-term offtake agreements with top-ten biopharma accounts.
Among European platform specialists, Albumedix exemplifies the proprietary yeast-expression archetype sustaining therapeutic-grade positioning. Merck KGaA anchors the backward-integrated tier through in-house cell culture media production. Thermo Fisher Scientific occupies the distribution-anchored position extending global reach across pharmaceutical and diagnostic end users.
| Leading Market Players |
|---|
| Albumedix |
| Merck KGaA |
| Ventria Bioscience |
| InVitria |
| Sartorius AG |
| NCPC |
| HiMedia Laboratories |
| Thermo Fisher Scientific |
| ACROBiosystems |
| Others |
Value Chain & Pricing Dynamics
Plasma-derived albumin displacement by recombinant alternatives simultaneously concentrates supply geography in GMP-certified European and North American facilities while compressing pricing economics across all grade tiers. Yeast expression platform maturation enables cost-competitive substitution, yet endotoxin clearance requirements preserve premium positioning for pharmaceutical-grade material against diagnostic and research-grade commoditization.
Pricing Analysis
Biopharmaceutical procurement teams anchor contract-based long-term offtake pricing, with pharmaceutical-grade material commanding substantial premiums over diagnostic and research tiers based on FDA process validation certification and dedicated manufacturing suite access. Price differentiation stems from endotoxin threshold compliance and geographic delivery cost, with Singaporean and South Korean CDMOs undercutting European suppliers on freight-adjusted terms. Margins are tightening due to yeast extract raw material inflation and multi-step chromatography yield compression. Research institutions exhibit highest price sensitivity, while gene therapy developers show least elasticity given qualification timeline constraints.
Supply Chain Analysis
Fermentation-grade yeast extract supply concentrates in Germany, Denmark, and the Netherlands, creating single-source vulnerability for defined media components essential to Pichia pastoris expression. Recombinant albumin production draws from concentrated European supplier bases for yeast extract, chromatography resins, and WFI-grade water systems. Tariff exposure on Chinese-sourced chromatography media elevates cost uncertainty for new facility ramp-ups. Distribution runs through qualified supplier programs for pharmaceutical-grade tiers, with catalog-channel intermediaries serving diagnostic and research segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as top-ten biopharmaceutical accounts consolidate excipient supplier panels, compressing vendor counts and extending audit leverage across qualification timelines.
For Market Incumbents: Compound GMP certification advantages by securing dedicated production line commitments from monoclonal antibody developers in Massachusetts and California before EMA Annex 2 compliance timelines lengthen. Anchor backward integration into yeast extract supply through offtake agreements with European fermentation media specialists, neutralizing raw material concentration risk that threatens margin stability. For New Entrants and Emerging Players: Anchor in plant-based expression platforms using Nicotiana benthamiana systems to penetrate diagnostic-grade immunoassay supply, where endotoxin-free production commands lot-to-lot consistency premiums. Target Chinese regenerative medicine CDMOs with captive supply partnership structures aligned to national biosecurity initiatives, bypassing established plasma-derived formulary contracts that block therapeutic-grade entry. For Investors and Strategic Acquirers: Capital is best deployed toward yeast-expression platform owners with existing EMA Annex 2 certification and unutilized perfusion bioreactor capacity across the analysis window. Watch for inflection when Chinese NMPA biologics manufacturing standards trigger mandatory GMP facility upgrades, accelerating consolidation among uncertified domestic suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Facility Certification | EMA Annex 2 compliance unlocks pharmaceutical-grade contract eligibility with European biopharma. |
| Perfusion Bioreactor Adoption | Singaporean CDMOs compress capital requirements while achieving multi-tonne annual outputs. |
| Captive Supply Integration | Chinese cell therapy developers secure supply chain autonomy under METI biosecurity frameworks. |
| Plant-Based Expression Scale-Up | Nicotiana benthamiana systems penetrate diagnostic-grade immunoassay manufacturing with endotoxin-free production. |
| Long-Term Offtake Agreements | Top-ten US biopharma accounts lock dedicated production lines through consolidated supplier panels. |
Study Parameters
The analysis maps pharmaceutical-grade, diagnostic-grade, and research-grade supply tiers, each validated through formulation scientists at monoclonal antibody developers, regulatory affairs leads at CDMOs, and hospital procurement managers managing blood product formularies. Primary interview findings triangulate against FDA 483 inspection observations, EMA GMP inspection reports, ClinicalTrials.gov excipient disclosure data, and customs trade records for fermentation media imports. Bottom-up volume estimates from facility capacity announcements reconcile with top-down consumption projections derived from biopharmaceutical production trends.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models segmentation by product grade tier, application category, end-user type, and delivery mode, with CAGRs derived from elasticity-adjusted substitution curves for plasma-derived displacement. Forecast inputs incorporate Pichia pastoris yield improvement trajectories, regulatory compliance timeline assumptions, and CDMO captive supply adoption rates in Chinese regenerative medicine clusters.
Material uncertainties — regulatory divergence between FDA process validation and EMA biosimilar frameworks, yeast extract supply disruption, and plasma-derived contract renewal inertia — sit outside the modeled envelope. Forecasts reflect assumptions about GMP certification velocity and expression platform cost convergence. Practitioners should keep alternative scenarios live as NMPA biologics manufacturing standards and national biosecurity initiatives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
Global MRSA Drugs Market
Biopharmaceuticals
Daptomycin Market
Biopharmaceuticals
Atipamezole Market
Biopharmaceuticals
Glycosylated Peptide Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Biopharmaceutical Oral Drug Delivery Market
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
Global Levofloxacin Market
Biopharmaceuticals
Generic Oncology Drugs Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
Global Endocrinology Drugs Market
Biopharmaceuticals
Ocular Tuberculosis Therapeutics Market
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
Paediatric Oncology Therapeutics Market