
 GPIO Expanders Market | 2026-2036
GPIO Expanders Market Size, Share, and Industry Trends Forecast 2026-2036
GPIO Expanders Market Foresight
Embedded firmware engineering talent is rotating toward mixed-signal design teams as GPIO expander architectures grow more complex. Texas Instruments leverages its broad analog portfolio to sustain integrated expander-plus-level-shifter bundles. NXP Semiconductors anchors automotive-qualified portfolios with AEC-Q100 variants for body electronics modules. Microchip Technology specializes in low-pin-count expanders that compete on board-space efficiency for space-constrained IoT endpoints.
GPIO expanders are integrated circuits that multiply the number of general-purpose input/output pins available to a host microcontroller or processor, typically communicating via I2C or SPI buses at clock speeds up to 400 kHz or 10 MHz respectively, and are used to control LEDs, read switches, or manage peripheral devices without redesigning the base processor. I2C expanders dominate unit shipments due to their two-wire simplicity and widespread driver support across Linux and RTOS environments. SPI expanders capture higher-margin slots in industrial automation where deterministic latency matters for robotic motor control. Low-power CMOS variants are gaining design wins in battery-operated IoT devices as sleep-current specifications tighten below one microamp.
The EU Ecodesign Directive and REACH compliance frameworks constrain material choices and standby power budgets for expanders sold into European consumer and industrial channels. The FDA's quality system regulations shape traceability requirements for expanders incorporated into medical device subassemblies in the United States. Stakeholders must monitor how automotive functional safety standards migrate from powertrain domains into body electronics where GPIO expanders proliferate.
Market Dynamics
The EU Green Deal's Ecodesign standby power limits are compressing peripheral IC power budgets while industrial automation OEMs scale robotics control board procurement, creating simultaneous pull and push forces across GPIO expander supply chains.
Growth Catalysts
- Industrial Robotics Density:Automotive and electronics manufacturing lines in Germany's Munich-Stuttgart corridor are expanding multi-axis robotic cells that demand deterministic GPIO expansion for motor control interfaces.
- REACH Material Compliance:European Ecodesign Directive enforcement is accelerating redesign cycles for low-power CMOS variants that eliminate restricted substances from package substrates.
- Battery-Operated IoT Proliferation:Smart home and industrial sensor nodes require sub-microamp sleep-current expanders to extend field deployment lifecycles without battery replacement.
Market Restraints
- Silicon Wafer Input Volatility:Foundry capacity allocation for mature-node mixed-signal processes constrains expander die availability during automotive MCU demand surges.
- Single-Source Concentration Risk:Taiwan-based packaging and test houses handle disproportionate volumes of small-outline expander packages, exposing supply continuity to geopolitical friction.
- Integrated MCU Substitution:Advanced 32-bit microcontrollers with native 80+ GPIO pins are absorbing expander functions in cost-sensitive consumer electronics designs.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor assembly and test are attracting expander packaging investments to serve domestic appliance and automotive markets.
- Medical Device Traceability:FDA quality system regulations are mandating component-level documentation that favors qualified expander suppliers with established Device History Record capabilities.
- SPI-I2C Convergence:Dual-interface expanders that auto-negotiate bus protocols are capturing design wins in platform products serving both Linux-based industrial controllers and bare-metal IoT endpoints.
Industry Challenges
- Mixed-Signal Firmware Talent Scarcity:Embedded engineering teams lack depth in simultaneous analog characterization and digital protocol stack optimization required for modern expander architectures.
- AEC-Q100 Certification Timelines:Automotive body electronics qualification cycles extend 18-24 months, delaying revenue recognition for expander variants targeting next-generation vehicle platforms.
- Legacy I2C Bus Integration:Brownfield industrial automation systems running 100 kHz legacy clock speeds require careful timing margin analysis when cascading modern 400 kHz-capable expander devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GPIO Expanders Market |
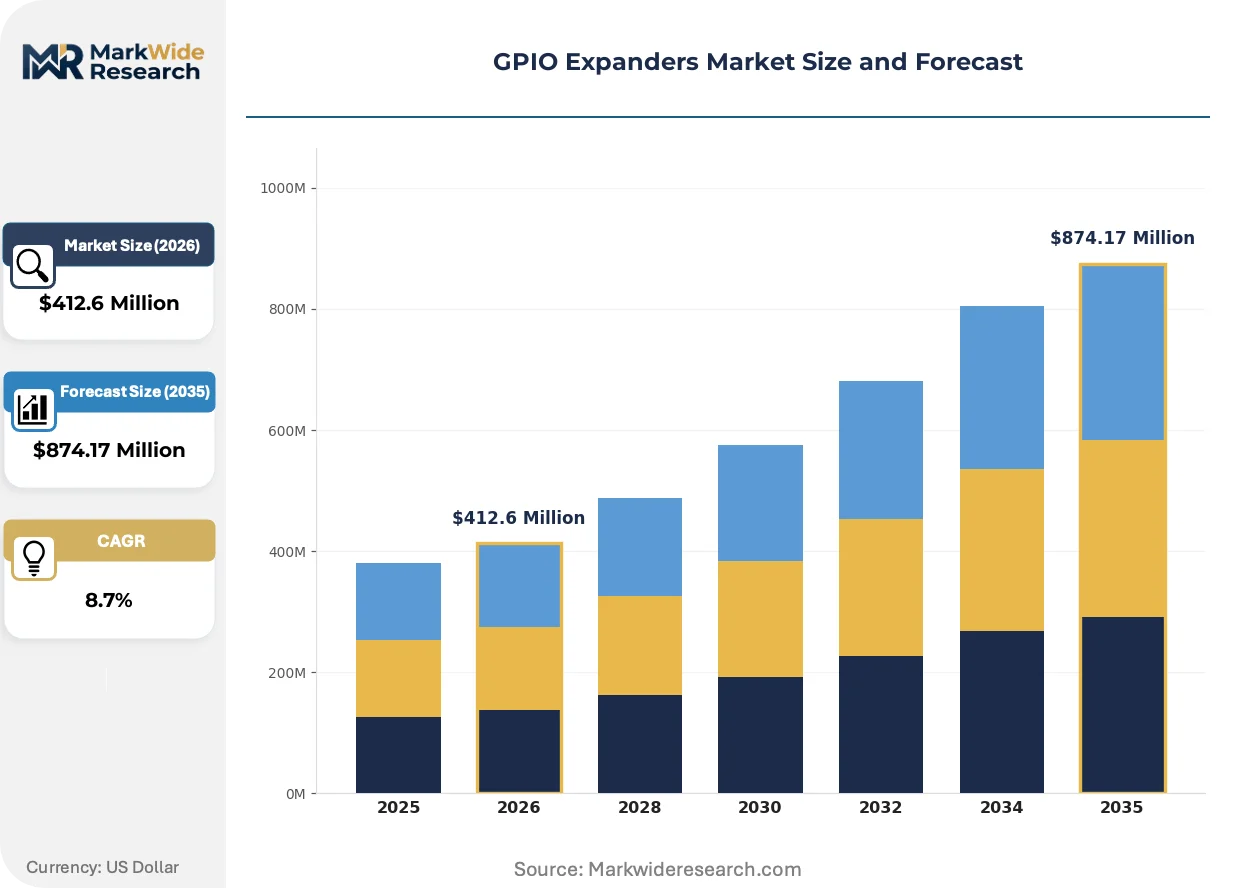
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: I2C Expanders, SPI Expanders, Parallel Expanders, Serial Expanders Technology: Low-Power, High-Speed, Bi-Directional, CMOS End User: Consumer Electronics, Automotive, Industrial Automation, Medical Devices Application: Robotics, Home Automation, IoT Devices, Communication Systems |
| Companies Covered | NXP Semiconductors, Texas Instruments, Microchip Technology, STMicroelectronics, Analog Devices, Maxim Integrated, ON Semiconductor, Renesas Electronics, Lattice Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GPIO Expanders Market Shifts & Advancements
Active developments across three vectors are compressing expander design cycles: process technology migration, regulatory power budgeting, and procurement model restructuring toward qualified supplier consolidation.
Integrated level-shifter functionality is supplanting discrete voltage translation components in robotics control boards. Automotive body electronics modules operating at 3.3V and 5V domains simultaneously are adopting these combined devices to reduce BOM line items. The structural consequence is margin compression for standalone level-shifter suppliers as expander vendors capture that socket.
EU F-Gas Regulation phase-down schedules are indirectly pressuring semiconductor manufacturing by constraining etching gas availability for wafer processing. Foundries serving mixed-signal expander production are qualifying alternative chemistries to maintain throughput. European industrial automation OEMs are prioritizing suppliers with demonstrated supply chain resilience documentation.
Consolidated vendor qualification is displacing multi-source commodity purchasing in medical and automotive verticals. Procurement teams are reducing approved vendor lists to three or fewer qualified expander suppliers per socket to simplify compliance auditing. This concentration is most pronounced in FDA-regulated device manufacturing where component traceability requirements dominate supplier selection criteria.
GPIO Expanders Market Segmentation
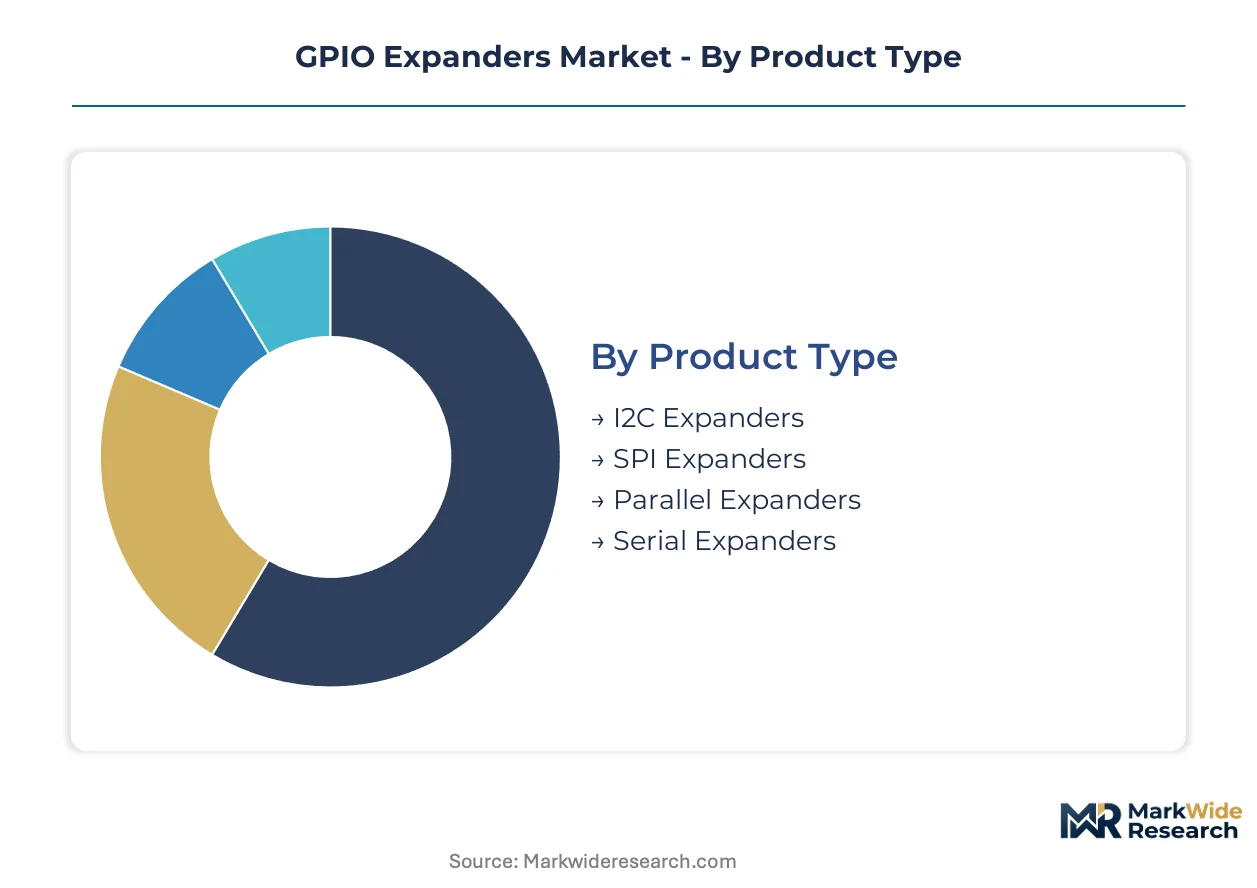
GPIO expander segmentation reveals how interface protocols, power architectures, and end-use requirements fragment procurement patterns across electronics supply chains. Discrete segment boundaries are blurring as vendors bundle level-shifters and multi-protocol support into unified platforms.
Product Type:
I2C expanders face the most acute substitution pressure from integrated MCUs with native high-pin-count GPIO, while SPI variants defend socket retention through deterministic latency performance in motion control applications.
- I2C Expanders:Two-wire serial interfaces operating at 100-400 kHz dominate unit shipments through Linux driver ubiquity and minimal PCB trace requirements. Demand concentrates in Germany's Munich-Stuttgart automotive corridor for body electronics modules where wire count reduction matters. REACH-compliant low-power variants are accelerating redesign cycles as Ecodesign standby limits tighten.
- SPI Expanders:Four-wire full-duplex architectures achieve 10 MHz clock speeds with predictable latency for robotic motor control interfaces. Industrial automation OEMs in Bavaria specify these for multi-axis positioning systems where timing jitter must stay below 50 nanoseconds. The segment captures premium pricing against I2C alternatives.
- Parallel Expanders:Direct byte-wide port expansion serves legacy industrial controllers with 8-bit data bus architectures.
- Serial Expanders:Single-wire implementations reduce pin overhead in ultra-constrained IoT sensor nodes.
I2C expanders retain volume leadership; SPI expanders hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium high-speed variants from commodity CMOS implementations, with power specification now the primary purchasing filter in battery-operated designs.
- Low-Power:Sub-microamp sleep-current specifications enable multi-year battery life in field-deployed industrial sensors. Smart home device manufacturers specify these for door locks and environmental monitors where physical access for battery replacement is costly. EU Ecodesign Directive enforcement is accelerating adoption.
- CMOS:Mature-node mixed-signal processes deliver cost-optimized GPIO expansion for consumer electronics with relaxed power budgets. Foundry capacity allocation constraints from automotive MCU demand surges are periodically limiting die availability. The segment serves high-volume, price-sensitive sockets.
- High-Speed:Enhanced slew-rate control supports signal integrity at elevated clock frequencies.
- Bi-Directional:Auto-configuring I/O direction eliminates firmware overhead in dynamic pin reassignment scenarios.
CMOS variants retain volume leadership; low-power architectures hold the steepest expansion curve.
End User:
Customer type concentration varies sharply: automotive procurement demands AEC-Q100 qualification with 18-24 month timelines, while consumer electronics prioritizes rapid design cycles and cost minimization.
- Industrial Automation:Multi-axis robotic cells and programmable logic controllers require deterministic GPIO expansion with extended temperature ranges. Germany's electronics manufacturing sector specifies these for automotive production lines around Munich and Stuttgart. FDA quality system regulations are mandating component-level traceability in medical-adjacent automation.
- Automotive:Body electronics modules operating across 3.3V and 5V domains simultaneously drive demand for integrated level-shifter functionality. AEC-Q100 qualification cycles extend revenue recognition timelines. NHTSA functional safety standards are migrating from powertrain into body electronics where expanders proliferate.
- Consumer Electronics:Cost-sensitive designs with high-volume production targets.
- Medical Devices:FDA-regulated subassemblies requiring Device History Record documentation.
Industrial automation retains volume leadership; automotive applications hold the steepest expansion curve.
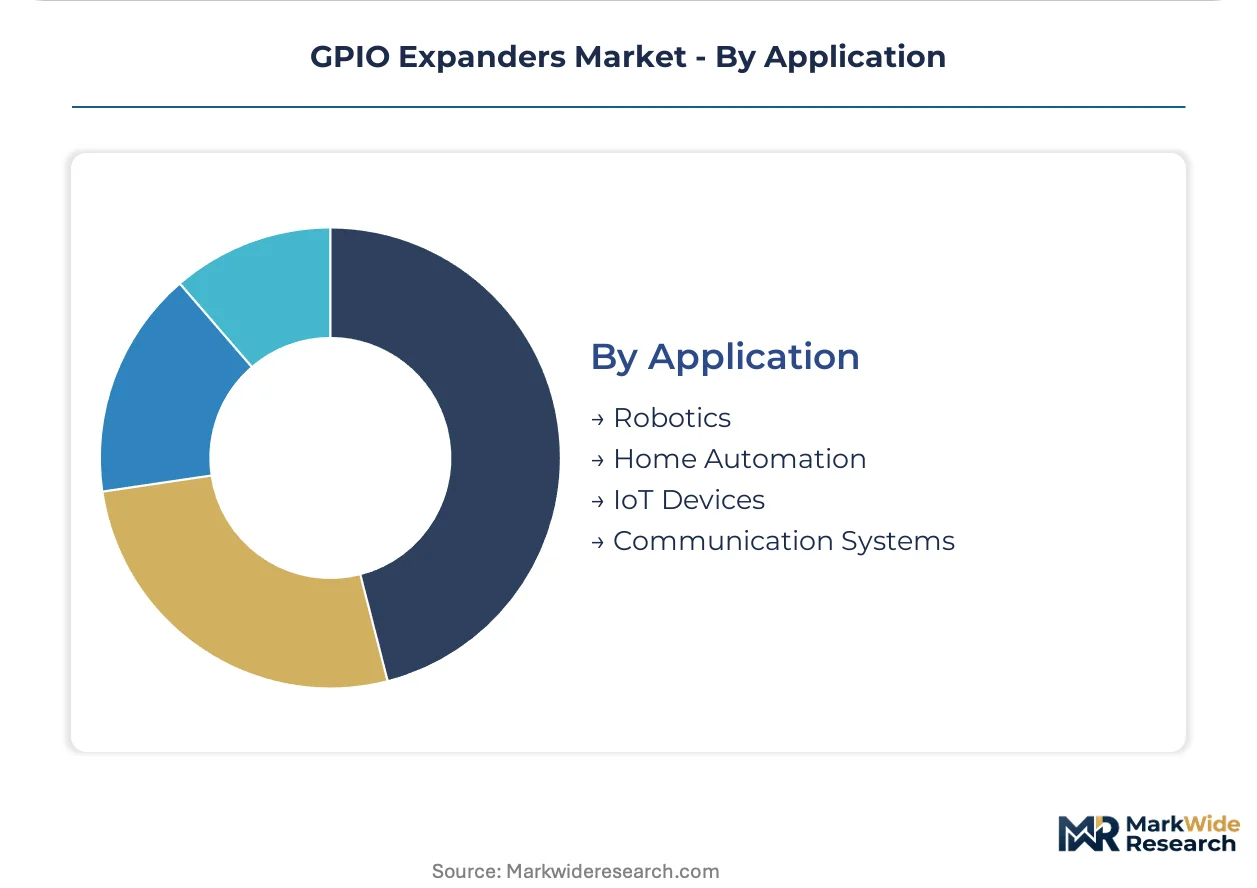
Application:
Application maturity diverges: home automation and IoT devices compete on power efficiency and board-space minimization, while robotics and communication systems prioritize signal integrity and protocol flexibility.
- Robotics:Motor control interfaces and end-effector sensing demand low-latency GPIO expansion with integrated level translation. Automotive and electronics manufacturing lines in Germany deploy these in multi-axis cells. SPI interfaces dominate for deterministic timing requirements.
- IoT Devices:Battery-operated sensor nodes in smart home and industrial deployments require sub-microamp sleep states. European Ecodesign standby power limits are compressing acceptable current budgets. Dual-interface expanders auto-negotiating I2C or SPI are capturing platform design wins.
- Home Automation:Wall-powered controllers with relaxed power constraints.
- Communication Systems:Baseband processing and antenna switching interfaces.
IoT devices retain volume leadership; robotics applications hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for GPIO expanders concentrates in Germany's automotive electronics corridor, while cost-sensitive procurement dominates in India's emerging appliance manufacturing clusters. This asymmetry shapes how vendors allocate AEC-Q100 qualification investments versus high-volume CMOS die production.
United States
Medical device manufacturers in Minnesota and Massachusetts drive demand for expanders with FDA-mandated Device History Record traceability. The FDA's quality system regulations enforce component-level documentation that favors qualified suppliers with established audit trails. Boston-area medical electronics clusters specify these for patient monitoring subassemblies.
Germany
Automotive body electronics modules operating across 3.3V and 5V domains require integrated level-shifter functionality in the Munich-Stuttgart corridor. The EU Ecodesign Directive's standby power limits compress acceptable current budgets for peripheral ICs. Bavarian robotics OEMs specify SPI expanders for multi-axis positioning systems with sub-50 nanosecond timing jitter requirements.
China
Industrial automation OEMs in the Yangtze River Delta scale procurement for robotics control boards with deterministic GPIO expansion. The MIIT's dual carbon goals pressure foundries to qualify alternative etching chemistries for mixed-signal wafer processing. Shenzhen electronics manufacturing clusters absorb high volumes of I2C expanders for consumer appliance controllers.
Japan
Automotive tier-one suppliers in the Nagoya-Chubu region specify AEC-Q100 qualified expanders for next-generation vehicle platforms. METI's industrial policy supports domestic semiconductor packaging investments to reduce Taiwan concentration risk. Toyota City electronics clusters demand 18-24 month qualification cycles for body electronics integration.
India
Appliance and automotive manufacturers in Maharashtra and Gujarat expand procurement under PLI scheme incentives for semiconductor assembly. The CEA's power efficiency mandates align with EU Ecodesign standby limits for exported consumer electronics. Bangalore electronics manufacturing clusters attract expander packaging investments to serve domestic IoT sensor node production.
GPIO Expanders Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the GPIO expander supply base. The market structure consolidates around diversified analog-semiconductor conglomerates with broad mixed-signal portfolios, while specialized vendors compete on board-space efficiency for constrained IoT endpoints. Three archetypes dominate: integrated analog-platform suppliers bundling expanders with level-shifters, automotive-qualified specialists with AEC-Q100 certification depth, and low-pin-count specialists optimizing for space-constrained designs. Competitive moves concentrate on strategic partnerships for foundry capacity allocation and portfolio diversification into dual-interface protocol support.
Within the integrated analog-platform tier, Texas Instruments and NXP Semiconductors exemplify vendors leveraging broad semiconductor portfolios to sustain bundled expander-plus-level-shifter offerings. Microchip Technology occupies a position among low-pin-count specialists competing on board-space efficiency. These three anchors represent how vendor selection criteria fragment across industrial automation, automotive body electronics, and battery-operated IoT endpoints.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Texas Instruments |
| Microchip Technology |
| STMicroelectronics |
| Analog Devices |
| Maxim Integrated |
| ON Semiconductor |
| Renesas Electronics |
| Lattice Semiconductor |
| Others |
Supply & Pricing Matrix
AEC-Q100 automotive qualification gates both supplier roster expansion and price tier separation in GPIO expander procurement. The certification burden compresses qualified vendor lists to three or fewer per socket while enabling premium positioning for validated variants serving body electronics modules.
Pricing Analysis
German automotive OEMs pay 40-60% premiums over Indian appliance manufacturers for functionally identical I2C expanders, reflecting certification-grade stratification. Three-tier pricing structure across AEC-Q100 qualified, industrial-grade, and consumer-grade levels separates automotive body electronics from smart home endpoints. Cost compression in consumer CMOS variants is intensifying because integrated MCUs with native high-pin-count GPIO absorb expander sockets in cost-sensitive designs. Appliance manufacturers in India's PLI scheme zones exhibit highest price sensitivity; Munich-Stuttgart automotive clusters show lowest sensitivity due to traceability mandates.
Supply Chain Analysis
Inventory buffers for small-outline expander packages stretched to 16-20 weeks during recent automotive MCU demand surges, exposing lead-time fragility. Taiwan, China, and South Korea anchor wafer fabrication and packaging capacity for mixed-signal expander die. Foundry allocation for mature-node processes draws from 200mm silicon wafer supply that competes with automotive MCU and power management IC demand. Single-source concentration in Taiwan-based test houses creates tariff-exposure risk as geopolitical friction escalates. Distribution runs through authorized distributors serving qualified vendor programs in medical and automotive verticals, bypassing spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPIO expander procurement is evolving toward qualified-supplier consolidation that embeds firmware customization and long-term support contracts as recurring-revenue layers expanding faster than hardware unit shipments.
For Market Incumbents: Secure captive foundry capacity allocation for mature-node mixed-signal processes before automotive MCU demand surges constrain die availability. Deepen AEC-Q100 certification pipelines to defend socket retention against integrated MCU substitution in body electronics modules. Prioritize backward integration into packaging operations in India to exploit PLI scheme incentives and reduce Taiwan concentration exposure. For New Entrants and Emerging Players: Lead with dual-interface expanders auto-negotiating I2C and SPI protocols to capture platform design wins in industrial automation serving both Linux-based controllers and bare-metal IoT endpoints. Target India's domestic appliance and automotive markets where PLI scheme incentives are attracting packaging investments and qualified supplier lists remain under construction. Position through firmware engineering services bundled with hardware to differentiate from commodity CMOS vendors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automotive-qualified expander variants as AEC-Q100 certification timelines extend 18-24 months and foundry deposits escalate. Five-to-ten year viability favors diversified analog-platform suppliers with existing mixed-signal portfolios over pure-play expander vendors facing integrated MCU substitution. Monitor automotive functional safety standard migration from powertrain into body electronics as inflection signal for expander demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Interface Protocol Integration | Auto-negotiating I2C-SPI expanders capture platform design wins across industrial and IoT endpoints. |
| India Packaging Footprint Expansion | PLI scheme incentives reduce Taiwan concentration risk while serving domestic appliance demand growth. |
| AEC-Q100 Certification Pipeline Investment | Eighteen-to-twenty-four month qualification cycles gate automotive body electronics socket access. |
| Firmware Engineering Service Attach | Mixed-signal talent scarcity creates recurring-revenue layer expanding faster than hardware shipments. |
| Integrated Level-Shifter Bundling | Combined devices reduce BOM line items in robotics control boards operating across 3.3V and 5V domains. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC semiconductor filings, EU Ecodesign Directive enforcement documentation, and automotive production databases. Primary interviews engaged embedded firmware engineering directors, Tier 1 automotive supplier procurement leads, industrial automation OEM platform architects, and medical device quality system managers. Secondary validation drew from FDA quality system regulation guidance, AEC-Q100 qualification timelines, and India PLI scheme operational guidelines. Bottom-up unit shipment modeling triangulated against top-down semiconductor industry revenue allocations.
Segmentation dimensions modeled span interface protocol, power architecture tier, end-use vertical, and regional regulatory cluster across the analysis window. CAGRs derived from trend-line extrapolation of historical procurement patterns adjusted for technology substitution effects. Forecast inputs incorporated foundry capacity allocation constraints, REACH material compliance redesign cycles, and automotive functional safety standard migration timelines.
Forecasts assume regulatory continuity in EU Ecodesign, FDA quality system, and AEC-Q100 regimes; material policy shifts would require re-modeling. Automotive MCU demand surges, Taiwan geopolitical friction, and integrated MCU substitution represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
USB Wall Charger Market
Electronic Components
Speaker Cone Material Market
Electronic Components
SAW Filters Market
Electronic Components
Europe PCB Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
Digital Isolator Market
Electronic Components
Radiation Hardened Electronics Market
Electronic Components
Digital Class-D Amplifier Market
Electronic Components
Global Multilayer Varistors Market
Electronic Components
Tower Mounted Amplifier Market
Electronic Components
Global Capacitive Stylus Market
Electronic Components
Passive Attenuator Market
Electronic Components
North America Miniature Ball Bearing Market
Electronic Components
Capacitor Kits Market
Electronic Components
Cordless Phone Battery Market