
 Circuit Protection Kits Market | 2026-2036
Circuit Protection Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Circuit Protection Kits Market Outlook
Silicon carbide integration in power electronics is narrowing the performance gap between traditional fuses and solid-state protection. Eaton Corporation plc leverages its aerospace-grade breaker architectures to anchor premium industrial kit offerings. Bourns, Inc. specializes in compact surface-mount fuse arrays for consumer electronics OEMs. Schneider Electric SE controls distribution channels across European electrical wholesale networks.
Circuit protection kits are engineered assemblies containing fuses, circuit breakers, surge suppressors, and coordination accessories rated for specific voltage-current envelopes and interrupting capacities. These kits serve to isolate fault currents, prevent equipment damage, and ensure selective coordination across power distribution hierarchies. Fuse kits retain dominance in automotive and industrial applications where arc-quenching speed and cost efficiency outweigh reset capability. Electronic protection segments are expanding fastest in renewable energy inverters where remote monitoring and self-diagnostics reduce truck-roll maintenance. Thermal technology occupies the largest installed base across residential and light commercial breaker panels.
UL 248 and IEC 60269 standards govern fuse performance and interchangeability across North American and European markets, directly shaping product certification costs and market access timelines. The US EPA and the EU Ecodesign Directive are pressing manufacturers to eliminate cadmium and lead from fuse element alloys, forcing reformulation of legacy product lines. China GB standards and Japan JIS requirements add parallel testing burdens for suppliers serving Asia-Pacific assembly operations. Stakeholders must monitor how semiconductor fuse coordination evolves as wide-bandgap devices push switching frequencies beyond traditional protection curves.
Market Dynamics
Silicon carbide power semiconductors are compressing the performance advantage of traditional fuse-based protection, forcing kit manufacturers to integrate solid-state coordination logic into electromechanical assemblies or lose specification battles in high-frequency inverter applications.
Growth Catalysts
- Automotive electrification:Battery management systems in electric vehicles require fused protection assemblies with precise arc-quenching characteristics. OEM procurement teams in Germany are expanding vendor qualification programs for these specialized kits.
- IEC 60269-4 coordination mandates:Semiconductor fuse standards now require tighter selectivity curves with upstream breakers. This regulatory pressure is driving replacement cycles in European industrial automation installations.
- Renewable energy inverter deployment:Solar and wind power conversion equipment needs protection kits rated for harsh environmental cycling. Installers across utility-scale projects are specifying assemblies with remote monitoring capabilities.
Market Restraints
- Silver price volatility:Fuse element alloys depend on silver for conductivity and arc-quenching. Spot market fluctuations in precious metals directly compress margin structures for mid-tier kit assemblers.
- Supply concentration in ceramic substrates:High-grade alumina and steatite substrates for fuse bodies concentrate among Japanese and German specialty ceramic producers. Geographic clustering creates vulnerability to logistics disruptions.
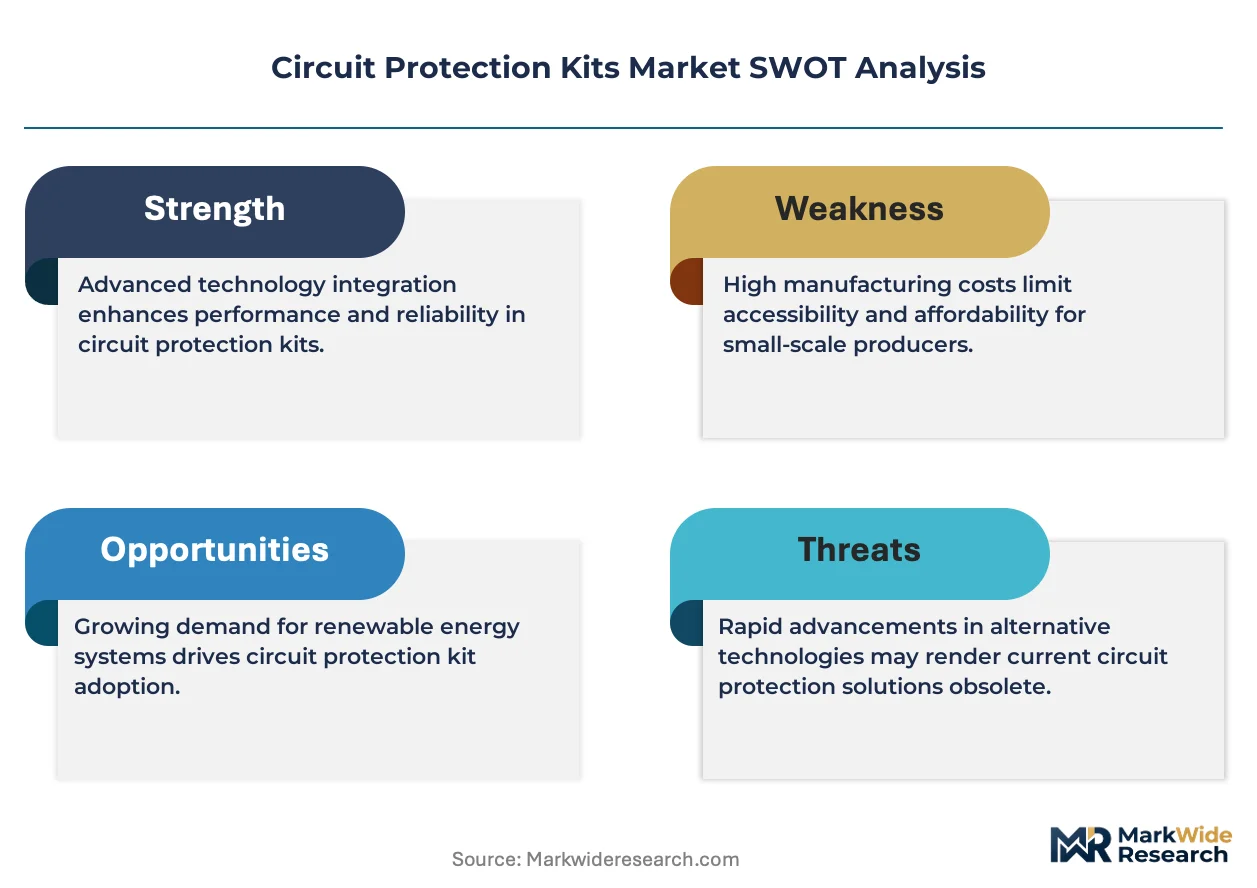
- Solid-state circuit breaker substitution:Wide-bandgap devices enable electronic protection with self-resetting capability. This technical alternative threatens fuse kit volumes in premium industrial segments where downtime costs dominate purchasing decisions.
Strategic Opportunities
- India industrial electrification:Bureau of Indian Standards certification requirements for low-voltage switchgear are tightening. Domestic manufacturing incentives under the PLI scheme attract kit producers to establish local assembly operations serving Southeast Asian export markets.
- DC microgrid protection:Data center and marine applications are migrating to DC distribution architectures. Fuse coordination in these systems requires redesigned time-current characteristics that incumbent suppliers have not yet optimized.
- EU Ecodesign Directive substance restrictions:Cadmium and lead elimination mandates are forcing reformulation of legacy fuse alloys. First-movers with compliant element designs capture specification priority from European electrical wholesalers.
Industry Challenges
- Wide-bandgap device protection engineering:Silicon carbide and gallium nitride switching frequencies exceed traditional fuse melting curves. Engineering teams lack standardized methodologies for coordinating electromechanical protection with nanosecond-scale fault events.
- Multi-standard certification timelines:Simultaneous UL 248, IEC 60269, and China GB testing creates sequential approval bottlenecks. Each jurisdiction requires separate arc-testing protocols that extend product launch schedules by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circuit Protection Kits Market |
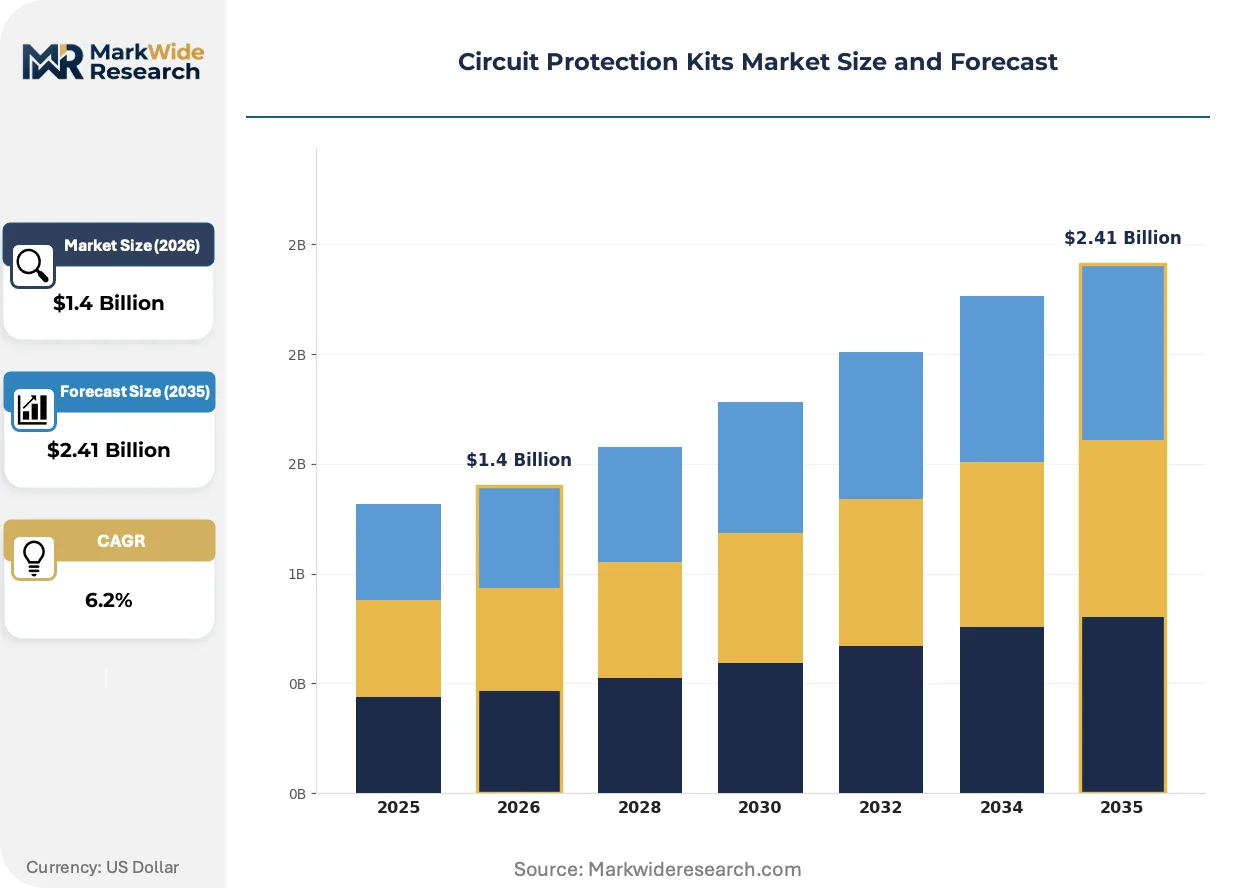
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surge Protectors, Fuse Kits, Circuit Breakers, Adapters End User: Residential, Commercial, Industrial, OEMs Technology: Thermal, Electromagnetic, Electronic, Hybrid Application: Power Distribution, Renewable Energy, Automotive, Consumer Electronics |
| Companies Covered | Littelfuse, Inc., Eaton Corporation plc, Schneider Electric SE, ABB Ltd., Siemens AG, Mitsubishi Electric Corporation, Bourns, Inc., TDK Corporation, Bel Fuse Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circuit Protection Kits Market Strategic Shifts
Protection kit architectures are bifurcating between commodity electromechanical assemblies and intelligent electronic systems, with the boundary between these categories shifting as semiconductor costs decline and coordination software becomes portable across hardware platforms.
Hybrid fuse-breaker coordination modules are collapsing the traditional separation between overcurrent protection technologies. These integrated assemblies combine electromechanical interrupting capability with electronic sensing and communication. Automotive tier-one suppliers in Germany are adopting them for 800-volt battery pack protection. The technology is collapsing the separate procurement channels that historically segmented fuse and breaker purchasing decisions.
REACH substance restrictions and EU Ecodesign Directive amendments are eliminating cadmium and lead from fuse element alloys. Manufacturers must reformulate brazing materials and melting alloys without sacrificing time-current precision. German automotive OEMs and industrial automation clusters are most affected, pressuring suppliers to accelerate compliant product qualification ahead of enforcement deadlines.
Electrical wholesalers are consolidating kit specification authority through private-label assembly programs. Schneider Electric's European distribution network and regional specialists are capturing margin that previously flowed to branded manufacturers. This channel restructuring is most visible in Germany, where specification-heavy purchasing by automotive and automation clusters rewards distributors with deep technical support capabilities.
Circuit Protection Kits Market Segmentation
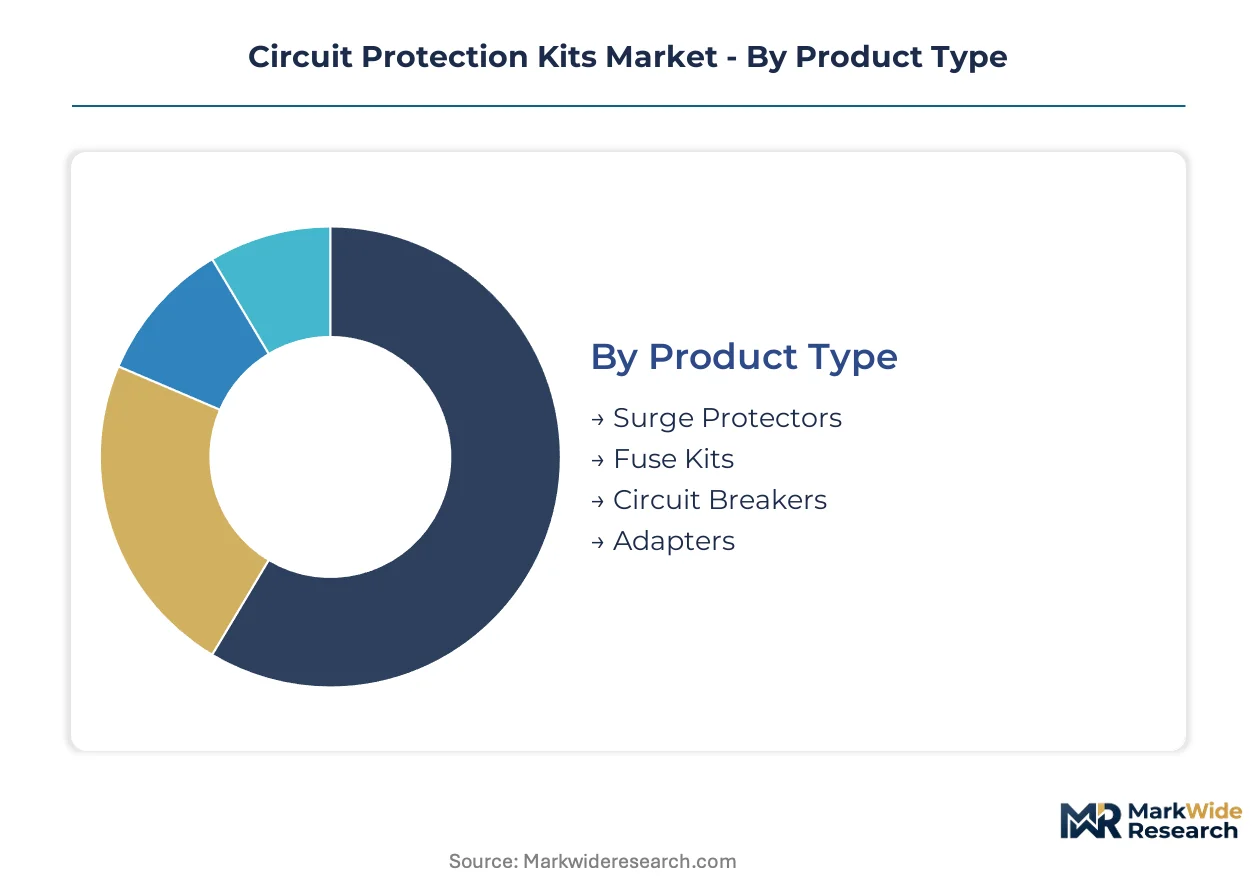
Circuit protection kits fragment across four distinct taxonomies that shape procurement behavior and margin structures. Product type determines the core interrupting technology. End user dictates certification burden and volume scale. Technology governs coordination complexity with upstream power electronics. Application anchors environmental rating requirements and aftermarket service intensity.
Product Type:
Mature electromechanical formats dominate revenue concentration while electronic alternatives capture specification priority in high-frequency inverter applications.
- Fuse Kits:Assemblies containing fusible elements with precise melting curves for arc-quenching fault isolation. German automotive OEMs and industrial automation clusters drive specification-heavy purchasing of these kits for battery management systems and motor protection. IEC 60269 and UL 248 standards tighten coordination requirements with upstream breakers, forcing replacement cycles in European installations.
- Circuit Breakers:Resettable electromechanical devices with thermal-magnetic or electronic trip units. Demand concentrates in commercial and industrial power distribution where downtime costs outweigh the premium over fuse-based protection. Eaton Corporation leverages aerospace-grade architectures to anchor premium industrial kit offerings in this segment.
- Surge Protectors:Voltage-clamping devices for transient overvoltage suppression. Bourns specializes in compact surface-mount arrays for consumer electronics OEMs requiring board-level protection density.
- Adapters:Coordination accessories and mounting hardware for integrating protection elements into distribution panels. These components enable modular kit configuration for custom industrial enclosures.
Fuse kits handle the majority of throughput; circuit breakers are expanding most quickly in premium industrial segments where reset capability commands specification priority.
End User:
Volume scale inversely correlates with technical specification density across customer categories.
- Industrial:Heavy-current applications requiring selective coordination across multi-level distribution hierarchies. Procurement teams prioritize interrupting capacity and arc-fault containment over unit cost. Schneider Electric controls distribution channels across European electrical wholesale networks serving this segment.
- OEMs:Original equipment manufacturers integrating protection into end products. Automotive electrification is expanding procurement of fused protection assemblies for 800-volt battery pack architectures. German tier-one suppliers are adopting hybrid fuse-breaker coordination modules that collapse traditional procurement channel separation.
- Commercial:Light industrial and facility power distribution with standardized panel configurations. Thermal technology occupies the largest installed base across residential and light commercial breaker panels.
- Residential:Consumer-grade protection for branch circuit and surge suppression applications. Price sensitivity dominates purchasing with minimal coordination engineering required.
Industrial users generate the highest revenue per kit; OEMs are climbing the fastest on share as automotive electrification accelerates vendor qualification programs.
Technology:
Protection response mechanisms span a spectrum from passive thermal sensing to active semiconductor-based interruption.
- Thermal:Bimetallic strip or fusible alloy devices responding to accumulated heat from overcurrent conditions. This technology commands the largest installed base across legacy residential and commercial breaker panels. Cost efficiency and proven reliability sustain dominance in price-sensitive applications.
- Electronic:Microprocessor-based sensing with programmable time-current curves and remote monitoring capability. Renewable energy inverter deployment is driving fastest expansion in this segment where self-diagnostics reduce truck-roll maintenance across utility-scale solar and wind projects.
- Electromagnetic:Magnetic trip mechanisms responding to instantaneous fault currents. Industrial motor protection and heavy-load switching applications specify these devices for high interrupting capacity without thermal delay.
- Hybrid:Integrated assemblies combining electromechanical interrupting with electronic sensing and communication. Wide-bandgap device protection engineering challenges are forcing kit manufacturers to integrate solid-state coordination logic into these electromechanical assemblies.
Thermal technology maintains the broadest footprint; electronic protection is gaining share fastest as remote monitoring becomes standard in renewable energy and data center applications.
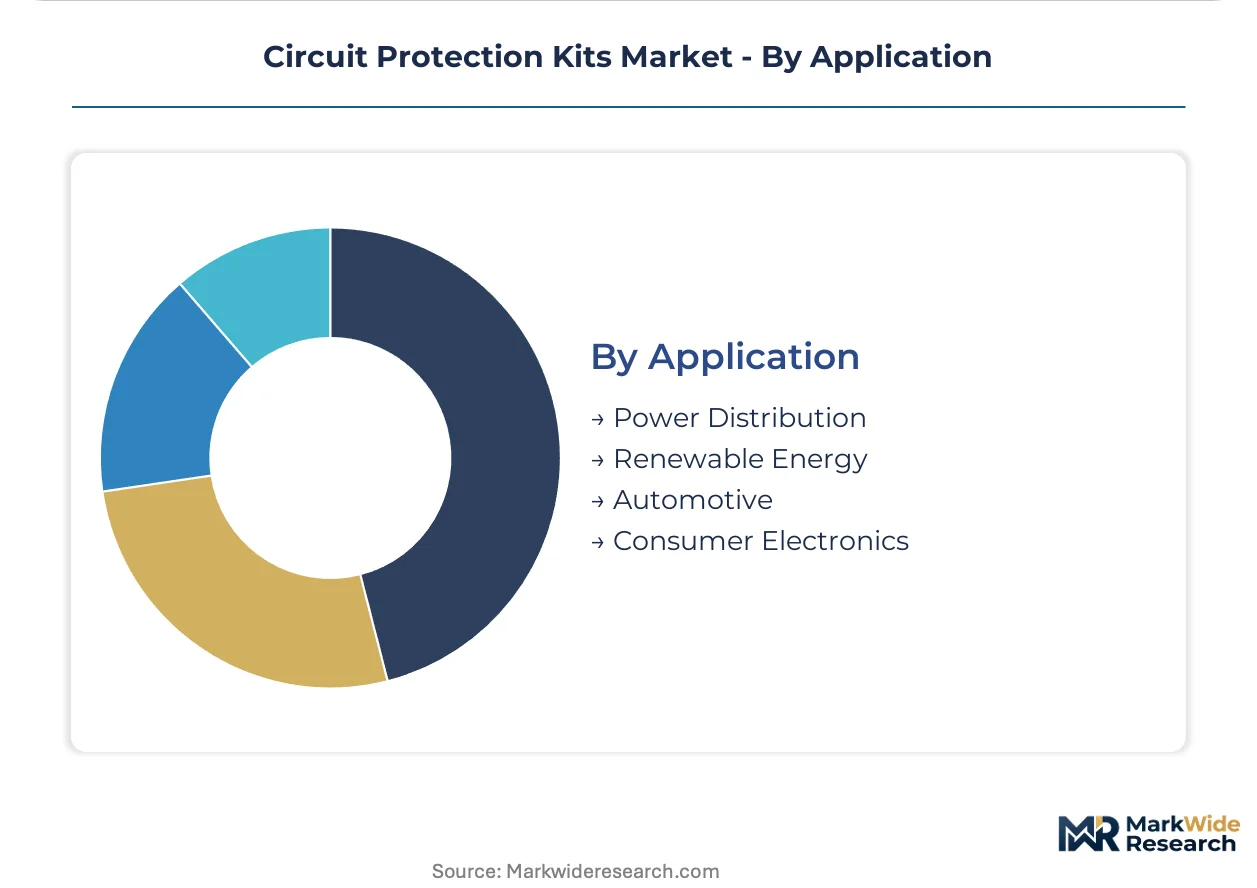
Application:
Environmental exposure severity and coordination complexity vary sharply across deployment contexts.
- Power Distribution:Utility and facility-scale electrical infrastructure requiring selective coordination across transformer and feeder hierarchies. IEC 60269-4 coordination mandates for semiconductor fuses are driving replacement cycles in European industrial automation installations.
- Automotive:Battery management systems and onboard charging architectures for electric vehicles. OEM procurement teams in Germany are expanding vendor qualification programs for specialized fused protection assemblies with precise arc-quenching characteristics.
- Renewable Energy:Solar inverters and wind power conversion equipment rated for harsh environmental cycling. Installers across utility-scale projects are specifying assemblies with remote monitoring capabilities and DC microgrid protection coordination.
- Consumer Electronics:Board-level and adapter-integrated protection for computing and mobile devices. Surface-mount fuse arrays from specialty manufacturers serve high-volume OEM assembly operations.
Power distribution absorbs the greatest kit volume; automotive applications are expanding most steeply as 800-volt architectures proliferate across European and Asia-Pacific vehicle platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specification-heavy purchasing by automotive OEMs and industrial automation clusters concentrates in Germany, while electric vehicle electrification and renewable energy deployment create distinct demand profiles across North American, European, and Asia-Pacific manufacturing centers.
Germany
Automotive OEM procurement teams in Stuttgart and Munich are expanding vendor qualification programs for fused protection assemblies in 800-volt battery management systems. IEC 60269-4 coordination mandates for semiconductor fuses are tightening selectivity requirements with upstream breakers. The Baden-Württemberg industrial automation cluster drives replacement cycles in European manufacturing installations.
United States
Data center operators in Northern Virginia and Texas are migrating to DC microgrid architectures requiring redesigned fuse coordination characteristics. The EPA is pressing manufacturers to eliminate cadmium and lead from fuse element alloys under emerging hazardous substance guidelines. Silicon carbide power semiconductor adoption in renewable energy inverters is compressing traditional fuse performance advantages across utility-scale solar projects in California and Arizona.
China
Domestic electric vehicle manufacturers in Shanghai and Shenzhen are scaling procurement of specialized protection kits for battery pack architectures. GB standards and dual carbon goals are adding parallel testing burdens for suppliers serving Asia-Pacific assembly operations. The Yangtze River Delta electronics manufacturing corridor concentrates demand for compact surface-mount fuse arrays in consumer electronics OEM operations.
India
Bureau of Indian Standards certification requirements for low-voltage switchgear are tightening under the CEA regulatory framework. Domestic manufacturing incentives under the PLI scheme attract kit producers to establish local assembly operations in Gujarat and Maharashtra. These facilities target Southeast Asian export markets while serving indigenous automotive electrification programs in Tamil Nadu and Karnataka.
Japan
High-grade alumina and steatite substrate production for fuse bodies concentrates among specialty ceramic producers in Nagoya and Osaka industrial zones. METI oversight of JIS standards creates certification coordination requirements for suppliers integrating wide-bandgap device protection. Automotive tier-one suppliers in the Chubu region are adopting hybrid fuse-breaker coordination modules for next-generation vehicle platforms.
Circuit Protection Kits Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tier structures. Electrical wholesalers are consolidating kit specification authority through private-label assembly programs. Three archetypes dominate: aerospace-grade industrial specialists, compact consumer electronics suppliers, and distribution-network controllers. M&A activity targets ceramic substrate supply security, while portfolio diversification into hybrid electromechanical-electronic assemblies accelerates.
Among diversified electrical equipment conglomerates, Eaton Corporation plc and Schneider Electric SE exemplify channel-control strategies, with the latter anchoring premium industrial offerings through European wholesale network dominance. Bourns, Inc. represents the product-specialist archetype, occupying a position focused on surface-mount fuse density for high-volume OEM assembly operations. These three entities illustrate how competitive positioning bifurcates between specification-engineered industrial kits and commoditized consumer-grade protection.
| Leading Market Players |
|---|
| Littelfuse, Inc. |
| Eaton Corporation plc |
| Schneider Electric SE |
| ABB Ltd. |
| Siemens AG |
| Mitsubishi Electric Corporation |
| Bourns, Inc. |
| TDK Corporation |
| Bel Fuse Inc. |
| Others |
Value Chain & Pricing Dynamics
Japanese and German specialty ceramic producers concentrate high-grade alumina and steatite substrate supply, anchoring margin pools with fuse body manufacturers who face limited alternative sourcing for arc-quenching integrity. This upstream concentration cascades into tiered pricing power across kit assemblers serving automotive OEMs and industrial automation clusters.
Pricing Analysis
Cost-plus contracts with silver price indexation dominate fuse kit procurement between mid-tier assemblers and automotive OEMs. Pricing stratifies across aerospace-grade industrial specifications, UL/IEC dual-certified assemblies, and commodity residential breaker panels. Silver spot market volatility is compressing margin structures for mid-tier kit assemblers who lack captive precious metal hedging. Residential segments exhibit highest price sensitivity; industrial buyers prioritize interrupting capacity and coordination engineering over unit cost.
Supply Chain Analysis
Contract manufacturing for surface-mount fuse arrays concentrates with EMS providers in the Yangtze River Delta and Shenzhen electronics corridors. Fuse element alloys draw from silver suppliers in Mexico and Peru; ceramic substrates feed from Japanese and German specialty producers; electromechanical breaker assemblies source from Malaysian and Thai industrial component clusters. Single-source vulnerability in high-grade alumina substrates creates exposure to logistics disruptions across the Nagoya-Osaka industrial zone. Distribution runs through European electrical wholesale networks and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Circuit protection kits are shifting toward platform economics as hybrid fuse-breaker coordination modules collapse traditional procurement channel separation, with interoperability standards across 800-volt automotive architectures driving ecosystem consolidation.
For Market Incumbents: Build certification moats around IEC 60269-4 semiconductor fuse coordination and UL 248 dual-standard testing capabilities. Solid-state circuit breaker substitution from wide-bandgap device manufacturers threatens fuse kit volumes in premium industrial segments. Incumbents should deepen backward integration into ceramic substrate supply and anchor channel control through European electrical wholesale network partnerships. For New Entrants and Emerging Players: Pursue DC microgrid protection coordination for data center and marine applications where redesigned time-current characteristics remain unoptimized by incumbent suppliers. India industrial electrification under PLI scheme incentives offers the most penetrable geography for establishing local assembly operations. A go-to-market angle targeting Southeast Asian export markets from Gujarat and Maharashtra facilities bypasses entrenched European distribution networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier kit assemblers lacking hybrid electromechanical-electronic assembly capabilities and ceramic substrate supply security. Long-term viability centers on portfolio diversification into intelligent protection systems with remote monitoring software. Watch silicon carbide inverter deployment rates as the inflection signal for traditional fuse displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Assembly Development | Combines electromechanical interrupting with electronic sensing for 800-volt battery pack protection. |
| Ceramic Substrate Backward Integration | Captive supply of high-grade alumina from Nagoya-Osaka producers reduces logistics disruption exposure. |
| Multi-Standard Certification Investment | Simultaneous UL 248, IEC 60269, and China GB testing accelerates product launch timelines. |
| DC Microgrid Protection Engineering | Redesigned time-current characteristics capture specification priority in data center migration. |
| EU Ecodesign Compliance Reformulation | Cadmium and lead elimination from fuse alloys captures European wholesaler specification priority. |
Study Parameters
Initial hypotheses were tested against primary input from fuse kit procurement managers at automotive OEMs, electrical wholesale specification engineers, industrial automation maintenance directors, and renewable energy inverter procurement teams, then refined through secondary validation against IEC 60269 and UL 248 standard documentation, SEC 10-K filings from diversified electrical equipment conglomerates, customs trade data for ceramic substrate imports, and automotive production databases. Bottom-up segment sizing triangulated with top-down market reconstruction across product type, end user, technology, and application dimensions.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling volume and value outputs through segmentation across fuse kit, circuit breaker, surge protector, and adapter product types; industrial, OEM, commercial, and residential end users; thermal, electronic, electromagnetic, and hybrid technologies; and power distribution, automotive, renewable energy, and consumer electronics applications. CAGRs were derived from installed base replacement cycles and electrification-driven new demand buildout, with semiconductor fuse coordination standards and wide-bandgap device adoption curves as critical forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in silver spot prices, automotive electrification capex cycles, or China GB standard enforcement timelines would shift the trajectory. Forecasts reflect documented assumptions regarding IEC 60269-4 coordination mandate implementation pace and solid-state circuit breaker cost curves. Quarterly review of silicon carbide inverter deployment rates, precious metal price indices, and European electrical wholesale inventory levels is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
Efuse Market
Electronic Components
Data Acquisition Card Market
Electronic Components
Industrial Relays Market
Electronic Components
Coin Battery Holder Market
Electronic Components
Global Flexible Electronics and Circuit Market
Electronic Components
Silicon Capacitors Market
Electronic Components
Fuse Bases Market
Electronic Components
Low-Dropout (LDO) Regulator Market
Electronic Components
Multilayer Transparent Conductors Market
Electronic Components
Digital Class-D Amplifier Market
Electronic Components
Data Bus Market
Electronic Components
Operational Amplifier Market
Electronic Components
Safety Relay Market
Electronic Components
Ceramic Disc Capacitor Market
Electronic Components
Touchless Tubes Market