
 Ceramic Capacitors Market | 2026-2036
Ceramic Capacitors Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Capacitors Market Analysis
Automotive OEMs is redrawing procurement priorities for ceramic capacitors as electrified powertrains and zone-based architectures multiply passive component counts per vehicle platform. Murata Manufacturing Co., Ltd. leverages vertically integrated dielectric powder production to secure formulation consistency across high-reliability grades. Samsung Electro-Mechanics anchors capacity expansion in Busan and Tianjin to serve Korean and Chinese automotive module suppliers. TDK Corporation differentiates through proprietary C0G and X7R temperature-compensating formulations for under-hood applications.
Ceramic capacitors store electrical energy in a dielectric ceramic material between metal electrodes, with multilayer ceramic capacitors stacking hundreds of alternating dielectric and electrode layers to achieve microfarad-range capacitance in sub-millimeter footprints. They primarily function for decoupling, filtering, and energy storage in circuits where volumetric efficiency and temperature stability determine system reliability. Multilayer capacitors dominate absolute volume and revenue as miniaturization trends in smartphones and wearables compress board space, while high-voltage ratings represent the fastest-expanding margin pool as EV onboard chargers and DC-DC converters demand 500V to 1kV class components. Disc capacitors retain niche strength in line-frequency filtering and snubber applications where through-hole mounting and cost simplicity outweigh density requirements.
RoHS and REACH in Europe restrict lead content and hazardous substances in dielectric formulations, compelling reformulation of relaxor-based compositions and supply chain requalification. China's SAMR enforces GB standards for capacitor reliability grading that gate access to telecom infrastructure tenders and state-backed automotive programs. The EU AI Act and emerging functional safety standards for autonomous systems will extend traceability requirements to passive component lots. Stakeholders must monitor dielectric material substitution timelines and regional qualification bottlenecks to avoid supply disruption as automotive and telecom certifications diverge.
Market Dynamics
Automotive electrification is compressing capacitor qualification timelines as EV platforms demand 1kV-rated MLCCs that survive thermal cycling from -55°C to 150°C under hood.
Growth Catalysts
- EV Powertrain Proliferation:Battery management systems and onboard chargers require 30-50% more passive components per vehicle than internal combustion equivalents, pulling high-voltage MLCC volumes.
- REACH and RoHS Reformulation:European material compliance mandates are accelerating lead-free dielectric development, locking qualified suppliers into long-term automotive certification pipelines.
- Busan-Tianjin Manufacturing Corridor:Korean and Chinese production clusters are capturing module assembly localization as automotive tier suppliers regionalize sourcing.
Market Restraints
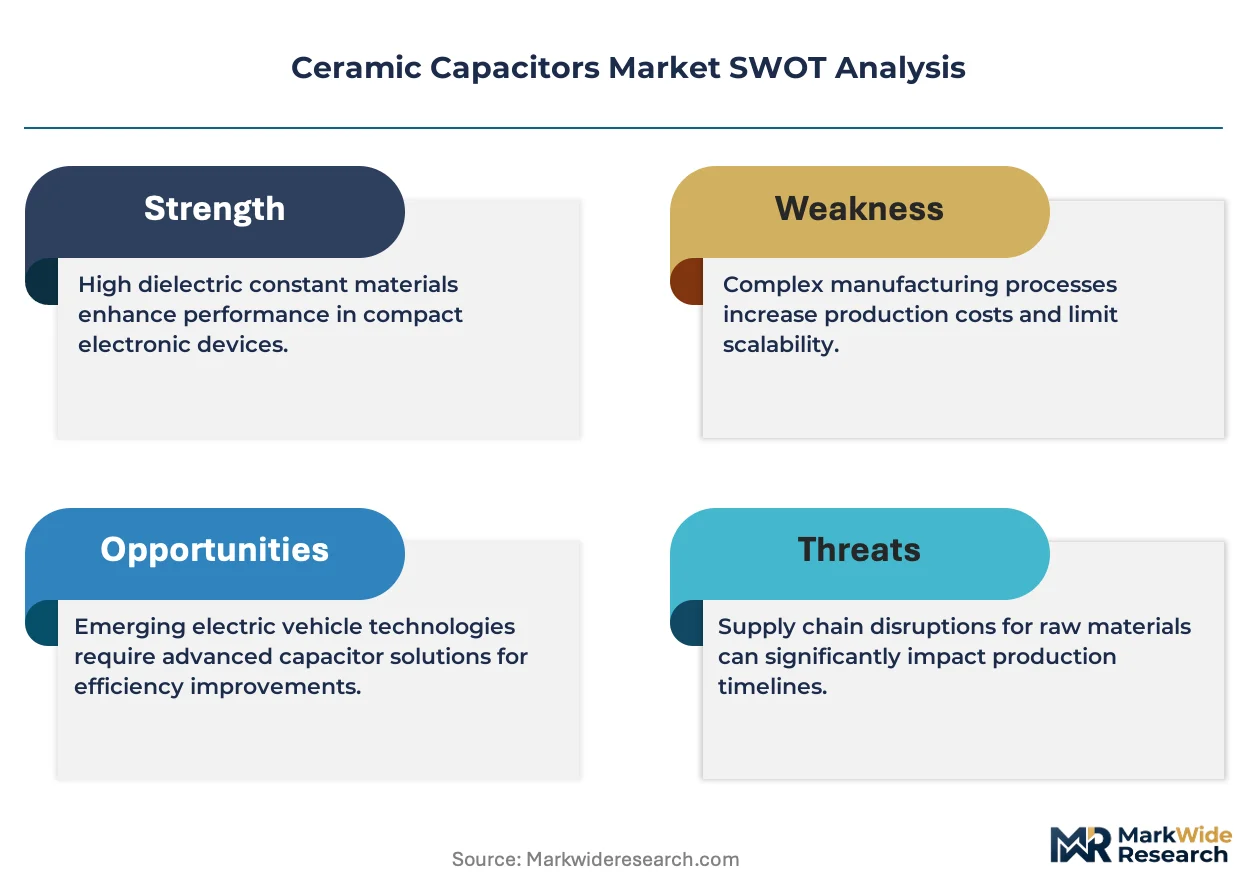
- Nickel-Palladium-Silver Electrode Volatility:Precious metal price swings in electrode pastes compress margin predictability for mid-tier manufacturers lacking hedging programs.
- East Asian Powder Concentration:Dielectric ceramic formulation expertise clusters in Japan and South Korea, creating single-source vulnerability for automotive-grade barium titanate precursors.
- Relaxor Dielectric Temperature Drift:X7R and Y5V formulations exhibit capacitance loss at temperature extremes, limiting deployment in under-hood EV applications without costly C0G substitution.
Strategic Opportunities
- Indian Electronics Manufacturing:PLI scheme incentives for telecom and automotive component production are drawing MLCC packaging investments to Gujarat and Tamil Nadu corridors.
- Zone-Based Vehicle Architectures:Distributed power distribution modules are fragmenting capacitor specifications across 30-40 domain controllers per premium EV platform.
- EU AI Act Traceability Mandates:Functional safety documentation requirements for autonomous systems are creating certified component lot tracking as a service differentiator.
Industry Challenges
- Thin-Layer Dielectric Process Control:Sub-micron layer deposition for 0201 and 01005 case sizes demands cleanroom environments that inflate capex intensity for capacity expansion.
- AEC-Q200 Qualification Timelines:12-18 month automotive reliability testing creates working capital strain during product transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Capacitors Market |
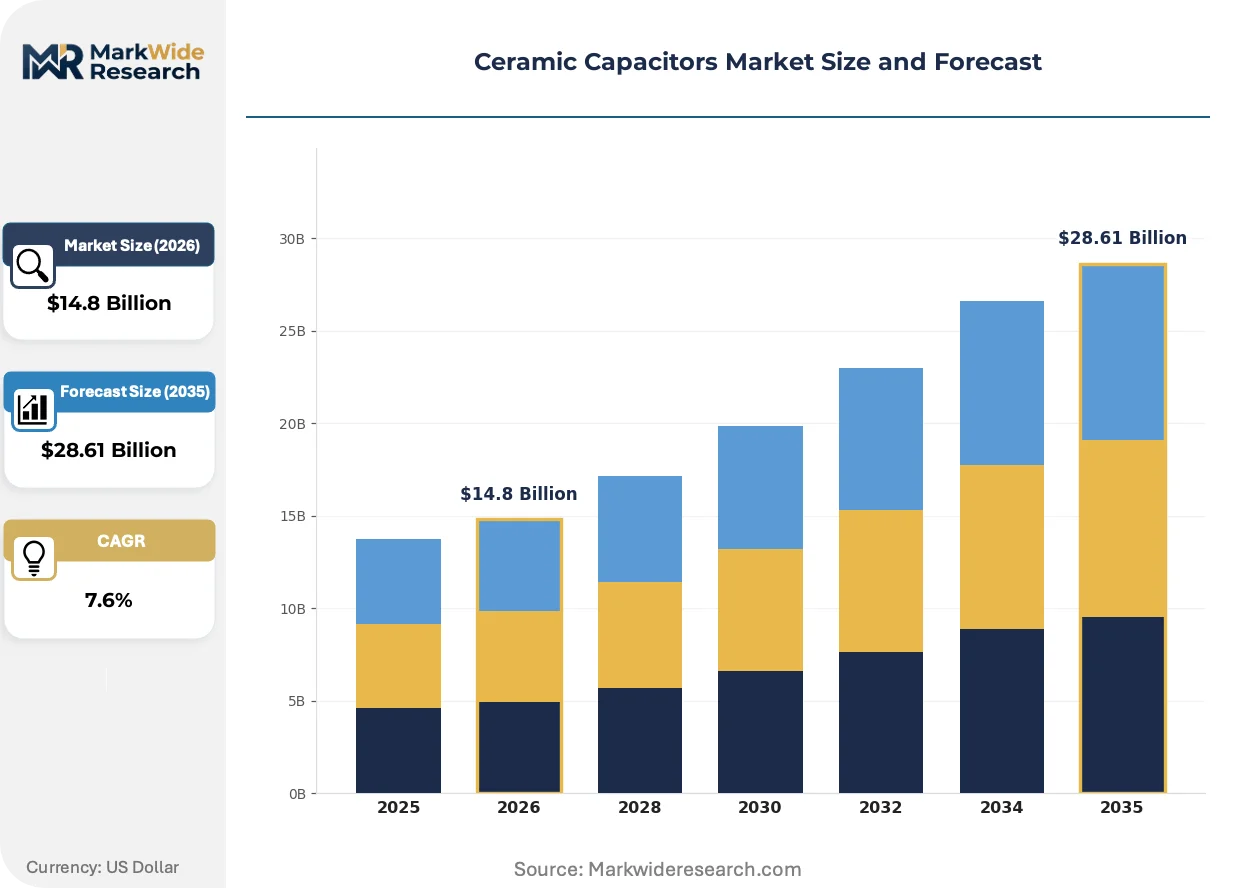
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multilayer Capacitors, Disc Capacitors, Chip Capacitors, Ceramic Filters End User: Consumer Electronics, Automotive, Telecommunications, Industrial Application: Power Supply, Signal Coupling, Filtering, Timing Circuits Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage |
| Companies Covered | Murata Manufacturing Co., Ltd., Samsung Electro-Mechanics, TDK Corporation, Yageo Corporation, Taiyo Yuden Co., Ltd., Vishay Intertechnology, KEMET Corporation, Walsin Technology Corporation, Kyocera Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Capacitors Market Emerging Trajectories
Material science breakthroughs and regulatory traceability mandates are restructuring how capacitor manufacturers qualify formulations and document supply chains for safety-critical applications.
Base-metal electrode formulations utilizing copper and nickel alloys are supplanting traditional silver-palladium systems in mid-voltage MLCCs. Korean automotive module suppliers have accelerated qualification of BME-based X7R grades for 48V mild-hybrid systems. The transition is compressing electrode material costs while forcing ceramic sintering process redesigns to prevent oxidation during high-temperature firing.
China's SAMR enforcement of GB/T capacitor reliability standards is tightening access to state-backed 5G infrastructure tenders and NEV subsidy programs. Domestic manufacturers must demonstrate 1,000-hour life test compliance under humidity bias conditions. The regulatory friction is advantaging vertically integrated producers with in-house powder synthesis capabilities over import-dependent packagers.
Automotive tier-one procurement teams are consolidating supplier panels from 15-20 qualified vendors to 5-7 strategic partners with captive dielectric formulation. German and Japanese OEMs now mandate lot-level material composition disclosure for REACH Article 33 compliance. The consolidation pressure is most visible in Korean battery supply chains, where LG Energy Solution and Samsung SDI have imposed preferred MLCC vendor lists on their module suppliers.
Ceramic Capacitors Market Segmentation
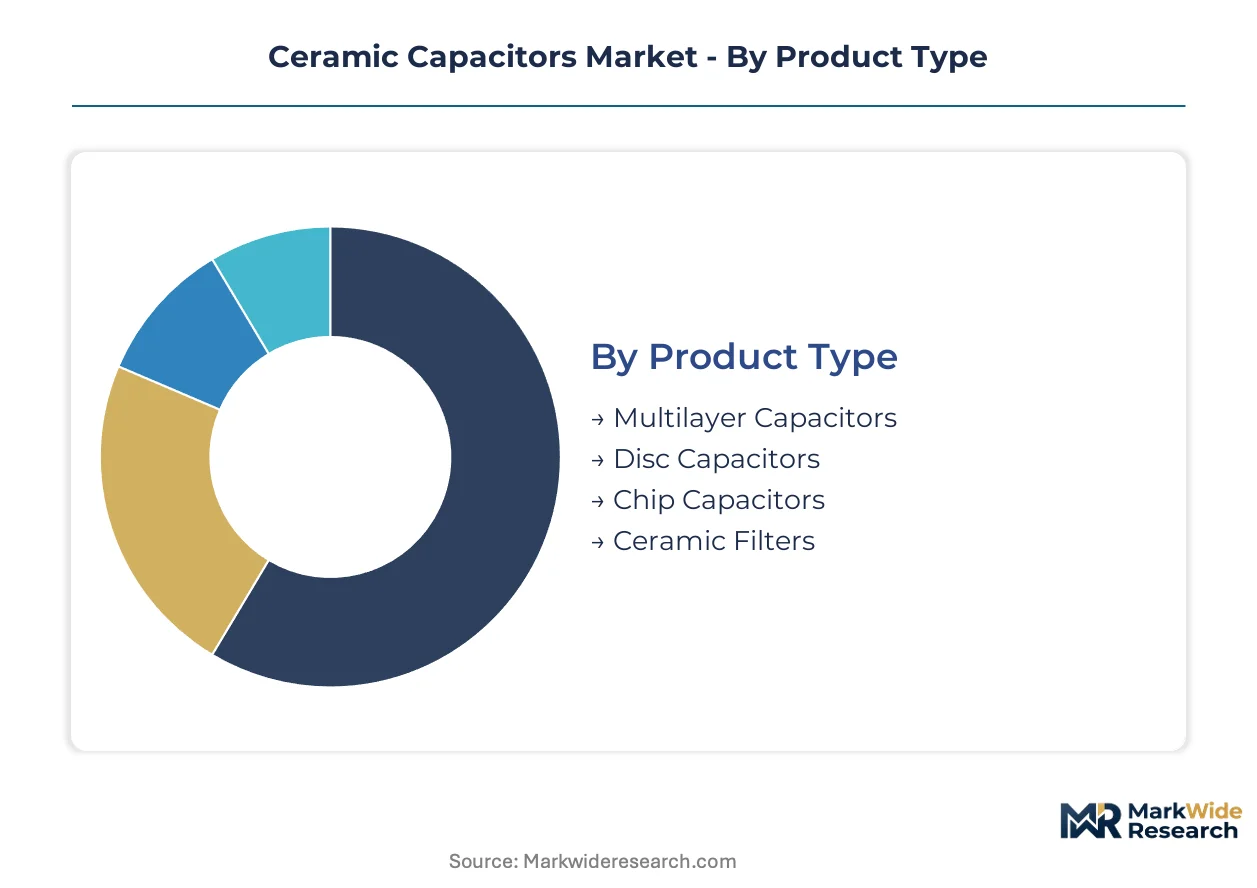
Segmentation in ceramic capacitors tracks diverging qualification regimes across automotive, telecom, and industrial verticals. Dielectric formulation requirements and voltage class certifications fragment supplier portfolios and pricing architectures.
Product Type:
REACH and RoHS compliance timelines in Europe differentiate product categories by material substitution urgency and requalification burden.
- Multilayer Capacitors:Hundreds of alternating dielectric and electrode layers achieve microfarad-range capacitance in sub-millimeter footprints. Smartphone and wearable miniaturization in Japan, South Korea, and Taiwan compresses board space requirements while automotive module suppliers demand AEC-Q200 grades.
- Disc Capacitors:Through-hole ceramic discs with radial leads serve line-frequency filtering and snubber applications. Industrial equipment manufacturers in Germany and the United States favor these for cost simplicity where volumetric efficiency matters less than repairability.
- Chip Capacitors:Surface-mount variants without leads optimize automated assembly throughput.
- Ceramic Filters:Frequency-selective components integrate capacitive and inductive elements for RF signal conditioning.
Multilayer capacitors handle the majority of throughput; high-voltage MLCC variants for EV powertrains are expanding most quickly on share.
End User:
Cost tier stratification separates premium-qualified automotive grades from standard consumer electronics specifications.
- Automotive:Battery management systems and onboard chargers pull 500V to 1kV MLCC volumes as EV platforms replace internal combustion architectures. Korean battery module suppliers impose preferred vendor lists that consolidate procurement panels from 15-20 to 5-7 qualified sources.
- Telecommunications:Base station deployments and 5G infrastructure tenders in China require GB/T reliability compliance with 1,000-hour humidity bias testing. SAMR enforcement gates state-backed contracts to vertically integrated domestic manufacturers with captive powder synthesis.
- Consumer Electronics:Smartphones, tablets, and wearables drive sub-millimeter case size adoption.
- Industrial:Motor drives, power inverters, and automation systems demand temperature stability across extended operating lifetimes.
Automotive commands premium pricing tiers; telecommunications infrastructure is gaining share fastest as 5G deployment accelerates.
Application:
Volume concentration in decoupling functions contrasts with margin expansion in specialized timing and filtering roles.
- Power Supply:Bulk capacitance and ripple current management dominate unit economics.
- Signal Coupling:DC blocking and AC transmission between circuit stages.
- Filtering:EMI suppression and noise attenuation in switch-mode converters.
- Timing Circuits:Oscillator and resonant frequency stabilization with C0G temperature-compensating formulations. German and Japanese OEMs mandate lot-level material composition disclosure for REACH Article 33 compliance in safety-critical autonomous systems.
Power supply applications absorb the highest unit volumes; timing circuits for functional safety systems are climbing the fastest on margin contribution.
Voltage Rating:
Supply concentration in high-voltage dielectric expertise creates qualification bottlenecks for emerging EV platforms.
- Low Voltage:Consumer electronics and general-purpose decoupling below 50V.
- Medium Voltage:48V mild-hybrid systems and industrial control circuits.
- High Voltage:500V to 1kV ratings for EV onboard chargers and DC-DC converters. Murata, Samsung Electro-Mechanics, and TDK anchor regional supply from Japanese and Korean manufacturing clusters with proprietary barium titanate precursor formulations.
- Ultra High Voltage:Specialized grades for grid infrastructure and medical equipment exceeding 1kV.
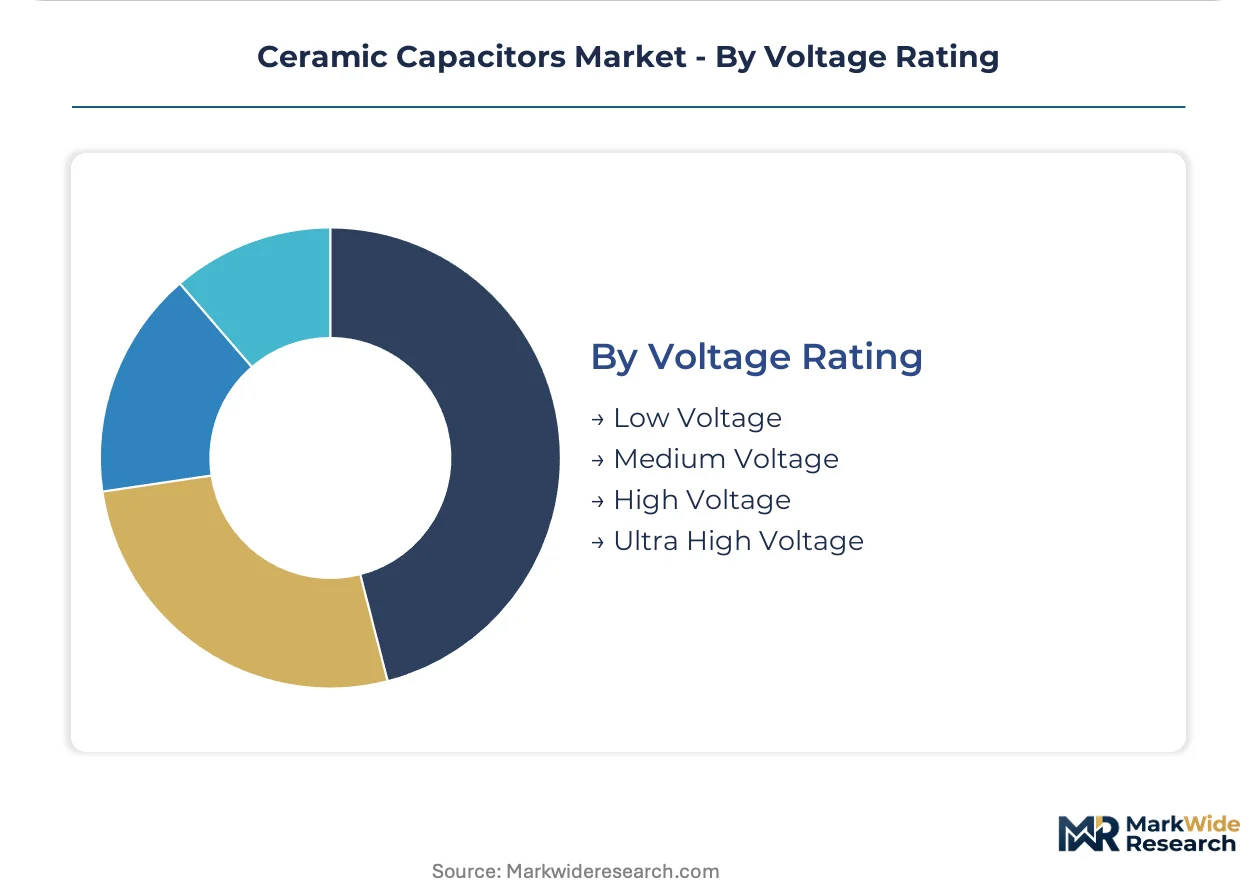
Low voltage handles the majority of unit shipments; high voltage ratings are gaining share fastest as electrification multiplies component counts per vehicle platform.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan anchors East Asian ceramic capacitor logistics, handling raw barium titanate precursors from Japanese suppliers and finished MLCC exports to automotive module plants across the region.
China
Domestic NEV production and 5G base station deployment consume high-voltage MLCC volumes. SAMR enforces GB/T reliability standards with 1,000-hour humidity bias testing for state-backed telecom tenders. The Tianjin manufacturing corridor hosts Samsung Electro-Mechanics capacity expansion serving Korean and Chinese automotive tier suppliers.
Japan
Murata Manufacturing and TDK Corporation anchor proprietary dielectric formulation expertise for AEC-Q200 automotive grades. METI oversees export controls on advanced ceramic materials. The Kyoto-Nara industrial cluster concentrates vertically integrated powder synthesis and thin-layer deposition cleanrooms for sub-millimeter case sizes.
South Korea
LG Energy Solution and Samsung SDI impose preferred MLCC vendor lists on battery module suppliers, consolidating procurement panels. The Busan-Ulsan manufacturing belt captures localized packaging for 48V mild-hybrid systems. Korean automotive module suppliers accelerated qualification of base-metal electrode X7R grades.
Germany
German OEMs mandate lot-level material composition disclosure for REACH Article 33 compliance in autonomous driving systems. The Baden-Württemberg automotive supply cluster sources high-voltage MLCCs for onboard chargers and DC-DC converters. ECHA enforcement of RoHS restrictions drives lead-free dielectric reformulation timelines.
United States
Industrial equipment manufacturers in the Midwest favor disc capacitors for line-frequency filtering where repairability outweighs density. The EPA oversees hazardous substance reporting for ceramic dielectric waste streams. Texas and Arizona fabrication corridors attract packaging investments for defense and aerospace qualified grades.
Ceramic Capacitors Market Vendor Landscape
Listed leaders compete with private specialists across dielectric formulation depth and automotive certification pipelines. The market structure concentrates around vertically integrated Japanese and Korean conglomerates with captive powder synthesis, while mid-tier packagers depend on imported ceramic precursors. Three archetypes dominate: conglomerate integrators with in-house material science, regional packaging specialists serving consumer electronics, and niche high-reliability suppliers for aerospace and medical segments. Capacity expansion and strategic partnerships represent the dominant competitive moves as automotive qualification timelines lengthen.
Among Japanese conglomerates with material science depth, Murata Manufacturing Co., Ltd., TDK Corporation, and Taiyo Yuden Co., Ltd. exemplify the vertically integrated archetype controlling dielectric powder production. Samsung Electro-Mechanics occupies a position bridging Korean automotive module supply chains with East Asian manufacturing scale. These three names anchor the premium-tier supplier panel that German and Japanese OEMs have consolidated toward for REACH-compliant, lot-traceable component sourcing.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| Samsung Electro-Mechanics |
| TDK Corporation |
| Yageo Corporation |
| Taiyo Yuden Co., Ltd. |
| Vishay Intertechnology |
| KEMET Corporation |
| Walsin Technology Corporation |
| Kyocera Corporation |
| Others |
Supply Flow & Price Mechanics
Base-metal electrode substitution for silver-palladium systems is simultaneously redrawing procurement geography toward Korean packaging corridors and compressing electrode material costs by half. This input transition feeds back into supplier selection as automotive module makers prioritize BME-qualified sources with captive sintering process control.
Pricing Analysis
Volume-discount tiering structures separate AEC-Q200 automotive grades from standard consumer electronics specifications, with certification level and dielectric formulation quality as primary price differentiation drivers. Pricing pressure stems from nickel-palladium-silver electrode volatility as precious metal swings compress margin predictability for mid-tier manufacturers lacking hedging programs. Consumer electronics buyers exhibit highest price sensitivity due to commoditized specifications, while German and Japanese OEMs absorb premium tiers for REACH-compliant lot traceability.
Supply Chain Analysis
Just-in-time inventory strategies dominate smartphone and wearable procurement, while automotive tier suppliers maintain strategic stockpiles of qualified dielectric precursors to buffer 12-18 month AEC-Q200 requalification timelines. Supply concentrates in Japanese and Korean manufacturing clusters drawing from barium titanate precursor deposits and proprietary formulation expertise. Single-source vulnerability in automotive-grade powder synthesis creates structural risk as SAMR enforcement gates Chinese state-backed contracts to vertically integrated domestic producers. Distribution runs through Busan and Tianjin packaging corridors serving regional module assembly localization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Korean battery module suppliers impose preferred MLCC vendor lists, consolidating procurement panels from 15-20 qualified sources to 5-7 strategic partners with captive dielectric formulation.
For Market Incumbents: Consolidate supplier relationships through backward integration into dielectric powder synthesis and capacity expansion in Tianjin corridors to serve Chinese NEV subsidy programs. Lock in long-term automotive certification pipelines before REACH reformulation deadlines accelerate. Defend margin position by controlling barium titanate precursor supply as SAMR enforcement advantages vertically integrated producers. For New Entrants and Emerging Players: AEC-Q200 certification fast-tracks offer entry into 48V mild-hybrid supply chains where Korean automotive module suppliers have accelerated BME-based X7R qualification. Target Indian PLI scheme corridors in Gujarat and Tamil Nadu for telecom and automotive packaging investments with lower incumbent saturation. Pursue white-label partnerships with European industrial equipment manufacturers favoring disc capacitors for repairability over density. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier packagers dependent on imported Japanese ceramic precursors and lacking automotive-grade formulation capabilities. Five-to-ten year viability hinges on securing captive powder synthesis or strategic offtake agreements with Murata or TDK. Watch SAMR enforcement intensity as the inflection signal—accelerated GB/T reliability standard adoption will strand import-dependent packagers outside state-backed 5G and NEV tender access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dielectric Powder Synthesis | SAMR enforcement advantages vertically integrated producers with in-house barium titanate formulation for Chinese state tenders. |
| AEC-Q200 Certification Pipeline Investment | 12-18 month automotive reliability testing creates working capital barriers that consolidate procurement panels toward qualified incumbents. |
| Base-Metal Electrode Process Redesign | BME transition compresses electrode costs while forcing ceramic sintering redesigns to prevent oxidation during high-temperature firing. |
| Indian PLI Scheme Manufacturing Localization | Gujarat and Tamil Nadu corridors attract MLCC packaging investments serving telecom infrastructure and automotive module regionalization. |
| REACH Article 33 Lot-Level Traceability Systems | German OEM mandates for material composition disclosure create certified component lot tracking as a service differentiator. |
Methodological Framework
A standing panel of Tier 1 automotive supplier procurement directors, capacitor plant operations managers, dielectric materials R&D leads, and Korean battery module supply chain executives provided ongoing calibration across primary interview rounds. Secondary validation drew from customs trade data, METI export control filings, SAMR GB/T standard enforcement notices, and SEC 10-K disclosures from listed Japanese and Korean conglomerates. Bottom-up volume modeling triangulated against top-down value estimates from regional production cluster analysis.
Consistency checks validated volume and value outputs against automotive MLCC content-per-vehicle benchmarks, smartphone case size adoption curves, and 5G base station deployment databases across the projection horizon. Segmentation modeling tracked dielectric formulation grade, voltage rating class, end-use vertical, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating EV platform rollout schedules and REACH reformulation timelines.
Underlying assumptions cover automotive electrification penetration rates and SAMR enforcement intensity, with deviation risk concentrated in precious metal electrode price volatility and single-source powder synthesis bottlenecks. Revision becomes warranted when AEC-Q200 qualification timelines extend beyond working capital tolerance thresholds or when ECHA expands RoHS restricted substance lists.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
USB Wall Charger Market
Electronic Components
Audio Capacitor Market
Electronic Components
Tower Mounted Amplifier Market
Electronic Components
Household Appliances Electric Commutators Market
Electronic Components
Surface Mountable Laser Direct Structuring Antenna (LDS) Market
Electronic Components
Lowpass Filters Market
Electronic Components
Global Smartphone Cover Glass Market
Electronic Components
Bonding Wires and Ribbons Market
Electronic Components
Conductive Polymer Capacitor Market
Electronic Components
Lead Zirconate Titanate (PZT) Market
Electronic Components
Coaxial Coupler Market
Electronic Components
Speaker Membranes Market
Electronic Components
Digital Class-D Amplifier Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
High Density Interconnect (HDI) PCB Market
Electronic Components
Film Capacitor Market