
 United Kingdom MLCC Market | 2026-2036
United Kingdom MLCC Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom MLCC Market Insights
Japan is reconfiguring ceramic capacitor supply chains through expanded domestic firing capacity and advanced dielectric R&D investments. Murata Manufacturing Co. Ltd. leverages proprietary barium titanate formulations to dominate high-reliability automotive grades. TDK Corporation anchors European distribution through its UK technical service centers, sustaining close OEM relationships. Samsung Electro-Mechanics competes aggressively on cost-performance ratios in consumer electronics tiers.
Multilayer Ceramic Capacitors (MLCCs) are passive electronic components constructed from alternating layers of ceramic dielectric and metal electrodes, sintered at temperatures exceeding 1,200°C to achieve capacitance densities critical for miniaturized circuits. These devices function primarily for charge storage, noise filtering, and voltage stabilization across high-frequency applications. Automotive Systems represents the fastest-expanding application segment as electrified powertrains demand AEC-Q200 qualified components with extended temperature ratings. Multilayer configurations command the dominant product position due to superior volumetric efficiency, while Surface Mount installation methods displace through-hole alternatives across British contract manufacturing.
UK product safety falls under BEIS market surveillance with CE marking requirements, while REACH and RoHS frameworks from ECHA govern substance restrictions in ceramic dielectrics and termination metallizations. These regulations compel manufacturers to maintain detailed material declarations and restricted substance testing protocols. Stakeholders must monitor evolving critical raw material designations for nickel and palladium, as supply security directly shapes component availability for domestic electronics assemblers.
Market Dynamics
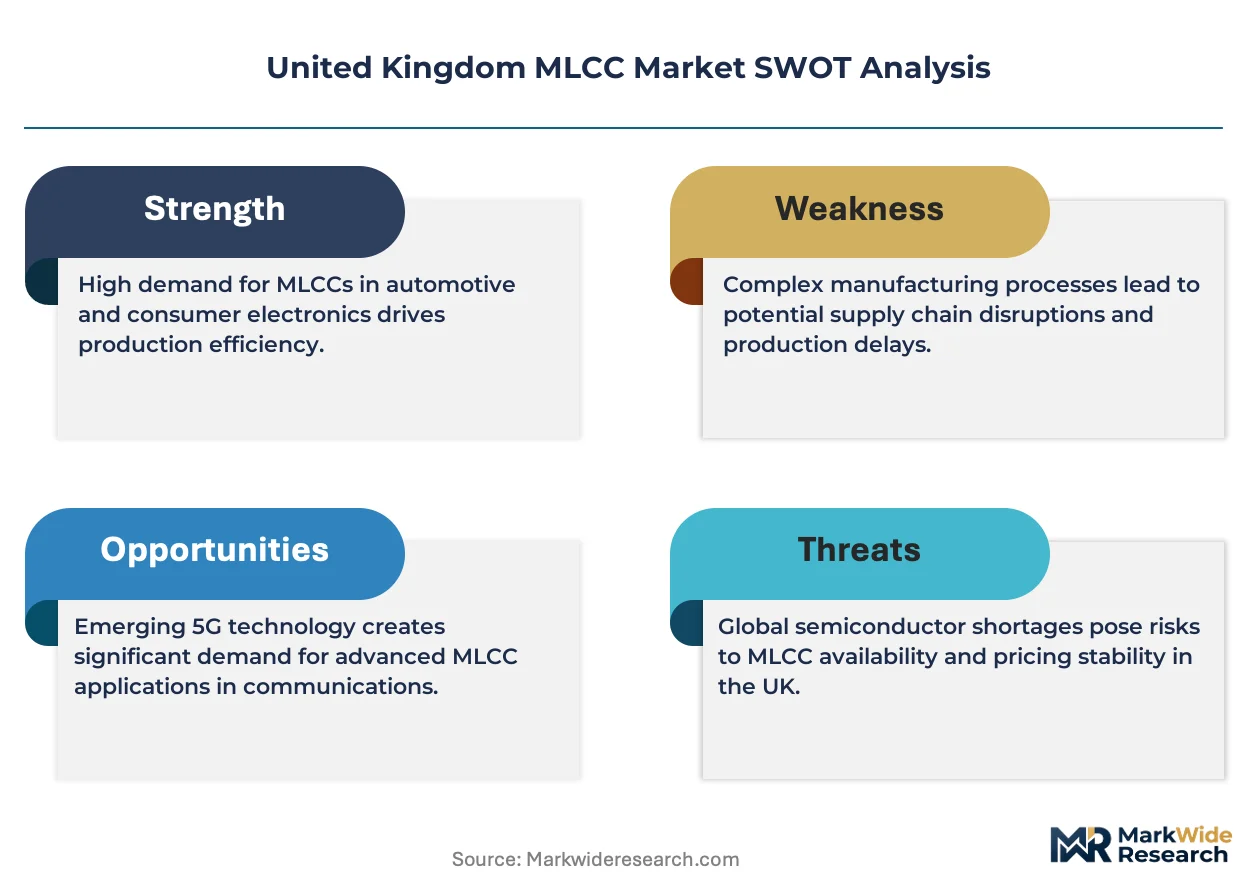
Automotive electrification is forcing UK MLCC procurement toward AEC-Q200 qualified components, with BEIS market surveillance tightening traceability requirements across British EV supply chains. This structural pressure concentrates purchasing power among Tier 1 automotive suppliers while squeezing legacy consumer electronics distributors.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving critical raw material designations are accelerating domestic testing infrastructure investment. British assemblers now demand detailed material declarations upstream.
- Cambridge semiconductor corridor:England's chip design clusters generate captive demand for high-reliability ceramic capacitors. Local R&D partnerships between foundries and passive component distributors are deepening.
- Nickel-based termination metallization:Palladium substitution in electrode formulations is reducing input cost volatility. UK contract manufacturers are qualifying these formulations for automotive grades.
Market Restraints
- Palladium supply concentration:Russian and South African mining dominance creates price volatility in termination materials. British manufacturers hold limited buffer inventory against supply disruption.
- RoHS compliance friction:ECHA's restricted substance testing protocols extend qualification timelines for new dielectric formulations. Small-batch UK distributors struggle with documentation burdens.
- Base-metal electrode limitations:Nickel-copper systems exhibit inferior high-frequency performance versus precious metal alternatives. Aerospace and defense applications retain palladium dependency.
Strategic Opportunities
- Bristol aerospace cluster:Underpenetrated demand for MIL-PRF-qualified MLCCs exists among satellite and UAV manufacturers. Local technical service partnerships could displace German distribution channels.
- BEIS critical minerals strategy:Government stockpiling initiatives for nickel and rare earth elements may stabilize input costs. Domestic capacitor assemblers could secure preferred supplier status.
- Silicon carbide power module convergence:Wide-bandgap semiconductors require MLCCs with extended temperature ratings above 150°C. British automotive inverter manufacturers represent a captive growth vertical.
Industry Challenges
- AEC-Q200 certification timelines:Automotive qualification cycles extend 18-24 months for new dielectric formulations. UK distributors face working capital strain during customer validation.
- Dielectric R&D talent scarcity:Barium titanate formulation expertise concentrates among aging specialists. British universities produce limited ceramic engineering graduates.
- Legacy through-hole inventory:Contract manufacturers maintain obsolete component stocks for industrial maintenance contracts. Mixed procurement systems complicate surface-mount transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom MLCC Market |
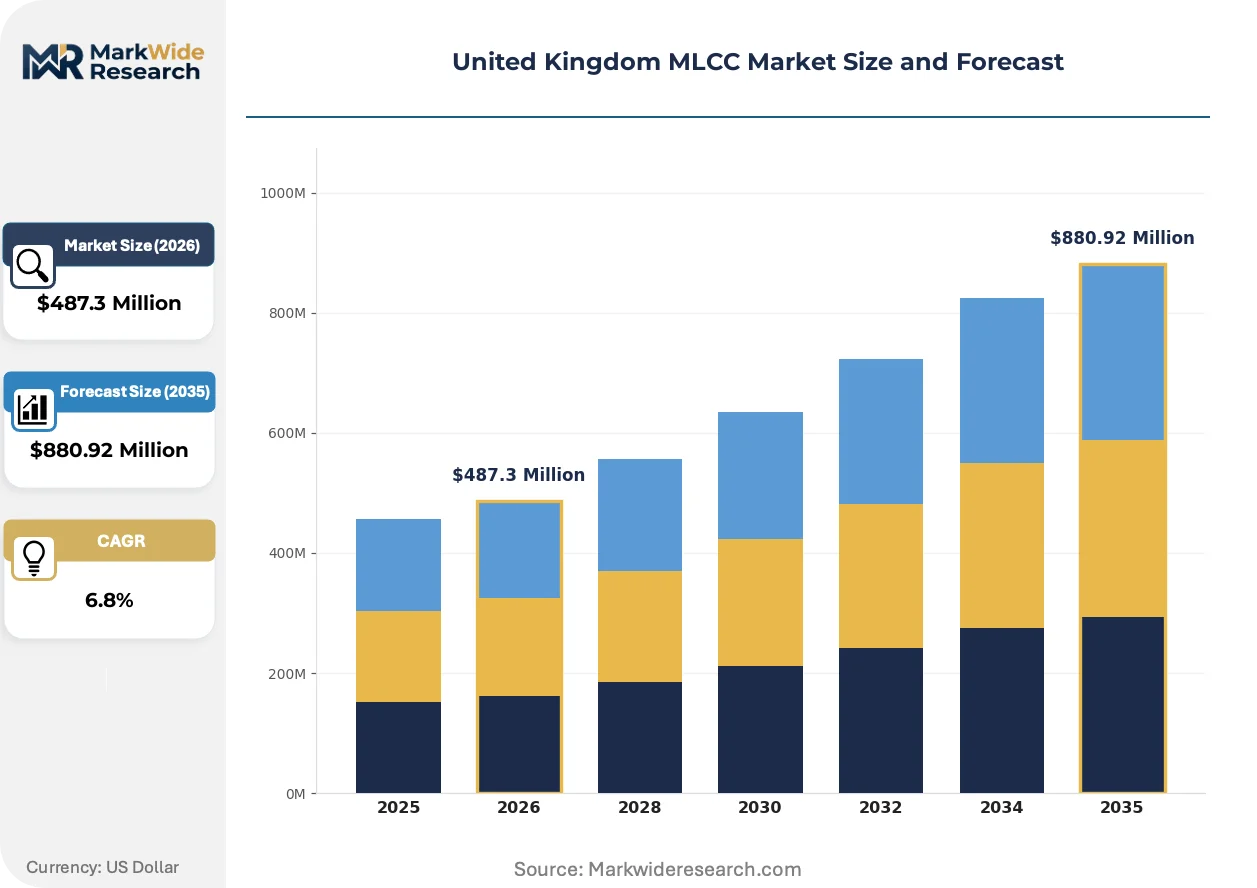
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multilayer, Single-layer, Targeted Capacitance, Special Type Application: Consumer Electronics, Automotive Systems, Telecommunications, Power Supplies End User: OEMs, Aftermarket Providers, Electronics Manufacturers, Assemblers Installation: Surface Mount, Through-hole, Embedded, Modular |
| Companies Covered | Murata Manufacturing Co. Ltd., TDK Corporation, Samsung Electro-Mechanics, Taiyo Yuden Co. Ltd., Yageo Corporation, KYOCERA AVX Components Corporation, Vishay Intertechnology Inc., Maruwa Co. Ltd., Walsin Technology Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom MLCC Market Trends and Innovations
Dielectric material science and firing process control are compressing capacitor form factors while extending temperature envelopes. British automotive and aerospace procurement specifications are evolving in parallel.
High-voltage X7R dielectric formulations are rendering obsolete mid-voltage Y5V and Z5U grades in automotive DC-DC converters. Jaguar Land Rover and Aston Martin procurement teams now specify X7R minimums for 48V mild-hybrid systems. This specification tightening is compressing distributor margins on commodity-grade inventory.
RoHS substance restrictions from ECHA are mandating lead-free termination finishes across all CE-marked electronics. British contract manufacturers must maintain dual qualification tracks for aerospace exemptions versus commercial compliance. Automotive Tier 1 suppliers are consolidating purchasing around distributors with integrated testing laboratories.
Consignment inventory models are displacing traditional spot purchasing among England's semiconductor corridor assemblers. Cambridge and Bristol chip designers now demand vendor-managed stock programs with weekly consumption reporting. This shift concentrates purchasing power among distributors with local warehousing capacity.
United Kingdom MLCC Market Segmentation
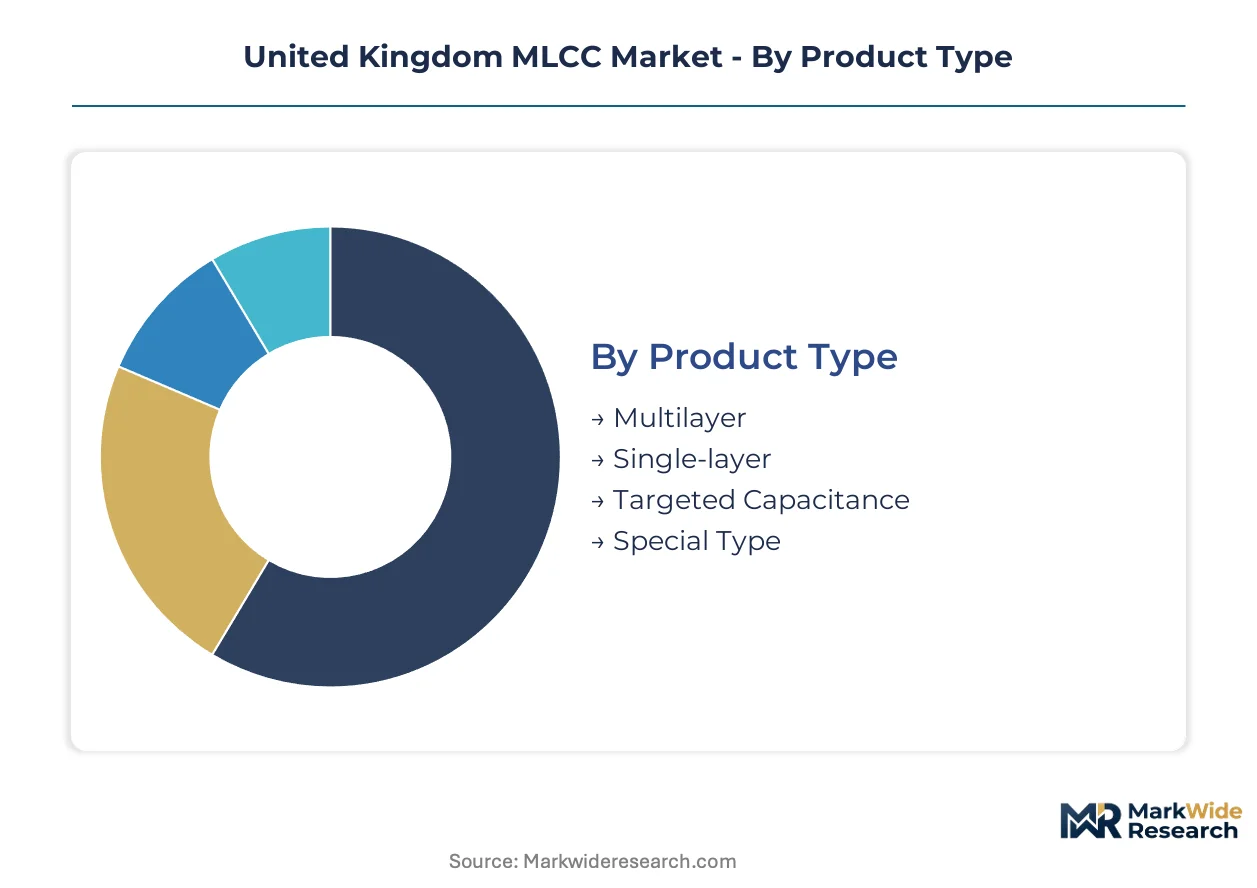
MLCC procurement in the United Kingdom fragments across technical specifications, end-use requirements, and supply chain integration models. Understanding these divisions reveals where pricing power concentrates and which customer relationships demand specialized service investments.
Product Type:
After-sales service intensity varies dramatically across product categories, with specialized formulations requiring dedicated technical support teams while commodity grades operate through self-service portals.
- Multilayer:These devices stack alternating ceramic dielectric and metal electrode layers sintered above 1,200°C to achieve superior volumetric efficiency. Demand concentrates in England's semiconductor corridor around Cambridge and Bristol, where chip designers specify these for miniaturized power management circuits. BEIS market surveillance for CE marking compliance adds documentation overhead that favors distributors with integrated testing laboratories.
- Single-layer:Constructed from a single ceramic disk with metallized surfaces, these capacitors serve cost-sensitive filtering applications. Bristol aerospace assemblers retain limited demand for legacy equipment maintenance, though procurement volumes trail multilayer alternatives by substantial margins.
- Targeted Capacitance:Precision-tolerance components specified for tight capacitance stability across temperature ranges. British automotive inverter manufacturers qualify these for silicon carbide power modules.
- Special Type:Custom geometries and dielectric formulations addressing niche thermal or mechanical stress requirements. UK satellite manufacturers in the Bristol cluster specify MIL-PRF-qualified variants.
By volume, Multilayer leads. By growth pace, Targeted Capacitance is expanding most quickly.
Application:
Cost tier stratification separates premium-qualified automotive grades from commodity consumer electronics inventory, with margin structures reflecting certification burden differentials.
- Automotive Systems:AEC-Q200 qualified components with extended temperature ratings support electrified powertrain architectures. Jaguar Land Rover and Aston Martin procurement teams now specify X7R dielectric minimums for 48V mild-hybrid systems, tightening qualification requirements.
- Consumer Electronics:High-volume, cost-optimized capacitors for smartphones, tablets, and wearables. Demand concentrates among contract manufacturers serving international brands with limited UK value capture.
- Telecommunications:Base station and network infrastructure components requiring stable high-frequency performance. Cambridge R&D partnerships between foundries and passive distributors deepen local procurement relationships.
- Power Supplies:Filtering and energy storage for industrial and commercial conversion equipment. Nickel-based termination metallization reduces input cost volatility for British assemblers.
Automotive Systems commands premium pricing tiers. Consumer Electronics maintains volume leadership.
End User:
Customer type determines contract structure, with OEMs demanding vendor-managed inventory while aftermarket providers accept spot-market terms.
- OEMs:Original equipment manufacturers with consolidated purchasing power and long-term supply agreements. Tier 1 automotive suppliers concentrate procurement among distributors with AEC-Q200 testing capabilities and local warehousing.
- Electronics Manufacturers:Contract assemblers producing printed circuit boards for diverse end-markets. REACH compliance documentation requirements from ECHA strain small-batch procurement operations.
- Aftermarket Providers:Maintenance and repair distributors serving legacy equipment. RoHS substance restrictions create dual qualification tracks against aerospace exemptions.
- Assemblers:Final integration facilities with limited component specification authority. Consignment inventory models displace traditional spot purchasing among Cambridge corridor chip designers.
OEMs dominate procurement value. Electronics Manufacturers represent the steepest expansion trajectory.
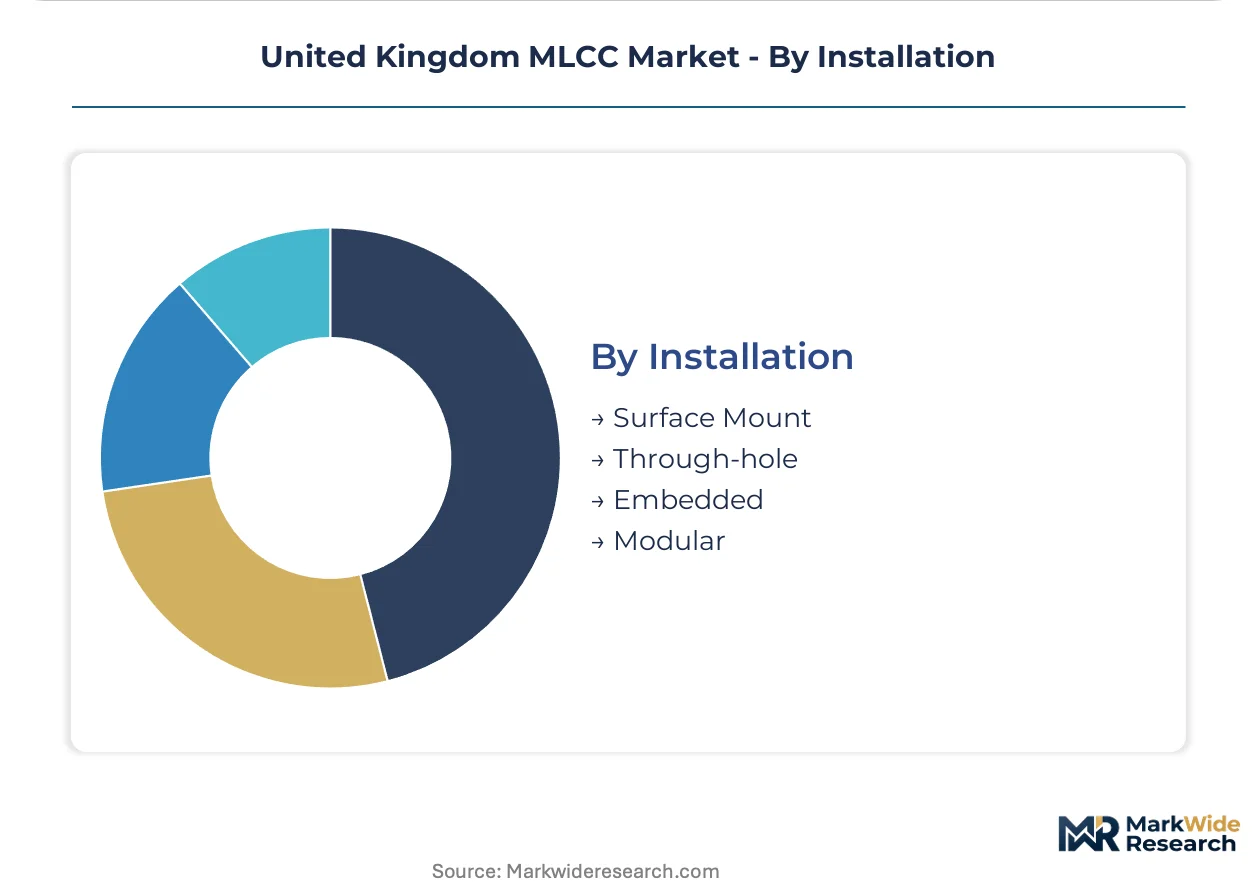
Installation:
Volume scale separates high-automation surface-mount lines from manual through-hole operations, with capital investment requirements shaping competitive entry barriers.
- Surface Mount:Automated pick-and-place compatible components dominating contemporary British contract manufacturing. Bristol and Cambridge clusters have nearly completed transition from legacy alternatives.
- Through-hole:Leaded components for hand-soldering or legacy equipment maintenance. Industrial maintenance contracts sustain residual demand despite technology obsolescence.
- Embedded:Capacitors integrated within substrate or package structures for extreme miniaturization. Advanced packaging R&D in England's semiconductor corridor drives qualification activity.
- Modular:Pre-integrated capacitor banks for simplified assembly. Power supply manufacturers value reduced component count and simplified procurement.
Surface Mount leads by unit volume. Embedded is gaining share fastest among next-generation designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Felixstowe anchors UK electronics import corridors, handling containerized passive components bound for Cambridge and Bristol assembly clusters. National Grid interconnections to continental Europe stabilize power supply for precision firing operations in ceramic capacitor manufacturing.
England
Jaguar Land Rover and Aston Martin electrification programs drive AEC-Q200 component procurement. BEIS market surveillance tightens CE marking traceability across automotive supply chains. The Cambridge semiconductor corridor concentrates chip design activity that generates captive MLCC demand for power management circuits.
Scotland
Space satellite manufacturing in Glasgow creates demand for MIL-PRF-qualified high-reliability capacitors. Scottish Enterprise innovation funding supports advanced packaging R&D initiatives. Edinburgh's fintech hardware startups specify miniaturized multilayer configurations for portable encryption devices.
Wales
Compound semiconductor foundries in Newport source specialized dielectric formulations for wide-bandgap power modules. Welsh Government advanced manufacturing grants attract testing laboratory investment. Cardiff's automotive wiring harness assemblers consolidate purchasing around REACH-compliant distributors.
Northern Ireland
Medical device manufacturers in Belfast require RoHS-compliant components for diagnostic equipment exports. Invest Northern Ireland supports electronics assembly reshoring from Asian contract manufacturers. Londonderry's aerospace maintenance facilities sustain residual through-hole demand for legacy avionics.
Midlands
Battery gigafactory announcements near Coventry intensify procurement of high-voltage X7R grades for electric powertrains. West Midlands Combined Authority infrastructure investment improves logistics connectivity to continental European component hubs. Derby's rail signaling suppliers specify extended temperature-rated capacitors for rolling stock electronics.
United Kingdom MLCC Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream where dielectric formulation expertise and firing process control determine performance differentiation. The UK MLCC procurement landscape tilts toward consolidated distribution channels serving Tier 1 automotive suppliers, with smaller contract manufacturers facing qualification documentation burdens. Three archetypes dominate: Japanese ceramic specialists with proprietary material science, Korean scale-driven fabricators competing on cost-performance, and European technical service providers anchoring local OEM relationships. Capacity expansion and strategic technical partnerships constitute the dominant competitive vectors as electrification intensifies demand for automotive-qualified inventory.
Among Japanese ceramic specialists, Murata Manufacturing Co. Ltd. and TDK Corporation exemplify the premium-tier archetype through proprietary barium titanate expertise and European technical service infrastructure. Samsung Electro-Mechanics occupies a position representing the cost-performance competitive vector. These three entities anchor the supplier base visible in British automotive and semiconductor corridor procurement specifications, with their relative positioning reflecting divergent strategic emphasis on material science depth versus manufacturing scale.
| Leading Market Players |
|---|
| Murata Manufacturing Co. Ltd. |
| TDK Corporation |
| Samsung Electro-Mechanics |
| Taiyo Yuden Co. Ltd. |
| Yageo Corporation |
| KYOCERA AVX Components Corporation |
| Vishay Intertechnology Inc. |
| Maruwa Co. Ltd. |
| Walsin Technology Corporation |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Japanese ceramic firing facilities is tightening supply discipline across automotive-grade MLCC tiers, compelling British distributors to accept longer contract terms and reduced spot-market flexibility. This utilization squeeze transmits directly into pricing leverage for AEC-Q200 qualified inventory, while consumer electronics grades face divergent cost compression dynamics.
Pricing Analysis
Three-tier pricing structure across AEC-Q200 automotive, industrial-grade, and consumer electronics levels governs British procurement. Price differentiation hinges on certification burden and volume scale, with Jaguar Land Rover and Aston Martin absorbing premium tiers for extended temperature ratings. Cost compression in consumer grades is intensifying because Samsung Electro-Mechanics and Yageo Corporation compete aggressively on cost-performance ratios. Tier 1 automotive suppliers exhibit lowest price sensitivity due to qualification lock-in, while small-batch contract manufacturers face margin strain from REACH documentation overhead.
Supply Chain Analysis
Cambridge and Bristol contract manufacturers hold concentrated surface-mount capacity for British semiconductor corridor demand. Component supply draws from Japan, South Korea, and Taiwan for multilayer dielectric fabrication. Raw material dependencies center on barium titanate formulations, nickel-based termination metallization, and palladium electrode alternatives. Palladium supply concentration across Russian and South African mining operations creates single-source vulnerability for aerospace-grade termination materials. Distribution runs through consolidated technical service providers with integrated AEC-Q200 testing laboratories and local warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story driven by silicon carbide power module convergence in British automotive inverter manufacturing, where wide-bandgap semiconductor adoption is creating captive demand for 150°C-rated MLCC configurations.
For Market Incumbents: Entrench AEC-Q200 certification moats through accelerated dielectric R&D partnerships with Cambridge foundries. Prioritize backward integration into nickel-based electrode formulation capacity to dampen palladium price volatility exposure. Defensive consolidation around testing laboratory infrastructure will raise barriers against emerging Korean cost competitors seeking automotive qualification.
For New Entrants and Emerging Players: Bristol aerospace cluster underpenetration offers white-space access for MIL-PRF-qualified high-reliability variants serving satellite and UAV manufacturers. Scottish space manufacturing in Glasgow presents secondary entry point with lower incumbent saturation. Technical service partnerships displacing German distribution channels provide viable go-to-market angle without direct Murata and TDK confrontation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among distributors with vendor-managed inventory programs and consignment models serving England's semiconductor corridor. Long-term viability favors acquisition targets possessing integrated REACH compliance documentation capabilities and AEC-Q200 testing infrastructure. The signal to watch is BEIS critical minerals strategy implementation, where government nickel stockpiling would stabilize input costs and revalue domestic assemblers with preferred supplier status.
| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q200 Testing Laboratory Investment | Integrated REACH and RoHS compliance capabilities attract Tier 1 automotive consolidation. |
| Dielectric R&D Partnership with Foundries | Cambridge semiconductor corridor collaborations accelerate X7R formulation qualification cycles. |
| Vendor-Managed Inventory Program Launch | Consignment models with weekly consumption reporting capture chip designer procurement consolidation. |
| Backward Integration into Nickel Electrode Supply | Palladium substitution reduces termination material cost volatility for automotive grades. |
| MIL-PRF Qualification for Aerospace Vertical | Bristol satellite manufacturers offer underpenetrated demand for high-reliability ceramic capacitors. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary source validation. Primary interviews encompassed Tier 1 automotive supplier procurement directors, Cambridge foundry platform engineers, Bristol aerospace manufacturing leads, passive component distributor technical service heads, and ECHA regulatory compliance officers. Secondary sources included BEIS market surveillance documentation, ECHA REACH substance restriction databases, SEC filings from listed ceramic capacitor manufacturers, and customs import records through Port of Felixstowe. Bottom-up demand modeling across automotive inverter, semiconductor, and aerospace applications was triangulated against top-down supply capacity assessments from Japanese and Korean fabrication facilities.
Forecast inputs considered dielectric technology transitions, AEC-Q200 certification pipeline velocity, and BEIS critical minerals policy implementation across the analysis window. Segmentation dimensions encompassed product type hierarchy, application-grade certification tiers, end-user contract structures, and installation technology migration patterns. CAGRs were derived from installed base growth in electric powertrains and silicon carbide module penetration curves. Industry-specific inputs included palladium price volatility scenarios and REACH substance restriction evolution timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Korean fabricators or accelerated palladium substitution breakthroughs would shift outcomes. Quarterly review of AEC-Q200 certification queue lengths, ECHA critical raw material designations, and Cambridge-Bristol semiconductor corridor foundry expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Inductors, Cores and Beads Market
Passive And Interconnecting Electronic Components
Discrete Diodes Market
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market
Passive And Interconnecting Electronic Components
Through-Hole Passive Components Market
Passive And Interconnecting Electronic Components
High Density Interconnect Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Multilayer Ceramic Capacitor Market
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Hybrid Capacitor Market
Passive And Interconnecting Electronic Components
LAMEA Thermal Protector Market
Passive And Interconnecting Electronic Components
Precision Chip Resistors Market
Passive And Interconnecting Electronic Components
Power and Utilities MLCC Market
Passive And Interconnecting Electronic Components
Galvanic Isolators Market