
 Digital Electronic Detonator Market | 2026-2036
Digital Electronic Detonator Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Electronic Detonator Market Insights
The EU Green Deal and associated mine decarbonization mandates is recalibrating procurement priorities across European hard-rock extraction. Orica Limited leverages its integrated blasting services model to anchor long-term supply contracts in Australian iron ore precincts. Dyno Nobel competes through dense distributor networks across North American coal and aggregates operations. MAXAM Corp specializes in emulsion-electronic hybrid systems for Latin American copper mega-mines.
A digital electronic detonator is a semiconductor-controlled initiation device that stores encrypted firing codes and delivers precision-timed detonation pulses with microsecond accuracy, typically operating at 3-24 volts with programmable delay intervals from 1 millisecond to over 10 seconds. Its primary purpose is to optimize rock fragmentation while minimizing ground vibration, air overpressure, and flyrock hazards in surface and underground blasting. Smart Detonators command the highest unit margins due to firmware complexity and cybersecurity certification requirements, while Shock Tube systems retain volume dominance in developing-market quarrying. Mining absorbs the majority of programmable detonator volumes, though Controlled Demolition applications in dense urban corridors generate premium pricing through liability-sensitive project specifications.
The US Bureau of Alcohol, Tobacco, Firearms and Explosives and Australia's Work Health and Safety Regulators enforce divergent storage, transport, and traceability standards that fragment product certification pathways and extend qualification timelines for new entrants. China's Ministry of Emergency Management and SAMR impose domestic GB standards on electronic initiation systems that foreign suppliers must satisfy through local joint ventures or licensed manufacturing. Stakeholders must monitor evolving encryption export controls and blast-data sovereignty rules as digital firing systems become networked and cloud-traceable across multinational mining portfolios.
Market Dynamics
The programmable initiation segment is experiencing a structural compression as encrypted firing codes become mandatory for underground extraction permits across multiple mining jurisdictions. Semiconductor-controlled timing precision now determines blast economics at copper and iron ore operations.
Growth Catalysts
- EU Explosives Directive:Encrypted firing code mandates in European hard-rock extraction are forcing contractor upgrades toward smart detonator platforms with traceable blast data.
- Copper mega-mines:Latin American extraction operations are adopting emulsion-electronic hybrid systems to optimize fragmentation and reduce ground vibration in high-altitude deposits.
- Microsecond accuracy:Programmable delay intervals from 1 millisecond to over 10 seconds enable precision rock breakage that minimizes flyrock hazards and air overpressure.
Market Restraints
- GB standards compliance:China's Ministry of Emergency Management and SAMR impose domestic certification requirements that foreign suppliers must satisfy through local joint ventures, extending qualification timelines.
- Input concentration:Semiconductor supply for firing circuit production concentrates in East Asian foundries, creating vulnerability for detonator manufacturers.
- Shock tube substitution:Developing-market quarrying operations retain volume preference for non-electronic initiation systems due to lower unit costs and simpler logistics.
Strategic Opportunities
- Western China modernization:State-owned mining conglomerates in Xinjiang and Sichuan provinces are retrofitting blast operations with digital signal processing technology.
- Urban demolition:Controlled demolition applications in dense metropolitan corridors generate premium pricing through liability-sensitive project specifications requiring precision timing.
- Cloud traceability:Networked firing systems with blast-data sovereignty features align with emerging multinational mining portfolio requirements.
Industry Challenges
- Firmware cybersecurity certification:Smart detonator platforms require complex encryption validation that extends product development cycles and testing costs.
- Legacy system integration:Underground mining operators face operational friction when retrofitting programmable initiation systems into existing blast pattern workflows.
- Cross-jurisdictional storage rules:Divergent transport and traceability standards between the US Bureau of Alcohol, Tobacco, Firearms and Explosives and Australian Work Health and Safety Regulators fragment product certification pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Electronic Detonator Market |
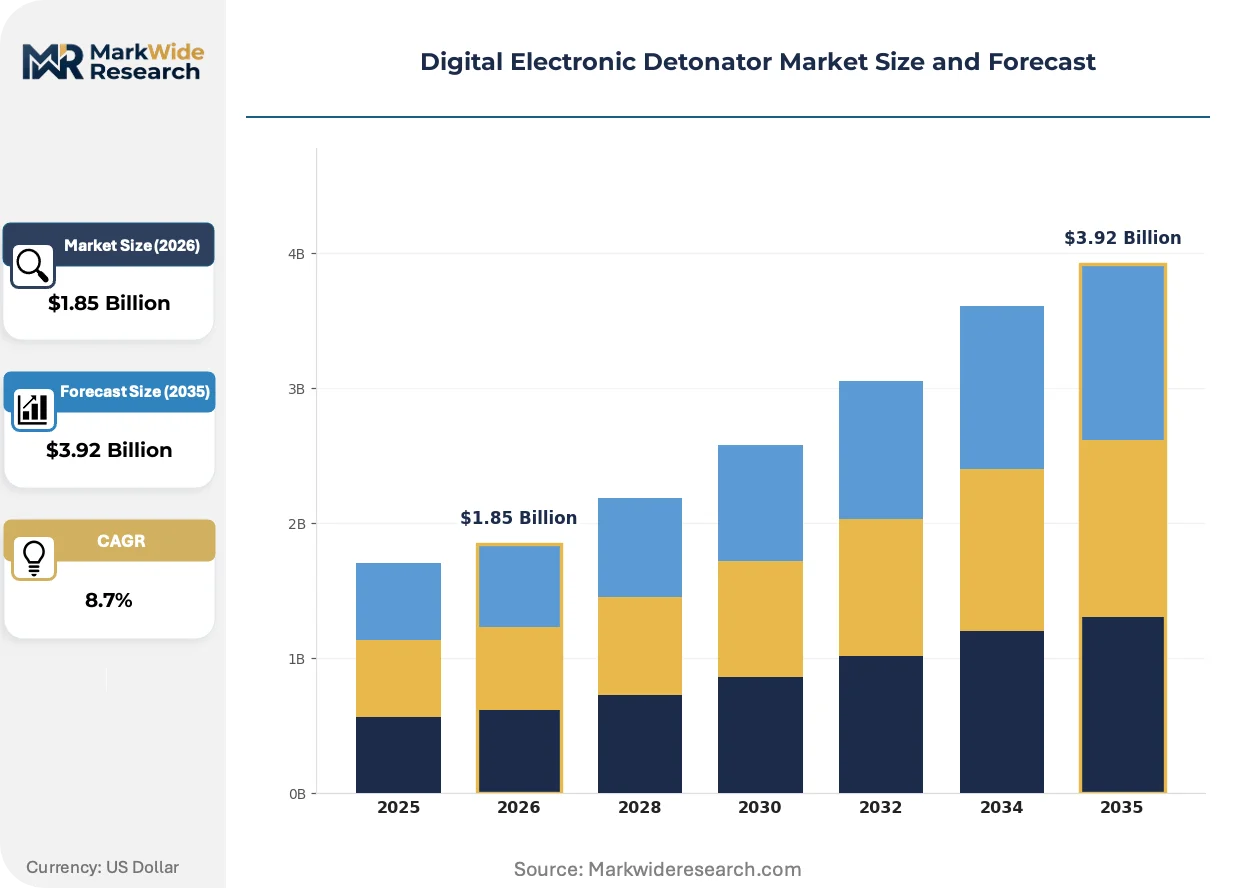
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shock Tube, Electric Detonators, Non-electric Detonators, Smart Detonators End User: Mining, Construction, Oil & Gas, Demolition Technology: Wireless Detonation, Programmable Detonators, Remote Initiation, Digital Signal Processing Application: Blast Hole Drilling, Quarrying, Safe Transportation, Controlled Demolition |
| Companies Covered | Orica Limited, Dyno Nobel, MAXAM Corp, ENAEX S.A., Austin Powder, BME, AEL Mining Services, Hanwha Corporation, EPC Groupe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Electronic Detonator Market Trends and Innovations
Blast optimization technology is converging with data sovereignty requirements, reshaping how initiation systems are specified, procured, and deployed across extraction operations. Firmware complexity and encrypted firing codes are becoming primary competitive differentiators.
Mesh-networked detonator architecture is decentralizing blast control from centralized firing boxes to distributed node communication. Underground operators in Australian iron ore precincts are piloting these systems for real-time delay adjustments. This topology is decentralizing procurement decisions toward site-level technical teams rather than corporate engineering departments.
REACH chemical compliance and the EU Green Deal mine decarbonization mandates are recalibrating procurement priorities across European hard-rock extraction. Contractors must document lifecycle emissions for initiation system components. Smart detonator platforms with embedded carbon accounting features are capturing specification share in German and Scandinavian tunnelling projects.
Site-level engineering teams are specifying initiation systems directly rather than deferring to corporate procurement functions. Dense distributor networks in North American coal and aggregates operations are losing influence to manufacturer-direct technical sales. This pattern is most visible in Australian iron ore precincts where integrated blasting services models anchor long-term supply relationships.
Digital Electronic Detonator Market Segmentation
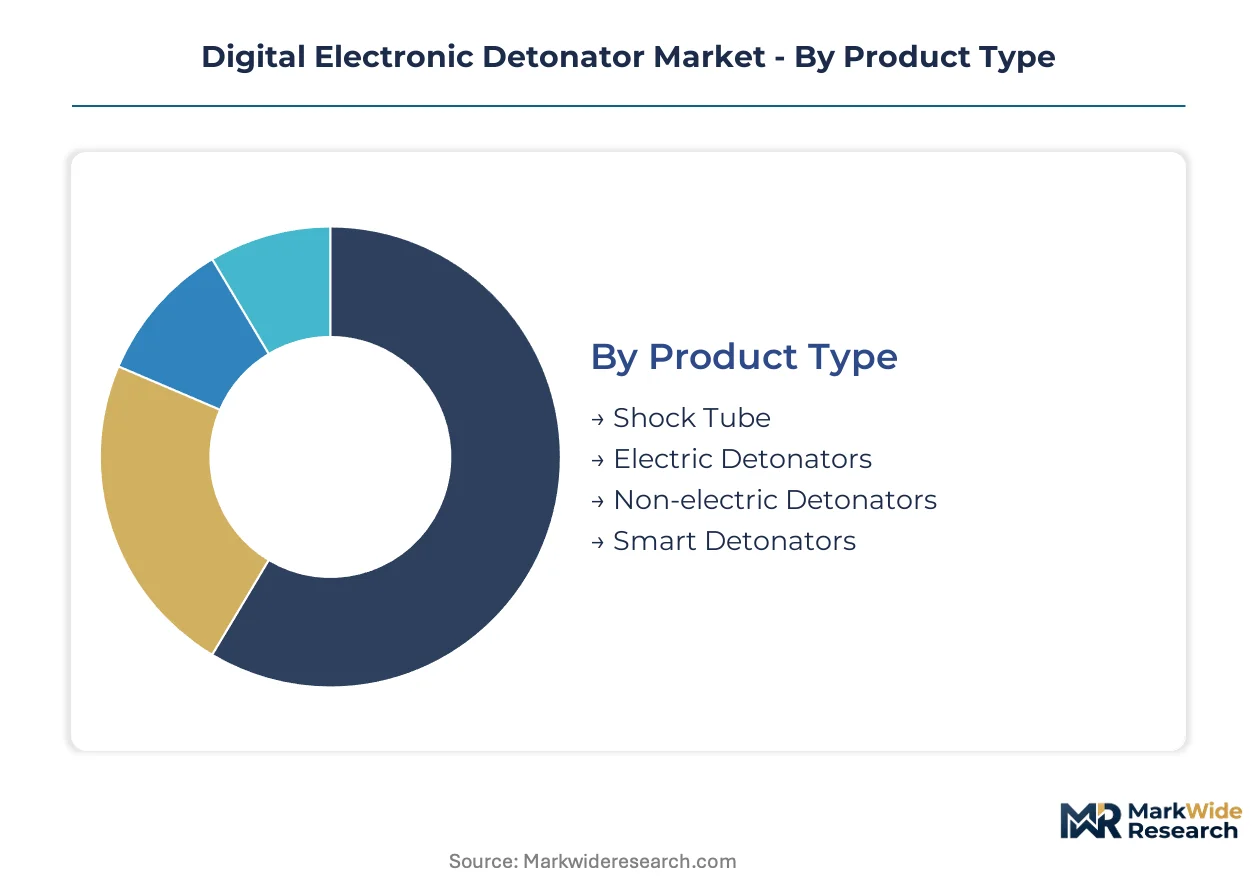
Programmable initiation systems fragment across four distinct taxonomies that reshape procurement economics. Each segmentation layer exposes different capital requirements, margin profiles, and regulatory exposure for detonator manufacturers and their distributor networks.
Product Type:
Capital intensity varies sharply across initiation technologies, with semiconductor-controlled systems demanding tenfold higher upfront investment than conventional alternatives.
- Smart Detonators:Semiconductor-controlled devices store encrypted firing codes and deliver microsecond-precision timing through programmable delay intervals. Australian underground iron ore operators and Chilean copper mega-mines absorb the majority of procurement volumes as they retrofit blast patterns to reduce overbreak and ground vibration. Firmware cybersecurity certification extends development cycles and concentrates supply among integrated blasting services providers.
- Shock Tube:Non-electric initiation systems transmit firing signals through hollow plastic tubes coated with reactive material, eliminating electromagnetic interference risks. Developing-market quarrying operations in Latin America and Southeast Asia retain volume dominance due to lower unit costs and simpler logistics chains, though margins compress against electronic alternatives.
- Electric Detonators:Conventional wire-connected devices operate at 3-24 volts with fixed delay intervals, serving legacy surface mining contracts and training applications where programmable precision remains unnecessary.
- Non-electric Detonators:Initiation systems relying on shock wave or pyrotechnic transmission without electrical components persist in remote extraction sites lacking reliable power infrastructure.
Most installed capacity flows through Shock Tube systems. Expansion is steepest in Smart Detonators.
End User:
Customer type determines specification complexity, with liability-sensitive applications commanding premium pricing tiers.
- Mining:Underground and surface extraction operations absorb programmable detonator volumes as fragmentation economics drive adoption of precision timing systems. Copper deposits in Latin America and iron ore precincts in Western Australia anchor demand concentration.
- Demolition:Controlled demolition in dense urban corridors generates premium pricing through microsecond-accurate sequencing requirements and liability-sensitive project specifications. European tunnelling contractors under EU Green Deal mandates increasingly specify carbon-accounting features.
- Construction:Infrastructure blasting for road cuts and foundation work utilizes mid-tier programmable systems where vibration constraints intersect with cost sensitivity.
- Oil & Gas:Seismic exploration and well stimulation applications demand specialized detonators rated for high-pressure, high-temperature downhole environments.
Mining commands the dominant share of programmable volumes. Demolition climbs the fastest on value terms.
Technology:
Technical architecture separates legacy wired systems from emerging wireless and cloud-traceable platforms.
- Programmable Detonators:Encrypted firing code storage with delay programming from 1 millisecond to over 10 seconds enables precision fragmentation optimization. EU Explosives Directive mandates are forcing European contractor upgrades toward these platforms.
- Digital Signal Processing:Advanced timing algorithms and real-time blast pattern adjustments concentrate in Western China modernization programs where state-owned mining conglomerates retrofit operations.
- Wireless Detonation:Mesh-networked architectures decentralize control from centralized firing boxes to distributed node communication, piloting in Australian iron ore precincts for real-time delay adjustments.
- Remote Initiation:Radio-frequency or satellite-triggered systems serve specialized military and security applications with extended standoff requirements.
Programmable Detonators anchor current installed base. Digital Signal Processing gains share fastest in state-directed procurement.
Application:
Site-specific hazard profiles dictate initiation system selection across extraction and demolition workflows.
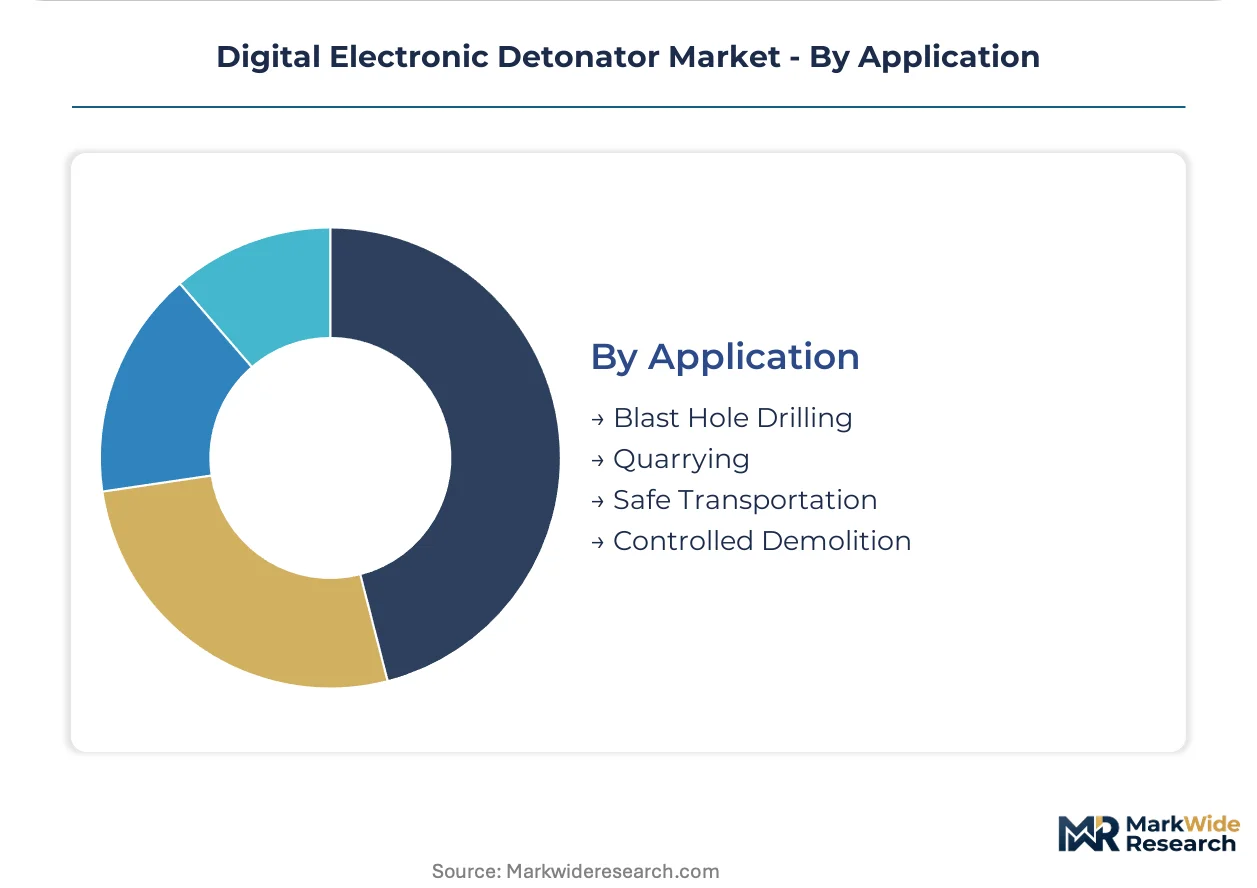
- Blast Hole Drilling:Surface and underground drilling patterns for ore body fragmentation constitute the core demand driver, with programmable timing optimizing muckpile configuration for loading equipment efficiency.
- Controlled Demolition:Urban structural takedowns requiring sequential column failure and minimal flyrock generate premium pricing through precision sequencing specifications.
- Quarrying:Dimension stone and aggregate extraction balances fragmentation quality against air overpressure constraints in proximity to populated areas.
- Safe Transportation:Specialized detonator packaging and monitoring systems for hazardous materials logistics address divergent storage rules between US ATF and Australian Work Health and Safety Regulators.
Blast Hole Drilling carries the volume base. Controlled Demolition expands most quickly on margin contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized blasting engineers and semiconductor firmware developers concentrate in mining-intensive economies where precision initiation commands premium procurement budgets.
Australia
Underground iron ore operators in the Pilbara region are retrofitting programmable initiation systems to reduce overbreak and improve extraction economics. Work Health and Safety Regulators enforce traceability standards that fragment product certification pathways for foreign entrants. Perth-based technical teams now specify smart detonator platforms directly rather than deferring to corporate procurement functions.
Chile
Copper mega-mines in the Atacama Desert are adopting emulsion-electronic hybrid systems to optimize fragmentation at high-altitude deposits. The country's national mining regulator imposes storage and transport rules that push contractors toward encrypted firing code platforms. Santiago anchors regional supply relationships for Latin American extraction operations.
China
State-owned mining conglomerates in Xinjiang and Sichuan provinces are modernizing blast operations with digital signal processing technology. SAMR and the Ministry of Emergency Management impose domestic GB standards on electronic initiation systems that foreign suppliers must satisfy through local joint ventures. Western provincial governments direct capital toward retrofitting legacy surface mining infrastructure.
Germany
Tunnelling contractors under EU Green Deal mandates increasingly specify smart detonator platforms with embedded carbon accounting features. REACH chemical compliance and the EU Explosives Directive recalibrate procurement priorities across hard-rock extraction. The Ruhr industrial corridor hosts engineering centers developing firmware cybersecurity certification protocols.
United States
Coal and aggregates operations across Appalachian basins retain volume preference for conventional initiation systems due to cost sensitivity and simpler logistics. The Bureau of Alcohol, Tobacco, Firearms and Explosives enforces divergent storage standards that extend qualification timelines for programmable system entrants. Dense distributor networks in North American mining regions are losing influence to manufacturer-direct technical sales channels.
Digital Electronic Detonator Market Competitive Landscape
Capital-heavy integrated blasting services providers compete with asset-light semiconductor firmware specialists for specification influence at mine sites. The vendor base concentrates among three tiers: multinational chemical-industrial conglomerates with captive explosives divisions, regional distributors with dense field service networks, and emerging technology licensors focused on encryption and cloud traceability. Dominant competitive moves include backward integration into semiconductor firing circuit production and strategic partnerships with mining operators for long-term supply anchoring.
Among Australia-based integrated service providers, Orica Limited occupies a position exemplifying the blasting-services-anchored model. Dyno Nobel and MAXAM Corp represent alternative archetypes within the multinational tier, with the former sitting within North American industrial chemical structures and the latter anchoring Latin American copper mine relationships. These three entities collectively illustrate how geographic origin and service integration depth determine procurement channel access across divergent regulatory jurisdictions.
| Leading Market Players |
|---|
| Orica Limited |
| Dyno Nobel |
| MAXAM Corp |
| ENAEX S.A. |
| Austin Powder |
| BME |
| AEL Mining Services |
| Hanwha Corporation |
| EPC Groupe |
| Others |
Pricing and Supply Chain Analysis
EU Explosives Directive mandates for encrypted firing codes are forcing European contractors toward smart detonator platforms, compelling manufacturers to absorb firmware cybersecurity certification costs and concentrate supply relationships among integrated blasting services providers with captive technical validation capabilities.
Pricing Analysis
The bundled-vs-unbundled service split separates procurement economics across the market. Integrated blasting services providers capture premium pricing through firmware-embedded platforms with traceable blast data, while transactional component sales compress margins. Price differentiation rests on cybersecurity certification grade and after-sales technical support depth. Cost compression in Shock Tube tiers is intensifying because developing-market quarrying operators prioritize unit economics over precision timing. Mining conglomerates in Australia and Chile show least price sensitivity due to fragmentation economics, whereas North American coal operations exhibit highest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements from Australian Work Health and Safety Regulators and Chile's national mining regulator mandate multi-supplier qualification for encrypted firing code platforms. Semiconductor firing circuit production concentrates in Taiwan, South Korea, and Japan. Raw material dependencies include silicon wafers, reactive emulsion compounds, and specialized encapsulation polymers. Single-source vulnerability sits with East Asian foundries for precision timing chips. Distribution runs through manufacturer-direct technical sales channels in Australian iron ore precincts and dense distributor networks in North American aggregates markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in firmware-tier upgrades as blast-data sovereignty requirements displace conventional initiation systems, with semiconductor-controlled platforms commanding tenfold premium multiples over Shock Tube alternatives.
For Market Incumbents: Cement long-term supply anchoring through backward integration into semiconductor firing circuit production, securing captive supply of precision timing components against East Asian foundry concentration risk. Deepen technical sales presence at site-level engineering teams in Australian iron ore precincts to preempt distributor disintermediation. Prioritize GB standards certification investment for China joint venture structures.
For New Entrants and Emerging Players: Launch via licensed manufacturing partnerships with state-owned mining conglomerates in Xinjiang and Sichuan provinces to satisfy domestic certification requirements without extended qualification timelines. Target controlled demolition applications in European urban corridors where EU Green Deal mandates and liability-sensitive specifications create specification entry points. Emphasize carbon-accounting firmware features as technical differentiation.
For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor firmware specialists possessing encrypted firing code intellectual property and cloud-traceable blast data platforms. Long-term viability favors entities with demonstrated regulatory navigation across divergent US ATF and Australian storage standards. Monitor encryption export control tightening as inflection indicator for supply chain restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Production | Captive supply of precision timing chips mitigates East Asian foundry concentration risk for firing circuit manufacturers. |
| GB Standards Certification Investment | Joint venture licensing with Chinese state-owned miners unlocks Xinjiang and Sichuan modernization procurement flows. |
| Cloud-Traceable Blast Data Platform Launch | EU Explosives Directive alignment positions vendors for encrypted firing code mandate compliance across European hard-rock extraction. |
| Site-Level Technical Sales Expansion | Direct specification influence at Perth-based engineering teams preempts distributor network displacement in Australian iron ore. |
| Carbon-Accounting Firmware Development | REACH chemical compliance and EU Green Deal positioning captures German and Scandinavian tunnelling project specifications. |
Research Methodology
Coverage spans Australia, Chile, China, Germany, and the United States, with primary inputs from each mining jurisdiction combined with secondary validation. Interviews with blasting services procurement managers, underground mine engineers, semiconductor component suppliers, regulatory compliance officers, and distributor network heads informed demand-side dynamics. Secondary sources include customs and trade data for initiation system imports, SEC filings from integrated explosives providers, EU regulatory directive documentation, and national mining safety regulator guidance materials. Bottom-up volume modeling triangulated against top-down market sizing across product type and end-use dimensions.
Granularity-level modeling deployed programmable initiation system specifications by technology architecture, with separate treatment of encrypted firing code platforms versus conventional alternatives. End-use segmentation captured mining, demolition, construction, and oil and gas applications with distinct pricing and regulatory exposure profiles. CAGRs derived from installed base replacement cycles, retrofit adoption curves in Western China, and mandate-driven upgrade timelines under EU Explosives Directive. Industry-specific inputs included blast pattern optimization economics, ground vibration constraint thresholds, and firmware development cycle durations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption scenarios or encryption export control escalation. Forecasts reflect assumptions regarding regulatory mandate enforcement timelines, joint venture qualification success rates, and site-level procurement decentralization persistence. Deviation in East Asian foundry capacity allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Battery Shunt Resistor Market
Electronic Components
VPX SBC Market
Electronic Components
Audio Capacitor Market
Electronic Components
High Density Interconnect (HDI) PCB Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
USB Wall Charger Market
Electronic Components
Conductive Polymer Capacitor Market
Electronic Components
Lowpass Filters Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
Coaxial Coupler Market
Electronic Components
Astable Multivibrator Market
Electronic Components
Frequency Control and Timing Devices Market
Electronic Components
Americas MPU Market
Electronic Components
Global Ethernet Controller Market
Electronic Components
Special Function Data Convertors Market