
 Lead Zirconate Titanate (PZT) Market | 2026-2036
Lead Zirconate Titanate (PZT) Market Size, Share, and Industry Trends Forecast 2026-2036
Lead Zirconate Titanate (PZT) Market Foresight
Software-defined calibration services for piezoelectric stacks is realigning how PZT suppliers monetize long-term customer relationships. PI Ceramics GmbH leverages its vertically integrated wafer-to-stack manufacturing to anchor premium positioning in medical imaging channels. CeramTec GmbH sustains dominance across European automotive sensor programs through captive ceramic powder production. KYOCERA Corporation extends its reach into Asian consumer electronics actuator supply through dedicated foundry partnerships.
Lead Zirconate Titanate is a perovskite-structured piezoelectric ceramic with the chemical formula Pb[ZrxTi1-x]O3, typically engineered with dopants such as niobium or lanthanum to modify electromechanical coupling coefficients and Curie temperature for specific resonant frequency applications. Hard PZT formulations dominate high-power ultrasonic welding and industrial cleaning equipment where mechanical quality factor and low dielectric loss prove critical, while soft PZT variants capture expanding share in precision positioning actuators and medical imaging transducers where enhanced piezoelectric sensitivity outweighs power handling limitations. Composite PZT architectures are displacing monolithic designs in underwater sonar and aerospace sensing where acoustic impedance matching to water or composite structures determines system performance.
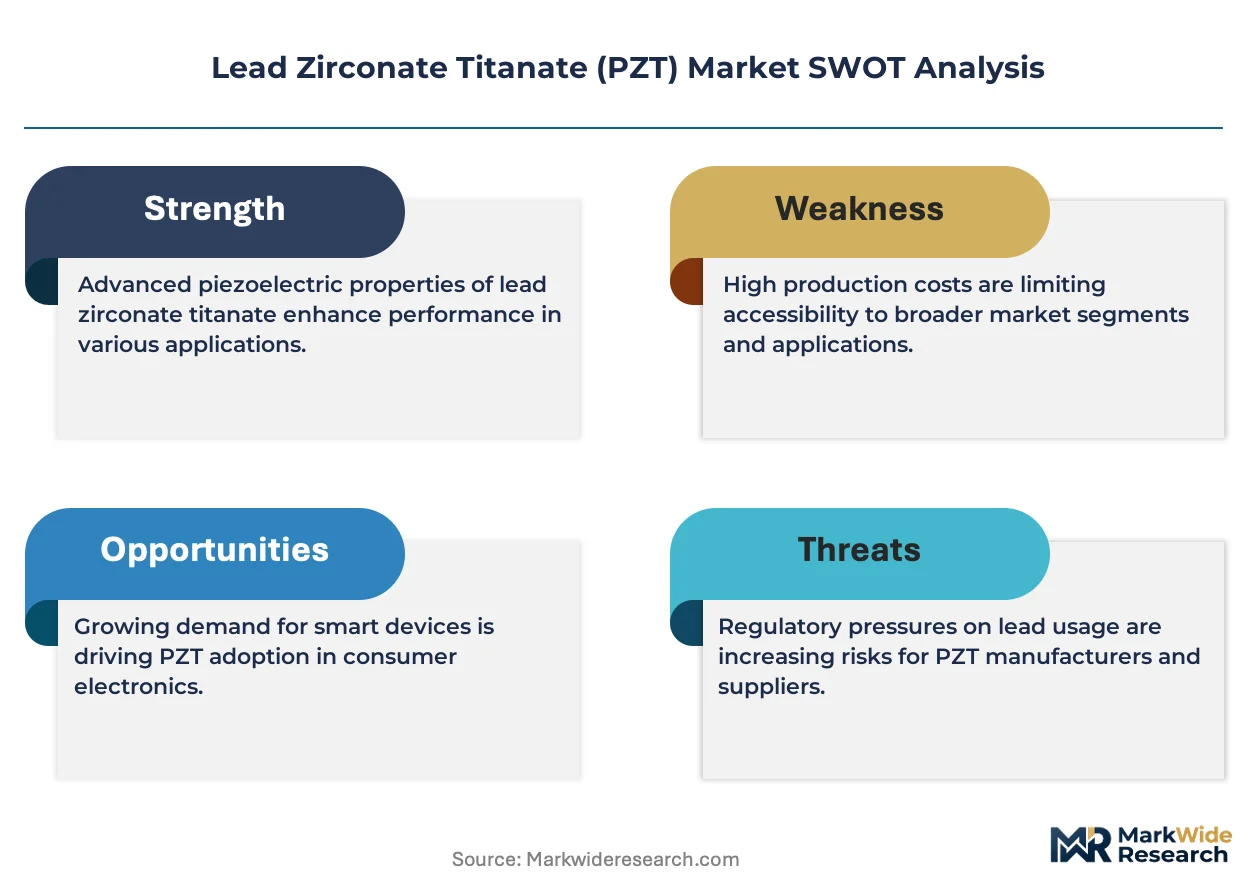
EPA lead compound regulations in the United States and REACH authorization requirements in the European Union are bifurcating the supplier base between exempted high-reliability grades and emerging lead-free alternatives, with China's GB standards providing a separate compliance pathway for domestic electronics manufacturing. FDA device classification rules for diagnostic ultrasound and therapeutic lithotripters directly specify PZT transducer performance thresholds that lock approved suppliers into validated material sources. Stakeholders must monitor regulatory exemption renewal timelines against lead-free piezoelectric maturity curves to time capacity allocation between legacy PZT and substitute ceramic platforms.
Market Dynamics
REACH authorization timelines and EPA lead compound restrictions are bifurcating procurement flows between exempted high-reliability grades and emerging lead-free alternatives, forcing suppliers to dual-track capacity investments.
Growth Catalysts
- Medical imaging upgrade cycles:Healthcare systems in Germany, Japan, and the United States are expanding diagnostic ultrasound procurement. FDA device classification rules lock approved transducer suppliers into validated PZT material sources.
- REACH exemption renewals:European Union authorization requirements sustain demand for exempted high-performance PZT grades in aerospace and defense applications where lead-free alternatives lack maturity.
- China's industrial electronics corridor:Domestic actuator and sensor production scales rapidly in Shenzhen and Suzhou clusters, concentrating procurement from regional powder processors.
Market Restraints
- Lead oxide price volatility:Raw material input costs fluctuate with mining output from Peruvian and Australian concentrate suppliers, compressing margin predictability for ceramic processors.
- Substitution threat from potassium sodium niobate:Lead-free piezoelectric ceramics advance in consumer electronics and automotive sensors where performance thresholds permit trade-offs in electromechanical coupling.
- Supply concentration in Japanese powder synthesis:Captive ceramic production by integrated manufacturers limits independent processor access to premium-grade feedstock.
Strategic Opportunities
- Underpenetrated Indian medical device manufacturing:CDSCO regulatory alignment with FDA standards opens validated supplier pathways for diagnostic ultrasound transducer production.
- Composite PZT architectures:1-3 piezoelectric-epoxy configurations displace monolithic designs in underwater sonar where acoustic impedance matching to seawater determines system performance.
- Software-defined calibration services:Piezoelectric stack maintenance contracts monetize long-term customer relationships beyond hardware shipment.
Industry Challenges
- Dual-track certification timelines:Validating lead-free piezoelectric formulations against FDA and EMA device performance thresholds extends product development cycles by 18-36 months.
- Perovskite synthesis expertise scarcity:Specialized knowledge in dopant engineering for modified electromechanical coupling coefficients concentrates among retiring cohorts in Japanese and German research institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lead Zirconate Titanate (PZT) Market |
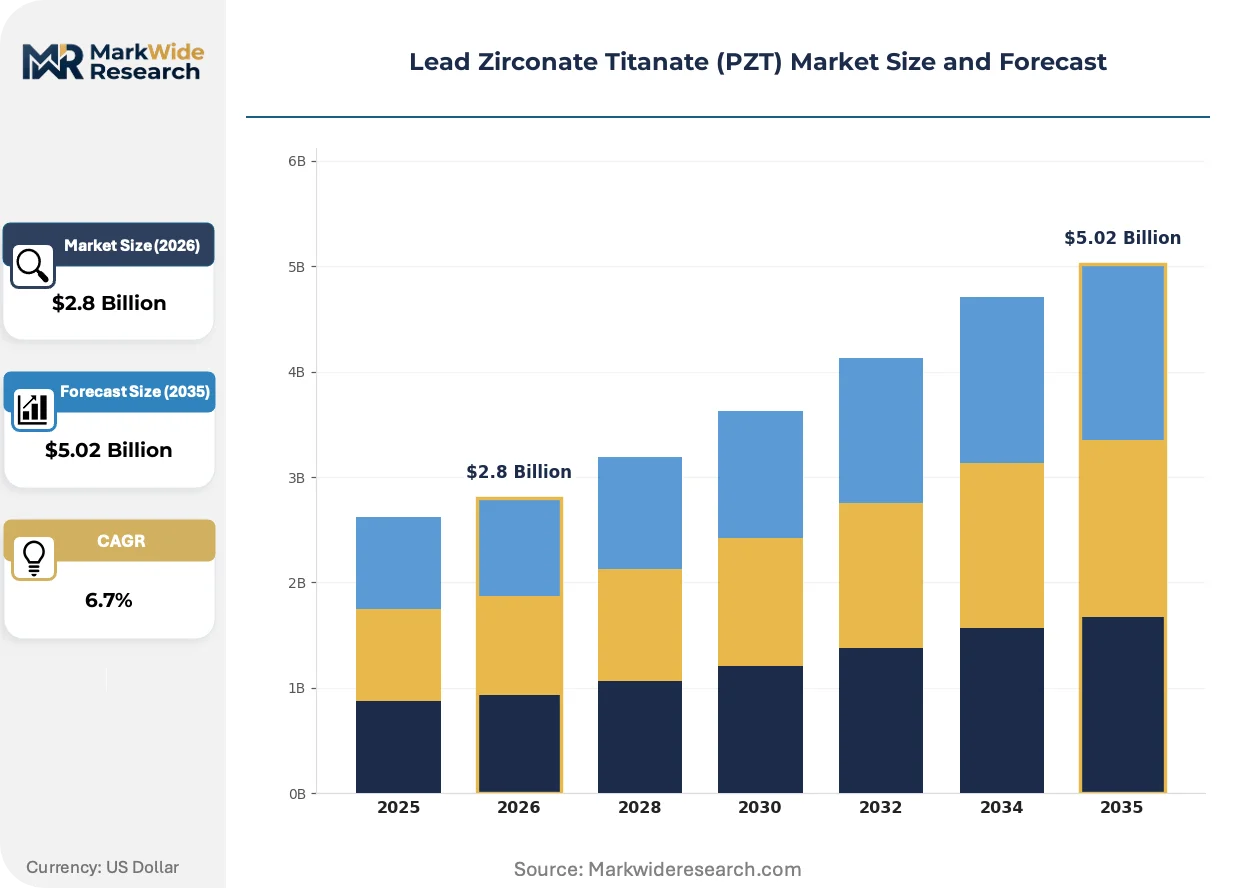
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard PZT, Soft PZT, Composite PZT, PPTZ Application: Actuators, Sensors, Transducers, RF Filters End User: Consumer Electronics, Automotive, Aerospace, Healthcare Technology: Piezoelectric Devices, Ceramic Technology, Microelectromechanical Systems, Energy Harvesting |
| Companies Covered | PI Ceramics GmbH, APC International, Ltd., CeramTec GmbH, CTS Corporation, KYOCERA Corporation, Advanced Ceramic Materials, American Elements, Stanford Advanced Materials, Physik Instrumente (PI) GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lead Zirconate Titanate (PZT) Market Shifts & Advancements
Material science advances and regulatory compliance pressures are converging to reshape competitive positioning across the piezoelectric ceramic value chain.
Composite PZT architectures with interdigitated electrode configurations are consolidating market share in high-frequency medical imaging and underwater sensing applications. Diagnostic ultrasound manufacturers in the United States and Germany are accelerating adoption of 2-2 connectivity piezoelectric-polymer composites. This consolidation is compressing addressable volume for monolithic ceramic suppliers in frequency bands above 5 MHz.
REACH authorization renewal procedures are tightening traceability requirements for lead content in exempted high-reliability grades. ECHA documentation mandates now require batch-level compositional verification extending back to raw material sourcing. European aerospace sensor programs are responding by qualifying secondary powder suppliers to reduce single-source dependency.
Transducer manufacturers are unbundling hardware procurement from calibration and maintenance service contracts. Medical imaging equipment operators in Japan and South Korea now specify performance-based service agreements with guaranteed uptime thresholds. This reconfiguration is most visible in lithotripter and HIFU therapeutic device segments where acoustic output degradation directly impacts clinical efficacy.
Lead Zirconate Titanate (PZT) Market Segmentation
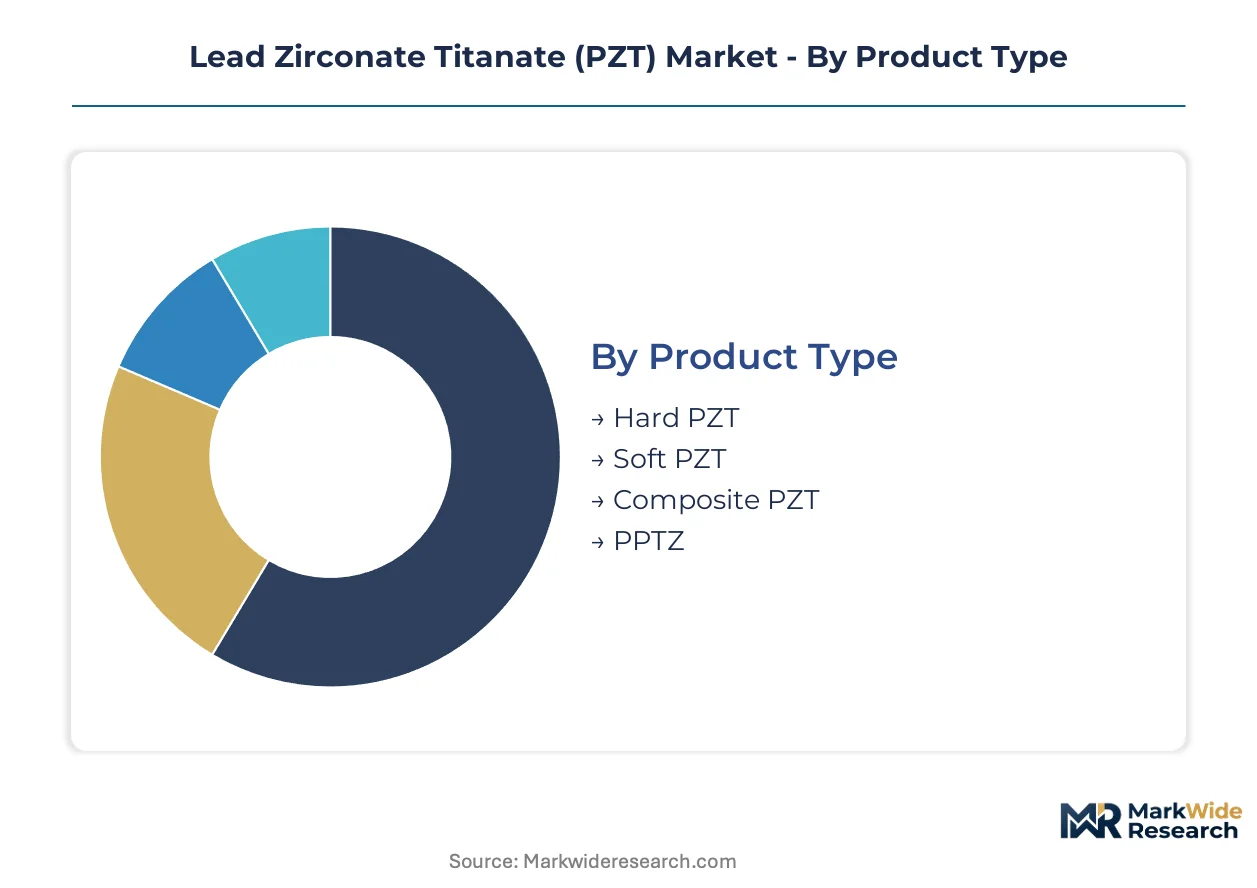
Material formulation, application requirements, and regulatory compliance create distinct procurement channels in the PZT value chain. Each segment exhibits unique supply concentration patterns that determine competitive positioning and margin structure.
Product Type:
Supply concentration in Japanese and German powder synthesis facilities favors integrated manufacturers with captive ceramic production capabilities.
- Hard PZT:Doped with acceptor ions to elevate mechanical quality factor and suppress dielectric losses. High-power ultrasonic welding equipment manufacturers in Germany and Japan specify hard formulations for industrial cleaning systems where thermal stability under sustained drive voltages proves critical.
- Soft PZT:Engineered with donor dopants to maximize piezoelectric charge coefficients and electromechanical coupling. Precision positioning actuator producers in Shenzhen and Suzhou clusters source soft PZT for semiconductor manufacturing equipment where nanometer-scale displacement resolution dominates specification sheets.
- Composite PZT:1-3 and 2-2 piezoelectric-polymer configurations reduce acoustic impedance for underwater sonar arrays.
- PPTZ:Lead-free perovskite variants advance under REACH authorization pressure for exempted-grade substitution.
Hard PZT absorbs the bulk of installed capacity; soft PZT is expanding most quickly.
Application:
End-use performance thresholds bifurcate procurement between FDA-validated medical grades and industrial commodity specifications.
- Actuators:Precision positioning stages in semiconductor lithography and optical alignment systems demand sub-nanometer resolution. Japanese machine tool builders and Chinese electronics manufacturers drive volume concentration in this segment.
- Sensors:Automotive knock detection and aerospace pressure monitoring applications specify temperature-stable formulations. German automotive sensor programs and Chinese EV powertrain monitoring systems anchor demand concentration.
- Transducers:Diagnostic ultrasound and therapeutic lithotripter manufacturers lock suppliers into FDA-validated material sources with batch-level traceability requirements.
- RF Filters:5G base station and smartphone front-end modules utilize thin-film PZT for frequency selection in sub-6 GHz bands.
Transducers command premium pricing through regulatory validation; actuators are climbing the fastest on semiconductor capital equipment cycles.
End User:
Customer concentration in China's industrial electronics corridor reshapes regional procurement patterns for commodity-grade formulations.
- Consumer Electronics:Haptic feedback actuators and microphone components in smartphones and wearables. South Korean and Chinese handset assemblers specify miniaturized multilayer stacks with tight dimensional tolerances.
- Automotive:Piezoelectric fuel injectors, parking sensors, and ADAS ultrasound modules. German premium OEMs and Chinese EV manufacturers drive divergent specification requirements for high-temperature stability.
- Aerospace:Vibration monitoring and adaptive wing structures specify exempted high-reliability grades under REACH authorization renewals. European and US defense programs maintain qualified supplier lists with limited substitution flexibility.
- Healthcare:Diagnostic imaging and therapeutic devices lock material sources through FDA and EMA device classification rules. German and Japanese equipment manufacturers concentrate procurement among pre-validated ceramic processors.
Healthcare captures the steepest margin premiums; automotive is gaining share fastest on electrification sensor proliferation.
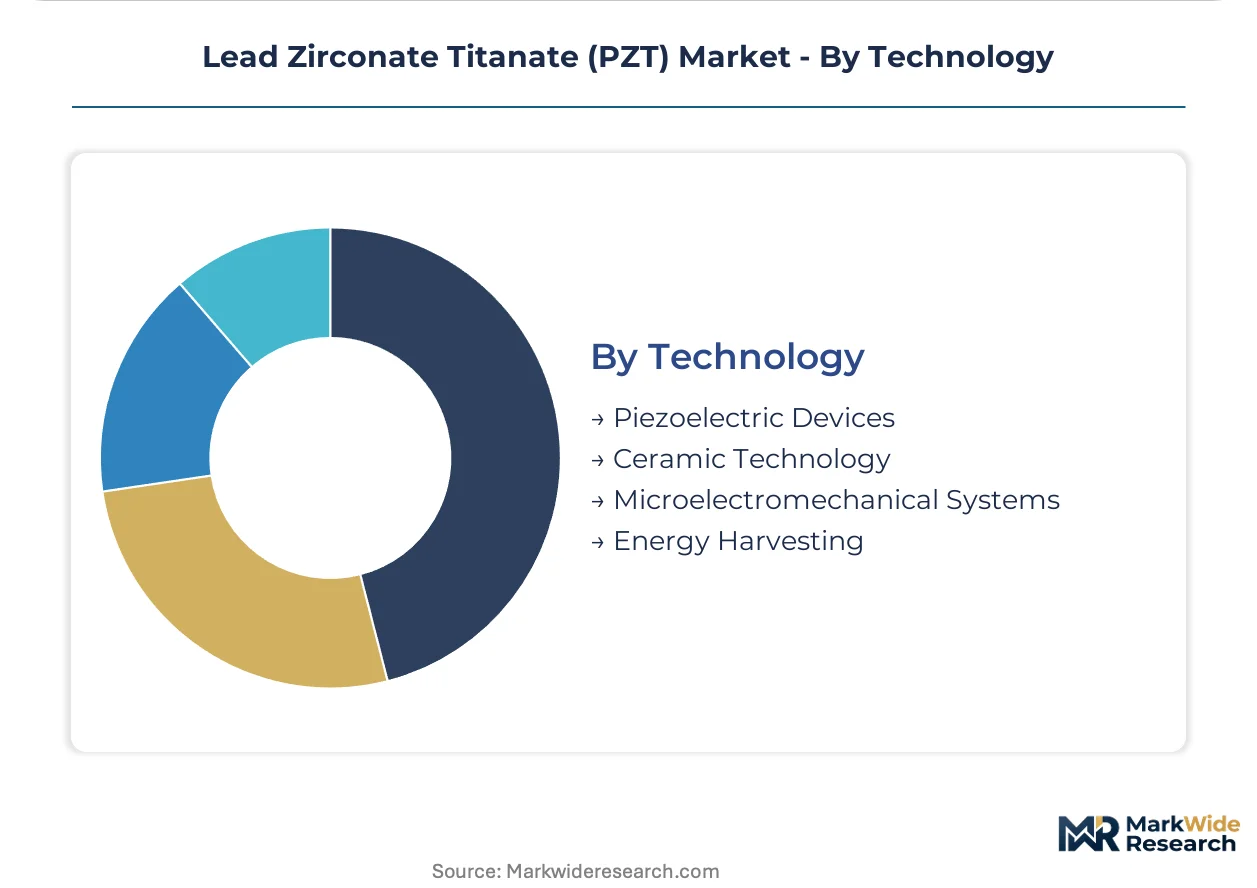
Technology:
Integration complexity determines whether suppliers capture value at the ceramic powder, processed wafer, or packaged device level.
- Piezoelectric Devices:Bulk ceramic stacks and single-crystal alternatives for high-power ultrasound and precision positioning. Japanese and German specialists dominate stacked actuator fabrication with proprietary electrode patterning.
- Ceramic Technology:Tape casting, dry pressing, and isostatic compaction methods for substrate and component manufacturing. Chinese regional powder processors scale capacity for domestic actuator and sensor production.
- Microelectromechanical Systems:Thin-film PZT deposition on silicon for RF filters and inkjet printheads. Foundry partnerships in Taiwan and South Korea concentrate advanced MEMS piezoelectric manufacturing.
- Energy Harvesting:Vibration-powered wireless sensors for industrial IoT and structural health monitoring. Emerging deployments in Japanese smart infrastructure and German predictive maintenance systems test commercial viability.
Ceramic technology retains the largest installed base; MEMS integration shows the steepest expansion trajectory on consumer electronics miniaturization demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and German manufacturers dominate powder synthesis, while Chinese processors scale rapidly for domestic actuator demand. Consumption concentrates in medical imaging corridors and industrial electronics clusters across four major economies.
United States
Diagnostic ultrasound equipment manufacturers in Massachusetts and Minnesota drive medical-grade PZT procurement. FDA device classification rules lock transducer suppliers into validated material sources with batch-level traceability. Boston's medical device corridor anchors concentration for imaging transducer production.
Germany
Automotive sensor programs and industrial ultrasonic welding equipment sustain hard PZT demand. REACH authorization requirements from ECHA sustain exempted high-reliability grades for aerospace applications. Bavaria's industrial electronics belt hosts precision actuator manufacturers serving semiconductor capital equipment.
China
Domestic actuator and sensor production scales rapidly in Shenzhen and Suzhou clusters. GB standards provide separate compliance pathways for consumer electronics and automotive sensor manufacturing. Yangtze River Delta ceramic processors expand capacity for regional machine tool builders.
Japan
Captive ceramic production by integrated manufacturers limits independent processor access to premium-grade feedstock. METI industrial policy supports domestic piezoelectric stack fabrication for semiconductor lithography systems. Nagoya's precision machinery corridor concentrates demand for sub-nanometer positioning actuators.
South Korea
Handset assemblers specify miniaturized multilayer stacks for haptic feedback actuators and microphone components. MFDS alignment with FDA standards opens pathways for medical device component sourcing. Seoul Capital Area electronics manufacturers drive MEMS piezoelectric integration for RF filters.
Lead Zirconate Titanate (PZT) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the PZT value chain. Japanese and German integrated manufacturers control captive powder synthesis, while regional processors in China scale commodity-grade ceramic production. Three archetypes dominate: vertically integrated specialists with wafer-to-stack capabilities, independent ceramic processors serving medical and industrial channels, and materials distributors sourcing from multiple powder suppliers. Capacity expansion and strategic foundry partnerships represent the dominant competitive moves as suppliers dual-track legacy and lead-free formulations.
Among German specialists, PI Ceramics GmbH and CeramTec GmbH exemplify the vertically integrated archetype with in-house powder production. KYOCERA Corporation occupies a position representing Japanese integrated manufacturers with captive ceramic capabilities. These three entities anchor the premium tier where medical imaging and aerospace qualification requirements create substantial barriers to independent processor entry.
| Leading Market Players |
|---|
| PI Ceramics GmbH |
| APC International, Ltd. |
| CeramTec GmbH |
| CTS Corporation |
| KYOCERA Corporation |
| Advanced Ceramic Materials |
| American Elements |
| Stanford Advanced Materials |
| Physik Instrumente (PI) GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Lead oxide price volatility on the London Metal Exchange cascades through PZT supply chains into three distinct pricing tiers: FDA-validated medical grades commanding certification premiums, industrial commodity grades tracking raw material indices, and emerging lead-free formulations absorbing R&D amortization costs.
Pricing Analysis
Margin tightening in medical-grade PZT reflects REACH authorization renewal costs and batch-level traceability investments. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated transducer materials from industrial sensor grades and commodity actuator formulations. Cost-down pressure on standard-tier ceramics accelerates because Chinese regional processors scale capacity for domestic machine tool builders. Consumer electronics assemblers in South Korea exhibit highest price sensitivity, while German diagnostic ultrasound manufacturers absorb premium differentials for validated supply security.
Supply Chain Analysis
Specialized perovskite synthesis expertise scarcity in Japanese and German research institutes constrains capacity expansion at premium-grade powder facilities. Supply concentrates in Japan, Germany, and China, with captive ceramic production by KYOCERA and CeramTec limiting independent processor access. Raw material dependencies draw from Peruvian and Australian lead concentrate suppliers, plus niobium and lanthanum dopant channels. Single-source vulnerability in Japanese powder synthesis creates structural risk for aerospace and medical imaging programs. Distribution runs through direct OEM partnerships for validated grades, with spot market channels serving commodity industrial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lead-free piezoelectric maturation curves and REACH exemption renewal timelines are consolidating supplier tiers, forcing sub-scale ceramic processors toward acquisition or exit.
For Market Incumbents: Anchor medical imaging channel relationships through software-defined calibration service contracts that monetize long-term uptime guarantees. Deepen backward integration into niobium and lanthanum dopant sourcing to insulate margin structures from rare earth price volatility. Defend against potassium sodium niobate substitution by accelerating composite PZT architecture roadmaps for underwater sonar and aerospace sensing applications. For New Entrants and Emerging Players: Lead-free piezoelectric formulation expertise offers entry wedge into European automotive sensor programs facing REACH authorization pressure. Target Indian medical device manufacturing corridors where CDSCO-FDA alignment creates validated supplier pathway gaps. Pursue foundry partnerships with Taiwanese MEMS fabricators for thin-film PZT deposition in 5G RF filter applications. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap ceramic processors with captive powder production in Germany and Japan facing succession-driven divestiture. Long-term viability hinges on dual-track capacity allocation capability between legacy PZT and lead-free platforms. Watch ECHA exemption renewal timelines against KNN ceramic electromechanical coupling coefficient improvement curves as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dopant Supply | Captive niobium and lanthanum sourcing insulates Japanese and German processors from rare earth price volatility. |
| Lead-Free Formulation R&D Partnership | Joint development with Max Planck and Tohoku University institutes accelerates KNN ceramic maturity curves. |
| Software-Defined Service Contract Launch | Performance-based maintenance agreements monetize long-term relationships with Japanese lithotripter operators. |
| Indian Manufacturing Joint Venture | CDSCO-aligned production capacity captures diagnostic ultrasound transducer demand from underpenetrated medical device corridors. |
| Composite Architecture Capacity Expansion | 1-3 piezoelectric-epoxy configurations displace monolithic designs in German underwater sonar programs. |
Research Methodology
SEC 10-K filings, ECHA authorization documentation, and Japanese METI industrial statistics formed the secondary backbone, supplemented by customs trade data tracking lead concentrate and ceramic powder flows. Primary fieldwork engaged piezoelectric stack fabrication engineers, medical device procurement managers at German and Japanese imaging equipment manufacturers, aerospace sensor qualification leads, and ceramic powder synthesis specialists at research institutes. Bottom-up and top-down triangulation validated volume estimates against machine tool builder actuator specifications and hospital system transducer replacement cycles.
Bottom-up modeling built from individual application segments—actuators, sensors, transducers, and RF filters—across hardness grades and connectivity architectures. Top-down verification cross-checked against semiconductor capital equipment shipment forecasts, automotive sensor proliferation curves, and diagnostic imaging upgrade cycles. CAGRs derived from regression analysis of historical powder processing capacity against end-use equipment production indices, with explicit modeling of REACH exemption renewal probability weights.
Several conditions sit outside the modeled scope, including abrupt ECHA revocation of aerospace and medical exemptions, breakthrough KNN ceramic electromechanical coupling parity, and Chinese GB standard harmonization with REACH restrictions. Forecasts reflect assumptions about lead-free substitution elasticity and dual-track certification timeline stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Capacitor Aluminum Polymer Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
China Crystal Oscillator Market
Electronic Components
Discrete Capacitors Market
Electronic Components
US Frequency Control and Timing Devices Market
Electronic Components
Electronic Shelf Label Market
Electronic Components
Handheld Devices Battery Market
Electronic Components
Audio Capacitor Market
Electronic Components
Wearable Technology Component Market
Electronic Components
Amplifier Market
Electronic Components
DVB/SAT Remote Controls Market
Electronic Components
Flexible Heater Market
Electronic Components
AC Adapter Market
Electronic Components
Global Ethernet Controller Market
Electronic Components
Serial Device Servers Market
Electronic Components
Hydrogen Thyratron Market