
 Gas Discharge Tube Market | 2026-2036
Gas Discharge Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Discharge Tube Market Analytics
Silicon-carbide integration in power electronics is reconfiguring surge protection architectures across industrial and telecom systems. Littelfuse, Inc. leverages its vertical integration in ceramic-to-metal sealing to dominate high-reliability applications. TDK Corporation anchors Asian supply chains through captive production of precision glass envelopes for miniature discharge tubes. Bourns, Inc. differentiates via R&D intensity in multi-electrode designs for broadband communication networks.
A gas discharge tube is a sealed component containing an inert gas mixture between two or more electrodes, ionizing when transient overvoltage exceeds a specified breakdown threshold to divert surge current away from protected equipment. The device relies on precise gas pressure control, electrode gap geometry, and hermetic sealing to achieve microsecond response times and kiloamp surge current handling. Standard and heavy-duty types occupy the mature volume base in utility surge protection, while miniature variants for compact telecom equipment capture expanding margin pools. Multi-stage configurations integrating gas discharge tubes with metal-oxide varistors are gaining traction in data center power distribution where cascading protection architectures reduce clamping voltage residuals.
IEC 61643 and UL 1449 standards govern surge protective device performance validation, with IEC revisions tightening impulse current test levels for telecommunications applications. China's GB/T 18802 standards and the EU's CE marking requirements under the Low Voltage Directive shape market access conditions for component suppliers. Stakeholders must monitor evolving test protocols for combined wave generators and coordinate with notified bodies to maintain certification currency across target markets.
Market Dynamics
The Gas Discharge Tube Market faces structural compression as silicon-carbide power electronics redefine surge protection hierarchies, forcing legacy gas-based components to defend niche positions in high-impulse telecom and utility applications where microsecond response remains non-negotiable.
Growth Catalysts
- 5G Infrastructure Mandates:Southeast Asian governments are accelerating base station construction, creating surge protection procurement waves for ceramic-body gas discharge tubes in outdoor telecom enclosures.
- IEC 61643-21 Revisions:Tighter impulse current test levels for telecommunications surge protective devices are forcing equipment upgrades across export-certified product lines.
- Data Center Power Distribution:Cascading protection architectures combining gas discharge tubes with metal-oxide varistors are capturing design wins in hyperscale facility construction.
Market Restraints
- Precious Metal Electrode Costs:Palladium and ruthenium price volatility in electrode coatings compresses margin structures for standard-duty tube variants.
- Ceramic Body Supply Concentration:High-purity alumina substrate production clusters in China's Jiangsu and Guangdong provinces, creating geographic single-source vulnerability.
- Solid-State Surge Suppressors:Thyristor-based protection arrays are displacing gas discharge tubes in sub-kilovolt industrial control applications.
Strategic Opportunities
- India Telecom Infrastructure:BharatNet rural broadband expansion and private 5G spectrum allocations are opening surge protection procurement channels previously dominated by European suppliers.
- Multi-Electrode Miniaturization:Broadband communication networks are demanding three-electrode designs for differential-mode protection in compact fiber-to-the-home terminals.
- EU Green Deal Compliance:RoHS exemption reviews for mercury-containing alternatives are positioning inert gas discharge technologies as environmentally preferred surge protection paths.
Industry Challenges
- Hermetic Sealing Expertise Gap:Ceramic-to-metal brazing specialists with vacuum furnace experience are scarce across North American and European manufacturing bases.
- Dual Certification Timelines:Simultaneous IEC 61643 and UL 1449 approval processes extend product launch cycles by eight to fourteen months for multi-market suppliers.
- Legacy System Integration:Gas discharge tube replacement in decades-old utility substation protection schemes requires custom electrode spacing retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Discharge Tube Market |
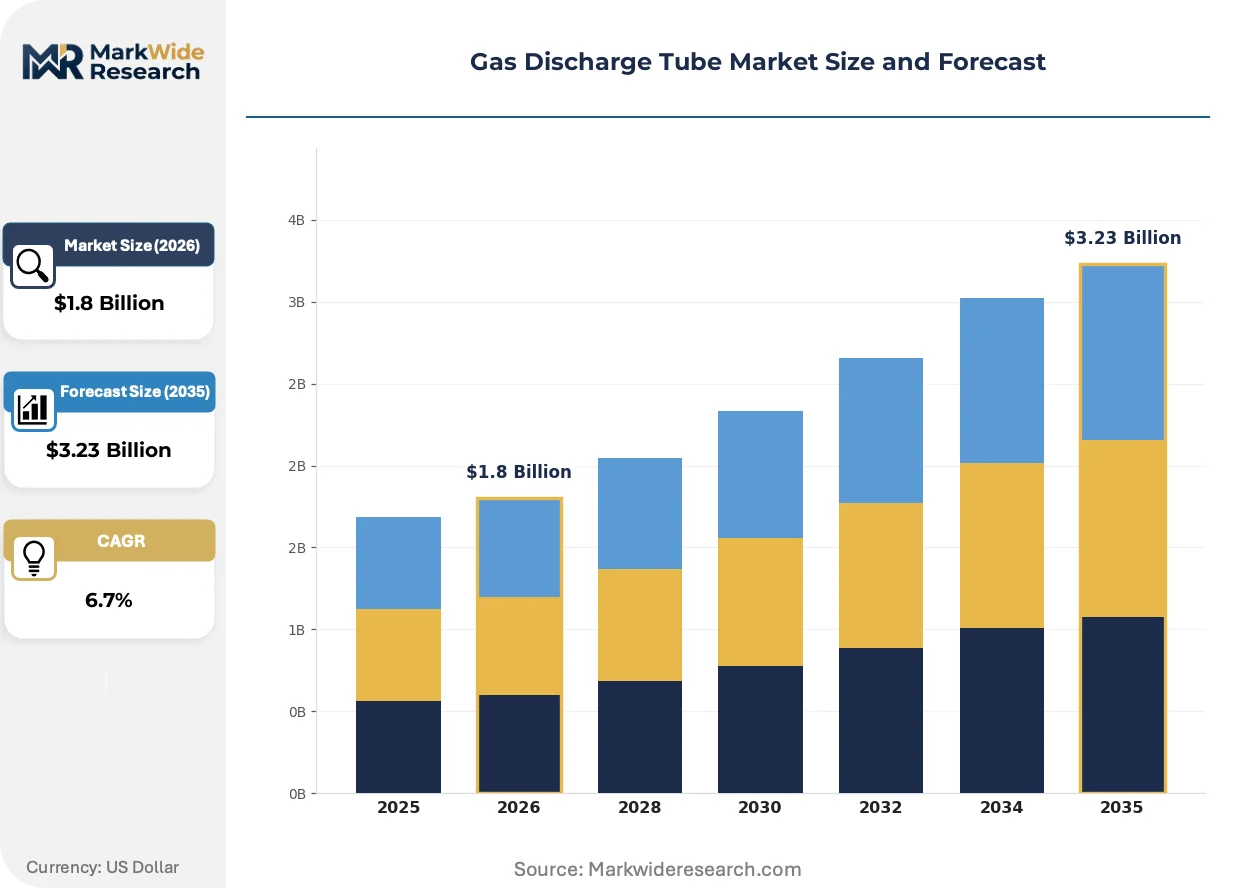
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Standard, Heavy Duty, Miniature, Multi-Stage Application: Telecommunications, Power Supply, Lighting, Surge Protection End User: Telecom Providers, Utility Companies, Electronics Manufacturers, Contractors Material: Silicon, Aluminum, Glass, Ceramics |
| Companies Covered | Littelfuse, Inc., TDK Corporation, Bourns, Inc., Eaton, Weidmüller Interface GmbH & Co. KG, HUBER+SUHNER, Phoenix Contact, YAGEO Group, DEHN SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Discharge Tube Market Evolving Landscape
Silicon-carbide integration is forcing surge protection architecture reinvention, compressing the addressable window for conventional gas-based components while opening premium niches for specialized high-impulse designs.
Hybrid surge protection modules are digitizing fault detection and response coordination in industrial power distribution systems. Manufacturing facilities in Germany and Japan are adopting these intelligent protection arrays to enable predictive maintenance workflows. The technology is digitizing how facility managers monitor transient overvoltage events across distributed electrical networks.
REACH substance restriction expansions are pressuring electrode material formulations across European export supply chains. The European Chemicals Agency's scrutiny of ruthenium compounds is accelerating palladium-silver alloy substitutions in precision glass envelope designs. Telecom equipment OEMs serving EU markets are demanding full material disclosure documentation from component suppliers.
Direct procurement relationships between gas discharge tube manufacturers and hyperscale data center operators are displacing traditional distributor channels. Infrastructure procurement teams at cloud service providers are negotiating volume contracts for multi-stage protection assemblies. This channel compression is most visible in Northern Virginia and Frankfurt data center clusters where facility construction cycles concentrate demand.
Gas Discharge Tube Market Segmentation
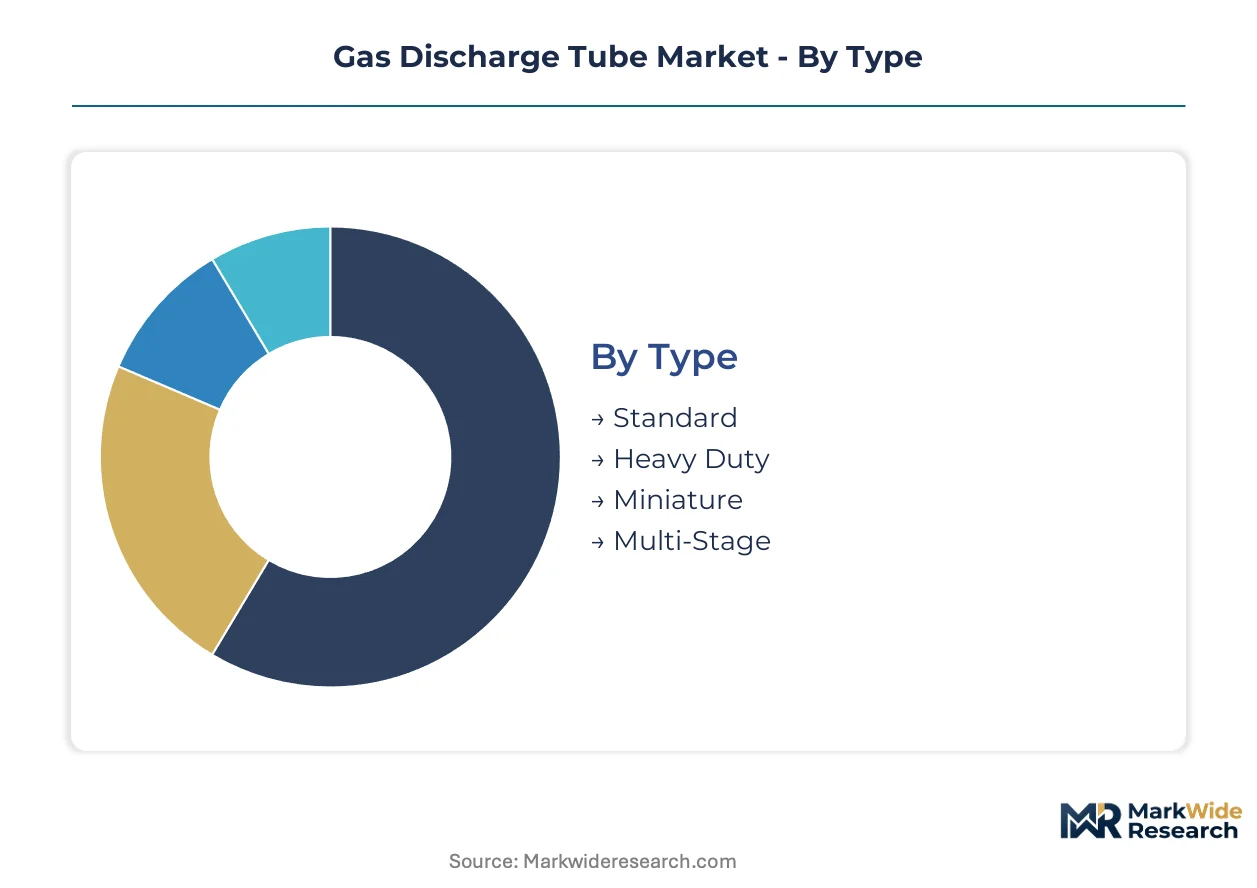
Gas discharge tube architectures diverge sharply across impulse current ratings and physical scale, with ceramic-body designs commanding telecom infrastructure while miniature variants penetrate fiber-to-the-home terminals. Material selection and electrode geometry determine response speed, hermetic integrity, and compliance with IEC 61643 surge protection standards.
Type:
Use-case spectrum spans utility substation hardening to compact consumer electronics, with impulse current tolerance and package dimensions defining procurement criteria.
- Standard:Mid-range impulse current handling with conventional two-electrode ceramic construction satisfies legacy telecommunications exchange protection. Demand concentrates in Southeast Asian 5G base station retrofits where cost-sensitive procurement favors proven designs over emerging alternatives.
- Heavy Duty:Kilovolt-class breakdown thresholds with reinforced alumina bodies and expanded electrode surface area address utility substation lightning protection. Procurement volumes track China's State Grid ultra-high voltage transmission expansion and rural electrification programs in India.
- Miniature:Precision glass envelope construction enables sub-5mm form factors for fiber-to-the-home optical network terminals.
- Multi-Stage:Cascaded gas discharge tube and metal-oxide varistor integration delivers reduced clamping voltage residuals for hyperscale data center power distribution.
Established volume favors Heavy Duty; emerging adoption favors Multi-Stage.
Application:
Application requirements map directly to impulse waveform specifications, with telecommunications demanding microsecond response and power supply segments prioritizing sustained current handling.
- Telecommunications:Three-electrode differential-mode configurations protect broadband communication equipment from lightning-induced transients. Deployment concentrates in outdoor enclosures across Indonesia, Philippines, and Vietnam where tropical thunderstorm frequency drives replacement cycles.
- Power Supply:AC mains surge protection for industrial drives and medical equipment requires coordinated thermal fusing. Demand tracks German manufacturing automation upgrades and Japanese precision equipment exports.
- Lighting:LED driver protection against switching transients and grid voltage fluctuations.
- Surge Protection:Standalone surge protective device modules for building electrical distribution panels.
Telecommunications maintains revenue concentration; Surge Protection is climbing the fastest as building codes mandate panel-level protection.
End User:
Procurement authority sits with infrastructure owners for installed-base protection and with contract manufacturers for embedded equipment integration.
- Telecom Providers:Direct specification of ceramic-body gas discharge tubes for 5G macro cell and small cell deployments. State-owned operators in China and private carriers in India negotiate multi-year volume contracts.
- Utility Companies:Substation protection schemes require custom electrode spacing for legacy relay coordination. Procurement cycles align with FERC transmission reliability mandates in the United States and CEA grid modernization directives.
- Electronics Manufacturers:OEM integration of miniature tubes into power supply modules and telecommunications equipment.
- Contractors:Installation and replacement services for building surge protection systems.
Telecom Providers dominate specification authority; Contractors gain influence through data center construction procurement.
Material:
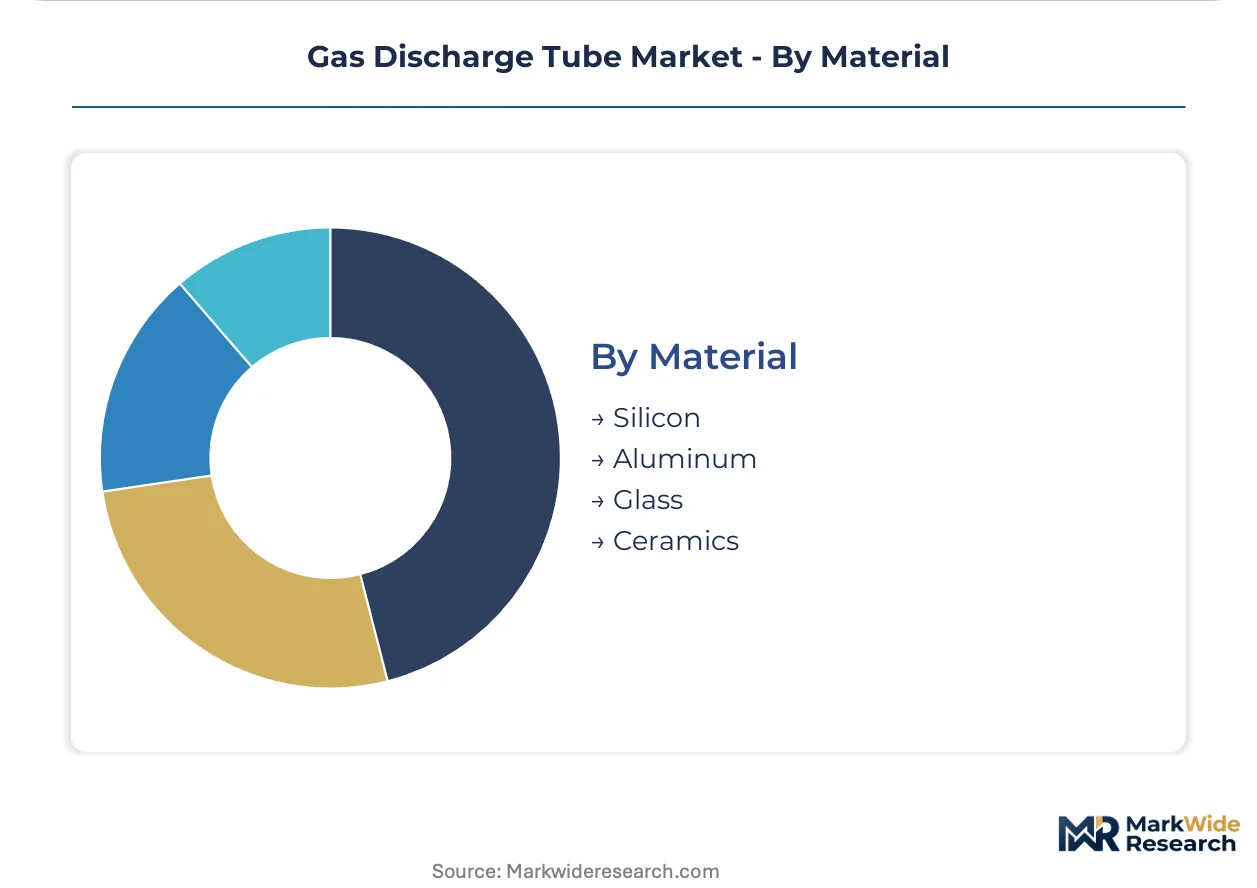
Material selection governs thermal cycling tolerance, hermetic sealing integrity, and RoHS compliance pathways for European market access.
- Silicon:Semiconductor-grade substrates enable integrated protection arrays combining gas discharge tubes with solid-state switching.
- Aluminum:Lightweight electrode substrates with palladium-silver coating for standard-duty applications.
- Glass:Precision borosilicate envelopes for miniature discharge tubes achieve sub-microsecond response through controlled gas pressure. Japanese and German manufacturing facilities specialize in precision glass-to-metal sealing.
- Ceramics:High-purity alumina bodies dominate heavy-duty and standard segments with superior thermal shock resistance. Production concentrates in China's Jiangsu and Guangdong provinces.
Ceramics anchor volume production; Glass captures expanding margin pools in miniature telecom applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu and Guangdong ceramic-body production clusters supply surge protection components to Southeast Asian telecom infrastructure buildouts and European data center construction. This trade corridor concentrates high-purity alumina substrate manufacturing capacity while export demand pulls volume toward IEC 61643-certified product lines.
China
5G base station deployment and hyperscale data center construction drive ceramic-body gas discharge tube consumption. MIIT infrastructure mandates accelerate State Grid ultra-high voltage transmission expansion. Yangtze River Delta manufacturing clusters in Jiangsu province dominate high-purity alumina substrate production for heavy-duty tube variants.
United States
FERC transmission reliability mandates and rural broadband electrification programs sustain utility substation protection procurement. FERC grid modernization directives shape certification requirements for lightning protection components. Northern Virginia data center clusters concentrate demand for multi-stage protection assemblies through direct manufacturer contracts.
Germany
Industrial automation upgrades and precision equipment exports sustain AC mains surge protection demand. REACH substance restrictions pressure electrode material formulations for European market access. Manufacturing facilities in Bavaria adopt hybrid intelligent protection arrays for predictive maintenance workflows.
India
BharatNet rural broadband expansion and private 5G spectrum allocations open surge protection procurement channels. CEA grid modernization directives align with rural electrification program timelines. Telangana and Karnataka telecom infrastructure clusters drive specification authority for ceramic-body designs in outdoor enclosures.
Japan
Precision equipment exports and METI industrial efficiency standards sustain demand for miniature glass envelope designs. JIS standards coordinate with IEC 61643 revisions for telecommunications surge protective devices. Chubu region manufacturing facilities specialize in precision glass-to-metal sealing for sub-microsecond response tubes.
Gas Discharge Tube Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: vertically integrated ceramic-to-metal sealing specialists, precision glass envelope manufacturers with captive Asian supply chains, and multi-electrode design innovators serving broadband networks. Dominant competitive moves include backward integration into high-purity alumina substrate production and strategic partnerships with hyperscale data center operators for direct procurement relationships.
Within the vertically integrated tier, Littelfuse, Inc. exemplifies ceramic-to-metal sealing dominance for high-reliability applications. TDK Corporation anchors Asian supply chain positioning through precision glass envelope production. Bourns, Inc. occupies the multi-electrode innovation vector for broadband communication networks. These three entities represent distinct competitive positioning strategies: backward integration control, geographic supply chain anchoring, and R&D-intensive product differentiation.
| Leading Market Players |
|---|
| Littelfuse, Inc. |
| TDK Corporation |
| Bourns, Inc. |
| Eaton |
| Weidmüller Interface GmbH & Co. KG |
| HUBER+SUHNER |
| Phoenix Contact |
| YAGEO Group |
| DEHN SE |
| Others |
Value Network & Pricing Analysis
China's Jiangsu and Guangdong ceramic-body production clusters concentrate high-purity alumina substrate manufacturing, capturing margin pools in heavy-duty gas discharge tubes while miniature glass envelope variants command premium pricing in fiber-to-the-home terminals. This upstream concentration shapes downstream pricing power across telecom infrastructure procurement waves.
Pricing Analysis
Legacy two-electrode ceramic constructions trade at commodity-equivalent levels against multi-stage hybrid designs integrating metal-oxide varistors that capture data center premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61643-certified telecom variants from UL 1449 utility grades and uncertified aftermarket replacements. Cost compression in standard-duty segments is intensifying because palladium and ruthenium electrode coating volatility feeds directly into bill-of-materials pressure. Contract manufacturers serving Southeast Asian 5G deployments exhibit highest price sensitivity, while hyperscale data center operators in Northern Virginia and Frankfurt tolerate premium positioning for multi-stage protection assemblies with direct procurement relationships.
Supply Chain Analysis
High-purity alumina feedstock draws from China's Jiangsu province ceramic substrate foundries, Japanese Chubu region precision glass-to-metal sealing facilities, and German Bavaria hybrid protection array manufacturing centers. Raw material dependencies center on palladium-silver electrode alloys, borosilicate glass envelopes, and semiconductor-grade silicon substrates for integrated protection arrays. Single-source vulnerability concentrates in Jiangsu and Guangdong ceramic body production clusters, where geographic concentration creates tariff exposure and logistics chokepoint risk. Distribution runs through direct manufacturer contracts with hyperscale data center operators, displacing traditional distributor channels in high-volume procurement corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gas discharge tube demand sits in early-cycle expansion as 5G infrastructure mandates across Southeast Asia and India accelerate surge protection procurement waves ahead of silicon-carbide displacement timelines.
For Market Incumbents: Build certification moats around simultaneous IEC 61643 and UL 1449 approvals that extend competitor launch cycles by eight to fourteen months. Backward integration into high-purity alumina substrate production in Jiangsu province defends margin structures against ceramic body supply concentration risks. Channel control through direct procurement relationships with hyperscale data center operators in Northern Virginia and Frankfurt clusters locks out distributor-dependent challengers. For New Entrants and Emerging Players: India's BharatNet rural broadband expansion and private 5G spectrum allocations represent the most penetrable geographic underpenetration, with procurement channels previously dominated by European suppliers now opening to new specification authorities. Telangana and Karnataka telecom infrastructure clusters offer specification entry points through ceramic-body designs for outdoor enclosures. Go-to-market positioning should emphasize RoHS-compliant inert gas formulations that align with EU Green Deal exemption reviews, targeting contract manufacturers serving European export markets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with precision glass envelope manufacturers holding captive Asian supply chains and multi-electrode design specialists serving broadband networks. Long-term viability through the technology transition window hinges on hybrid protection array capabilities that bridge gas discharge and solid-state architectures. Acquisition targets should display hermetic sealing expertise with vacuum furnace operations and existing IEC 61643 certification currency. The signal to watch is silicon-carbide power electronics penetration rates in sub-kilovolt industrial control applications, where thyristor-based suppressors displace gas-based components.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-to-Metal Sealing Capacity Expansion | Jiangsu province vacuum furnace investments capture heavy-duty tube margin pools in State Grid procurement. |
| Multi-Electrode R&D Intensification | Three-electrode differential-mode designs secure fiber-to-the-home terminal specifications in Indonesia and Philippines. |
| Direct Data Center Procurement Relationships | Bypassing distributor channels in Northern Virginia clusters locks in hyperscale volume contracts. |
| Dual Certification Investment | Simultaneous IEC 61643 and UL 1449 approvals create eight-to-fourteen-month launch barriers for competitors. |
| Hybrid Protection Array Development | Gas discharge tube and metal-oxide varistor integration addresses cascading protection demand in hyperscale facilities. |
Research Methodology
Operator-level perspectives from telecom infrastructure procurement managers, utility substation protection engineers, ceramic-to-metal sealing specialists, and hyperscale data center facility planners anchored the qualitative base. Primary fieldwork combined structured interviews with component specification authorities at state-owned operators in China and private carriers in India, validated against secondary sources including IEC 61643 standard revision documentation, FERC transmission reliability mandate filings, and MIIT infrastructure deployment disclosures. Bottom-up volume triangulation across ceramic-body, glass envelope, and multi-stage product categories converged with top-down market sizing anchored to 5G base station deployment trajectories and data center construction permits.
Scenario-bracketing around silicon-carbide power electronics penetration rates and RoHS exemption review timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include tube architecture type, impulse current rating tier, application vertical, end-user procurement authority, and regional regulatory cluster. CAGRs derived from volume-demand elasticity against telecom infrastructure capex cycles and utility grid modernization program timelines. Industry-specific forecast inputs incorporated palladium price volatility indices and hyperscale data center power distribution architecture adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by solid-state surge suppressor manufacturers or ceramic substrate capacity additions by non-traditional entrants would shift outcomes. Cross-checking against hyperscaler capex disclosure trends and State Grid ultra-high voltage transmission expansion schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Microspeaker Market
Electronic Components
Timing Relay Market
Electronic Components
Intel Motherboards Market
Electronic Components
Global Capacitor Market
Electronic Components
Global Industrial Media Converters Market
Electronic Components
Primary Charge Roller Market
Electronic Components
Global Multilayer Varistors Market
Electronic Components
Digital Potentiometer Market
Electronic Components
Lowpass Filters Market
Electronic Components
Audio Transistors Market
Electronic Components
Silicon Capacitors Market
Electronic Components
Global Smartphone Cover Glass Market
Electronic Components
Digital Isolator Market
Electronic Components
USB Charger Market
Electronic Components
Amplifier Market