
 Buffered Encoders and Decoders Market | 2026-2036
Buffered Encoders and Decoders Market Size, Share, and Industry Trends Forecast 2026-2036
Buffered Encoders and Decoders Market Analysis
The EU Green Deal's embedded carbon accounting for industrial components is rebalancing procurement criteria toward energy-efficient position sensing. HEIDENHAIN sustains technology leadership through in-house optical grating manufacturing. Sensata Technologies anchors automotive encoder supply with captive magnetic sensor fabrication. FRABA B.V. differentiates via wireless absolute encoder architectures that eliminate slip-ring maintenance.
Buffered encoders and decoders are electromechanical transducers that convert rotary or linear displacement into digital or analog electrical signals, typically achieving resolutions below one arc-minute through optical interferometry or magnetic field sensing. They serve primarily to close motion-control loops in precision machinery, enabling real-time position feedback to servo drives. Digital encoders occupy the dominant revenue position due to direct microcontroller compatibility and noise immunity in factory environments. Optical technology retains margin concentration in semiconductor and metrology applications where nanometer-scale accuracy remains non-negotiable. Magnetic technology captures fastest expansion in heavy-industrial and automotive systems where contamination resistance outweighs absolute precision requirements.
The US FCC governs electromagnetic emissions from encoder electronics, compelling shielding designs that add material cost but ensure interoperability with adjacent drives and sensors. Japan's METI promotes next-generation manufacturing standards that explicitly mandate predictive maintenance interfaces, favoring encoders with integrated condition-monitoring outputs. China's MIIT enforces GB standards for industrial equipment safety that affect encoder sealing ratings and fault-response protocols. Stakeholders must weigh magnetic versus optical technology bets against evolving regional compliance portfolios and end-user total-cost-of-ownership models.
Market Dynamics
Semiconductor fabrication expansion in Taiwan and South Korea is compressing encoder deployment cycles, while EU F-Gas Regulation constraints on optical refrigerants are forcing rapid magnetic technology substitution in precision positioning systems.
Growth Catalysts
- Wafer positioning intensity:Taiwan's TSMC-led foundry expansion demands nanometer-scale rotary encoders for lithography stages. Equipment OEMs specify buffered architectures to isolate vibration from cleanroom servo loops.
- EU F-Gas Regulation:Optical encoder cooling systems face refrigerant phase-out timelines, accelerating magnetic encoder qualification in German automotive paint lines and French packaging machinery.
- Yangtze River Delta robotics:China's domestic OEM cluster scales automated assembly, sourcing absolute encoders with integrated drive interfaces to reduce cabinet wiring complexity.
Market Restraints
- Rare earth magnet supply:Neodymium price volatility from Chinese export quotas raises magnetic encoder BOM uncertainty, compressing margins for mid-tier suppliers.
- Optical grating fabrication concentration:Master-scale manufacturing for interferometric encoders clusters in German and Japanese specialty glassworks, creating single-source vulnerability.
- Absolute magnetic resolution ceiling:16-bit magnetic systems cannot match 26-bit optical equivalents for semiconductor metrology, segmenting addressable markets.
Strategic Opportunities
- Wireless absolute architectures:Slip-ring elimination via FRABA-style inductive power and data transmission opens retrofit markets in rotating packaging turrets and wind turbine pitch systems.
- Predictive maintenance interfaces:Japan's METI next-generation manufacturing standards mandate encoder-integrated vibration and temperature outputs, creating specification pull.
- India industrial automation:PLI scheme incentives for electronics manufacturing attract encoder distributors to Pune and Chennai automation corridors.
Industry Challenges
- Embedded firmware security:IEC 62443 certification for encoder communication stacks extends development timelines and requires dedicated cybersecurity engineering hires.
- Legacy fieldbus coexistence:BiSS-C and SSI encoder interfaces must interoperate with decades-installed PROFIBUS networks in German automotive plants, complicating retrofit quoting.
- Cleanroom contamination protocols:Encoder sealing to ISO 14644-1 Class 3 standards demands specialized assembly environments that smaller suppliers cannot replicate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buffered Encoders and Decoders Market |
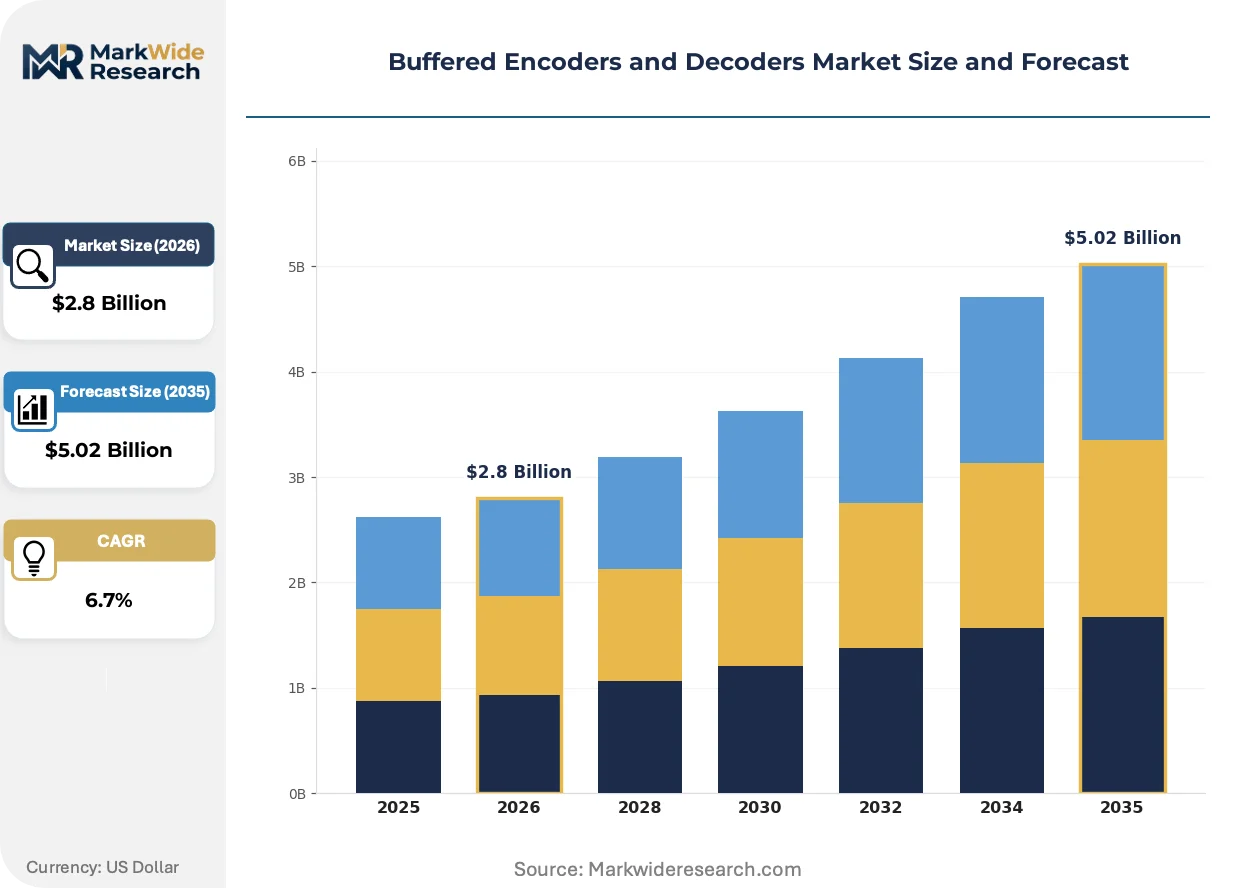
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Encoders, Digital Encoders, Decoders, Hybrid Encoders Technology: Incremental Technology, Absolute Technology, Optical Technology, Magnetic Technology Application: Industrial Automation, Robotics, Mechanical Engineering, Automotive Systems End User: Manufacturers, OEMs, Automotive, Consumer Electronics |
| Companies Covered | Sensata Technologies, HEIDENHAIN, Fortive (Dynapar), Renishaw plc, Mitutoyo Corporation, FRABA B.V., ifm electronic, Peperl+Fuchs, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buffered Encoders and Decoders Market Emerging Trajectories
Motion control architectures are collapsing discrete component boundaries, with encoder-drive-controller integration eliminating cabinet-level wiring and compressing commissioning timelines for multi-axis systems.
Single-chip encoder-drive integration is unifying position sensing and servo amplification into sealed motor-mounted modules. Semiconductor equipment builders in Taiwan adopt these integrated units to reduce cable harness complexity in vacuum-wafer-handling robots. The technology is unifying supply chains previously split between encoder specialists and drive manufacturers, forcing component vendors into partnership or acquisition decisions.
EU F-Gas Regulation phase-down schedules are constraining refrigerant-dependent optical encoder cooling systems. German machine tool OEMs accelerate magnetic encoder validation for five-micron tolerance applications previously reserved for interferometric solutions. Automotive body-in-white lines in Spain and Italy now specify magnetic absolute encoders with IP67 sealing as standard, accepting modest accuracy trade-offs for contamination immunity.
Buyer consolidation among Chinese robotics OEMs is compressing encoder procurement cycles and demanding direct technical integration support. Domestic Yangtze Delta system integrators now bypass distribution, contracting encoder firmware customization directly with manufacturer application engineers. This disintermediation concentrates volume with suppliers maintaining captive field application teams, marginalizing pure distribution-dependent competitors.
Buffered Encoders and Decoders Market Segmentation
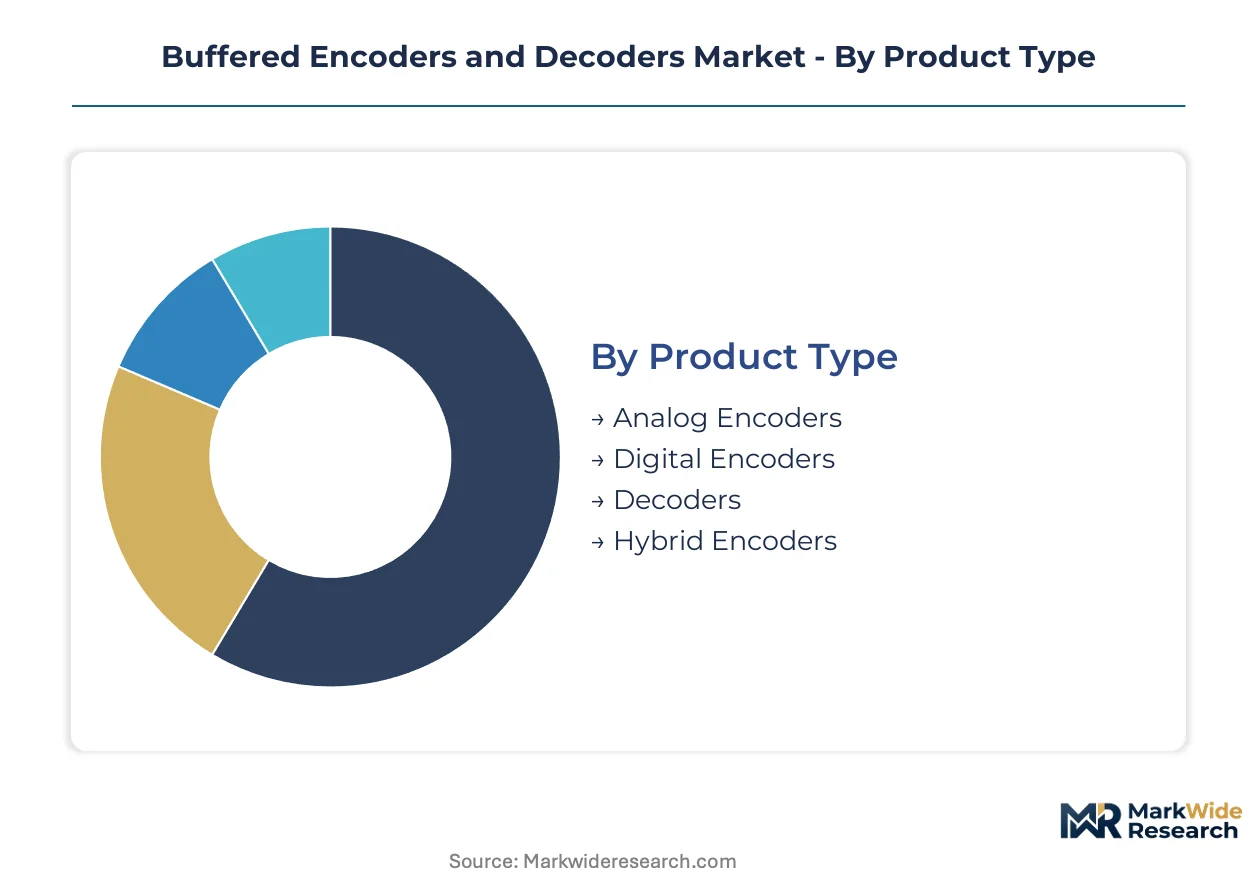
Buffered encoders and decoders segment across integration depth, sensing physics, and customer procurement models. Each dimension reveals distinct margin structures and supplier concentration patterns that shape competitive positioning.
Product Type:
Standalone encoder modules dominate high-precision applications, while embedded decoder chips increasingly penetrate cost-optimized motion systems.
- Analog Encoders:These devices output continuous voltage or current signals proportional to shaft position, requiring external analog-to-digital conversion for microcontroller interfacing. Legacy machine tool retrofit markets in Germany and Japan sustain demand despite declining share in new designs. Analog encoders retain footholds in cost-sensitive hydraulic positioning systems where digital bus infrastructure remains absent.
- Digital Encoders:Direct digital output via SSI, BiSS-C, or proprietary protocols eliminates signal conditioning overhead and delivers noise immunity in electrically harsh factory floors. Taiwan's semiconductor equipment OEMs specify buffered digital architectures to isolate lithography stage vibrations from servo control loops. Digital encoders lead volumes today; hybrid architectures are gaining share fastest.
- Decoders:Signal processing ICs that convert raw sensor waveforms into position data, often co-packaged with drive electronics in integrated motor modules. Decoder chips enable single-chip encoder-drive integration that collapses wiring complexity in multi-axis robotics.
- Hybrid Encoders:Combine analog sensing front-ends with digital output stages, bridging legacy system compatibility and modern bus connectivity. Hybrid designs serve automotive tier-1 suppliers managing multi-generation powertrain platform commonality.
Digital architectures dominate new equipment specifications; hybrid variants expand most quickly in automotive platform consolidation.
Technology:
Resolution requirements and environmental exposure dictate technology selection, with optical physics commanding premium positioning and magnetic sensing capturing contamination-intensive applications.
- Incremental Technology:Generates pulse trains relative to a reference position, requiring homing routines after power loss. Incremental encoders saturate general-purpose industrial automation where absolute position memory adds unnecessary cost.
- Absolute Technology:Maintains unique position identifiers across power cycles via multi-track code patterns or battery-backed memory. Absolute encoders command specification in China's Yangtze River Delta robotics cluster, where domestic OEMs eliminate homing delays from automated assembly line restart sequences. Absolute systems carry BOM premiums that segment addressable markets by application criticality.
- Optical Technology:Interferometric grating systems achieve sub-arc-second resolution through photodiode array detection of moiré fringe patterns. Taiwan's TSMC-led foundry expansion drives optical encoder deployment for wafer stage positioning where nanometer-scale accuracy is non-negotiable. EU F-Gas Regulation refrigerant constraints on optical cooling systems are compressing addressable markets outside semiconductor and metrology applications.
- Magnetic Technology:Hall-effect or magnetoresistive sensing of encoded magnetic fields delivers contamination immunity and shock resistance. German automotive paint lines and French packaging machinery accelerate magnetic encoder qualification as optical cooling faces phase-out timelines. Magnetic encoders lead volumes today; absolute magnetic variants are climbing the fastest.
Optical technology anchors premium positioning; magnetic systems show steepest expansion trajectory amid regulatory-driven substitution.
Application:
Application segmentation tracks motion control sophistication, from simple velocity feedback to multi-axis coordinated positioning with real-time synchronization.
- Industrial Automation:Conveyor positioning, packaging machinery, and material handling systems constitute volume demand. Industrial automation encoders prioritize reliability metrics and fieldbus compatibility over absolute precision.
- Robotics:Multi-axis articulated arms and SCARA systems demand compact encoder packages with integrated drive interfaces. Robotics applications in China's domestic OEM cluster specify absolute encoders with BiSS-C outputs to reduce cabinet wiring complexity.
- Mechanical Engineering:Machine tools, coordinate measuring machines, and precision grinding equipment require interferometric-grade feedback. Mechanical engineering sustains optical encoder margins through resolution specifications below one arc-second.
- Automotive Systems:Powertrain position sensing, steering angle measurement, and chassis dynamics control prioritize ASIL-rated functional safety. Automotive body-in-white lines in Spain and Italy now specify magnetic absolute encoders with IP67 sealing as standard.
Industrial automation generates highest unit volumes; robotics applications show strongest specification upgrading.
End User:
Procurement authority segments by technical integration depth, from component distributors serving maintenance markets to OEM engineering teams specifying custom firmware.
- Manufacturers:Factory operators purchasing replacement encoders for existing equipment through industrial distribution channels. Manufacturers prioritize interchangeability and rapid availability over technical differentiation.
- OEMs:Original equipment manufacturers integrating encoders into motion systems sold under their own brand. China's Yangtze Delta system integrators increasingly bypass distribution, contracting firmware customization directly with encoder application engineers.
- Automotive:Tier-1 and tier-2 suppliers subject to IATF 16949 quality mandates and PPAP qualification protocols. Automotive procurement concentrates volume with suppliers maintaining captive field application teams.
- Consumer Electronics:Low-cost rotary feedback for camera gimbals, drone stabilization, and gaming peripherals. Consumer electronics demands chip-scale packages at price points incompatible with industrial-grade sealing and cabling.
OEMs dominate technical specification authority; automotive end users concentrate highest per-unit value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision encoder manufacturing through specialized glassworks mastering interferometric grating fabrication. Japanese and American firms subsequently scaled optical and magnetic variants for industrial automation. Today production concentrates in German, Japanese, Taiwanese, and South Korean manufacturing clusters serving semiconductor and automotive demand.
Germany
Automotive paint lines and packaging machinery in Baden-Württemberg and Bavaria accelerate magnetic encoder validation as EU F-Gas Regulation refrigerant constraints compress optical cooling system deployment. German machine tool OEMs now qualify five-micron tolerance magnetic solutions for applications previously reserved for interferometric systems. Stuttgart and Munich industrial corridors concentrate encoder-drive integration engineering for body-in-white automation.
Japan
METI next-generation manufacturing standards mandate predictive maintenance interfaces with integrated vibration and temperature outputs from position sensors. Nagoya and Osaka precision equipment manufacturers specify absolute encoders with BiSS-C protocols to reduce cabinet wiring complexity in multi-axis robotics. Japanese semiconductor equipment builders adopt encoder-drive-controller integration to compress commissioning timelines for vacuum-wafer-handling systems.
United States
FCC electromagnetic emissions regulations compel shielding designs that add material cost but ensure interoperability between encoders and adjacent servo drives. Michigan and Ohio automotive tier-1 suppliers subject encoder procurement to IATF 16949 quality mandates and PPAP qualification protocols. Boston and Silicon Valley industrial automation clusters demand chip-scale encoder packages for collaborative robot joint modules.
South Korea
Semiconductor fabrication expansion led by Samsung and SK Hynix compresses encoder deployment cycles for lithography stage positioning. Korean industrial safety standards enforced by KOSHA affect encoder sealing ratings and fault-response protocols in automated display panel manufacturing. Gyeonggi-do and Incheon electronics corridors source nanometer-scale rotary encoders with buffered architectures isolating cleanroom vibration from servo control loops.
Taiwan
TSMC-led foundry expansion drives optical encoder deployment for wafer stage positioning where sub-arc-second resolution remains non-negotiable. Taiwan's Ministry of Economic Affairs promotes smart manufacturing adoption that favors encoder-integrated condition monitoring outputs. Hsinchu Science Park and Taichung Precision Machinery clusters specify 26-bit optical absolute encoders for EUV lithography equipment serving advanced node production.
Buffered Encoders and Decoders Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology depth and application certification tiers. The vendor base stratifies between optical grating specialists capturing semiconductor metrology premiums and magnetic sensing fabricators serving contamination-intensive industrial volumes. Three archetypes dominate: captive vertical integrators controlling sensor fabrication, partnership-dependent assemblers sourcing decoder chips externally, and wireless architecture innovators eliminating mechanical wear components. Competitive moves concentrate on encoder-drive integration partnerships and predictive maintenance interface standardization.
Within the captive fabrication tier, HEIDENHAIN and Sensata Technologies exemplify contrasting vertical integration strategies. HEIDENHAIN sustains technology leadership through in-house optical grating manufacturing while Sensata Technologies anchors automotive encoder supply with captive magnetic sensor fabrication. FRABA B.V. occupies a distinct wireless absolute encoder position eliminating slip-ring maintenance requirements for rotating machinery retrofit markets. These three represent the dominant competitive archetypes shaping procurement criteria across semiconductor, automotive, and heavy-industrial end uses.
| Leading Market Players |
|---|
| Sensata Technologies |
| HEIDENHAIN |
| Fortive (Dynapar) |
| Renishaw plc |
| Mitutoyo Corporation |
| FRABA B.V. |
| ifm electronic |
| Peperl+Fuchs |
| Omron Corporation |
| Others |
Supply Flow & Price Mechanics
Captive optical grating fabrication anchors both supply security and premium pricing power for interferometric encoder specialists serving semiconductor metrology. HEIDENHAIN's in-house manufacturing of precision glass scales insulates against raw material volatility while supporting margin structures that commodity magnetic suppliers cannot replicate.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates optical interferometric systems from magnetic absolute encoders and incremental commodity units. Price differentiation rests on certification grade—ASIL-rated automotive encoders command substantial premiums over industrial-grade alternatives—and volume scale, with Yangtze Delta robotics OEMs extracting tiered discounts through direct manufacturer contracts. Cost compression in mid-tier magnetic encoders is intensifying because neodymium price volatility from Chinese export quotas squeezes BOM predictability. Automotive tier-1 suppliers exhibit lowest price sensitivity due to PPAP qualification switching costs, while maintenance-driven replacement buyers in general industrial automation prioritize interchangeability and rapid availability over technical differentiation.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Taichung anchor hub-and-spoke patterns that position encoder inventory within 48-hour reach of major automation corridors. Manufacturing concentrates in Germany for precision optical glassworks, Taiwan for semiconductor-grade encoder modules, and China for cost-optimized magnetic sensing components. Raw material dependencies draw from Japanese specialty glass for interferometric gratings, Chinese rare earth elements for magnetic encoder magnets, and German engineered polymers for high-temperature sealing applications. Single-source vulnerability in master-scale grating fabrication creates structural risk for optical encoder supply continuity. Distribution runs through authorized technical distributors serving OEM specification teams, with direct manufacturer contracts displacing traditional channel relationships among high-volume Chinese system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Buffered Encoders and Decoders Market functions as a stable compounder anchored by irreversible automation penetration in precision manufacturing. Semiconductor fabrication expansion and regulatory-driven magnetic substitution create durable demand layers that sustain supplier margins across cycle phases.
For Market Incumbents: Extend captive sensor fabrication capabilities to defend against margin erosion from neodymium price volatility and emerging wireless architecture competitors. Deepen backward integration into rare earth magnet supply through long-term offtake agreements with Chinese processors. Invest in IEC 62443 cybersecurity certification to capture predictive maintenance interface specifications mandated by Japan's METI standards. For New Entrants and Emerging Players: Capture wireless absolute encoder retrofit opportunities in rotating packaging turrets and wind turbine pitch systems where slip-ring elimination delivers measurable maintenance cost reduction. Target India's Pune and Chennai automation corridors where PLI scheme incentives attract electronics manufacturing investment and encoder distribution remains underdeveloped. Lead with integrated drive-interface firmware customization to bypass established distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for magnetic sensing specialists because automotive qualification barriers and IATF 16949 mandates create sticky customer relationships that compound acquisition value. Five-to-ten-year viability rests on regulatory substitution tailwinds from EU F-Gas constraints and cleanroom contamination protocol expansion. Watch encoder-drive-controller integration adoption rates in Taiwanese vacuum-wafer-handling robotics as the signal indicating architectural consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Encoder-Drive Integration Partnership | Unifies position sensing and servo amplification into sealed motor-mounted modules for semiconductor equipment builders. |
| Wireless Absolute Architecture Development | Eliminates slip-ring maintenance requirements through inductive power and data transmission for rotating machinery retrofit markets. |
| Predictive Maintenance Interface Certification | Captures specification pull from Japan's METI next-generation manufacturing standards mandating vibration and temperature outputs. |
| Rare Earth Magnet Supply Securement | Reduces BOM uncertainty from Chinese export quota volatility through captive processing or long-term offtake agreements. |
| Automotive Functional Safety Investment | Enables ASIL-rated encoder qualification for powertrain and chassis dynamics applications subject to IATF 16949 mandates. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build grounded demand estimates for buffered encoder and decoder applications. Primary fieldwork engaged encoder application engineers at OEM specification teams, maintenance directors at German automotive paint lines, procurement leads at Chinese robotics system integrators, and aftermarket service heads at industrial distribution channels. Secondary validation drew from SEC 10-K filings of listed component suppliers, customs and trade data for encoder import flows, semiconductor equipment capex disclosures from TSMC and Samsung, and METI smart manufacturing policy documents. Bottom-up unit demand modeling triangulated against top-down market sizing from equipment installation bases.
Segment-weighting approaches distributed value and volume across product type, sensing technology, application intensity, and end-user procurement authority dimensions. The analytical framework applied differential growth assumptions across the projection horizon for optical versus magnetic technology substitution, semiconductor capital expenditure cycles, and automotive electrification content shifts. CAGRs derived from equipment replacement rates, technology transition timelines, and regional automation adoption curves. Industry-specific forecast inputs incorporated EU F-Gas Regulation phase-down schedules and China's GB standard enforcement timelines for industrial equipment safety.
Neodymium export policy shifts, lithography equipment demand volatility, and cybersecurity certification timeline extensions are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about technology substitution rates and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Global DC Motor Control Devices Market
Electronic Components
Electric Capacitor Market
Electronic Components
Audio DSP Market
Electronic Components
US Supercapacitor Market
Electronic Components
USB Charger Market
Electronic Components
Operational Amplifier Market
Electronic Components
Ceiling Microphone Market
Electronic Components
Electric Fuse Market
Electronic Components
Circuit Protection Kits Market
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
SAW Filters Market
Electronic Components
Digital Class-D Amplifier Market
Electronic Components
Resonators Market
Electronic Components
Global Industrial Media Converters Market
Electronic Components
Silicon Capacitors Market
Electronic Components
Special Function Data Convertors Market