
 Impulse Relays Market | 2026-2036
Impulse Relays Market Size, Share, and Industry Trends Forecast 2026-2036
Impulse Relays Market Analytics
Digital relay architectures is fragmenting legacy electromechanical supply chains as semiconductor-based control displaces coil-driven designs in precision applications. Siemens AG leverages deep vertical integration in industrial automation to sustain captive demand for its relay portfolios. Schneider Electric anchors European distribution channels for electromechanical and hybrid impulse relays across factory floors. Omron Corporation specializes in compact CMOS relay modules for Japanese electronics OEMs seeking millisecond switching speeds.
Impulse relays are electrically operated switching devices that use a brief control pulse to toggle between stable output states, typically rated for coil voltages between 12V and 230V AC/DC and contact currents up to 16A. They serve primarily in remote control and automation circuits where sustained coil energization would generate excessive heat or power drain. Solid-state impulse relays are capturing share in motor control and safety systems applications where arc suppression and cycle endurance exceed ten million operations prove decisive. Electromechanical variants still dominate lighting control installations where cost sensitivity and legacy compatibility outweigh performance premiums.
The US FCC and OSHA frameworks govern electromagnetic emissions and workplace electrical safety for relay-integrated equipment, while the EU RoHS directive and CE marking constrain hazardous substance content and market access across Europe. Japan's METI enforces JIS standards on relay reliability metrics for domestic industrial procurement. Stakeholders must weigh semiconductor migration timelines against electromechanical replacement cycles when calibrating R&D budgets and inventory positions.
Market Dynamics
Solid-state switching architectures are fragmenting legacy electromechanical supply chains as semiconductor-based control displaces coil-driven designs in precision automation applications across factory floors.
Growth Catalysts
- Industrial Automation Demand:German automotive OEMs and factory automation integrators source high-reliability switching components for robotic assembly lines and conveyor systems requiring millisecond response times.
- REACH Compliance:European material and safety specifications under ECHA frameworks are tightening hazardous substance constraints, forcing relay manufacturers toward lead-free contact materials and eco-design compliance.
- Energy Efficiency Mandates:Japan's METI enforces JIS reliability metrics that favor solid-state impulse relays in motor control applications where sustained coil energization would generate excessive heat drain.
Market Restraints
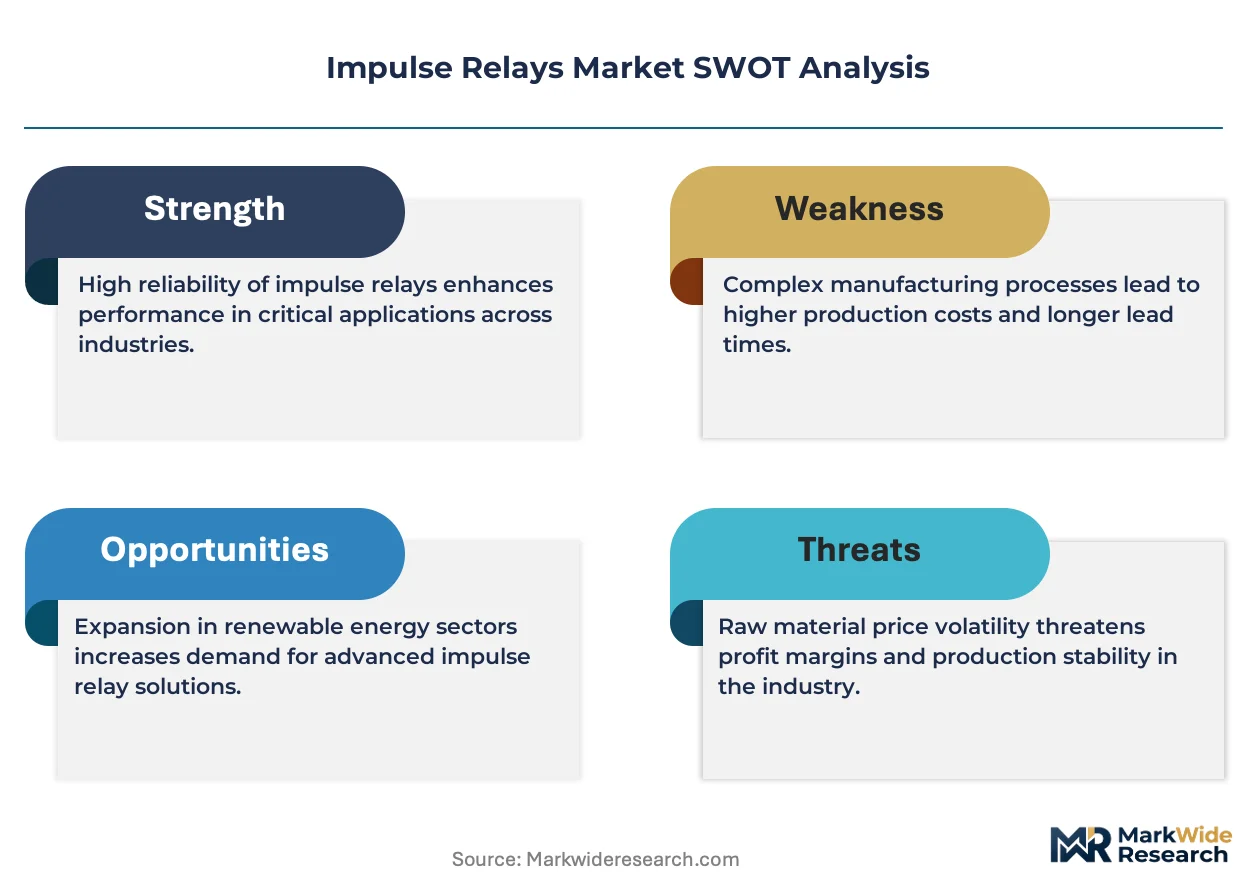
- Copper and Silver Price Volatility:Electromechanical relay production depends on precious metal contacts, exposing manufacturers to commodity input cost swings that compress margin structures.
- Semiconductor Supply Concentration:Solid-state relay fabrication relies on concentrated Asian wafer foundry capacity, creating vulnerability to geopolitical trade friction and capacity allocation priorities.
- Electromechanical Endurance Limits:Mechanical contact wear limits electromechanical variants to approximately one million operations, restricting deployment in high-cycle safety systems where solid-state alternatives dominate.
Strategic Opportunities
- Building Automation Retrofit:European commercial real estate operators are replacing legacy lighting contactors with compact impulse relay modules to enable smart building integration and demand-response grid participation.
- Renewable Energy Integration:Solar inverter and battery storage OEMs require arc-free switching for DC circuit isolation, creating specification pull for solid-state impulse relays in photovoltaic string combiners.
- IEC 61810 Harmonization:International standard convergence on relay testing protocols is reducing certification duplication costs for manufacturers seeking multi-regional market access.
Industry Challenges
- Embedded Firmware Expertise Gap:Solid-state relay development requires power electronics and thermal management engineering talent that legacy electromechanical manufacturers struggle to recruit against semiconductor industry compensation benchmarks.
- Dual Certification Timelines:Products must simultaneously satisfy IEC safety standards for industrial markets and UL listings for North American building codes, extending time-to-revenue by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impulse Relays Market |
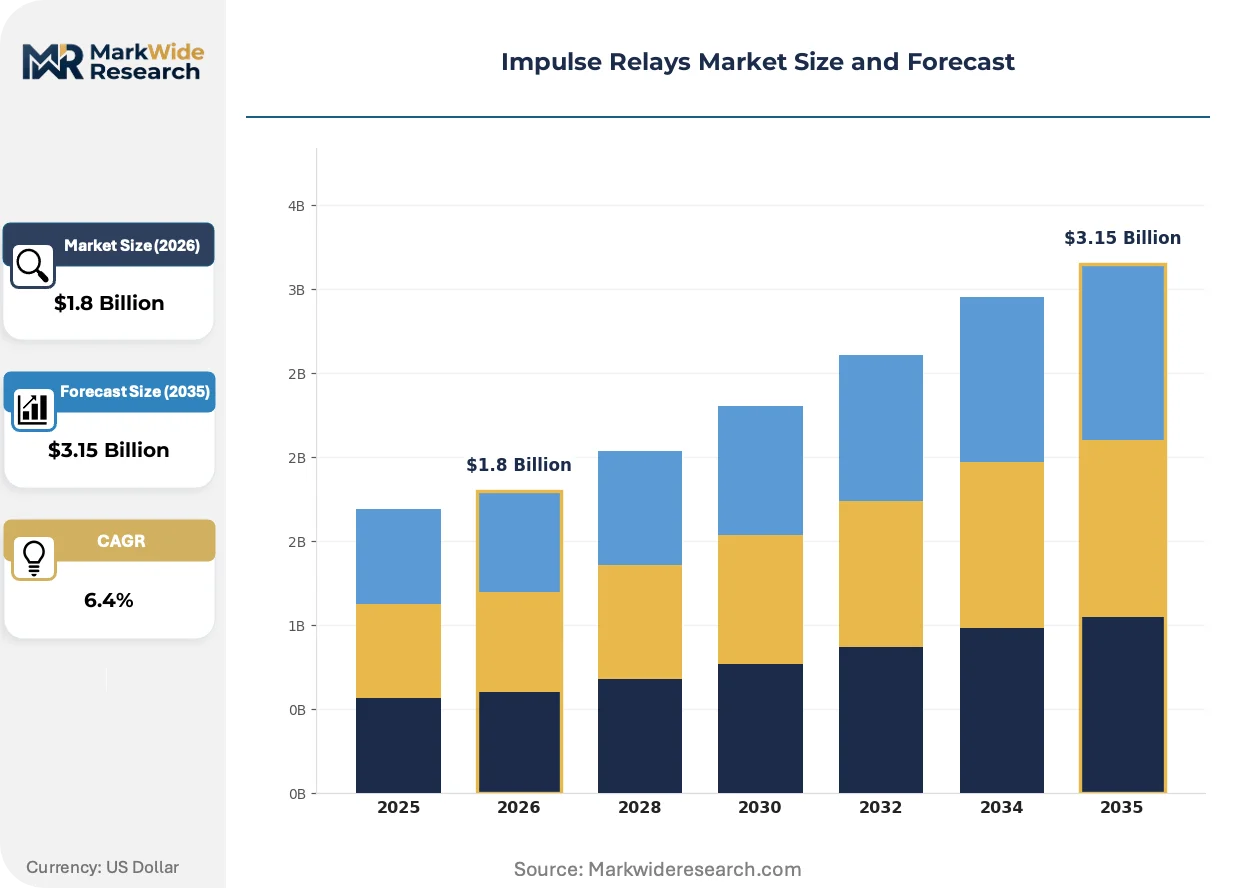
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Solid State, Hybrid, CMOS End User: Automotive OEMs, Industrial Automation, Home Appliances, Telecommunications Technology: Relay Control, Power Management, Circuit Protection, Signal Conditioning Application: Motor Control, Lighting Control, Safety Systems, Consumer Electronics |
| Companies Covered | Siemens AG, Schneider Electric, Omron Corporation, TE Connectivity, ABB Group, Eaton Corporation, Mitsubishi Electric Corporation, Panasonic Corporation, Fuji Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impulse Relays Market Evolving Landscape
Digital control architectures are compressing replacement cycles as buyers prioritize semiconductor endurance over mechanical longevity in critical automation infrastructure.
Hybrid relay technology is hybridizing electromechanical robustness with solid-state switching speed in a single package. Food and beverage packaging machinery OEMs are specifying these modules for washdown environments where pure semiconductor devices fail from thermal cycling. This convergence is compressing the traditional segmentation between premium solid-state and economy electromechanical tiers.
REACH substance restrictions are forcing contact material transitions across European supply chains. Manufacturers must eliminate cadmium plating and certain beryllium copper alloys from relay construction, accelerating investment in silver-nickel and gold-flash alternatives. German industrial distributors report inventory rotation toward RoHS-compliant SKUs as procurement departments enforce green sourcing mandates.
Buyer consolidation among systems integrators is reshaping channel economics. Large automation houses in the US Midwest are bypassing traditional electrical distributors to negotiate direct volume agreements with relay manufacturers, extracting price concessions in exchange for sole-source specifications. This disintermediation concentrates purchasing power among a handful of procurement teams at Detroit-area automotive tier-one suppliers.
Impulse Relays Market Segmentation
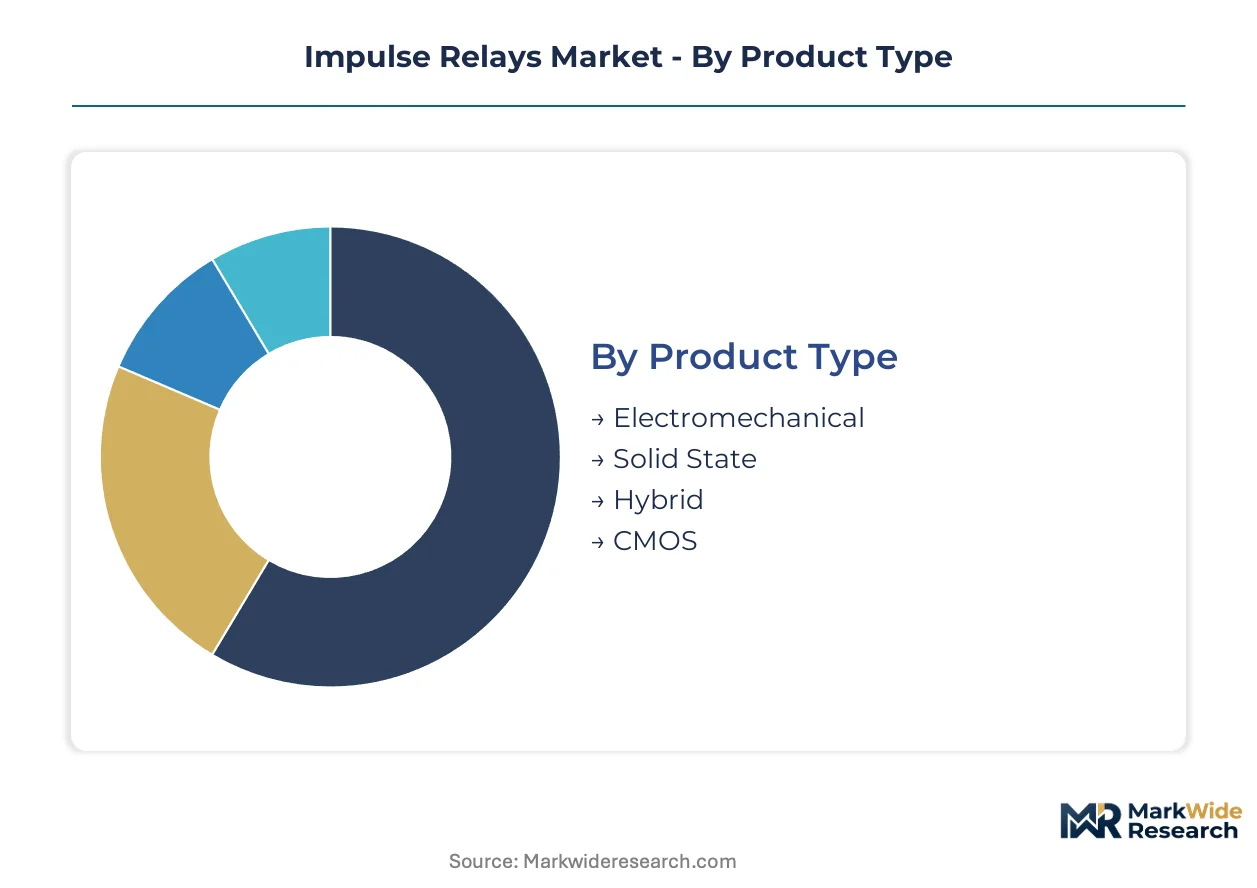
Impulse relay procurement patterns diverge sharply across electrical load requirements, environmental conditions, and switching frequency demands. Buyers calibrate product selection against thermal constraints, arc suppression needs, and legacy system compatibility rather than optimizing on unit cost alone.
Product Type:
Cost tier segmentation separates premium semiconductor-based designs from economy coil-driven alternatives, with hybrid architectures occupying a narrowing middle band.
- Electromechanical:Coil-activated mechanical contacts rated for 12V to 230V AC/DC operation dominate lighting control retrofits where procurement teams prioritize legacy compatibility and low capital outlay. German commercial real estate operators specify these modules for building automation upgrades that must interface with existing contactor infrastructure.
- Solid State:Thyristor and MOSFET-based switching eliminates contact arcing and extends operational life beyond ten million cycles. Japanese automotive OEMs source these for robotic assembly lines where millisecond response times and arc-free operation prevent weld spatter contamination in battery pack production.
- Hybrid:Combines electromechanical power handling with solid-state control logic for washdown environments in food processing machinery. Italian packaging equipment manufacturers specify these for thermal cycling resistance where pure semiconductors degrade from condensation exposure.
- CMOS:Sub-miniature relay modules utilizing complementary metal-oxide-semiconductor gates for signal-level switching in consumer electronics. South Korean smartphone component suppliers integrate these for audio circuit routing where board space constraints dominate specification criteria.
The dominant share belongs to electromechanical variants, while solid-state architectures are closing the gap fastest in high-cycle industrial applications.
End User:
Application intensity varies dramatically across customer categories, with factory floor automation demanding tenfold higher switching frequency than residential installations.
- Automotive OEMs:Assembly line conveyor systems and robotic weld controllers require arc suppression and millisecond switching precision. Detroit-area tier-one suppliers negotiate direct volume agreements with relay manufacturers, bypassing traditional electrical distributors to extract sole-source pricing concessions.
- Industrial Automation:Factory floor integration spans motor starters, safety interlocks, and process control loops. German industrial corridor procurement teams enforce REACH-compliant material specifications, rotating inventory toward RoHS-certified SKUs with lead-free contact materials.
- Home Appliances:Washing machine and HVAC control panels utilize economy-grade electromechanical relays for intermittent duty cycles. Chinese white goods manufacturers drive volume procurement with standardized 16A contact ratings and 230V coil configurations.
- Telecommunications:Base station power distribution and data center circuit protection demand signal-grade switching with minimal insertion loss. Indian telecom infrastructure operators specify compact modules for outdoor cabinet installations subject to monsoon humidity exposure.
Industrial automation captures the largest procurement volume, though automotive OEM specifications command the highest per-unit performance premiums.
Technology:
Functional specialization determines margin structure, with power management modules commanding price multiples over basic relay control functions.
- Relay Control:Core latching and impulse logic for remote switching applications where sustained coil energization would generate excessive thermal load. French building automation integrators deploy these for demand-response grid participation in commercial real estate.
- Power Management:Integrated voltage monitoring and load shedding capabilities for critical infrastructure. Brazilian renewable energy developers specify these for photovoltaic string combiner DC isolation where arc-free switching prevents fire hazards.
- Circuit Protection:Overcurrent detection with automatic reset functionality for motor control centers. Australian mining equipment OEMs require these for conveyor system protection in dust-laden environments.
- Signal Conditioning:Noise filtering and galvanic isolation for sensitive measurement circuits. Swiss precision instrumentation manufacturers integrate these for laboratory automation where electromagnetic interference corrupts sensor data acquisition.
Relay control functions anchor baseline demand, while power management capabilities are expanding most quickly in renewable energy integration.
Application:
Environmental severity and duty cycle frequency segment the installed base across radically different reliability requirements.
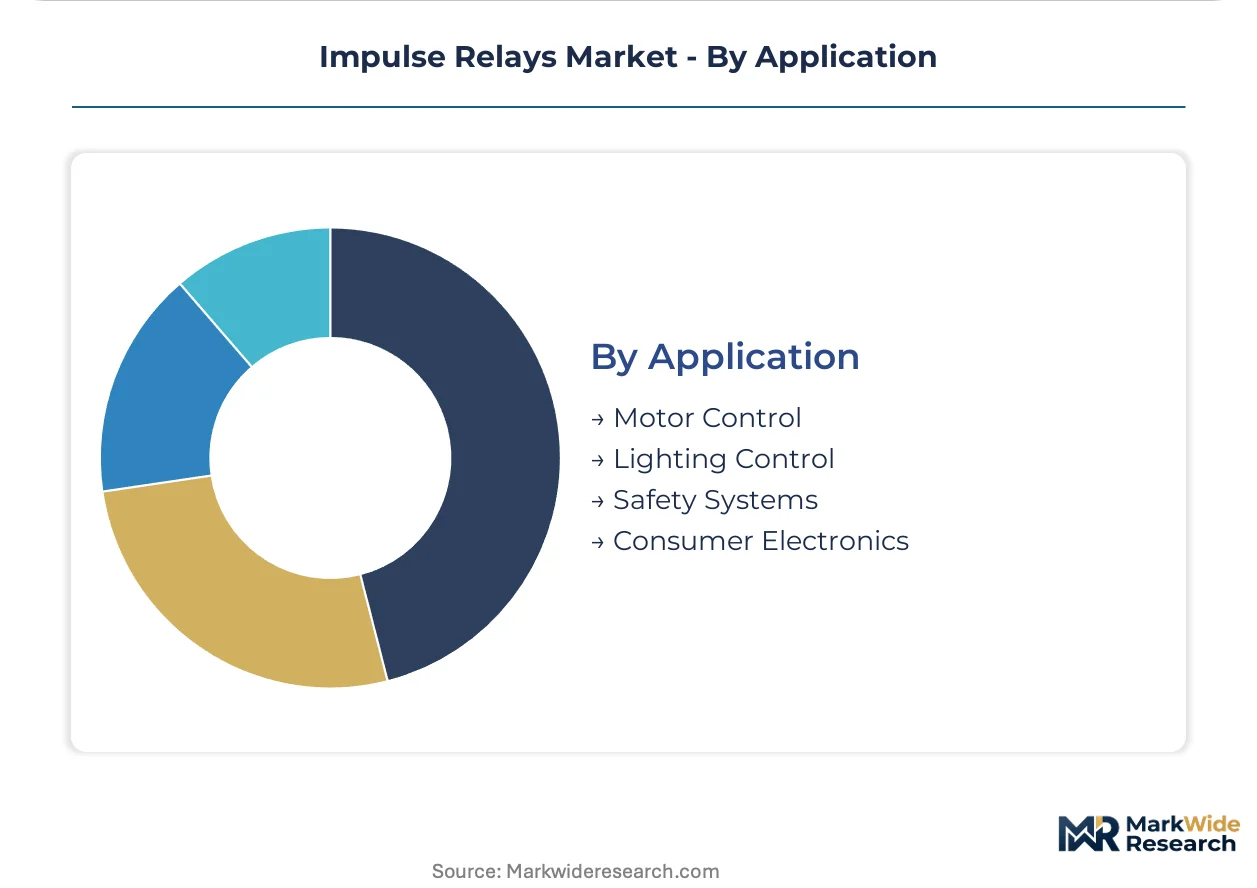
- Motor Control:Three-phase induction motor starting and overload protection in industrial machinery. Spanish automotive stamping plants specify hybrid relays for servo motor drives where electromechanical endurance limits would trigger premature replacement cycles.
- Lighting Control:Commercial and residential illumination switching with legacy compatibility requirements. UK facilities management contractors retrofit compact impulse modules to enable smart building integration without rewiring legacy contactor circuits.
- Safety Systems:Emergency stop circuits and interlock verification with fail-safe redundancy mandates. Canadian oil sands extraction operators require these for process safety shutdown systems subject to CSA hazardous location certification.
- Consumer Electronics:Low-current signal routing in portable devices and home entertainment systems. Taiwanese ODM manufacturers source CMOS variants for laptop docking station power path management.
Motor control applications generate the highest replacement part revenue, while safety systems specifications impose the most stringent certification burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation OEMs export solid-state impulse relay modules to Japanese automotive assembly plants, establishing a trans-Eurasian trade corridor for high-reliability switching components.
Germany
Automotive tier-one suppliers in Stuttgart and Munich source hybrid impulse relays for robotic weld controllers. ECHA REACH compliance mandates eliminate cadmium plating from contact materials, forcing suppliers toward silver-nickel alternatives. The Baden-Württemberg industrial corridor concentrates procurement teams enforcing RoHS-certified SKU rotation.
Japan
Automotive battery pack manufacturers in Nagoya require millisecond switching speeds to prevent weld spatter contamination. METI JIS reliability metrics favor solid-state architectures in motor control applications. The Chubu region hosts CMOS relay specialists supplying compact modules for electronics OEMs.
United States
Detroit-area automotive integrators negotiate direct volume agreements bypassing electrical distributors. FCC electromagnetic emissions frameworks govern relay-integrated equipment certification. The Midwest automation belt concentrates demand for safety interlock systems in conveyor applications.
China
White goods manufacturers in Guangdong drive volume procurement of economy-grade electromechanical relays. MIIT GB standards constrain hazardous substance content in domestic production. The Pearl River Delta hosts foundry capacity for solid-state relay semiconductor fabrication.
Italy
Food packaging machinery OEMs in Emilia-Romagna specify hybrid relays for washdown thermal cycling resistance. CE marking requirements constrain hazardous substance thresholds for European market access. The Bologna industrial district concentrates procurement for conveyor system retrofits.
Impulse Relays Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base spans consolidated electrical conglomerates with captive distribution networks alongside focused relay specialists serving single industries. Three archetypes dominate: vertically integrated automation houses, semiconductor-forward solid-state specialists, and legacy electromechanical fabricators. Competitive moves concentrate on backward integration into semiconductor foundry relationships and geographic expansion through distributor acquisition.
Among Germany-based industrial conglomerates, Siemens AG and ABB Group exemplify channel-controlling archetypes with captive automation demand. Japanese specialists Omron Corporation and Panasonic Corporation occupy positions within the compact CMOS relay tier for electronics OEMs. Schneider Electric anchors European distribution breadth across electromechanical and hybrid product lines.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric |
| Omron Corporation |
| TE Connectivity |
| ABB Group |
| Eaton Corporation |
| Mitsubishi Electric Corporation |
| Panasonic Corporation |
| Fuji Electric |
| Others |
Value Network & Pricing Analysis
Silver and copper foundry concentration in China and Mexico feeds directly into margin pools at German and Japanese relay manufacturers, where precious metal contact costs constitute the dominant variable in unit economics. Electromechanical variants absorb commodity swings through volume scaling, while solid-state producers pass semiconductor wafer premiums to automation buyers.
Pricing Analysis
Current-generation solid-state impulse relays command price multiples over prior-generation electromechanical coil designs, while next-generation hybrid architectures occupy a narrowing mid-band. Three-tier pricing structure across premium solid-state, standard hybrid, and economy electromechanical levels reflects certification grade differentiation and volume scale. Cost compression in the electromechanical tier is intensifying because Chinese white goods manufacturers enforce standardized 16A contact specifications. Chinese home appliance OEMs exhibit highest price sensitivity; Japanese automotive battery pack manufacturers show least sensitivity due to arc-free switching requirements.
Supply Chain Analysis
Silver-nickel contact alloys and copper coil windings draw from concentrated refining capacity in China, Chile, and Peru. Thyristor and MOSFET semiconductor fabrication rests on wafer foundry output from Taiwan, South Korea, and the Pearl River Delta. Single-source vulnerability to geopolitical trade friction concentrates risk at the semiconductor tier. Distribution runs through captive channels of vertically integrated automation houses alongside independent electrical distributors serving retrofit contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket firmware updates and predictive maintenance subscriptions for solid-state relay modules expand faster than hardware replacement cycles, creating recurring revenue attachment opportunities for component suppliers.
For Market Incumbents: Build captive semiconductor foundry relationships as a procurement moat against wafer allocation volatility. Secure long-term silver and copper offtake agreements to hedge precious metal contact cost swings. Deepen backward integration into lead-free contact material processing to preempt REACH compliance disruptions. For New Entrants and Emerging Players: Establish a beachhead in European building automation retrofit segments where legacy contactor compatibility requirements favor hybrid relay specifications. Target Italian food packaging machinery OEMs seeking washdown thermal cycling resistance unavailable from pure semiconductor alternatives. Pursue direct volume agreements with Midwest US automotive integrators bypassing traditional distributor markups. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electromechanical specialists lacking solid-state firmware development capabilities. Five-to-ten year viability favors manufacturers with hybrid technology pipelines bridging mechanical endurance and semiconductor speed. Watch for inflection when Japanese automotive OEMs mandate solid-state switching in new battery platform specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Foundry Partnership | Secures wafer allocation priority for solid-state relay fabrication against capacity constraints. |
| REACH-Compliant Material Transition | Eliminates cadmium and beryllium copper from contact construction for European market access. |
| Hybrid Relay Platform Launch | Captures food packaging washdown applications where pure semiconductors fail from condensation. |
| Direct Distribution Channel | Bypasses electrical distributor margins through volume agreements with Detroit automotive integrators. |
| Firmware-as-a-Service Development | Attaches recurring revenue for predictive maintenance and switching parameter optimization. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of IEC certification databases, ECHA substance restriction filings, and semiconductor trade flow records. Plant engineers at German automotive tier-one suppliers, procurement leads at Japanese battery manufacturers, and aftermarket service heads at Italian packaging OEMs provided operational validation. Customs data from China and Mexico, SEC filings of listed electrical conglomerates, and METI JIS standard documentation furnished external triangulation. Bottom-up unit demand estimates and top-down industrial automation spend analysis were cross-referenced for convergence.
Forecast inputs span product type segmentation across electromechanical, solid-state, hybrid, and CMOS architectures; end-use intensity from residential appliances to factory automation; and technology functional specialization from basic relay control to integrated power management. CAGRs were derived from segment-level growth rate reconciliation against macro industrial capital expenditure patterns. Semiconductor migration timelines and electromechanical replacement cycle data informed technology transition assumptions across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles and precious metal commodity prices would shift the trajectory. Forecasts reflect documented assumptions regarding REACH enforcement stringency and solid-state cost parity achievement. Cross-checking against IHS Markit industrial automation equipment forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Europe PCB Market
Electronic Components
AC Adapter Market
Electronic Components
Audio Amplifier Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
Gas Discharge Tube Market
Electronic Components
PTC Resettable Device Market
Electronic Components
Distribution Components Market
Electronic Components
Electronic Wipe Market
Electronic Components
Docking Station Market
Electronic Components
US Supercapacitor Market
Electronic Components
Electromechanical Timers Market
Electronic Components
Data Bus Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
Low-Dropout (LDO) Regulator Market
Electronic Components
Plastics in Consumer Electronics Market
Electronic Components
Capacitor Aluminum Polymer Market