
 Power Resistor Market | 2026-2036
Power Resistor Market Size, Share, and Industry Trends Forecast 2026-2036
Power Resistor Market Analysis
REACH compliance is pivoting the cost-of-entry calculus for power resistor suppliers serving European industrial markets. Vishay Intertechnology leverages its broad thin-film portfolio to sustain certification across multiple material categories. KOA Corporation anchors its competitive stance through specialized thick-film expertise in automotive-grade current sensing. Bourns Inc. differentiates via integrated manufacturing that controls ceramic substrate supply for high-temperature applications.
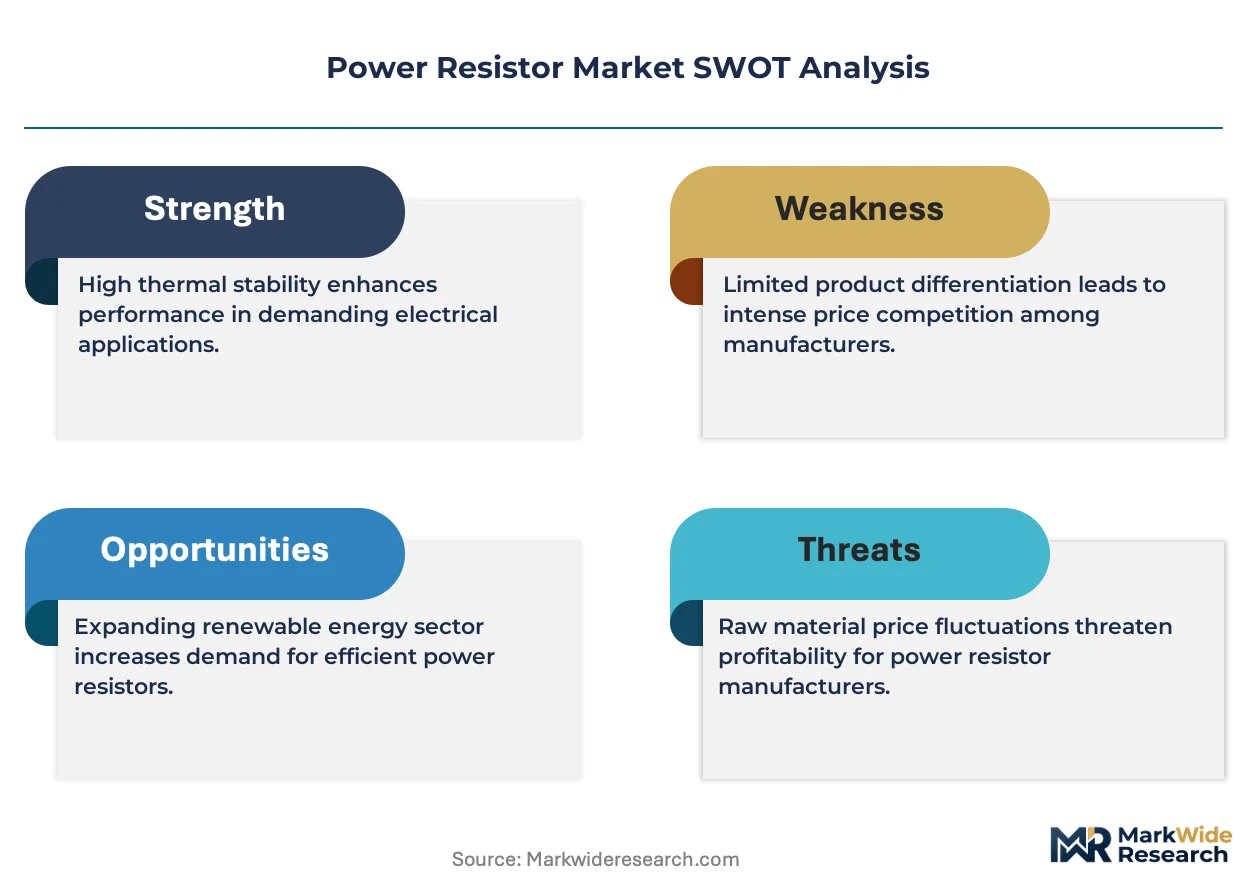
A power resistor is a passive electronic component engineered to dissipate substantial electrical energy as heat, typically constructed from resistive wire alloys, metal oxide films, or carbon composite materials and rated for wattages from fractions of a watt to multiple kilowatts. Wirewound constructions dominate high-power industrial segments where tolerance stability under thermal cycling determines system reliability. Metal film variants capture expanding share in precision current-sensing applications for EV inverters and charging infrastructure. Thick film technology leads cost-sensitive consumer electronics volume, though margin pools concentrate in automotive-qualified surface-mount formats.
The EPA governs hazardous substance restrictions affecting resistor coatings and termination materials in US-bound products, while the EU Green Deal and RoHS directives enforce substance phase-outs that reshape supplier qualification requirements. Japan's METI energy-efficiency standards for industrial equipment indirectly drive demand for low-loss resistive elements in motor drives and power converters. Stakeholders must monitor evolving material compliance thresholds and decide whether captive ceramic processing or qualified second-source agreements offer stronger protection against supply interruption.
Market Dynamics
Drivetrain electrification is compressing design cycles for thermal management components as EV powertrain manufacturers demand precision current-sensing resistors with tighter tolerance bands and higher operating temperatures.
Growth Catalysts
- EU F-Gas Regulation:Tightening material specifications for fluorinated gases used in thermal management systems are forcing industrial equipment makers to redesign heat-dissipation architectures, directly expanding demand for high-wattage wirewound resistors with improved thermal cycling stability.
- Machine builders in Germany's industrial automation corridor:Motor control system integrators are specifying elevated power ratings and customized termination configurations, creating sustained pull for application-engineered resistor assemblies.
- Thick-film surface-mount formats:Automotive-qualified thick-film technology is capturing volume in EV inverter and charging infrastructure deployments where space constraints and automated assembly requirements dominate procurement criteria.
Market Restraints
- Nickel-chromium alloy supply concentration:Resistive wire production clusters in select East Asian metallurgical centers, exposing procurement timelines to concentrate logistics disruptions and alloying element price volatility.
- REACH substance restrictions:ECHA's expanding candidate list of substances of very high concern is disqualifying legacy coating chemistries and termination platings, forcing reformulation investments before market access.
- Ceramic substrate sourcing bottlenecks:High-purity alumina supply for high-temperature applications concentrates among limited qualified suppliers, constraining capacity expansion for automotive-grade current-sensing products.
Strategic Opportunities
- India's industrial motor drive sector:BIS certification requirements and domestic manufacturing incentives under the PLI scheme are creating localized demand for wirewound power resistors in variable-frequency drive installations.
- Silicon carbide inverter integration:Wide-bandgap semiconductor adoption in next-generation EV power electronics is expanding into higher switching frequencies, requiring precision current-sensing resistors with reduced parasitic inductance and improved pulse-load tolerance.
- Direct OEM contracting:Tier-1 automotive suppliers are bypassing traditional distribution channels for high-volume resistor programs, enabling margin capture through application-specific co-development agreements.
Industry Challenges
- AEC-Q200 qualification timelines:Extended stress-test protocols for automotive passive components compress product launch windows and tie up engineering resources across multiple temperature-grade iterations.
- Legacy system integration:Industrial retrofit projects require mechanical and electrical compatibility with decades-old resistor footprints, constraining form-factor innovation and forcing dual-generation product maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Resistor Market |
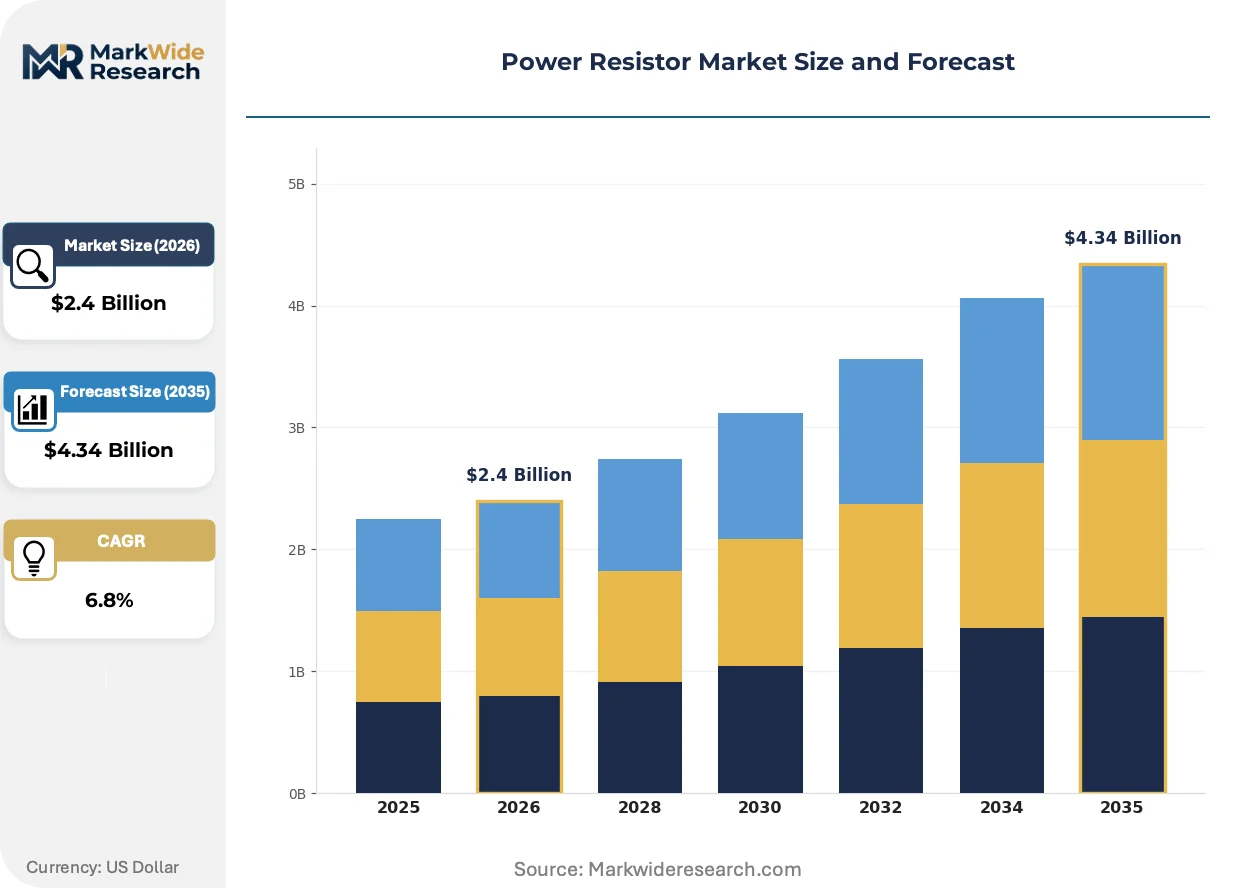
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Wirewound, Metal Film, Carbon Film, Thick Film Application: Power Conversion, Current Sensing, Load Testing, Dynamic Braking End User: Consumer Electronics, Automotive, Industrial Machinery, Renewable Energy Packaging Type: Surface Mount, Through Hole, Axial, Radial |
| Companies Covered | KOA Corporation, Panasonic Corporation, Vishay Intertechnology, TE Connectivity, Yageo Corporation, Bourns Inc., Murata Manufacturing, Stackpole Electronics Inc., Ohmite Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Resistor Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are simultaneously enabling new performance tiers and disqualifying incumbent manufacturing processes across the power resistor value chain.
Metal film technology is expanding into precision current-sensing applications for EV inverters and charging infrastructure. Tier-1 automotive suppliers are adopting thin-film resistors with TCR ratings below 50 ppm/°C for battery management systems. This precision requirement is expanding into adjacent industrial segments where energy metering accuracy standards are tightening.
REACH and RoHS substance phase-outs are reshaping termination metallurgy and protective coating formulations across European-bound production. ECHA's restriction proposals on hexavalent chromium and certain flame retardants are forcing alloy substitutions in wirewound element terminations. Automotive-qualified thick-film manufacturers are responding with nickel-palladium-gold plating systems that maintain solderability under extended thermal aging.
Consolidated procurement by EV powertrain integrators is compressing supplier qualification cycles and elevating technical collaboration requirements. Direct engineering relationships are displacing catalog-based purchasing for high-volume current-sensing programs. This concentration is most visible in Germany's automotive supply corridor, where machine builders now specify resistor performance jointly with inverter semiconductor vendors.
Power Resistor Market Segmentation
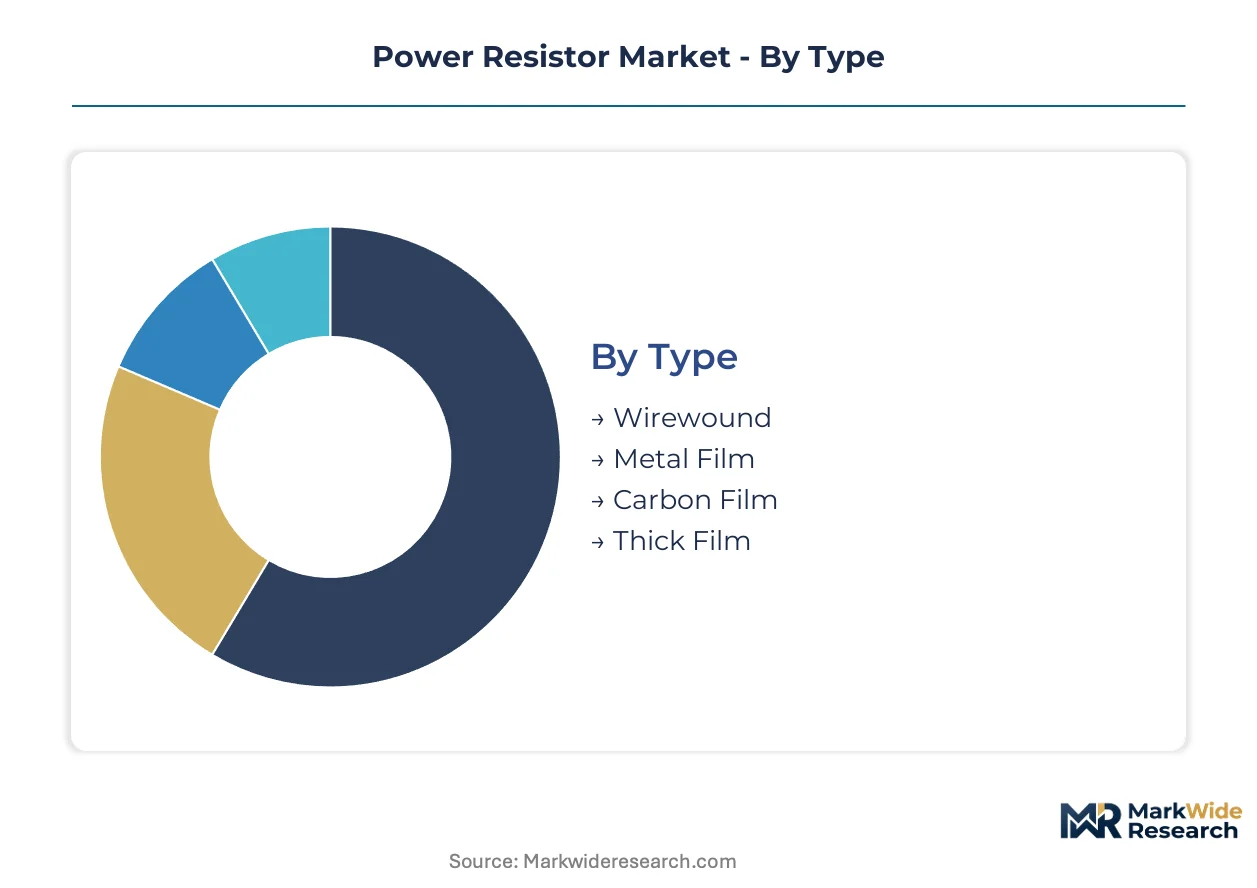
Power resistor procurement patterns diverge sharply across construction methods and mounting formats, with thermal cycling requirements and automated assembly compatibility driving specification splits. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization pressures dominate.
Type:
Equipment refresh cycles and thermal performance upgrades are reshaping technology mix across industrial and automotive installations.
- Wirewound:Precision-wound resistive wire on ceramic cores delivers superior pulse-load tolerance and stability under sustained thermal stress. German machine builders specify these for motor control systems requiring decades of service life under cyclic loading.
- Metal Film:Vacuum-deposited metal layers on cylindrical substrates achieve tight tolerance bands below 50 ppm/°C temperature coefficient. EV battery management system integrators in Germany's automotive corridor are standardizing on these for precision current measurement.
- Carbon Film:Pyrolytic carbon deposition on ceramic rods balances cost against moderate precision for general-purpose industrial applications.
- Thick Film:Screen-printed resistive pastes on alumina substrates dominate cost-sensitive consumer electronics volume.
Wirewound sits at the top of the volume ranking, with Metal Film climbing the fastest.
Application:
Cost tier differentiation separates commodity replacement demand from engineered specification opportunities.
- Power Conversion:Grid-tied inverters and variable-frequency drives require resistors that dissipate switching losses while maintaining stability across input voltage ranges. Renewable energy installations in Germany specify elevated power ratings for solar string inverter braking circuits.
- Current Sensing:Low-ohm precision elements measure current flow without significant power loss. EV powertrain manufacturers specify shunt resistors with Kelvin connections for battery state-of-charge algorithms.
- Load Testing:High-wattage resistive banks simulate electrical loads for generator and power supply validation.
- Dynamic Braking:Dissipative elements convert kinetic energy to heat during motor deceleration, with industrial automation systems requiring customized thermal profiles.
Power Conversion commands the largest installed base, though Current Sensing gains share fastest on electrification trends.
End User:
Customer type determines qualification burden and pricing power, with automotive and industrial buyers extracting very different commercial terms.
- Consumer Electronics:High-volume, low-margin demand for standard thick-film surface-mount units in power supplies and chargers.
- Automotive:AEC-Q200 qualification requirements and zero-defect quality agreements support premium pricing for current-sensing and pre-charge applications.
- Industrial Machinery:Application-engineered wirewound assemblies for motor drives and braking systems, with German automation OEMs driving customized termination specifications.
- Renewable Energy:Grid-scale inverters and energy storage systems require extended temperature range performance and long service life guarantees.
Industrial Machinery represents the largest revenue pool, with Automotive expanding most quickly on EV platform proliferation.
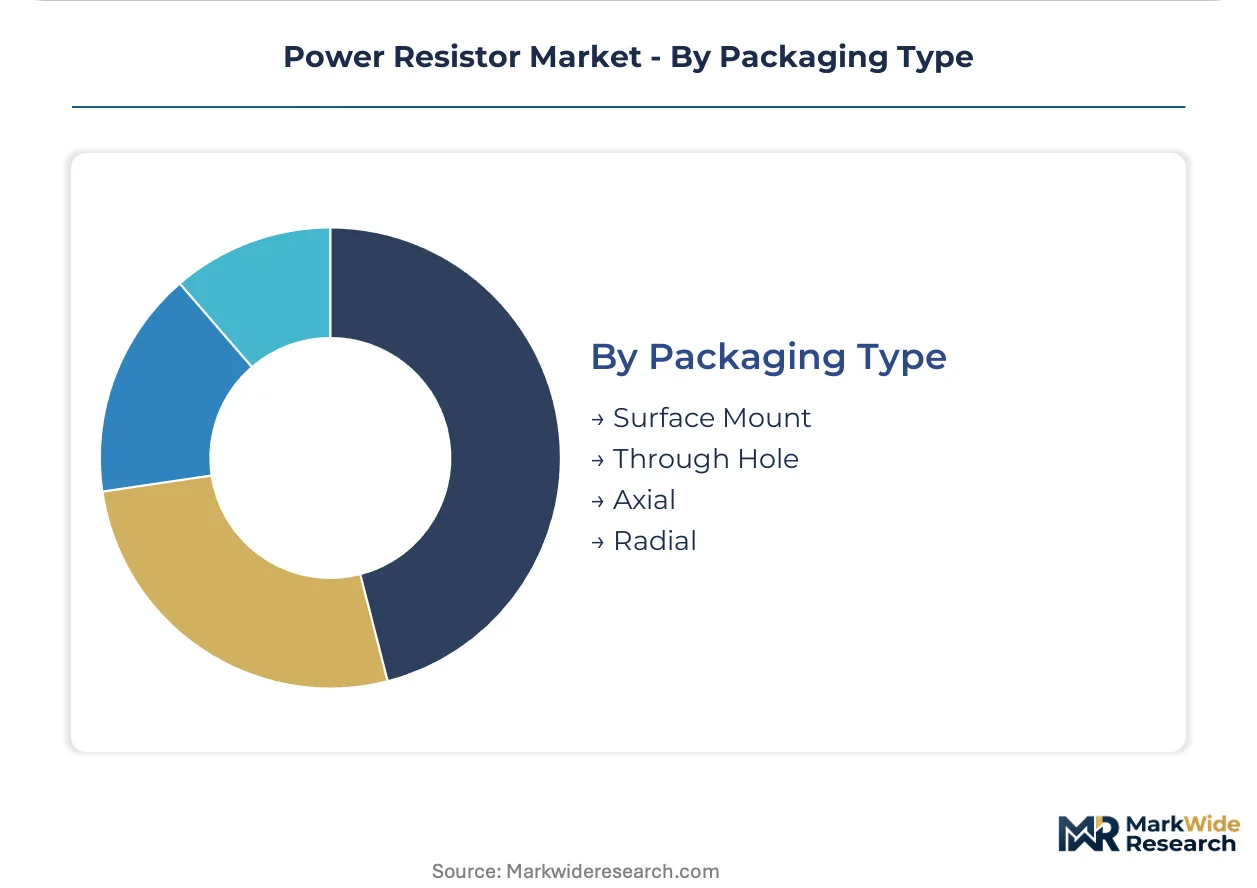
Packaging Type:
Manufacturing process compatibility and thermal management constraints dictate format selection across assembly technologies.
- Surface Mount:Automated pick-and-place assembly compatibility dominates high-volume automotive and consumer electronics production, with thick-film and metal film constructions available in chip formats.
- Through Hole:Mechanical robustness and superior thermal dissipation sustain demand for industrial equipment requiring field serviceability.
- Axial:Cylindrical leaded formats with leads extending from opposite ends persist in legacy industrial designs and high-voltage applications.
- Radial:Leads emerging from a common side facilitate vertical mounting density in space-constrained power supply designs.
Surface Mount leads absolute unit volume, with Through Hole retaining pricing power in industrial replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in precision electronics manufacturing anchor regional demand clusters. Metallurgical expertise and automotive supply chain density determine where specification-grade procurement concentrates.
Germany
Machine builders in the Baden-Württemberg automation corridor specify high-wattage wirewound resistors for motor control systems. The EU F-Gas Regulation tightens thermal management material specifications, forcing equipment redesigns. Stuttgart-based drivetrain integrators co-develop precision current-sensing components with resistor manufacturers.
United States
EPA hazardous substance restrictions reshape coating and termination material choices for industrial equipment exports. The Inflation Reduction Act accelerates domestic EV battery plant construction, expanding demand for automotive-qualified current-sensing resistors. Michigan and Texas host expanding power electronics manufacturing clusters.
China
MIIT energy-efficiency standards for industrial motor drives elevate demand for low-loss resistive elements. GB standards compliance requirements filter supplier qualification for grid-tied inverter installations. The Yangtze River Delta concentrates thick-film surface-mount production for consumer electronics and automotive applications.
Japan
METI industrial equipment efficiency mandates indirectly drive precision resistor specification in variable-frequency drives. JIS standards certification remains mandatory for automotive supplier qualification. The Chubu region around Nagoya anchors automotive electronics manufacturing with integrated passive component supply chains.
India
BIS certification requirements and PLI scheme incentives localize demand for wirewound power resistors in industrial motor drive installations. CEA grid code compliance for renewable energy inverters specifies extended temperature range components. Gujarat and Maharashtra host expanding variable-frequency drive manufacturing facilities.
Power Resistor Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers. The market structure fragments between mass-market thick-film producers and precision thin-film specialists serving automotive qualification requirements. Three archetypes dominate: integrated materials-to-components manufacturers controlling ceramic substrate supply, precision thin-film specialists leveraging vacuum deposition expertise, and high-volume thick-film houses optimizing automated assembly compatibility. Capacity expansion and direct OEM contracting represent the dominant competitive moves as EV procurement concentrates.
Within the precision thin-film tier, Vishay Intertechnology and KOA Corporation exemplify divergent strategic positioning. Vishay leverages broad portfolio breadth across multiple material categories to sustain regulatory compliance. KOA anchors its stance through specialized expertise in automotive-grade current sensing. Bourns Inc. occupies a distinct position via integrated manufacturing that controls ceramic substrate supply for high-temperature applications. Among Japanese manufacturers, Panasonic Corporation and Murata Manufacturing sit within diversified electronics conglomerates where resistor production benefits from shared metallurgical and ceramic processing capabilities. Yageo Corporation represents scale-driven consolidation in thick-film surface-mount formats.
| Leading Market Players |
|---|
| KOA Corporation |
| Panasonic Corporation |
| Vishay Intertechnology |
| TE Connectivity |
| Yageo Corporation |
| Bourns Inc. |
| Murata Manufacturing |
| Stackpole Electronics Inc. |
| Ohmite Manufacturing Company |
| Others |
Supply Flow & Price Mechanics
Nickel-chromium alloy spot indices on the London Metal Exchange cascade through resistor manufacturing cost structures, amplifying margin compression for wirewound producers while thick-film houses absorb ceramic substrate volatility through longer-term offtake agreements. Automotive-grade current-sensing programs command premium pricing tiers that offset raw material swings, whereas industrial replacement demand shows acute sensitivity to alloy price spikes.
Pricing Analysis
Component-plus-engineering-service bundling separates precision current-sensing programs from catalog resistor sales, with EV powertrain manufacturers paying for application-specific co-development and AEC-Q200 qualification support. Price differentiation hinges on temperature coefficient grade and REACH-compliant termination metallurgy, with sub-50 ppm/°C thin-film units capturing 3-4x markup over standard thick-film equivalents. Cost compression in consumer-grade thick-film segments is intensifying as Chinese surface-mount houses expand automated capacity. Machine builders in Germany's automation corridor demonstrate lowest price sensitivity due to total-cost-of-ownership procurement frameworks.
Supply Chain Analysis
Single-source vulnerability sits with high-purity alumina ceramic substrate production concentrated among Japanese and German specialty ceramics manufacturers. Resistive wire feedstock draws from East Asian metallurgical centers in China and Japan, with nickel-chromium and copper-manganese alloy supply resting on concentrated alloying element processing. Tariff exposure on ceramic substrates imported into the European Union creates margin risk for wirewound assemblers lacking qualified second-source agreements. Distribution runs through authorized distributors for automotive qualification programs, while industrial volumes flow via direct OEM contracting and specialized electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power resistor market reads as a late-cycle quality story where precision current-sensing specifications for silicon carbide EV inverters displace commodity thick-film volume. Specification-grade procurement concentrates margin pools with manufacturers sustaining AEC-Q200 qualification breadth.
For Market Incumbents: Acquire ceramic substrate processing capabilities to secure high-temperature wirewound supply continuity against alumina sourcing bottlenecks. Incumbent suppliers must expand thick-film automotive qualification portfolios before REACH substance restrictions disqualify legacy coating chemistries. Backward integration into resistive wire alloying mitigates nickel-chromium price volatility exposure from East Asian metallurgical concentration. For New Entrants and Emerging Players: Direct OEM engineering engagement via specialized application teams offers the most penetrable route around entrenched distribution relationships. India's PLI-backed industrial motor drive sector presents white-space opportunity for BIS-certified wirewound producers. Target silicon carbide inverter integration programs with Kelvin-connected shunt designs that reduce parasitic inductance. For Investors and Strategic Acquirers: Asymmetric upside sits with precision thin-film specialists holding vacuum deposition expertise and automotive qualification infrastructure. Long-term viability over a multi-year window favors manufacturers with captive ceramic processing and direct Tier-1 contracting relationships. Watch silicon carbide inverter penetration rates in EV platforms as the signal indicating precision current-sensing demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrate Production | Captive alumina supply insulates automotive-grade current-sensing programs from qualified-supplier bottlenecks. |
| AEC-Q200 Qualification Expansion | Broad temperature-grade certification opens EV battery management and charging infrastructure procurement channels. |
| Direct OEM Engineering Partnership | Co-development agreements with Stuttgart-based drivetrain integrators displace catalog-based purchasing concentration. |
| REACH-Compliant Metallurgy Transition | Nickel-palladium-gold plating systems maintain solderability under extended thermal aging for European-bound production. |
| Silicon Carbide Inverter Design Collaboration | Kelvin-connected low-inductance shunt development aligns with wide-bandgap semiconductor switching frequency demands. |
Methodological Framework
Coverage spans Germany, the United States, China, Japan, and India, with primary inputs from each market informing demand segmentation and competitive positioning assessments. The analysis combines structured interviews with power electronics procurement managers, automotive Tier-1 supplier quality engineers, and industrial automation OEM specification leads with secondary validation from EPA hazardous substance filings, ECHA REACH candidate list updates, MIIT energy-efficiency standard disclosures, and METI industrial equipment efficiency mandates. Bottom-up resistor shipment estimates triangulate against top-down power electronics equipment production forecasts.
Rate-of-change decomposition separates volume growth from mix-shift and pricing trajectory across the projection horizon. The analytical framework models construction type, application function, end-user industry, and packaging format segmentation dimensions alongside regional regulatory compliance tier as a cross-cutting qualifier. CAGRs derive from equipment production elasticities and content-per-unit assumptions for EV inverters, industrial motor drives, and renewable energy installations.
Alloy price volatility, REACH substance restriction expansion, and silicon carbide inverter adoption pacing are the dominant revision risks to forecast assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
2D Electronics Market
Electronic Components
Global Capacitive Stylus Market
Electronic Components
Flash Charger Adapter Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
Film Capacitor Market
Electronic Components
Data Acquisition Hardware Market
Electronic Components
High-Voltage Interlock Loop Wiring Components Market
Electronic Components
Audio CODEC Market
Electronic Components
Single Layer Capacitors Market
Electronic Components
Wearable Display Device Materials Market
Electronic Components
Chip Shield Market
Electronic Components
High Density Interconnect (HDI) PCB Market
Electronic Components
Timing Relay Market
Electronic Components
Conductive Polymer Capacitor Market
Electronic Components
Coaxial Attenuators Market
Electronic Components
Electronic Wipe Market