
 Structural Electronics Market | 2026-2036
Structural Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Structural Electronics Market Analysis
Market Overview
Modularization of sensor-electronics-mechanical assemblies is expanding buyer choice across automotive and aerospace procurement. Panasonic Corporation leverages its materials science depth to anchor positions in conductive film substrates. TactoTek Oy specializes in injection-molded structural electronics for curved automotive surfaces. Continental Aktiengesellschaft competes on manufacturing scale for integrated control modules.
Structural electronics embed active and passive electronic functions within load-bearing mechanical structures, typically combining conductive traces, sensors, and actuators in polymer, metal, or composite substrates manufactured through additive or subtractive processes. These systems eliminate separate circuit boards and housings, reducing mass by 30-70% in weight-critical applications. Printed electronics currently leads product-type margins due to established roll-to-roll infrastructure, while embedded sensors represents the fastest-growing application category driven by structural health monitoring mandates in aerospace and civil infrastructure. Flexible circuits maintain mature positions in consumer wearables where bend radius specifications below 5mm dominate design requirements.
EU REACH restrictions on halogenated compounds and the F-Gas Regulation reshape material selection for substrate manufacturing across Europe. The FAA certifies structural electronic systems in commercial aircraft under updated special conditions for non-traditional architectures. Stakeholders must monitor evolving flammability standards from ECHA and the FAA as these determine market access timelines for next-generation integrated structures.
Market Dynamics
REACH substance restrictions and FAA certification requirements for non-traditional architectures are forcing simultaneous material migration and compliance pathway reinvention across substrate manufacturing.
Growth Catalysts
- Automotive battery enclosure integration:German OEMs embed structural electronics into chassis components to reduce wiring mass and assembly steps in electric vehicle platforms.
- REACH halogenated compound phase-out:European manufacturers accelerate substrate reformulation toward phosphorus-nitrogen flame retardant systems ahead of 2026 enforcement milestones.
- Additive manufacturing convergence:Aerosol jet and selective laser sintering processes enable conformal antenna and sensor integration into load-bearing composite structures.
Market Restraints
- Conductive polymer feedstock concentration:Specialty resin supply concentrates among Japanese and German chemical producers, exposing buyers to allocation risk during demand spikes.
- FAA special conditions timeline:Certification of non-traditional electronic architectures requires case-by-case validation, extending commercial aircraft program schedules by 18-36 months.
- Copper trace reliability thresholds:Thermal cycling performance of embedded conductors in polymer substrates remains below traditional PCB benchmarks for high-current applications.
Strategic Opportunities
- Civil infrastructure health monitoring:Bridge and wind turbine operators in the United States and Germany deploy embedded strain sensors to replace manual inspection cycles.
- Medical device form factor convergence:Wearable diagnostic platforms integrate load-bearing electronics to eliminate rigid circuit boards against curved anatomical surfaces.
- EU Green Deal manufacturing incentives:Battery passport requirements and carbon border adjustments favor localized structural electronics production for automotive supply chains.
Industry Challenges
- Multiphysics simulation talent scarcity:Design of structural electronics requires simultaneous thermal, mechanical, and electromagnetic modeling capabilities rarely found in single engineering teams.
- Legacy avionics integration friction:ARINC 429 and MIL-STD-1553 data bus architectures resist seamless incorporation of distributed structural sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Structural Electronics Market |
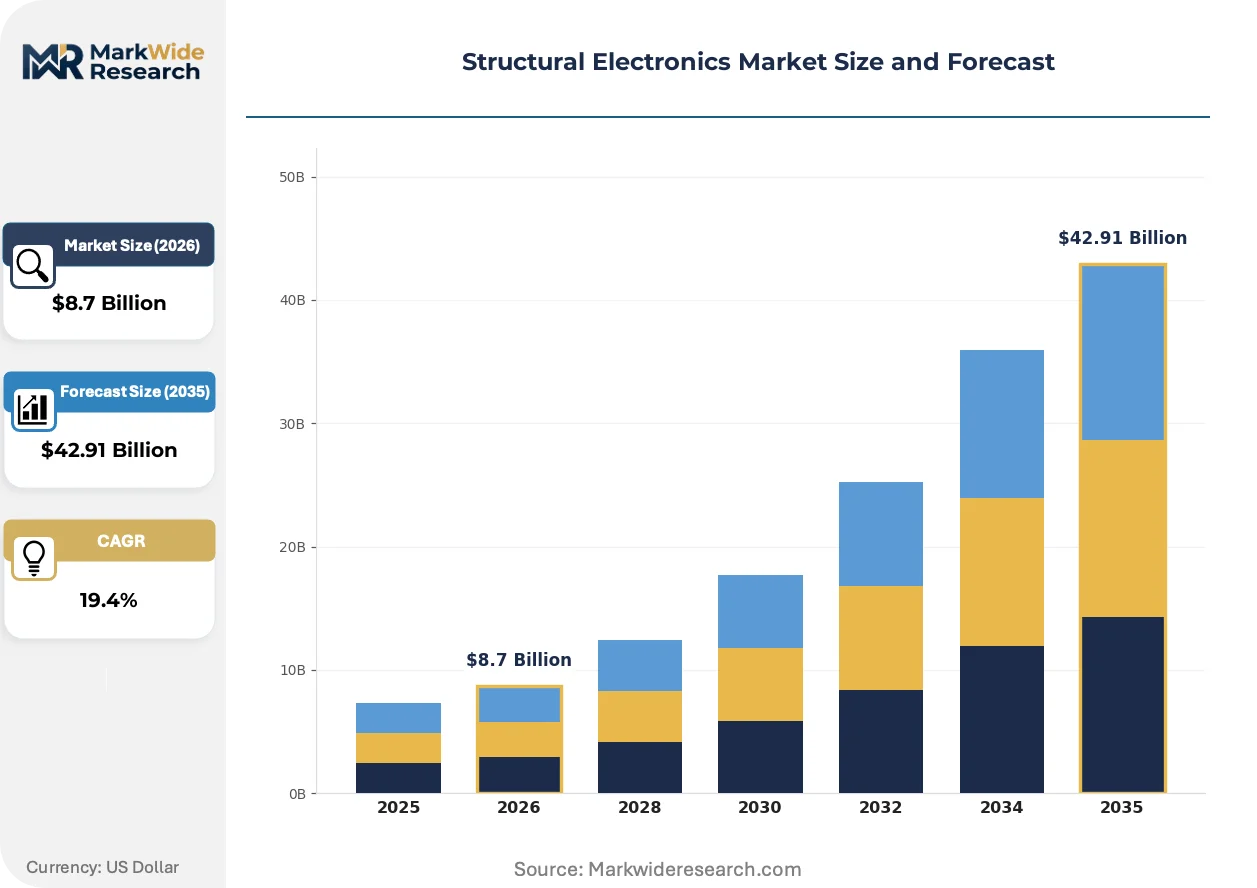
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Circuits, Printed Electronics, Embedded Sensors, Conductive Adhesives Application: Consumer Electronics, Automotive Components, Aerospace Structures, Medical Devices End User: OEMs, Tier-1 Suppliers, Design Engineers, Research Institutions Technology: 3D Printing, Laser Annealing, Nanoimprinting, Roll-to-Roll Processing |
| Companies Covered | TactoTek Oy, Panasonic Corporation, Canatu Oy, Neotech AMT GmbH, Pulse Electronics, The Boeing Company, Continental Aktiengesellschaft, Optomec Inc., Heraeus Holding GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Structural Electronics Market Emerging Trajectories
Material-process convergence and regulatory-driven substrate reformulation are compressing development cycles while expanding addressable application spaces beyond traditional electronics packaging.
Printed electronics manufacturing is overtaking conventional PCB assembly in weight-critical applications. Roll-to-roll gravure and flexographic deposition systems produce meter-scale conductive patterns on polymer films at throughputs exceeding pick-and-place operations. Aerospace tier-one suppliers now specify printed antenna and heater elements for wing de-icing systems previously served by wired harnesses.
ECHA's evolving flammability standards under REACH are restructuring supply relationships. Substrate manufacturers must demonstrate halogen-free flame retardance through oxygen index and smoke density testing regimes not required for legacy materials. German automotive battery enclosure suppliers have established dedicated compliance laboratories to accelerate material qualification against these protocols.
Sensor-electronics-mechanical procurement is consolidating under systems integrators with in-house structural electronics capabilities. Tier-one suppliers now contract directly for finished battery trays and wing spars rather than sourcing discrete sensors and controllers separately. This pattern concentrates most visibly in Bavaria and Baden-Württemberg, where automotive and aerospace clusters overlap with specialized polymer processing infrastructure.
Structural Electronics Market Segmentation
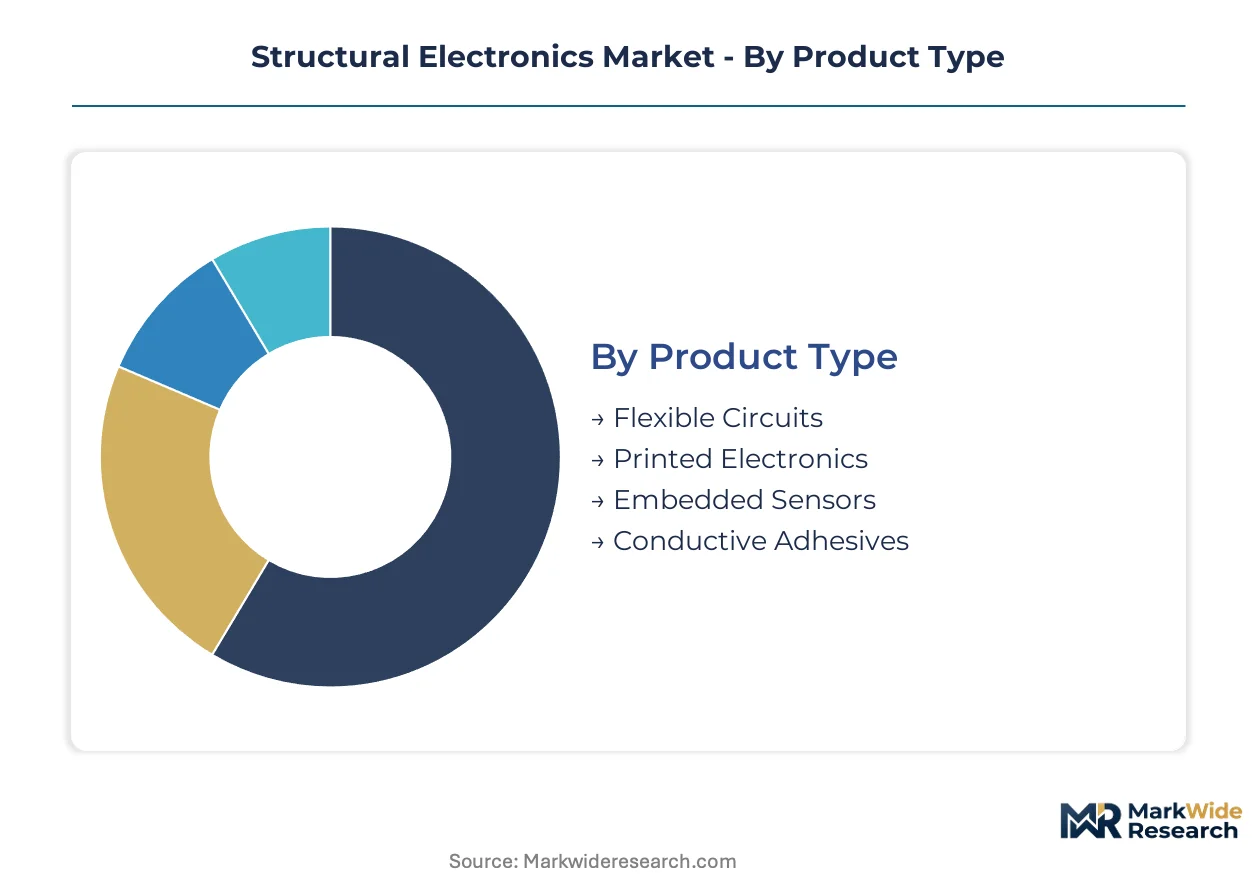
Structural electronics segmentation reveals how manufacturing capabilities and procurement patterns diverge across weight-critical applications. Each dimension—product architecture, use case, buyer type, and fabrication method—carries distinct margin profiles and technical barriers that reshape competitive positioning.
Product Type:
Supply concentration among Japanese and German specialty chemical producers shapes material availability and pricing power across substrate categories.
- Flexible Circuits:Polyimide or liquid crystal polymer substrates with etched copper traces achieve bend radii below 5mm for wearable and foldable device integration. Consumer electronics procurement in South Korea and Taiwan dominates volume, though automotive harness replacement applications in Germany are accelerating qualification cycles.
- Printed Electronics:Roll-to-roll gravure and screen-printed conductive inks on polymer films eliminate subtractive etching steps and reduce material waste. Aerospace de-icing elements and antenna systems in the United States and France specify these for wing structures where mass reduction exceeds 50% against wired alternatives.
- Embedded Sensors:Strain, temperature, and pressure transducers fabricated within load-bearing composites enable structural health monitoring without discrete component mounting. Civil infrastructure operators in Germany and the United States deploy these for bridge and wind turbine condition assessment.
- Conductive Adhesives:Silver-filled epoxy and sintered metal pastes replace soldered interconnects in temperature-sensitive polymer substrates. REACH-compliant formulations from Bavarian chemical suppliers are displacing legacy halogenated systems in European automotive battery enclosures.
Today's leader: Printed Electronics. Tomorrow's challenger: Embedded Sensors.
Application:
End-use margins stratify sharply around certification requirements and production scale, with aerospace commanding premium pricing against consumer volume plays.
- Consumer Electronics:Foldable smartphones and wearable fitness bands drive flexible circuit consumption through specifications demanding 200,000+ bend cycles. Samsung Electronics and Apple Inc. procurement teams in South Korea and California coordinate directly with substrate manufacturers for custom form factors.
- Automotive Components:Battery enclosure heaters, chassis strain sensors, and interior control surfaces integrate structural electronics to reduce wiring mass and assembly labor. BMW Group and Volkswagen AG platforms in Munich and Wolfsburg specify these for electric vehicle architectures.
- Aerospace Structures:Wing spars, fuselage panels, and control surfaces embed de-icing elements and load sensors under FAA special conditions certification. Airbus SE and Boeing Commercial Airplanes programs in Toulouse and Seattle require 18-36 month validation timelines for non-traditional electronic architectures.
- Medical Devices:Conformable diagnostic patches and surgical instruments eliminate rigid circuit boards against curved anatomical surfaces. FDA 510(k) pathways in the United States and MDR compliance in Europe govern biocompatibility and sterilization validation.
Automotive Components capture the steepest expansion trajectory as electric vehicle platforms multiply addressable socket counts per vehicle.
End User:
Procurement authority is migrating upstream as systems integrators internalize structural electronics capabilities previously sourced through tiered supply chains.
- OEMs:Automotive and aerospace original equipment manufacturers establish captive structural electronics design teams to control intellectual property and accelerate platform integration. Vertical integration into substrate manufacturing remains rare due to capital intensity.
- Tier-1 Suppliers:Continental Aktiengesellschaft and Aptiv PLC contract for finished battery trays and wing spars rather than discrete sensors and controllers. Bavarian and Baden-Württemberg manufacturing clusters concentrate these procurement decisions.
- Design Engineers:Product development teams specify structural electronics early in concept phases to optimize mass and packaging constraints. Multiphysics simulation software from Ansys Inc. and Dassault Systèmes SE enables concurrent thermal, mechanical, and electromagnetic modeling.
- Research Institutions:Fraunhofer-Gesellschaft in Germany and MIT Media Lab in the United States advance aerosol jet printing and nanoimprinting process development. Public funding through EU Horizon programs and U.S. Department of Defense research contracts supports technology maturation.
Tier-1 Suppliers currently intermediate the majority of commercial volume. OEM direct sourcing is gaining share fastest as platform architecture decisions centralize.
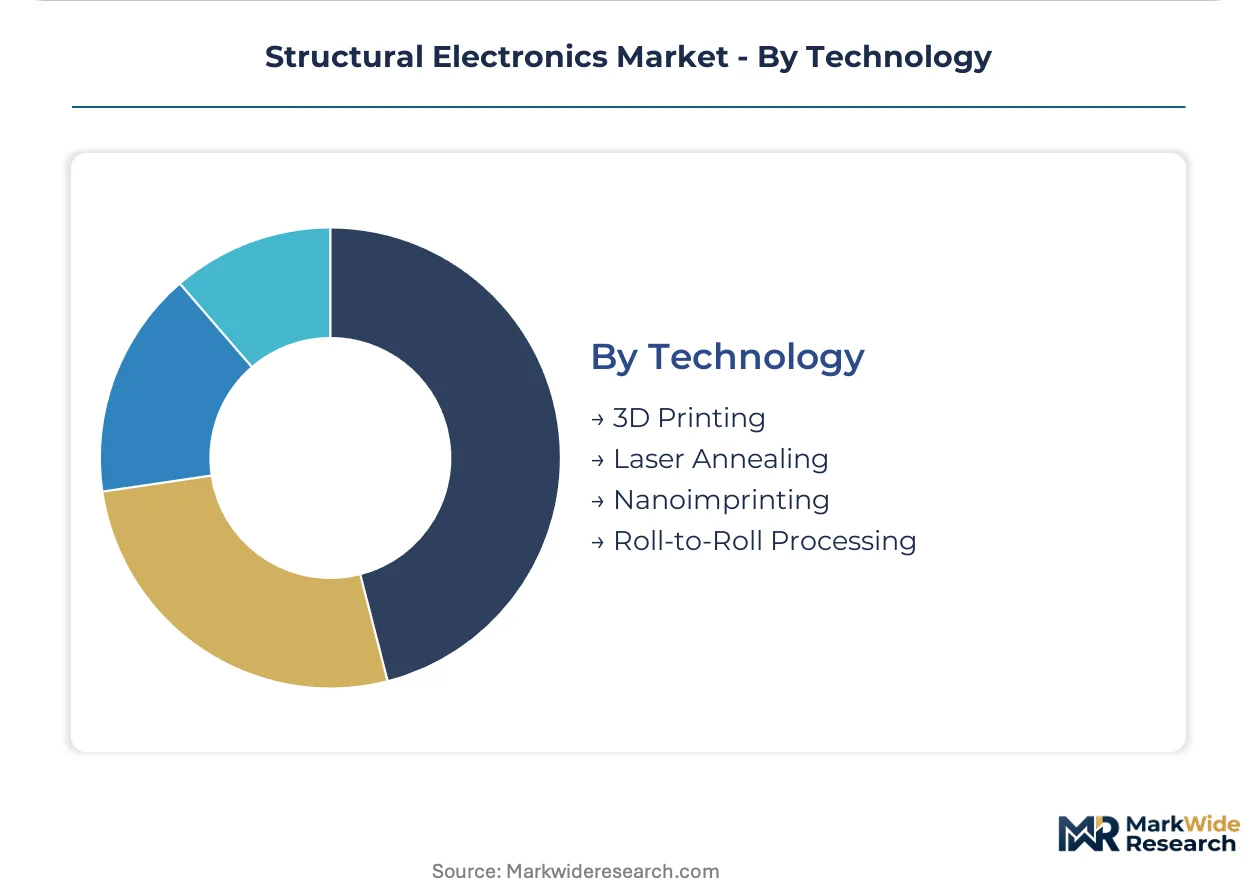
Technology:
Process selection determines substrate compatibility, feature resolution, and throughput economics across application categories.
- 3D Printing:Aerosol jet and material extrusion systems deposit conductive traces onto curved injection-molded surfaces for automotive interior components. TactoTek Oy in Finland specializes in this integration for curved control panels.
- Laser Annealing:Pulsed laser processing converts printed metal oxide patterns into conductive traces without thermal damage to polymer substrates. Feature resolution below 10 micrometers enables fine-pitch interconnects for medical device applications.
- Nanoimprinting:Mechanical patterning of conductive polymers achieves sub-micrometer feature sizes for high-frequency antenna applications. Throughput limitations restrict deployment to specialized aerospace and telecommunications components.
- Roll-to-Roll Processing:Continuous gravure and flexographic deposition on polymer films achieves meter-scale production at throughputs exceeding batch processes. Panasonic Corporation leverages this infrastructure for conductive film substrate supply to consumer electronics manufacturers.
Roll-to-Roll Processing maintains manufacturing scale leadership. 3D Printing is climbing the fastest as conformal integration requirements multiply across automotive and medical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The structural electronics industry traces its commercial origins to Finnish and German automotive prototyping labs in the early 2010s, where injection-molded circuitry first demonstrated viable mass reduction for curved interior surfaces. From these foundations, production networks have crystallized around aerospace certification hubs and battery manufacturing clusters.
United States
FAA special conditions certification for wing-embedded de-icing systems and structural health monitoring mandates drive aerospace demand. The Inflation Reduction Act's clean vehicle tax credits accelerate automotive battery enclosure integration. Seattle-Tacoma and Wichita manufacturing corridors concentrate tier-one supplier engineering for Boeing Commercial Airplanes programs.
Germany
Automotive OEMs embed load-bearing electronics into chassis components and battery trays for electric vehicle platforms. REACH substance restrictions enforce halogenated flame retardant phase-outs ahead of 2026 milestones. Bavarian and Baden-Württemberg clusters host concentrated substrate qualification laboratories serving Continental Aktiengesellschaft and BMW Group procurement.
Japan
Specialty resin feedstock production for conductive polymer substrates concentrates among chemical producers serving Panasonic Corporation's roll-to-roll infrastructure. METI funding for next-generation mobility technologies supports structural electronics process development. Tokyo-Osaka industrial corridors maintain materials science depth for high-temperature substrate formulations.
Finland
TactoTek Oy pioneered injection-molded structural electronics for curved automotive control surfaces, establishing a template for European tier-one supplier adoption. EU Green Deal manufacturing incentives favor localized production for battery passport compliance. Oulu-Tampere technology corridors concentrate aerosol jet printing and 3D-molded circuitry expertise.
South Korea
Samsung Electronics and LG Electronics procurement teams specify flexible circuit substrates for foldable smartphone and wearable fitness band form factors. MFDS biocompatibility pathways govern conformable diagnostic patch development for medical device exports. Seoul-Suwon manufacturing belts achieve 200,000+ bend cycle specifications through direct substrate manufacturer coordination.
Structural Electronics Market Vendor Landscape
The competitive structure tilts toward materials-science conglomerates with captive polymer processing infrastructure. Japanese and German chemical producers dominate specialty resin feedstock supply, while Finnish and German specialists anchor injection-molded structural electronics capabilities. Three archetypes define positioning: roll-to-roll substrate manufacturers, aerosol jet printing specialists, and systems integrators with in-house structural electronics design teams. Capacity expansion and strategic partnerships constitute the dominant competitive moves as tier-one suppliers consolidate procurement under finished component contracts.
Among Finnish specialists, TactoTek Oy exemplifies the injection-molded structural electronics archetype for curved automotive surfaces. Panasonic Corporation represents Japanese conglomerate positioning through materials science depth in conductive film substrates. Continental Aktiengesellschaft occupies the systems integrator tier, competing on manufacturing scale for integrated control modules and battery enclosure assemblies.
| Leading Market Players |
|---|
| TactoTek Oy |
| Panasonic Corporation |
| Canatu Oy |
| Neotech AMT GmbH |
| Pulse Electronics |
| The Boeing Company |
| Continental Aktiengesellschaft |
| Optomec Inc. |
| Heraeus Holding GmbH |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap German chemical specialists anchor specialty resin feedstock production, translating concentrated ownership into disciplined allocation protocols that buffer pricing volatility during aerospace demand spikes. Their captive polymer processing infrastructure feeds directly into Bavarian automotive battery enclosure supply, creating tight cost pass-through mechanics between raw material indices and finished substrate quotes.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between Tier-1 suppliers and Japanese-German resin producers, with price differentiation anchored in REACH compliance tier and volume scale. Certification-grade substrates for FAA special conditions command substantial premiums over consumer-grade flexible circuits. Cost compression in standard-grade printed electronics is intensifying as roll-to-roll capacity expands across East Asian contract manufacturers. Automotive OEMs exhibit highest price sensitivity due to battery cost floor pressures, while aerospace programs absorb premium pricing for de-icing element reliability guarantees.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for battery tray assemblies, while distribution runs through specialized polymer distributors for smaller medical device developers. Geographic supply concentrates in Japan for high-temperature resin formulations, Germany for REACH-compliant flame retardant substrates, and Finland for injection-molded 3D circuitry. Raw material dependencies include silver-filled epoxy pastes, liquid crystal polymer films, and halogen-free phosphorus-nitrogen compounds. Single-source vulnerability around Japanese specialty resin producers exposes buyers to allocation risk during automotive platform ramp-ups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where ECHA's 2026 REACH enforcement milestones for halogenated flame retardants are compressing qualification timelines and concentrating procurement among pre-certified substrate suppliers.
For Market Incumbents: Acquire aerosol jet printing capability to defend against Finnish specialists encroaching on curved automotive interior contracts. Backward integration into conductive polymer resin production reduces exposure to Japanese chemical producer allocation protocols. Prioritize captive REACH compliance laboratory investment in Bavaria to accelerate material qualification against evolving ECHA oxygen index standards. For New Entrants and Emerging Players: Embedded sensor fabrication for civil infrastructure health monitoring represents the most penetrable white-space target, with bridge and wind turbine operators in Germany and the United States replacing manual inspection cycles. Medical device conformable diagnostic patches offer secondary entry path through MFDS biocompatibility pathways. Go-to-market leverage rests on partnerships with Fraunhofer-Gesellschaft research institutions for process validation credibility. For Investors and Strategic Acquirers: Valuations sit cheapest among roll-to-roll substrate manufacturers lacking structural electronics integration capabilities but holding established aerospace qualification heritage. Long-term viability over the next decade hinges on successful migration from discrete component supply to finished battery tray and wing spar contracts. Monitor FAA special conditions certification timeline compression as the critical inflection signal for aerospace tier-one supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Laboratory Investment | ECHA oxygen index pre-qualification accelerates German automotive battery enclosure procurement decisions. |
| Aerosol Jet Printing Capability Acquisition | Conformal antenna integration into load-bearing composites addresses Boeing and Airbus wing de-icing specifications. |
| Conductive Polymer Resin Backward Integration | Captive supply of specialty feedstock buffers margin pressure from Japanese chemical producer concentration. |
| Civil Infrastructure Sensor Partnership | Fraunhofer-Gesellschaft collaboration validates embedded strain monitoring for German bridge operators. |
| Medical Device Biocompatibility Certification | MFDS pathway compliance unlocks conformable diagnostic patch exports to South Korean electronics procurement. |
Methodological Framework
Coverage spans Germany, the United States, Japan, Finland, and South Korea, with primary inputs from each regional cluster combining interviews with automotive platform engineers, aerospace Tier-1 supplier procurement leads, polymer substrate R&D directors, civil infrastructure maintenance directors, and medical device regulatory affairs specialists. Secondary validation draws from ECHA substance restriction filings, FAA special conditions certification databases, SEC 10-K disclosures from materials-science conglomerates, and EU Horizon program funding announcements. Bottom-up demand modeling for battery enclosure and wing structure applications triangulates against top-down chemical producer capacity estimates.
Granularity-level framing models product-type segmentation at the substrate technology tier, application segmentation at the platform-architecture level, and geographic segmentation at the manufacturing-cluster level. CAGRs derive from multivariate regression across electric vehicle platform ramp schedules, aerospace program certification timelines, and REACH compliance phase-out enforcement dates. Industry-specific forecast inputs include BMW Group and Volkswagen AG battery tray procurement specifications, plus Airbus SE wing de-icing system qualification protocols.
The model holds under stable REACH enforcement schedules and FAA certification throughput; deviation in ECHA substance restriction acceleration or aerospace safety directive revisions would shift demand timing. Forecasts embed assumptions around specialty resin supply elasticity and aerosol jet printing yield maturation. Periodic stress-testing of base assumptions against actual Tier-1 supplier contract awards is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
High-Voltage Interlock Loop Wiring Components Market
Electronic Components
Tower Mounted Amplifier Market
Electronic Components
Handheld Devices Battery Market
Electronic Components
North America Safety Relay and Timers Market
Electronic Components
Coin Battery Holder Market
Electronic Components
Global Suction Tube Market
Electronic Components
Battery Shunt Resistor Market
Electronic Components
Chip Shield Market
Electronic Components
Surface Mountable Laser Direct Structuring Antenna (LDS) Market
Electronic Components
Fixed Capacitor Market
Electronic Components
2D Electronics Market
Electronic Components
Display Port Adapters Market
Electronic Components
Global DC Motor Control Devices Market
Electronic Components
Audio DSP Market
Electronic Components
Touch Screen Controllers Market
Electronic Components
Metal Composite Power Inductor Market