
 Global Capacitor Market | 2026-2036
Global Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Capacitor Market Analysis
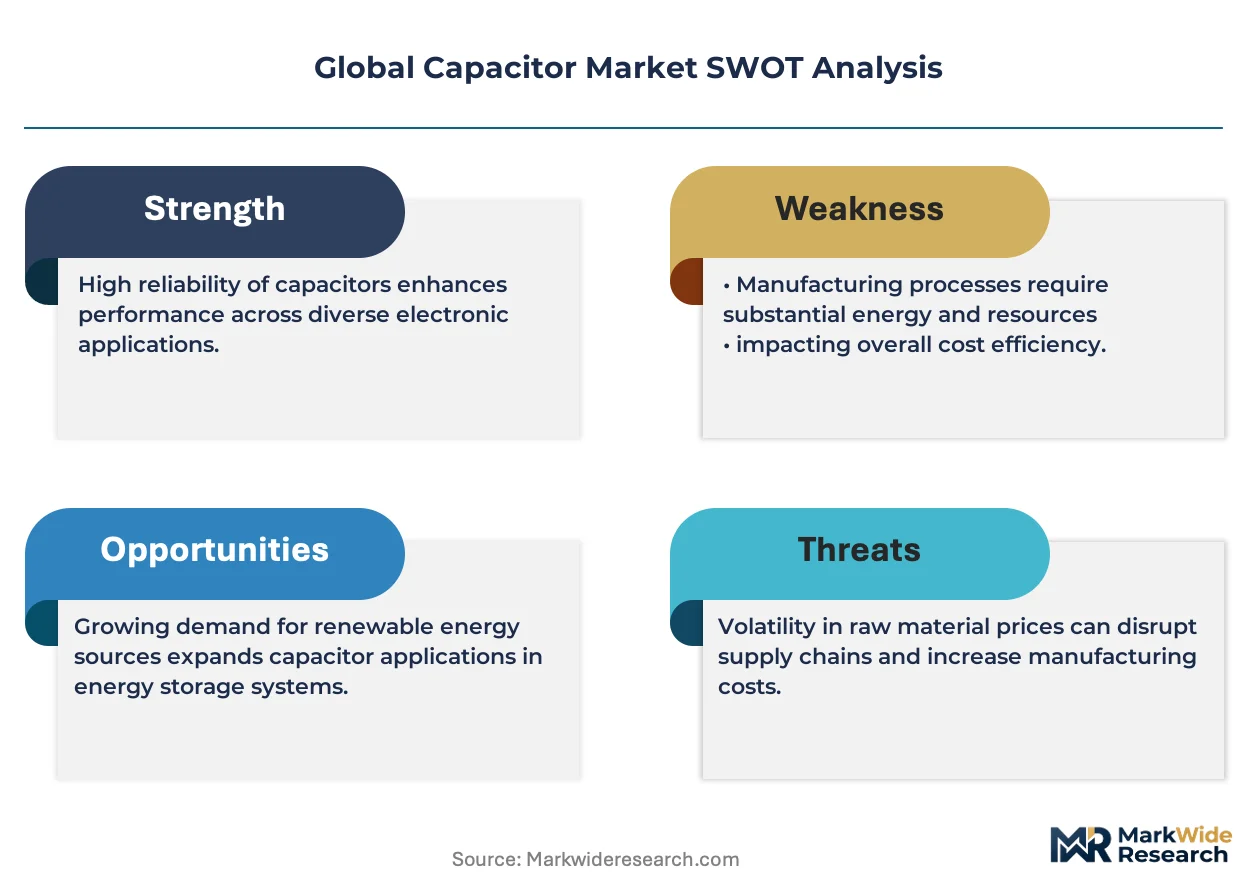
Dielectric material substitution away from barium titanate toward niobium-based and polymer composites is fragmenting traditional capacitor architectures across high-frequency applications. Murata Manufacturing sustains leadership in monolithic ceramic solutions through captive powder metallurgy operations. TDK Corporation anchors automotive-grade film capacitor supply with in-house polypropylene film extrusion. Samsung Electro-Mechanics competes aggressively in consumer electronics multilayer ceramic capacitors through scale manufacturing in Suwon.
A capacitor stores electrical energy in an electric field between conductive plates separated by a dielectric medium, with capacitance measured in farads and voltage ratings spanning millivolts to kilovolts depending on dielectric thickness and material breakdown strength. Ceramic capacitors dominate volume shipment in consumer electronics and telecommunications infrastructure due to miniaturization trajectories below 0402 case sizes. Film capacitors capture premium margin pools in renewable energy inverters and electric vehicle DC-link applications where self-healing dielectric properties and microfarad-range capacitance prove essential. Electrolytic variants retain cost-positioned relevance in industrial motor drives and legacy power supply designs despite aluminum foil supply constraints.
The EU F-Gas Regulation and REACH restrict fluorinated greenhouse gas use in capacitor manufacturing processes while China's MEE enforces wastewater discharge standards for etched aluminum foil production. Japan's METI circular economy guidelines mandate rare metal recovery rates from tantalum capacitor scrap. Stakeholders must monitor dielectric material passport requirements under emerging EU CSRD supply chain disclosure rules and position procurement toward qualified secondary tantalum sources.
Market Dynamics
Powertrain electrification is forcing capacitor architectures toward higher voltage ratings and temperature resilience, while dielectric material compliance tightens across East Asian manufacturing clusters and European regulatory frameworks.
Growth Catalysts
- Automotive Inverter Demand:Electric vehicle DC-link capacitors now require microfarad-range film solutions with self-healing properties. Tier-1 suppliers in Germany and Japan are qualifying polypropylene film extrusions for 800V architectures.
- REACH and F-Gas Compliance:The EU F-Gas Regulation is accelerating fluorinated gas phase-out in capacitor manufacturing. European producers are retrofitting etching lines to eliminate PFC emissions from aluminum foil production.
- Telecommunications Infrastructure:5G base station deployments in South Korea and coastal China are consuming multilayer ceramic capacitors below 0402 case sizes. Miniaturization trajectories favor niobium-based dielectrics for high-frequency filtering.
Market Restraints
- Aluminum Foil Supply Concentration:Etched anode foil for electrolytic capacitors depends on captive smelter capacity in China and Japan. Spot pricing volatility for high-purity aluminum ingot compresses margin pools in industrial motor drive applications.
- Tantalum Ore Sourcing Risk:Conflict mineral traceability requirements under SEC rules and EU CSRD create documentation burdens. Secondary tantalum recovery from capacitor scrap remains below METI circular economy targets.
- Barium Titanate Substitution Limits:Niobium pentoxide and polymer composite dielectrics exhibit lower capacitance density in Class 2 ceramics. High-K formulations struggle to match temperature stability for automotive-grade multilayer stacks.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and component packaging are attracting multilayer ceramic capacitor assembly investments. Domestic demand from smartphone and automotive electronics is outpacing local supply capacity.
- Renewable Energy Inverters:Wind and solar installations require DC-link film capacitors with 20-year operational life. Polypropylene metallization techniques enabling self-healing properties command premium positioning against electrolytic alternatives.
- Solid-State Battery Integration:Next-generation electric vehicle platforms are converging capacitor and battery management functions. Solid-state cell architectures demand higher ripple current tolerance from DC-link components.
Industry Challenges
- Powder Metallurgy Talent Scarcity:Captive dielectric powder production requires ceramic engineering expertise concentrated in Japanese and South Korean universities. Western manufacturers face recruitment friction for high-frequency material formulation roles.
- CSRD Supply Chain Disclosure:The EU Corporate Sustainability Reporting Directive mandates dielectric material passports tracing rare metal content. Implementation timelines compress procurement qualification cycles for tantalum and niobium suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Capacitor Market |
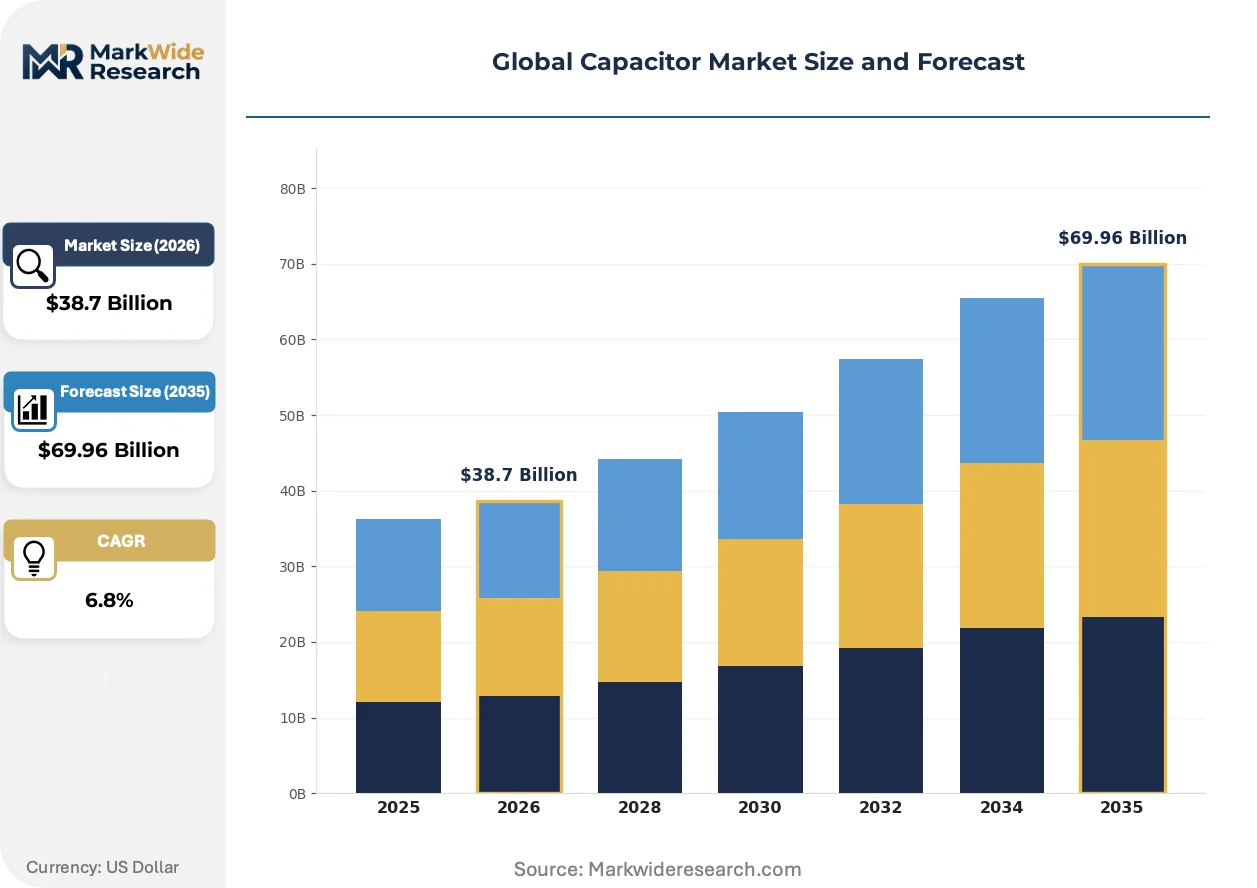
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electrolytic, Ceramic, Tantalum, Film Application: Consumer Electronics, Automotive, Industrial Equipment, Renewable Energy End User: Manufacturers, Distributors, Retailers, Enterprises Installation: Surface Mount, Through Hole, Bulk, Integrated |
| Companies Covered | Murata Manufacturing Co., Ltd., TDK Corporation, Samsung Electro-Mechanics, Vishay Intertechnology, Inc., KYOCERA AVX Components Corp., Nippon Chemi-Con Corporation, Panasonic Holdings Corporation, Taiyo Yuden Co., Ltd., Yageo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Capacitor Market Emerging Trajectories
Dielectric material science and manufacturing process control are converging to reshape capacitor performance hierarchies across voltage ratings and frequency domains.
Niobium-based dielectric formulations are migrating from specialty RF applications toward mainstream automotive multilayer ceramic capacitors. These materials offer higher Curie temperatures than barium titanate for inverter modules operating above 150°C. German and Japanese automotive suppliers are accelerating qualification timelines for niobium pentoxide Class 1 ceramics in traction drive systems.
The EU F-Gas Regulation is prohibiting hydrofluorocarbon use in aluminum electrolytic capacitor etching processes by 2030. European foil producers are investing in plasma etching and laser structuring as fluorine-free alternatives. High-voltage industrial capacitor supply chains face capital intensity spikes from equipment replacement cycles.
Consolidated procurement by electric vehicle platform architects is compressing supplier qualification from 24 months to 14 months. Tier-1 inverter manufacturers in South Korea and Germany now mandate concurrent engineering partnerships with dielectric material suppliers. This pattern concentrates volume allocation toward vertically integrated ceramic powder producers with captive film extrusion capabilities.
Global Capacitor Market Segmentation
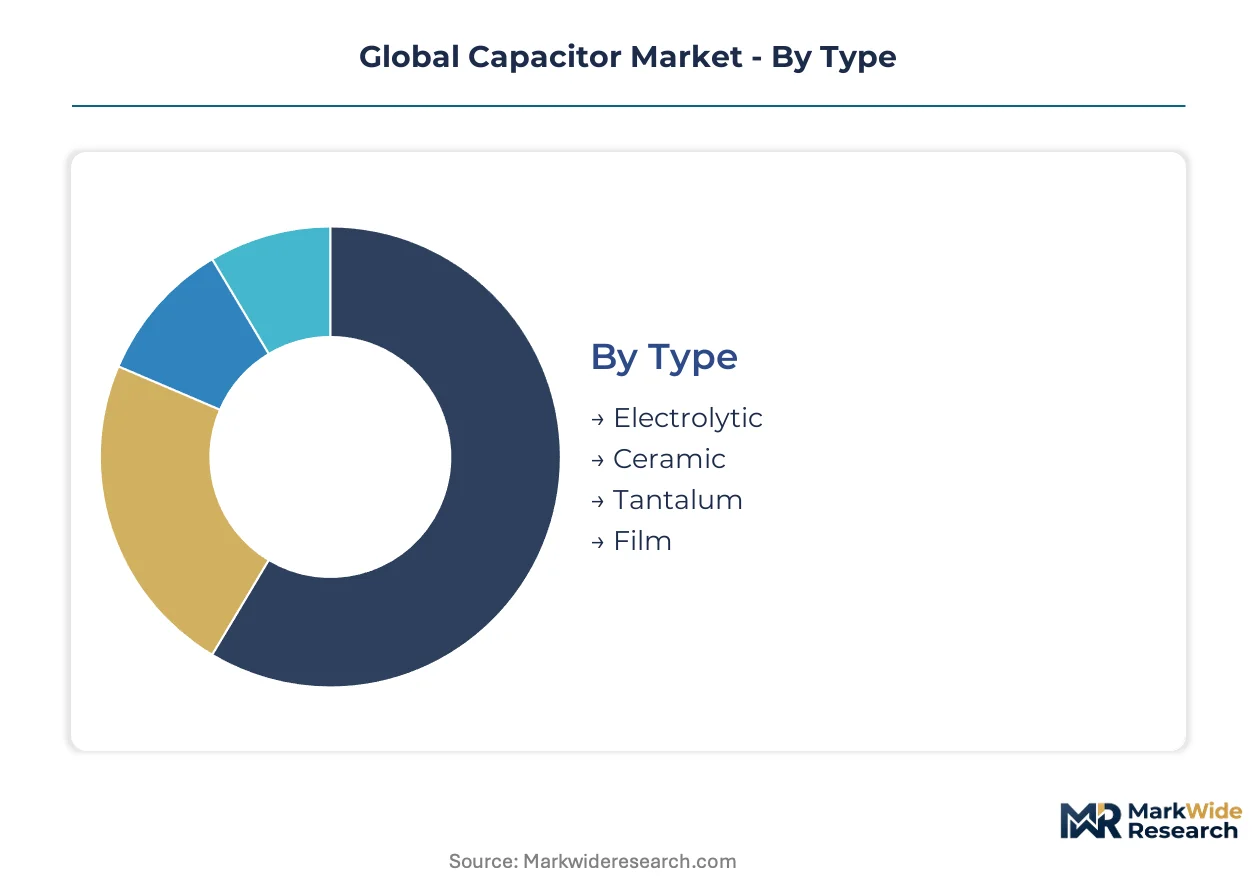
Capacitor procurement patterns diverge sharply across dielectric technologies and mounting formats, with automotive and renewable energy applications driving specification premiums while consumer electronics volumes compress margins. Understanding segment-specific qualification timelines and supply chain configurations enables targeted positioning across voltage ratings and temperature resilience tiers.
Type:
After-sales service intensity varies dramatically by dielectric chemistry, with electrolytic and film capacitors requiring proactive field monitoring for end-of-life replacement scheduling while ceramic variants offer fit-and-forget reliability profiles.
- Electrolytic:Aluminum oxide dielectric layers formed through electrochemical etching deliver high capacitance density in cylindrical or surface-mount packages. Demand concentrates in industrial motor drives across German manufacturing clusters and legacy power supply designs in China's Pearl River Delta, constrained by high-purity aluminum ingot spot pricing volatility from captive Japanese and Chinese smelters.
- Ceramic:Barium titanate or niobium-based formulations in multilayer stacks achieve miniaturization below 0402 case sizes for high-frequency filtering. Japanese and South Korean telecommunications infrastructure deployments in Seoul and Shenzhen absorb volume shipments, with niobium pentoxide migration accelerating for automotive-grade temperature stability above 150°C.
- Tantalum:Manganese dioxide or polymer cathode systems in chip configurations provide stable capacitance in confined spaces. Medical implant and aerospace applications in the US and Switzerland drive qualification cycles, though SEC conflict mineral traceability and EU CSRD documentation burdens compress procurement flexibility.
- Film:Polypropylene, polyester, or polycarbonate dielectrics with metallized electrodes enable self-healing properties for DC-link applications. Wind and solar inverter installations in Denmark and Spain require 20-year operational life guarantees, with German and Japanese Tier-1 suppliers qualifying 800V polypropylene extrusions for electric vehicle architectures.
Ceramic capacitors hold the largest share by unit volume; momentum sits with film solutions for electrified powertrain DC-link requirements.
Application:
Cost tier stratification separates commodity consumer electronics procurement from automotive-grade qualification premiums, with industrial and renewable energy applications occupying intermediate positions on specification intensity.
- Consumer Electronics:Smartphones, laptops, and wearables demand multilayer ceramic capacitors in sub-0402 footprints for space-constrained PCB layouts. Samsung Electro-Mechanics' Suwon manufacturing cluster and Murata's captive powder metallurgy operations in Japan supply volume to South Korean and Chinese device assemblers, with miniaturization trajectories pushing niobium-based dielectric adoption.
- Automotive:Inverter modules, onboard chargers, and battery management systems require film and ceramic capacitors with AEC-Q200 qualification and temperature resilience above 150°C. German OEM platform consolidation around 800V architectures compresses supplier qualification from 24 months to 14 months, favoring vertically integrated dielectric producers with concurrent engineering capabilities.
- Industrial Equipment:Motor drives, welding equipment, and uninterruptible power supplies utilize electrolytic and film capacitors for bulk energy storage. Chinese industrial automation clusters in Suzhou and Shenzhen absorb cost-positioned aluminum electrolytic supply, though EU F-Gas Regulation compliance costs for etching processes are reshaping European procurement patterns.
- Renewable Energy:Photovoltaic inverters and wind turbine converters demand polypropylene film capacitors with microfarad-range capacitance and self-healing metallization. Danish and Spanish installation growth drives DC-link specification premiums against electrolytic alternatives, with 20-year operational life requirements locking in supplier relationships.
Consumer electronics generates the highest unit volumes; renewable energy inverters are climbing the fastest on value expansion.
End User:
Customer type determines procurement sophistication, with manufacturers and enterprises conducting direct technical qualification while distributors and retailers intermediate for standardized specifications.
- Manufacturers:OEMs and EMS providers in automotive, telecommunications, and industrial sectors conduct direct dielectric material qualification with captive powder and film extrusion suppliers. Japanese and South Korean manufacturers leverage concurrent engineering partnerships to compress development cycles.
- Distributors:Arrow, Avnet, and regional specialists in Asia-Pacific and Europe manage inventory for standard ceramic and electrolytic specifications. Distributor consolidation is concentrating procurement leverage for commodity multilayer ceramic capacitors.
- Retailers:Electronics component retailers and online marketplaces serve hobbyist, repair, and small-scale manufacturing demand with limited technical support requirements.
- Enterprises:Large industrial and energy utilities conduct direct procurement for high-voltage film capacitor installations with long-term service agreements. German and Japanese renewable energy developers specify 20-year operational life guarantees with scheduled replacement protocols.
Manufacturers command the largest procurement value; enterprise direct purchasing is gaining share fastest on renewable energy project scale.
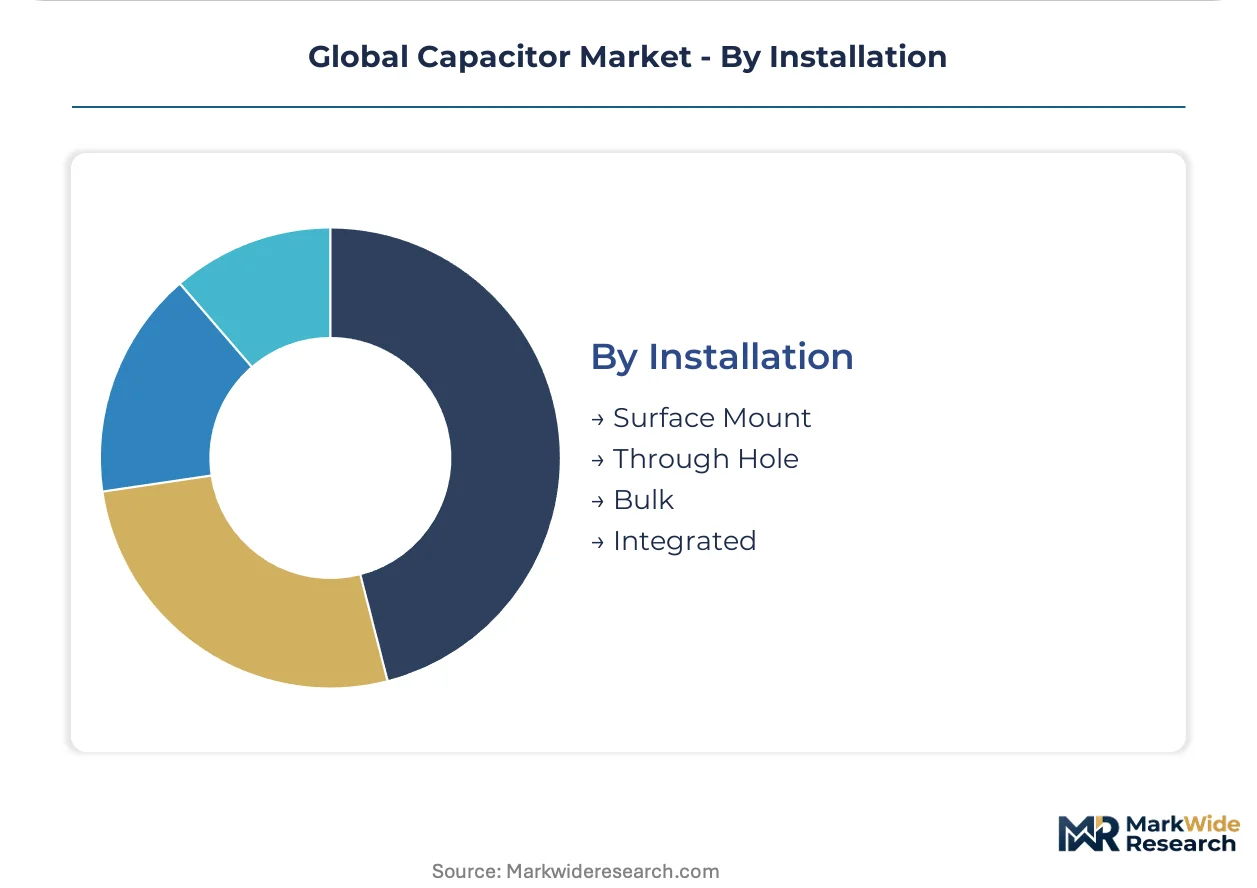
Installation:
Mounting technology selection tracks PCB density requirements and field service accessibility, with surface mount dominating volume production and through-hole retaining relevance for high-stress industrial environments.
- Surface Mount:Reflow-solderable ceramic and tantalum chip capacitors enable automated assembly for consumer electronics and telecommunications equipment. Miniaturization below 0402 case sizes in South Korean and Chinese 5G base station deployments favors multilayer ceramic surface mount solutions.
- Through Hole:Radial and axial leaded configurations for electrolytic and film capacitors support manual assembly and high-vibration industrial applications. German and Japanese automotive suppliers specify through-hole film capacitors for traction inverter modules requiring mechanical robustness.
- Bulk:Unencapsulated capacitor elements for integration into custom assemblies and power modules. Renewable energy inverter manufacturers in Denmark and Spain source bulk polypropylene film for proprietary DC-link module construction.
- Integrated:Capacitor functions embedded within semiconductor packages, power modules, or solid-state battery management systems. Next-generation electric vehicle platforms in Germany and South Korea are converging capacitor and cell monitoring functions, demanding higher ripple current tolerance from integrated components.
Surface mount captures the highest unit shipments; integrated configurations are expanding most quickly on powertrain electrification convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capacitor trade flows reflect East Asian manufacturing dominance against European and North American import dependence, with China, Japan, and South Korea collectively supplying over two-thirds of global export volumes while Germany and the United States absorb premium-grade imports for automotive and industrial applications.
China
Domestic consumption of multilayer ceramic capacitors surges from 5G base station deployments in Shenzhen and Dongguan manufacturing corridors. The MEE enforces wastewater discharge standards for etched aluminum foil production, compressing electrolytic capacitor supply capacity. Yangtze River Delta clusters in Suzhou and Wuxi concentrate dielectric powder metallurgy operations serving captive automotive inverter demand.
Japan
Murata Manufacturing and TDK Corporation anchor global supply through captive ceramic powder and polypropylene film extrusion capabilities. METI circular economy guidelines mandate rare metal recovery rates from tantalum capacitor scrap, reshaping end-of-life processing economics. Kanto and Kansai industrial belts in Tokyo and Osaka retain concentrated engineering talent for high-frequency material formulation.
Germany
Tier-1 automotive suppliers in Stuttgart and Munich qualify 800V polypropylene film capacitors for electric vehicle DC-link architectures. The EU F-Gas Regulation accelerates fluorinated gas phase-out from aluminum electrolytic etching processes by 2030. Bavarian and Baden-Württemberg manufacturing clusters face capital intensity spikes from plasma etching equipment replacement cycles.
South Korea
Samsung Electro-Mechanics scales multilayer ceramic capacitor output from Suwon facilities for consumer electronics and telecommunications infrastructure. The Seoul Capital Area absorbs volume shipments for domestic 5G base station construction while exporting to Chinese device assemblers. Busan-Ulsan industrial corridors concentrate concurrent engineering partnerships between dielectric suppliers and automotive platform architects.
United States
Medical implant and aerospace applications in Minneapolis and Boston drive tantalum capacitor qualification cycles with extended documentation requirements. SEC conflict mineral traceability rules and impending EU CSRD alignment create procurement friction for primary tantalum sourcing. Southwestern industrial zones concentrate renewable energy inverter assembly demanding polypropylene film solutions with 20-year operational guarantees.
Global Capacitor Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated dielectric material producers with captive powder metallurgy and film extrusion capabilities. Japanese and South Korean conglomerates dominate premium-tier automotive and telecommunications specifications through backward integration into ceramic formulation and polypropylene metallization. Three archetypes define competitive positioning: scale-driven consumer electronics suppliers, technology-anchored automotive-grade specialists, and diversified industrial component conglomerates. M&A activity concentrates on rare metal recovery assets and fluorine-free etching technology licenses, while capacity expansion targets Indian PLI scheme incentives and European renewable energy inverter demand.
Among Japanese fabricators, Murata Manufacturing Co., Ltd. and TDK Corporation exemplify the technology-anchored archetype through integrated dielectric material control. Samsung Electro-Mechanics represents scale-driven positioning in consumer electronics multilayer ceramic capacitors. These three entities occupy positions that concentrate procurement leverage among automotive platform architects and telecommunications infrastructure deployers, with qualification timelines compressing from 24 months toward 14 months for concurrent engineering partnerships.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| TDK Corporation |
| Samsung Electro-Mechanics |
| Vishay Intertechnology, Inc. |
| KYOCERA AVX Components Corp. |
| Nippon Chemi-Con Corporation |
| Panasonic Holdings Corporation |
| Taiyo Yuden Co., Ltd. |
| Yageo Corporation |
| Others |
Supply Flow & Price Mechanics
Aluminum foil supply concentration in Chinese and Japanese smelters compresses margin pools across electrolytic capacitor tiers while simultaneously forcing procurement diversification toward film and ceramic alternatives. This single-source dependency for high-purity anode foil widens pricing spreads between automotive-grade film capacitors and industrial electrolytic supply, with concurrent engineering partnerships commanding qualification premiums that commodity spot purchases cannot match.
Pricing Analysis
Current-generation barium titanate ceramic formulations trade at commodity rates against prior-generation Class 2 dielectrics, while next-generation niobium pentoxide and polymer composites capture tiered pricing stratification across premium, standard, and economy levels. Price differentiation rests on AEC-Q200 certification status and captive powder metallurgy capabilities, with automotive-grade multilayer ceramic capacitors from Japanese producers maintaining resilience against consumer electronics margin erosion. Cost compression in sub-0402 case sizes intensifies because Samsung Electro-Mechanics scales Suwon output for smartphone assemblers. Consumer electronics procurement exhibits highest price sensitivity; medical implant tantalum buyers demonstrate lowest.
Supply Chain Analysis
Export-control regimes limiting fluorinated gas etching technologies under EU F-Gas Regulation reshape aluminum foil procurement patterns for European capacitor producers. Geographic supply concentration centers on Japan, South Korea, and coastal China for dielectric powder and polypropylene film extrusion. Raw material dependencies draw from high-purity aluminum ingot, niobium pentoxide, and metallized polypropylene film. Single-source vulnerability in etched anode foil from captive Japanese and Chinese smelters elevates procurement risk. Distribution runs through Arrow and Avnet for standard ceramic specifications, with direct OEM qualification dominating automotive and renewable energy volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacitor procurement is converging toward platform-economics dynamics as electric vehicle architects consolidate DC-link specification authority across 800V architectures, forcing dielectric suppliers to embed concurrent engineering capabilities or exit premium tier qualification.
For Market Incumbents: Insulate automotive-grade positioning through backward integration into niobium pentoxide powder metallurgy and polypropylene film extrusion, countering Samsung Electro-Mechanics scale advantages in consumer electronics. Prioritize METI-mandated rare metal recovery infrastructure to preempt EU CSRD documentation burdens on tantalum supply chains. Defend margin pools by locking 20-year service agreements with Danish and Spanish renewable energy developers before commodity film alternatives gain traction. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme corridor for multilayer ceramic capacitor assembly, where domestic smartphone and automotive electronics demand outpaces local supply capacity. Target fluorine-free etching technology licensing to European foil producers facing EU F-Gas Regulation equipment replacement cycles. Pursue concurrent engineering partnerships with German Tier-1 suppliers as the most penetrable entry vector for automotive qualification. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated dielectric material producers with captive powder and film capabilities over pure-play assemblers. Long-term viability across the projection horizon hinges on rare metal recovery assets and fluorine-free process licenses. Watch niobium pentoxide qualification timelines at German automotive suppliers as the inflection signal for dielectric substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dielectric Powder Production | Murata Manufacturing's captive metallurgy operations lock automotive qualification timelines against scale competitors. |
| Fluorine-Free Etching Technology Licensing | European foil producers under EU F-Gas Regulation face capital intensity spikes from plasma equipment replacement. |
| Concurrent Engineering Partnership Formation | German Tier-1 suppliers compress supplier qualification from 24 months toward 14 months for 800V architectures. |
| Rare Metal Recovery Asset Acquisition | Japan's METI circular economy guidelines mandate tantalum scrap recovery rates reshaping end-of-life economics. |
| India PLI Scheme Manufacturing Footprint | Domestic electronics demand from smartphone and automotive sectors outpaces local multilayer ceramic capacitor supply. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across capacitor procurement, dielectric material formulation, and power electronics engineering domains. Primary interviews captured OEM platform architects at German and South Korean automotive suppliers, powder metallurgy specialists at Japanese ceramic producers, and procurement leads at renewable energy inverter manufacturers in Denmark and Spain. Secondary validation drew from SEC conflict mineral filings, EU F-Gas Regulation implementation guidance, METI circular economy reports, and customs trade data for aluminum foil and niobium concentrate flows. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Calibration against historical capacity utilization rates and qualification timeline compression patterns anchored the projection framework. Segmentation dimensions modeled include dielectric technology type, voltage rating tier, mounting format, end-use application, and regional manufacturing cluster. CAGRs derived from elasticity-adjusted demand curves for electric vehicle powertrain content and 5G telecommunications infrastructure deployment. Industry-specific forecast inputs incorporated polypropylene film metallization yield improvements and niobium pentoxide Curie temperature performance trajectories.
Macroeconomic conditions sit as an overlay; deviation in electric vehicle adoption curves, aluminum ingot spot pricing, or REACH enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on dielectric substitution rates and regulatory phase-out timelines. Cross-checking against IEA renewable energy capacity additions and automotive platform electrification announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Timing Relay Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
Audio DSP Market
Electronic Components
Speaker Cone Material Market
Electronic Components
Wireless Charging Stand Market
Electronic Components
Industrial Relays Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
Fuel Pump Driver Module Market
Electronic Components
AC Adapter Market
Electronic Components
Trackpad Market
Electronic Components
Capacitor Kits Market
Electronic Components
US Frequency Control and Timing Devices Market
Electronic Components
Digital Isolator Market
Electronic Components
PTC Resettable Device Market
Electronic Components
Passive Attenuator Market
Electronic Components
Power Inductors Market