
 Semiconductor POD Cleaner Market | 2026-2036
Semiconductor POD Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor POD Cleaner Market Insights
Preventive maintenance contracts and software-defined cleaning protocols is broadening the commercial scope of semiconductor POD cleaner engagements beyond discrete equipment sales. Modutek Corporation leverages its vertical integration into wet process equipment to sustain recurring service revenue streams across North American fabs. ACM Research, Inc. anchors its competitive stance through megasonic technology leadership in advanced node applications. Ransohoff differentiates via specialized solvent recovery systems that extend equipment lifecycle value for integrated device manufacturers.
A semiconductor POD cleaner is a precision wet-processing system engineered to remove particulate, metallic, and organic contaminants from front-opening unified pods used in automated wafer transport, typically operating with sub-ppb purity chemistries and ISO Class 1-compatible construction materials. Its primary industrial purpose is to eliminate yield-destroying contamination events at the critical interface between wafer storage media and process equipment. Non-ionic cleaners currently dominate formulation demand due to their compatibility with advanced photoresist materials and reduced surface residue profiles, while megasonic cleaning technology leads growth trajectories as 3nm and below nodes require acoustic cavitation precision that conventional ultrasonic methods cannot achieve. Foundry end users concentrate the largest margin pools given their high-volume, repetitive cleaning cycles and stringent particle-count specifications.
The EPA governs volatile organic compound emissions from solvent-based chemistries in US semiconductor manufacturing, while REACH restricts hazardous substance use across European supply chains, and China's MEE enforces wastewater discharge standards that directly impact cleaner system design. These regulatory frameworks collectively elevate demand for closed-loop chemical recycling and aqueous formulation alternatives that reduce regulatory compliance burden. Stakeholders must monitor evolving dual carbon goals in China and the EU Green Deal's chemical footprint requirements to anticipate next-generation product certification standards and manufacturing location strategies.
Market Dynamics
Advanced node migration below 3nm is compressing particle tolerance thresholds, forcing foundries to replace conventional ultrasonic cleaning with megasonic cavitation systems that achieve sub-10nm removal precision without substrate damage.
Growth Catalysts
- EPA VOC emission standards:Tightening limits on volatile organic compounds from solvent chemistries are accelerating closed-loop recycling system deployments across US fabrication facilities.
- Taiwan Hsinchu cluster concentration:Dense fab clustering creates sustained demand for high-frequency POD cleaning cycles with dedicated service infrastructure.
- Megasonic technology maturation:Acoustic cavitation precision now satisfies 2nm node requirements, expanding addressable process windows for front-opening unified pod maintenance.
Market Restraints
- High-purity chemical input volatility:Ultra-pure water and sub-ppb solvent supply constraints in South Korea create cost instability for aqueous formulation systems.
- Single-source equipment dependency:Critical megasonic transducer components concentrate among Japanese suppliers, exposing buyers to geographic supply risk.
- REACH substance authorization delays:Pending ECHA decisions on specialty surfactants extend qualification timelines for European fab deployments.
Strategic Opportunities
- China Yangtze River Delta expansion:Domestic memory and logic capacity buildouts create demand for localized POD cleaner manufacturing and service capabilities.
- Dual carbon goal alignment:China's MEE wastewater discharge incentives reward aqueous chemistry adoption with accelerated environmental permitting.
- Predictive maintenance convergence:Integration of vibration sensing with chemical bath analytics enables condition-based cleaning cycles that reduce chemistry consumption.
Industry Challenges
- Cleanroom technician specialization gap:ISO Class 1-compatible equipment maintenance requires certified personnel scarce in emerging fab locations.
- Legacy ultrasonic fleet retrofit complexity:Existing tool footprints resist megasonic upgrade paths without full chamber replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor POD Cleaner Market |
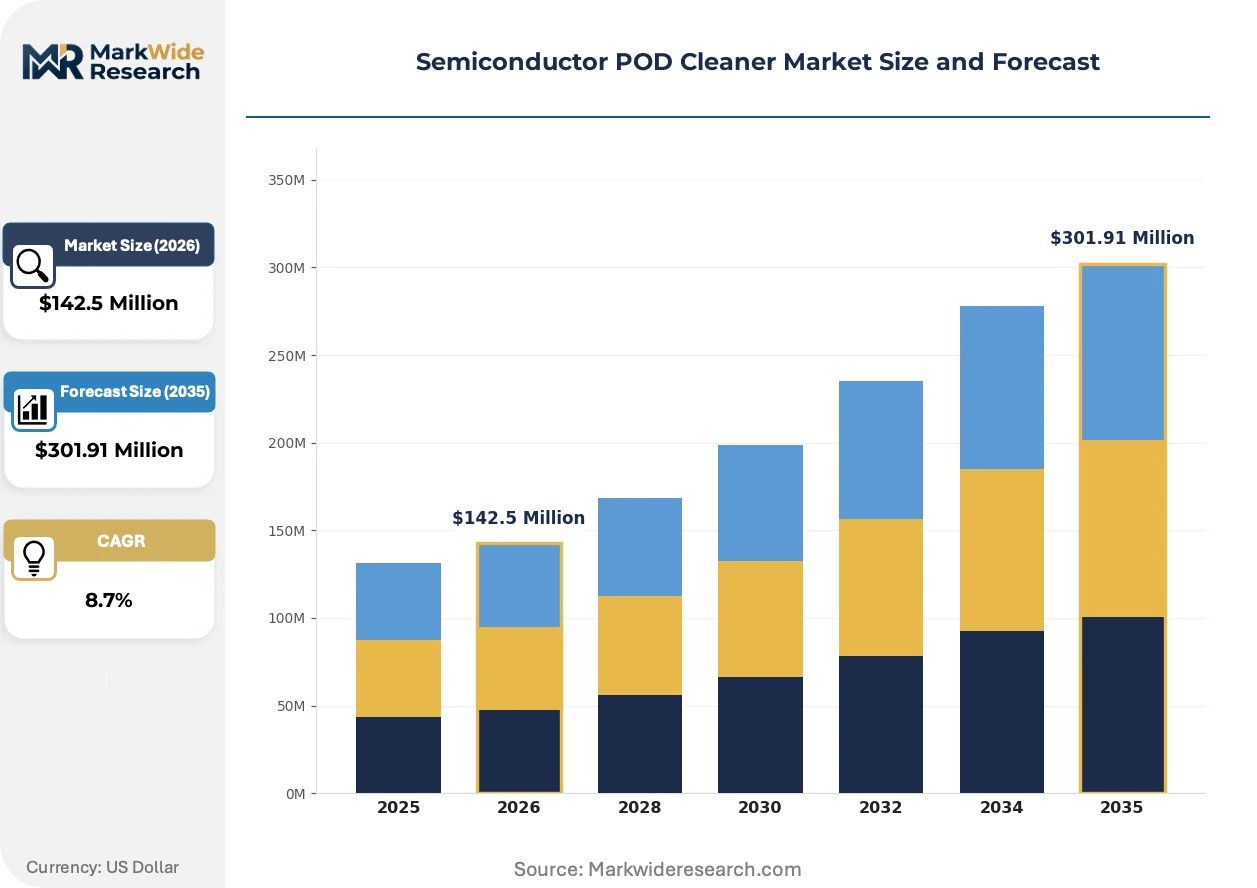
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $301.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anionic Cleaners, Cationic Cleaners, Non-Ionic Cleaners, Solvent-Based Cleaners Technology: Ultrasonic Cleaning, Megasonic Cleaning, Electrochemical Cleaning, Chemical Vapor Deposition Application: Wafer Fabrication, Photolithography, Packaging, Surface Preparation End User: Foundries, Integrated Device Manufacturers, Fabless Companies, Research Institutions |
| Companies Covered | Modutek Corporation, ACM Research, Inc., Ransohoff, C&D Semiconductor Services Inc, AXUS Technology, DEVICEENG Co., LTD, Hugle Electronics, Brooks Automation, TAZMO Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor POD Cleaner Market Trends and Innovations
Megasonic cleaning architectures are displacing legacy ultrasonic systems through superior particle removal efficiency, while regulatory chemistry restrictions and service model unbundling reshape how foundries procure contamination control.
Megasonic transducer arrays operating at 800kHz-1MHz frequencies are decentralizing process control from centralized chemical bath systems to pod-specific acoustic treatment stations. Leading memory manufacturers in South Korea's Pyeongtaek cluster deploy these modular units for inline cleaning between deposition steps. This topology shift is decentralizing capital allocation decisions from central engineering teams to individual process module owners.
REACH authorization requirements for perfluorinated surfactants are compressing formulation portfolios available to European equipment suppliers. ECHA's 2023-2025 substance evaluation calendar threatens withdrawal of chemistries critical to hydrophobic residue removal. Foundries in Germany and France accelerate aqueous alternative qualification programs to preempt supply discontinuity.
Service contract unbundling from equipment procurement is fragmenting vendor-customer relationships across Taiwan's foundry base. TSMC and UMC now separately negotiate chemical supply, maintenance labor, and performance guarantees rather than accepting bundled OEM packages. This purchasing pattern shift concentrates most acutely in Hsinchu Science Park facilities with mature internal metrology capabilities.
Semiconductor POD Cleaner Market Segmentation
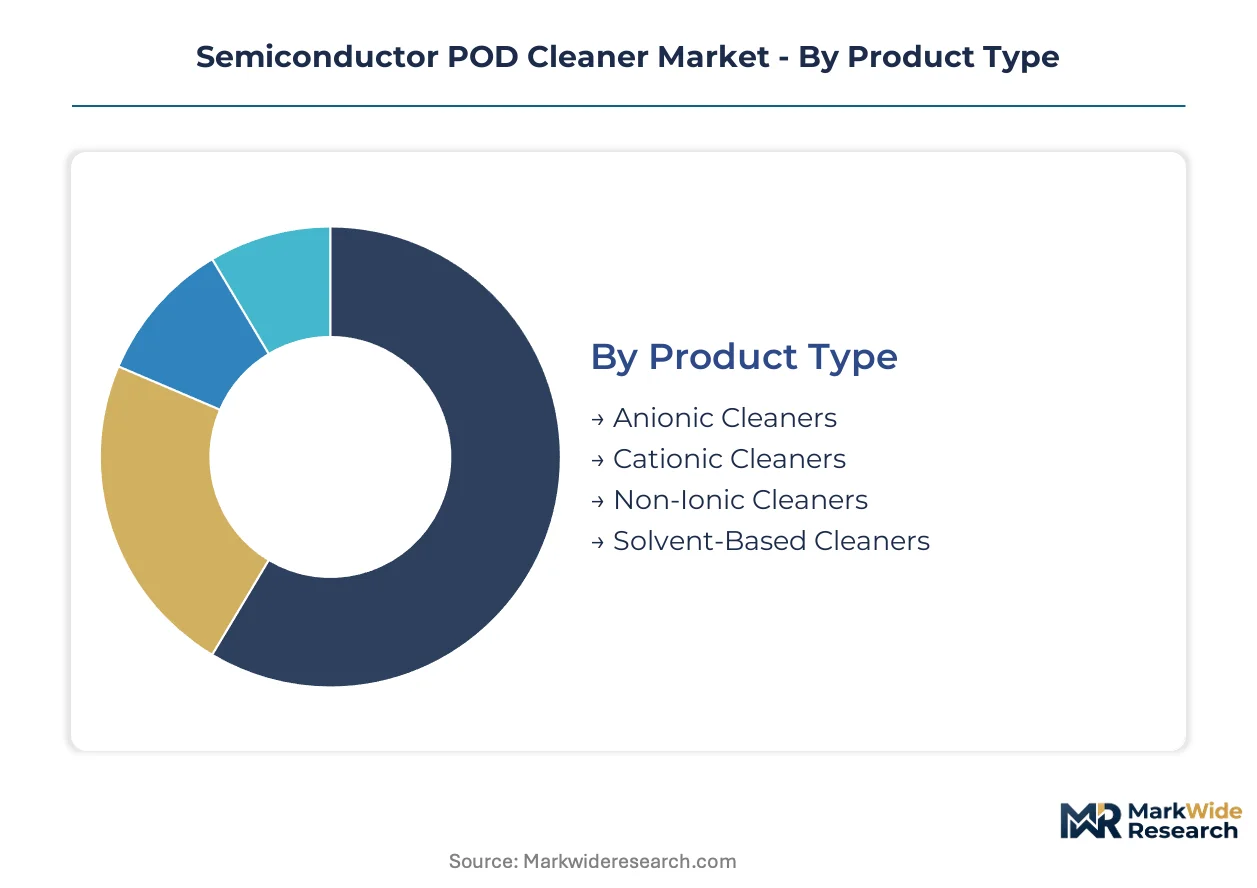
POD cleaner procurement varies sharply by process node and contamination risk profile. Technology selection and end-user scale dictate formulation chemistry, acoustic frequency, and service contract structures.
Product Type:
Formulation chemistry determines surface residue profiles and regulatory compliance pathways across fab locations.
- Non-Ionic Cleaners:These surfactant-based formulations minimize surface charge interactions that attract particulate redeposition. Demand concentrates in Taiwan's Hsinchu Science Park foundries where photoresist compatibility requirements are most stringent. EPA VOC thresholds are compressing solvent alternatives faster than anticipated.
- Solvent-Based Cleaners:Hydrocarbon and fluorinated formulations dissolve hydrophobic organic residues through polarity matching. South Korea's Pyeongtaek memory cluster sustains demand despite REACH authorization uncertainties for perfluorinated chemistries. Closed-loop recovery systems offset regulatory compliance costs.
- Anionic Cleaners:Negatively charged surfactant systems excel at metallic ion removal from aluminum-alloy POD surfaces.
- Cationic Cleaners:Positively charged formulations target silica and glass-native oxide contamination in quartz POD variants.
Non-ionic cleaners lead on scale; solvent-based formulations face steepest regulatory headwinds.
Technology:
Acoustic frequency selection separates legacy maintenance from advanced node qualification.
- Megasonic Cleaning:Transducer arrays operating at 800kHz-1MHz generate controlled cavitation bubbles that dislodge sub-10nm particles without substrate damage. South Korea's Samsung and SK Hynix deploy these systems for 3nm and below node transitions. The technology commands premium positioning through process window exclusivity.
- Ultrasonic Cleaning:Conventional 20-40kHz systems remain entrenched in mature node facilities with less stringent particle-count specifications. China's Yangtze River Delta corridor sustains volume demand for cost-sensitive domestic memory ramp-ups. Retrofit complexity limits upgrade pathways.
- Electrochemical Cleaning:Anodic dissolution methods target metallic contamination through controlled oxidation-reduction cycles.
- Chemical Vapor Deposition:Vapor-phase surface treatment enables dry-process alternatives for moisture-sensitive chemistries.
Ultrasonic cleaning retains volume dominance; megasonic systems gain share fastest.
Application:
Process step contamination risk dictates cleaning frequency and chemistry intensity.
- Wafer Fabrication:Deposition and etch cycles deposit metallic and organic residues requiring aggressive chemistry protocols. Taiwan's foundry base operates the highest-frequency cleaning schedules globally. Particle tolerance thresholds compress with each node migration.
- Photolithography:Photoresist and anti-reflective coating residues demand non-ionic formulations that prevent surface charge accumulation. EUV tool integration intensifies POD cleanliness requirements. Defect density specifications now measure single-digit particles per pod.
- Packaging:Post-dicing organic contamination from die-attach films requires specialized solvent formulations.
- Surface Preparation:Pre-deposition native oxide removal employs dilute acid chemistries in dedicated POD treatment stations.
Wafer fabrication commands the largest chemistry volumes; photolithography applications are climbing fastest.
End User:
Capital deployment scale and internal metrology capability shape vendor relationship structures.
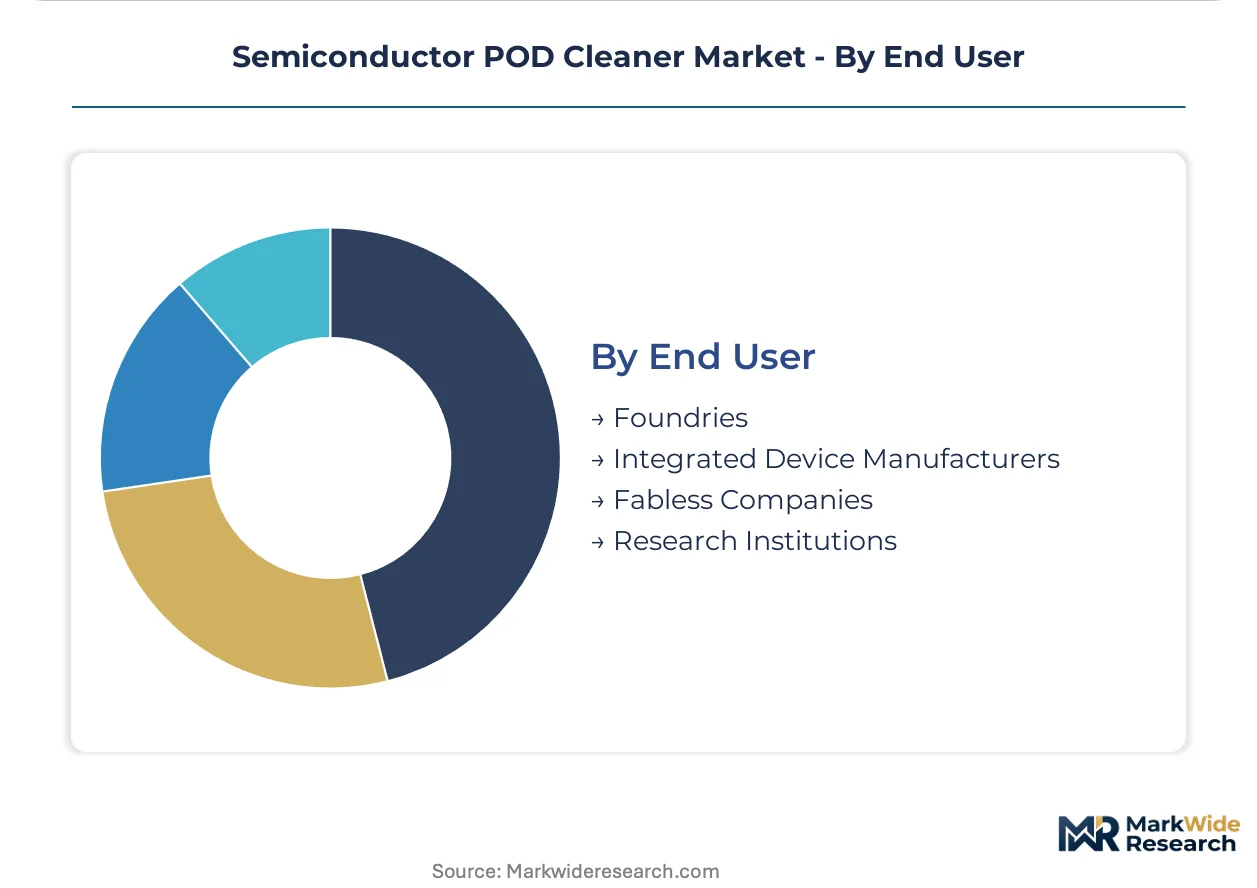
- Foundries:High-volume repetitive cleaning cycles with stringent particle-count specifications create the largest margin pools. TSMC and UMC in Taiwan's Hsinchu cluster unbundle service contracts from equipment procurement. Internal metrology teams negotiate performance guarantees separately.
- Integrated Device Manufacturers:Captive fab operations in the United States and Japan prioritize equipment lifecycle value through solvent recovery integration. IDMs consolidate vendor relationships to reduce qualification overhead.
- Fabless Companies:Outsourced manufacturing limits direct POD cleaner procurement to R&D pilot lines.
- Research Institutions:University and national laboratory fabs operate low-frequency cleaning with manual protocol flexibility.
Foundries lead on procurement scale; integrated device manufacturers concentrate most on total cost of ownership optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing semiconductor POD cleaner procurement toward jurisdictions with streamlined environmental permitting, while mature clusters absorb compliance premiums through scale advantages. Production migration patterns track divergence between REACH-encumbered European qualification timelines and accelerated permitting in Asian manufacturing corridors.
Taiwan
Foundry concentration in Hsinchu Science Park sustains the highest-frequency POD cleaning cycles globally, with TSMC and UMC unbundling service contracts from equipment procurement. The country's Environmental Protection Administration enforces wastewater discharge standards that favor closed-loop chemical recycling investments. Taichung's emerging fab cluster is replicating Hsinchu's dedicated service infrastructure for 2nm node ramp-ups.
South Korea
Samsung and SK Hynix deploy megasonic systems for 3nm and below transitions, creating premium equipment demand concentrated in Pyeongtaek's memory corridor. The Ministry of Environment enforces effluent standards that elevate aqueous chemistry adoption incentives. Seoul Capital Area fabs face ultra-pure water supply constraints that destabilize input costs for aqueous formulation systems.
China
Domestic memory and logic capacity buildouts in the Yangtze River Delta generate demand for localized manufacturing and service capabilities. The Ministry of Ecology and Environment's dual carbon goals reward aqueous chemistry adoption with accelerated environmental permitting. Shanghai's semiconductor corridor is consolidating regional supply chains to reduce import dependency for high-purity chemical inputs.
United States
Integrated device manufacturers prioritize equipment lifecycle value through solvent recovery integration, consolidating vendor relationships to reduce qualification overhead. EPA volatile organic compound emission standards accelerate closed-loop recycling system deployments across Arizona and Texas fabrication facilities. Greater Phoenix's emerging fab cluster is attracting dedicated service infrastructure from equipment suppliers.
Germany
Foundries in Dresden and Bavaria accelerate aqueous alternative qualification programs to preempt REACH authorization discontinuities for perfluorinated surfactants. ECHA's substance evaluation calendar compresses formulation portfolios available to domestic equipment suppliers. Saxony's semiconductor cluster faces extended qualification timelines that disadvantage European deployment schedules against Asian competitors.
Semiconductor POD Cleaner Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with foundry procurement favoring integrated service providers while IDMs consolidate around lifecycle-optimization partners. The vendor base organizes into three tiers: megasonic technology leaders commanding premium positioning, wet-process equipment generalists with backward integration into chemical supply, and regional fabricators competing on qualification speed. Competitive intensity concentrates on predictive maintenance convergence and chemistry formulation exclusivity rather than equipment hardware differentiation.
Among North American wet-process specialists, Modutek Corporation exemplifies the vertically integrated archetype with captive chemical supply capabilities. ACM Research, Inc. occupies a position representing megasonic technology leadership for advanced node applications. Ransohoff anchors the solvent recovery systems tier, serving integrated device manufacturers focused on total cost of ownership optimization. These three companies illustrate divergent strategic postures: backward integration, acoustic innovation, and lifecycle value extension respectively.
| Leading Market Players |
|---|
| Modutek Corporation |
| ACM Research, Inc. |
| Ransohoff |
| C&D Semiconductor Services Inc |
| AXUS Technology |
| DEVICEENG Co., LTD |
| Hugle Electronics |
| Brooks Automation |
| TAZMO Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Foundry unbundling of service contracts from equipment procurement is forcing suppliers to price components separately rather than as integrated bundles, compressing margins on standalone hardware while creating premium capture opportunities for recurring chemical and maintenance revenue streams.
Pricing Analysis
Distributor margins on megasonic transducer arrays typically run 15-20 points above conventional ultrasonic equipment due to Japanese supplier concentration and qualification complexity. Pricing stratifies across megasonic premium, ultrasonic standard, and aqueous chemistry economy tiers based on node compatibility and acoustic frequency specifications. Cost compression in ultrasonic segments is intensifying because Chinese domestic manufacturers are qualifying lower-frequency systems for mature node fabs. IDMs show least price sensitivity due to total cost of ownership optimization priorities, while emerging foundries in China's Yangtze River Delta corridor negotiate hardest on upfront capital expenditure.
Supply Chain Analysis
Dual-sourcing requirements for megasonic transducer components are now standard procurement policy at Samsung and SK Hynix after supply disruptions from single Japanese suppliers. Manufacturing concentrates in Japan, South Korea, and Taiwan for precision acoustic components, with Germany and the United States supplying specialized solvent recovery systems. The supply chain rests on high-purity quartz for transducer housings, sub-ppb grade solvents, and ISO Class 1-compatible stainless steel alloys. Single-source vulnerability persists in 800kHz-1MHz transducer arrays where only two qualified suppliers operate. Distribution runs through direct OEM relationships for foundry customers and regional service partners for IDM maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in semiconductor POD cleaning equipment hinges on chemistry consumption pull-through from installed base growth and the shift toward predictive maintenance service tiers that capture recurring revenue above discrete hardware sales.
For Market Incumbents: Extend megasonic technology roadmaps to 2nm node qualification before Chinese competitors close the acoustic frequency gap. Deepen captive chemical supply capabilities to defend against foundry unbundling trends that separate hardware from consumables procurement. Anchor defensive positioning through predictive maintenance software integration that locks in recurring service revenue streams. For New Entrants and Emerging Players: Launch via aqueous chemistry specialization targeting China's Yangtze River Delta memory fabs where MEE dual carbon incentives accelerate environmental permitting for water-based formulations. White-space opportunity concentrates in solvent recovery system retrofits for mature ultrasonic fleets in domestic Chinese foundries. Penetrate through localized service partnerships that bypass established OEM maintenance networks. For Investors and Strategic Acquirers: Asymmetric upside sits with megasonic technology specialists possessing qualified transducer supply relationships and advanced node process window exclusivity. Long-term viability favors equipment suppliers with backward integration into chemical formulation and software-defined service architectures. Watch for inflection signals in ECHA REACH authorization timelines that would accelerate aqueous chemistry substitution and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Chemical Recycling Deployment | EPA VOC compliance in Arizona and Texas fabs reduces regulatory burden and chemistry input costs. |
| Megasonic Transducer Frequency Extension | 2nm node qualification at Samsung Pyeongtaek creates process window exclusivity against ultrasonic alternatives. |
| Predictive Maintenance Platform Integration | Vibration sensing and bath analytics at TSMC Hsinchu reduce chemistry consumption per cleaning cycle. |
| Aqueous Formulation Qualification Acceleration | MEE permitting incentives in Shanghai corridor reward water-based chemistry adoption for domestic memory ramp-ups. |
| Regional Service Infrastructure Buildout | Dedicated maintenance hubs in Greater Phoenix support emerging fab clusters with ISO Class 1-certified technician pools. |
Research Methodology
Multiple input streams — primary interviews with fab engineering directors and cleanroom operations managers, secondary validation through SEMI equipment shipment databases and EPA emission disclosure filings, plus customs trade data on high-purity chemical imports — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included process module engineers at foundry operators, procurement leads at integrated device manufacturers, aftermarket service heads at wet-process equipment specialists, and regulatory affairs directors navigating REACH authorization timelines. Secondary sources encompassed ECHA substance evaluation calendars, Korean Ministry of Environment effluent standards, and China MEE dual carbon policy implementation guidelines.
Data-stream reconciliation across equipment unit shipments, chemistry consumption volumes, and service contract values informed the analytical framework over the projection horizon. Segmentation dimensions modeled include acoustic frequency tier, formulation chemistry type, end-user scale category, and regional regulatory cluster. CAGRs were derived from installed base growth projections and cleaning cycle frequency assumptions tied to node migration timelines. Industry-specific forecast inputs incorporated megasonic technology penetration curves and aqueous chemistry substitution elasticities responding to REACH authorization risk.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH substance withdrawal or geopolitical disruption to Japanese transducer supply. Deviation in ECHA's perfluorinated surfactant authorization timeline would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Cleanroom Technologies Market
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
Semiconductor Capital Equipment Market
Semiconductor Equipment
Semiconductor LPCVD Furnaces Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market
Semiconductor Equipment
Global Photoresist Market
Semiconductor Equipment
Sputtering Equipment Cathode Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Global SMT Placement Equipment Market
Semiconductor Equipment
Vacuum Chambers Market
Semiconductor Equipment
Africa Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
Europe Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Slide Processing System Market
Semiconductor Equipment
Semiconductor Photolithography Equipment Market
Semiconductor Equipment
Lithography Equipment Market