
 High Temperature Capacitor Market | 2026-2036
High Temperature Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
High Temperature Capacitor Market Foresight
Buyer concentration in aerospace and defense procurement is hardening around suppliers with extended temperature qualifications and traceable supply chains. TDK Corporation leverages its ceramic formulation expertise to sustain qualification portfolios across multiple airframe programs. KEMET Corporation anchors its position through captive tantalum sourcing and MIL-PRF-55365 certification depth. Vishay Intertechnology competes by dominating thick-film ceramic production for downhole and turbine applications.
High temperature capacitors are passive electronic components engineered to operate reliably above 125°C, utilizing dielectric materials such as X8R ceramic, polyimide film, or anodized tantalum with electrolyte systems formulated for thermal stability. These components filter, couple, or store charge in environments where standard capacitors degrade through dielectric breakdown or electrolyte evaporation. Ceramic products lead volume due to established supply chains and cost scalability, while film capacitors capture expanding share in automotive inverter modules where self-healing properties matter. The aerospace end-user segment commands premium positioning through qualification barriers, whereas industrial motor drive applications represent the fastest-growing volume pool as electrification extends into heavy process equipment.
FAA airworthiness directives and EASA certification standards enforce thermal cycling test protocols that determine supplier eligibility for primary flight systems. EPA REACH compliance and EU RoHS substance restrictions shape material selection for dielectric formulations and termination finishes. NHTSA functional safety requirements under ISO 26262 extend temperature validation into automotive traction inverters. Stakeholders must monitor how dual-use export controls and defense procurement localization reshape qualified supplier lists across NATO and Indo-Pacific defense industrial bases.
Market Dynamics
EU F-Gas Regulation phase-down schedules are accelerating dielectric material transitions across industrial and automotive procurement channels, compressing supplier qualification timelines while opening substitution windows for polyimide film formulations.
Growth Catalysts
- EU Green Deal industrial electrification mandates:Heavy process equipment OEMs in Germany's Ruhr corridor are retrofitting motor drives with high-temperature film capacitors to meet decarbonization targets.
- Downhole drilling depth extension:Permian Basin operators now require 200°C-rated components for extended-reach laterals, pulling ceramic and tantalum capacitor demand into oilfield services.
- NHTSA ISO 26262 functional safety adoption:Automotive traction inverter suppliers are validating X8R ceramic stacks for thermal cycling endurance under ASIL-D requirements.
Market Restraints
- Tantalum ore supply concentration:Over 60% of capacitor-grade tantalum originates from Central African artisanal mining, exposing KEMET and AVX to conflict mineral traceability enforcement.
- Polyimide film resin shortage:DuPont and Ube Industries control aromatic polymer feedstock for high-temperature dielectric films, constraining capacity expansion.
- FAA thermal cycling test duration:Primary flight system qualification requires 5,000-hour operational validation, freezing new supplier entry for 18-24 months.
Strategic Opportunities
- India PLI scheme for power electronics:Domestic inverter manufacturing incentives are creating localized demand for 150°C-rated DC-link capacitors in Gujarat and Tamil Nadu industrial zones.
- Solid-state battery thermal management integration:Next-generation EV platforms are converging capacitor banks with coolant loops, opening module-level design partnerships.
- Direct-to-OEM digital procurement channels:Aerospace tier-1 suppliers are bypassing distribution to negotiate multi-year qualification contracts through vendor-managed inventory platforms.
Industry Challenges
- Materials science PhD scarcity:Formulation chemists with ceramic dielectric expertise are concentrated at TDK, Murata, and three Japanese national laboratories, constraining R&D team scaling.
- Dual-use export control reclassification:US Commerce Department ECCN shifts are delaying tantalum capacitor shipments to NATO defense contractors by 90-120 days.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Temperature Capacitor Market |
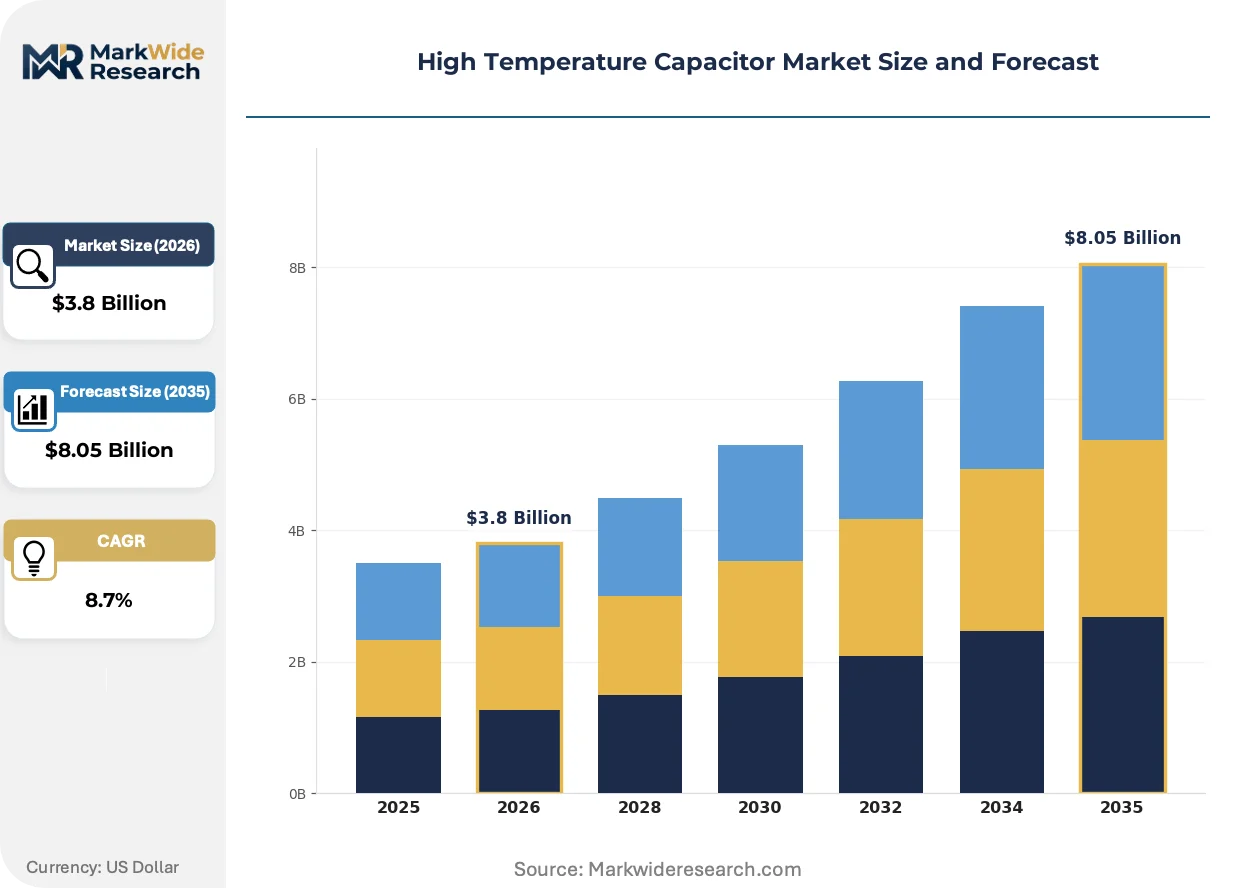
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic, Film, Aluminum Electrolytic, Tantalum Installation: Surface Mount, Through-Hole, Radial, Axial End User: Aerospace, Automotive, Industrial, Telecommunications Application: Power Supply, Motor Drives, Frequency Converters, High Voltage Systems |
| Companies Covered | KYOCERA AVX Components Corporation, TDK Corporation, KEMET Corporation, Johanson Dielectrics, Presidio Components, Vishay Intertechnology, Exxelia, Electrocube, Inc., Murata Manufacturing Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Temperature Capacitor Market Shifts & Advancements
Dielectric engineering and thermal interface design are converging to extend operational envelopes without sacrificing energy density, while procurement digitization compresses supplier selection cycles.
Hybrid ceramic-polyimide laminate construction is unifying the self-healing reliability of film with the volumetric efficiency of multilayer ceramic. Automotive inverter engineers at Bosch and Siemens are adopting these stacks for 800V architectures. The technology is unifying previously separate component categories into single-module thermal management solutions.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of electrolyte systems in wet tantalum capacitors. ECHA enforcement actions against non-compliant imports have redirected procurement toward Japanese and US suppliers with verified substance declarations. Industrial automation OEMs in Germany are now requiring full material disclosure as a contractual precondition.
Vendor consolidation among aerospace tier-1s has compressed the qualified supplier list from twelve to six dominant players over the past decade. Lockheed Martin and Raytheon now mandate dual-source arrangements with identical thermal qualification portfolios, forcing mid-tier capacitor manufacturers into expensive parallel certification tracks. This concentration is most visible in Phoenix and Tucson defense electronics clusters.
High Temperature Capacitor Market Segmentation
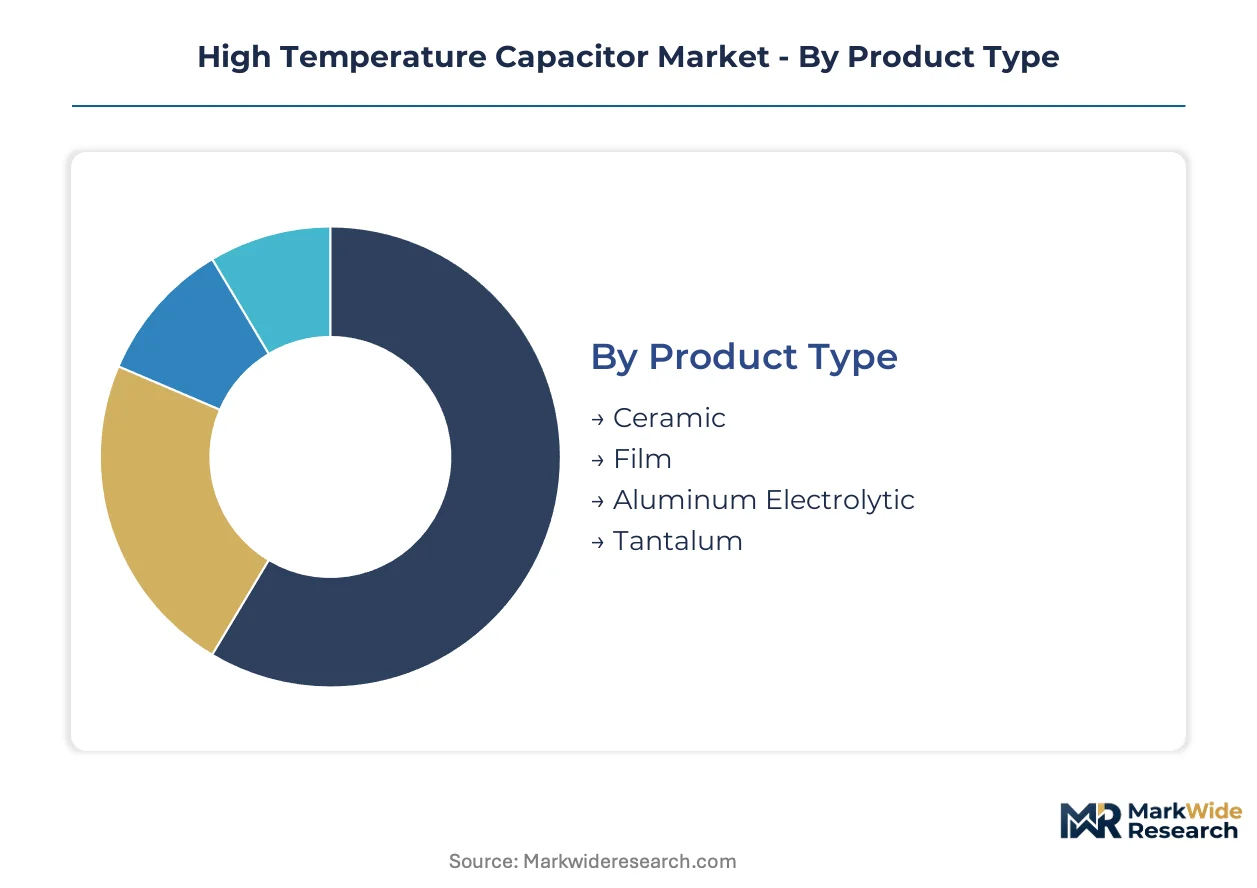
High temperature capacitor procurement splits sharply between volume-driven ceramic commoditization and premium-qualified film and tantalum segments. Installation methods and end-user specifications create incompatible qualification tracks that fragment supplier portfolios. Understanding where technical requirements harden versus where cost optimization dominates determines positioning strategy.
Product Type:
Ceramic dominates absolute shipment volumes while film and tantalum capture margin concentration in qualified applications.
- Ceramic:Multilayer ceramic capacitors utilizing X8R and C0G/NP0 dielectric formulations deliver the highest volumetric efficiency for temperatures up to 150°C. German industrial automation OEMs in the Ruhr corridor are standardizing on X8R stacks for motor drive inverters under EU Green Deal electrification mandates. Today's leader: Ceramic. Tomorrow's challenger: Film.
- Film:Polyimide and polyethylene naphthalate dielectric constructions provide self-healing failure modes essential for 800V automotive traction inverters. Bosch and Siemens inverter engineering teams are specifying these for ASIL-D functional safety compliance under NHTSA ISO 26262 adoption timelines. DuPont and Ube Industries resin supply constraints are capping expansion.
- Aluminum Electrolytic:Hybrid polymer and liquid electrolyte systems rated to 150°C serve cost-sensitive industrial power supplies where board space permits larger footprints.
- Tantalum:Wet and solid manganese dioxide constructions achieve 200°C operation for downhole drilling electronics in Permian Basin extended-reach laterals. Central African ore concentration exposes supply chains to conflict mineral traceability enforcement.
Film is climbing the fastest as automotive electrification prioritizes self-healing reliability over ceramic cost advantages.
Installation:
Mounting technology selection tracks thermal cycling severity and repair accessibility requirements across end-use environments.
- Surface Mount:Chip-scale ceramic and tantalum packages enable high-density assembly for aerospace avionics modules where FAA thermal cycling protocols demand 5,000-hour operational validation. Phoenix and Tucson defense electronics clusters specify these for primary flight systems.
- Through-Hole:Leaded construction survives mechanical stress in high-vibration turbine and downhole applications where solder joint fatigue would cripple surface-mount alternatives.
- Radial:Aluminum electrolytic and film capacitors with lead spacing optimized for industrial motor drive power supplies prioritize thermal dissipation over density.
- Axial:Cylindrical lead configurations suit legacy telecommunications equipment and replacement markets where board redesign costs prohibit surface-mount migration.
Surface Mount commands current design wins. Through-Hole retains irreplaceable positioning in extreme mechanical environments.
End User:
Qualification burden and procurement concentration vary dramatically across customer archetypes.
- Aerospace:FAA airworthiness directives and EASA certification standards enforce extended temperature validation that collapses qualified supplier lists to six dominant players. Lockheed Martin and Raytheon dual-source mandates force expensive parallel certification investments.
- Automotive:NHTSA functional safety requirements under ISO 26262 are extending thermal validation into traction inverters, pulling X8R ceramic and polyimide film demand from tier-1 suppliers.
- Industrial:Heavy process equipment OEMs in Germany's industrial automation corridor represent the steepest expansion trajectory as electrification retrofits multiply motor drive installations.
- Telecommunications:Base station and data center power supplies prioritize cost optimization over thermal extremes, sourcing standard-temperature components with minimal premium qualification.
Aerospace extracts maximum margin per unit. Industrial delivers expanding volume pools.
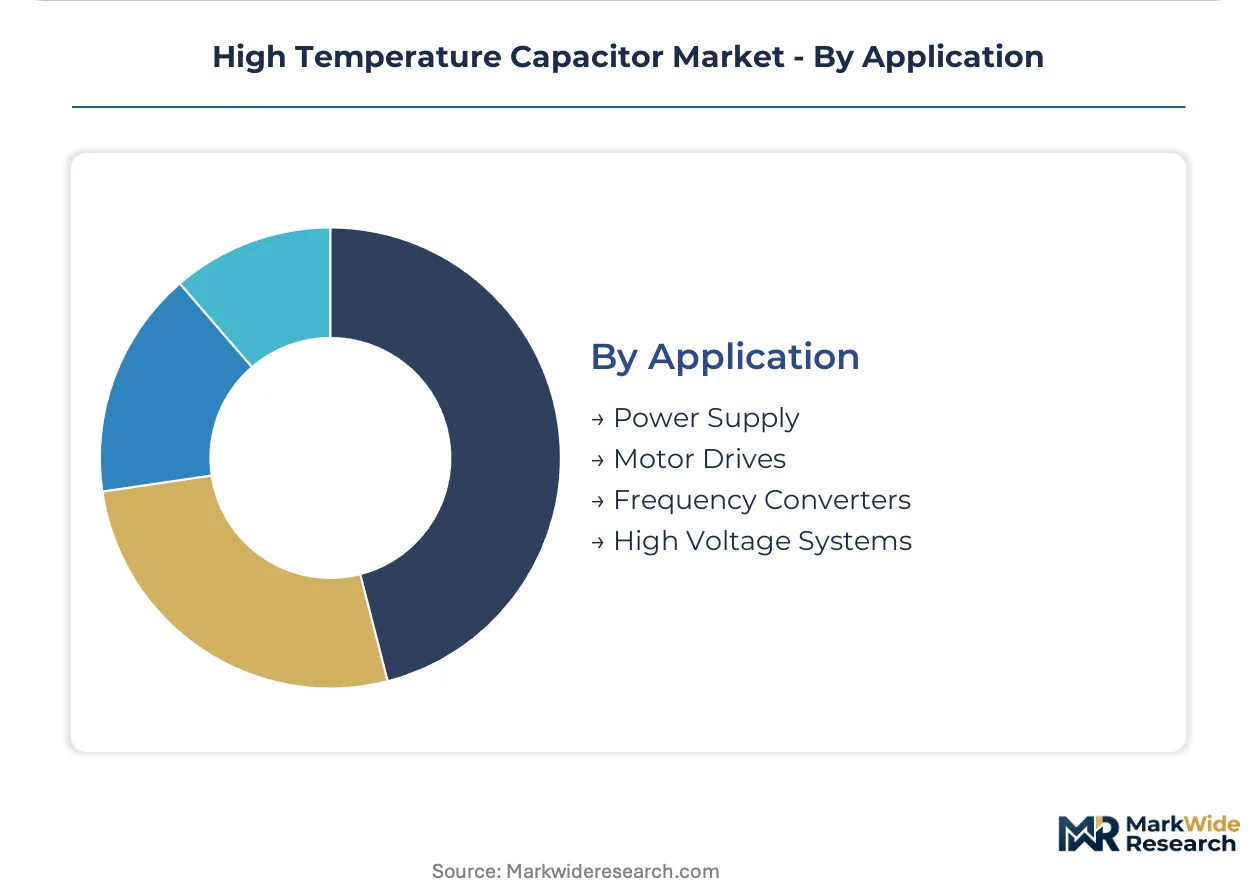
Application:
Functional role determines thermal cycling profile and dielectric stress characteristics.
- Power Supply:DC-link and filtering applications in industrial and telecommunications infrastructure prioritize ripple current handling and long service life over extreme temperature peaks.
- Motor Drives:Inverter output filtering for variable-frequency drives subjects capacitors to high dv/dt stress and thermal cycling as load conditions fluctuate. Germany's Ruhr corridor industrial electrification is concentrating demand here.
- Frequency Converters:Grid-tied and industrial converter applications require stable capacitance across wide temperature swings for power quality management.
- High Voltage Systems:Traction inverters, downhole tools, and aerospace power distribution push dielectric materials to voltage-temperature limits where partial discharge and ionic migration threaten reliability.
Motor Drives anchor present volume. High Voltage Systems define technical frontier requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States aerospace procurement concentrates around Phoenix and Tucson defense electronics clusters, while Germany's Ruhr corridor drives industrial automation demand through EU Green Deal electrification mandates. Japan anchors ceramic formulation expertise, India expands under PLI scheme incentives, and China's Yangtze River Delta integrates high-temperature components into EV traction systems.
United States
Defense electronics procurement concentrates in Arizona and Texas clusters where Lockheed Martin and Raytheon enforce dual-source qualification requirements. FAA airworthiness directives mandate 5,000-hour thermal cycling validation for primary flight systems, collapsing qualified supplier lists to six dominant players. Phoenix and Tucson defense electronics manufacturing corridors absorb premium-priced tantalum and ceramic components for aerospace power distribution.
Germany
Industrial motor drive electrification accelerates across the Ruhr corridor as heavy process equipment OEMs retrofit systems under EU Green Deal decarbonization timelines. ECHA REACH compliance and F-Gas Regulation phase-down schedules compress supplier qualification windows while opening substitution opportunities for polyimide film formulations. Siemens and Bosch inverter engineering teams in Baden-Württemberg specify ASIL-D validated components for 800V automotive architectures.
Japan
Ceramic dielectric formulation expertise concentrates at TDK, Murata, and three national laboratories, constraining R&D team scaling across the industry. METI industrial policy supports domestic capacitor manufacturing for automotive and industrial export markets. Tokyo and Osaka metropolitan areas host captive tantalum processing and multilayer ceramic stack production serving aerospace and defense contractors.
India
Domestic inverter manufacturing incentives under the PLI scheme generate localized demand for 150°C-rated DC-link capacitors in Gujarat and Tamil Nadu industrial zones. CEA power sector regulations and BIS certification requirements shape component specifications for grid-tied converter applications. Maharashtra and Karnataka electronics manufacturing clusters attract component suppliers establishing regional qualification capabilities.
China
EV platform thermal management integration drives demand for hybrid ceramic-polyimide laminate constructions in 800V traction inverter modules. MIIT automotive standards and GB certification protocols extend temperature validation requirements into domestic supply chains. Yangtze River Delta manufacturing corridors consolidate capacitor bank production with solid-state battery coolant loop integration partnerships.
High Temperature Capacitor Market Competitive Landscape
Japanese producers anchor the premium qualification tier; US specialists hold defense-aerospace positioning. The vendor base fragments across ceramic commoditization and qualified film-tantalum premium segments. Three archetypes dominate: formulation-led ceramic specialists, captive-sourced tantalum suppliers, and hybrid dielectric innovators. Competitive moves center on parallel certification investments for dual-source mandates and vendor-managed inventory platform deployment for direct aerospace procurement.
Within the premium qualification tier, TDK Corporation and KEMET Corporation exemplify archetype differentiation through dielectric expertise and captive material sourcing respectively. Vishay Intertechnology occupies a position among thick-film ceramic producers serving downhole and turbine applications. Murata Manufacturing Co., Ltd. anchors Japanese formulation capabilities alongside national laboratory partnerships. KYOCERA AVX Components Corporation sits within the tantalum supply chain concentration exposed to Central African ore sourcing complexities.
| Leading Market Players |
|---|
| KYOCERA AVX Components Corporation |
| TDK Corporation |
| KEMET Corporation |
| Johanson Dielectrics |
| Presidio Components |
| Vishay Intertechnology |
| Exxelia |
| Electrocube, Inc. |
| Murata Manufacturing Co., Ltd. |
| Others |
Supply & Pricing Matrix
Formulation chemists with ceramic dielectric expertise concentrate in Japan's Kansai region and Tokyo metropolitan laboratories, creating labor-cost differentials that widen spreads between premium-qualified and standard-grade capacitor tiers. These specialized workforce pools command compensation premiums that feed directly into pricing structures for aerospace and automotive qualification tracks.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for commodity-grade ceramic stacks while premium film and tantalum segments hold firm. Three-tier pricing structure across aerospace-qualified, automotive-validated, and industrial-economy levels separates segments by certification depth and thermal cycling test duration. Cost compression in standard ceramic grades is intensifying because Chinese producers are expanding multilayer stack output for motor drive applications. Industrial automation OEMs in Germany's Ruhr corridor exhibit highest price sensitivity, whereas Phoenix and Tucson defense electronics clusters absorb premium markups for traceable supply chains.
Supply Chain Analysis
Direct-to-OEM channels handle aerospace tier-1 procurement through vendor-managed inventory platforms, bypassing traditional distribution. Raw material supply draws from Central African tantalum ore deposits, Japanese ceramic powder formulations, and DuPont aromatic polymer feedstock for polyimide films. Geographic concentration in Japan, China, and Germany creates single-source vulnerability for qualified dielectric formulations. Distribution runs through specialized electronics distributors for industrial and automotive segments, with long-term offtake agreements dominating defense procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation phase-down schedule compounds demand for polyimide film substitutions, creating procurement urgency across industrial and automotive channels. This regulatory milestone accelerates supplier qualification timelines while compressing substitution windows.
For Market Incumbents: Deepen captive tantalum sourcing arrangements to insulate against Central African conflict mineral traceability enforcement. Expand parallel certification investments for Lockheed Martin and Raytheon dual-source mandates, which now require identical thermal qualification portfolios from competing suppliers. Vertical integration into aromatic polymer feedstock production reduces exposure to DuPont and Ube Industries capacity constraints. For New Entrants and Emerging Players: EU Green Deal industrial electrification mandates in Germany open a window for polyimide film capacitor suppliers to penetrate motor drive retrofit markets. Target India's PLI scheme power electronics incentives in Gujarat and Tamil Nadu industrial zones, where domestic inverter manufacturing generates localized demand for 150°C-rated DC-link components. Pursue module-level design partnerships with solid-state battery thermal management integrators as the primary go-to-market angle. For Investors and Strategic Acquirers: Aerospace and defense contractors are the most active acquirer in this space, seeking to secure qualified supplier capacity for primary flight systems. Mid-tier ceramic specialists with existing FAA thermal cycling test progress represent the optimal acquisition archetype over the coming decade. Watch for ECCN reclassification delays in US Commerce Department export controls as the inflection indicator for supply chain disruption severity.| Strategic Initiative | Industry Significance |
|---|---|
| Parallel Certification Investment | Dual-source mandates from Lockheed Martin and Raytheon force expensive simultaneous qualification tracks. |
| Captive Tantalum Sourcing | Upstream control over Central African ore supply mitigates conflict mineral traceability enforcement exposure. |
| Polyimide Film Capacity Expansion | EU F-Gas Regulation accelerates dielectric transitions, opening substitution windows for qualified suppliers. |
| Vendor-Managed Inventory Platform | Direct-to-OEM digital procurement channels compress supplier selection cycles for aerospace tier-1s. |
| Hybrid Dielectric R&D Partnership | Bosch and Siemens inverter engineering teams adopt ceramic-polyimide laminates for 800V architectures. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ceramic formulation chemists, aerospace procurement directors, automotive inverter engineers, and industrial motor drive OEMs with secondary validation. Trade data from customs filings, ECHA REACH substance declarations, FAA airworthiness directives, and SEC supplier disclosures anchored supply chain mapping. Bottom-up shipment tallies by dielectric type and installation method triangulated against top-down end-use demand estimates.
Comparable historical periods anchored growth trajectory modeling across the projection horizon. Segmentation dimensions included dielectric formulation, mounting technology, end-user qualification tier, and regional regulatory cluster. CAGRs derived from fitted trend analysis incorporating EU Green Deal electrification timelines, NHTSA ISO 26262 adoption curves, and defense procurement localization patterns. Industry-specific inputs encompassed tantalum ore supply concentration indices and thermal cycling test duration requirements.
Revisions become necessary when dual-use export control reclassifications, polyimide resin supply disruptions, or FAA qualification standard updates materialize. Forecasts reflect documented assumptions regarding ECHA enforcement intensity and PLI scheme incentive continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Household Appliances Electric Commutators Market
Electronic Components
Capacitor Kits Market
Electronic Components
Global Ethernet Controller Market
Electronic Components
SAW Filters Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
Trackpad Market
Electronic Components
Structural Electronics Market
Electronic Components
Wearable Technology Component Market
Electronic Components
Camera Battery Charger Market
Electronic Components
Audio DSP Market
Electronic Components
Stretchable and Conformal Electronics Market
Electronic Components
Wireless Charging Stand Market
Electronic Components
Industrial Relays Market
Electronic Components
Dual Relay Board Market
Electronic Components
Lead Zirconate Titanate (PZT) Market
Electronic Components
Flexible Heater Market