
 Loudspeaker Market | 2026-2036
Loudspeaker Market Size, Share, and Industry Trends Forecast 2026-2036
Loudspeaker Market Intelligence
Market Context
Direct-to-consumer streaming is reshaping how loudspeaker brands build recurring revenue beyond hardware sales. Bose Corporation leverages its retail footprint and proprietary spatial audio algorithms to sustain premium positioning across home theater installations. Samsung Electronics anchors its multi-room ecosystem through tight integration with its display and mobile product lines. Sony Group Corporation differentiates by controlling both content libraries and playback hardware, creating stickier consumer relationships than standalone speaker rivals.
Technical Definition and Segment Structure
A loudspeaker is an electroacoustic transducer that converts electrical audio signals into sound waves through the mechanical motion of a diaphragm, typically employing voice coils, permanent magnets, and enclosure designs tuned for specific frequency response profiles. Its primary commercial purpose spans entertainment reproduction, public address, professional monitoring, and increasingly, spatial audio rendering in vehicle cabins and immersive venues. Bluetooth-enabled personal audio and wireless home theater configurations represent the fastest-expanding technology-application intersection, while wired professional audio installations retain the deepest margin pools due to calibration services and long replacement cycles. Active loudspeakers with onboard amplification are displacing passive designs in consumer channels as room-correction DSP and streaming integration become baseline expectations rather than premium add-ons.
Regulatory Environment
The EU Ecodesign for Energy-related Products directive and REACH chemical restrictions constrain material choices and standby power budgets for loudspeakers sold across European markets. The FCC in the United States governs RF emissions for wireless audio protocols, while China's MIIT certifies Bluetooth and Wi-Fi implementations through compulsory GB standard testing. Stakeholders must monitor how evolving right-to-repair mandates in multiple jurisdictions affect sealed-unit designs and driver replacement economics.
Market Dynamics
Active loudspeakers with integrated DSP and streaming modules are collapsing the traditional separation between source, amplification, and transducer functions, forcing manufacturers to master semiconductor sourcing and software development alongside acoustic engineering.
Growth Catalysts
- EU Ecodesign standby power limits:Manufacturers redesigning power management circuits to meet tightening networked audio equipment standards are simultaneously unlocking battery-powered portable product lines.
- Immersive cabin audio in electric vehicles:Chinese EV OEMs specify multi-channel spatial audio as standard equipment, creating specification pull-through for premium driver and DSP suppliers.
- Bluetooth LE Audio and Auracast:Public venues and hearing assistance applications are adopting broadcast audio protocols that eliminate pairing friction and expand addressable installation base.
Market Restraints
- Rare earth magnet supply concentration:Neodymium processing capacity clusters in China, exposing driver manufacturers to export restriction risk and price volatility.
- REACH substance restrictions:Substitution of legacy flame retardants and phthalates in enclosure materials forces reformulation cycles that extend product development timelines.
- Voice coil copper price sensitivity:Motor assembly costs track London Metal Exchange copper futures, compressing margins on entry-level consumer segments.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Contract manufacturers establishing speaker assembly capacity gain duty advantage on exports to Middle East and Africa markets.
- Ambient computing audio endpoints:Smart home platforms integrating invisible ceiling and furniture-integrated transducers expand architectural audio specification channels.
- Right-to-repair mandates in France and Germany:Modular driver designs with standardized connectors capture regulatory preference in institutional procurement.
Industry Challenges
- Acoustic measurement engineering shortage:Fewer university programs graduate transducer designers with combined electroacoustic and DSP competency.
- Wireless protocol certification backlog:FCC and MIIT testing queue delays for Wi-Fi 6E and Bluetooth 5.3 implementations compress product launch windows.
- Legacy analog integration complexity:Professional installers face training costs bridging Dante/AES67 networked audio with existing copper infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loudspeaker Market |
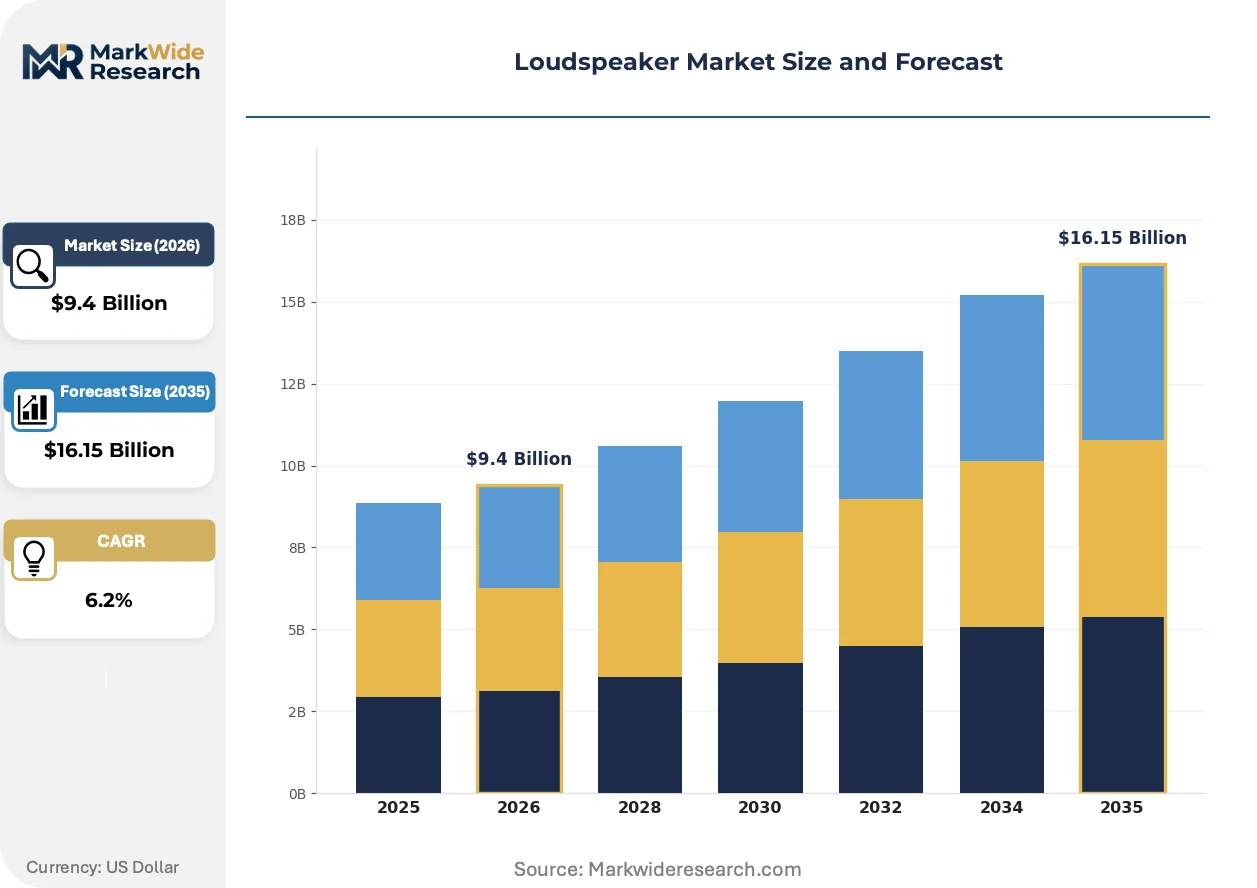
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.15 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Active, Passive, Subwoofer, Soundbar Technology: Bluetooth, Wi-Fi, Wired, NFC Application: Home Theater, Professional Audio, Personal Audio, Automotive End User: Consumers, Commercial, Educational, Event Organizers |
| Companies Covered | Panasonic Corporation, Sennheiser Electronic, Bose Corporation, Sonos, LG Electronics, Samsung Electronics, Yamaha Corporation, Harman International, Sony Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loudspeaker Market Strategic Shifts & Innovations
Beamforming and spatial audio rendering are migrating from cinema and automotive into residential and commercial installations, compressing hardware requirements while raising software content value.
Silicon carbide (SiC) power semiconductors in Class-D amplifier stages are collapsing thermal management requirements and enclosure volume for high-output active loudspeakers. Pro audio rental companies and fixed installation contractors are specifying these amplifiers for reduced truck pack volume and HVAC load. The technology is collapsing the traditional trade-off between output capability and physical footprint that constrained portable PA design.
REACH candidate list expansion for persistent organic pollutants is forcing reformulation of cone surround materials and cabinet adhesives used in European market products. Manufacturers qualifying alternative elastomers face 18-24 month validation cycles for fatigue and environmental stability. Professional monitor suppliers serving EU broadcast and studio markets are absorbing these compliance costs ahead of consumer divisions.
Subscription-based room calibration and DSP update services are displacing one-time hardware sales in residential channels. Installer networks in North American custom integration channels are bundling these recurring revenue streams with initial equipment specification. The model concentrates most rapidly in high-net-worth residential markets where acoustic treatment budgets exceed hardware expenditure.
Loudspeaker Market Segmentation
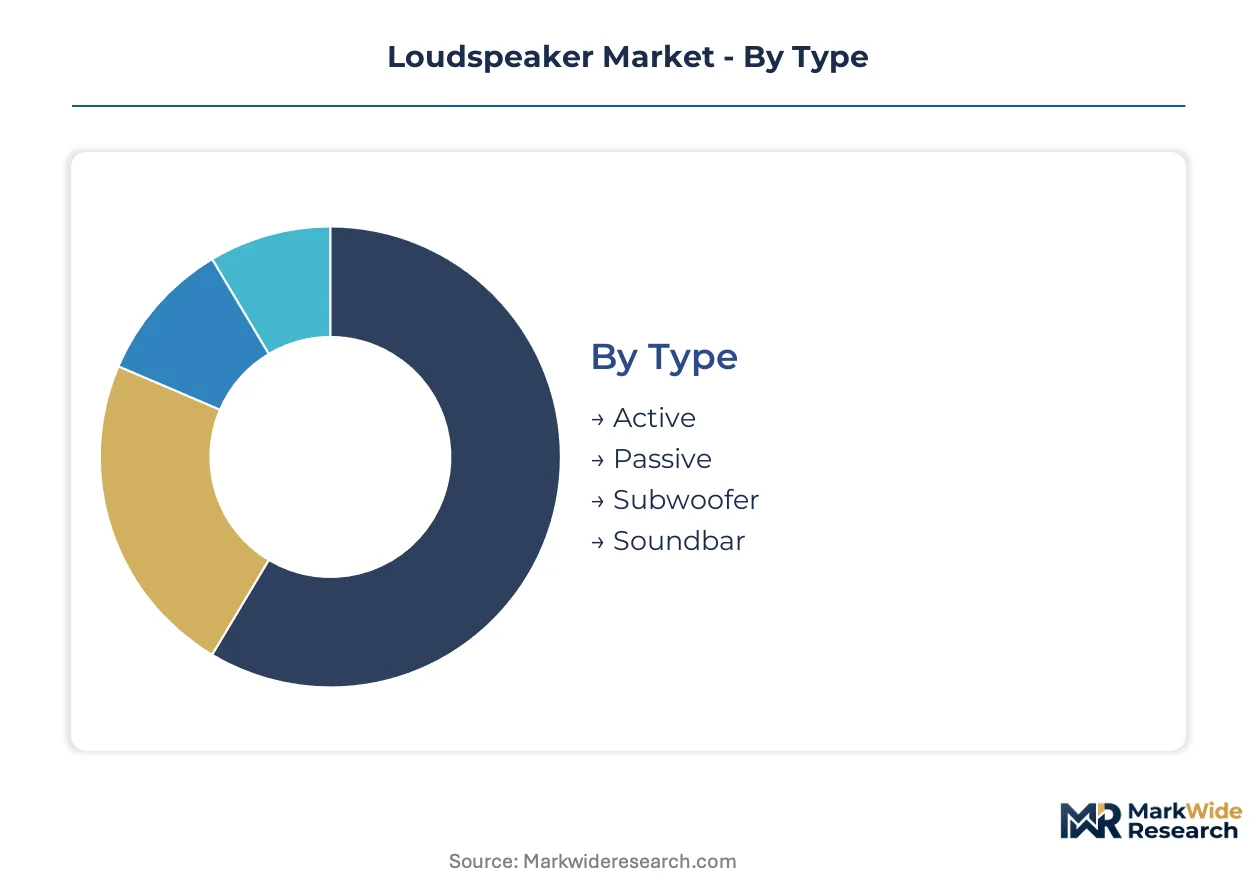
Segmentation in the loudspeaker market reveals how technology integration and end-use specialization drive divergent margin structures. Active designs with embedded amplification command premium positioning in residential channels, while passive configurations retain institutional preference where customization and longevity outweigh convenience.
Type:
Mature passive architectures coexist with emerging active platforms that collapse traditional component boundaries.
- Active:Integrated amplification and DSP processing eliminate external receiver requirements while enabling room-correction algorithms and streaming module embedding. Chinese EV manufacturers specify active multi-channel arrays as standard cabin equipment, pulling through premium driver and amplifier sourcing. Active designs retain volume leadership; Subwoofer holds the steepest expansion curve.
- Passive:Separate amplification requirements sustain professional monitor and high-end audiophile segments where component upgradability and repairability outweigh all-in-one convenience. European right-to-repair mandates reinforce specification preference for field-serviceable passive configurations in institutional procurement.
- Subwoofer:Dedicated low-frequency reproduction units anchor immersive audio configurations across home theater and automotive spatial audio systems.
- Soundbar:Integrated horizontal form factors address space-constrained residential installations with simplified wiring and virtual surround processing.
Active loudspeakers concentrate revenue in consumer channels; Subwoofer applications are expanding most quickly through automotive and cinema installations.
Technology:
Wireless protocols are displacing copper infrastructure across price tiers while wired installations defend margin in latency-critical professional environments.
- Bluetooth:LE Audio and Auracast broadcast capabilities eliminate pairing friction for public venue and hearing assistance deployments. Battery-powered portable product lines leverage Bluetooth power efficiency to meet EU Ecodesign standby limits while expanding outdoor and travel addressable markets.
- Wi-Fi:Higher bandwidth enables lossless streaming and multi-room synchronization across residential ecosystems. Whole-home audio specifications in North American custom integration channels favor Wi-Fi mesh architectures for whole-property coverage.
- Wired:Dante and AES67 networked audio protocols dominate broadcast, live sound, and installed professional markets where latency and reliability constraints exclude wireless alternatives.
- NFC:Tap-to-pair functionality reduces friction in hospitality and retail demonstration environments.
Wired technology retains margin leadership in professional channels; Bluetooth gains share fastest through portable and automotive accessory expansion.
Application:
Automotive and personal audio applications are climbing the fastest as immersive cabin specifications and mobile consumption reshape hardware requirements.
- Home Theater:Multi-channel spatial audio configurations with height channels and subwoofer integration anchor premium residential specification. Dolby Atmos and DTS:X decoding requirements drive active soundbar and satellite speaker replacement cycles.
- Professional Audio:Fixed installation and rental markets demand networked DSP, weatherized enclosures, and flight-case durability. Silicon carbide amplifier adoption reduces truck pack volume and HVAC load for touring applications.
- Personal Audio:Portable Bluetooth speakers and true wireless stereo pairs address mobile consumption and outdoor use cases.
- Automotive:Electric vehicle platforms integrate multi-channel spatial audio as standard equipment, with Chinese OEMs leading specification intensity for immersive cabin experiences.
Professional Audio commands the deepest margin pools; Automotive represents the steepest expansion trajectory through EV platform audio integration.
End User:
Commercial procurement patterns diverge sharply from consumer purchasing on durability specifications and service contract structures.
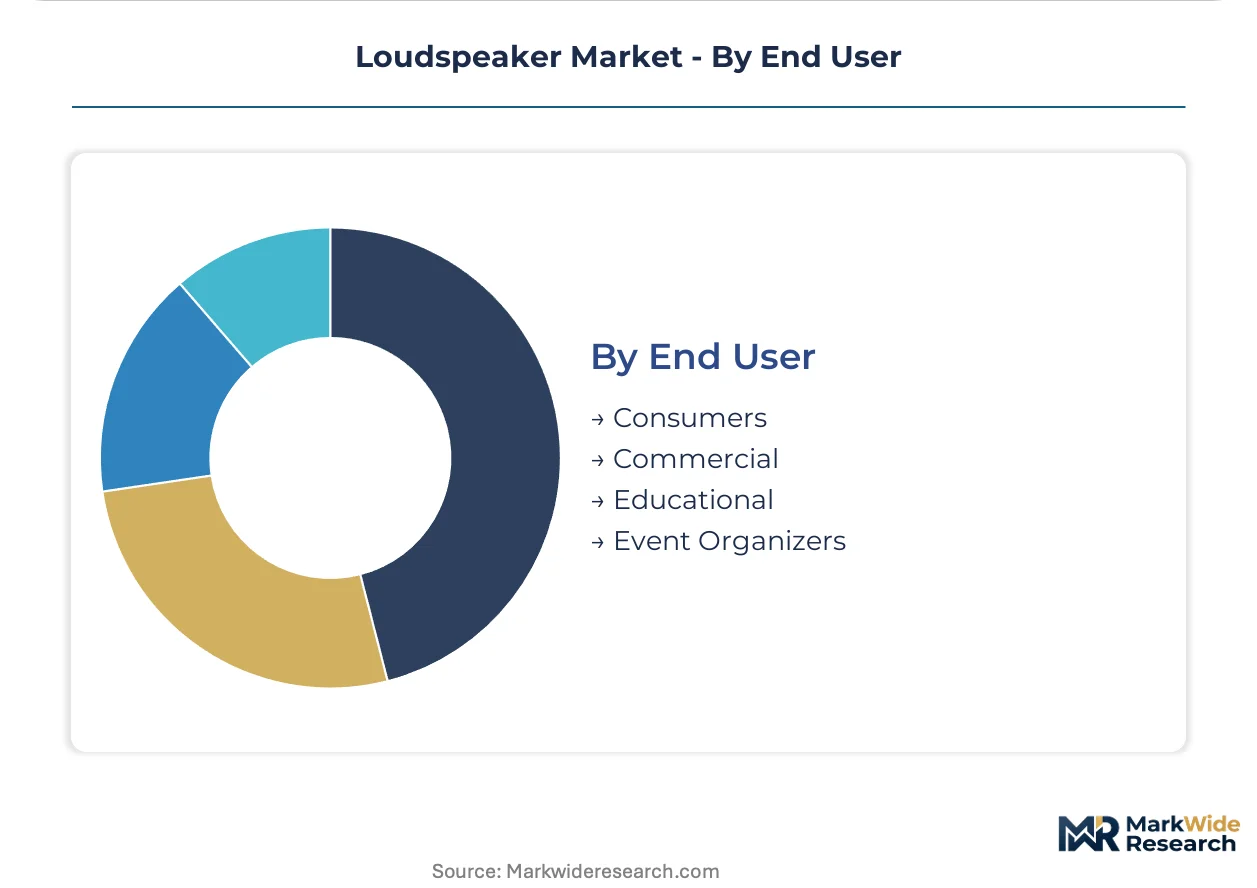
- Consumers:Direct-to-purchase channels emphasize design aesthetics, voice assistant integration, and streaming service compatibility. Subscription-based room calibration services are displacing one-time hardware transactions in high-net-worth residential markets.
- Commercial:Corporate, hospitality, and retail installations prioritize networked manageability, extended warranty terms, and centralized monitoring. India's PLI scheme for electronics manufacturing attracts contract assembly capacity serving Middle East and Africa export markets.
- Educational:K-12 and higher education procurement emphasizes durability, theft resistance, and simplified operation for non-technical staff.
- Event Organizers:Rental inventory demands rapid deployment, weather resilience, and standardized rigging compatibility across venue types.
Commercial end users drive professional channel volume; Consumers anchor the fastest-growing direct-to-consumer and subscription service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for electronics manufacturing is pulling assembly capacity toward South Asia, while EU Ecodesign directives reshape power management requirements across European supply chains. Chinese EV OEMs specify immersive cabin audio as standard equipment, accelerating premium driver sourcing from domestic and international suppliers.
United States
Residential spatial audio installations and professional touring markets drive demand for silicon carbide amplifier-equipped active loudspeakers. The FCC governs RF emissions for Bluetooth and Wi-Fi 6E implementations, with certification queues currently extending product launch timelines. Nashville and Los Angeles anchor professional audio engineering clusters where broadcast and studio monitor specifications concentrate.
China
Domestic EV brands including NIO, Li Auto, and Xpeng specify multi-channel spatial audio as standard cabin equipment, pulling premium DSP and driver sourcing. The MIIT certifies Bluetooth and Wi-Fi implementations through compulsory GB standard testing. Shenzhen and Dongguan host dense loudspeaker component manufacturing ecosystems serving both automotive OEMs and export markets.
Germany
Automotive Tier 1 suppliers engineer factory-installed premium audio systems for Mercedes-Benz, BMW, and Volkswagen electric platforms. The KBA oversees type approval for vehicle-integrated audio systems under UN ECE regulations. Stuttgart and Ingolstadt concentrate acoustic R&D facilities co-located with OEM headquarters.
India
Contract manufacturers establish speaker assembly capacity under the PLI scheme to capture duty advantages on Middle East and Africa exports. The BIS mandates ISI certification for electronic goods sold domestically. Tamil Nadu and Karnataka host emerging electronics manufacturing clusters where loudspeaker final assembly lines are scaling.
Japan
Specialist driver manufacturers supply precision transducers for professional monitor and high-end audiophile segments. METI oversees industrial standards alignment with international IEC frameworks. Tokyo and Osaka maintain legacy acoustic engineering expertise despite shrinking domestic consumer electronics assembly.
Loudspeaker Market Key Industry Players
On the supply side, the industry is consolidating around three strategic tiers: diversified electronics conglomerates with captive audio divisions, standalone acoustic specialists with deep transducer heritage, and automotive-focused Tier 1 suppliers. Japanese and Korean conglomerates leverage display and mobile ecosystem integration to anchor multi-room residential platforms. German and American specialists defend margin in professional channels through calibration services and long replacement cycles. Competitive moves concentrate on semiconductor sourcing partnerships for Class-D amplification and DSP modules, plus geographic expansion into Indian contract manufacturing.
Among diversified electronics conglomerates, Samsung Electronics and Sony Group Corporation exemplify ecosystem-anchored positioning, while Bose Corporation occupies a position within the premium standalone specialist tier. Samsung leverages tight integration across display, mobile, and home appliance portfolios to lock in multi-room audio specifications. Sony controls content libraries and playback hardware to create stickier consumer relationships than hardware-only rivals. Bose sustains premium positioning through proprietary spatial audio algorithms and retained retail footprint in North American custom integration channels.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Sennheiser Electronic |
| Bose Corporation |
| Sonos |
| LG Electronics |
| Samsung Electronics |
| Yamaha Corporation |
| Harman International |
| Sony Group Corporation |
| Others |
Cost & Logistics Intelligence
Shanghai-to-Rotterdam container freight corridors transmit cost volatility directly into loudspeaker landed costs, amplifying price spreads between China-sourced active assemblies and European-manufactured professional monitors while compressing margins on mid-tier consumer imports.
Pricing Analysis
Certification level creates the primary spread, with CE-marked and FCC-certified active loudspeakers commanding substantial premiums over uncertified gray-market alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by driver material grade and DSP sophistication. Pricing pressure stems from copper voice coil cost tracking London Metal Exchange volatility. Entry-level consumer segments exhibit acute price sensitivity, while professional studio monitor buyers prioritize calibration service bundles over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for loudspeaker manufacturers. Neodymium magnet processing concentrates in China, while precision driver assembly clusters in Japan and Germany. Raw material dependencies encompass rare earth magnets, copper voice coils, and silicon carbide semiconductors for Class-D amplification. Single-source vulnerability in neodymium supply exposes driver manufacturers to export restriction risk. Distribution runs through contract manufacturers in India leveraging PLI scheme benefits for Middle East and Africa re-export.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The loudspeaker market sits in a cyclical recovery phase as automotive OEMs replenish premium audio inventories following EV platform ramp-ups and deferred professional installation projects resume execution.
For Market Incumbents: Harden supply chain resilience by securing captive neodymium magnet sourcing through offtake agreements with Chinese processors or alternative rare earth development projects. Deepen backward integration into DSP semiconductor design to reduce dependence on external Class-D amplifier module suppliers. Prioritize certification investment for REACH-compliant enclosure materials ahead of EU candidate list expansion. For New Entrants and Emerging Players: Indian contract manufacturing capacity offers underpenetrated assembly footholds for export-oriented loudspeaker brands seeking PLI scheme duty advantages. Target the Middle East and Africa distribution channel with weatherized professional audio configurations adapted to high-temperature operating environments. Pursue white-label partnerships with Chinese EV OEMs seeking secondary audio supplier qualification. For Investors and Strategic Acquirers: Automotive-focused DSP specialists with validated cabin audio algorithms represent compelling acquisition targets as Tier 1 suppliers consolidate software-defined vehicle audio stacks. Long-term viability hinges on semiconductor sourcing relationships and automotive qualification timelines. Monitor Bluetooth LE Audio certification completion rates as an inflection indicator for broadcast audio market readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Amplifier Integration | Reduces thermal management requirements and enclosure volume for touring PA applications. |
| Backward Integration into DSP Design | Captures margin from streaming module and room-correction algorithm development. |
| India PLI Manufacturing Footprint | Secures duty advantages on Middle East and Africa export shipments. |
| REACH-Compliant Material Reformulation | Maintains EU market access as candidate list expands for persistent organic pollutants. |
| Bluetooth LE Audio Certification | Unlocks Auracast broadcast audio deployments in public venue and hearing assistance markets. |
Research Approach
A spread of perspectives from acoustic R&D directors, automotive Tier 1 procurement managers, professional audio rental company operators, and custom integration channel installers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against MIIT certification databases, FCC equipment authorization records, EU Ecodesign directive implementation guidance, and loudspeaker component trade flow data. Bottom-up demand modeling triangulated against top-down market sizing from electronics manufacturing value chain analysis.
Demand-supply balance dynamics anchored the forecast framework across the analysis window. Segmentation dimensions encompassed active versus passive architecture, wireless protocol technology, application vertical, and end-user procurement pattern. CAGRs derived from fitted growth curves calibrated to automotive audio content per vehicle trajectories and professional installation cycle recovery indicators. Input assumptions incorporated EV platform audio specification intensity, REACH substance restriction timelines, and India PLI scheme capacity buildout schedules.
Macroeconomic conditions sit as an overlay; deviation in container freight rates, copper futures, or rare earth export policy would shift the trajectory. Forecasts reflect documented assumptions about automotive production schedules and regulatory implementation timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Global Capacitor Market
Electronic Components
Global Circuit Protection Market
Electronic Components
VPX SBC Market
Electronic Components
Impulse Relays Market
Electronic Components
Class D Audio Amplifier Market
Electronic Components
Handheld Devices Battery Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
Laser Direct Structuring (LDS) Antenna Market
Electronic Components
Distribution Components Market
Electronic Components
North America MLCC Market
Electronic Components
Conductive Polymer Capacitor Market
Electronic Components
RAID Controller Card Market
Electronic Components
Printed Circuit Board Market
Electronic Components
AC Adapter Market
Electronic Components
Special Function Data Convertors Market
Electronic Components
Semiconductor Micro Components Market