
 Battery Fuel Gauge IC Market | 2026-2036
Battery Fuel Gauge IC Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Fuel Gauge IC Market Outlook
Modular battery management system architectures are repositioning how OEMs evaluate fuel gauge IC procurement, shifting from discrete component sourcing toward bundled subsystem contracts. Texas Instruments leverages its integrated portfolio to anchor premium design-ins across automotive and industrial verticals. Analog Devices competes on algorithm sophistication, sustaining R&D intensity in impedance-tracking methodologies. STMicroelectronics dominates European supply chains through manufacturing scale and channel control in Milan and Grenoble facilities.
A battery fuel gauge IC measures remaining charge capacity through coulomb counting, voltage correlation, or electrochemical impedance spectroscopy, typically operating at resolution thresholds below one percent error to prevent lithium-ion over-discharge. Integrated Circuits command the largest value pool due to silicon integration economies, while Hybrid technology variants are capturing design wins where analog precision meets digital configurability. Automotive applications sit at the fastest expansion trajectory as 800-volt architectures and cell-to-pack designs demand redundant gauging redundancy.
The EU Battery Regulation, EPA automotive emissions frameworks, and China's GB/T battery standards collectively shape compliance burdens that filter down to fuel gauge accuracy mandates and traceability requirements. FDA scrutiny of battery-powered medical devices further tightens tolerance specifications for implantable and portable diagnostic equipment. Stakeholders must monitor how solid-state battery chemistries disrupt existing state-of-charge algorithms and whether foundry capacity constraints in Taiwan and South Korea alter procurement timelines for automotive-qualified dies.
Market Dynamics
The Battery Fuel Gauge IC Market is experiencing structural pressure from the transition to 800-volt electric vehicle architectures, which demand redundant gauging systems and force IC vendors to recalibrate accuracy specifications for cell-to-pack designs.
Growth Catalysts
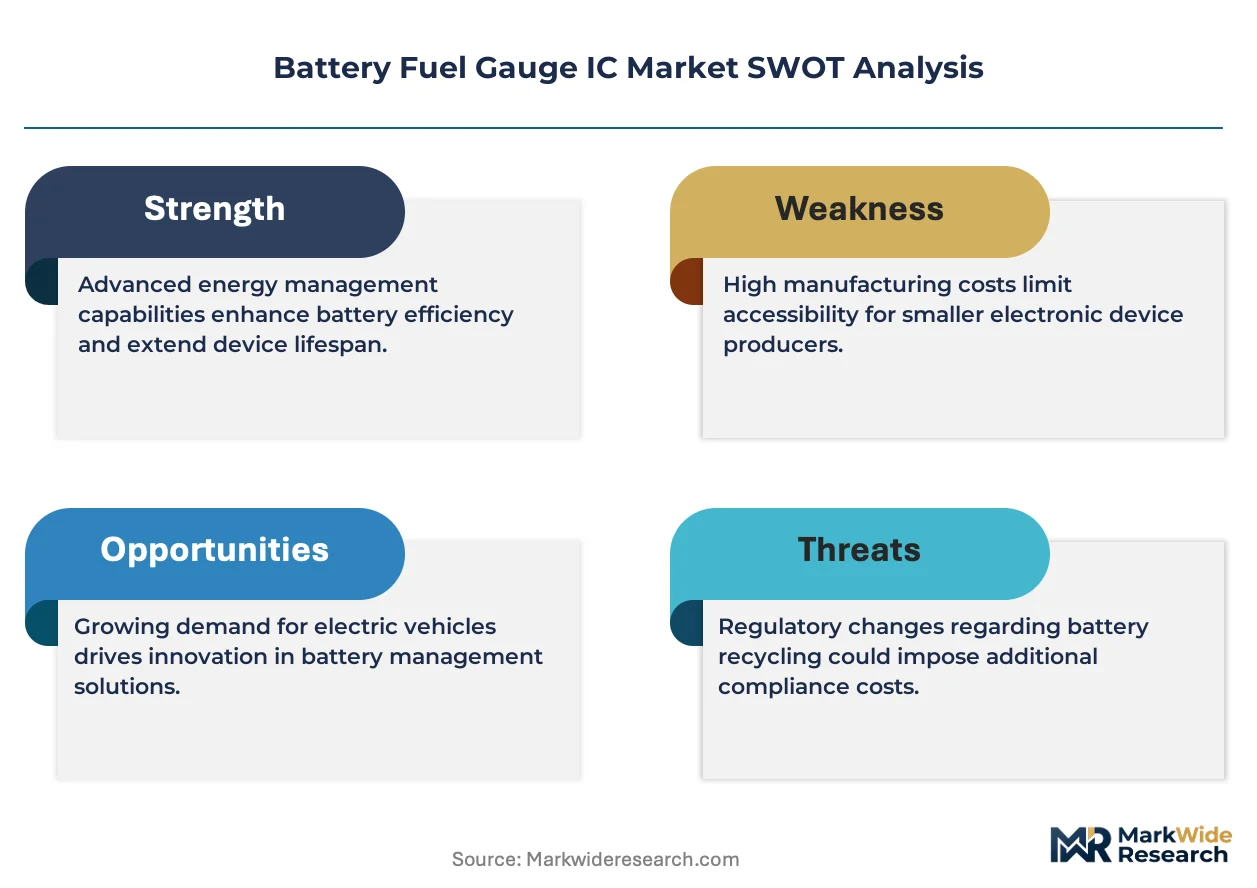
- EU Battery Regulation:Mandatory state-of-health disclosure requirements for rechargeable batteries sold in member states are forcing OEMs to upgrade fuel gauge precision, expanding demand for sub-one-percent error ICs.
- Electrochemical impedance spectroscopy:This measurement methodology is penetrating automotive battery management systems as manufacturers seek real-time aging diagnostics beyond traditional coulomb counting.
- China:Domestic EV production concentration and consumer electronics assembly dominance are consolidating procurement volumes toward vertically integrated battery pack suppliers.
Market Restraints
- Foundry concentration:Automotive-qualified die production depends on Taiwan and South Korea fabrication capacity, creating geographic single-point vulnerability for qualification timelines.
- Silicon integration economics:Hybrid technology variants face cost compression against monolithic ICs despite their analog-digital configurability advantages in precision applications.
- Solid-state chemistry disruption:Emerging solid-state battery formulations threaten to invalidate existing state-of-charge algorithms, forcing R&D redirection before commercial scale.
Strategic Opportunities
- Implantable medical devices:FDA tolerance tightening for battery-powered diagnostic equipment creates premium positioning for ultra-precise fuel gauge ICs with traceability documentation.
- Industrial energy storage:Grid-scale battery installations require predictive maintenance capabilities that impedance-tracking fuel gauges can monetize through service contracts.
- GB/T standards alignment:China's battery standard harmonization with automotive export requirements offers design-in pathways for IC vendors qualifying under dual regulatory frameworks.
Industry Challenges
- Algorithm engineering scarcity:Impedance-tracking methodology development requires electrochemical modeling expertise that competes with battery cell R&D for specialized talent pools.
- Dual qualification burden:Automotive AEC-Q100 and industrial IEC 61508 certification timelines run sequentially rather than in parallel, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Fuel Gauge IC Market |
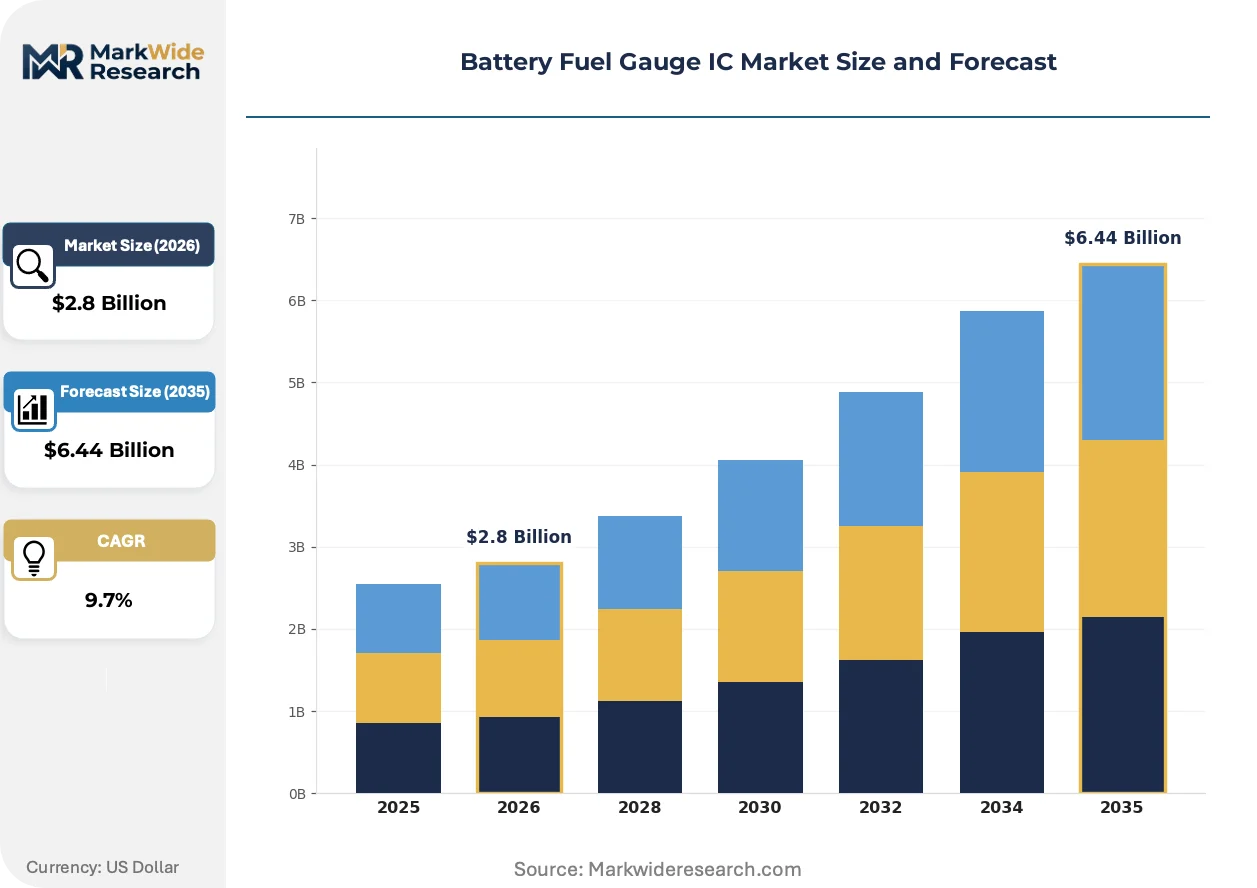
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Circuits, Discrete Components, Modules, Sensors Application: Consumer Electronics, Automotive, Industrial Equipment, Medical Devices End User: OEMs, Aftermarket Providers, System Integrators, Electronics Manufacturers Technology: Analog, Digital, Hybrid, Smart |
| Companies Covered | Texas Instruments, Analog Devices, Microchip Technology, Maxim Integrated, STMicroelectronics, NXP Semiconductors, ON Semiconductor, Renesas Electronics, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Fuel Gauge IC Market Strategic Shifts
Active consolidation across measurement methodologies and procurement models is compressing vendor margins while elevating algorithm sophistication as the primary differentiation axis. The competitive terrain favors integrated subsystem providers over discrete component specialists.
Electrochemical impedance spectroscopy is consolidating market position as the preferred methodology for lithium-ion state-of-health estimation in high-voltage automotive packs. Tier-1 battery management system suppliers are adopting this technique for 800-volt architectures, displacing voltage-correlation approaches in premium design-ins. The technology is consolidating R&D investment toward silicon integration that combines precision analog front-ends with embedded electrochemical models.
REACH substance restrictions and RoHS amendments are tightening material disclosure requirements for semiconductor packaging used in European-bound battery systems. Component suppliers must now document trace element composition through sub-tier supply chains, extending qualification documentation burdens. Medical device and automotive segments are responding by consolidating supplier bases toward vendors with pre-certified material libraries.
Design-in authority is migrating from discrete component selection toward subsystem specification, with OEMs delegating fuel gauge integration to battery pack assemblers. Tier-1 suppliers in China and Germany are capturing this decision-making role, compressing direct IC vendor relationships. This pattern is most visible in electric vehicle verticals where cell-to-pack designs eliminate module-level gauge redundancy.
Battery Fuel Gauge IC Market Segmentation
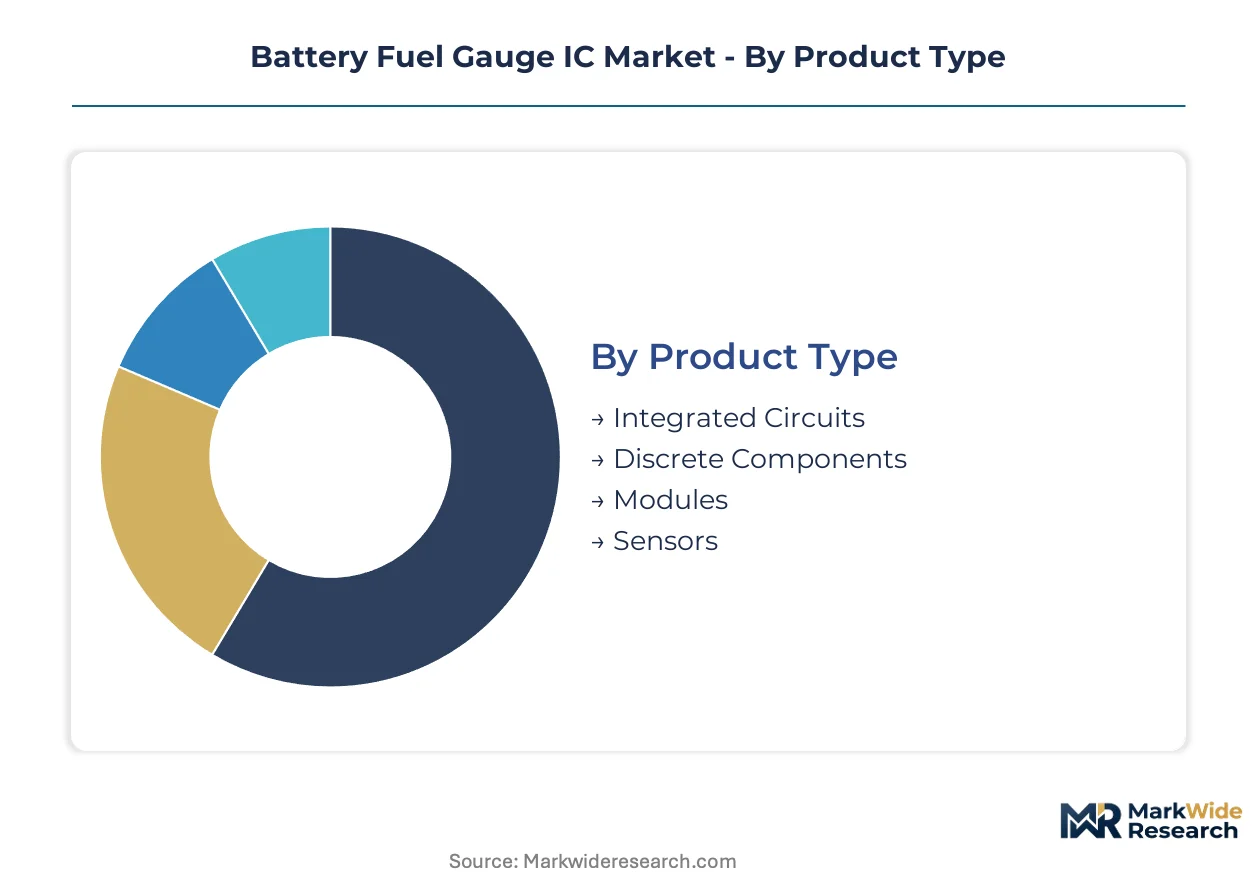
Segmentation in the Battery Fuel Gauge IC Market reveals how procurement authority migrates across value chain tiers and how measurement methodologies command premium positioning. Vendors must calibrate portfolio depth against the specific accuracy and integration requirements of each vertical.
Product Type:
Upgrade cycles in battery management architectures are compressing discrete component lifecycles while accelerating silicon integration roadmaps.
- Integrated Circuits:Monolithic silicon designs combine voltage sensing, coulomb counting, and temperature compensation on single dies. Automotive cell-to-pack designs in Germany and South Korea are consolidating procurement toward these devices to reduce BOM complexity and traceability documentation burdens.
- Discrete Components:Standalone voltage references, sense resistors, and analog front-ends persist in cost-optimized consumer electronics and legacy industrial retrofits. Chinese EMS providers maintain significant procurement volumes here for mid-tier smartphone and tablet designs where precision requirements sit below automotive thresholds.
- Modules:Pre-integrated gauge assemblies with embedded firmware and communication stacks. Demand concentrates in medical device manufacturing where FDA documentation requirements favor pre-certified subsystems over discrete component qualification.
- Sensors:Specialized electrochemical and thermal sensing elements for impedance spectroscopy implementations. Grid-scale energy storage installations in Texas and California are adopting these for predictive maintenance service contracts.
Integrated Circuits sits at the top of the volume ranking, with Sensors climbing the fastest.
Application:
Cost tier stratification separates premium precision requirements from commodity gauging functions across end-use verticals.
- Consumer Electronics:Smartphones, laptops, and wearables demand sub-one-percent error tolerance to prevent lithium-ion over-discharge failures. Procurement volumes concentrate through Shenzhen and Dongguan assembly clusters serving global OEM brands.
- Automotive:800-volt electric vehicle architectures require redundant gauging systems with AEC-Q100 qualification. Cell-to-pack designs in Stuttgart, Wolfsburg, and Shanghai are eliminating module-level redundancy in favor of pack-integrated precision.
- Industrial Equipment:Forklifts, robotics, and uninterruptible power systems prioritize cycle-life prediction over instantaneous accuracy. European industrial automation hubs in Munich and Milan specify impedance-tracking capabilities for fleet battery management.
- Medical Devices:Implantable cardiac devices and portable diagnostic equipment face FDA tolerance tightening for traceability documentation. OEMs in Minneapolis and Boston are consolidating supplier bases toward vendors with pre-certified material libraries under REACH and RoHS amendments.
Consumer Electronics commands the largest procurement volumes, while Automotive gains share fastest on electrification mandates.
End User:
Customer type determines whether fuel gauge selection resides with battery pack assemblers, system architects, or component distributors.
- OEMs:Original equipment manufacturers in automotive and medical verticals retain direct IC vendor relationships for critical safety systems. Tesla, BYD, and Medtronic maintain dedicated battery management engineering teams specifying gauge accuracy thresholds.
- Aftermarket Providers:Replacement battery pack suppliers for consumer electronics and industrial equipment source compatible gauge ICs through distribution channels. These buyers prioritize pin-compatible alternatives to minimize firmware redevelopment.
- System Integrators:Tier-1 battery management system suppliers in China and Germany are capturing design-in authority from OEMs. CATL and Samsung SDI now specify fuel gauge integration requirements for cell-to-pack designs delivered to automotive customers.
- Electronics Manufacturers:Contract EMS providers in Taiwan and Vietnam execute build-to-print contracts with limited component selection autonomy. Their procurement follows approved vendor lists established by OEM system architects.
System Integrators are displacing direct OEM procurement fastest, though Electronics Manufacturers still transact the highest unit volumes.
Technology:
Measurement methodology maturity separates established voltage-correlation approaches from emerging electrochemical modeling techniques.
- Analog:Voltage-based state-of-charge estimation through resistor networks and comparator circuits. Legacy implementations persist in cost-constrained consumer electronics where calibration complexity exceeds precision requirements.
- Digital:Firmware-implemented coulomb counting with microcontroller-based compensation algorithms. These dominate mid-tier applications where software configurability offsets analog precision limitations.
- Hybrid:Combined analog front-ends with digital signal processing and embedded electrochemical models. Automotive battery management systems in premium electric vehicles specify these for real-time aging diagnostics beyond traditional counting methods.
- Smart:AI-enhanced state estimation with cloud-connected model updates and predictive health forecasting. Industrial energy storage operators in California and Texas are piloting these for grid-scale predictive maintenance monetization.
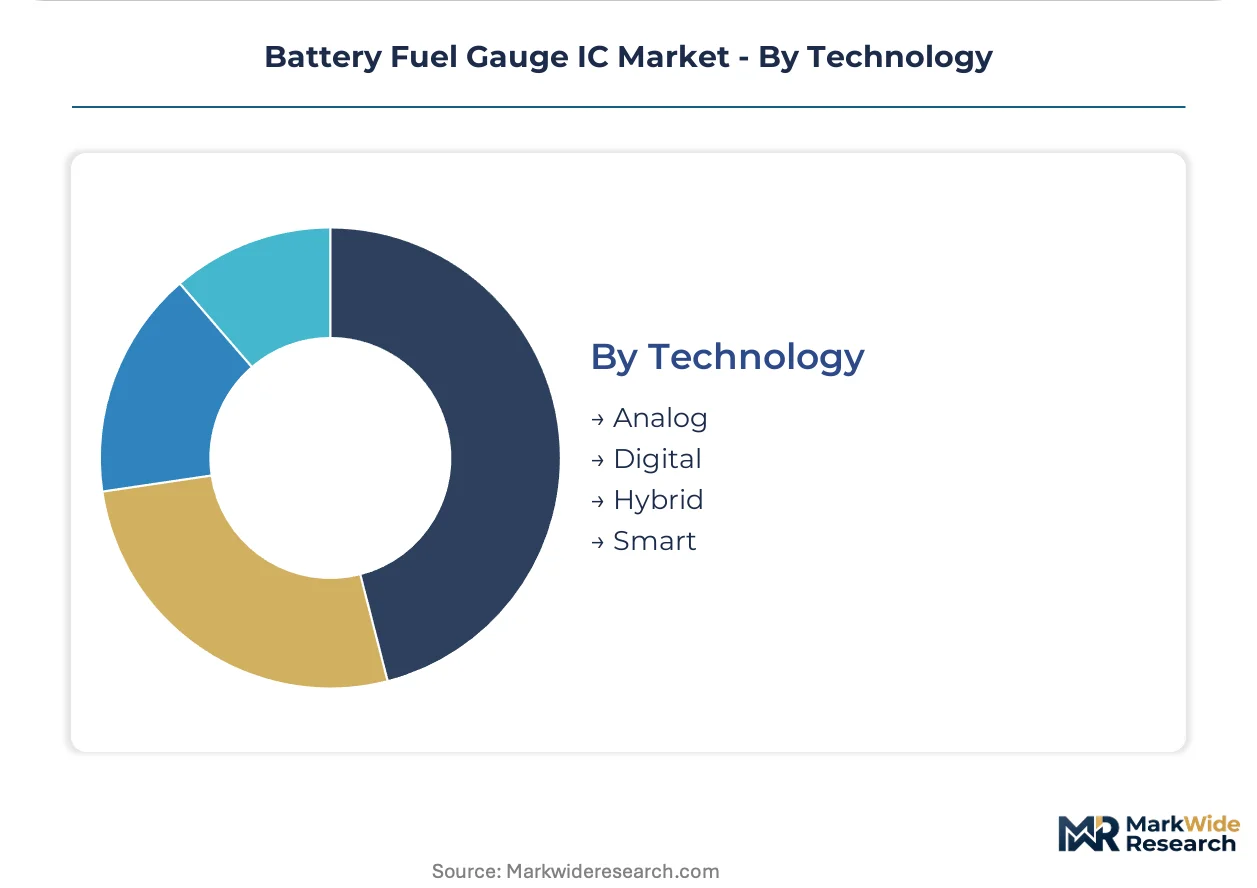
Hybrid technology holds the revenue concentration lead, with Smart implementations showing the steepest expansion trajectory in grid storage pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision battery management systems originated in German automotive engineering centers during the early hybrid vehicle era, then scaled through East Asian electronics manufacturing corridors. Today's procurement geography reflects this bifurcated heritage between European automotive qualification requirements and Asian volume production.
China
Domestic EV production concentration and consumer electronics assembly dominance concentrate fuel gauge IC procurement through vertically integrated battery pack suppliers. GB/T battery standards alignment with automotive export requirements creates dual-qualification pathways for IC vendors. Shenzhen and Dongguan assembly clusters execute the majority of global smartphone and laptop gauge integration.
Germany
Stuttgart and Wolfsburg automotive design centers specify AEC-Q100 qualified fuel gauges for 800-volt electric vehicle architectures with cell-to-pack redundancy elimination. EU Battery Regulation state-of-health disclosure mandates force sub-one-percent error tolerance upgrades across rechargeable battery systems. Munich industrial automation hubs demand impedance-tracking capabilities for fleet battery management.
United States
EPA automotive emissions frameworks filter down to fuel gauge accuracy mandates for electrified powertrains, while FDA scrutiny tightens tolerance specifications for Minneapolis and Boston medical device manufacturers. Grid-scale energy storage installations in Texas and California pilot AI-enhanced state estimation for predictive maintenance monetization. Silicon Valley fabless design houses anchor algorithm development for electrochemical impedance spectroscopy.
South Korea
Seoul-based battery management system suppliers capture design-in authority from automotive OEMs for cell-to-pack architectures. Foundry capacity constraints for automotive-qualified dies create qualification timeline vulnerabilities despite domestic fabrication advantages. Samsung SDI and LG Energy Solution specifications increasingly dictate fuel gauge integration requirements delivered to global automotive customers.
Japan
METI industrial policy supports precision analog front-end development for electrochemical modeling applications. Nagoya and Tokyo electronics corridors maintain heritage expertise in voltage-correlation methodologies while transitioning toward hybrid analog-digital configurations. Renesas Electronics anchors domestic semiconductor supply chains for automotive and industrial gauge applications.
Battery Fuel Gauge IC Market Competitive Environment
Premium-margin players sit above commodity-margin players across algorithm sophistication and automotive qualification tiers. The vendor base clusters around three strategic archetypes: integrated portfolio providers leveraging silicon economies, impedance-tracking specialists competing on electrochemical modeling depth, and manufacturing-scale defenders controlling European supply chains through captive fabrication. Consolidation pressure favors subsystem bundling over discrete component sourcing, while dual AEC-Q100 and IEC 61508 certification requirements extend product launch cycles for new entrants.
Within the integrated portfolio tier, Texas Instruments and Analog Devices occupy positions spanning automotive and industrial verticals through combined analog-digital capabilities. STMicroelectronics exemplifies the manufacturing-scale archetype through European channel control anchored in Milan and Grenoble facilities. These three entities represent the dominant competitive positioning vectors: silicon integration breadth, algorithmic precision depth, and geographic supply chain captivity.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| Microchip Technology |
| Maxim Integrated |
| STMicroelectronics |
| NXP Semiconductors |
| ON Semiconductor |
| Renesas Electronics |
| Infineon Technologies |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed foundry investments in Taiwan and South Korea are reshaping capital allocation across automotive-qualified die production, tightening pricing discipline for AEC-Q100 certification tiers while compressing margins for unqualified commodity gauges.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates automotive-grade impedance-tracking ICs from industrial hybrid configurations and consumer analog implementations. Price differentiation hinges on AEC-Q100 qualification status and algorithm sophistication depth. Cost compression in consumer electronics tiers is intensifying because Chinese EMS providers consolidate procurement volumes toward pin-compatible alternatives. Aftermarket providers exhibit highest price sensitivity, while automotive OEMs prioritize traceability documentation over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from German and US automotive OEMs are forcing Tier-1 battery management system suppliers to qualify secondary foundry partners despite concentration in Taiwan, South Korea, and Japan. Raw material dependencies center on 300mm silicon wafers, copper lead frames, and epoxy molding compounds. Single-source vulnerability around TSMC automotive process nodes creates qualification timeline risk for 800-volt architecture ramps. Distribution runs through authorized distributors serving cell-to-pack assemblers in Shenzhen and Stuttgart.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as electric vehicle manufacturers shift procurement authority toward impedance-tracking specialists capable of sub-one-percent error tolerance under EU Battery Regulation mandates.
For Market Incumbents: To counter algorithm engineering scarcity, anchor premium positioning through captive electrochemical modeling talent pools and backward integration into precision analog front-end design. Extend AEC-Q100 and IEC 61508 certification libraries to compress dual-qualification timelines for automotive-industrial crossover applications. For New Entrants and Emerging Players: Capture white-space in grid-scale energy storage predictive maintenance contracts by piloting AI-enhanced state estimation with California and Texas industrial operators. Target implantable medical device segments where FDA tolerance tightening favors pre-certified subsystem vendors over discrete component specialists. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid-technology specialists with automotive qualification pipelines but limited industrial scale. Long-term viability favors vendors with embedded firmware ecosystems capable of monetizing service contracts across battery lifecycle management. Watch solid-state battery chemistry announcements as algorithm obsolescence inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Impedance-Tracking Algorithm Investment | Secures design-ins for 800-volt automotive architectures requiring real-time aging diagnostics. |
| Dual-Qualification Pathway Expansion | Compresses product launch cycles under sequential AEC-Q100 and IEC 61508 certification burdens. |
| Cell-to-Pack Subsystem Integration | Captures procurement authority migrating from OEMs to CATL and Samsung SDI specifications. |
| Pre-Certified Material Library Development | Meets REACH and RoHS amendment documentation requirements for European-bound battery systems. |
| Grid-Scale Predictive Maintenance Partnership | Monetizes fuel gauge data through service contracts with Texas and California energy storage operators. |
Study Parameters
Coverage spans China, Germany, the United States, South Korea, and Japan, with primary inputs from each market's battery management system engineering directors, Tier-1 supplier procurement leads, semiconductor foundry account managers, and automotive platform architects. Secondary validation draws from SEC semiconductor filings, customs trade data for battery management components, EPA automotive emissions framework updates, and EU Battery Regulation implementation guidance. Bottom-up bill-of-materials analysis triangulates against top-down OEM production forecasts.
Rate-of-change decomposition separates volume expansion from value migration across silicon integration tiers, measurement methodology transitions, and application vertical shifts over the projection horizon. Segmentation modeling incorporates product type monolithic-to-discrete mix, technology analog-to-smart trajectory, end-user procurement authority migration, and regional regulatory cluster alignment. CAGRs derive from fitted adoption curves for 800-volt architectures and impedance spectroscopy penetration rates, cross-referenced against foundry capacity expansion announcements and automotive platform launch timelines.
Foundry capacity constraints, solid-state battery chemistry commercialization delays, and EU Battery Regulation enforcement variance are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions around qualification timeline continuity and algorithm portability across lithium-ion cell formats. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
Digital Audio IC Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
Display LSI IC Market
IC (Integrated Circuits)
Monolithic Microwave IC (MMIC) Market
IC (Integrated Circuits)
China Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market
IC (Integrated Circuits)
APAC Analog IC Market
IC (Integrated Circuits)
Taiwan Analog Integrated Circuits Market
IC (Integrated Circuits)
Isolated Interface Chip Market
IC (Integrated Circuits)
Europe Analog IC Market
IC (Integrated Circuits)
Automotive Special Purpose Logic IC Market
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market
IC (Integrated Circuits)
RFID Reader IC Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
Programmable ASIC Market