
 High-Throughput Satellite Market | 2026-2036
High-Throughput Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
High-Throughput Satellite Market Intelligence
Modular payload architectures is rebalancing procurement patterns across the High-Throughput Satellite value chain. SpaceX leverages vertical integration to compress launch-to-service timelines for constellation operators. Thales Alenia Space anchors European institutional demand through sovereign satellite programs. Hughes Network Systems LLC dominates North American consumer broadband distribution via managed service bundles.
High-Throughput Satellites are geostationary and non-geostationary orbital platforms employing multi-spot beam architectures and frequency-reuse patterns to deliver throughput exceeding 100 Gbps per spacecraft, primarily serving broadband backhaul, mobility connectivity, and government communications. Fixed Satellite configurations command the largest installed base, though Hybrid Satellite systems are capturing margin pools as operators blend geostationary assets with low-Earth-orbit relays. Beamforming technology is displacing conventional wide-beam architectures in new procurements, with Mesh Networking gaining traction in defense applications requiring peer-to-peer resilience.
The Federal Communications Commission shapes U.S. spectrum allocation and orbital debris mitigation rules, while the European Space Agency coordinates EU member-state procurement through joint programs. The International Telecommunication Union governs cross-border coordination mechanisms that determine market access for constellation operators. Stakeholders must monitor evolving national security review frameworks for foreign satellite operators seeking domestic landing rights.
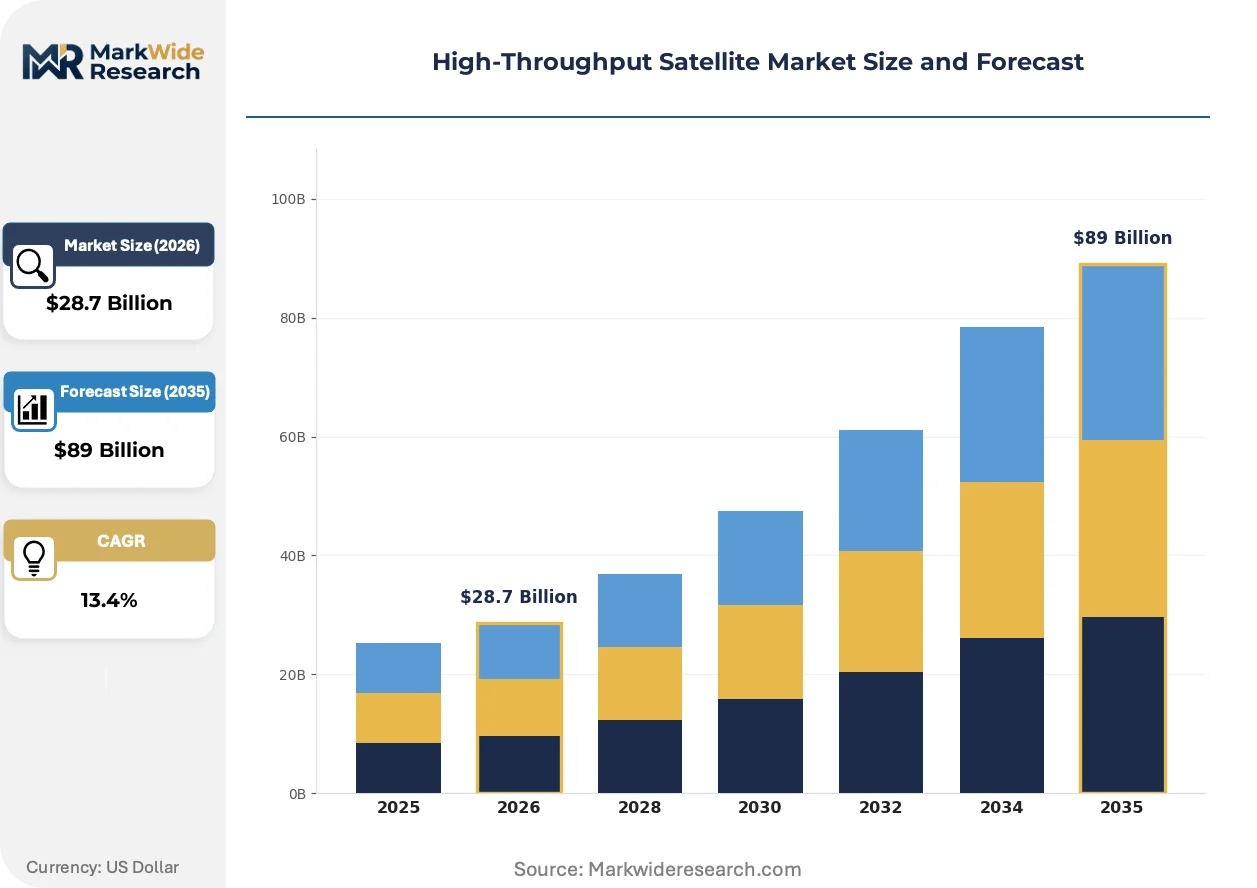
Market Dynamics
Ka-band spot beam deployment is compressing per-bit delivery economics while defense procurement cycles and rural broadband mandates concentrate demand in specific national markets. This structural force is reconfiguring fleet operator procurement priorities and satellite manufacturer order backlogs.
Growth Catalysts
- FCC Rural Digital Opportunity Fund:Subsidized broadband deployment drives HTS capacity leasing in underserved U.S. counties. Municipalities and regional ISPs accelerate gateway infrastructure buildouts.
- Maritime fleet digitization:Container shipping operators adopt vessel-to-shore data pipelines for predictive maintenance and route optimization. Crew welfare connectivity mandates expand addressable bandwidth demand.
- Beamforming processor maturation:Digital payload architectures enable dynamic capacity allocation across coverage footprints. Satellite operators reconfigure service beams without hardware replacement.
Market Restraints
- Launch capacity concentration:Heavy-lift vehicle availability bottlenecks geostationary satellite deployment schedules. Western operators face extended queue times for dedicated missions.
- Solar array input cost volatility:Gallium arsenide cell prices fluctuate with compound semiconductor substrate supply. Power subsystem procurement represents substantial spacecraft bill-of-materials exposure.
- Terrestrial fiber substitution:Subsea cable expansions erode HTS backhaul economics on dense international routes. Coastal markets migrate to lower-latency alternatives.
Strategic Opportunities
- Indonesian archipelago connectivity:Maritime dispersion and terrain fragmentation sustain satellite-dependent broadband demand. National universal service obligations channel public funding toward HTS procurement.
- In-orbit servicing convergence:Robotic refueling and payload swap capabilities extend geostationary asset lifespans. Operators defer replacement capital expenditure through life extension missions.
- EU Secure Connectivity Programme:Sovereign infrastructure mandates create dedicated procurement streams for European satellite manufacturers. Government anchor tenancy de-risks commercial capacity expansion.
Industry Challenges
- RF payload engineering talent scarcity:Specialized microwave design expertise concentrates within legacy defense contractors. Commercial satellite prime manufacturers compete for limited experienced workforce.
- ITU coordination timeline compression:Constellation filing deadlines and national licensing procedures create parallel-track regulatory complexity. Operators risk orbital slot forfeiture through procedural delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Throughput Satellite Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $89 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Satellite, Mobile Satellite, Hybrid Satellite, Ground Segment Service Type: Broadband Connectivity, Maritime Services, Government Services, Telecommunication Services Technology: Frequency Division Multiple Access, Time Division Multiple Access, Mesh Networking, Beamforming End User: Aerospace, Defense, Telecommunications, Broadcasting |
| Companies Covered | SpaceX, Airbus Defence and Space, The Boeing Company, Thales Alenia Space, Intelsat, SES S.A., Maxar Technologies, Hughes Network Systems LLC, Eutelsat S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Throughput Satellite Market Strategic Shifts & Innovations
Software-defined payload architectures are dissolving hardware-software boundaries in satellite manufacturing. This convergence enables post-launch service reconfiguration and accelerates procurement model evolution across operator fleets.
Digital transparent processors are unifying frequency conversion and routing functions previously implemented as discrete analog components. Maritime and aeronautical mobility operators adopt these payloads for seamless beam handover across oceanic coverage zones. The technology is unifying previously separate hardware qualification streams into single procurement specifications.
The FCC's updated orbital debris mitigation rules impose stricter post-mission disposal and collision avoidance obligations on licensed operators. Satellite manufacturers must integrate propulsion reserves and design for demise capabilities into standard platform offerings. U.S.-licensed geostationary constellations face accelerated compliance timelines compared to other ITU filing administrations.
Fleet operators are consolidating vendor relationships and demanding integrated ground-space service packages. Long-term managed bandwidth contracts displace traditional transponder leasing in maritime and energy sector procurement. This concentration is most visible in North Sea and Gulf of Mexico offshore platform connectivity, where integrated service providers capture multi-year exclusive supply agreements.
High-Throughput Satellite Market Segmentation
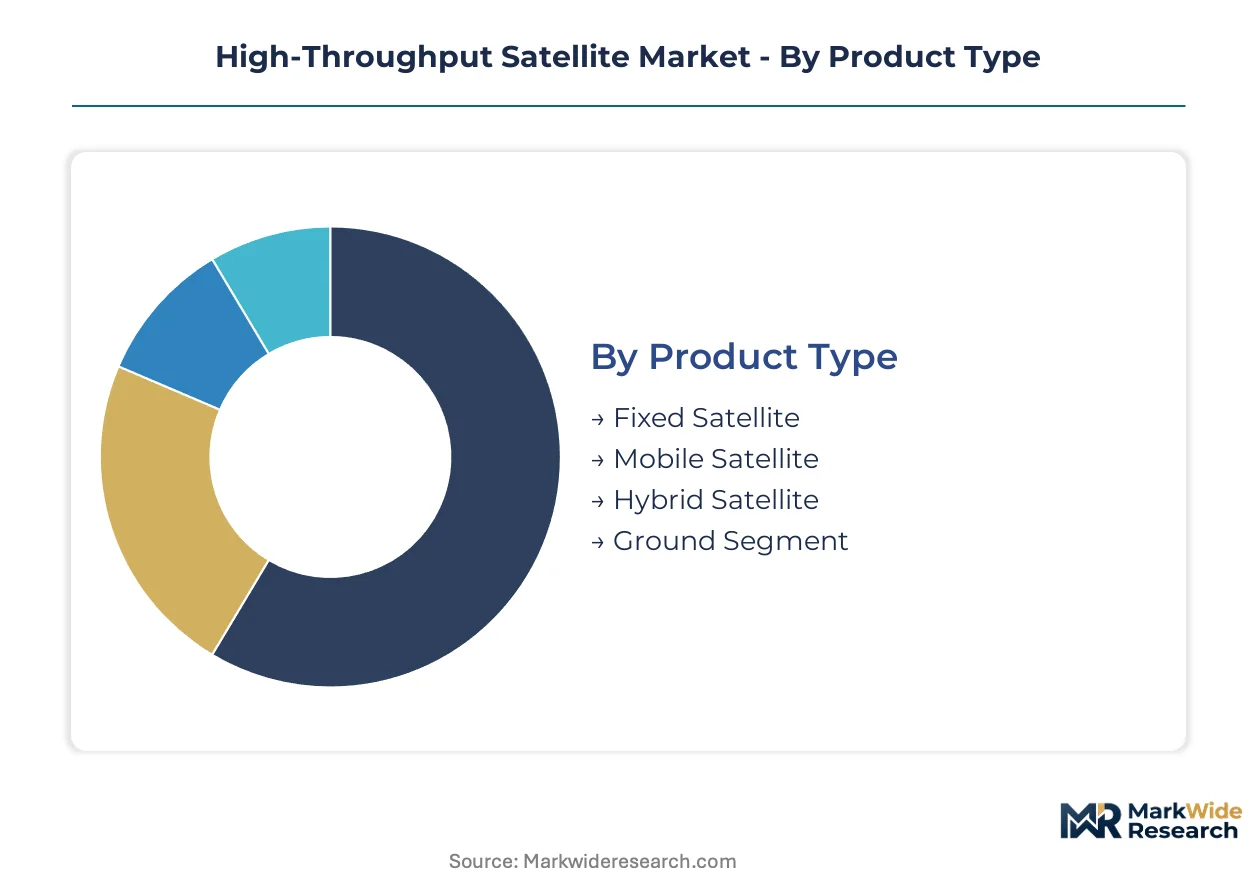
HTS market segmentation reveals how orbital architectures, service bundles, and frequency management techniques partition value across operator fleets. Procurement decisions increasingly hinge on payload flexibility and ground infrastructure integration rather than spacecraft capacity alone.
Product Type:
Orbital configuration determines capital deployment intensity and service lifecycle economics for fleet operators.
- Fixed Satellite:Geostationary platforms with wide-area coverage footprints anchor commercial broadband backhaul and broadcast distribution. Demand concentrates in rural U.S. counties under FCC subsidy programs where terrestrial fiber remains uneconomical.
- Mobile Satellite:Constellations with inter-satellite links and steerable beams serve aeronautical and maritime mobility segments. Container shipping operators drive procurement as vessel-to-shore data pipelines expand for predictive maintenance applications.
- Hybrid Satellite:Blended geostationary and low-Earth-orbit architectures optimize latency-sensitive traffic routing. European energy sector procurement favors these configurations for offshore platform connectivity in the North Sea.
- Ground Segment:Gateway infrastructure, user terminals, and network management systems complete the service delivery chain. Indonesian archipelago deployment accelerates as national universal service obligations channel public funding toward HTS procurement.
Fixed Satellite leads on scale; Hybrid Satellite leads on momentum.
Service Type:
Revenue models diverge between wholesale capacity leasing and vertically integrated managed services.
- Broadband Connectivity:Consumer and enterprise internet access represents the largest addressable demand pool. Municipalities and regional ISPs in underserved U.S. markets accelerate gateway infrastructure buildouts under subsidized deployment programs.
- Maritime Services:Crew welfare mandates and fleet digitization sustain vessel bandwidth growth. Container operators adopt these services for route optimization and predictive maintenance data pipelines.
- Government Services:Sovereign infrastructure mandates and defense procurement cycles anchor long-term contract visibility. EU Secure Connectivity Programme creates dedicated procurement streams for European satellite manufacturers.
- Telecommunication Services:Cellular backhaul and trunking applications serve mobile network operators in terrain-fragmented markets. Indonesian national universal service obligations channel public funding toward HTS procurement for archipelago coverage.
Broadband Connectivity dominates revenue contribution; Maritime Services climbs the fastest.
Technology:
Frequency management and beam control architectures determine spectral efficiency and service reconfigurability.
- Beamforming:Digital payload architectures enable dynamic capacity allocation across coverage footprints without hardware replacement. Maritime and aeronautical mobility operators adopt these processors for seamless beam handover across oceanic coverage zones.
- Mesh Networking:Peer-to-peer inter-satellite links provide resilience in contested electromagnetic environments. Defense applications requiring peer-to-peer resilience drive procurement concentration in U.S. national security programs.
- Frequency Division Multiple Access:Traditional channel allocation persists in legacy broadcast and backhaul applications. Fixed service providers maintain these systems where traffic patterns remain predictable.
- Time Division Multiple Access:Burst-mode transmission suits intermittent connectivity requirements in remote monitoring use cases. Energy sector procurement favors these economics for offshore platform telemetry.
Beamforming leads on technology transition velocity; Mesh Networking leads on defense premium capture.
End User:
Vertical-specific requirements shape terminal specifications, service level agreements, and security certifications.
- Defense:Hardened payloads and anti-jam waveforms command procurement priority in national security budgets. U.S. defense contracts concentrate demand for resilient peer-to-peer architectures.
- Telecommunications:Mobile network operators and fixed-line carriers source backhaul capacity for rural and remote cell sites. Regional ISPs in underserved U.S. counties accelerate gateway infrastructure buildouts.
- Aerospace:Commercial aviation and business jet connectivity requirements drive terminal miniaturization and installation standardization. Fleet digitization intensifies bandwidth demand for passenger and operational data.
- Broadcasting:Video distribution and contribution feeds sustain transponder leasing in media markets. Traditional wide-beam architectures persist where one-to-many distribution dominates.
Defense leads on contract value concentration; Telecommunications leads on volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Satellite manufacturing and fleet operations trace their commercial scale to early U.S. and European defense programs, with Ka-band spot beam technology maturing through successive NASA and ESA technology demonstrations. Today's capacity deployment concentrates in national markets with sovereign infrastructure mandates and rural broadband subsidy frameworks.
United States
Defense procurement cycles and FCC Rural Digital Opportunity Fund subsidies concentrate HTS demand in underserved counties. The Federal Communications Commission shapes spectrum allocation and orbital debris mitigation rules that accelerate compliance timelines for licensed operators. California hosts constellation operators leveraging vertical integration to compress launch-to-service timelines.
Indonesia
Maritime dispersion across seventeen thousand islands and terrain fragmentation sustain satellite-dependent broadband demand. National universal service obligations channel public funding toward HTS procurement for archipelago coverage. Jakarta anchors gateway infrastructure buildouts as municipalities accelerate regional ISP partnerships.
Germany
European energy sector procurement favors hybrid satellite configurations for North Sea offshore platform connectivity. The European Space Agency coordinates EU member-state procurement through joint programs that de-risk commercial capacity expansion. Bavaria hosts satellite manufacturers anchoring European institutional demand through sovereign satellite programs.
United Arab Emirates
Government anchor tenancy and sovereign infrastructure mandates create dedicated procurement streams for regional fleet operators. The country's national telecommunications regulator governs landing rights and cross-border coordination mechanisms. Dubai clusters managed service providers capturing multi-year exclusive supply agreements for maritime and energy sector connectivity.
India
Terrain-fragmented markets and rural broadband mandates drive HTS backhaul procurement for mobile network operators. The Telecom Regulatory Authority of India governs spectrum allocation and foreign operator licensing procedures. Karnataka hosts technology development centers advancing beamforming processor architectures for dynamic capacity allocation.
High-Throughput Satellite Market Key Industry Players
The competitive structure tilts toward vertically integrated constellation operators and established geostationary fleet managers. Prime manufacturers and service providers occupy distinct tier positions based on payload integration depth and ground infrastructure ownership. Two strategic archetypes dominate: launch-integrated constellation operators compressing deployment timelines, and legacy fleet managers with anchor tenancy relationships. Capacity expansion through modular payload architectures and strategic partnerships for gateway infrastructure represent the dominant competitive moves.
Within the vertically integrated tier, SpaceX exemplifies launch-to-service compression through captive heavy-lift availability. Among European prime manufacturers, Thales Alenia Space occupies a position anchoring institutional demand through sovereign programs. Hughes Network Systems LLC represents the managed service archetype, bundling consumer broadband distribution with gateway infrastructure ownership.
| Leading Market Players |
|---|
| SpaceX |
| Airbus Defence and Space |
| The Boeing Company |
| Thales Alenia Space |
| Intelsat |
| SES S.A. |
| Maxar Technologies |
| Hughes Network Systems LLC |
| Eutelsat S.A. |
| Others |
Cost & Logistics Intelligence
Gallium arsenide cell price indices cascade through spacecraft power subsystem procurement into tiered service pricing for maritime and defense operators. Ka-band payload foundry costs compress per-bit economics while solar array volatility feeds margin pressure into long-term managed bandwidth contracts.
Pricing Analysis
Long-term managed bandwidth contracts anchor revenue stability for fleet operators serving North Sea energy platforms and Indonesian archipelago connectivity. Pricing stratifies across premium sovereign-grade, standard commercial, and economy wholesale tiers based on latency guarantees and security certification levels. Cost compression in consumer broadband stems from SpaceX vertical integration and reusable launch economics. Regional ISPs in FCC-subsidized U.S. counties exhibit highest price sensitivity; defense agencies demonstrate lowest sensitivity due to resilience requirements.
Supply Chain Analysis
Single-source vulnerability sits with gallium arsenide substrate suppliers concentrated in Germany and the United States. Spacecraft manufacturing draws from compound semiconductor foundries, precision antenna vendors, and heavy-lift launch providers concentrated in California and Florida. Tariff exposure on radiation-hardened electronics creates procurement risk for European prime manufacturers. Distribution runs through integrated ground-space service providers capturing multi-year exclusive agreements in maritime and offshore energy segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-Throughput Satellite procurement has shifted toward premium specifications as defense resilience requirements and sovereign infrastructure mandates harden demand for anti-jam waveforms and mesh networking capabilities.
For Market Incumbents: Acquire digital payload engineering teams to counter RF talent scarcity at legacy defense contractors. Consolidate gateway infrastructure ownership in Indonesian and North Sea markets to lock in multi-year exclusive supply agreements. Thales Alenia Space and Hughes Network Systems LLC already demonstrate this pattern through sovereign program anchoring and managed service bundling. For New Entrants and Emerging Players: Municipal broadband authorities in underserved U.S. counties represent the most penetrable buyer archetype given FCC Rural Digital Opportunity Fund subsidy flows. Target Indonesian regional ISPs facing national universal service obligations for archipelago coverage. Pursue partnership-based go-to-market models with established gateway infrastructure owners rather than capital-intensive vertical buildout. For Investors and Strategic Acquirers: Asymmetric upside sits with beamforming processor specialists enabling dynamic capacity allocation without hardware replacement. Five-to-ten year viability hinges on in-orbit servicing convergence extending geostationary asset lifespans. Watch FCC orbital debris compliance timelines as inflection indicator for U.S.-licensed operator capital deployment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Payload Architecture Migration | Enables post-launch service reconfiguration for maritime beam handover without hardware replacement. |
| In-Orbit Servicing Capability Buildout | Extends geostationary asset lifespans through robotic refueling, deferring replacement capital expenditure. |
| Sovereign Infrastructure Partnership | EU Secure Connectivity Programme de-risks commercial capacity expansion through government anchor tenancy. |
| Gateway Infrastructure Consolidation | Integrated ground-space packages displace traditional transponder leasing in North Sea offshore connectivity. |
| RF Engineering Talent Acquisition | Counteracts microwave design expertise concentration within legacy U.S. defense contractors. |
Research Approach
Direct dialogue with satellite fleet operators, payload procurement managers, maritime connectivity directors, and defense program officers grounded qualitative findings. Secondary validation drew from FCC spectrum allocation records, ESA joint program documentation, ITU coordination filings, and operator capex disclosures. Bottom-up capacity deployment modeling and top-down subsidy flow analysis enabled triangulation across independent estimation approaches.
Bottom-up segment sizing tracked orbital configuration, service bundle type, and frequency management technique across the projection horizon. Top-down validation cross-referenced sovereign procurement budgets, rural broadband mandate allocations, and maritime fleet digitization spending. CAGRs derived from fitted growth curves against historical capacity deployment patterns. Forecast inputs incorporated launch queue dynamics, gallium arsenide price trajectories, and ITU coordination timeline compression risks.
Underlying measurement precision varies by segment; defense and government services carry tighter precision due to visible procurement cycles than emerging maritime mobility applications. Forecasts reflect documented assumptions on subsidy program continuity, launch vehicle availability, and regulatory compliance timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Global Satellite Propulsion System Market
Satellite
LEO and GEO Satellite Market
Satellite
India Satellite Connectivity Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
Russia Satellite Connectivity Market
Satellite
Satellite Signal Meter Market
Satellite
United Arab Emirates Satellite-Based Earth Observation Market
Satellite
Global Enterprise VSAT System Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
All-Electric Satellites Market
Satellite
Russia Satellite Imagery Services Market
Satellite
Satellite Compass Market
Satellite
Brazil Satellite-Based Earth Observation Market
Satellite
Germany Satellite Connectivity Market
Satellite
Satellite Market
Satellite
China Satellite-Based Earth Observation Market