
 Maritime Patrol Naval Vessels (OPV) Market | 2026-2036
Maritime Patrol Naval Vessels (OPV) Market Size, Share, and Industry Trends Forecast 2026-2036
Maritime Patrol Naval Vessels (OPV) Market Insights
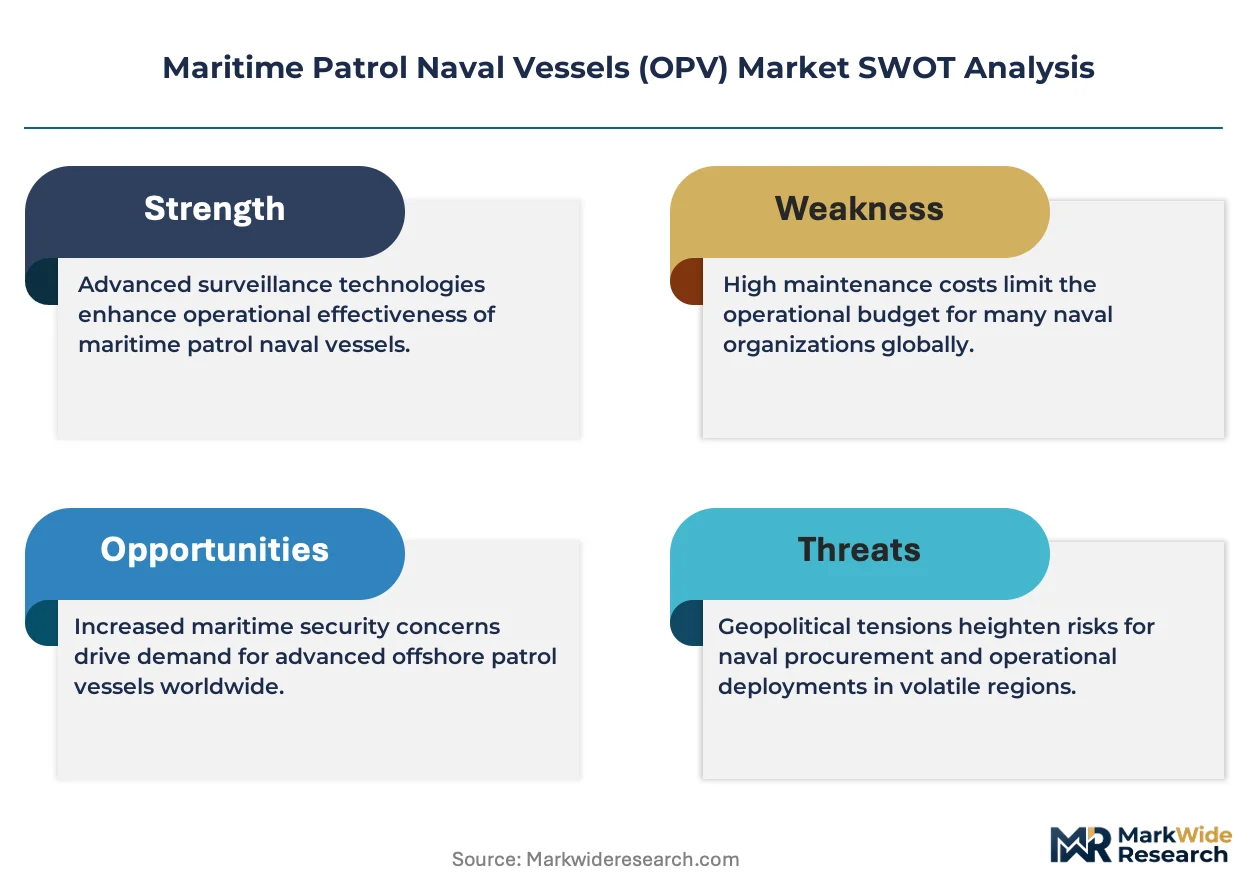
A capital-intensity divergence between full-service naval architects and modular-assembly specialists is unwinding competitive stability in OPV construction. Naval Group leverages sovereign design heritage and integrated combat-system architecture to sustain premium positioning in European navies. Damen Shipyards Group anchors its portfolio through standardized hull platforms that compete aggressively on delivery speed and lifecycle cost. Austal Limited differentiates via aluminum-hulled high-speed variants that dominate Indo-Pacific coastal patrol tenders.
Offshore Patrol Vessels constitute a steel or aluminum-hulled platform typically displacing 1,000–3,000 tonnes, configured for sustained operations beyond coastal waters with helicopter decks and modular mission bays for surveillance or interdiction roles. Coastal Patrol Vessels represent a mature segment where margin pools have compressed amid standardized procurement frameworks, while Autonomous Navigation technology integration is capturing disproportionate R&D investment as navies reduce crew complements and extend patrol endurance. Electronic Warfare Systems and Sonar Systems within the Technology dimension concentrate value-add as sovereign-content requirements intensify domestic sourcing mandates.
Naval procurement authorities in NATO member states reference STANAG interoperability standards, while the EU Green Deal emissions framework and national naval codes shape propulsion-system specifications and hull-material choices. The International Maritime Organization's safety conventions and regional Exclusive Economic Zone enforcement protocols directly determine sensor-suite minimums and patrol-range requirements. Stakeholders must monitor accelerating sovereign-content thresholds and propulsion-decision timelines as diesel-electric and hydrogen-fuel-cell pathways diverge.
Market Dynamics
Hybrid diesel-electric propulsion architectures are compressing traditional engine-supplier margins while extending patrol endurance requirements beyond 30 days, forcing naval architects to reconfigure power-train layouts and mission-bay modularity.
Growth Catalysts
- EEZ Enforcement Mandates:Coastal states across Southeast Asia and West Africa are expanding sovereign patrol fleets to secure fisheries and hydrocarbon blocks within 200-nautical-mile zones.
- NATO STANAG Interoperability:Standardized command-and-control interfaces enable cross-border task force integration, driving replacement cycles among Atlantic alliance members.
- Unmanned Surface Vessel Integration:Navies are deploying USV swarms for persistent surveillance, reducing crewed vessel procurement quantities while extending operational coverage.
Market Restraints
- Steel Price Volatility:Naval-grade high-tensile steel contracts face 18-24 month procurement lead times, compressing yard margins on fixed-price tenders.
- Sovereign-Content Thresholds:Domestic sourcing mandates for combat systems and sensors fragment supplier bases, inflating integration costs for export contracts.
- Crewed Vessel Substitution:Long-endurance autonomous platforms are capturing low-intelligence patrol missions, constraining demand for 1,500-tonne OPV hulls.
Strategic Opportunities
- Indonesia Archipelagic Patrol:The world's largest island nation requires 25+ new hulls for maritime domain awareness across 17,000 islands.
- EU Green Deal Propulsion Incentives:Emissions-reduction mandates are accelerating hydrogen-fuel-cell pilot programs for coastal patrol variants.
- Converged Sensor-AI Architectures:Machine-learning classification of radar and electro-optical feeds is enabling reduced-crew bridge designs with single-operator monitoring stations.
Industry Challenges
- Naval Architect Talent Scarcity:Shipyards face acute shortages of marine engineers qualified in integrated electric propulsion and combat-system interface design.
- Classification Society Certification Delays:Lloyd's Register and DNV rules for autonomous navigation systems remain in draft, freezing build specifications for unmanned-capable hulls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maritime Patrol Naval Vessels (OPV) Market |
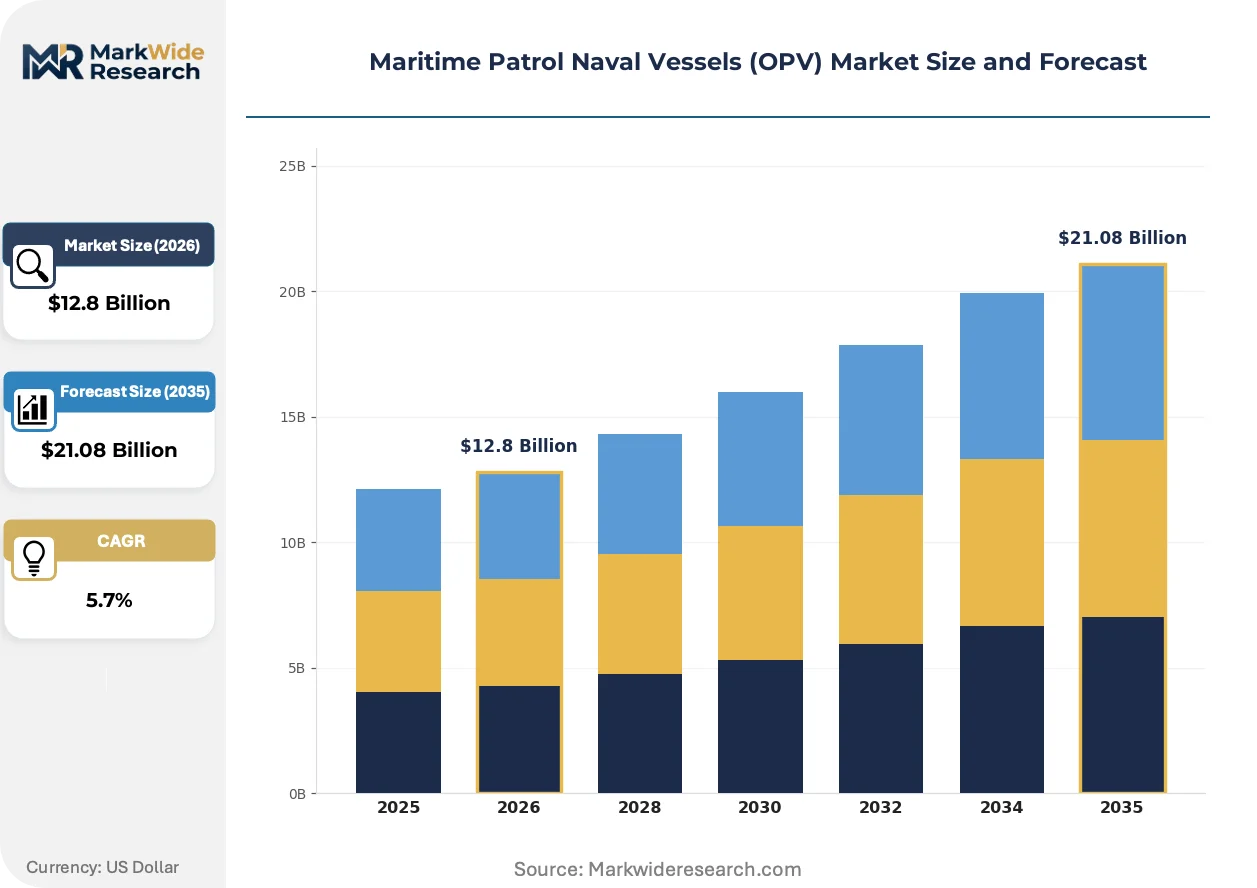
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Offshore Patrol Vessel, Coastal Patrol Vessel, Fast Patrol Boat, Riverine Patrol Vessel, Air Cushion Vehicle, Submersible Technology: Sonar Systems, Radar Platforms, Electronic Warfare Systems, Infrared Sensors, Communication Suites, Autonomous Navigation Mission Scope: Surveillance, Anti-Piracy, Search & Rescue, Environmental Protection, Law Enforcement, Disaster Response End User: Navy, Coast Guard, Border Security Forces, Maritime Law Enforcement, Port Authorities, Exclusive Economic Zone Agencies |
| Companies Covered | Austal Limited, Naval Group, BAE Systems, Huntington Ingalls Industries, Dearsan Shipyard, Fincantieri, Navantia, Mitsubishi Heavy Industries, Damen Shipyards Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maritime Patrol Naval Vessels (OPV) Market Trends and Innovations
Propulsion-system electrification and sensor-fusion architectures are compressing traditional design cycles while enabling multi-mission reconfiguration between patrol, search-and-rescue, and environmental enforcement roles.
Integrated electric propulsion is supplanting mechanical drive trains in 2,000-tonne-plus hulls. European navies specify this architecture for 80% of new patrol vessel orders. The shift collapses engine-room footprint requirements, freeing 15-20% of hull volume for mission-flexible payload bays.
EU Green Deal emissions frameworks are mandating shore-power compatibility and exhaust-aftertreatment systems for vessels operating in designated emission control areas. Shipyards in Germany and the Netherlands are certifying dual-fuel diesel-hydrogen configurations. This regulatory pressure concentrates investment in Baltic and North Sea patrol fleets where environmental enforcement missions dominate.
Lifecycle availability contracting is displacing traditional unit-procurement models. Royal Australian Navy and UK Royal Fleet Auxiliary tenders now specify 15-20 year through-life support bundles with guaranteed operational availability percentages. This restructuring shifts financial risk to prime contractors and concentrates vendor selection among integrated system houses with sovereign maintenance infrastructure.
Maritime Patrol Naval Vessels (OPV) Market Segmentation
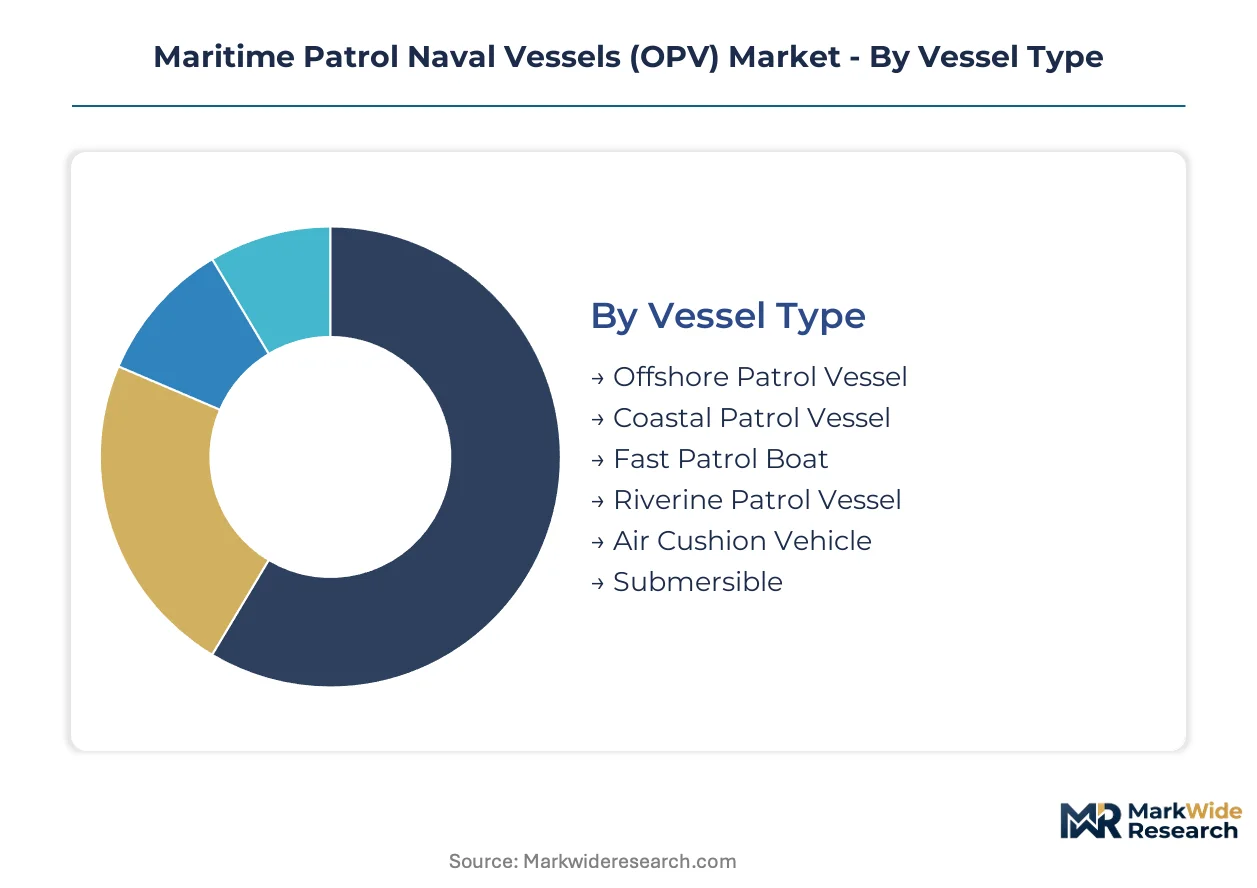
OPV procurement patterns fragment sharply across vessel displacement, sensor architecture, and mission mandate. Procurement authorities weight hull endurance against acquisition cost, while technology integration decisions determine through-life upgrade pathways. Understanding these segment boundaries clarifies where prime contractors concentrate engineering investment versus where modular suppliers capture assembly margins.
Vessel Type:
Margin pools concentrate in the 1,500-3,000 tonne displacement band where steel hulls, integrated electric propulsion, and helicopter deck certification compound engineering premiums.
- Offshore Patrol Vessel:Steel or aluminum-hulled platforms displace 1,000-3,000 tonnes with helicopter decks and modular mission bays for sustained operations beyond coastal waters. Indonesia, Vietnam, and the Philippines dominate tender activity as archipelagic states extend maritime domain awareness across dispersed island chains.
- Coastal Patrol Vessel:Standardized procurement frameworks have compressed margins in this mature segment where hull designs stabilize around 500-800 tonnes. Damen Shipyards Group and Austal Limited compete aggressively on delivery speed and lifecycle cost for West African and Caribbean littoral states.
- Fast Patrol Boat:Aluminum-hulled high-speed variants dominate Indo-Pacific coastal patrol tenders requiring rapid interdiction response.
- Riverine Patrol Vessel:Shallow-draft configurations serve internal waterway enforcement in the Amazon basin, Mekong delta, and Niger river systems.
- Air Cushion Vehicle:Specialized hovercraft platforms access littoral zones denied to conventional hulls in Arctic and marshland environments.
- Submersible:Manned and unmanned underwater platforms extend surveillance reach below surface clutter for exclusive economic zone integrity.
The dominant share belongs to Offshore Patrol Vessel, while Fast Patrol Boat is closing the gap fastest.
Technology:
Sensor fusion and autonomous navigation architectures are capturing disproportionate R&D investment as navies reduce crew complements and extend patrol endurance.
- Sonar Systems:Hull-mounted and towed-array configurations detect sub-surface threats in exclusive economic zone enforcement roles. Sovereign-content requirements intensify domestic sourcing mandates for combat systems, fragmenting supplier bases and inflating integration costs for export contracts.
- Electronic Warfare Systems:Electronic support measures and countermeasure suites concentrate value-add as NATO STANAG interoperability standards drive standardized command-and-control interfaces. Royal Australian Navy and UK Royal Fleet Auxiliary tenders specify 15-20 year through-life support bundles with guaranteed operational availability percentages.
- Radar Platforms:Solid-state active electronically scanned arrays replace mechanically scanned systems for multi-target tracking in dense littoral traffic.
- Infrared Sensors:Electro-optical/infrared turrets enable night-time identification and non-cooperative target tracking.
- Communication Suites:Satellite and line-of-sight links integrate task force coordination and shore-based command authority.
- Autonomous Navigation:Machine-learning classification of radar and electro-optical feeds enables reduced-crew bridge designs with single-operator monitoring stations.
Sonar Systems commands the largest installed base, though Autonomous Navigation is expanding most quickly as classification societies finalize certification rules.
Mission Scope:
Multi-mission reconfiguration capability determines platform pricing tiers, with surveillance-dominant hulls trading at discounts versus interdiction-configured variants.
- Surveillance:Persistent radar and electro-optical coverage of exclusive economic zones requires 30-plus day endurance with hybrid diesel-electric propulsion. EU Green Deal emissions frameworks mandate shore-power compatibility and exhaust-aftertreatment systems for vessels operating in designated emission control areas.
- Anti-Piracy:Boarding team facilities, rigid-hull inflatable boat davits, and stabilized weapon stations concentrate procurement specifications for Gulf of Guinea and Horn of Africa operations. Coastal states across West Africa are expanding sovereign patrol fleets to secure fisheries and hydrocarbon blocks within 200-nautical-mile zones.
- Search & Rescue:Medical facilities, survivor recovery decks, and diver support systems distinguish dedicated SAR variants.
- Environmental Protection:Oil spill response equipment and scientific sampling laboratories serve marine sanctuary enforcement.
- Law Enforcement:Detention facilities and evidence-handling protocols configure hulls for fisheries and customs interdiction.
- Disaster Response:Heavy-lift crane capacity and humanitarian supply storage enable post-cyclone and tsunami relief.
Surveillance retains the dominant procurement volume, while Environmental Protection is gaining share fastest under EU Green Deal regulatory pressure.
End User:
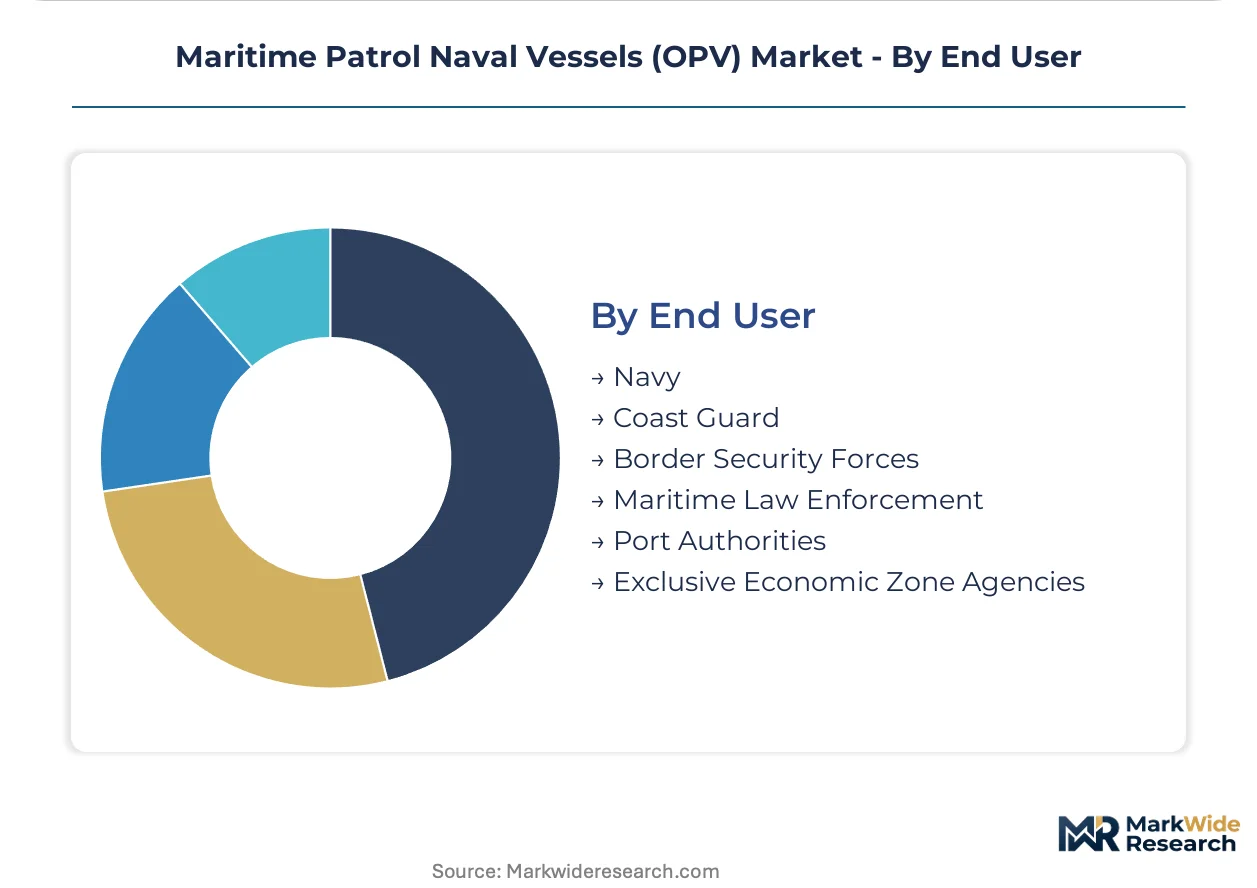
Institutional procurement authority determines specification stringency, with navy-led programs demanding integrated combat systems that coast guard tenders often defer.
- Navy:Full-spectrum combat system integration with anti-surface and limited anti-air capability drives premium hull pricing. Naval Group leverages sovereign design heritage and integrated combat-system architecture to sustain premium positioning in European navies.
- Coast Guard:Law enforcement and search-and-rescue mandates prioritize helicopter deck certification and boat launch recovery systems over weapons fit. Shipyards in Germany and the Netherlands are certifying dual-fuel diesel-hydrogen configurations for Baltic and North Sea patrol fleets where environmental enforcement missions dominate.
- Border Security Forces:Interdiction-focused procurement emphasizes speed and shallow-draft access over endurance.
- Maritime Law Enforcement:Fisheries protection and customs enforcement require evidence-chain integrity and detention facilities.
- Port Authorities:Harbor security and pilotage support demand maneuverability in confined waters.
- Exclusive Economic Zone Agencies:Scientific and resource-protection mandates configure hulls for environmental monitoring and hydrocarbon block security.
Navy accounts for the dominant procurement value, though Coast Guard is climbing the fastest as civil maritime security agencies separate from naval command structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in naval-grade steel and combat system components are redrawing procurement geography. Countries with sovereign design heritage trade vessel platforms across EEZ enforcement mandates.
Indonesia
Archipelagic patrol requirements across 17,000 islands drive demand for 25-plus new hulls. The national naval code mandates minimum 30-day endurance for maritime domain awareness vessels. Surabaya shipyards concentrate aluminum-hulled fast patrol construction for littoral interdiction roles.
Germany
Baltic Sea environmental enforcement missions accelerate dual-fuel diesel-hydrogen pilot programs. EU Green Deal emissions frameworks mandate shore-power compatibility for emission control area operations. Kiel and Hamburg clusters lead integrated electric propulsion certification for 2,000-tonne-plus hulls.
United States
Coast Guard recapitalization programs prioritize helicopter deck certification and boat launch recovery systems. Congressional funding cycles shape 15-20 year through-life support contracting models. Ingalls Shipbuilding in Mississippi and Austal USA in Alabama anchor domestic OPV fabrication capacity.
France
Naval Group leverages sovereign combat-system architecture for NATO STANAG interoperability compliance. The EU Green Deal drives exhaust-aftertreatment specifications for North Sea patrol fleets. Lorient and Cherbourg facilities concentrate premium integrated system house capabilities.
Vietnam
Territorial water disputes in the South China Sea expand surveillance-dominant hull procurement. Domestic sourcing mandates for sensors fragment supplier bases on export contracts. Da Nang shipyards specialize in 1,500-tonne steel hulls with reduced-crew bridge designs.
Maritime Patrol Naval Vessels (OPV) Market Competitive Landscape
Concentration sits with integrated system houses that combine sovereign design heritage with through-life support infrastructure. The vendor base stratifies across three tiers: full-service naval architects commanding premium positioning, modular-assembly specialists competing on delivery speed, and aluminum-hulled high-speed fabricators capturing Indo-Pacific tenders. Two competitive moves dominate: lifecycle availability contracting that shifts financial risk to prime contractors, and propulsion-system electrification that collapses engine-room footprints to free hull volume for mission-flexible payload bays.
Within the sovereign-heritage tier, Naval Group and BAE Systems exemplify integrated combat-system architecture positioning. Damen Shipyards Group anchors the modular-assembly vector through standardized hull platforms. Austal Limited occupies the aluminum-hulled high-speed specialist position for rapid interdiction response tenders.
| Leading Market Players |
|---|
| Austal Limited |
| Naval Group |
| BAE Systems |
| Huntington Ingalls Industries |
| Dearsan Shipyard |
| Fincantieri |
| Navantia |
| Mitsubishi Heavy Industries |
| Damen Shipyards Group |
| Others |
Pricing and Supply Chain Analysis
Steel-hull fabrication scale economies in South Korean and Japanese shipyards compress unit costs for 2,000-tonne-plus platforms while elevating price floors for smaller European yards facing 18-24 month procurement lead times on naval-grade high-tensile steel. This capacity-utilization divergence concentrates pricing power among integrated system houses with sovereign maintenance infrastructure, forcing modular-assembly specialists to compete on lifecycle availability contracting rather than upfront hull cost.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that bundle 15-20 year through-life support with guaranteed operational availability percentages. Price differentiation rests on certification grade for NATO STANAG interoperability and sovereign-content thresholds for combat systems. Pricing pressure stems from standardized procurement frameworks in the Coastal Patrol Vessel segment as Damen Shipyards Group and Austal Limited compete aggressively on delivery speed. Coast Guard procurement authorities exhibit highest price sensitivity, deferring weapons fit for helicopter deck certification, while Navy-led programs absorb premium hull pricing for integrated combat-system architecture.
Supply Chain Analysis
China and South Korea anchor steel hull fabrication and hybrid diesel-electric propulsion component manufacturing, while Germany and the Netherlands concentrate dual-fuel diesel-hydrogen pilot program certification. Raw material dependencies draw from naval-grade high-tensile steel, aluminum alloy plate for fast patrol variants, and solid-state active electronically scanned array radar subsystems. Single-source vulnerability concentrates in combat-system sensor suites where sovereign-content mandates fragment supplier bases. Distribution runs through prime contractor-led integrated system houses that shift financial risk via lifecycle availability contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maritime Patrol Naval Vessels procurement is recovering from cyclical defense budget compression as EEZ enforcement mandates accelerate replacement cycles across archipelagic states. Naval recapitalization programs in Southeast Asia and NATO Atlantic alliance members drive tender activity above trend.
For Market Incumbents: Fortify sovereign design heritage positioning by deepening backward integration into combat-system sensor manufacturing, countering sovereign-content threshold inflation on export contracts. Add certified capacity in hydrogen-fuel-cell propulsion pathways ahead of EU Green Deal emissions framework deadlines, as Baltic and North Sea environmental enforcement missions concentrate demand for dual-fuel configurations. For New Entrants and Emerging Players: Anchor in Indonesia's archipelagic patrol requirement for 25-plus new hulls across 17,000 islands, where domestic shipyard capacity constraints create white-space for aluminum-hulled fast patrol construction partnerships. Target reduced-crew bridge designs with single-operator monitoring stations as Autonomous Navigation certification rules finalize, enabling entry through machine-learning classification technology rather than sovereign heritage. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated system houses with through-life support infrastructure and sovereign maintenance networks, as Royal Australian Navy and UK Royal Fleet Auxiliary tenders displace unit-procurement models. Long-term viability across the analysis window favors prime contractors with 15-20 year availability contracting capabilities. Monitor classification society certification timelines for autonomous navigation systems as the inflection signal for unmanned-capable hull build specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Lifecycle Availability Contracting | Shifts financial risk to Naval Group and BAE Systems while concentrating vendor selection among integrated system houses. |
| Dual-Fuel Diesel-Hydrogen Certification | German and Dutch shipyards capture EU Green Deal incentives for Baltic and North Sea environmental enforcement fleets. |
| Autonomous Navigation Integration | Machine-learning classification enables reduced-crew designs as Lloyd's Register and DNV finalize certification rules. |
| Modular Mission Bay Reconfiguration | Integrated electric propulsion collapses engine-room footprints, freeing hull volume for multi-role payload flexibility. |
| Sovereign Content Threshold Navigation | Domestic sourcing mandates for Thales and Leonardo sensors inflate integration costs, favoring local joint ventures. |
Research Methodology
A spread of perspectives from naval procurement officers, shipyard program managers, combat-system integration engineers, and lifecycle support directors converged on the working assumptions underlying vessel demand forecasts. Primary interview intelligence combined with secondary validation from NATO STANAG documentation, EU Green Deal emissions framework filings, Lloyd's Register classification drafts, and national naval code specifications. Bottom-up hull delivery projections and top-down defense budget appropriations triangulated on segment-level demand estimates across the analysis window.
Vessel type, technology architecture, mission scope, and end-user institutional authority segmentation dimensions anchored the analytical framework. CAGRs derived from displacement-weighted tender pipelines and propulsion-system transition timelines across diesel-electric and hydrogen-fuel-cell pathways. Forecast inputs incorporated EEZ enforcement mandate expansion rates and sovereign-content threshold escalation patterns without specifying year-bound milestones.
Underlying assumptions cover NATO interoperability compliance timelines and classification society certification finalization, with deviation risk concentrated in autonomous navigation rule delays and naval-grade steel price volatility. Recalibration cycles align with material shifts in EU Green Deal enforcement and archipelagic state procurement award announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Naval Vessels and Surface Combatants Market
Naval Warfare
Military Marine Vessel Engines Market
Naval Warfare
Military Frigate Market
Naval Warfare
Naval Radar Systems Market
Naval Warfare
Naval Combat Vessels Market
Naval Warfare
Naval Missiles and Missile Launch Systems Market
Naval Warfare
Marine Radar Market
Naval Warfare
Global Naval Ship Propeller Market
Naval Warfare
Littoral Warship Market
Naval Warfare
Aircraft Carrier Ship Market
Naval Warfare
Naval Artillery System Market
Naval Warfare
Naval Gun System Market
Naval Warfare
Submarine Combat System Market
Naval Warfare
Aircraft Carrier Market
Naval Warfare
Global Naval Vessel MRO Market
Naval Warfare
Naval Combat Weapons Market