
 Global Enterprise VSAT System Market | 2026-2036
Global Enterprise VSAT System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise VSAT System Market Foresight
Flat-panel antenna technology is fragmenting the traditional parabolic VSAT hardware stack, forcing incumbents to rearchitect terminal portfolios around electronically steerable arrays. Hughes Network Systems leverages its managed network services footprint to sustain enterprise subscriber bases across North American rural zones. Viasat competes through vertically integrated satellite capacity, controlling both space segment and ground terminal production. Gilat Satellite Networks specializes in cellular backhaul gateways, occupying a niche where terrestrial infrastructure remains uneconomical.
Enterprise VSAT systems comprise two-way satellite ground terminals operating through geostationary or medium-earth orbit constellations, typically transmitting in the 500 MHz to 3 GHz intermediate frequency range before upconversion to Ka-band or Ku-band for space link closure. These systems provide dedicated broadband connectivity to locations beyond fiber or cellular reach, serving as primary backhaul for remote industrial operations and emergency communications infrastructure. Fixed VSAT terminals anchor the installed base across energy and government verticals, though maritime VSAT represents the fastest-expanding segment as vessel owners mandate always-on crew welfare and operational data links. Ka-band technology leads new terminal shipments, displacing Ku-band in high-throughput applications where spot-beam architecture delivers superior bits-per-Hertz economics.
The FCC governs terminal certification and spectrum licensing for U.S.-deployed systems, while the EU's Radio Equipment Directive mandates CE marking for terminal sales across member states; Brazil's ANATEL imposes homologation requirements that delay market entry for non-local manufacturers. ITU coordination procedures for orbital slot and frequency assignments constrain how quickly new satellite operators can serve enterprise VSAT demand in contested bands. Stakeholders must weigh constellation deployment timelines against terrestrial 5G expansion when committing to multi-year VSAT service contracts.
Market Dynamics
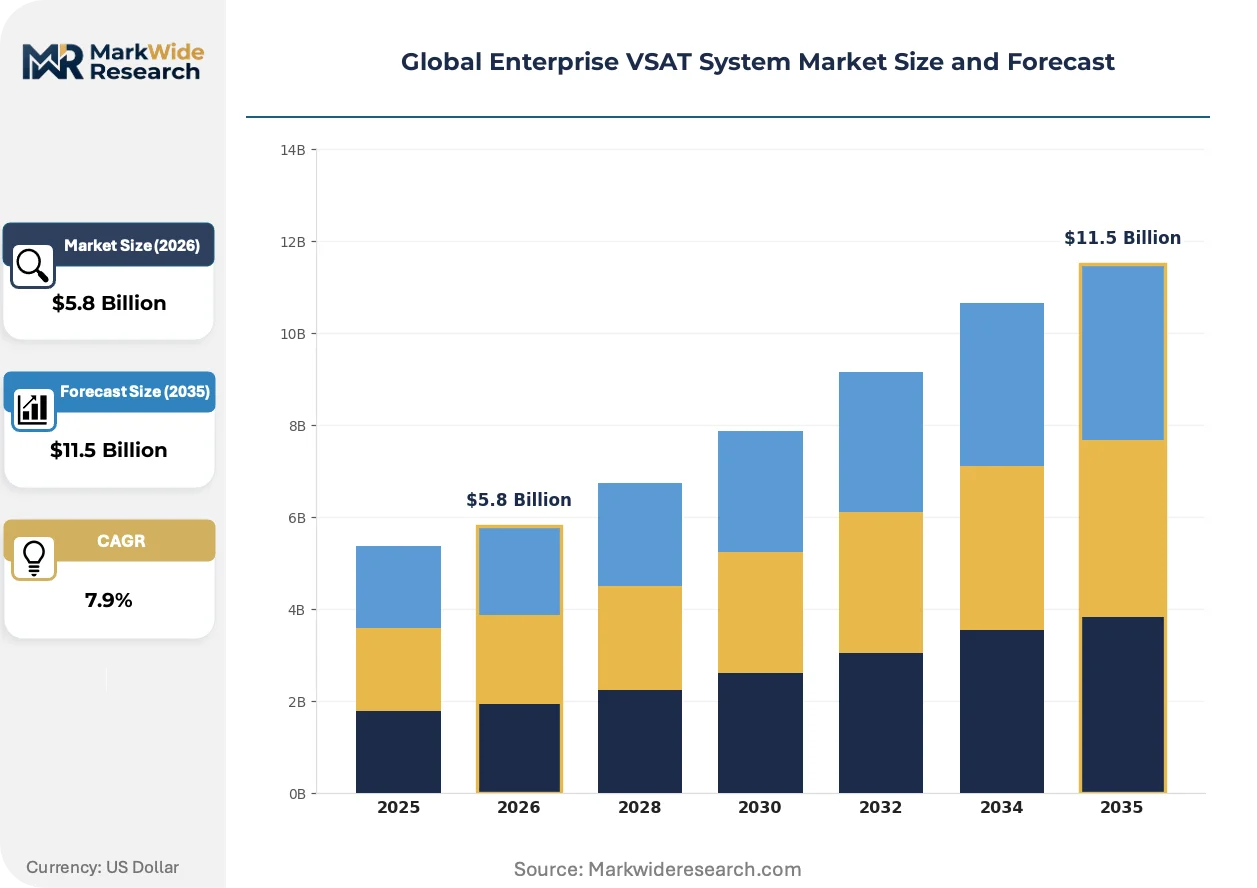
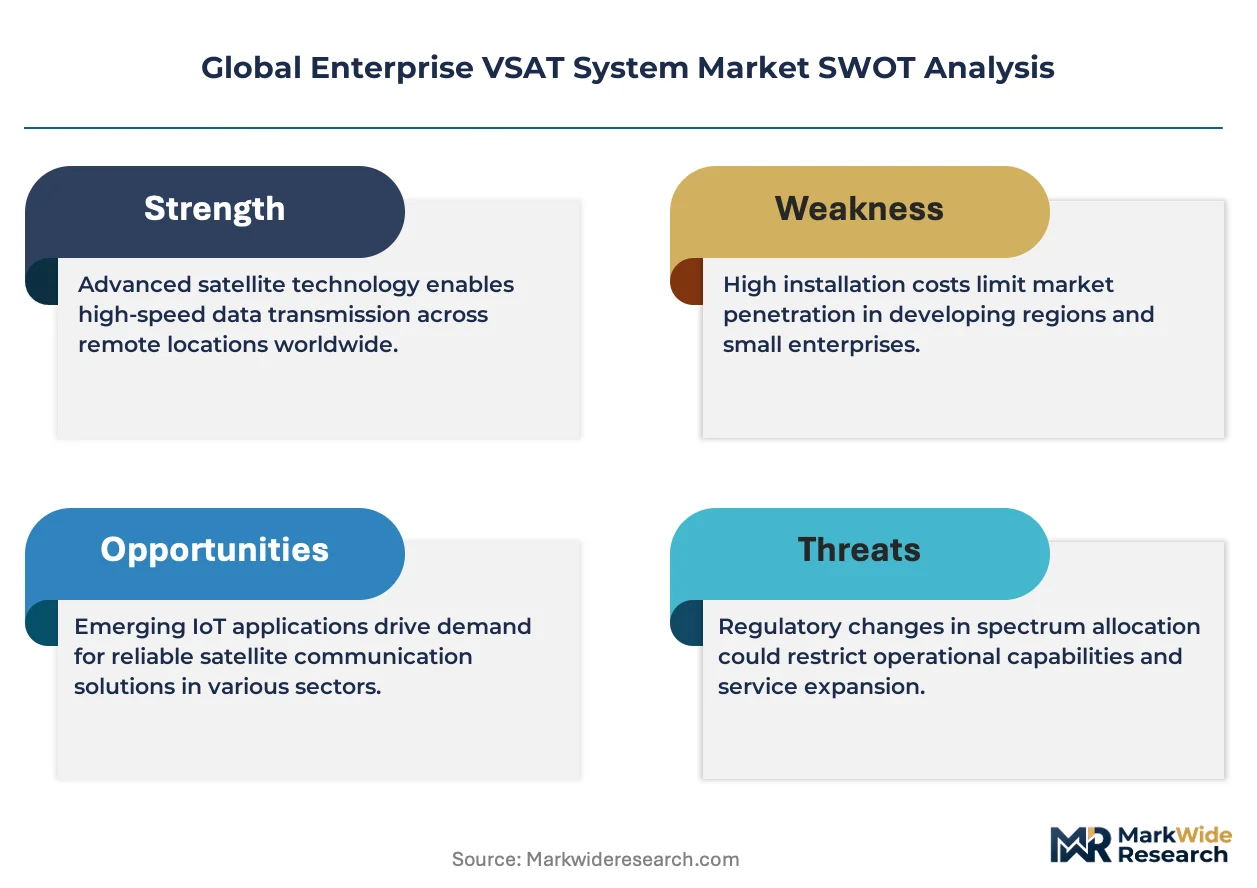
Flat-panel antenna architectures are compressing traditional parabolic hardware economics while spectrum scarcity in Ka-band forces operators toward medium-earth orbit constellations. This dual pressure reconfigures terminal vendor margins and constellation deployment priorities simultaneously.
Growth Catalysts
- Maritime digitization mandates:Southeast Asian fleet operators now require always-on crew welfare and operational data links, expanding addressable terminal demand across Indonesian and Vietnamese shipping lanes.
- FCC spectrum reallocation:Updated terminal certification rules in the United States accelerate hardware refresh cycles for enterprise subscribers seeking interference-resistant links.
- Offshore energy corridor gaps:Brazil's pre-salt oil fields lack fiber backhaul, positioning VSAT as the sole viable connectivity layer for remote platform operations.
Market Restraints
- Input cost volatility:Gallium nitride amplifier substrates face supply concentration from Chinese refiners, pressuring terminal bill-of-materials stability.
- Regulatory friction:Brazil's ANATEL homologation requirements impose 6-12 month certification delays for non-local manufacturers seeking market entry.
- Terrestrial substitution:Low-earth orbit broadband constellations threaten to displace geostationary VSAT in latency-sensitive enterprise applications.
Strategic Opportunities
- Cellular backhaul white space:Sub-Saharan African markets with uneconomical terrestrial infrastructure present untapped demand for gateway deployments.
- Technology convergence:Integration of electronically steerable arrays with 5G network slicing enables hybrid satellite-terrestrial service bundles.
- EU regulatory tailwind:The Radio Equipment Directive's streamlined CE marking pathways reduce time-to-market for compliant terminal portfolios.
Industry Challenges
- RF engineering talent scarcity:Specialized expertise in phased-array calibration remains concentrated among defense-sector veterans, constraining vendor hiring pipelines.
- Multi-constellation integration complexity:Enterprise buyers demand seamless handoff between geostationary and medium-earth orbit links, complicating modem firmware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise VSAT System Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed VSAT, Mobile VSAT, Portable VSAT, Maritime VSAT Technology: Ka-Band, Ku-Band, C-Band, X-Band Application: Oil & Gas Exploration, Military Communications, Broadband Connectivity, Disaster Management End User: Telecommunication Providers, Defense Agencies, Maritime Operators, Emergency Response Teams |
| Companies Covered | Hughes Network Systems, LLC, Viasat, Inc., Gilat Satellite Networks Ltd., Comtech Telecommunications Corp., SES S.A., Intelsat S.A., Telesat Corporation, ST Engineering iDirect, L3Harris Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise VSAT System Market Shifts & Advancements
Antenna form factors and spectrum utilization strategies are converging toward electronically steerable architectures that decouple physical pointing from link reliability. This shift compresses traditional installation timelines while opening new mobility applications.
Electronically steerable flat-panel arrays are migrating from fixed enterprise installations toward maritime and aeronautical platforms. Vessel operators in Southeast Asian shipping corridors now specify these terminals for crew welfare streaming and real-time engine telemetry. The technology is migrating from niche defense applications into mainstream commercial fleets as unit economics approach parabolic alternatives.
The FCC's updated Part 25 rules for earth station licensing impose stricter out-of-band emission limits on Ka-band terminals. This regulatory tightening forces manufacturers to redesign power amplifiers and filtering stages. Energy sector buyers in the United States now prioritize pre-certified hardware to avoid deployment delays.
Service contract structures are fragmenting from long-term bandwidth leases toward usage-based consumption models. Maritime fleet managers now demand per-gigabyte billing with burst capacity for port calls. This behavioral shift is most visible in Singapore and Rotterdam hub routes where vessel traffic density supports pooled capacity arrangements.
Global Enterprise VSAT System Market Segmentation
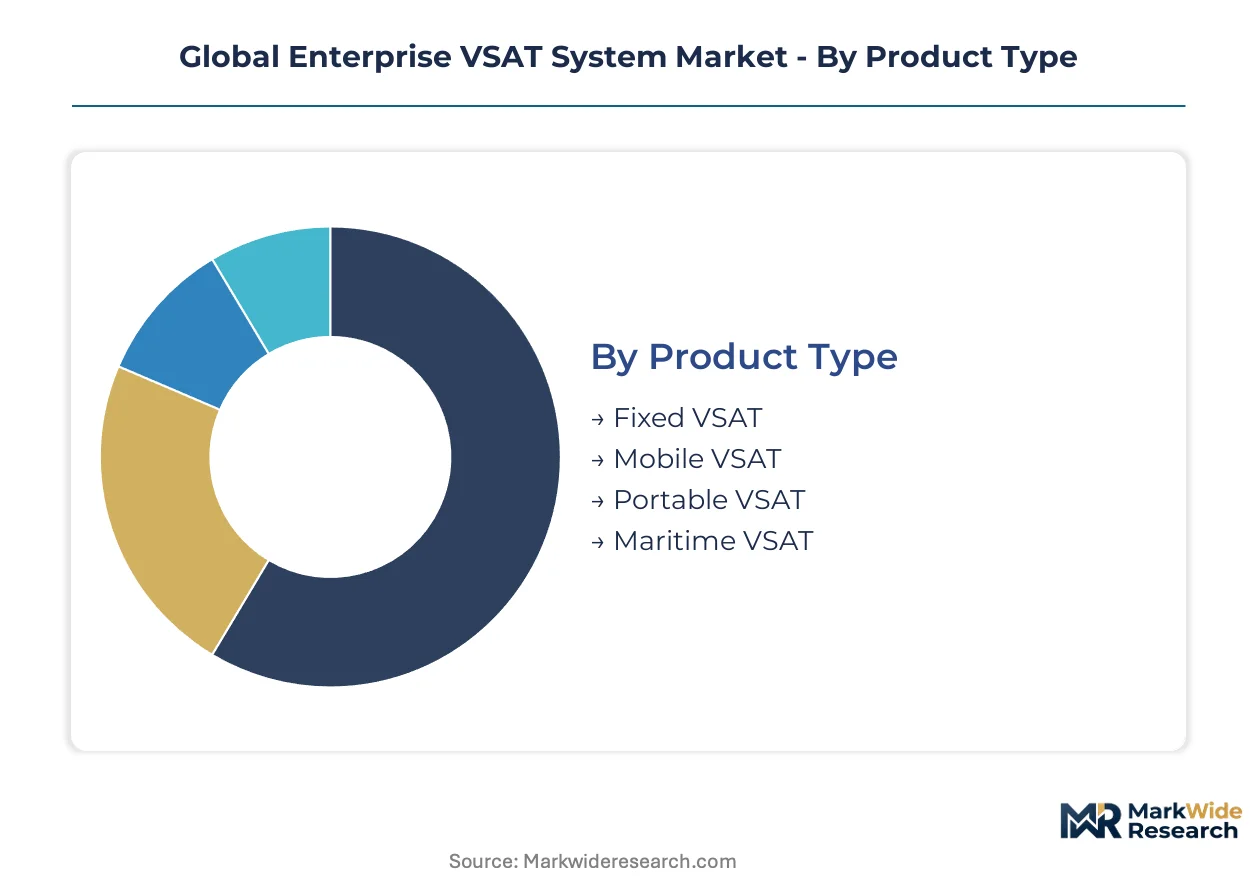
Enterprise VSAT procurement patterns diverge sharply across terminal mobility classes and frequency architectures. Buyers in remote industrial zones prioritize installation permanence and spectrum resilience over unit cost, while maritime operators trade hardware durability for link availability guarantees.
Product Type:
After-sales-service intensity varies dramatically across mobility tiers, with maritime deployments demanding 24/7 global sparing networks that fixed terrestrial installations rarely require.
- Fixed VSAT:Stationary ground terminals anchor permanent enterprise installations with parabolic or flat-panel architectures. Energy majors across Brazil's pre-salt corridor deploy these for platform telemetry where fiber backhaul remains unavailable. Service contracts typically span 5-7 years with guaranteed uptime clauses.
- Maritime VSAT:Stabilized antenna systems compensate for vessel motion through gyroscopic reference platforms. Indonesian and Vietnamese fleet operators now mandate these for crew welfare streaming under digitization directives. The segment commands premium service tiers due to salt corrosion exposure and remote repair logistics.
- Mobile VSAT:Vehicle-mounted terminals support rapid-deployment scenarios for emergency responders and military field units. These systems prioritize quick-stow mechanical designs over spectral efficiency.
- Portable VSAT:Man-portable flyaway terminals deliver suitcase-sized connectivity for disaster recovery and temporary events. Weight constraints limit antenna aperture, compressing link budgets compared to fixed equivalents.
Fixed VSAT holds the largest share; momentum sits with Maritime VSAT as fleet digitization mandates spread across Southeast Asian shipping lanes.
Technology:
Spectrum economics and rain fade resilience create distinct cost-performance tradeoffs that shape procurement decisions across climatic zones.
- Ka-Band:High-frequency spot-beam architectures deliver superior bits-per-Hertz throughput for bandwidth-intensive applications. United States energy sector buyers now prioritize Ka-band terminals certified under FCC's updated Part 25 emission rules. The frequency enables smaller apertures but suffers attenuation in tropical precipitation zones.
- Ku-Band:Mature ecosystem with established terminal supply chains and broader geographic beam coverage. Brazilian offshore operators favor Ku-band for its balance of availability and equipment sourcing flexibility.
- C-Band:Lower frequency allocation provides rain fade immunity critical for equatorial deployments. These systems require larger antennas, elevating installation costs.
- X-Band:Militarized spectrum reserved for defense and government applications with interference protection protocols. Terminal availability restricts to specialized vendors with security clearances.
Ku-Band retains the broadest installed base; Ka-Band is climbing the fastest as high-throughput satellite capacity expands.
Application:
Operational criticality determines whether VSAT serves as primary connectivity or backup failover, with corresponding impacts on redundancy architecture and service level agreements.
- Oil & Gas Exploration:Remote drilling platforms and seismic vessels require always-on links for real-time data telemetry and crew communications. Brazil's pre-salt fields represent concentrated demand where terrestrial alternatives remain uneconomical.
- Broadband Connectivity:Rural enterprise backhaul and community internet access drive volume deployments across North American zones beyond fiber reach. These applications tolerate higher latency than financial trading or defense use cases.
- Military Communications:Beyond-line-of-sight tactical networks demand anti-jam waveforms and rapid reconfiguration capabilities. Procurement flows through defense ministry budgets with multi-year program cycles.
- Disaster Management:First responders deploy portable terminals when terrestrial infrastructure fails. Usage spikes correlate with hurricane seasons and seismic events rather than steady consumption patterns.
Broadband Connectivity holds the largest share; Oil & Gas Exploration is gaining share fastest as offshore digitization accelerates.
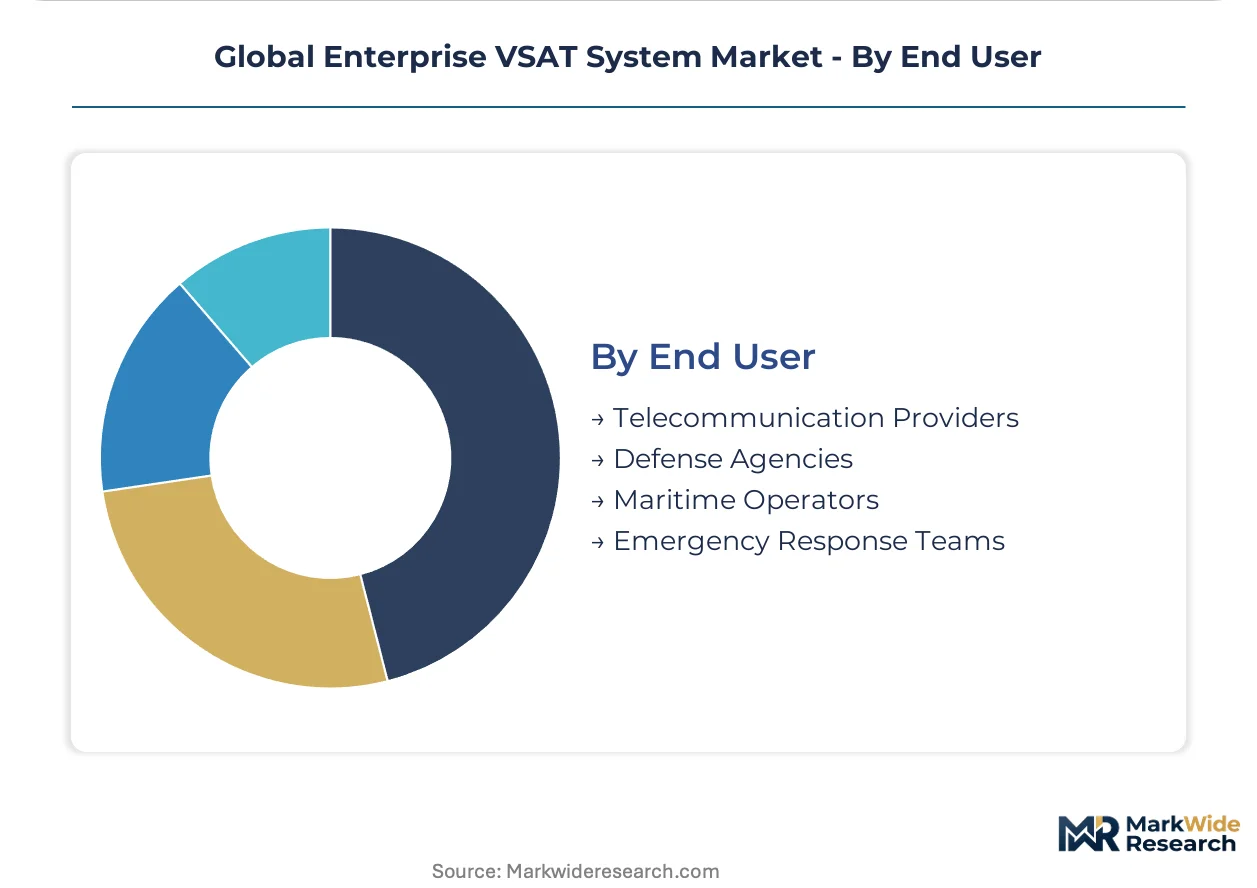
End User:
Procurement authority and technical specification control vary significantly across buyer categories, influencing vendor sales motion and contract structure.
- Telecommunication Providers:Mobile network operators deploy VSAT gateways for cellular backhaul in uneconomical terrestrial zones. Sub-Saharan African markets present concentrated demand where tower fiberization remains capital-constrained.
- Maritime Operators:Shipping companies and offshore vessel owners mandate connectivity for crew welfare compliance and engine monitoring. Southeast Asian registry fleets now specify minimum data rates in charter agreements.
- Defense Agencies:Military and paramilitary organizations require hardened terminals with encrypted waveforms and frequency-hopping resilience. Budget cycles extend 3-5 years with stringent qualification protocols.
- Emergency Response Teams:Government disaster management authorities and NGOs maintain rapid-deployment inventories for humanitarian crises. Funding derives from contingency appropriations rather than operational budgets.
Telecommunication Providers hold the largest share; Maritime Operators are expanding most quickly as regulatory mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States terminal manufacturers supply maritime operators across Southeast Asian shipping corridors. Brazilian offshore platforms absorb fixed VSAT capacity for pre-salt field telemetry. German industrial buyers demand CE-marked equipment for remote factory connectivity.
United States
FCC Part 25 rule updates mandate stricter out-of-band emission limits on Ka-band terminals, forcing hardware redesigns across power amplifier stages. Energy sector procurement now prioritizes pre-certified equipment to avoid deployment delays. Houston anchors domestic demand as Gulf Coast offshore operators refresh terminal fleets.
Brazil
ANATEL homologation requirements impose 6-12 month certification delays for non-local manufacturers, protecting domestic assembly operations. Pre-salt oil fields lack fiber backhaul, positioning VSAT as the sole viable connectivity layer for remote platform telemetry. Rio de Janeiro concentrates service provider operations serving the offshore energy corridor.
Indonesia
Fleet digitization mandates now require always-on crew welfare and operational data links across Indonesian and Vietnamese shipping lanes. The country's national telecommunications regulator enforces maritime communication standards that accelerate terminal refresh cycles. Jakarta serves as the regional hub for VSAT service provisioning across the archipelago.
Germany
The EU Radio Equipment Directive's streamlined CE marking pathways reduce time-to-market for compliant terminal portfolios entering continental markets. Industrial automation buyers in Baden-Württemberg deploy fixed VSAT for remote manufacturing site connectivity. Munich hosts several satellite service operators targeting Central European enterprise demand.
Singapore
Maritime fleet managers now demand per-gigabyte billing with burst capacity for port calls along Singapore and Rotterdam hub routes. The Maritime and Port Authority regulates vessel communication standards that embed minimum data rates into charter agreements. The city-state's shipping registry concentration supports pooled capacity arrangements for terminal operators.
Global Enterprise VSAT System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across terminal manufacturing and service provision. The vendor base spans vertically integrated satellite operators, dedicated hardware fabricators, and managed network service providers. Three archetypes dominate: capacity-owning constellation operators, terminal-focused equipment vendors, and hybrid service integrators. Competitive moves concentrate on spectrum portfolio expansion and electronically steerable array technology licensing.
Within the integrated-operator tier, Hughes Network Systems, LLC and Viasat, Inc. represent contrasting approaches to enterprise subscriber retention. Hughes anchors its position through managed network services footprints across North American rural zones. Viasat exemplifies vertical control spanning space segment and ground terminal production. Gilat Satellite Networks Ltd. occupies a specialist position in cellular backhaul gateway supply, serving markets where terrestrial infrastructure remains uneconomical.
| Leading Market Players |
|---|
| Hughes Network Systems, LLC |
| Viasat, Inc. |
| Gilat Satellite Networks Ltd. |
| Comtech Telecommunications Corp. |
| SES S.A. |
| Intelsat S.A. |
| Telesat Corporation |
| ST Engineering iDirect |
| L3Harris Technologies, Inc. |
| Others |
Supply & Pricing Matrix
Gallium nitride substrate concentration from Chinese refiners compresses terminal vendor margins while simultaneously forcing a three-tier pricing structure across premium, standard, and economy certification levels. This single-source dependency cascades through amplifier module costs and dictates where manufacturers anchor final assembly operations.
Pricing Analysis
The Ka-band versus Ku-band versus C-band technology-generation pricing gap spans roughly two-to-one from legacy parabolic systems to electronically steerable flat-panel arrays. Pricing stratifies across premium, standard, and economy tiers based on FCC Part 25 certification grade and after-sales service bundling intensity. Cost compression in standard-tier fixed terminals is intensifying because Brazilian energy buyers now demand pre-certified hardware to bypass ANATEL delays. Maritime operators show the least price sensitivity due to crew welfare compliance mandates, while rural broadband resellers in North America operate on thinnest margins.
Supply Chain Analysis
Upstream gallium nitride substrates draw from Chinese refiners, with secondary sourcing from Japanese and South Korean specialty chemical producers. Phased-array calibration expertise and RF engineering talent hinge on defense-sector veterans concentrated in the United States and Israel. Single-source vulnerability sits with GaN amplifier substrates where geopolitical friction threatens supply continuity. Distribution runs through authorized terminal distributors serving energy majors and direct service contracts with maritime fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory certification entrenchment creates sticky customer relationships that resist competitive displacement. The switching costs embedded in multi-year service contracts and homologation investments protect incumbent positions.
For Market Incumbents: Build switching-cost moats by deepening captive supply of GaN amplifier modules through backward integration into substrate sourcing. Anchor capacity addition in Brazil to circumvent ANATEL certification delays for local energy sector procurement. Defend against low-earth orbit broadband substitution by embedding hybrid satellite-terrestrial service bundles that complicate customer migration paths.
For New Entrants and Emerging Players: Build out cellular backhaul gateway deployments across Sub-Saharan African markets where tower fiberization remains capital-constrained. Target Indonesian maritime digitization mandates as the most penetrable segment given fleet refresh cycles and regulatory tailwinds. Pursue a channel partnership go-to-market angle with established service integrators rather than direct terminal sales.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated operators with captive satellite capacity and terminal manufacturing. Long-term viability across the projection horizon rests on spectrum portfolio depth and electronically steerable array technology licensing positions. Watch FCC Part 25 rule evolution as the inflection indicator for hardware refresh cycle acceleration and certification investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Electronically Steerable Array Licensing | Enables maritime and aeronautical mobility applications beyond fixed enterprise installations. |
| Brazilian Local Assembly Investment | Circumvents ANATEL homologation delays for pre-salt energy corridor terminal deployments. |
| Hybrid Satellite-Terrestrial Service Bundles | Integrates 5G network slicing with VSAT backhaul for latency-sensitive enterprise applications. |
| Sub-Saharan African Gateway Expansion | Captures cellular backhaul white space where terrestrial infrastructure remains uneconomical. |
| Ka-Band Power Amplifier Redesign | Addresses FCC Part 25 out-of-band emission limits for United States energy sector certification. |
Research Methodology
Desk research of ITU frequency coordination filings, FCC equipment authorization databases, and ANATEL homologation records preceded structured interviews with terminal procurement managers at energy majors, maritime fleet operators, and satellite service provider network engineers. Primary fieldwork with VSAT hardware engineering directors and cellular backhaul gateway deployment specialists was cross-checked against secondary validation from customs trade data and satellite operator capacity disclosure filings. Bottom-up terminal shipment estimates and top-down service revenue aggregates were triangulated for segment sizing.
Assumptions held fixed across the modeling period include constellation deployment timelines for medium-earth orbit systems and terrestrial 5G expansion trajectories in remote industrial zones. The analytical framework modeled terminal mobility classes, frequency architectures, and end-use verticals as core segmentation dimensions. CAGRs were derived from installed base evolution and replacement cycle compression. Forecast inputs incorporated gallium nitride substrate supply constraints and maritime digitization mandate adoption curves.
Stress conditions across gallium nitride supply disruption scenarios, FCC spectrum reallocation timing, and low-earth orbit broadband competitive encroachment were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory certification timeline shifts and constellation operational readiness. Cross-checking against satellite operator disclosed capacity utilization metrics and energy sector capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Attitude and Orbit Control System Market
Satellite
All-Electric Satellites Market
Satellite
Satellite Backhaul Market
Satellite
Europe Satellite IoT Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
Reconnaissance Satellite Market
Satellite
United Kingdom Satellite Communications Market
Satellite
UAE Satellite Communication Market
Satellite
Low-Cost Satellite Market
Satellite
EMEA Satellite Antenna Market
Satellite
Argentina Satellite Imagery Services Market
Satellite
Broadband Satellite System Market
Satellite
Canada Satellite-Based Earth Observation Market
Satellite
China Satellite-Based Earth Observation Market
Satellite
Satellite Operation Service Market
Satellite
Global Commercial Satellite Broadband Market