
 All-Electric Satellites Market | 2026-2036
All-Electric Satellites Market Size, Share, and Industry Trends Forecast 2026-2036
All-Electric Satellites Market Insights
ISO 9001 and AS9100 qualification cycles is bifurcating the supplier base into qualified aerospace tier-1 vendors and emerging commercial entrants. Airbus SE leverages its integrated satellite manufacturing footprint across European launch corridors. Boeing sustains long-standing relationships with U.S. government anchor customers through classified and civilian programs. Thales Alenia Space competes on dual-use telecommunications platforms that bridge commercial and defense specifications.
All-electric satellites replace conventional chemical propulsion with electric thruster systems—typically Hall effect or ion thrusters generating specific impulse values exceeding 1500 seconds—to perform station-keeping, orbit raising, and end-of-life disposal using solar-generated electrical power rather than onboard fuel mass. Hall Effect Thrusters dominate current production volumes due to mature heritage from geostationary programs, while Ion Thrusters capture investment focus for next-generation medium Earth orbit constellations demanding higher fuel efficiency. Telecommunications remains the anchor application segment, though Earth Observation is attracting accelerated procurement from defense and climate monitoring agencies.
FCC orbital debris mitigation rules and NASA technology readiness level requirements shape U.S. platform design standards, while ESA procurement guidelines and REACH material compliance constrain European subsystem sourcing. Commercial operators must navigate ITU spectrum coordination timelines alongside national export control frameworks that gate thruster technology transfers. Stakeholders should monitor how evolving debris remediation liabilities and propellant-less deorbit mandates recalculate total cost of ownership for constellation operators weighing electric against hybrid propulsion architectures.
Market Dynamics
Electric propulsion architectures are compressing satellite dry mass budgets, forcing subsystem suppliers to recalculate power density requirements and thermal management specifications across every mission profile.
Growth Catalysts
- FCC orbital debris mitigation rules:U.S. operators face mandatory deorbit timelines, making electric thrusters essential for propellant-efficient end-of-life disposal maneuvers.
- Geostationary telecom fleet renewal:Commercial operators retiring chemical-propulsion satellites are specifying all-electric platforms to maximize payload fraction and extend service life.
- Hall effect thruster heritage maturation:Decades of flight-proven operation on European and Asian geostationary programs have de-risked technology adoption for new entrants.
Market Restraints
- Xenon supply concentration:Global noble gas refining capacity clusters in Russia and Ukraine, creating input cost volatility and geopolitical sourcing exposure for thruster manufacturers.
- ITU spectrum coordination timelines:Multi-year filing queues for orbital slots and frequency assignments delay constellation deployment schedules regardless of platform readiness.
- Orbit-raising duration penalty:Electric propulsion requires weeks to months for geostationary transfer, compressing revenue-generating service windows versus chemical alternatives.
Strategic Opportunities
- Medium Earth orbit constellations:Next-generation broadband networks at intermediate altitudes favor ion thruster efficiency over Hall effect systems, opening new subsystem procurement categories.
- ESA Clean Space initiative:European procurement guidelines now mandate design-for-demise and active debris removal compatibility, creating specification advantages for all-electric platforms.
- Krypton propellant substitution:Emerging thruster designs using lower-cost noble gases are miniaturizing power processing units and reducing total propulsion system mass.
Industry Challenges
- Plasma physics specialization shortage:Thruster development requires rare expertise in discharge chamber modeling and magnetic topology optimization, constraining workforce scalability.
- AS9100 certification timelines:New subsystem vendors face 18-24 month qualification cycles to meet aerospace quality standards, delaying market entry regardless of technical readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | All-Electric Satellites Market |
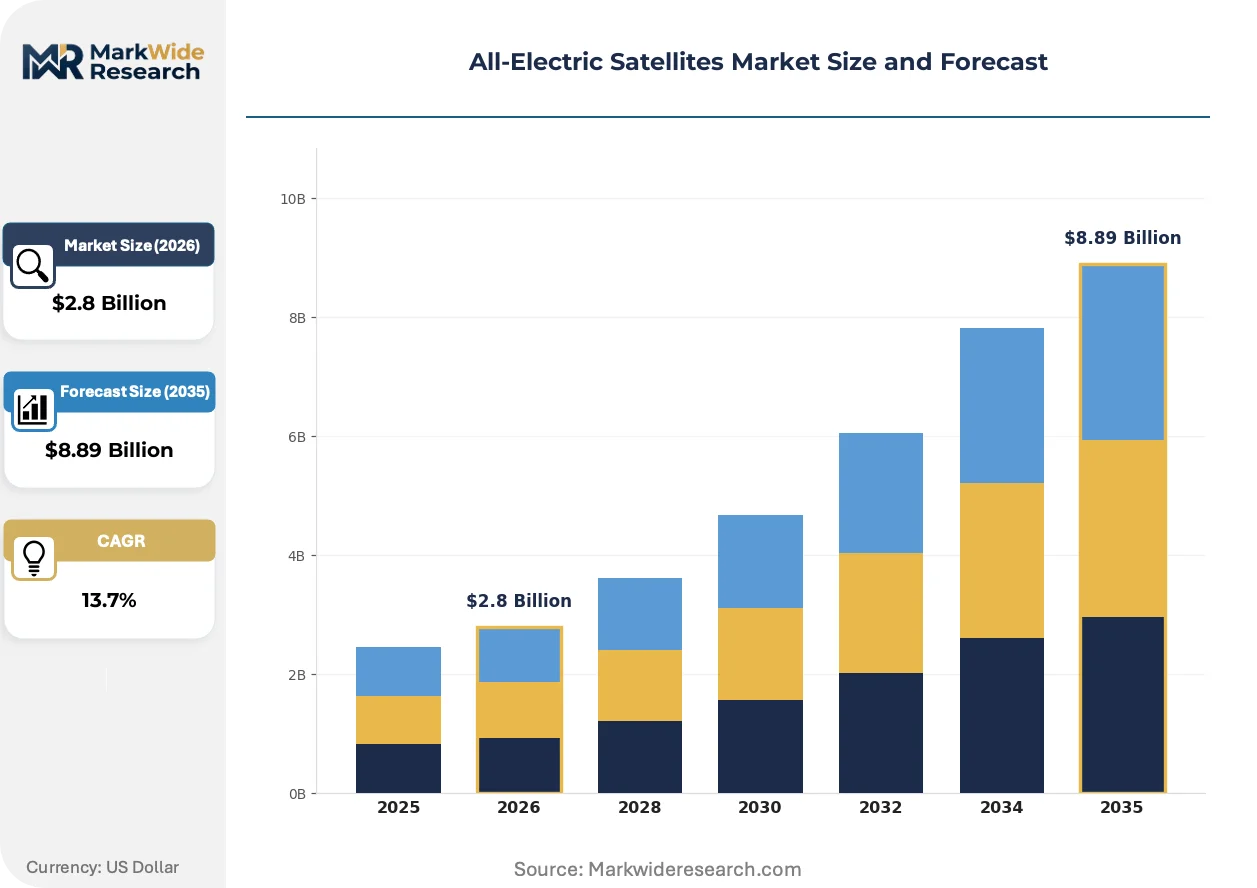
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.89 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propulsion Type: Hall Effect Thrusters, Ion Thrusters, Pulsed Plasma Thrusters, Electrostatic Thrusters, Magnetoplasmadynamic Thrusters Satellite Application: Telecommunications, Earth Observation, Scientific Research, Navigation, Space Exploration End User: Commercial Operators, Government Agencies, Defense Organizations, Space Research Institutes Orbit Type: Low Earth Orbit, Medium Earth Orbit, Geostationary Orbit, Highly Elliptical Orbit |
| Companies Covered | Airbus SE, Northrop Grumman Corporation, The Boeing Company, Lockheed Martin Corporation, Thales Alenia Space, Safran SA, L3Harris Technologies, OHB, SpaceX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
All-Electric Satellites Market Trends and Innovations
Propulsion subsystem evolution is intersecting with power electronics advancement and regulatory pressure to redefine platform architecture trade-offs across orbital regimes.
Solid-state power processing units are replacing conventional DC-DC converters in Hall effect thruster systems. Constellation operators procuring small satellite buses are specifying integrated propulsion modules to reduce assembly complexity. This integration is miniaturizing discharge supply electronics and enabling single-string redundancy architectures previously impossible at kilowatt power levels.
REACH material compliance is constraining European thruster manufacturers' sourcing of specialized ceramics and magnetic alloys. The regulation's substance restriction lists now cover several heritage materials used in discharge channel liners and pole piece assemblies. French and German subsystem suppliers are accelerating qualification of alternative ceramics to maintain ESA program eligibility.
Service-based propulsion procurement is emerging as constellation operators seek to transfer thruster lifetime risk to subsystem vendors. Prime contractors are responding with power-by-the-hour contracts covering orbit-raising and station-keeping duty cycles. This model is most visible in U.S. low Earth orbit broadband deployments, where operators prioritize predictable operating expenditures over capital-intensive subsystem ownership.
All-Electric Satellites Market Segmentation
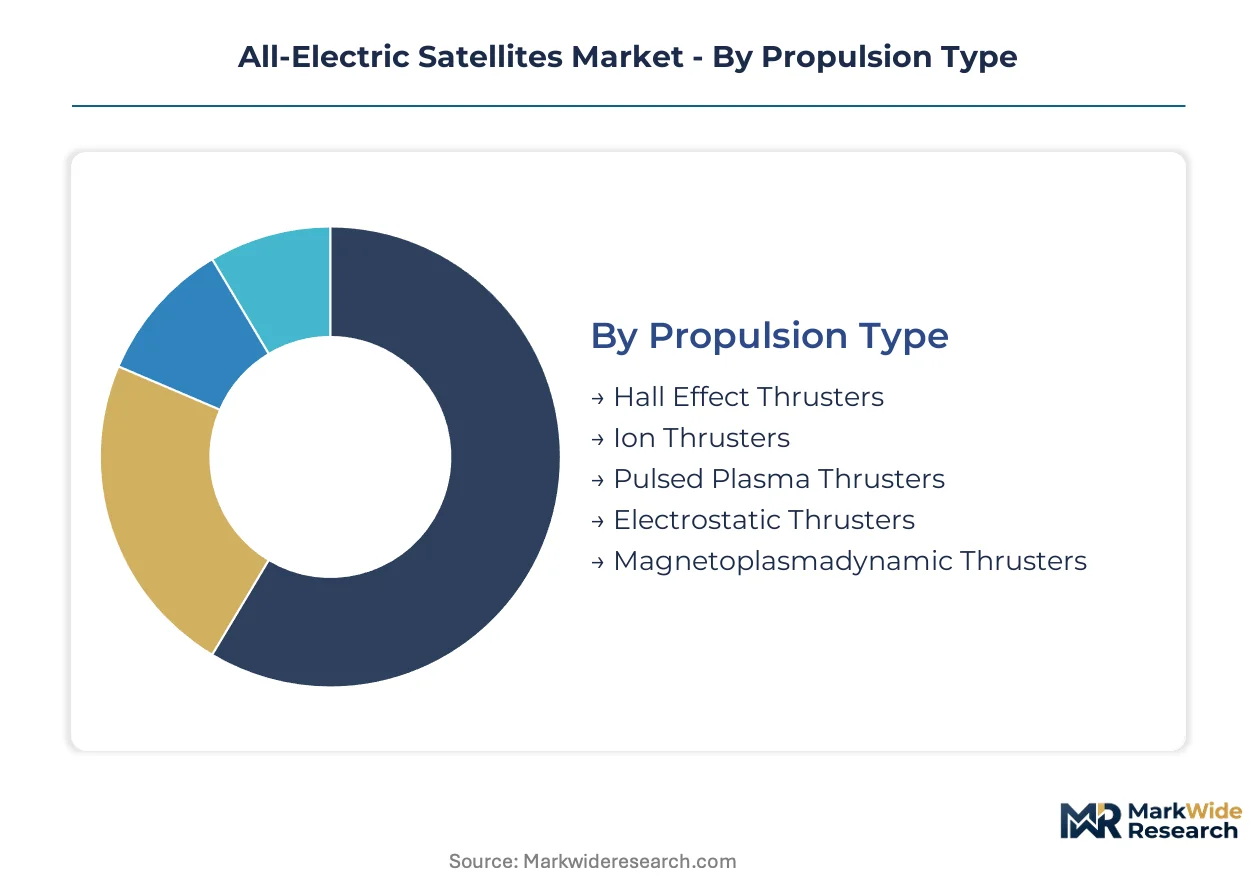
Electric satellite architectures fragment across propulsion physics, orbital regimes, and procurement authority, with each axis carrying distinct margin structures and qualification barriers. Segment boundaries are blurring as constellation operators demand modular thruster packages adaptable across multiple mission profiles.
Propulsion Type:
Highest margins concentrate in thruster categories with flight heritage and xenon-compatible power processing units, where AS9100 qualification creates vendor stickiness.
- Hall Effect Thrusters:These devices accelerate ions using perpendicular electric and magnetic fields in an annular discharge chamber, achieving specific impulse values between 1500-2000 seconds. Commercial geostationary operators in the United States specify Hall systems for station-keeping based on decades of European flight heritage and proven reliability against FCC deorbit mandates.
- Ion Thrusters:Gridded electrostatic acceleration produces exhaust velocities exceeding 30 km/s, maximizing propellant efficiency for high-delta-V missions. Medium Earth orbit broadband constellations favor ion architectures for orbit-raising efficiency, though procurement volumes remain constrained by power processing unit complexity and longer qualification cycles.
- Pulsed Plasma Thrusters:Ablative solid propellant systems using Teflon fuel bars and capacitor discharge ignition suit cubesat-scale momentum management.
- Electrostatic Thrusters:Colloid and field emission variants target precision formation flying for scientific interferometry missions.
- Magnetoplasmadynamic Thrusters:High-power coaxial electrode designs remain laboratory-stage for future crewed Mars transfer applications.
The dominant share belongs to Hall Effect Thrusters, while Ion Thrusters is closing the gap fastest.
Satellite Application:
Application segments diverge sharply in power budget allocation, with telecom platforms dedicating 30-40% of dry mass to propulsion versus sub-10% shares in Earth observation.
- Telecommunications:Geostationary broadcast and broadband relay satellites deploy electric propulsion for orbit raising and 15-year station-keeping duty cycles. U.S. operators retiring chemical fleets specify all-electric replacements to maximize payload mass fraction and comply with FCC orbital debris rules.
- Earth Observation:Synthetic aperture radar and multispectral imaging constellations prioritize propellant-efficient constellation phasing and collision avoidance maneuvers. Defense and climate monitoring agencies in the United States are accelerating procurement of agile platforms with electric thrust vectoring.
- Scientific Research:Deep space probes and heliophysics missions leverage electric propulsion for extended low-thrust trajectories.
- Navigation:GPS augmentation and alternative PNT constellations require precise orbit maintenance.
- Space Exploration:Lunar gateway logistics and asteroid rendezvous missions test high-power electric propulsion for crewed architectures.
Telecommunications commands the largest revenue pool, though Earth Observation is expanding most quickly.
End User:
Procurement authority shapes contract structures, with defense organizations demanding fixed-price qualification milestones and commercial operators favoring power-by-the-hour service models.
- Commercial Operators:Constellation developers and geostationary fleet managers procure integrated propulsion modules through long-term supply agreements. U.S. low Earth orbit broadband ventures are transferring thruster lifetime risk to subsystem vendors via operational expenditure contracts.
- Government Agencies:NASA and civilian space programs fund technology maturation through cost-plus development contracts.
- Defense Organizations:Classified programs require ITAR-compliant supply chains and domestic thruster manufacturing.
- Space Research Institutes:University and laboratory missions access flight-proven thrusters through rideshare and hosted payload arrangements.
Commercial Operators generate the highest absolute demand, while Government Agencies provide the steadiest funding commitment.
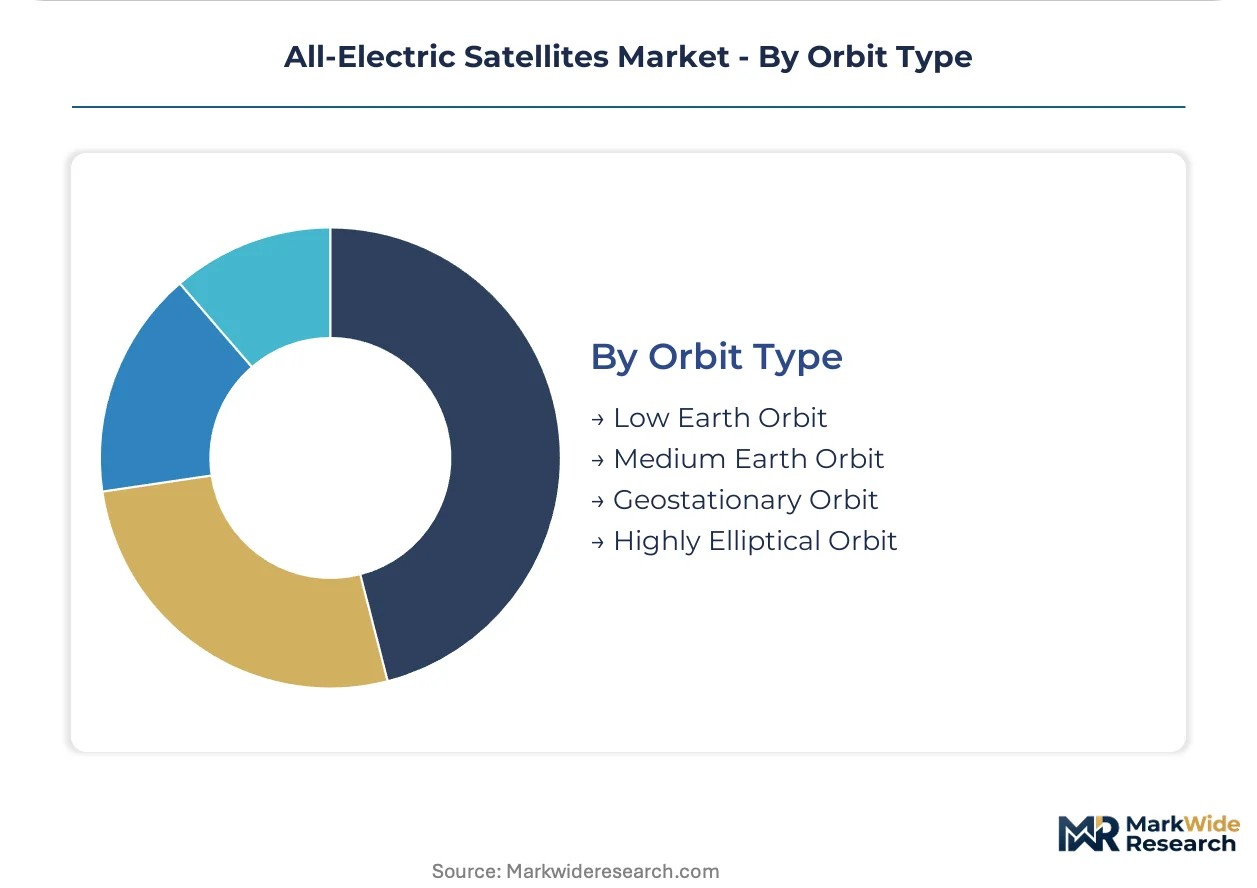
Orbit Type:
Orbital altitude determines radiation tolerance requirements and eclipse duration, driving power processing unit specification divergence.
- Geostationary Orbit:Station-keeping at 35,786 km altitude demands continuous thrust for inclination control and longitude maintenance. U.S. telecom operators retiring legacy chemical satellites specify all-electric replacements to extend service life and reduce launch mass.
- Low Earth Orbit:Constellation deployment and atmospheric drag compensation favor high-thrust-density Hall thrusters. FCC debris mitigation rules mandate propellant-efficient deorbit capability for LEO platforms.
- Medium Earth Orbit:Intermediate altitudes balance coverage footprint with latency, favoring ion thruster efficiency for orbit raising.
- Highly Elliptical Orbit:Molniya and Tundra orbits for high-latitude coverage require apogee raising maneuvers.
Geostationary Orbit retains the largest installed base, though Low Earth Orbit is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC orbital debris mitigation rules and NASA technology readiness requirements are accelerating U.S. platform procurement, while ESA Clean Space mandates and REACH compliance reshape European sourcing strategies across the supplier base.
United States
Commercial telecom operators in the United States are retiring chemical-propulsion fleets and specifying all-electric replacements to maximize payload mass fraction. FCC spectrum policies and mandatory deorbit timelines favor lighter, more maneuverable satellite architectures. Los Angeles and Denver corridors host integrated satellite manufacturing clusters where prime contractors consolidate Hall thruster supply chains.
France
French subsystem suppliers are accelerating qualification of alternative ceramics to maintain ESA program eligibility under REACH substance restrictions. The ESA Clean Space initiative mandates design-for-demise and active debris removal compatibility, creating specification advantages for all-electric platforms. Toulouse anchors European geostationary platform assembly with integrated thruster testing facilities.
Germany
German propulsion specialists face 18-24 month AS9100 certification cycles that delay market entry for emerging commercial entrants. ESA procurement guidelines constrain subsystem sourcing to qualified aerospace tier-1 vendors. Munich and Bremen concentrate Hall effect thruster heritage manufacturing with flight-proven discharge chamber modeling capabilities.
Japan
Japanese METI funding supports ion thruster maturation for medium Earth orbit constellation applications demanding higher fuel efficiency. Domestic manufacturers prioritize gridded electrostatic acceleration systems for next-generation broadband networks. Tsukuba and Nagoya host plasma physics research institutes specializing in magnetic topology optimization for electric propulsion.
United Kingdom
UK defense organizations require ITAR-compliant supply chains and domestic thruster manufacturing for classified programs. The UK Space Agency coordinates national procurement with ESA framework contracts for dual-use telecommunications platforms. Harwell and Glasgow clusters concentrate small satellite bus integration with electric propulsion module specification.
All-Electric Satellites Market Competitive Landscape
Player mix skews toward integrated prime contractors with captive propulsion capabilities and specialized subsystem vendors seeking AS9100 qualification. Market structure concentrates around aerospace heritage conglomerates with geostationary flight heritage and emerging commercial entrants commercializing krypton-compatible thruster designs. Two strategic archetypes dominate: vertically integrated satellite manufacturers with in-house thruster production, and independent propulsion specialists pursuing power-by-the-hour service contracts. Competitive moves center on M&A to secure xenon supply chain access and strategic partnerships for constellation-scale propulsion module procurement.
Among European integrated primes, Airbus SE and Thales Alenia Space exemplify the heritage-tier archetype with established ESA program relationships and REACH-compliant supply chains. Safran SA occupies a position within the specialized subsystem tier, representing French propulsion expertise concentrated in discharge chamber heritage manufacturing. These three anchors demonstrate how flight-proven qualification cycles create vendor stickiness in geostationary procurement while constellation operators seek operational expenditure models that transfer lifetime risk.
| Leading Market Players |
|---|
| Airbus SE |
| Northrop Grumman Corporation |
| The Boeing Company |
| Lockheed Martin Corporation |
| Thales Alenia Space |
| Safran SA |
| L3Harris Technologies |
| OHB |
| SpaceX |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month AS9100 certification cycles concentrate supplier power among heritage aerospace tier-1 vendors, compressing margins for emerging entrants while amplifying pricing leverage for qualified incumbents serving FCC-mandated deorbit timelines.
Pricing Analysis
Certification level (AS9100/REACH-compliant) creates the primary spread between heritage subsystem vendors and commercial entrants. Three-tier pricing structure across flight-proven, qualified-alternative, and developmental tiers reflects xenon-compatible power processing unit maturity. Pricing pressure stems from krypton propellant substitution programs miniaturizing discharge supply electronics. Commercial constellation operators exhibit highest price sensitivity through power-by-the-hour procurement models, while defense organizations accept premium tiers for ITAR-compliant domestic manufacturing.
Supply Chain Analysis
Eighteen-to-twenty-four-month inventory cycles for specialized ceramics and magnetic alloys expose European thruster manufacturers to REACH substance restriction disruptions. Xenon refining capacity clusters in Russia and Ukraine, while Hall effect thruster heritage manufacturing concentrates in France and Germany. Supply chains draw from noble gas extraction, precision ceramic fabrication, and radiation-hardened power electronics. Single-source vulnerability runs through geopolitically exposed xenon supply. Distribution runs through prime contractor integration facilities in Los Angeles, Denver, Toulouse, and Munich corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The all-electric satellites market functions as a regulatory-entrenchment defensive moat, where AS9100 qualification cycles and FCC debris mitigation mandates create switching costs that lock in heritage vendor relationships across multi-satellite procurement programs.
For Market Incumbents: Compound flight heritage advantages through captive krypton thruster development programs and strategic xenon supply agreements. Vertical integration into solid-state power processing units defends against emerging entrants commercializing integrated propulsion modules. Accelerate REACH-compliant alternative ceramic qualification to maintain ESA program eligibility against French and German subsystem specialists.
For New Entrants and Emerging Players: Differentiate on krypton-compatible miniaturized discharge supply electronics for low Earth orbit constellation operators seeking operational expenditure models. White-space concentrates in medium Earth orbit ion thruster procurement for next-generation broadband networks, and in service-based propulsion contracts transferring lifetime risk from constellation developers. Target U.S. commercial operators through power-by-the-hour offerings bypassing capital-intensive subsystem ownership barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a procurement-concentration play because constellation-scale deployments consolidate supplier relationships around vendors with flight-proven qualification cycles. Acquisition targets center on specialized subsystem vendors with plasma physics expertise and pending AS9100 certification. Signal to monitor: ESA Clean Space initiative procurement volumes shifting specification advantages toward design-for-demise compatible platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Krypton Thruster Development Program | Reduces xenon supply chain exposure while miniaturizing power processing unit mass for constellation operators. |
| AS9100 Certification Investment | Unlocks ESA and NASA procurement eligibility for emerging subsystem vendors seeking heritage-tier contracts. |
| Power-by-the-Hour Service Launch | Transfers thruster lifetime risk to vendors, aligning revenue models with commercial constellation operator preferences. |
| REACH-Compliant Ceramic Qualification | Maintains European program eligibility as substance restrictions eliminate heritage discharge channel liner materials. |
| Xenon Supply Agreement Securement | Mitigates geopolitical sourcing concentration risk through long-term offtake contracts with noble gas refiners. |
Research Methodology
Initial hypotheses were tested against primary input from satellite platform engineers, electric propulsion subsystem specialists, constellation procurement directors, and regulatory affairs managers at space agencies, then refined through secondary validation against ESA procurement guidelines, FCC orbital debris mitigation filings, NASA technology readiness level documentation, and REACH substance restriction updates. Bottom-up triangulation across thruster unit economics and top-down validation against constellation deployment schedules anchored market sizing.
Variance decomposition across the projection horizon isolates volume drivers (constellation deployment rates, geostationary fleet replacement cycles) from price drivers (xenon cost volatility, certification tier premiums). Segmentation dimensions modeled include propulsion physics type, orbital regime, application vertical, procurement authority, and regional regulatory framework. CAGRs derive from fitted adoption curves incorporating Hall effect thruster heritage maturation and ion thruster efficiency advantages for medium Earth orbit altitudes.
The analysis sits within stated boundaries; outcomes outside FCC rule stability, ESA funding continuity, or noble gas supply normalization would require recalibration. Forecasts reflect documented assumptions about technology readiness level progression and debris mitigation liability allocation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Small Satellite Launch Market
Satellite
Satellite Transponder Market
Satellite
Israel Satellite Imagery Services Market
Satellite
United States Satellite Communications Market
Satellite
Low-Cost Satellite Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
Europe Satellite Launch Vehicle Market
Satellite
Japan Satellite Imagery Services Market
Satellite
Commercial LEO Satellite Market
Satellite
Global Commercial Satellite Broadband Market
Satellite
Spain Satellite Imagery Services Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
Global Commercial Satellite Imagery Market
Satellite
Global Small Satellite Service Market
Satellite
France Satellite Connectivity Market