
 Russia Satellite Connectivity Market | 2026-2036
Russia Satellite Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Satellite Connectivity Market Insights
Russia's orbital infrastructure expansion is rewriting the competitive map for domestic satellite services. Gazprom Space Systems leverages its energy-sector anchor customer base to sustain predictable demand for Ku-band capacity across remote extraction sites. Rostelecom competes through last-mile integration, bundling satellite links with terrestrial fiber where ground infrastructure remains sparse. Bureau 1440 specializes in classified government payloads, occupying a protected segment insulated from commercial price pressure.
Satellite connectivity denotes the transmission of voice, video, and data signals via artificial Earth-orbiting relay stations operating across designated frequency allocations, with Ka-band systems delivering throughput exceeding 100 Mbps per terminal through spot-beam architecture. The primary commercial purpose spans broadband extension to unserved territories, broadcast distribution, and mission-critical communications for mobile platforms. Ku-band broadcast services dominate current revenue pools across Russia's vast territory, while Ka-band internet access represents the fastest-expanding segment driven by enterprise and consumer broadband substitution. Military service type commands premium pricing through hardened encryption requirements and dedicated orbital resources.
Russia's Federal Service for Supervision of Communications, Information Technology and Mass Media (Roskomnadzor) enforces licensing regimes that shape foreign operator market access and mandate domestic ground station presence. The State Commission for Radio Frequencies coordinates spectrum assignments that directly determine which bands operators may commercialize, with Ka-band allocations increasingly favored for broadband services. State security certification requirements from the Federal Security Service impose technical standards limiting non-Russian equipment deployment in sensitive applications. Stakeholders must monitor the trajectory of import-substitution mandates and their accelerating impact on supply chain configuration for terminal manufacturing.
Market Dynamics
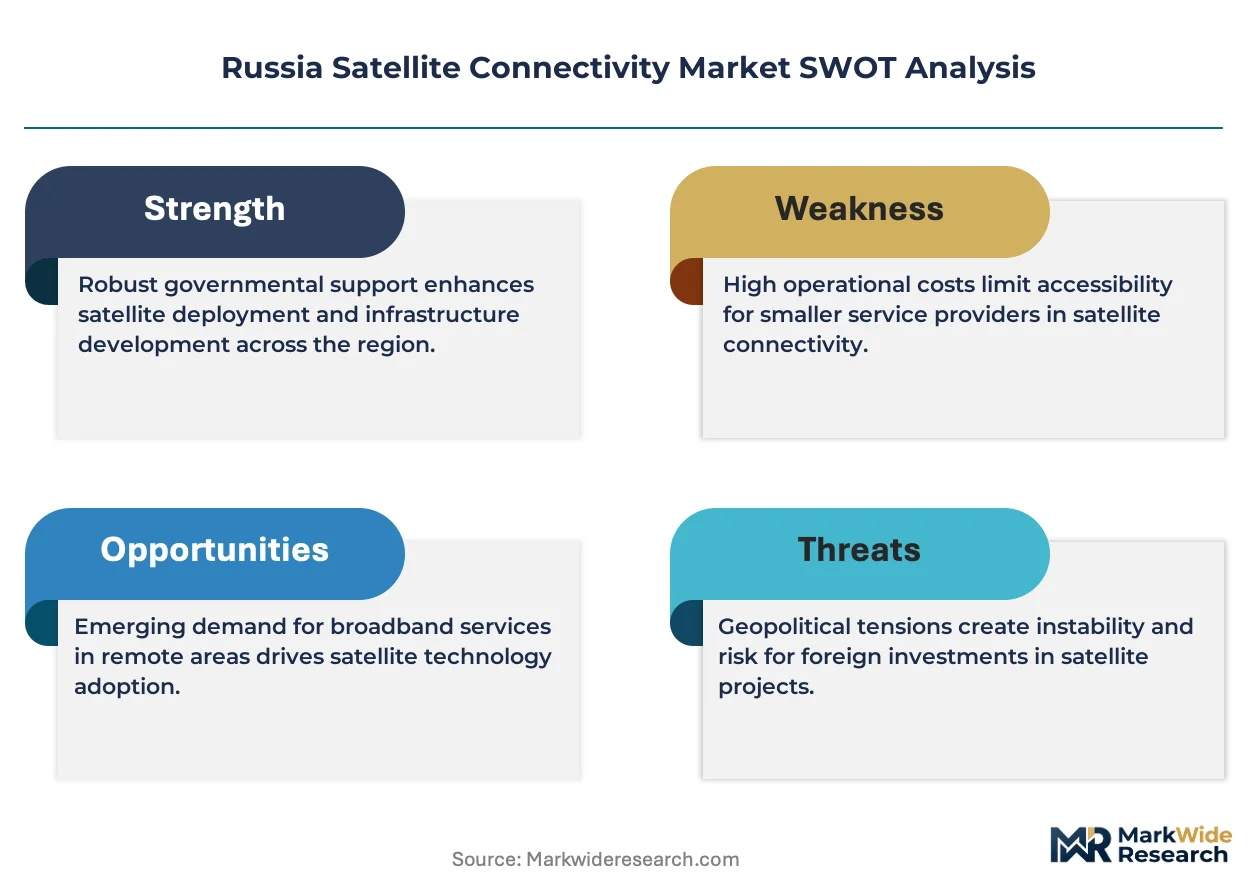
Ka-band spot-beam architectures are compressing Ku-band economics across Russia's broadband extension projects, while Roskomnadzor licensing mandates force foreign operators into domestic ground station partnerships that reshape competitive entry costs.
Growth Catalysts
- Federal Security Service certification standards:Hardened encryption requirements for military service types sustain premium pricing tiers that subsidize commercial segment development.
- Remote extraction site connectivity:Energy sector anchor demand across Siberian and Arctic territories generates predictable capacity commitments for satellite operators.
- State Commission for Radio Frequencies spectrum policy:Accelerated Ka-band allocations enable throughput exceeding 100 Mbps per terminal, unlocking enterprise broadband substitution.
Market Restraints
- Import-substitution mandates:Terminal manufacturing supply chains face forced reconfiguration away from non-Russian component sources, extending procurement timelines.
- Terrestrial fiber substitution:Rostelecom's last-mile bundling in population corridors erodes addressable market for satellite broadband in European Russia.
- Orbital resource scarcity:Dedicated military frequency reservations constrain commercial spectrum availability in protected bands.
Strategic Opportunities
- Far Eastern Federal District underpenetration:Sparse ground infrastructure across Sakha and Kamchatka creates captive demand for mobile platform communications.
- Consumer broadband substitution:Ka-band residential access represents white space as terrestrial alternatives fail to reach remote settlements.
- Convergence with IoT sensors:Satellite backhaul for industrial monitoring networks combines with energy sector digitalization mandates.
Industry Challenges
- Specialized RF engineering talent scarcity:Domestic workforce gaps in Ka-band system design delay deployment schedules for new orbital assets.
- Legacy Ku-band terminal integration:Enterprise customers demand backward compatibility that complicates spot-beam architecture rollouts.
- Ground station certification timelines:Federal Security Service technical audits extend facility commissioning by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Satellite Connectivity Market |
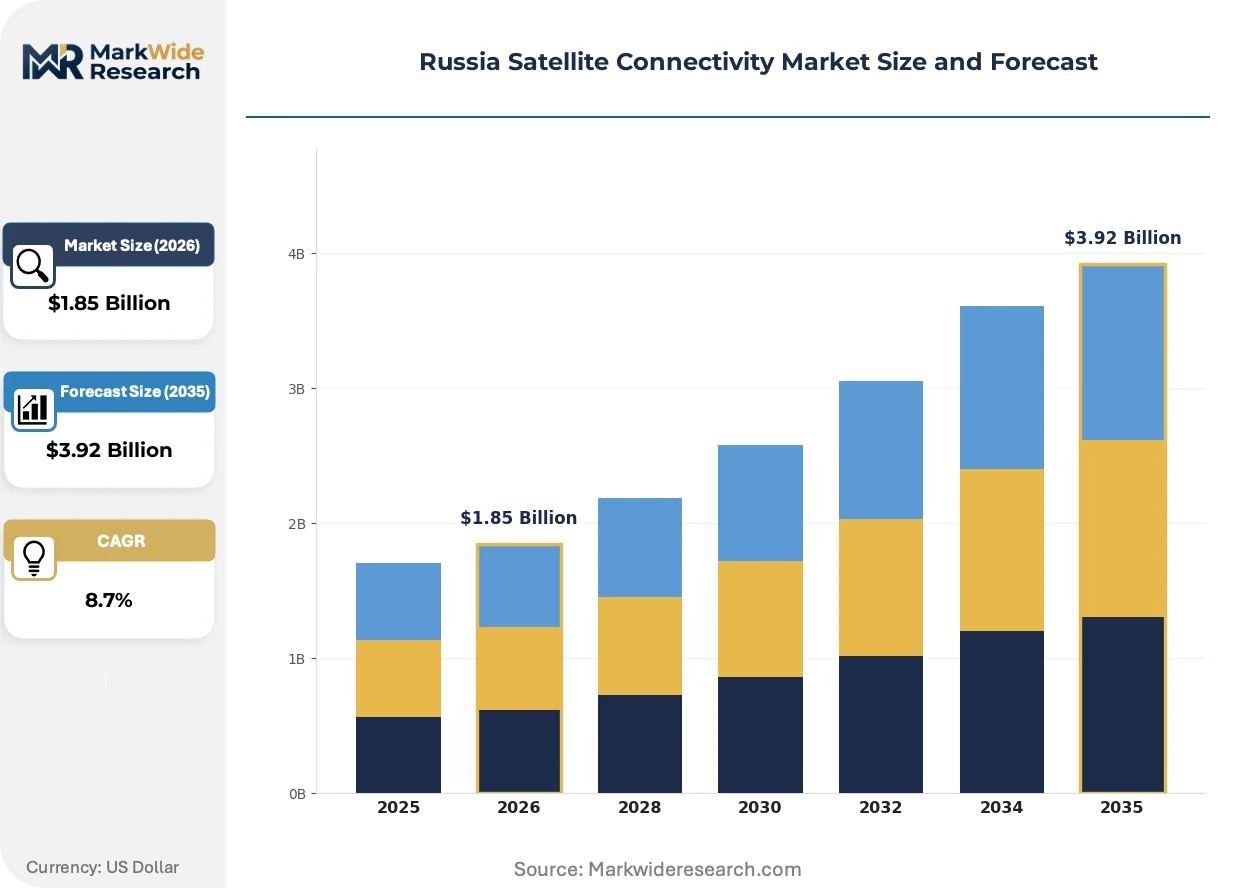
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: L-band, Ku-band, Ka-band, Multi-band Service Type: Broadcast, Internet, Military, Telecommunications End User: Government, Aviation, Maritime, Enterprise Deployment: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Russian Satellite Communications Company, Bureau 1440, Rostelecom, Gazprom Space Systems, AltegroSky, RTComm, Sputnix, Raduga-Internet, ICS Holding, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Satellite Connectivity Market Trends and Innovations
Active beamforming and software-defined payloads are compressing traditional satellite economics, while procurement patterns shift toward managed service contracts that bundle capacity with terrestrial integration.
High-throughput satellites equipped with reconfigurable spot beams are rendering obsolete fixed-beam Ku-band architectures that served Russia's broadcast distribution market for two decades. Energy sector buyers in Yamalo-Nenets and Krasnoyarsk Krai are migrating contracts to Ka-band within 18-24 month refresh cycles. The technology is compressing price per megabit to levels that threaten legacy operator margin structures.
Roskomnadzor's foreign operator licensing regime now mandates domestic legal entity establishment and ground station presence as conditions for spectrum access. This policy friction is diverting capital toward local partnership structures rather than direct market entry. European and Asian satellite operators are responding through joint ventures with Russian terrestrial carriers.
Enterprise buyers in aerospace and defense contractor clusters are consolidating procurement under multi-year managed service agreements that unbundle hardware ownership from capacity access. System integrators in Moscow's technopolis districts are displacing direct operator relationships. This pattern concentrates most visibly among classified government payload contractors seeking single-vendor accountability.
Russia Satellite Connectivity Market Segmentation
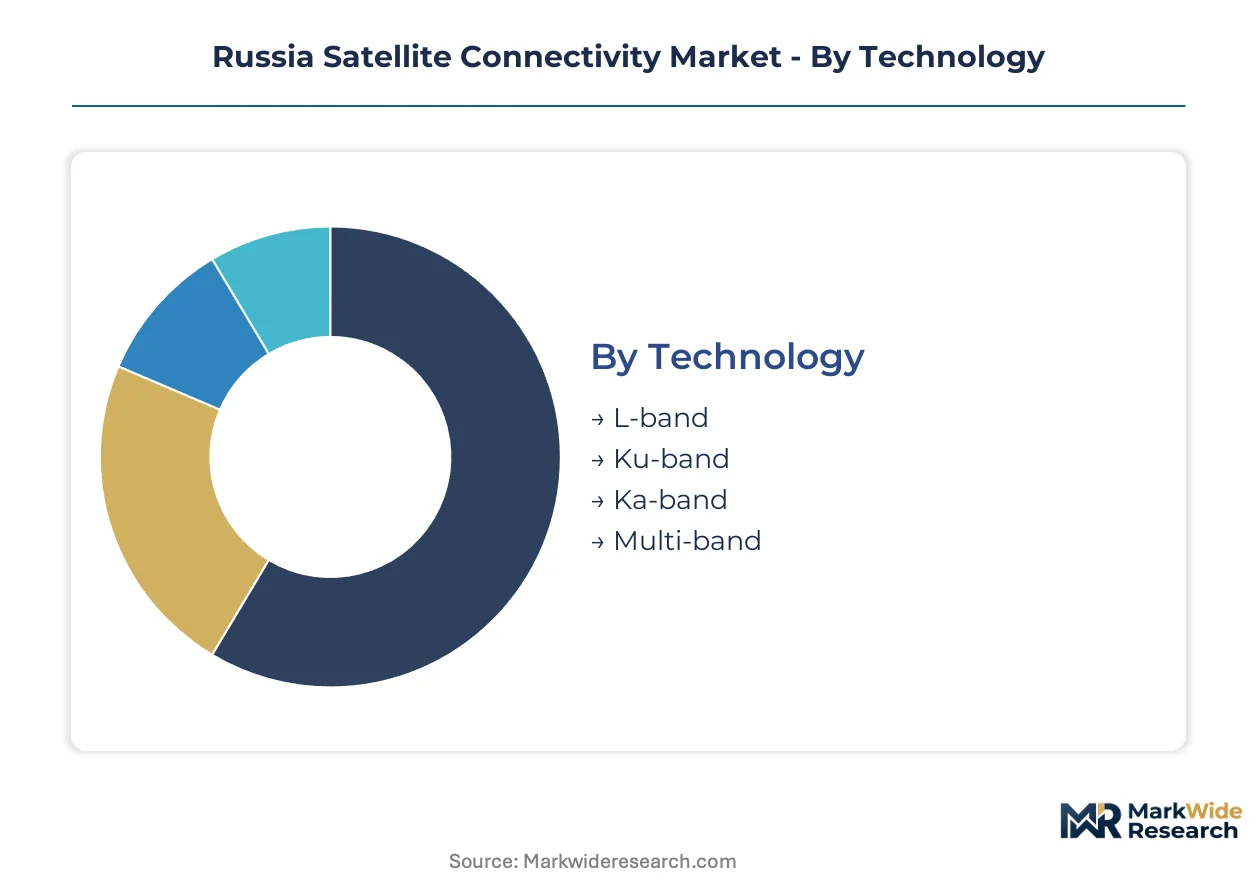
Russia's satellite connectivity market fragments across frequency bands, service applications, and deployment architectures that each carry distinct regulatory and commercial imperatives. Understanding these divides reveals where capital concentrates and where policy creates protected profit pools.
Technology:
Mature Ku-band architectures dominate current revenue while Ka-band systems represent the emerging throughput frontier reshaping competitive economics.
- Ku-band:Fixed-beam architectures operating in the 12-18 GHz range deliver proven broadcast distribution and enterprise broadband across Russia's established ground station footprint. Energy extraction sites in Yamalo-Nenets and Krasnoyarsk Krai sustain predictable capacity commitments through long-term contracts.
- Ka-band:Spot-beam systems in the 26.5-40 GHz allocation enable throughput exceeding 100 Mbps per terminal through frequency reuse and narrow beamwidth. State Commission for Radio Frequencies spectrum policy is accelerating deployment for broadband substitution in remote settlements.
- L-band:Lower frequency allocation provides resilient mobile connectivity for maritime and aeronautical platforms requiring all-weather signal penetration.
- Multi-band:Hybrid terminal architectures combine frequency flexibility for mission-critical government and defense applications requiring service continuity.
Ku-band handles the majority of throughput; Ka-band is the fastest mover on share.
Service Type:
Application-driven cost tiers separate premium military services from commoditized broadcast distribution.
- Broadcast:One-to-many video distribution across Russia's vast territory leverages Ku-band economies for television and radio relay. State media distribution contracts provide baseline revenue stability for orbital operators.
- Military:Hardened encryption requirements and dedicated orbital resources command premium pricing through Federal Security Service certification standards. Bureau 1440 and classified payload contractors anchor demand in this protected segment.
- Internet:Ka-band broadband extension targets consumer and enterprise substitution where terrestrial fiber remains uneconomical.
- Telecommunications:Backhaul and trunking services integrate satellite links with Rostelecom's terrestrial infrastructure in remote federal districts.
Broadcast services generate the volume base; military applications capture the margin premium.
End User:
Customer-type concentration maps directly to procurement sophistication and contract duration.
- Government:Classified payloads and secure communications drive multi-year managed service agreements with system integrators in Moscow's aerospace cluster. Single-vendor accountability requirements favor consolidated procurement.
- Enterprise:Energy sector digitalization mandates across Siberian extraction sites combine satellite backhaul with industrial IoT sensor networks.
- Aviation:In-flight connectivity demand concentrates on transcontinental routes linking European Russia with Far Eastern destinations.
- Maritime:Arctic shipping lanes and Pacific fishing fleets require continuous coverage across high-latitude orbital footprints.
Government contracts provide the longest duration; enterprise segments show the steepest expansion trajectory.
Deployment:
Architecture choice reflects the tension between control, scalability, and mobility requirements.
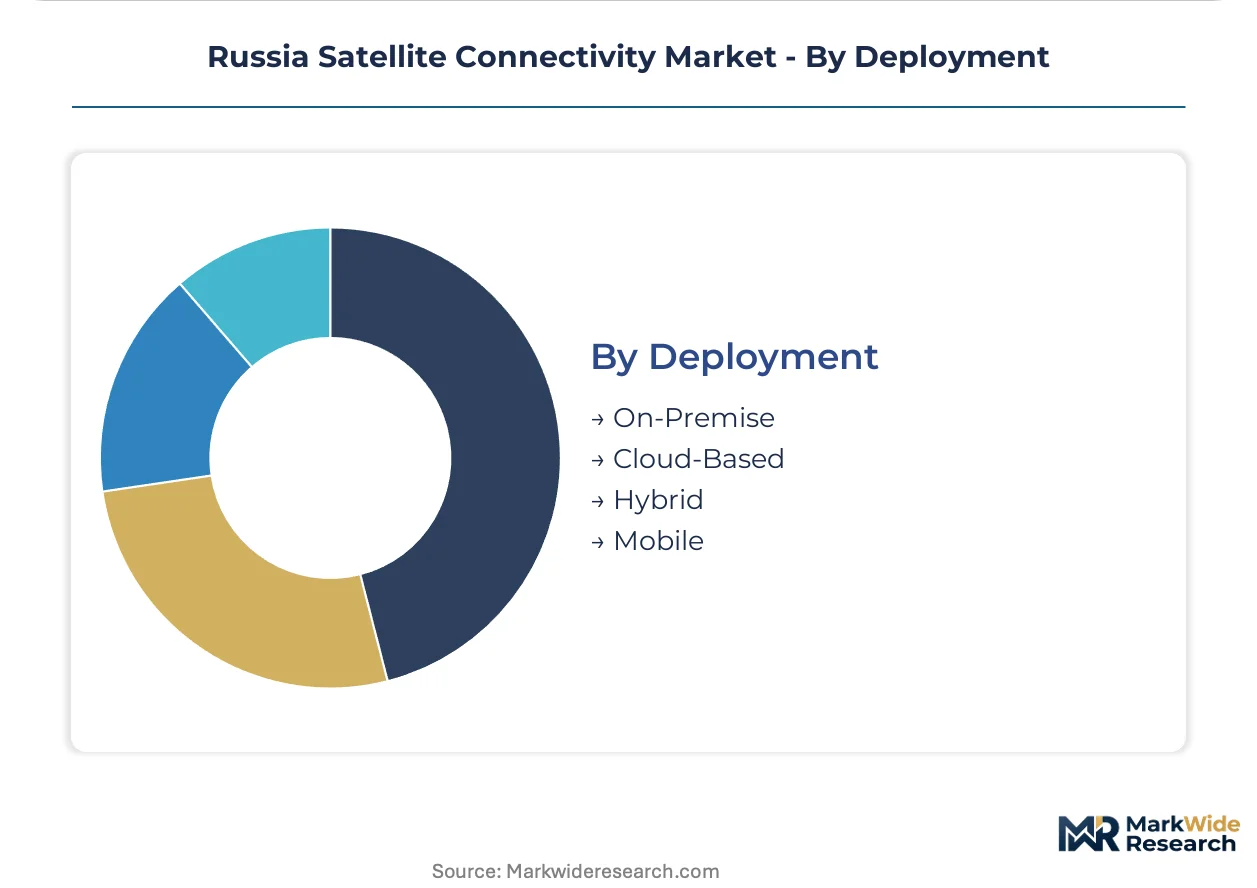
- On-Premise:Dedicated ground station ownership meets Federal Security Service technical audit requirements for sensitive applications. Extended commissioning timelines of 8-14 months apply.
- Cloud-Based:Virtualized network functions enable rapid service provisioning for commercial broadband operators avoiding capital-intensive infrastructure.
- Hybrid:Split architectures combine on-premise encryption with cloud-delivered capacity for enterprises seeking operational flexibility.
- Mobile:Transportable terminals serve emergency response, military field operations, and temporary extraction site connectivity.
On-premise deployments dominate security-sensitive applications; cloud-based models are climbing fastest in commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Roskomnadzor anchors regulatory oversight across Russia's federal structure, with spectrum allocation authority diffusing through regional administrative boundaries that shape operator deployment priorities and ground station licensing timelines.
Moscow and Central Federal District
Aerospace and defense contractor clusters concentrate procurement sophistication for classified payloads. Federal Security Service technical audits impose 8-14 month commissioning delays on ground station facilities. Moscow's technopolis districts host system integrators consolidating multi-year managed service agreements under single-vendor accountability structures.
Siberian Federal District
Energy extraction sites across Krasnoyarsk Krai and Yamalo-Nenets generate predictable Ku-band capacity commitments for remote connectivity. State Commission for Radio Frequencies Ka-band allocations unlock broadband substitution in settlements beyond terrestrial fiber economics. Novosibirsk anchors regional technical talent pools for RF engineering specialization.
Far Eastern Federal District
Sparse ground infrastructure across Sakha and Kamchatka creates captive demand for mobile platform communications. Maritime coverage requirements for Pacific fishing fleets and Arctic shipping lanes drive L-band service procurement. Vladivostok clusters port logistics operators seeking continuous high-latitude orbital connectivity.
Northwestern Federal District
St. Petersburg's industrial base sustains demand for hybrid deployment architectures combining on-premise encryption with cloud-delivered capacity. Roskomnadzor licensing mandates force foreign operators into domestic legal entity establishment for spectrum access. The region's defense manufacturing legacy supports Bureau 1440's protected segment positioning.
Ural Federal District
Mineral extraction and heavy industry across Chelyabinsk and Sverdlovsk Oblasts combine satellite backhaul with industrial IoT sensor networks. Import-substitution mandates reconfigure terminal manufacturing supply chains toward domestic component sourcing. Yekaterinburg hosts emerging system integration capabilities for enterprise broadband deployment.
Russia Satellite Connectivity Market Competitive Landscape
Capability concentration sits with specialized government contractors; scale advantage sits with energy-sector integrated operators. The vendor base separates into three functional tiers: state-affiliated incumbents with spectrum priority, defense-specialized boutiques with security certification, and regional service aggregators with last-mile integration. Consolidation pressure operates through managed service contract consolidation and import-substitution driven supply chain reconfiguration.
Within the state-affiliated tier, Russian Satellite Communications Company and Gazprom Space Systems exemplify divergent anchor strategies—one serving broadcast distribution breadth, the other capturing energy-sector vertical demand. Bureau 1440 occupies a protected position in classified payload contracting insulated from commercial pricing pressure. These three entities collectively represent the spectrum of competitive positioning available under Roskomnadzor's licensing architecture.
| Leading Market Players |
|---|
| Russian Satellite Communications Company |
| Bureau 1440 |
| Rostelecom |
| Gazprom Space Systems |
| AltegroSky |
| RTComm |
| Sputnix |
| Raduga-Internet |
| ICS Holding |
| Others |
Pricing and Supply Chain Analysis
Domestic RF component manufacturing concentration in Russia's Ural Federal District anchors margin capture for certified terminal producers while forcing import-dependent assemblers into cost-prohibitive compliance pathways. State Commission for Radio Frequencies spectrum licensing fees and Federal Security Service audit requirements concentrate pricing power among incumbent operators with established ground station footprints.
Pricing Analysis
Moscow-to-Vladivostok geographic spreads exceed threefold for equivalent Ka-band capacity, reflecting transport economics and ground infrastructure density gradients. Three-tier pricing structure across premium, standard, and economy levels segments by Federal Security Service certification grade and managed service bundling intensity. Cost compression in commercial broadband tiers intensifies because Rostelecom's fiber bundling erodes addressable satellite demand in European Russia. Energy extraction buyers in Yamalo-Nenets exhibit lowest price sensitivity due to operational continuity requirements, while consumer residential segments in remote settlements show highest elasticity.
Supply Chain Analysis
Upstream feedstock for satellite terminals draws from China, South Korea, and domestic Russian semiconductor packaging facilities, with RF front-end components and phased-array antenna substrates representing critical input categories. Gallium nitride power amplifiers, silicon-germanium transceivers, and precision waveguide assemblies constitute primary bill-of-materials dependencies. Single-source vulnerability concentrates in high-frequency semiconductor foundry access, where export control classifications restrict non-Russian supplier relationships. Distribution runs through Moscow-based system integrators serving aerospace and defense contractor clusters, with direct operator relationships displaced by managed service aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against terrestrial fiber extension and low-earth orbit constellation proliferation, both threatening geostationary capacity economics. Incumbents must harden anchor customer relationships before alternative connectivity architectures achieve price parity.
For Market Incumbents: Insulate government and energy sector accounts through multi-year managed service contracts that bundle terrestrial integration with orbital capacity, locking in switching costs before low-earth orbit alternatives mature. Deepen backward integration into domestic RF component manufacturing to satisfy import-substitution mandates and compress procurement timelines for Federal Security Service-certified terminals.
For New Entrants and Emerging Players: Far Eastern Federal District maritime and aviation connectivity represents the most penetrable entry point, with Sakha and Kamchatka ground infrastructure gaps creating captive demand for mobile platform services. Ka-band residential broadband in settlements beyond Rostelecom fiber reach offers white-space expansion with lower regulatory friction than government segments. Partner with regional terrestrial carriers for last-mile integration rather than pursuing direct spectrum licensing.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Ka-band high-throughput satellite deployment, favoring scaled operators with existing orbital slots and ground station footprints. Acquisition targets should display Federal Security Service certification capabilities and energy sector contract concentration. Monitor State Commission for Radio Frequencies spectrum auction timing as the critical inflection signal for competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Ka-band Capacity Expansion | Spot-beam architectures unlock 100 Mbps-plus throughput for enterprise broadband substitution in Siberian extraction zones. |
| Domestic Terminal Manufacturing | Import-substitution mandates force supply chain reconfiguration toward Ural Federal District component sourcing. |
| Managed Service Consolidation | Single-vendor accountability requirements concentrate procurement with Moscow system integrators serving classified payloads. |
| Spectrum Portfolio Optimization | State Commission for Radio Frequencies Ka-band allocations determine which operators may commercialize broadband services. |
| Terrestrial Integration Partnerships | Rostelecom last-mile bundling in population corridors erodes standalone satellite addressable market. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with satellite network architects, Federal Security Service certification auditors, energy sector procurement leads, and Roskomnadzor licensing officials. Secondary validation incorporated State Commission for Radio Frequencies spectrum allocation records, customs data on RF component imports, and operator capacity disclosure filings. Bottom-up terminal deployment estimates and top-down orbital capacity supply assessments were triangulated to anchor market sizing.
Calibration against historical capacity utilization rates and contract renewal patterns informed trajectory assumptions across the projection horizon. Segmentation modeling spanned frequency band, service type, end-user category, and deployment architecture dimensions. CAGRs were derived from elasticity-adjusted demand curves and supply-side capacity addition schedules. Forecast inputs incorporated energy sector digitalization mandates, military procurement cycles, and terrestrial fiber buildout timelines.
Stress conditions across spectrum allocation delays, export control tightening, and low-earth orbit competitive entry were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding orbital asset deployment schedules and regulatory enforcement intensity. Cross-checking against operator-reported capacity utilization and contract backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
GEO Satellite Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
Satellite Backhaul Market
Satellite
Small Satellite Market
Satellite
Global Enterprise VSAT System Market
Satellite
France Satellite-Based Earth Observation Market
Satellite
China Satellite-Based Earth Observation Market
Satellite
Europe Small Satellite Market
Satellite
Eastern Europe and North Africa Satellite Communication Market
Satellite
Healthcare Satellite Connectivity Market
Satellite
US Satellite Connectivity Market
Satellite
North America Small Satellite Market
Satellite
Satellite Communication Subsystem Market
Satellite
M2M Satellite Communication Market
Satellite
UK Satellite Connectivity Market
Satellite
Argentina Satellite-Based Earth Observation Market