
 Aircraft Cargo Container Market | 2026-2036
Aircraft Cargo Container Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Cargo Container Market Analysis
TSO-C90c certification is collapsing the supplier base as smaller fabricators lack the capital to sustain fire-resistance and structural-load testing cycles. DoKaSch GmbH leverages its in-house composite lamination capabilities to control certification timelines and reduce third-party dependency. Nordisk Aviation anchors Scandinavian routes through specialized refrigerated container fleets serving pharmaceutical lanes. Cargo Composites differentiates by dominating the PMC pallet-container hybrid segment where military and commercial freight specifications converge.
An aircraft cargo container is a unit load device engineered to specific ATA dimensional standards, typically fabricated from aluminum sheet, fiberglass-reinforced polymer, or hybrid sandwich panels, designed to interface with cargo loading systems and restraint rails inside wide-body and narrow-body freighter aircraft. The primary purpose is maximizing volumetric efficiency while protecting contents from G-force shifts, pressure differentials, and thermal excursions during flight. LD3 containers sustain the largest installed base due to universal compatibility with Boeing 767 and Airbus A330 lower-deck configurations, though composite-material variants are capturing margin pools as fuel-burn penalties on aluminum weight accumulate. PMC pallet-containers lead on main-deck applications where dimensional flexibility for oversized aeronautical freight and defense equipment commands premium pricing over standard footprints.
The FAA mandates TSO-C90c and SAE AS36100 standards for fire containment and structural integrity, while EASA enforces parallel CS-25 certification pathways that shape European product development cycles and market access conditions. The EU Green Deal's emerging requirements on aircraft operational emissions are pressuring operators to retire heavier aluminum containers ahead of schedule, redirecting procurement toward composite and hybrid-material platforms. Stakeholders must monitor how ICAO's developing sustainable aviation fuel framework may cascade into container weight-reduction mandates that redefine competitive positioning across material segments.
Market Dynamics
Composite material substitution is decomposing the aluminum-dominated installed base as fuel-burn penalties on legacy container weight accumulate across cargo operator fleets. FAA fire containment mandates for lithium battery transport are forcing simultaneous redesigns of wall structures and liner systems, compressing supplier margins while accelerating certification timelines.
Growth Catalysts
- E-commerce pharmaceutical logistics:Temperature-sensitive biologics shipments are expanding refrigerated container demand across European and Asian cargo hubs.
- EU Green Deal operational emissions pressure:Aircraft operators face accelerating container retirement schedules that redirect procurement toward lightweight composite platforms.
- Lithium battery transport volumes:Consumer electronics and electric vehicle supply chains are mandating enhanced fire-resistant container specifications for main-deck and lower-deck configurations.
Market Restraints
- Certification cost concentration:TSO-C90c fire-resistance and structural-load testing cycles require capital reserves that eliminate smaller fabricators from the supplier base.
- Raw material supply volatility:Carbon fiber and epoxy resin prices fluctuate with energy market conditions, compressing composite container margins unpredictably.
- Aluminum weight legacy lock-in:Existing fleet amortization schedules delay replacement cycles despite fuel-burn penalties on heavier containers.
Strategic Opportunities
- India cargo hub expansion:Bangalore and Hyderabad pharmaceutical export corridors lack sufficient refrigerated container capacity for temperature-controlled biologics.
- SAF-linked weight reduction mandates:ICAO sustainable aviation fuel frameworks may cascade into formal container mass-reduction requirements that favor composite suppliers.
- Defense-commercial specification convergence:PMC pallet-container hybrids serving military oversized freight can capture dual-use procurement contracts.
Industry Challenges
- Composite lamination skill scarcity:In-house manufacturing capabilities for fire-resistant sandwich panels require specialized technician training that outpaces labor market supply.
- Dual certification timeline compression:Parallel FAA TSO-C90c and EASA CS-25 approval pathways extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Cargo Container Market |
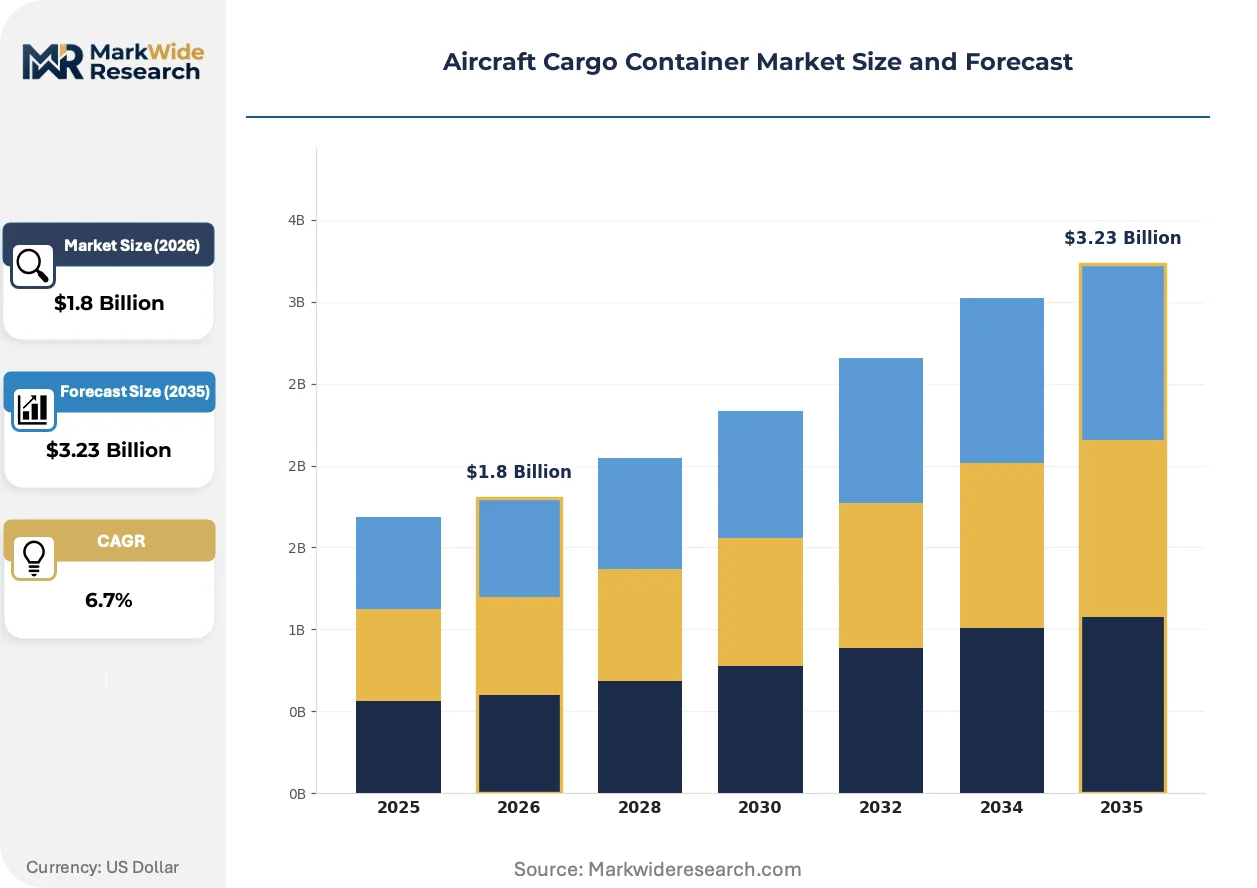
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: LD3, LD6, PMC, PMC-Container Material: Aluminum, Composite, Plastic, Steel Application: Aeronautical Freight, Medical Supplies, E-Commerce, Defense Size: Standard, Oversized, Miniature, Custom |
| Companies Covered | DoKaSch GmbH, Nordisk Aviation, Cargo Composites, Satco Inc., VRR-Aviation, Granger Aerospace, PalNet GmbH, Envirotainer, AAR Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Cargo Container Market Emerging Trajectories
Material science advances and regulatory pressure on fire containment are converging to reshape container architecture. Three developments are restructuring competitive positioning across fabrication methods and certification strategies.
Hybrid sandwich panel construction is decomposing traditional aluminum sheet dominance in lower-deck LD3 configurations. Pharmaceutical logistics operators in Germany and the Netherlands are adopting fiberglass-reinforced polymer variants at accelerated replacement cycles. This technology is decomposing the historical trade-off between structural load ratings and container tare weight.
REACH chemical safety protocols and parallel EU Green Deal emissions frameworks are tightening material composition standards for container liners and adhesives. European manufacturers must now document full supply chain chemical footprints alongside structural certification. Composite fabricators with captive resin formulation capabilities are capturing margin pools that aluminum suppliers cannot access.
Airline procurement departments are consolidating vendor relationships around full-service container lifecycle management. Long-term leasing arrangements with embedded maintenance and recertification obligations are displacing spot purchases in North American and Asian carrier fleets. This restructuring is most visible among e-commerce dedicated freighter operators managing rapid fleet expansion cycles.
Aircraft Cargo Container Market Segmentation
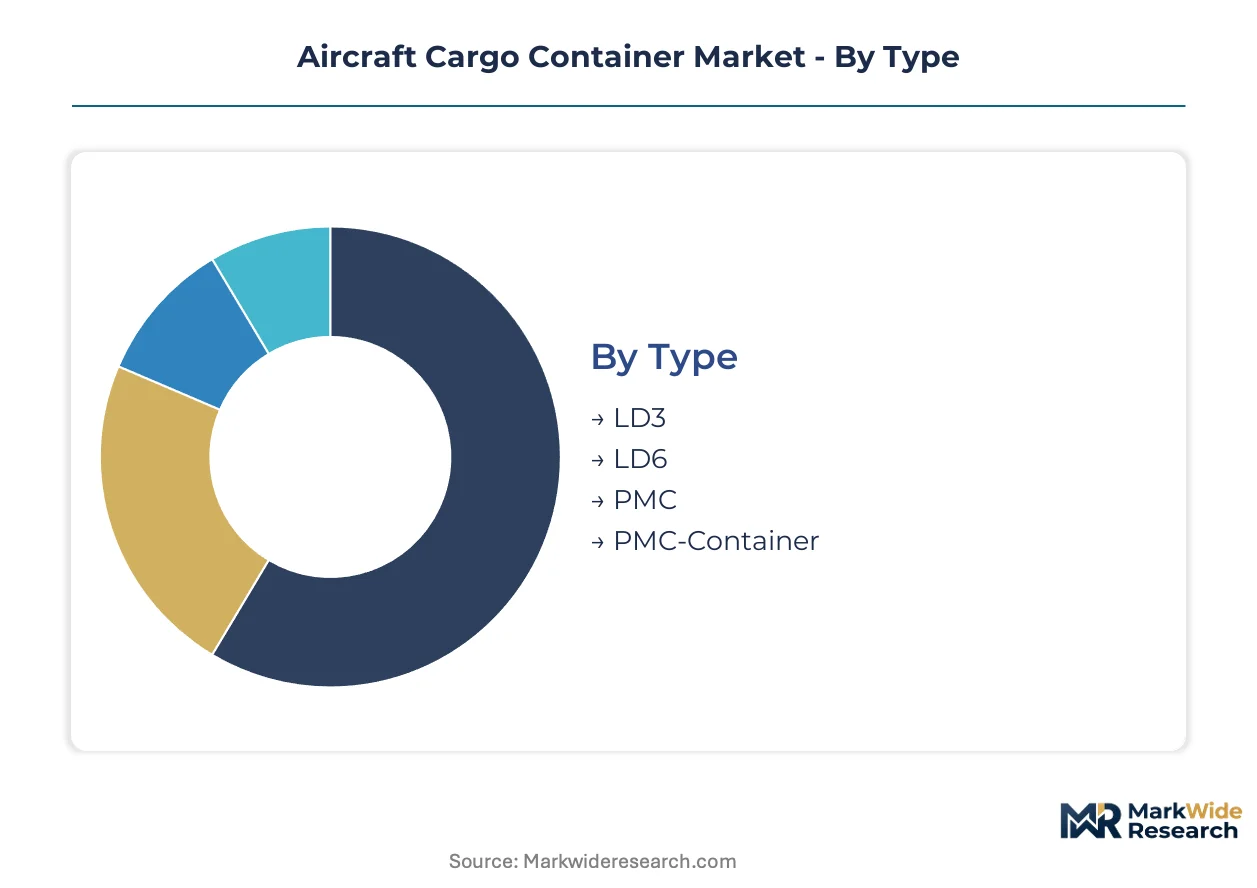
Container specification choices determine fuel-burn penalties, certification pathways, and fleet interoperability across cargo operator procurement cycles. Segmentation reveals where composite substitution pressures legacy aluminum economics and which dimensional standards lock in long-term fleet commitments.
Type:
LD3 configurations face the most intense substitution threat as composite sandwich panels decompose aluminum's historical dominance in lower-deck applications.
- LD3:Half-width containers engineered to ATA standard dimensions interface with Boeing 767 and Airbus A330 lower-deck cargo systems. German pharmaceutical logistics operators at Frankfurt and Hamburg hubs are accelerating replacement cycles toward fiberglass-reinforced polymer variants as EU Green Deal emissions pressure compounds fuel-burn penalties on legacy aluminum tare weight.
- LD6:Full-width lower-deck containers double LD3 volumetric capacity for dense freight consolidation on wide-body routes. E-commerce dedicated freighter fleets expanding across Asian cargo corridors favor LD6 configurations for parcel density optimization, though certification timelines for composite variants lag LD3 development by approximately 18 months.
- PMC:Palletized main-deck platforms dominate aeronautical and defense freight where dimensional flexibility outweighs containerization efficiency.
- PMC-Container:Hybrid configurations merge pallet base structures with collapsible container walls for dual-use military-commercial procurement.
LD3 retains volume leadership; PMC-Container holds the steepest expansion curve.
Material:
Cost tier stratification separates premium composite platforms from commodity aluminum as certification requirements concentrate supplier capabilities.
- Aluminum:Sheet-metal fabrication with riveted corner castings maintains the largest installed base due to amortization schedules and repair network density. Legacy fleet operators in the United States delay replacement despite accumulating fuel-burn penalties, preserving aluminum's near-term revenue concentration.
- Composite:Fiberglass-reinforced polymer and carbon-epoxy sandwich panels reduce tare weight by 15-25 percent versus aluminum equivalents. DoKaSch GmbH and Nordisk Aviation control European procurement through in-house lamination capabilities that compress FAA TSO-C90c certification timelines.
- Plastic:Rotationally molded polyethylene variants serve miniature and custom applications where structural load ratings are secondary to chemical resistance and cost minimization.
- Steel:Reinforced corner posts and base rails in hybrid configurations address main-deck military freight requiring ballistic protection or electromagnetic shielding specifications.
Aluminum dominates installed base value; composite is gaining share fastest.
Application:
Customer type divergence separates temperature-controlled pharmaceutical logistics from commodity parcel freight in procurement specification intensity.
- Aeronautical Freight:Engine components and maintenance parts require PMC pallet-container hybrids with specialized tie-down configurations for irregular geometries. Defense procurement specifications in the United States and Germany are converging toward dual-use commercial-military platforms.
- Medical Supplies:Temperature-sensitive biologics and vaccines mandate refrigerated container fleets with validated cold-chain performance. Indian pharmaceutical export corridors through Bangalore and Hyderabad lack sufficient refrigerated capacity, creating procurement urgency.
- E-Commerce:Parcel density optimization drives demand for lightweight LD3 and LD6 configurations in dedicated freighter fleets.
- Defense:Oversized equipment transport requires main-deck platforms with reinforced load ratings and rapid reconfiguration capabilities.
Aeronautical Freight anchors revenue concentration; Medical Supplies shows the steepest specification escalation.
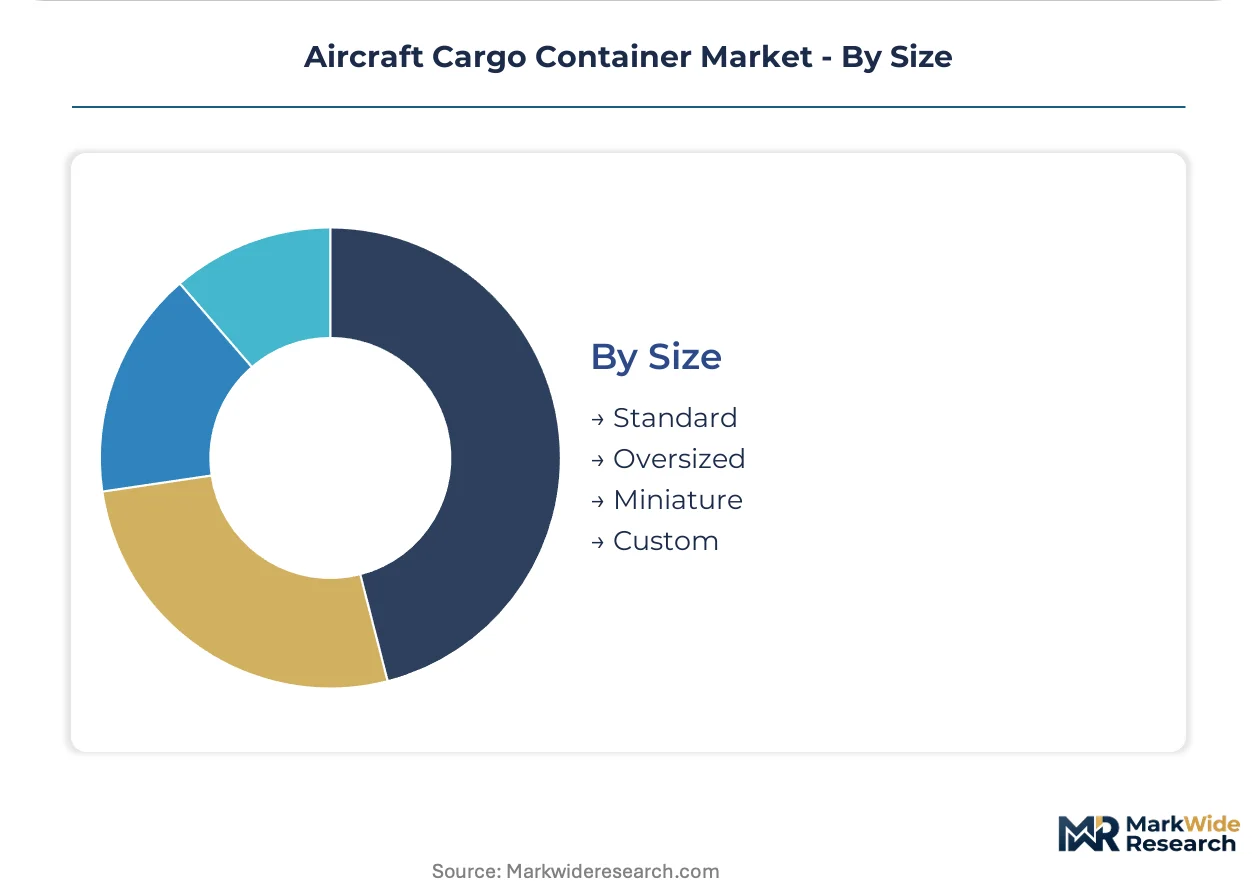
Size:
Maturity gradients separate standardized ATA footprints from emerging custom configurations serving specialized pharmaceutical and defense requirements.
- Standard:ATA-specified LD3, LD6, and PMC dimensions ensure interoperability across Boeing and Airbus freighter fleets. Standard containers concentrate procurement volume and enable secondary market liquidity for leasing operators.
- Oversized:Extended-length and height variants accommodate aeronautical freight and defense equipment exceeding dimensional limits. FAA and EASA certification pathways for oversized composite structures remain underdeveloped, preserving aluminum dominance.
- Miniature:Reduced-footprint containers serve narrow-body converted freighter operations and regional cargo networks.
- Custom:Application-specific dimensions for pharmaceutical temperature-control systems or military electromagnetic shielding bypass standardization economies.
Standard retains procurement volume leadership; Custom holds the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cargo operators concentrate procurement decisions around three hub archetypes: European pharmaceutical consolidation corridors, North American e-commerce fulfillment networks, and Asian biologics export gateways. Each geography imposes distinct certification timelines and material specifications on container suppliers.
United States
E-commerce dedicated freighter fleets at Louisville and Memphis cargo hubs drive demand for lightweight LD3 configurations that reduce fuel-burn penalties on high-frequency parcel routes. The FAA mandates TSO-C90c fire containment standards that compress supplier certification timelines and eliminate smaller fabricators from procurement shortlists. Chicago O'Hare anchors Midwest pharmaceutical distribution with refrigerated container fleets serving temperature-sensitive biologics.
Germany
Frankfurt and Hamburg cargo hubs anchor European air freight consolidation with the continent's densest concentration of refrigerated container capacity for pharmaceutical logistics. The EU Green Deal accelerates retirement schedules for aluminum containers as operational emissions pressure compounds fuel-burn penalties. DoKaSch GmbH leverages in-house composite lamination capabilities in Bavaria to control EASA CS-25 certification pathways and reduce third-party testing dependency.
China
Shanghai Pudong and Beijing Capital cargo hubs expand refrigerated container fleets to handle temperature-sensitive pharmaceutical exports along Belt and Road corridors. The country's national aviation regulator enforces parallel fire containment standards that extend product launch cycles for composite variants. Yangtze River Delta manufacturing clusters supply fiberglass-reinforced polymer components to domestic and export markets.
India
Bangalore and Hyderabad pharmaceutical export corridors lack sufficient refrigerated container capacity for temperature-controlled biologics, creating urgent procurement demand. The Directorate General of Civil Aviation aligns certification pathways with ICAO standards while maintaining domestic testing protocols. Western India manufacturing zones supply aluminum sheet fabrication for legacy fleet operators delaying composite replacement cycles.
United Arab Emirates
Dubai International and Abu Dhabi cargo hubs position as transshipment intermediaries between European pharmaceutical markets and Asian manufacturing zones. The General Civil Aviation Authority adopts FAA-aligned fire containment standards that favor suppliers with existing TSO-C90c certification. Jebel Ali free zone clusters concentrate third-party logistics operators consolidating container leasing arrangements.
Aircraft Cargo Container Market Vendor Landscape
Player mix skews toward specialized composite fabricators with captive certification capabilities and diversified metal-forming conglomerates serving legacy aluminum demand. The supplier base concentrates around three strategic archetypes: in-house lamination specialists controlling testing timelines, pallet-container hybrid engineers serving dual-use military-commercial procurement, and full-service lifecycle managers embedding maintenance obligations into long-term leases. Competitive moves center on backward integration into resin formulation and geographic expansion into underpenetrated pharmaceutical export corridors.
Among European fabricators, DoKaSch GmbH and Nordisk Aviation exemplify the in-house lamination archetype with captive composite manufacturing capabilities. Cargo Composites occupies a position on the hybrid-configuration vector where PMC pallet-container specifications converge. These three anchors demonstrate how certification control and material integration separate premium-tier suppliers from commodity aluminum competitors.
| Leading Market Players |
|---|
| DoKaSch GmbH |
| Nordisk Aviation |
| Cargo Composites |
| Satco Inc. |
| VRR-Aviation |
| Granger Aerospace |
| PalNet GmbH |
| Envirotainer |
| AAR Corporation |
| Others |
Supply Flow & Price Mechanics
FAA TSO-C90c certification gates supplier qualification and price differentiation simultaneously, concentrating procurement power among fabricators with captive fire-resistance testing capabilities while compressing margins for aluminum-dependent competitors.
Pricing Analysis
Cost-plus contracts with carbon fiber and epoxy resin indexation dominate procurement between composite fabricators and cargo operators. Three-tier pricing structure across premium composite, standard aluminum, and economy refurbished tiers separates certified in-house lamination specialists from third-party-dependent competitors. Pricing pressure stems from raw material volatility as energy markets feed through to resin costs. E-commerce dedicated freighter fleets exhibit highest price sensitivity due to rapid fleet expansion cycles, while pharmaceutical logistics operators prioritize cold-chain validation over unit cost.
Supply Chain Analysis
Germany and China anchor composite lamination capacity, with Bavaria housing DoKaSch GmbH's captive manufacturing and Yangtze River Delta clusters supplying fiberglass-reinforced polymer components. Raw material dependencies center on carbon fiber from Japan and South Korea, epoxy resins from German specialty chemical producers, and aluminum sheet from Western India manufacturing zones. Single-source vulnerability concentrates in certified fire-resistant liner membrane supply. Distribution runs through Dubai Jebel Ali free zone leasing clusters and direct OEM relationships at Frankfurt, Louisville, and Shanghai Pudong cargo hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft cargo container market sits at a high-growth inflection as EU Green Deal emissions mandates and FAA lithium battery fire containment rules simultaneously decompose legacy aluminum economics and open premium capture for composite specialists.
For Market Incumbents: Fortify backward integration into resin formulation to insulate margins from commodity volatility and compress EASA CS-25 certification timelines. Expand in-house lamination technician training programs to address skill scarcity threatening production scale. Lock in long-term leasing arrangements with embedded recertification obligations at North American e-commerce freighter operators before emerging competitors establish lifecycle management relationships. For New Entrants and Emerging Players: Lead with refrigerated container capacity targeting Bangalore and Hyderabad pharmaceutical export corridors where cold-chain infrastructure gaps create urgent procurement demand. Capture white-space in PMC pallet-container hybrid configurations serving dual-use military-commercial specifications converging between United States and German defense procurement. Establish partnerships with third-party logistics operators consolidating leasing arrangements in Dubai Jebel Ali free zone clusters. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across composite manufacturing as fire-resistance testing equipment and captive lamination facilities replace outsourced fabrication. Long-term viability favors vertically integrated mid-cap specialists controlling certification timelines rather than aluminum sheet metal conglomerates facing accelerated retirement schedules. Watch for ICAO sustainable aviation fuel framework developments cascading into formal container mass-reduction mandates as the signal for composite share inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive supply of fire-resistant epoxy systems compresses EASA CS-25 certification timelines for German fabricators. |
| Refrigerated Container Fleet Expansion | Temperature-controlled capacity additions at Bangalore and Hyderabad pharmaceutical hubs address critical cold-chain infrastructure gaps. |
| Long-term Leasing with Embedded Maintenance | Lifecycle management contracts at Louisville and Memphis e-commerce hubs displace spot purchases among rapid-growth freighter operators. |
| Dual-use Military-Commercial Certification | PMC pallet-container hybrids converging United States and German defense specifications capture premium procurement pools. |
| In-house Lamination Technician Training | Specialized composite sandwich panel skills outpace labor market supply, creating captive capability moats for European fabricators. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FAA TSO-C90c certification databases, EASA CS-25 approval registries, and EU Green Deal emissions framework documentation. Primary interviews with cargo operator procurement directors, composite fabricator plant managers, and third-party logistics leasing specialists triangulate against customs trade data and airline fleet expansion disclosures. Bottom-up container unit demand modeling and top-down cargo tonnage projections cross-validate market sizing across the analysis window.
Segmentation dimensions modeled include container type, material composition, application vertical, and geographic hub cluster. CAGRs derive from volumetric fleet replacement schedules, fuel-burn penalty accumulation curves, and pharmaceutical logistics capacity expansion plans. Forecast inputs incorporate EU Green Deal operational emissions pressure trajectories and ICAO sustainable aviation fuel framework development timelines throughout the projection horizon.
Forecasts assume regulatory continuity in FAA TSO-C90c and EASA CS-25 certification regimes; material policy shifts would require re-modeling. Composite raw material price volatility and lithium battery transport mandate acceleration represent primary forecast revision risks. Recalibration cycles align with material shifts in sustainable aviation fuel policy developments and pharmaceutical cold-chain infrastructure investments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Middle East and Africa Aviation Market
Aircraft
United States Aerospace and Defense Market
Aircraft
US Aircraft Windshield Wiper and Washer System Market
Aircraft
France Aviation Market
Aircraft
Aviation Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Docking System Market
Aircraft
Airplane Ailerons Market
Aircraft
Manned Evtol Crafts Market
Aircraft
Australia Aviation Market
Aircraft
Global Electronic Flight Bag Market
Aircraft
India Winglets Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
North America Commercial Aircraft Market
Aircraft
Aircraft Anchoring System Market
Aircraft
Onboard Oxygen Generating System (OBOGS) Market