
 Robotic Combat Vehicle (RCV) Market | 2026-2036
Robotic Combat Vehicle (RCV) Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Combat Vehicle (RCV) Market Insights
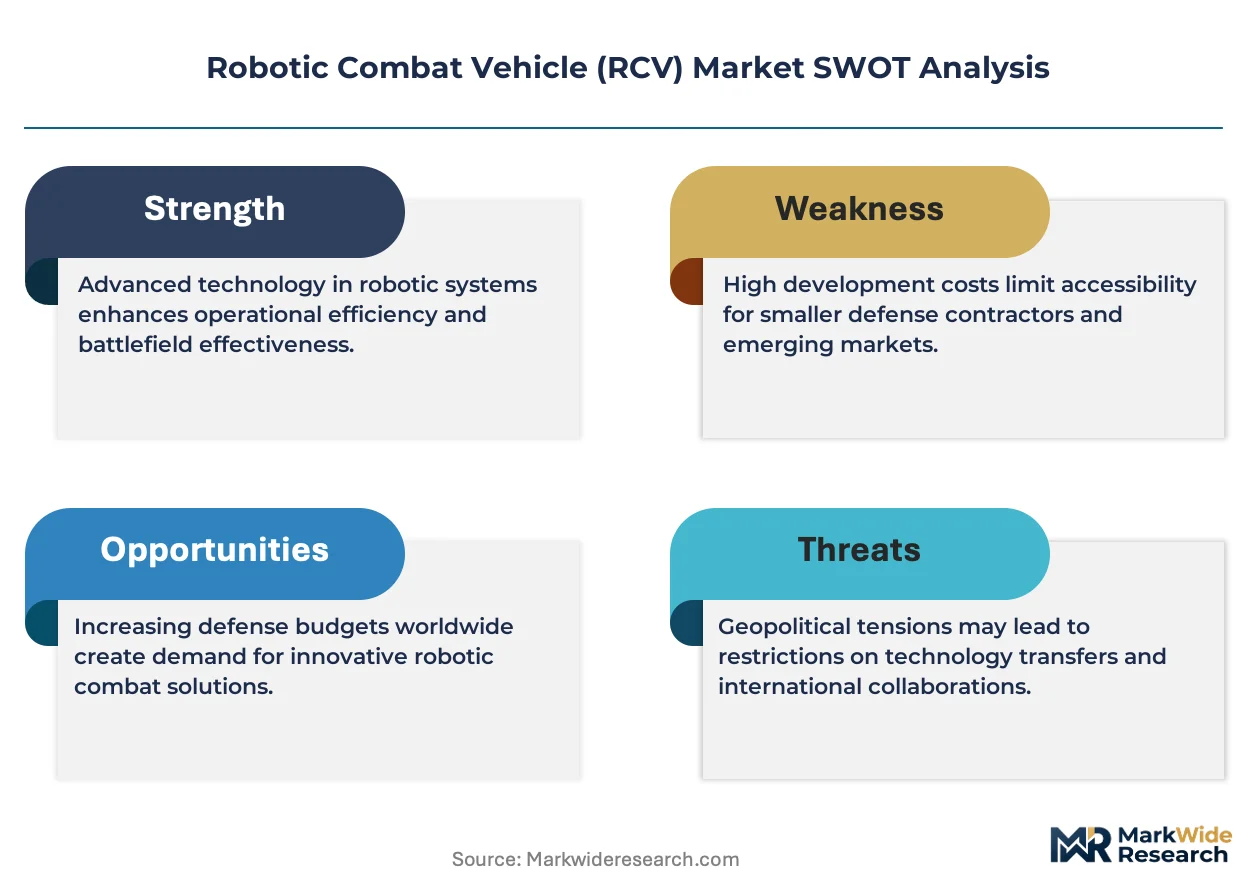
Steel-aluminum hybrid hulls is hardening platform survivability against shaped-charge threats while trimming curb weight. Rheinmetall AG leverages its automotive heritage to produce modular suspension architectures for tracked variants. Elbit Systems anchors its position through integrated electro-optical payload suites that merge targeting with autonomous navigation.
A robotic combat vehicle denotes an unmanned ground platform spanning ten to thirty metric tons, powered by diesel-electric or full-electric drivetrains, and tasked with reconnaissance, direct fire, or logistics missions without onboard crew. Wheeled configurations dominate procurement volumes due to lower lifecycle costs and highway mobility, while tracked variants capture the premium segment where terrain traversal determines mission success. Fire support applications attract the deepest R&D investment as gun-laden RCVs require recoil-dampening chassis engineering that few suppliers master.
The US Department of Defense, the UK Ministry of Defence, and Germany's BAAINBw each impose distinct cybersecurity and interoperability standards that fragment supplier qualification pathways. NATO's STANAG 4586 governs command-and-control interfaces, yet national annexes create de facto market access barriers. Stakeholders must monitor which procurement authority moves first to mandate fully autonomous engagement protocols, as that regulatory choice will reshape competitive qualification requirements across allied supply chains.
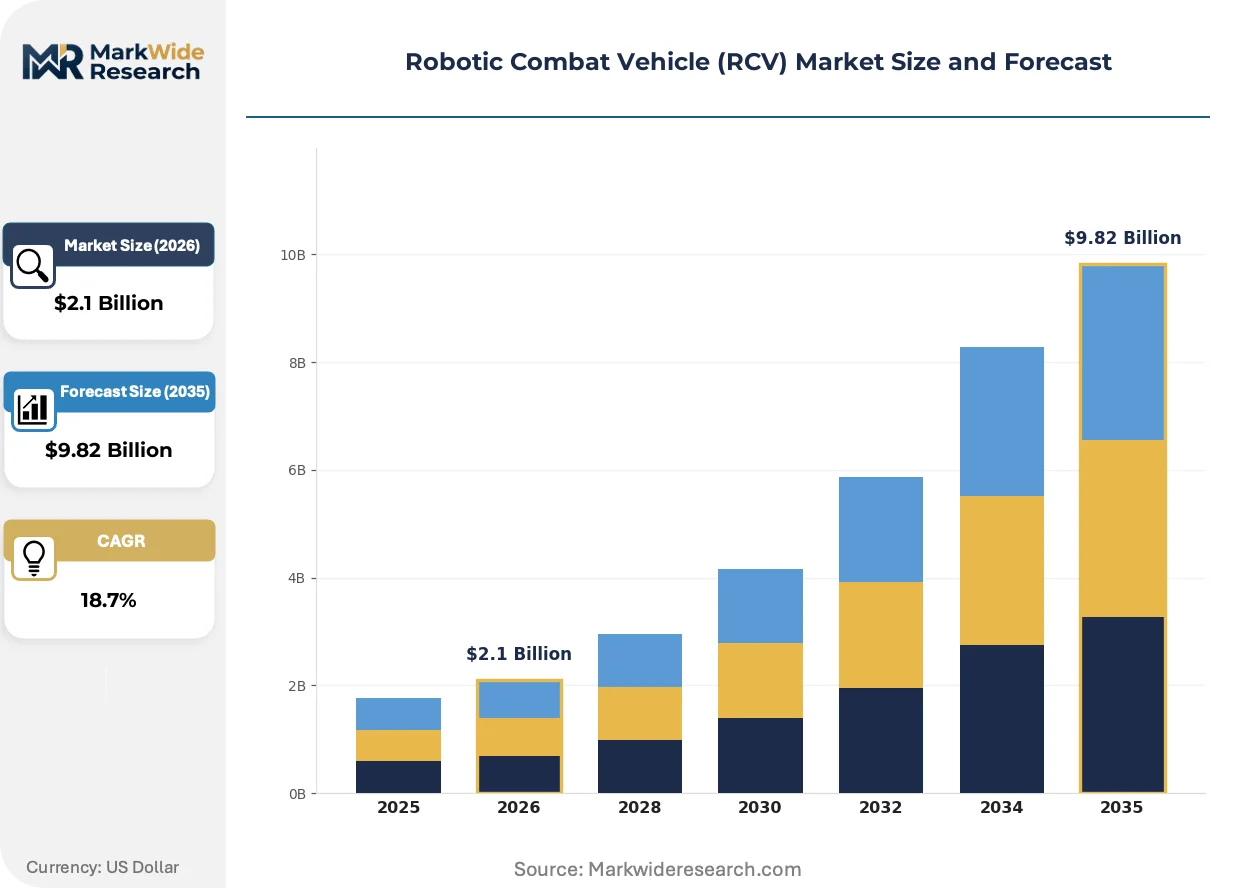
Market Dynamics
Defense procurement authorities are mandating hardened cybersecurity architectures and autonomous engagement protocols faster than suppliers can certify platforms, compressing development timelines and fragmenting qualification pathways across NATO member states.
Growth Catalysts
- Replicator Initiative:The US Department of Defense's program to field thousands of attritable autonomous systems by 2026 is concentrating demand in Western military procurement channels and accelerating platform orders.
- STANAG 4586:NATO's command-and-control interoperability standard is reducing integration friction between national platforms, enabling cross-border joint operations and pooled procurement.
- Edge-computing payloads:Onboard AI inference engines are reducing reliance on contested datalinks, expanding operational envelopes in GPS-denied environments and electronic warfare conditions.
Market Restraints
- Steel-aluminum hybrid armor:Input cost volatility for hardened composites and rare-earth magnet materials is squeezing platform margins and complicating multi-year contract pricing.
- Tracked suspension suppliers:Production capacity for heavy-duty modular track systems concentrates in Central European industrial clusters, creating single-source vulnerability for premium-variant manufacturers.
- Autonomous engagement protocols:National regulatory fragmentation around rules of engagement for lethal autonomous systems is delaying fielding timelines and inflating compliance costs.
Strategic Opportunities
- UK Ministry of Defence:The British Army's experimentation with robotic platoon concepts at Salisbury Plain creates early-adopter demand for integrated fire-support and logistics variants.
- Diesel-electric to full-electric transition:Converging advances in solid-state battery chemistry and silicon carbide power electronics are opening platform redesign cycles for silent-running reconnaissance missions.
- Germany's BAAINBw:The Federal Office of Bundeswehr Equipment's emphasis on modular open-system architectures is creating qualification pathways for non-traditional subsystem suppliers.
Industry Challenges
- Recoil-dampening chassis engineering:The specialized mechanical design talent required for gun-stabilized platforms is scarce, with fewer than a dozen qualified engineering teams across NATO suppliers.
- Platform-as-a-service transition:Defense ministries are demanding availability-based contracting rather than capital acquisition, forcing manufacturers to restructure balance sheets and build captive maintenance networks.
- Legacy vehicle integration:Retrofitting autonomous navigation suites onto existing manned fleets requires solving electromagnetic interference with 1980s-era analog systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Combat Vehicle (RCV) Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.82 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Tracked, Wheeled, Hybrid, Legged Technology: LIDAR, Infrared Sensors, Autonomous Navigation, Machine Learning, Remote Control Application: Reconnaissance, Fire Support, Logistics Support, Surveillance, Electronic Warfare Operator: Military Forces, Defense Contractors, Security Agencies, Research Institutions |
| Companies Covered | Elbit Systems, Lockheed Martin Corporation, General Dynamics Land Systems, Rheinmetall AG, Northrop Grumman Corporation, Textron Systems, Israel Aerospace Industries, QinetiQ, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Combat Vehicle (RCV) Market Trends and Innovations
Active electronically scanned array radars and multi-spectral sensor fusion are compressing the sensor-to-shooter timeline, while procurement authorities experiment with subscription-based fleet management models that transfer operational risk to manufacturers.
Multi-domain tethering architectures are automating cross-platform tasking between aerial drones and ground RCVs. US Army Futures Command units are field-testing these swarming protocols at Fort Hood. The technology is automating decentralized target handoff and reducing command latency in contested electromagnetic environments.
The EU AI Act's risk-classification framework for autonomous weapons systems is forcing European suppliers to document algorithmic decision trails and human oversight checkpoints. German and French procurement offices are now requiring third-party algorithmic audits as pre-qualification conditions. Fire-support platforms with lethal autonomous capabilities face the steepest compliance burdens and longest certification timelines.
Availability-based service contracts are displacing traditional capital procurement for wheeled logistics variants. British and Dutch defense ministries are piloting per-kilometer pricing models that bundle platform, maintenance, and software updates. This shift is most visible in Western European NATO members with constrained capital budgets and aging vehicle fleets requiring rapid replacement.
Robotic Combat Vehicle (RCV) Market Segmentation
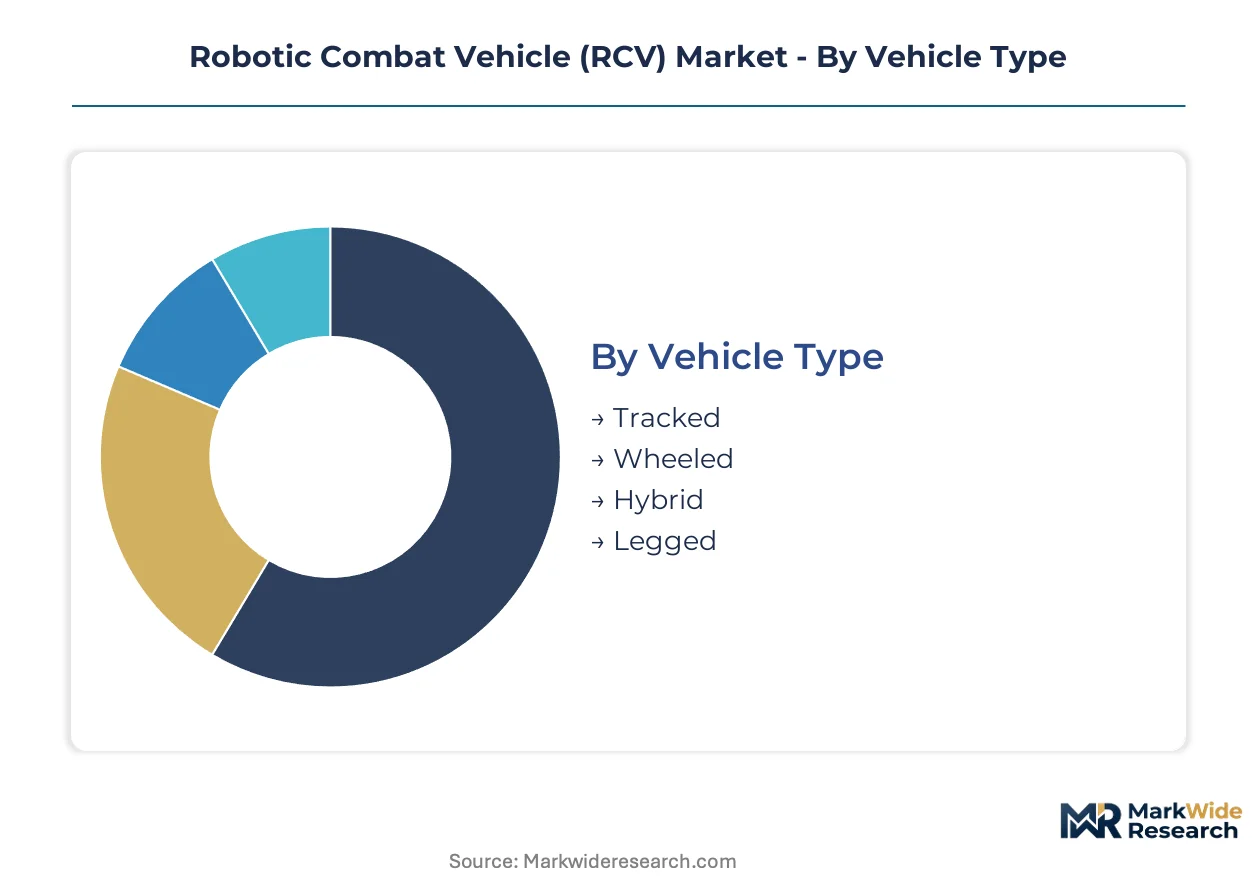
Platform segmentation in the RCV market determines supplier qualification pathways, as NATO STANAG 4586 compliance and national cybersecurity annexes apply differentially across vehicle architectures and mission profiles. Procurement authorities segment demand by operational envelope rather than technical specification alone.
Vehicle Type:
Tracked variants demand the most intensive certification under Germany's BAAINBw structural integrity protocols, while wheeled platforms navigate lighter UK Ministry of Defence highway mobility standards.
- Tracked:Heavy-duty modular suspension systems support 20-30 metric ton platforms in terrain-traversal missions. German and Polish procurement channels concentrate demand here, driven by armored corps requirements for direct-fire support in contested eastern flank scenarios.
- Wheeled:Diesel-electric drivetrains power 10-15 ton configurations optimized for road mobility and rapid deployment. US Army Futures Command and British Army experimentation at Salisbury Plain favor these variants for logistics and reconnaissance missions where lifecycle cost dominates procurement calculus.
- Hybrid:Convertible track-wheel architectures bridge capability gaps for expeditionary forces requiring multimodal transport.
- Legged:Experimental quadruped platforms navigate terrain impassable to conventional vehicles, attracting DARPA and research institution investment.
Wheeled configurations sit at the top of the volume ranking, with hybrid architectures climbing the fastest as expeditionary doctrines evolve.
Technology:
Cost tier segmentation separates hardened military-grade payloads from commercial-derivative sensor suites, with price multiples exceeding 4x for radiation-hardened edge-computing modules.
- LIDAR:Frequency-modulated continuous-wave systems generate 3D terrain maps for autonomous navigation in GPS-denied environments. US Replicator initiative specifications mandate these payloads for contested electromagnetic operations, concentrating demand in Western procurement channels.
- Infrared Sensors:Cooled multi-spectral detectors enable target acquisition through smoke and foliage. Elbit Systems and Rheinmetall integrate these into electro-optical suites for fire-support platforms where human-in-the-loop targeting remains mandatory under EU AI Act risk classifications.
- Autonomous Navigation:Simultaneous localization and mapping algorithms reduce datalink dependency.
- Machine Learning:Onboard inference engines process sensor fusion at the edge.
- Remote Control:Line-of-sight and beyond-line-of-sight command links retain human oversight for lethal engagement protocols.
Remote control technology retains the largest installed base, though machine learning capabilities are expanding most quickly as autonomy thresholds advance.
Application:
Margin concentration follows mission criticality, with fire-support platforms commanding premium pricing due to recoil-dampening chassis engineering scarcity.
- Fire Support:Gun-stabilized platforms mounting 30-50mm cannons require specialized mechanical design talent available from fewer than a dozen qualified NATO engineering teams. US and German procurement offices prioritize these variants for robotic platoon integration, accepting extended development timelines for lethality certification.
- Reconnaissance:Silent-running electric drivetrains and low-observable signatures dominate platform specifications here. British Army and Dutch defense ministries pilot availability-based contracting for these variants, bundling per-kilometer pricing with predictive maintenance.
- Logistics Support:Payload capacity and fuel efficiency drive procurement decisions for supply convoy protection.
- Surveillance:Persistent stare capabilities require stabilized mast-mounted sensor arrays.
- Electronic Warfare:Direction-finding and jamming payloads demand electromagnetic compatibility hardening.
Logistics support sits at the top of the volume ranking, with electronic warfare applications climbing the fastest as spectrum contestation intensifies.
Operator:
Customer type determines contract structure, with defense ministries demanding availability-based service models while research institutions procure through capital acquisition.
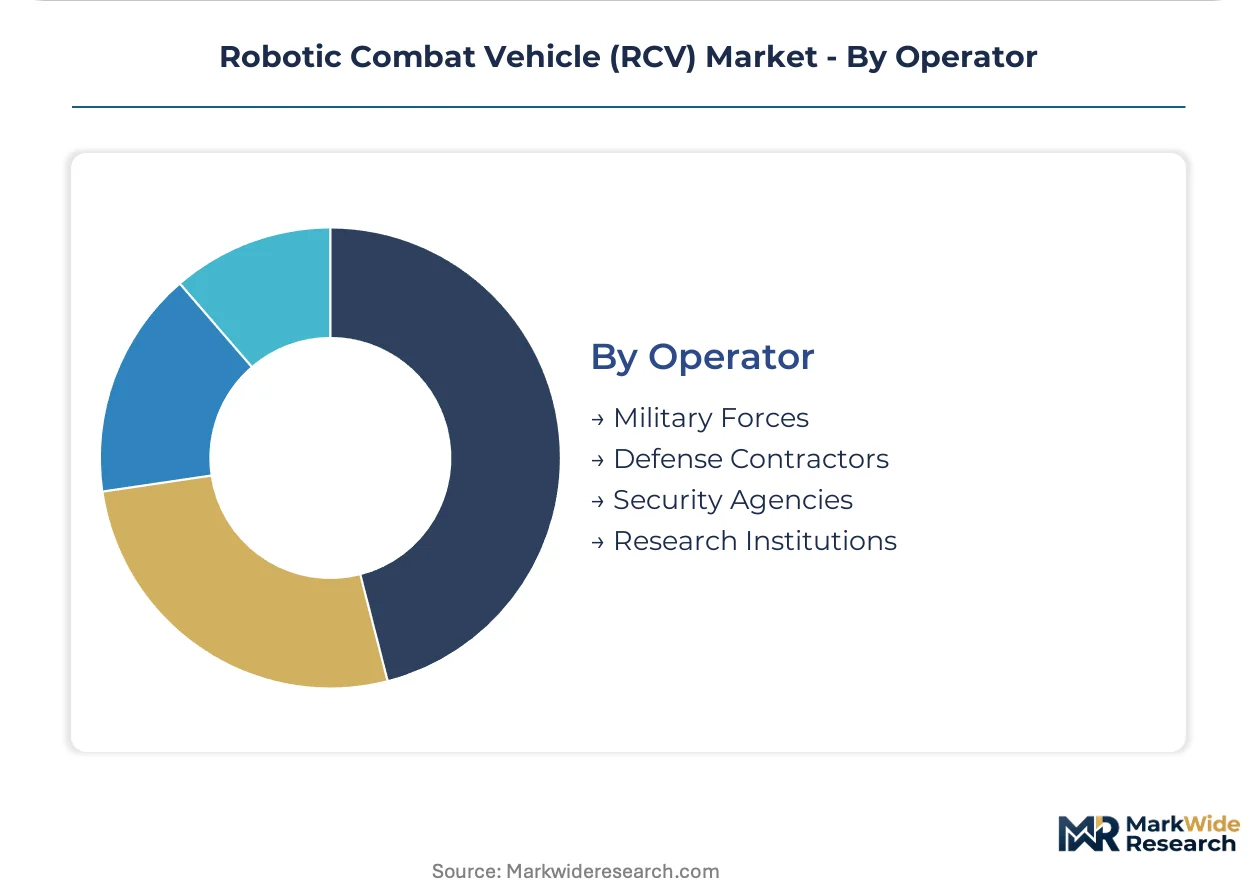
- Military Forces:National armored corps and infantry brigades constitute the primary demand channel, with US Department of Defense Replicator initiative and UK robotic platoon programs driving platform orders. These customers mandate STANAG 4586 interoperability and national cybersecurity annex compliance.
- Defense Contractors:Systems integrators and subsystem suppliers purchase platforms for technology demonstration and foreign military sales support.
- Security Agencies:Border protection and critical infrastructure defense units procure lighter wheeled variants.
- Research Institutions:DARPA, Army Research Laboratory, and university-affiliated labs acquire experimental platforms for algorithm development.
Military forces sit at the top of the volume ranking, with security agencies climbing the fastest as perimeter defense applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Central European industrial clusters concentrate tracked suspension manufacturing and armored vehicle engineering talent, anchoring supply-side capacity for NATO procurement channels.
United States
The US Department of Defense's Replicator initiative drives attritable autonomous system procurement through 2026, with Fort Hood hosting swarming protocol field tests. Army Futures Command mandates STANAG 4586 interoperability for cross-border joint operations. Textron Systems and General Dynamics Land Systems anchor production in Michigan and Virginia industrial corridors.
Germany
BAAINBw structural integrity protocols impose the most intensive tracked variant certification requirements across NATO member states. The Federal Office of Bundeswehr Equipment prioritizes modular open-system architectures for subsystem supplier qualification. Rheinmetall AG leverages automotive heritage from Düsseldorf-region manufacturing clusters to produce modular suspension architectures.
United Kingdom
British Army robotic platoon experimentation at Salisbury Plain creates early-adopter demand for integrated fire-support variants. The UK Ministry of Defence pilots availability-based per-kilometer pricing models for wheeled logistics platforms. QinetiQ and BAE Systems anchor subsystem integration capabilities in southern England defense corridors.
Israel
Israel Defense Forces operational requirements drive electro-optical payload integration at the platform level. Elbit Systems and Israel Aerospace Industries merge targeting systems with autonomous navigation suites for contested electromagnetic environments. Tel Aviv-area engineering clusters concentrate hardened military-grade sensor development.
Poland
Armored corps requirements for eastern flank direct-fire support concentrate tracked variant demand in Polish procurement channels. The country's defense ministry accelerates autonomous ground system acquisition aligned with NATO deterrence posture. Industrial partnerships with German and US prime contractors localize final assembly capacity.
Robotic Combat Vehicle (RCV) Market Competitive Landscape
Global majors compete with regional champions across qualification pathway fragmentation, as national cybersecurity annexes and STANAG 4586 compliance requirements create tiered market access. The vendor base separates into three archetypes: integrated platform primes with captive subsystem production, electro-optical specialists supplying sensor suites across multiple airframes, and modular suspension engineering houses with automotive heritage. Consolidation pressure intensifies around autonomous navigation algorithm development and recoil-dampening chassis design talent scarcity.
Within the integrated platform tier, Lockheed Martin Corporation and General Dynamics Land Systems exemplify prime contractors navigating multi-year US Department of Defense acquisition cycles, while Rheinmetall AG anchors European tracked variant engineering from Central European manufacturing clusters. Elbit Systems occupies a specialist position bridging electro-optical payload integration with edge-computing autonomy architectures.
| Leading Market Players |
|---|
| Elbit Systems |
| Lockheed Martin Corporation |
| General Dynamics Land Systems |
| Rheinmetall AG |
| Northrop Grumman Corporation |
| Textron Systems |
| Israel Aerospace Industries |
| QinetiQ |
| BAE Systems |
| Others |
Pricing and Supply Chain Analysis
The EU AI Act's risk-classification framework for autonomous weapons systems gates both qualified supply and premium-tier pricing access, as third-party algorithmic audits and human oversight documentation requirements concentrate production capacity among certified suppliers while inflating compliance costs for lethal-capable platforms.
Pricing Analysis
Input-cost pass-through from rare-earth magnet volatility and hardened composite armor pricing feeds directly into platform margins, with steel-aluminum hybrid hulls commanding significant premiums over standard configurations. Pricing stratifies across STANAG 4586-certified primes, national-annex compliant variants, and developmental prototypes lacking full interoperability validation. Cost compression in wheeled logistics variants is intensifying because British and Dutch defense ministries pilot per-kilometer availability contracting. Military procurement offices exhibit lowest price sensitivity for fire-support platforms where recoil-dampening chassis engineering scarcity limits supplier alternatives.
Supply Chain Analysis
Certification and qualification gating under Germany's BAAINBw structural integrity protocols and US Department of Defense cybersecurity annexes fragments supplier access, concentrating tracked suspension manufacturing in Central European industrial clusters around Düsseldorf and Warsaw. Production draws from rare-earth magnet processors in China, hardened steel foundries in Germany, and silicon carbide power electronics from Japan. Single-source vulnerability pervades modular track system supply, as fewer than three qualified producers serve NATO premium-variant demand. Distribution runs through national defense procurement channels with prime contractor integration, bypassing commercial logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RCV market reads as a late-cycle quality story, with defense ministries shifting procurement criteria toward hardened cybersecurity architectures and autonomous engagement protocols that favor certified incumbents over price-competitive challengers.
For Market Incumbents: Anticipate regulatory fragmentation around lethal autonomous engagement protocols by pre-certifying platforms across multiple national annexes before mandate deadlines compress qualification windows. Capture scarce recoil-dampening chassis engineering talent through targeted acquisition of Central European mechanical design houses, as fewer than a dozen qualified teams serve NATO demand. Prioritize backward integration into edge-computing payload production to defend margin position against electro-optical specialist suppliers. For New Entrants and Emerging Players: Capture white-space opportunity in wheeled logistics variants where availability-based contracting models lower capital barriers to entry and British Army per-kilometer pilots demonstrate demand elasticity. Target security agency perimeter defense applications as the fastest-growing operator segment with lighter certification burdens than military-grade fire-support platforms. Pursue subsystem supplier qualification under Germany's BAAINBw modular open-system architecture pathways rather than competing for integrated platform primes. For Investors and Strategic Acquirers: Roll-up economics work for electro-optical payload specialists because national cybersecurity annexes create sticky customer relationships and recurring software update revenue streams across multiple airframe programs. Long-term viability hinges on positioning for the transition from diesel-electric to full-electric drivetrains as solid-state battery chemistry matures. Monitor which procurement authority first mandates fully autonomous engagement protocols as the inflection signal for competitive qualification requirement reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Open-System Architecture Adoption | BAAINBw qualification pathways enable non-traditional subsystem supplier entry into NATO supply chains. |
| Edge-Computing Payload Integration | Onboard AI inference engines reduce datalink dependency for US Army Futures Command contested operations. |
| Recoil-Dampening Chassis Engineering Acquisition | Consolidation of scarce mechanical design talent addresses fire-support platform certification bottlenecks. |
| Availability-Based Service Contract Expansion | Per-kilometer pricing models transfer operational risk to manufacturers for British and Dutch logistics fleets. |
| Multi-Domain Tethering Protocol Development | Swarming architectures automate cross-platform tasking between aerial drones and ground RCVs at Fort Hood. |
Research Methodology
Coverage spans North America, Western Europe, and the Middle East, with primary inputs from each region combined with secondary validation. Interviews with program managers at US Army Futures Command, procurement officers at BAAINBw, platform engineers at Rheinmetall AG, and subsystem integration leads at Elbit Systems informed demand-side and supply-side assessments. Secondary sources include NATO STANAG 4586 documentation, EU AI Act regulatory filings, national defense procurement databases, and SEC 10-K disclosures from listed primes. Bottom-up platform shipment tallies triangulate against top-down defense budget allocation analysis.
Granularity-level modeling disaggregates volume and value across vehicle type, technology payload, application mission profile, and operator category throughout the projection horizon. Tracked, wheeled, hybrid, and legged architectures were modeled separately with distinct certification pathway timelines. Technology segmentation incorporated cost-tier differentiation between hardened military-grade and commercial-derivative sensor suites. CAGRs derive from logistic curve adoption modeling calibrated to Replicator initiative fielding schedules and BAAINBw procurement cycle documentation.
Underlying measurement precision varies by segment; wheeled logistics variants carry tighter precision than experimental legged platforms due to established procurement data availability. Forecasts reflect assumptions about regulatory harmonization timelines, rare-earth supply stability, and autonomous engagement protocol adoption thresholds. A model refresh is warranted upon material change in EU AI Act enforcement posture or US Department of Defense Replicator initiative scope revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Military Ground Robots Market
Military Vehicles
Global Military Vehicle Electrification Market
Military Vehicles
Eastern Europe Defense Market
Military Vehicles
Military Land Vehicles Market
Military Vehicles
Military Unmanned Ground Vehicle Market
Military Vehicles
Combat Support Vehicle Market
Military Vehicles
Amphibious Land Craft Market
Military Vehicles
Russia Defense Market
Military Vehicles
Military Amphibious Vehicle Market
Military Vehicles
Southeast Asia Defense Market
Military Vehicles
Military Ground Vehicle Actuators Market
Military Vehicles
Main Battle Tank Market
Military Vehicles
Taiwan Defense Market
Military Vehicles
Colombia Defense Market
Military Vehicles
Middle East Military Vehicles Market